
 Aluminum-Free Food Pouch Market | 2026-2036
Aluminum-Free Food Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum-Free Food Pouch Market Outlook
The aluminum-free food pouch category is repositioning around a sharp split between premium mono-material solutions certified for store-drop recycling and commodity-grade plastic laminates competing on unit cost. Amcor Limited leverages its global film extrusion footprint to supply certified recyclable structures to European retail chains. Mondi Group anchors its position through integrated kraft paper and barrier coating operations that bypass aluminum entirely. Berry Plastic Corporation competes with high-volume blown film capacity serving North American snack producers seeking cost-neutral aluminum replacement.
Aluminum-free food pouches are flexible primary packages constructed from polymer films, paper substrates, or biodegradable laminates that exclude aluminum foil barrier layers, typically achieving oxygen transmission rates below 1 cc/m²/day through metallized or oxide-coated alternatives. Their commercial purpose centers on shelf-stable food protection while enabling mechanical recyclability or industrial compostability streams. Stand-up pouches lead volume adoption due to shelf presence and dosing convenience, though flat pouches command tighter margins in single-serve beverage applications where material minimization drives cost. Biodegradable materials represent the fastest-growing structural segment as German and French food manufacturers face extended producer responsibility mandates, while composite structures still dominate where moisture and oxygen barriers must match legacy aluminum performance.
The EU Green Deal and F-Gas Regulation are reshaping material specifications across European packaging supply chains, with EFSA migration limits additionally constraining adhesive and coating chemistries in food-contact layers. The US FDA maintains substance-by-substance clearance pathways for novel barrier polymers, creating asynchronous market access timelines between jurisdictions. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York, where aluminum-free claims face emerging greenwashing enforcement standards.
Market Dynamics
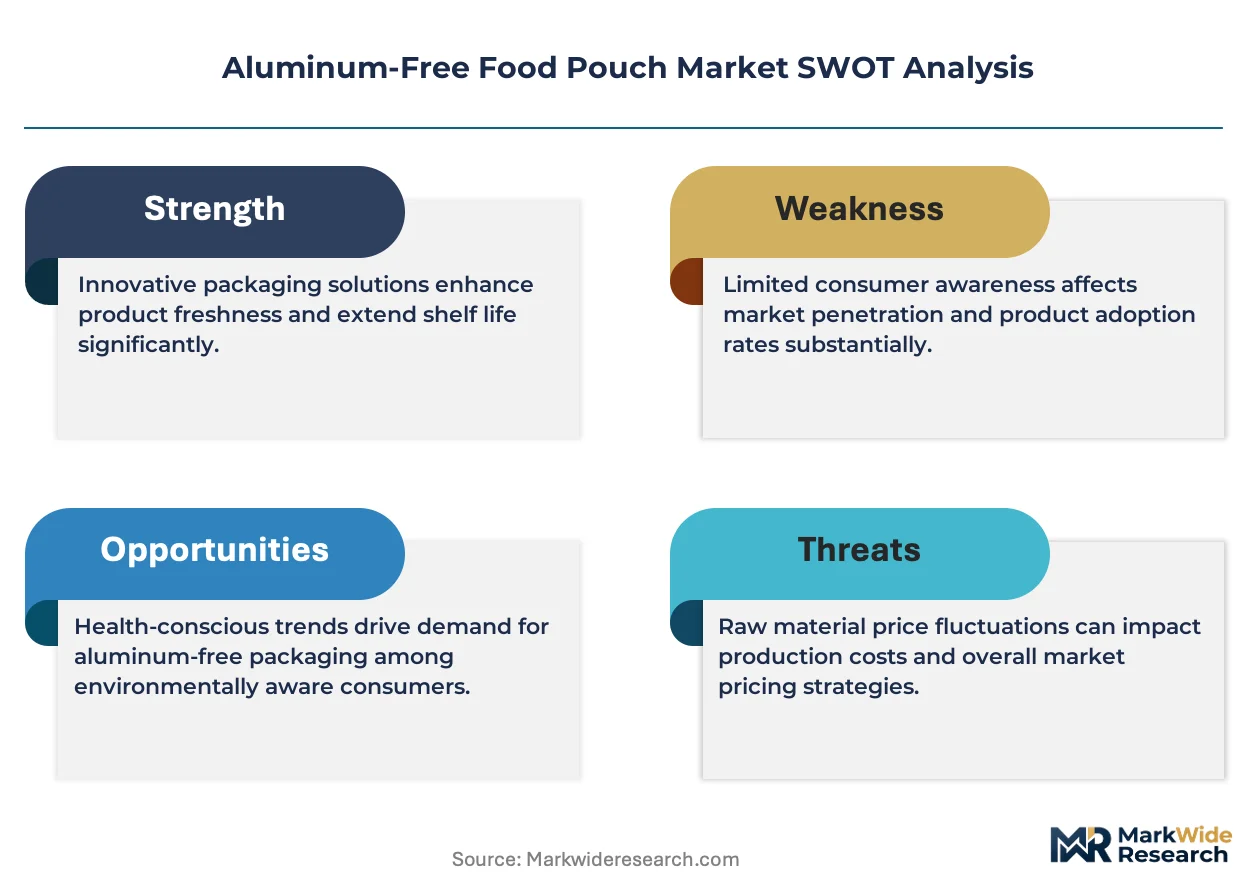
Mono-material barrier technology is consolidating around certified recyclable structures as the EU Green Deal and F-Gas Regulation force aluminum substitution across European retail supply chains, compressing legacy multilayer specifications.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility rules in Germany and France compel food manufacturers to eliminate aluminum foil layers from shelf-ready formats.
- Store-drop recycling certification:Retail chains now require How2Recycle and OPRL labels, pulling mono-material pouches into premium private-label programs.
- Metallized PET barrier films:Oxide-coated polyester achieves sub-1 cc/m²/day oxygen transmission, matching legacy aluminum performance at comparable unit economics.
Market Restraints
- Ethylene-vinyl alcohol resin supply concentration:Japanese and South Korean polymer suppliers control high-barrier EVOH grades, exposing converters to input cost volatility.
- EFSA migration limit compliance:Food-contact adhesive chemistries face tightening European Food Safety Authority scrutiny, extending qualification timelines.
- Glass and rigid plastic substitution:Premium organic baby food brands retain aluminum-free glass jars for perceived safety, capping pouch penetration in infant nutrition.
Strategic Opportunities
- Italian retail private-label expansion:Coop Italia and Conad are mandating aluminum-free formats across store-brand prepared meals, creating volume anchors for certified suppliers.
- Industrial compostable laminates:Home-compostable barrier films certified to TÜV OK Compost HOME open shelf-stable pet food applications.
- California SB 54 implementation:Extended producer responsibility legislation creates compliance-driven demand for mono-material structures in West Coast snack distribution.
Industry Challenges
- High-speed form-fill-seal retrofit requirements:Converting from aluminum-barrier to mono-material web tension demands capital-intensive line reconfiguration.
- Multi-jurisdiction certification complexity:Asynchronous FDA substance-by-substance clearances and EFSA renewal cycles delay synchronized product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum-Free Food Pouch Market |
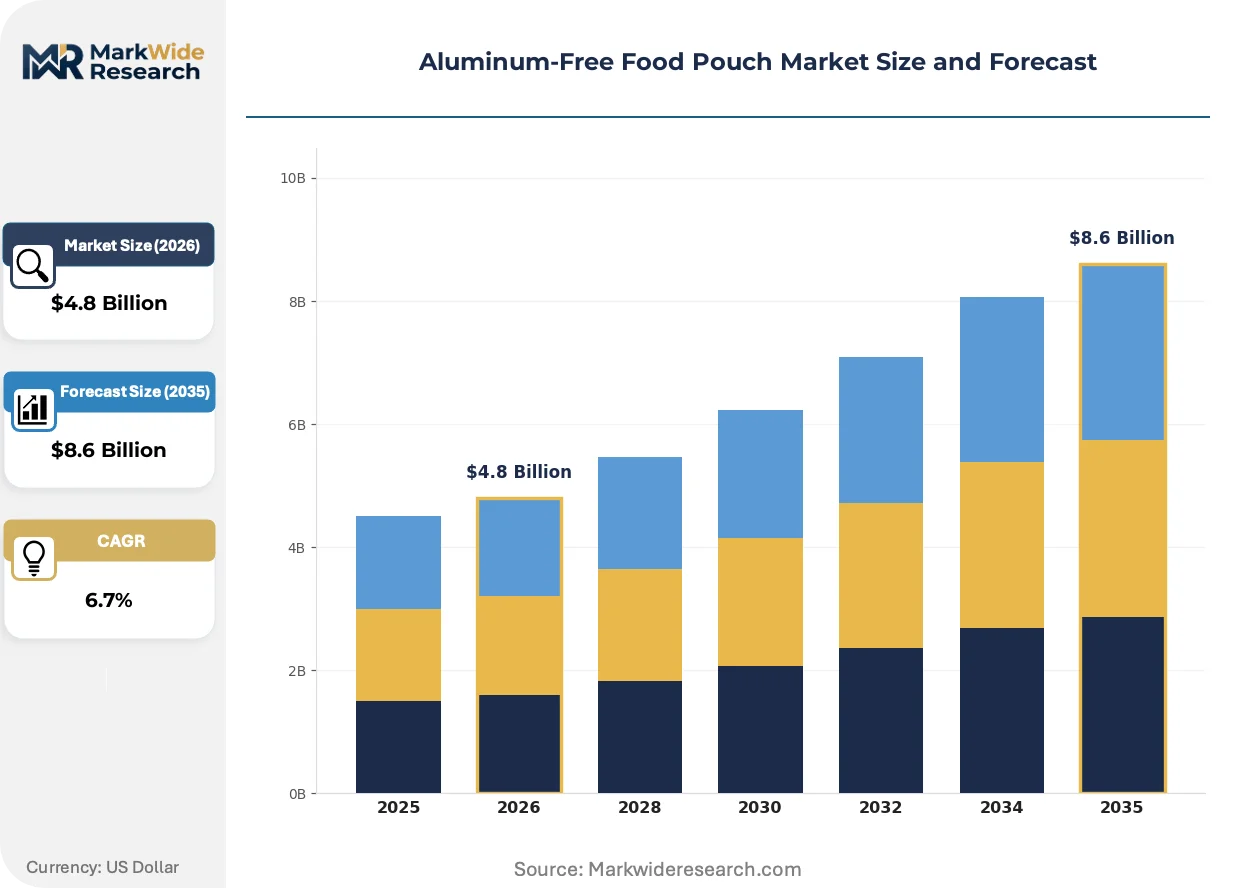
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Paper, Biodegradable, Composite Closure Type: Zipper, Tear Notch, Resealable, Heat Seal End User: Food Manufacturers, Beverage Companies, Snack Producers, Retailers Packaging Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Vacuum Sealed Pouches |
| Companies Covered | Amcor Limited, Bemis Company, Inc., Sealed Air Corporation, Astrapak Limited, Berry Plastic Corporation, Covers, Mondi Group, Sonoco, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum-Free Food Pouch Market Strategic Shifts
Barrier coating chemistry and substrate engineering are converging to displace aluminum foil without sacrificing shelf stability, reshaping material specifications across infant nutrition, pet food, and ready-to-eat meal segments.
High-barrier oxide-coated films are consolidating technical specifications around silicon oxide and aluminum oxide vapor-deposited layers. European organic baby food producers are qualifying these structures for twelve-month shelf life at accelerated adoption rates. This consolidation is compressing demand for legacy metallized films and forcing coating equipment suppliers to expand deposition capacity.
REACH and F-Gas Regulation restrictions on fluorinated greenhouse gases are eliminating perfluorinated barrier coatings from food-contact applications. Industrial consequence includes accelerated R&D spending on bio-based barrier polymers. German and French converters are most affected, pivoting toward water-based coating systems ahead of enforcement deadlines.
Retail procurement specifications now embed recyclability certification as a gate criterion for shelf placement. Private-label buying committees are displacing open-specification tendering with pre-qualified mono-material vendor pools. This pattern is most visible in Italian and Spanish supermarket chains consolidating supplier bases around certified structures.
Aluminum-Free Food Pouch Market Segmentation
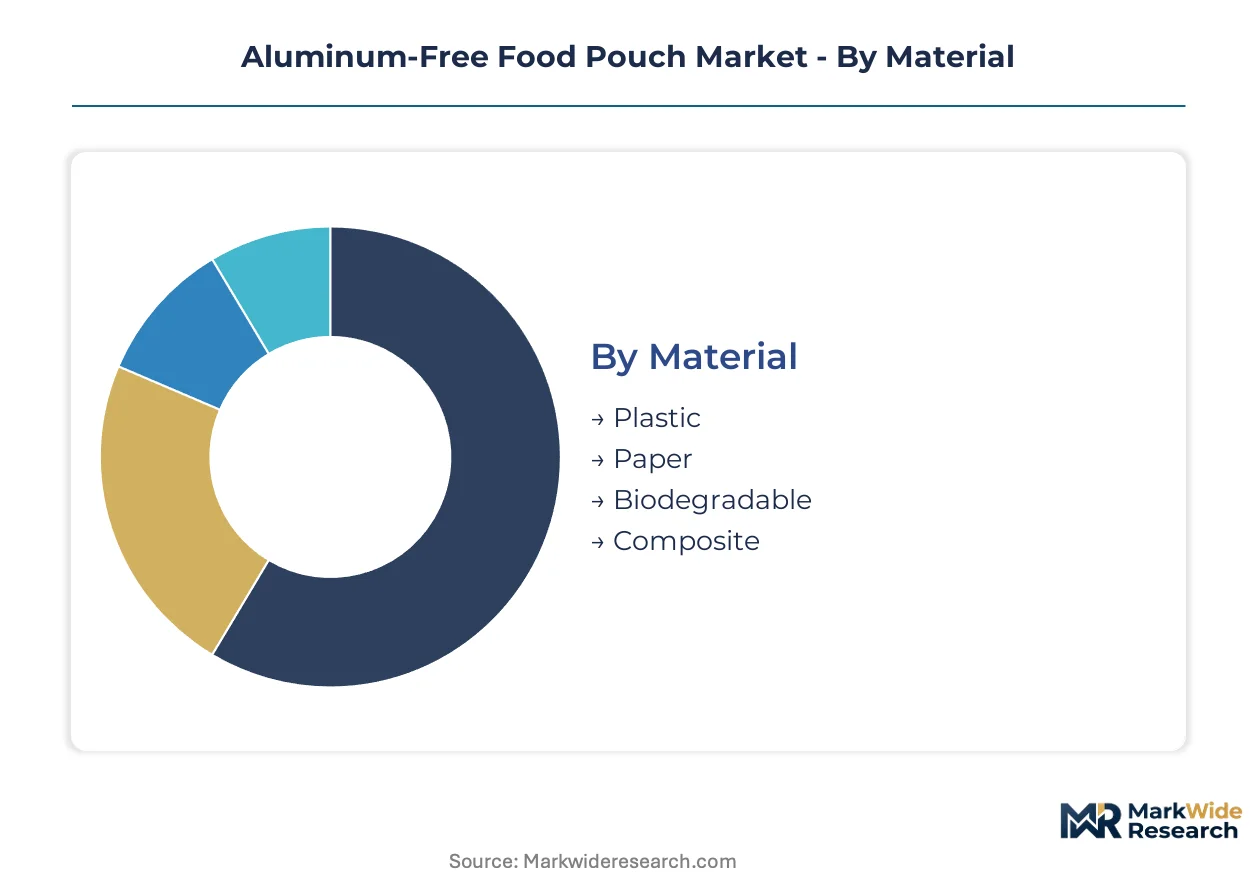
Material selection determines barrier performance and recyclability certification, the two non-negotiable gate criteria for retail shelf placement. Closure engineering and pouch geometry then modulate unit economics and consumer convenience across divergent end-use workflows.
Material:
Buyers prioritize barrier-to-cost ratios against specific shelf-life targets and regional recycling infrastructure.
- Plastic:Multi-layer polyethylene and polypropylene laminates deliver sub-1 cc/m²/day oxygen transmission through metallized or oxide-coated layers. German and French private-label retailers specify certified mono-material PE structures for store-drop recycling compliance under EU Green Deal mandates.
- Biodegradable:Industrial and home-compostable films certified to TÜV OK Compost HOME standards are climbing the fastest as extended producer responsibility rules tighten across Europe. PLA and PBAT blends serve shelf-stable pet food and organic meal kit applications where end-of-life differentiation commands premium positioning.
- Paper:Fiber-based substrates with water-based barrier coatings bypass aluminum and plastic entirely. Italian retail chains source kraft-paper pouches for dry goods where moisture sensitivity is moderate.
- Composite:Hybrid polymer-paper laminates balance printability with heat-seal integrity. North American snack producers specify these for high-speed form-fill-seal lines requiring web tension tolerance.
Plastic leads on scale; biodegradable leads on momentum.
Closure Type:
Line speed requirements and reseal functionality expectations split procurement specifications across ambient and refrigerated supply chains.
- Zipper:Press-to-close interlocking profiles enable multi-dose consumption for family-size formats. Berry Plastic Corporation supplies slider-integrated zipper webs to North American snack producers running 200+ pouches per minute.
- Tear Notch:Laser-scored opening features minimize material overhead for single-serve beverage and condiment applications. Flat pouch configurations in this closure type dominate unit-cost-sensitive commodity segments.
- Resealable:Adhesive strip or mechanical latch systems bridge zipper performance with heat-seal simplicity. Pet food manufacturers specify these for multi-pound formats requiring portion control without zipper machinery capital.
- Heat Seal:Plain top-seal structures maximize material efficiency and line speed. Prepared meal producers in Italy and Spain default to this closure for cook-chill distribution where reseal is irrelevant.
Heat seal dominates volume throughput; zipper commands the widest price premium.
End User:
Formulation sensitivity and brand positioning intensity dictate barrier specification stringency and certification investment levels.
- Food Manufacturers:Organic baby food producers drive qualification of oxide-coated barrier films for twelve-month shelf stability. These buyers mandate How2Recycle or OPRL labels as procurement preconditions.
- Retailers:Private-label buying committees at Coop Italia and Conad consolidate supplier bases around pre-certified mono-material pools. Their specification power is compressing converter margins while locking in volume anchors.
- Snack Producers:High-volume blown film demand prioritizes cost-neutral aluminum replacement over recyclability certification. California SB 54 compliance is now redirecting some procurement toward certified structures.
- Beverage Companies:Flat pouch configurations for single-serve concentrates emphasize material minimization and dosing precision. Migration limit compliance under EFSA scrutiny extends adhesive qualification timelines for these buyers.
Food manufacturers set the technical standard; retailers set the certification gate.
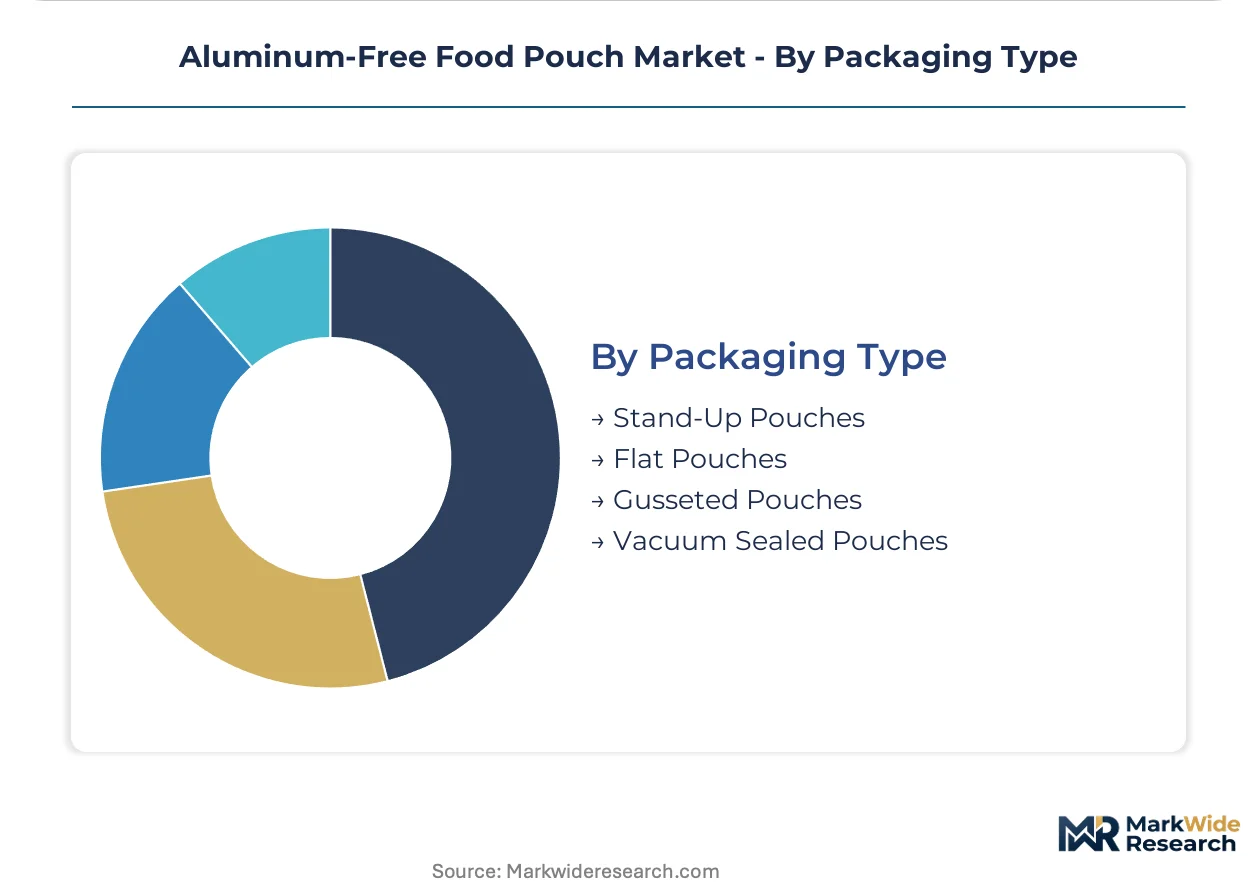
Packaging Type:
Shelf presence requirements and dosing ergonomics determine geometry selection against filling line retrofit constraints.
- Stand-Up Pouches:Doyen-style bottom gussets provide vertical shelf presence and stable dispensing. This geometry leads volume adoption across infant nutrition and pet food where brand visibility at point-of-sale justifies material premium.
- Flat Pouches:Two-seal configurations minimize material use for single-serve beverages and condiments. Tighter margins in this segment reflect intense price competition and lower barrier specification tolerance.
- Gusseted Pouches:Side-gusset expansion accommodates bulk dry goods and coffee with minimal headspace. Italian coffee roasters specify these for aroma retention without aluminum valve structures.
- Vacuum Sealed Pouches:High-barrier coextrusions enable extended shelf life for cured meats and prepared meals. EFSA migration limits on food-contact adhesives particularly constrain this segment's qualification cycles.
Stand-up pouches anchor revenue concentration; vacuum sealed pouches face the steepest regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and polymer chemists concentrate in Germany's industrial belt, Italy's Emilia-Romagna corridor, and California's Central Valley food-tech cluster, anchoring regional innovation capacity for aluminum-free barrier solutions.
Germany
Private-label retailers at Rewe and Edeka mandate aluminum-free formats across store-brand prepared meals and organic baby food lines. The EU Green Deal and extended producer responsibility rules under the Packaging Act force converters to eliminate multilayer aluminum-barrier specifications. Düsseldorf and Hamburg host the densest converter networks, where oxide-coated film qualification cycles compress legacy metallized film demand.
France
Carrefour and Intermarché buying committees pre-qualify mono-material pouches for shelf placement, pulling certified structures into premium private-label programs. EFSA migration limits on food-contact adhesives extend qualification timelines for high-barrier laminates. Lyon and Paris basin converters pivot toward water-based coating systems ahead of F-Gas Regulation enforcement deadlines on fluorinated barrier chemistries.
Italy
Coop Italia and Conad consolidate supplier bases around certified mono-material pools for store-brand pasta sauces and ready-to-eat meals. The EU Green Deal accelerates substitution away from aluminum-valve coffee pouches in favor of oxide-coated alternatives. Bologna and Modena anchor the packaging machinery cluster where form-fill-seal line retrofits for mono-material web tension concentrate.
United States
California SB 54 implementation drives compliance demand for mono-material structures in West Coast snack and beverage distribution. The FDA maintains substance-by-substance clearance pathways for novel barrier polymers, creating asynchronous market access versus European timelines. Chicago and Minneapolis-St. Paul host blown film capacity serving North American producers seeking cost-neutral aluminum replacement.
United Kingdom
Tesco and Sainsbury's procurement specifications embed OPRL recyclability certification as a gate criterion for aluminum-free pouch placement. Post-Brexit regulatory divergence from EU F-Gas Regulation creates uncertainty for fluorinated coating phase-out timelines. Manchester and Birmingham converters specialize in kraft-paper barrier pouches for dry goods where moisture sensitivity remains moderate.
Aluminum-Free Food Pouch Market Competitive Environment
Capital-heavy integrated film producers compete with asset-light packaging designers and regional converters, creating a tiered structure where scale and certification access determine tier placement. The vendor base splits between global film extruders with certified recyclable portfolios, paper-based substrate specialists leveraging integrated kraft operations, and high-volume blown film suppliers serving cost-sensitive snack applications. Three archetypes dominate: integrated polymer producers controlling barrier coating deposition, paper-packaging converters bypassing aluminum through fiber engineering, and regional specialists retrofitting legacy form-fill-seal lines for mono-material web handling. Competitive moves concentrate on pre-qualification for retail private-label vendor pools and capacity expansion for oxide-coated film deposition.
Within the integrated polymer tier, Amcor Limited and Berry Plastic Corporation exemplify scale-driven positioning through global extrusion footprints and high-volume blown film operations respectively. Mondi Group occupies a distinct archetype as a paper-based substrate specialist leveraging integrated kraft and barrier coating operations that bypass aluminum entirely. These three companies anchor the competitive landscape by representing divergent technical pathways—polymer film certification, paper-fiber engineering, and volume cost engineering—through which aluminum-free barrier performance is commercialized.
| Leading Market Players |
|---|
| Amcor Limited |
| Bemis Company, Inc. |
| Sealed Air Corporation |
| Astrapak Limited |
| Berry Plastic Corporation |
| Covers |
| Mondi Group |
| Sonoco |
| Amcor plc |
| Others |
Value Chain & Pricing Dynamics
Polymer chemists and coating engineers concentrated in Germany's Ruhr industrial belt and Italy's Emilia-Romagna corridor create labor-cost differentials that widen pricing-tier spreads between certified mono-material structures and commodity-grade laminates.
Pricing Analysis
Certification-bundled pricing separates How2Recycle-certified mono-material pouches from uncertified commodity laminates competing on unit cost. Price differentiation rests on oxide-coated barrier performance tiers and retail chain vendor-prequalification status. Pricing pressure stems from EVOH resin supply concentration among Japanese and South Korean polymer suppliers. Snack producers in North America exhibit highest price sensitivity, while organic baby food manufacturers absorb premiums for twelve-month shelf-life certification.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's extended producer responsibility rules are reshaping sourcing toward European converter networks. Supply concentrates in Germany, France, and Italy for certified mono-material structures, with North American blown film capacity serving cost-sensitive snack applications. Raw material dependencies center on metallized PET films, EVOH barrier resins, and water-based adhesive chemistries. Single-source vulnerability runs through Japanese EVOH suppliers controlling high-barrier grades. Distribution runs through retail private-label buying committees pre-qualifying certified vendor pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through oxide-coated barrier technology cost-down curves and premium-tier consolidation around store-drop recyclability certification.
For Market Incumbents: Lock in retail private-label vendor pool pre-qualification at Rewe, Carrefour, and Coop Italia before qualification windows close. Expand oxide-coated film deposition capacity in Düsseldorf and Hamburg to capture German converter demand. Secure backward integration into metallized PET substrate supply to defend margins against resin cost volatility from Japanese polymer suppliers. For New Entrants and Emerging Players: Regional Italian converters represent the most penetrable channel partner type for certified mono-material pouch supply. Target industrial compostable laminates for German and French pet food applications where TÜV OK Compost HOME certification commands premium positioning. Enter through co-manufacturing arrangements with Bologna-area packaging machinery specialists retrofitting form-fill-seal lines. For Investors and Strategic Acquirers: Integrated paper-packaging specialists with captive kraft and barrier coating operations are the most active acquirer in this space. Five-to-ten-year viability favors converters with certified recyclable portfolios and retail chain vendor lock-ins. Watch Italian supermarket chain procurement consolidation as the inflection signal for volume-anchor availability.| Strategic Initiative | Industry Significance |
|---|---|
| Oxide-Coated Film Deposition Capacity Expansion | Captures German and French baby food producer qualification demand under EU Green Deal mandates. |
| Retail Private-Label Vendor Pool Pre-Qualification | Locks in volume anchors with Coop Italia and Conad specification power. |
| Water-Based Barrier Coating R&D Pivot | Anticipates F-Gas Regulation enforcement eliminating fluorinated chemistries. |
| California SB 54 Compliance Certification | Opens West Coast snack and beverage distribution channels. |
| Industrial Compostable Laminate Qualification | Targets German extended producer responsibility mandates for pet food applications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged polymer chemists at German and Italian converter facilities, retail private-label buying committee members at Rewe and Carrefour, packaging machinery engineers in Bologna and Modena, and food manufacturer procurement leads at organic baby food producers. Secondary validation drew from EU Packaging Act regulatory filings, EFSA migration limit documentation, How2Recycle certification databases, and trade customs data for metallized PET and EVOH resin flows. Bottom-up volume modeling triangulated against top-down market sizing across material, closure, end-user, and packaging-type segments.
Historical reference periods anchored the projection horizon to pre- and post-EU Green Deal implementation phases. The analytical framework modeled demand across plastic, biodegradable, paper, and composite material tiers; zipper, tear notch, resealable, and heat-seal closure types; food manufacturer, retailer, snack producer, and beverage company end-users; and stand-up, flat, gusseted, and vacuum-sealed pouch geometries. CAGRs derived from segment-level growth rate reconciliation with macro packaging demand indicators. Forecast inputs incorporated EVOH resin price elasticity and retail chain certification mandate rollout timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation enforcement timing and EFSA adhesive chemistry restriction expansion. Forecasts reflect documented assumptions regarding oxide-coated barrier film performance maturation and extended producer responsibility rule harmonization across EU member states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Wrap-Around Packers Market
Pouch
Europe Retort Pouches Market
Pouch
2 Seal Pouches Market
Pouch
Twin Pouch Packaging Market
Pouch
Spouted Pouches Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Feed Pouches Market
Pouch
Heat Seal Pouch Market
Pouch
Latin America Pouch Packaging Market
Pouch
Foil Pouch Packaging Market
Pouch
Benelux Pouch Packaging Market
Pouch
Vented Stretch Wrap Market
Pouch
Global Pre Zippered Pouches Market
Pouch
Self-Seal Pouches Market
Pouch
Kraft Pouch Market
Pouch
Foam Pouch Market