
 UAE Pouch Packaging Market | 2026-2036
UAE Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Pouch Packaging Market Insights
Premium-grade multilayer barrier specifications are rotating through the UAE pouch packaging landscape as brands seek extended shelf stability for ambient distribution. Huhtamaki Oyj leverages its regional converting footprint to supply high-barrier retort formats to dairy and meat processors. Swiss Pac UAE anchors customized digital-print pouch volumes for emerging F&B startups seeking shorter runs. Hotpack Global dominates the foodservice disposables-to-flexibles extension, supplying hotels and airline caterers across the Gulf.
Pouch packaging denotes a flexible primary container formed from laminated films, sealed on three or four sides, with functional parameters including oxygen transmission rates below 0.1 cc/m²/day for retort applications and seal strengths exceeding 15 N/15mm for liquid containment. Stand-up pouches with spouted fitments lead consumer shelf presence in the UAE's retail environment, while vacuum pouches sustain margin pools in red meat and seafood export processing. Composites comprising polyethylene terephthalate, aluminum oxide-coated polyethylene, and cast polypropylene capture growing share as brands replace conventional metal cans for convenience meals.
MOHAP's food-contact notification requirements and the Emirates Authority for Standardization and Metrology's UAE.S GSO standards govern migration limits and label claims for pouch structures entering the local supply chain. The UAE's mandatory halal certification protocols, administered by accredited bodies under the Emirates International Accreditation Centre, shape material selection and production line segregation for converters serving Islamic markets. Stakeholders must monitor Dubai Municipality's evolving sustainable packaging mandates, as single-use plastic restrictions are forcing laminate redesign toward paper-based and mono-material alternatives.
Market Dynamics
MOHAP's tightening food-contact material protocols are compressing import clearance timelines for laminate structures, forcing converters toward localized compounding and halal-segregated production lines.
Growth Catalysts
- Retort pouch line expansion:Food and beverage processors in Dubai and Abu Dhabi are scaling ready-to-eat meal formats, pulling demand for high-barrier multilayer films.
- UAE.S GSO migration standards:The Emirates Authority for Standardization and Metrology's updated limits are certifying local converters for Gulf Cooperation Council export eligibility.
- Jebel Ali corridor concentration:Converting capacity clustering along this industrial belt generates scale economies for regional flexible packaging supply.
Market Restraints
- Aluminum oxide-coated polyethylene input volatility:Specialty barrier film raw materials face price swings tied to petrochemical feedstock fluctuations.
- Single-supplier reliance for digital print substrates:Swiss Pac UAE and comparable converters depend on narrow imported substrate channels.
- Halal certification timeline friction:Emirates International Accreditation Centre body audits extend production line qualification periods.
Strategic Opportunities
- Abu Dhabi industrial zone expansion:KIZAD free zone incentives are attracting mono-material pouch pilot lines for paper-based laminate alternatives.
- Airline catering channel growth:Hotpack Global's foodservice extension model demonstrates scalable fitment-integrated formats for premium travel segments.
- Dubai Municipality sustainable packaging mandates:Pending single-use plastic restrictions will force laminate redesign toward recyclable structures.
Industry Challenges
- High-barrier film metallization skill scarcity:Vacuum deposition technicians with aluminum oxide process expertise command premium wages in the Emirates.
- Retort validation capex intensity:Steam sterilization compatibility testing for new laminate recipes requires dedicated pilot retort installations.
- Legacy gravure-to-digital workflow integration:Converters managing hybrid print floors face color management system incompatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Pouch Packaging Market |
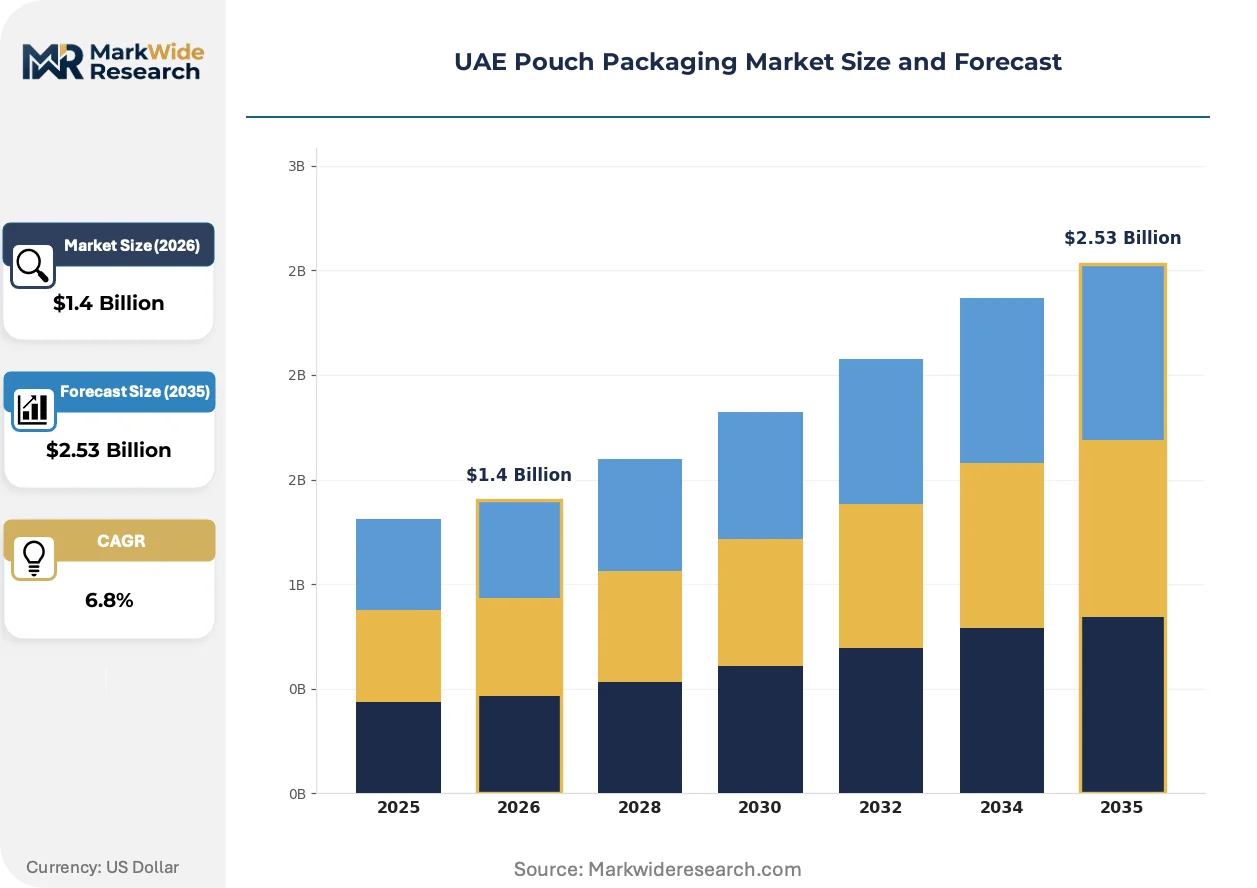
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zip Pouches, Vacuum Pouches Material: Plastic, Paper, Aluminum, Composites End User: Food & Beverages, Personal Care, Pharmaceuticals, Chemicals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Huhtamaki Oyj, Swiss Pac UAE, Amber Packaging LLC, Radiant Packaging Industry LLC, ENPI Group, Integrated Plastics Packaging, Arabian Flexible Packaging LLC, Hotpack Global, Falcon Pack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Pouch Packaging Market Trends and Innovations
Active packaging formats and digital production workflows are compressing run-length economics while regulatory pressure on plastic substrates accelerates material substitution timelines.
Aluminum oxide vapor-deposited polyethylene terephthalate films deliver oxygen transmission barriers below 0.1 cc/m²/day without foil lamination. Dairy and meat processors in Sharjah are qualifying these structures for ambient distribution. The technology is miniaturizing conventional retort pouch thickness profiles while maintaining 18-month shelf stability.
MOHAP's 2024 food-contact notification overhaul requires pre-import submission of full laminate layer compositions and migration test data. Converters now maintain dedicated regulatory affairs staff to manage documentation. Small F&B startups are delaying product launches pending clearance, favoring established suppliers with validated dossiers.
Airline caterers and hotel procurement departments are consolidating pouch specifications toward fitment-integrated stand-up formats with spouted closures. Swiss Pac UAE's digital print capacity captures these shorter-run, SKU-proliferated orders. Dubai's hospitality procurement concentration makes this channel the decisive testbed for premium pouch innovation.
UAE Pouch Packaging Market Segmentation
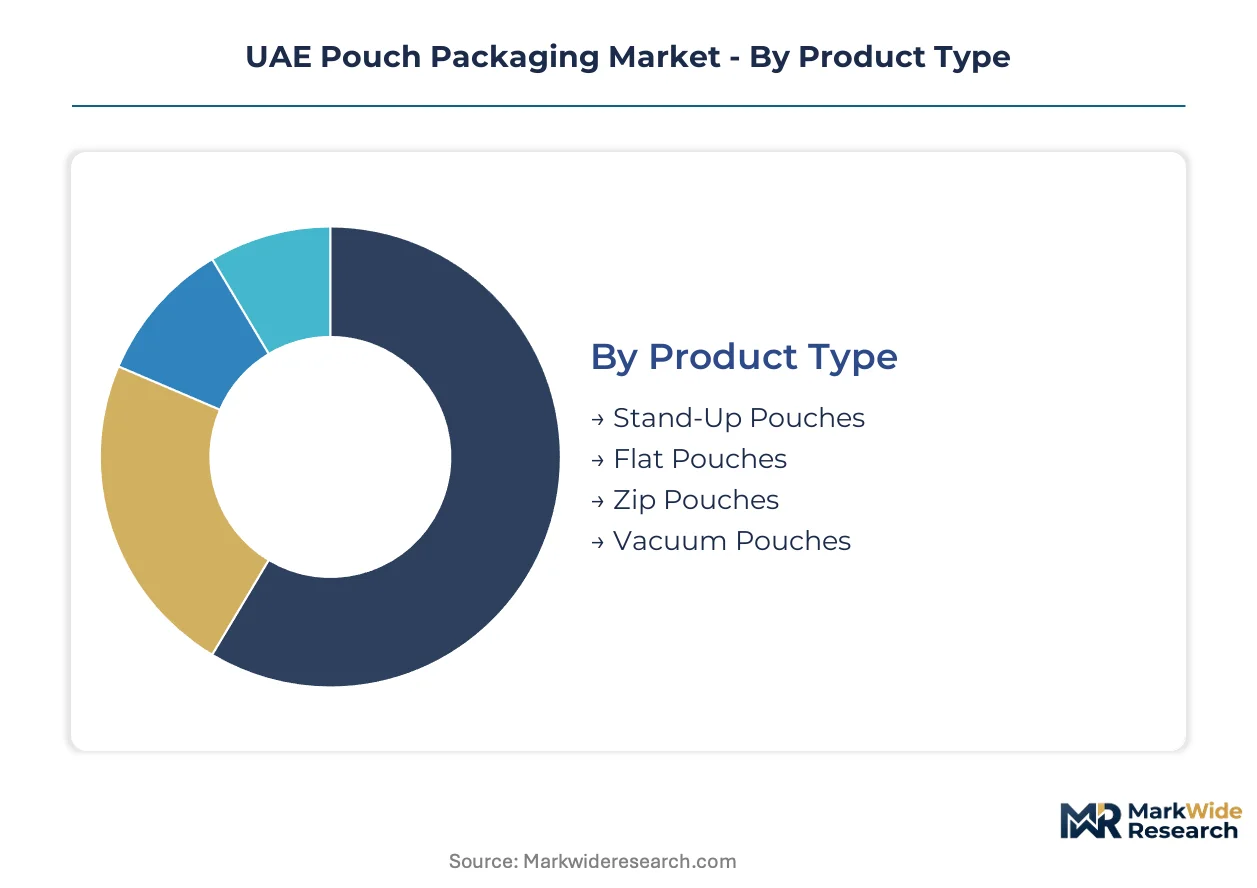
UAE pouch packaging segmentation reveals how MOHAP compliance requirements and halal certification protocols reshape procurement patterns across product formats and material stacks. Distinct technical specifications govern each category's eligibility for food-contact applications in Dubai and Abu Dhabi.
Product Type:
MOHAP's food-contact notification protocols apply differential testing burdens based on pouch geometry and seal configuration.
- Stand-Up Pouches:Bottom-gusseted structures with spouted fitments dominate Dubai retail shelves. Emirates Authority for Standardization and Metrology certification for these formats concentrates in Jebel Ali corridor converters serving hotel and airline catering procurement.
- Flat Pouches:Three-side-sealed laminates with oxygen transmission rates below 0.1 cc/m²/day anchor red meat and seafood export processing. Sharjah processors qualify these structures for 18-month ambient distribution to Gulf Cooperation Council markets.
- Zip Pouches:Reclosure fitments add seal-strength validation requirements under UAE.S GSO standards.
- Vacuum Pouches:Four-side-sealed formats sustain margin pools in protein export channels with high-barrier metallized specifications.
Stand-up pouches handle the majority of throughput; flat pouches are expanding most quickly on share as retort-ready formats displace metal cans.
Material:
Cost tiers separate commodity substrates from specialty barrier laminates requiring dedicated compounding lines.
- Plastic:Polyethylene terephthalate and cast polypropylene laminates form the volume base. Dubai Municipality's pending single-use plastic restrictions are forcing converters toward mono-material redesigns.
- Composites:Aluminum oxide-coated polyethylene structures deliver foil-free barriers for halal-segregated production. KIZAD free zone pilot lines are qualifying paper-based alternatives here.
- Paper:Fiber-based substrates with bio-polymer barriers attract sustainability-mandated procurement from Emirates airline caterers.
- Aluminum:Conventional foil laminations face displacement as aluminum oxide vapor deposition achieves equivalent barrier performance at reduced thickness.
Plastic substrates command current volume; composites are gaining share fastest as migration-compliant structures penetrate premium segments.
End User:
Application-specific validation timelines stretch from 90 days for industrial chemicals to 18 months for pharmaceutical primary packaging.
- Food & Beverages:Ready-to-eat meal retort formats and ambient dairy structures drive laminate innovation. Abu Dhabi processors are scaling high-barrier lines for GCC export eligibility.
- Pharmaceuticals:Blister-compatible pouch formats for unit-dose compliance packaging carry Emirates International Accreditation Centre audit requirements for production line segregation.
- Personal Care:Spouted stand-up formats for hotel amenities concentrate demand in Dubai's hospitality procurement cluster.
- Chemicals:Industrial lubricant and agrochemical pouches require chemical resistance validation under less stringent notification protocols.
Food and beverages handles the majority of throughput; pharmaceuticals is climbing the fastest as compliance packaging demand accelerates.
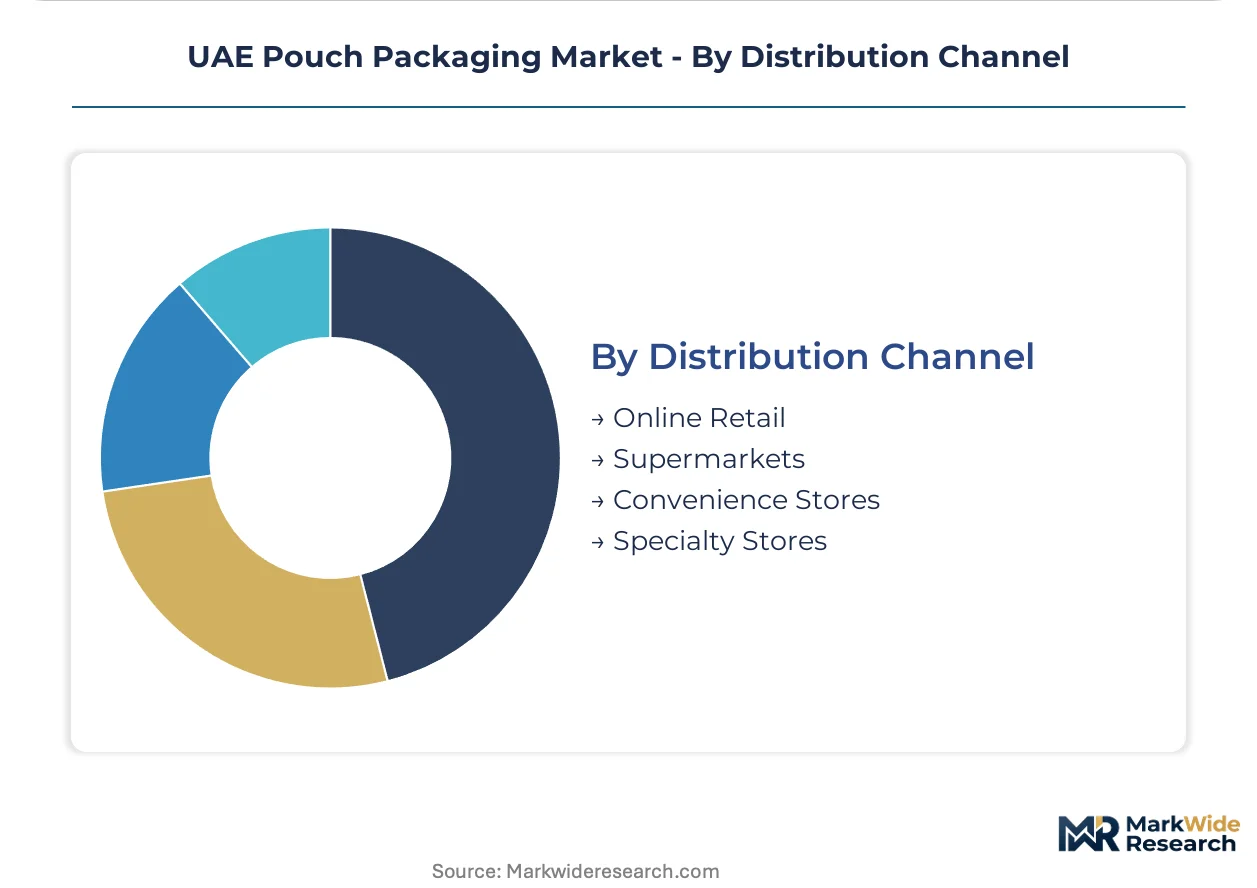
Distribution Channel:
Customer type determines run-length economics and print technology selection across digital and gravure workflows.
- Supermarkets:High-volume gravure-printed formats with standardized graphics dominate Carrefour and Lulu procurement in Dubai.
- Online Retail:Shorter-run digital print with SKU-proliferated graphics serves emerging F&B startup brands. Swiss Pac UAE capacity concentrates here.
- Convenience Stores:Single-serve portion formats with price-optimized specifications serve petrol station retail networks.
- Specialty Stores:Premium gift and organic food channels demand tactile finishes and metallic effects on limited editions.
Supermarkets handle the majority of throughput; online retail is gaining share fastest as direct-to-consumer brands proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Sharjah's protein processing corridor exhibit acute price sensitivity on commodity flat pouches, while Dubai's hospitality procurement clusters absorb premium markups for fitment-integrated stand-up formats without volume elasticity.
Dubai
Jebel Ali's converting belt anchors high-barrier retort capacity serving GCC export channels. Dubai Municipality's pending single-use plastic restrictions are accelerating laminate redesign toward paper-based mono-materials. Hotel and airline caterers in the emirate's procurement cluster drive specification consolidation toward spouted stand-up formats.
Abu Dhabi
KIZAD free zone incentives attract pilot lines for sustainable pouch alternatives as processors scale ready-to-eat meal formats. MOHAP's food-contact notification protocols compress import clearance timelines for laminate structures. Industrial zone expansion concentrates mono-material qualification capacity for ambient dairy distribution.
Sharjah
Red meat and seafood export processors sustain margin pools in vacuum pouch formats with metallized barrier specifications. Emirates Authority for Standardization and Metrology certification requirements shape local converter investment in migration testing infrastructure. The emirate's protein processing corridor qualifies flat pouches for 18-month ambient GCC distribution.
Northern Emirates
Ras Al Khaimah and Fujairah host emerging converting capacity targeting price-optimized convenience store segments. Halal certification timeline friction from Emirates International Accreditation Centre audits extends production line qualification. Smaller converters in these emirates serve petrol station retail networks with single-serve portion specifications.
UAE Pouch Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UAE pouch packaging landscape. The market structure tilts toward consolidated high-barrier specialists and fragmented commodity converters serving distinct procurement tiers. Three archetypes dominate: multinational laminate technology licensors, regional digital-print specialists, and integrated foodservice-to-flexibles operators. Capacity expansion and halal-segregated production line qualification represent the dominant competitive moves as MOHAP protocols tighten.
Within the multinational technology tier, Huhtamaki Oyj occupies a position exemplifying high-barrier retort supply to dairy and meat processors. Swiss Pac UAE represents the digital-print specialist archetype, anchoring customized shorter-run capacity for emerging F&B startups. Hotpack Global sits within the integrated foodservice extension model, demonstrating scalable fitment-integrated formats for premium travel and hospitality segments.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Swiss Pac UAE |
| Amber Packaging LLC |
| Radiant Packaging Industry LLC |
| ENPI Group |
| Integrated Plastics Packaging |
| Arabian Flexible Packaging LLC |
| Hotpack Global |
| Falcon Pack |
| Others |
Pricing and Supply Chain Analysis
Aluminum oxide vapor-deposited polyethylene terephthalate displacement of conventional foil laminates simultaneously concentrates supply geography around Jebel Ali corridor converters and compresses pricing premiums for high-barrier specifications. This substitution dynamic restructures procurement economics as halal-segregated production lines capture margin pools previously distributed across imported metallized substrates.
Pricing Analysis
After-sales technical service and retort validation support drive lifetime value for pouch converters serving Abu Dhabi dairy processors. Three-tier pricing structure across premium, standard, and economy levels separates MOHAP-validated halal lines from commodity gravure-printed formats and uncoated polyethylene commodity tiers. Cost compression in standard-grade laminates is intensifying because Sharjah protein processors negotiate volume aggregations across GCC export channels. Small F&B startups exhibit acute price sensitivity; airline caterers absorb premium markups for fitment-integrated formats without volume elasticity.
Supply Chain Analysis
Strategic stockpiling of aluminum oxide-coated polyethylene substrates dominates converter inventory strategy as petrochemical feedstock volatility disrupts just-in-time procurement. Raw material sourcing draws from Saudi Arabia's petrochemical base, South Korea's biaxially oriented film capacity, and China's metallized substrate exports. Single-source vulnerability concentrates in digital print substrate channels where Swiss Pac UAE and comparable converters rely on narrow imported supply lines. Distribution runs through Jebel Ali industrial corridor warehousing with direct-to-processor fulfillment for retort-ready laminates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's 2024 food-contact notification overhaul constitutes a regulatory inflection that accelerates market disruption by disqualifying import-dependent converters and rewarding localized halal-segregated capacity.
For Market Incumbents: Shield margin pools by deepening backward integration into aluminum oxide vapor deposition equipment and captive halal-segregated compounding lines. Incumbent converters face substitution threat from KIZAD free zone pilot lines qualifying paper-based mono-material alternatives; priority lever sits with securing Emirates International Accreditation Centre pre-approval for laminate layer compositions before import clearance timelines compress further. For New Entrants and Emerging Players: Differentiate on digital print workflow integration for SKU-proliferated airline catering and hospitality procurement channels. White-space targets concentrate in online retail shorter-run formats and Northern Emirates convenience store single-serve specifications. Go-to-market angle centers on MOHAP dossier-ready laminate recipes that bypass established suppliers' validation queues. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with halal-certified production infrastructure. Long-term viability favors converters controlling both metallization technology and regulatory affairs capabilities. Acquisition target archetype: mid-cap Jebel Ali corridor operators with validated migration testing infrastructure. Signal to watch is Emirates Authority for Standardization and Metrology certification queue length as proxy for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Halal-Segregated Production Line Qualification | Emirates International Accreditation Centre pre-approval compresses competitor import clearance timelines. |
| Aluminum Oxide Vapor Deposition Capacity Addition | Jebel Ali corridor converters capture foil-displacement margin pools in dairy and meat processing. |
| Digital Print Workflow Integration | Swiss Pac UAE model demonstrates scalable capture of SKU-proliferated hospitality procurement. |
| Mono-Material Laminate Pilot Line Investment | KIZAD free zone incentives attract paper-based alternatives ahead of Dubai Municipality plastic restrictions. |
| Retort Validation Infrastructure Buildout | Steam sterilization compatibility testing secures 18-month ambient distribution eligibility for GCC export. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Jebel Ali corridor converters, procurement leads at Abu Dhabi dairy processors, MOHAP regulatory affairs officers, and airline catering supply chain directors; and secondary validation through Emirates Authority for Standardization and Metrology certification databases, UAE customs import records for laminate structures, and Dubai Municipality sustainable packaging mandate disclosures. Bottom-up capacity aggregation across Sharjah protein processing facilities and top-down demand estimation from GCC export channel volumes were triangulated against MOHAP food-contact notification clearance data.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation dimensions spanning pouch geometry, material stack composition, end-use application validation timelines, and distribution channel run-length economics. CAGRs were derived from laminate throughput trajectories at converting capacity clusters and substitution elasticity estimates for aluminum oxide deposition versus conventional foil. Industry-specific forecast inputs incorporated halal certification timeline friction from Emirates International Accreditation Centre audit queues and Dubai Municipality single-use plastic restriction implementation phasing.
The analysis sits within stated boundaries; outcomes outside sustained MOHAP enforcement intensity or petrochemical feedstock price stability would require recalibration. Forecasts reflect documented assumptions regarding GCC export channel expansion and airline catering procurement consolidation. Revision becomes warranted when KIZAD free zone pilot line qualification rates or Northern Emirates halal certification backlog durations cross threshold inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Sterilization Pouches Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market
Pouch
Poland Pouch Packaging Market
Pouch
Slider Pouches Market
Pouch
Utility Pouches Market
Pouch
United States Retort Pouches Market
Pouch
Spouted Pouches Market
Pouch
Fin Seal Pouches Market
Pouch
Liquid Pouch Packaging Market
Pouch
Liquid Pouch Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Pouch Dispensing Fitment Market