
 Vacuum Chamber Pouches Market | 2026-2036
Vacuum Chamber Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Chamber Pouches Market Analytics
EU REACH compliance is consolidating the cost-of-entry calculus for vacuum chamber pouch suppliers targeting European food processors. Sealed Air Corporation leverages its captive film extrusion network to sustain margin control across high-barrier nylon lines. Amcor Plc anchors its position through integrated printing and forming operations that compete on custom printed packaging for branded protein processors. Mondi Group Plc differentiates via biodegradable plastics development that navigates tightening packaging waste directives without performance trade-offs.
Vacuum chamber pouches are flexible packaging structures engineered from multi-layer coextruded films—typically combining polyethylene sealant layers with nylon or ethylene vinyl alcohol barrier substrates—to achieve oxygen transmission rates below 1 cc/m²/day under vacuum conditions. Their primary purpose is to evacuate atmospheric gases from food, medical, or industrial contents, then hermetically seal the package to inhibit oxidation, microbial growth, and moisture ingress. Gusseted pouches occupy the largest volume share in food processing applications where standing presentation and expanded capacity matter, while biodegradable plastics represent the fastest-expanding material category as European and North American brands face Extended Producer Responsibility mandates. Flat pouches retain dominance in electronics and medical devices where minimal headspace and precise dimensional control protect sensitive components during sterilization and transport.
FDA food contact substance regulations govern migration limits for polyethylene and nylon layers in U.S. applications, while EU REACH and the Packaging and Packaging Waste Regulation set material disclosure and recyclability thresholds for products entering European supply chains. Germany's national packaging act implements stricter sorting and recycling quotas that force converters to validate mono-material or certified recyclable structures. Stakeholders must monitor how divergent transatlantic compliance timelines reshape sourcing geography and capital allocation for film extrusion and converting assets.
Market Dynamics
EU REACH compliance and Germany's national packaging act are forcing vacuum chamber pouch converters to validate mono-material barrier structures, consolidating cost-of-entry calculus and reshaping competitive positioning among film extruders and form-fill-seal operators.
Growth Catalysts
- Extended Producer Responsibility mandates:European and North American brands face binding recycling quotas that accelerate demand for certified recyclable barrier films in meat and ready-meal packaging.
- Industrial meat processing clusters:Germany's concentration of protein processors drives premium pouch consumption for extended shelf-life applications requiring oxygen transmission rates below 1 cc/m²/day.
- Multi-layer coextrusion advances:Nylon-ethylene vinyl alcohol barrier substrates now achieve hermetic sealing performance without aluminum foil laminates, enabling lighter-weight pouch structures.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Asian petrochemical suppliers dominate EVOH feedstock, exposing European converters to input cost volatility and currency fluctuation risk.
- REACH substance authorization timelines:ECHA's phased restrictions on phthalate plasticizers in sealant layers force reformulation cycles that extend product validation periods by 18-24 months.
- Biodegradable barrier performance gaps:PLA and PHA alternatives exhibit moisture sensitivity and inferior oxygen barrier versus conventional multi-layer structures, limiting adoption in high-value protein applications.
Strategic Opportunities
- Medical device sterilization pouches:Flat pouch formats for electronics and surgical instruments remain underpenetrated in North American hospital supply chains, offering margin expansion versus commodity food packaging.
- Channel consolidation in protein processing:Direct converter relationships with branded meat packers bypass traditional distribution intermediaries, capturing value from custom printed high-barrier structures.
- Dual carbon goals alignment:China's national carbon neutrality targets create procurement preference for domestic converters with certified low-carbon film extrusion capabilities.
Industry Challenges
- Mono-material certification complexity:Validating recyclable barrier structures to Germany's national packaging act sorting quotas requires capital-intensive pilot lines and third-party testing protocols.
- Barrier film talent scarcity:Polymer scientists with coextrusion die design expertise command premium compensation, constraining mid-tier converters' R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Chamber Pouches Market |
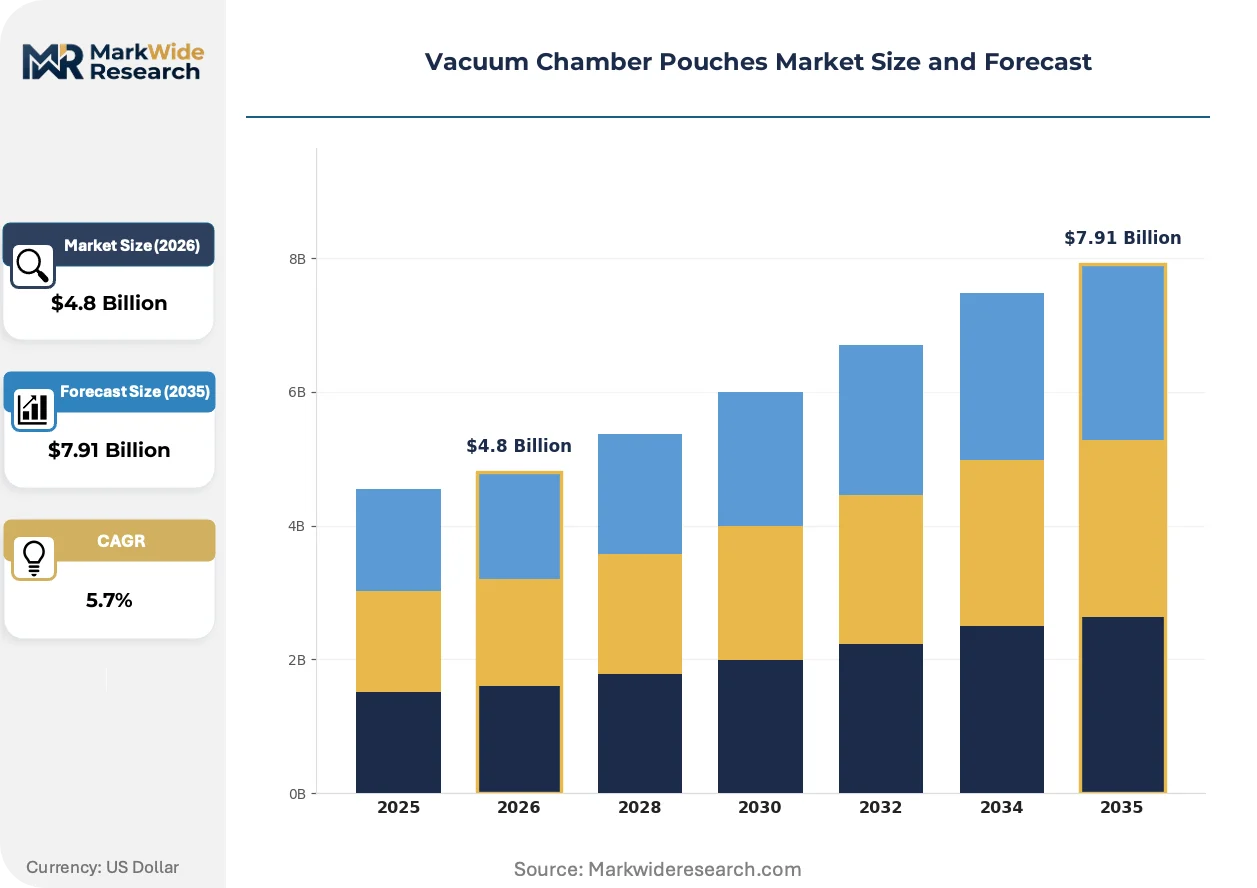
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Gusseted Pouches, Ziplock Pouches, Roll Stock Material: Polyethylene, Nylon, Barrier Films, Biodegradable Plastics End User: Food Processing, Medical Devices, Electronics, Industrial Applications Packaging Type: Custom Printed, Standard, Bulk, Pre-made |
| Companies Covered | Sealed Air Corporation, Amcor Plc, Berry Global Inc., Mondi Group Plc, Winpak Ltd., Coveris Holdings S.A., Multivac Sepp Haggenmuller SE & Co. KG, Proampac, Genpak Food Containers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Chamber Pouches Market Evolving Landscape
Active and intelligent packaging technologies are reshaping vacuum chamber pouch functionality beyond passive barrier protection, embedding sensing and communication capabilities directly into multi-layer film structures.
Digital printing is integrating variable data and short-run customization into pouch converting workflows. Branded protein processors in Germany and the Netherlands adopt inkjet-decorated vacuum pouches for SKU proliferation and traceability compliance. This capability is compressing minimum order quantities and enabling regionalized production footprints that reduce inventory carrying costs.
REACH substance restrictions are tightening migration limits for polyethylene sealant layers in European food contact applications. EFSA's updated guidance on oligomer migration forces converters to validate new catalyst systems and polymerization conditions. High-barrier nylon lines destined for ready-meal manufacturing face the most intensive retesting burden, delaying new product introductions by two to three quarters.
Ready-meal manufacturers are consolidating supplier relationships around converters with captive film extrusion and integrated forming operations. Long-term framework agreements with volume commitments replace spot purchasing for standard barrier specifications. This concentration is most visible in France and Italy, where private-label meal kit brands demand just-in-time delivery flexibility that only vertically integrated pouch suppliers can reliably execute.
Vacuum Chamber Pouches Market Segmentation
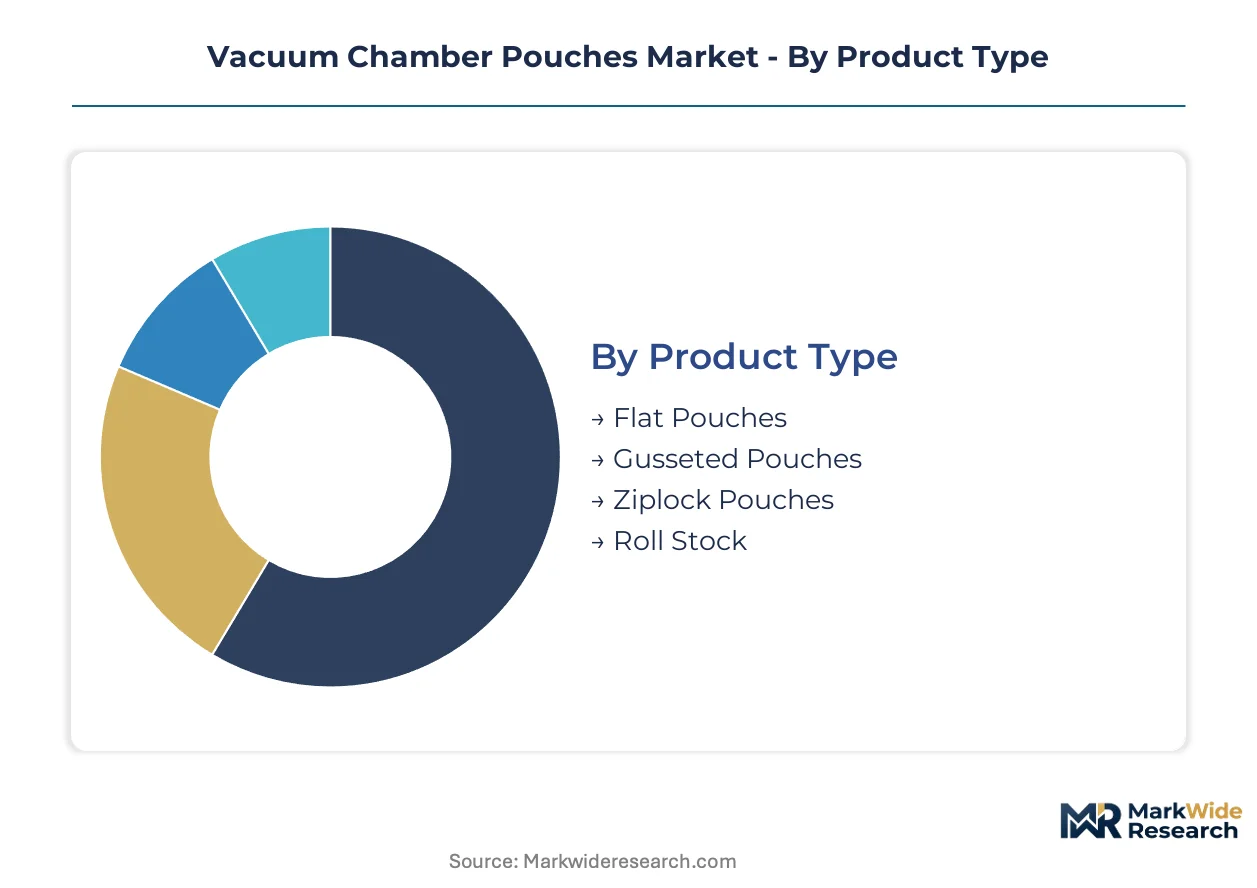
Equipment refresh cycles and regulatory compliance deadlines drive differentiated upgrade patterns across vacuum chamber pouch categories. Food processors replace barrier film specifications faster than medical device manufacturers, creating asynchronous demand waves that suppliers must sequence.
Product Type:
Upgrade cycles vary dramatically by format complexity, with forming equipment compatibility dictating replacement timing.
- Flat Pouches:Two-dimensional structures with minimal headspace dominate electronics sterilization and surgical instrument packaging. Demand concentrates in North American hospital supply chains where dimensional precision protects moisture-sensitive components during gamma irradiation.
- Gusseted Pouches:Side-folded structures expand capacity while enabling standing presentation on retail shelves. German meat processors and French ready-meal manufacturers specify these formats for oxygen transmission rates below 1 cc/m²/day in extended shelf-life protein applications.
- Ziplock Pouches:Reclosable interlocking strips add consumer convenience for multi-use food storage. Premium branded cheese and cured meat packers in Italy and Spain specify these for refrigerated retail segments.
- Roll Stock:Continuous web format feeds automated form-fill-seal lines for high-volume commodity packaging. Industrial bakeries and snack food operations in the United States favor roll stock for throughput economics on legacy equipment.
Gusseted pouches sit at the top of the volume ranking, with biodegradable alternatives in development climbing the fastest.
Material:
Cost tiers separate performance-grade specifications from compliance-driven substitutions.
- Polyethylene:Sealant layer foundation providing heat-activated bonding surfaces. FDA migration limits govern oligomer content for U.S. food contact, forcing catalyst system validations that extend qualification timelines.
- Nylon:Structural substrate delivering puncture resistance and mechanical durability. REACH substance restrictions on caprolactam monomer residues tighten European supply specifications, favoring converters with captive polymerization capabilities.
- Barrier Films:Multi-layer coextrusions combining ethylene vinyl alcohol with polyethylene and nylon substrates. Asian petrochemical suppliers dominate EVOH feedstock, exposing European converters to input cost volatility.
- Biodegradable Plastics:PLA and PHA alternatives navigating Extended Producer Responsibility mandates. Moisture sensitivity and inferior oxygen barrier versus conventional structures limit adoption in high-value protein applications.
Barrier films command the highest volume position, with biodegradable plastics gaining share fastest despite performance constraints.
End User:
Application maturity determines margin structure and supplier relationship intensity.
- Food Processing:Industrial meat, seafood, cheese, and ready-meal operations requiring hermetic evacuation and extended shelf stability. Germany's protein processing clusters drive premium specification adoption.
- Medical Devices:Sterilization packaging for surgical instruments and implantable components. Flat pouch formats remain underpenetrated in North American hospital supply chains.
- Electronics:Moisture and oxygen protection for semiconductors and sensitive components during transport. Minimal headspace requirements favor precision-formed flat structures.
- Industrial Applications:Metal parts, chemicals, and machinery components requiring corrosion inhibition. Lower barrier specifications tolerate commodity polyethylene constructions.
Food processing anchors volume leadership, with medical device applications expanding most quickly as sterilization standards tighten.
Packaging Type:
Customer scale and branding requirements segment procurement patterns.
- Custom Printed:Rotogravure and digital inkjet decoration for branded protein and ready-meal presentation. German and Dutch private-label manufacturers compress minimum order quantities through short-run digital workflows.
- Standard:Unprinted commodity specifications for private-label and foodservice distribution. Spot purchasing patterns dominate with price-sensitive bakery and produce operations.
- Bulk:High-count palletized shipments for industrial processors with captive forming equipment. Volume commitments secure preferential resin allocation during supply constraints.
- Pre-made:Finished pouches delivered to small and mid-tier converters lacking forming capabilities. Regional distribution networks in France and Italy serve fragmented meat processing bases.
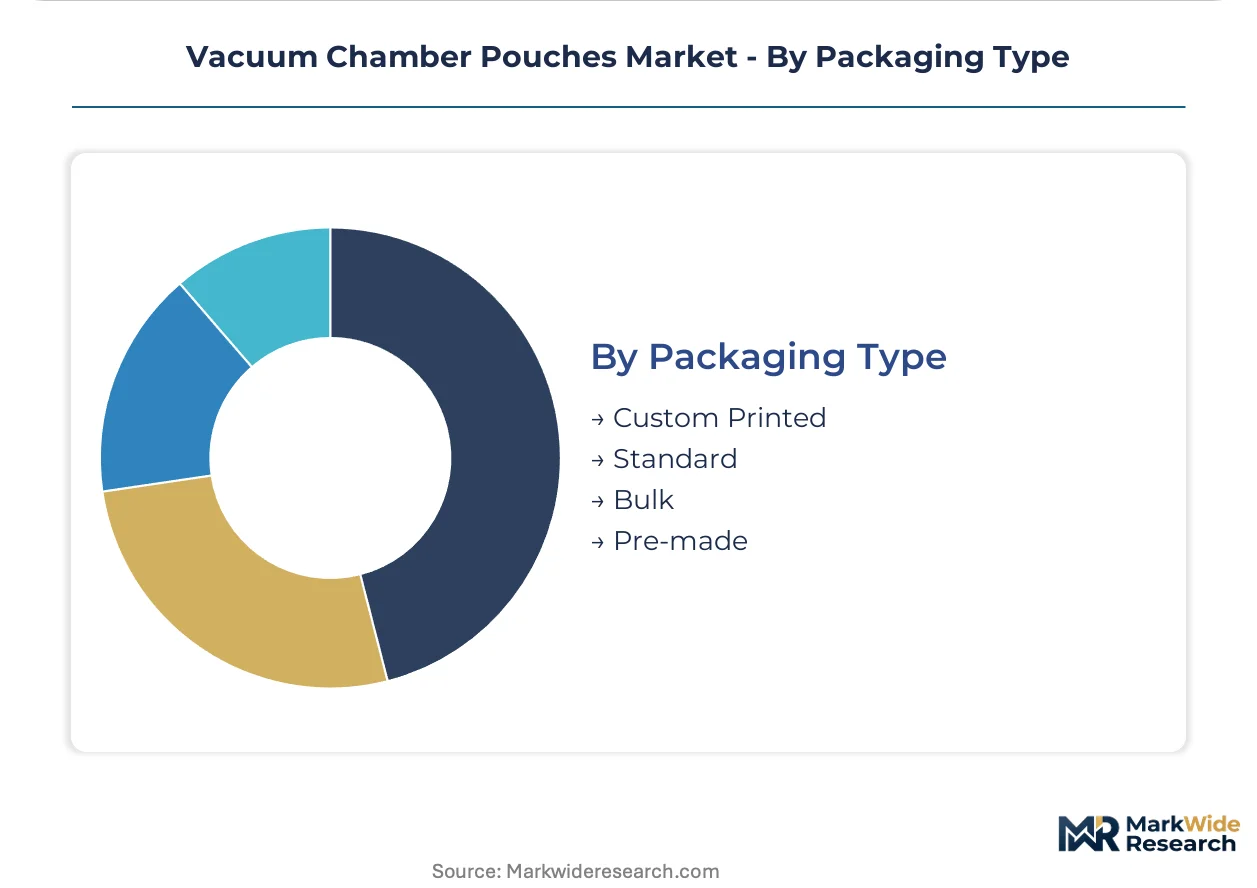
Standard packaging holds volume dominance, with custom printed formats climbing fastest as SKU proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vacuum chamber pouch industry traces its commercial origins to post-war German meat processing automation, where hermetic packaging first achieved industrial scale. From these Bavarian and North Rhine-Westphalian clusters, barrier film technology diffused across Atlantic and Pacific manufacturing basins. Today's geographic footprint reflects this lineage while adapting to divergent regulatory timelines and protein processing concentrations.
Germany
Industrial meat processing in Lower Saxony and Bavaria consumes premium gusseted pouches with oxygen transmission rates below 1 cc/m²/day. The national packaging act enforces stricter sorting and recycling quotas than EU baseline requirements. Wolfsburg and Munich host converting operations that validate mono-material barrier structures for ready-meal manufacturers.
United States
Flat pouch demand concentrates in North Carolina and Minnesota medical device sterilization supply chains. FDA food contact substance regulations govern migration limits for polyethylene sealant layers in protein packaging applications. Chicago-area industrial bakeries favor roll stock formats for legacy form-fill-seal throughput economics.
China
Dual carbon goals create procurement preference for domestic converters with certified low-carbon film extrusion capabilities. Yangtze River Delta meat processors are adopting vacuum packaging to reduce cold-chain spoilage losses. Shanghai and Suzhou house the country's largest concentration of EVOH barrier film coextrusion capacity.
France
Private-label meal kit brands in Île-de-France demand just-in-time delivery flexibility from vertically integrated pouch suppliers. EFSA's updated guidance on oligomer migration forces converters to validate new catalyst systems for ready-meal applications. Lyon and Lille anchor the country's premium protein packaging specification adoption.
Italy
Branded cheese and cured meat packers in Emilia-Romagna specify ziplock pouches for refrigerated retail segments. REACH substance restrictions on caprolactam monomer residues tighten nylon supply specifications. Parma and Modena clusters drive custom printed rotogravure decoration demand for export-oriented protein processors.
Vacuum Chamber Pouches Market Competitive Landscape
The competitive structure tilts toward integrated film extruders with captive converting operations. Three tiers separate global multi-material suppliers, regional specialists in barrier formulations, and equipment-integrated converters serving local protein processors. Consolidation pressure concentrates among mid-tier players lacking upstream resin relationships or downstream forming capabilities. Strategic moves cluster around backward integration into EVOH supply and digital printing asset deployment for short-run customization.
Among North American packaging conglomerates, Sealed Air Corporation and Berry Global Inc. exemplify scale-driven archetypes with integrated film networks. Amcor Plc anchors the premium-tier vector through global converting footprints. Mondi Group Plc occupies a position within the sustainability-specialist tier, navigating biodegradable development without performance trade-offs. Multivac Sepp Haggenmuller SE & Co. KG represents the equipment-integrated archetype, bundling machinery and pouch supply for European meat processors.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor Plc |
| Berry Global Inc. |
| Mondi Group Plc |
| Winpak Ltd. |
| Coveris Holdings S.A. |
| Multivac Sepp Haggenmuller SE & Co. KG |
| Proampac |
| Genpak Food Containers |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters across Northern Italy and Southern Germany anchor supply-side discipline through generational capital structures that resist short-term margin compression. Their patient financing models sustain multi-year EVOH inventory positions and captive film extrusion investments that transnational competitors cannot replicate, insulating premium-tier pricing from commodity volatility while forcing price discipline on spot-market dependent rivals.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies vacuum chamber pouch procurement by certification grade and volume commitment scale. Premium tiers command defensible positioning through REACH-compliant mono-material validation and custom rotogravure decoration for branded German protein processors. Cost compression in standard specifications is intensifying because Asian EVOH feedstock volatility transmits directly into converter input costs. Industrial bakeries and foodservice distributors exhibit highest price sensitivity, while medical device sterilization purchasers prioritize dimensional precision over unit economics.
Supply Chain Analysis
EVOH barrier resin supply rests on Japanese and South Korean petrochemical producers, with Chinese state-backed converters rapidly scaling domestic coextrusion capacity. Nylon substrate production concentrates in Germany, Belgium, and the United States, where caprolactam polymerization facilities face REACH substance restriction compliance costs. Single-source vulnerability runs through Asian EVOH feedstock channels, exposing European converters to currency fluctuation and logistics chokepoint risk. Distribution runs through regional converting hubs that serve fragmented meat processing clusters with just-in-time pre-made pouch delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
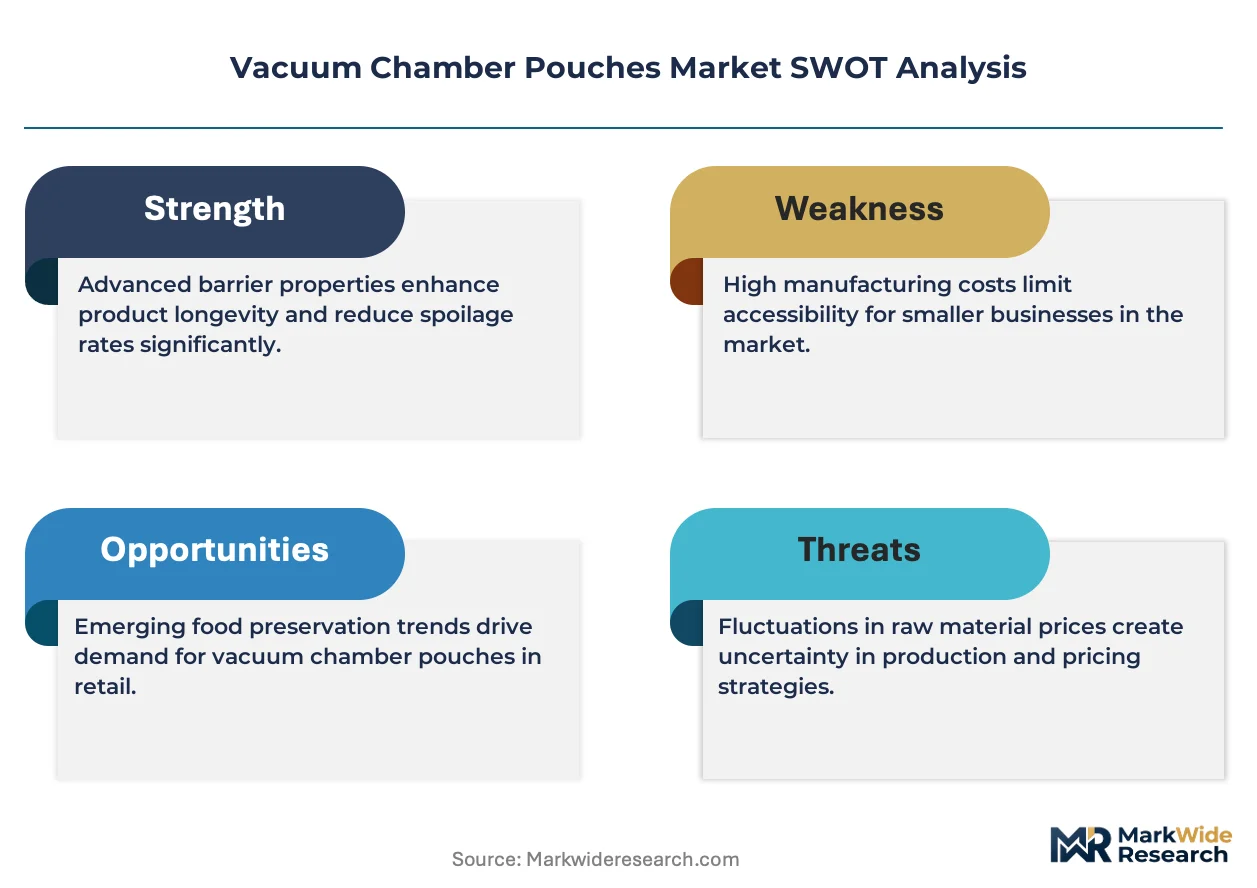
Vacuum chamber pouch economics favor margin expansion through biodegradable barrier film premiumization and captive EVOH supply consolidation. Cost-down pressure from Extended Producer Responsibility mandates accelerates converter consolidation around integrated extrusion-forming operations.
For Market Incumbents: To counter Asian EVOH feedstock volatility, Sealed Air Corporation and Amcor Plc should deepen backward integration into barrier resin polymerization through long-term offtake agreements with Japanese suppliers. Certification investment in Germany's national packaging act mono-material validation creates switching costs that lock in branded protein processor relationships. For New Entrants and Emerging Players: The eighty-point spread between premium medical sterilization pouches and commodity foodservice roll stock opens white-space targeting in North American hospital supply chains. Underpenetrated flat pouch demand in Minnesota and North Carolina surgical instrument packaging offers the most penetrable entry vector. Go-to-market execution should prioritize FDA food contact substance pre-validation to compress qualification timelines versus incumbent response. For Investors and Strategic Acquirers: Valuations sit cheapest among equipment-integrated European specialists with captive forming operations and regional protein processor relationships. The five-to-ten year viability window favors converters with demonstrated REACH compliance navigation and biodegradable plastics R&D pipelines. Watch ECHA's phased phthalate restriction timelines as inflection indicator for reformulation-driven supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Supply | Captive resin access insulates margin from Asian petrochemical currency volatility. |
| Mono-Material Certification Investment | Germany's national packaging act validation creates regulatory moat around premium protein accounts. |
| Digital Printing Asset Deployment | Short-run inkjet customization captures SKU proliferation demand from Dutch private-label meal kit brands. |
| Medical Device Sterilization Pouch Expansion | Flat pouch precision specifications command margin premiums versus commodity food packaging. |
| Biodegradable Barrier Film Development | PLA and PHA alternatives navigate Extended Producer Responsibility mandates without performance trade-offs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with polymer scientists, meat processing procurement directors, and medical device sterilization packaging managers with secondary validation. FDA food contact substance filings, ECHA REACH substance authorization databases, EU Packaging and Packaging Waste Regulation impact assessments, and German national packaging act compliance disclosures anchored top-down market sizing. Bottom-up triangulation cross-referenced converter capacity announcements, resin producer supply disclosures, and protein processor packaging specification tenders.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation modeling spanning pouch format complexity, barrier film material composition, end-use application maturity, and regional regulatory cluster intensity. CAGRs derived from equipment refresh cycle analysis, compliance deadline sequencing, and protein processing automation adoption curves. Industry-specific forecast inputs incorporated EVOH resin price elasticity coefficients and REACH substance restriction phase-in timelines.
Caveats apply where ECHA authorization delays, biodegradable barrier performance breakthroughs, or Asian petrochemical supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and protein processor automation capex commitments. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Vented Stretch Wrap Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Zipper Pouch Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Telemetry Pouch Market
Pouch
Flat Bottom Pouch Market
Pouch
Liquid Pouch Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Child Resistant Pouches Market
Pouch
Europe Retort Pouches Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Latin America Pouch Packaging Market
Pouch
South Africa Pouch Packaging Market
Pouch
Heat Sealed Lamination Pouch Market