
 Doyen Style Pouches Market | 2026-2036
Doyen Style Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Doyen Style Pouches Market Analysis
Asset-light leasing models for converting equipment is tilting competitive dynamics toward mid-tier converters with limited capital reserves. Amcor plc leverages its global film supply network to sustain cost advantages across multiple geographies. Mondi Group anchors its position through integrated paper-based barrier solutions that differentiate against conventional plastic formats. Sealed Air Corporation competes via automated packaging systems that extend pouch throughput for food processors.
Doyen style pouches are flexible packaging formats featuring a bottom gusset that enables self-standing display, typically constructed from multi-layer laminated films incorporating polyethylene, polyethylene terephthalate, or aluminum oxide barrier coatings to provide oxygen and moisture protection. These structures serve primary commercial purposes in food preservation, cosmetic dispensing, and pharmaceutical unit-dose containment where shelf visibility and consumer convenience intersect. Stand-up pouches occupy the largest volume position due to retail shelf efficiency and brand billboard space, while biodegradable film represents the fastest-growing material segment as European and North American regulators tighten single-use plastic restrictions. Zip lock closures command premium positioning in resealable snack and pet food applications where repeat-use functionality justifies higher unit economics.
FDA food contact substance notifications govern material safety for U.S. packaged goods, while EFSA and REACH frameworks in Europe dictate chemical migration limits and substance authorization requirements that directly filter permissible pouch constructions. ISO 9001 and BRCGS packaging certification standards further condition market access for suppliers serving multinational food and pharmaceutical clients. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return system expansions that will reshape material recovery economics and format selection criteria.
Market Dynamics
EU Green Deal mandates and REACH substance restrictions are forcing material transitions from multi-layer laminates toward mono-polymer and paper-based barrier structures, compressing converter margins while opening positions for integrated film suppliers.
Growth Catalysts
- REACH chemical authorization:European converters accelerate recyclable mono-material adoption to preempt compliance deadlines, creating pull for compatible sealing and printing technologies.
- Food processor automation:Robotic filling lines demand pouch formats with dimensional consistency, favoring suppliers with tight gauge control and real-time quality monitoring.
- German retail consolidation:Aldi and Rewe sustainability commitments cascade through private-label supply chains, mandating recyclable or reusable packaging formats by specified transition windows.
Market Restraints
- Aluminum oxide supply:Thin-film barrier coating feedstock concentrates among Japanese and Korean chemical suppliers, exposing converters to yen-denominated volatility and allocation risk.
- Multi-layer delamination:Current mechanical recycling infrastructure cannot separate PET-PE-foil laminates, rendering post-industrial scrap uneconomical to recover in most European territories.
- Biopolymer performance gaps:PLA and PHA films exhibit moisture sensitivity and seal-strength limitations that disqualify them from retort and extended-shelf-life applications.
Strategic Opportunities
- Deposit-return expansion:Germany's DRS expansion to include beverage pouches creates infrastructure for closed-loop material recovery that converters can monetize through certified recycled content.
- Pharmaceutical unit-dose:Blow-fill-seal alternatives in oral-solid-dose packaging present white space for sterilizable high-barrier pouches with child-resistant closure integration.
- Digital watermarking:AI-driven sorting systems using embedded markers enable flexible packaging identification in mixed-waste streams, unlocking recyclability claims previously blocked by format complexity.
Industry Challenges
- BRCGS certification timelines:Food safety audits for high-hygiene pouch production require 6-12 month preparation cycles that delay new converter market entry.
- Legacy heat-seal retrofit:Converting equipment designed for multi-layer structures requires jaw replacement and temperature-profile reprogramming to handle mono-material seal initiation temperatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Doyen Style Pouches Market |
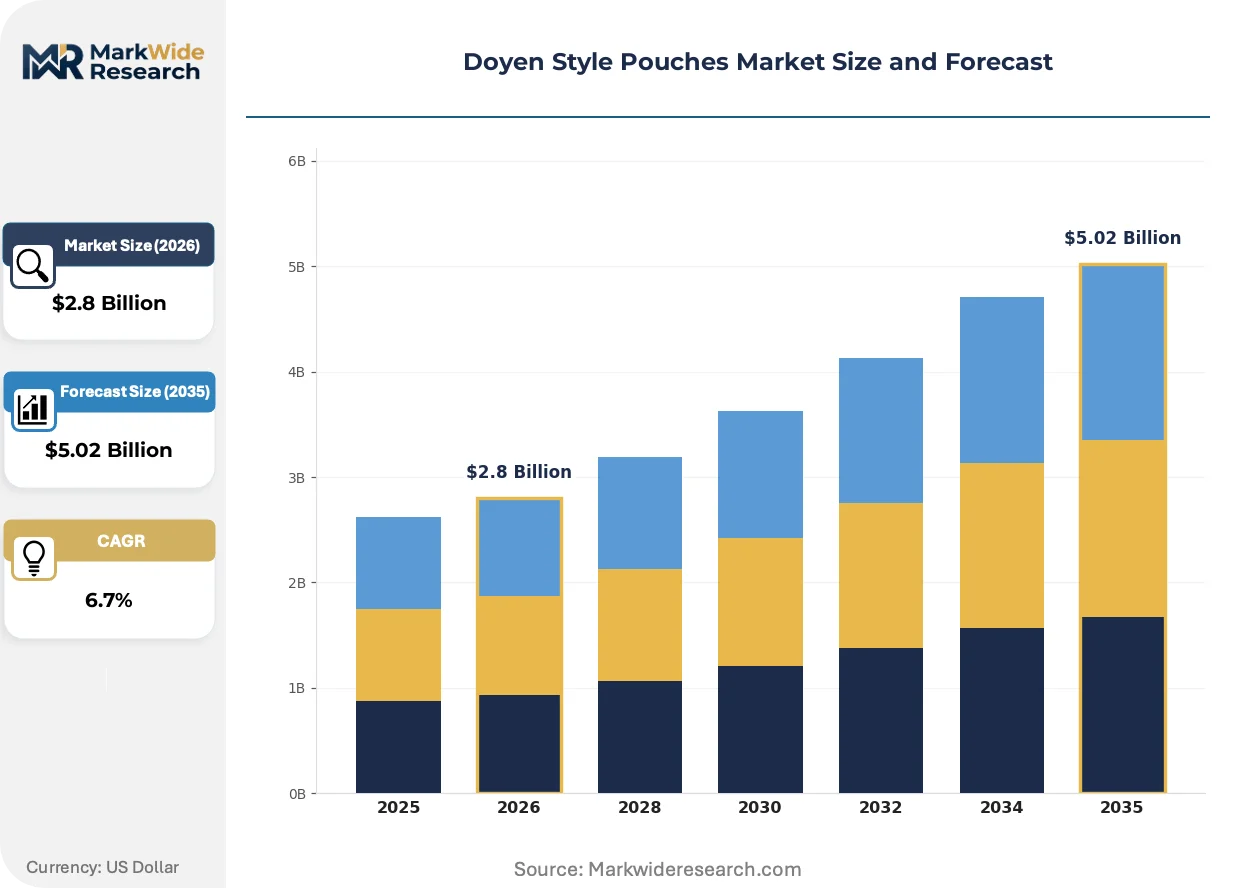
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Zipper Pouches, Window Pouches Material: Plastic, Paper, Aluminum Foil, Biodegradable Film End User: Food Industry, Cosmetics, Pharmaceuticals, Retail Closure Type: Zip Lock, Heat Seal, Press-to-Close, Adhesive |
| Companies Covered | Amcor plc, Mondi Group, Sealed Air Corporation, Berry Global Inc., ProAmpac LLC, Sonoco Products Company, Constantia Flexibles GmbH, Coveris Holdings S.A., Glenroy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Doyen Style Pouches Market Emerging Trajectories
Active and intelligent packaging integration is redefining value propositions beyond containment, with sensor-enabled freshness indicators and connected supply chain traceability becoming standard in premium segments.
Digital printing with water-based inks is digitizing short-run customization for regional brand variants and promotional campaigns. Nestlé and Unilever procurement teams specify digitally printed pouches for seasonal SKUs with sub-50,000 unit volumes. This capability compresses minimum order quantities from traditional rotogravure thresholds, enabling market testing without plate inventory carrying costs.
EU Green Deal packaging and packaging waste regulation revisions mandate extended producer responsibility fee modulation based on recyclability performance. This industrial consequence forces brand owners to redesign multi-material structures or absorb escalating EPR contributions. Food and pet food segments in Germany, France, and Italy face the steepest compliance deadlines and are accelerating mono-polymer transitions ahead of statutory phase-in.
Brand procurement teams now specify circularity credentials as primary vendor selection criteria, displacing historical price-ton prioritization. Retail private-label buyers in German and Benelux markets require third-party recyclability certifications such as Interseroh or cyclos-HTP. This behavioral shift concentrates volume among converters with verified testing partnerships and transparent polymer sourcing documentation.
Doyen Style Pouches Market Segmentation
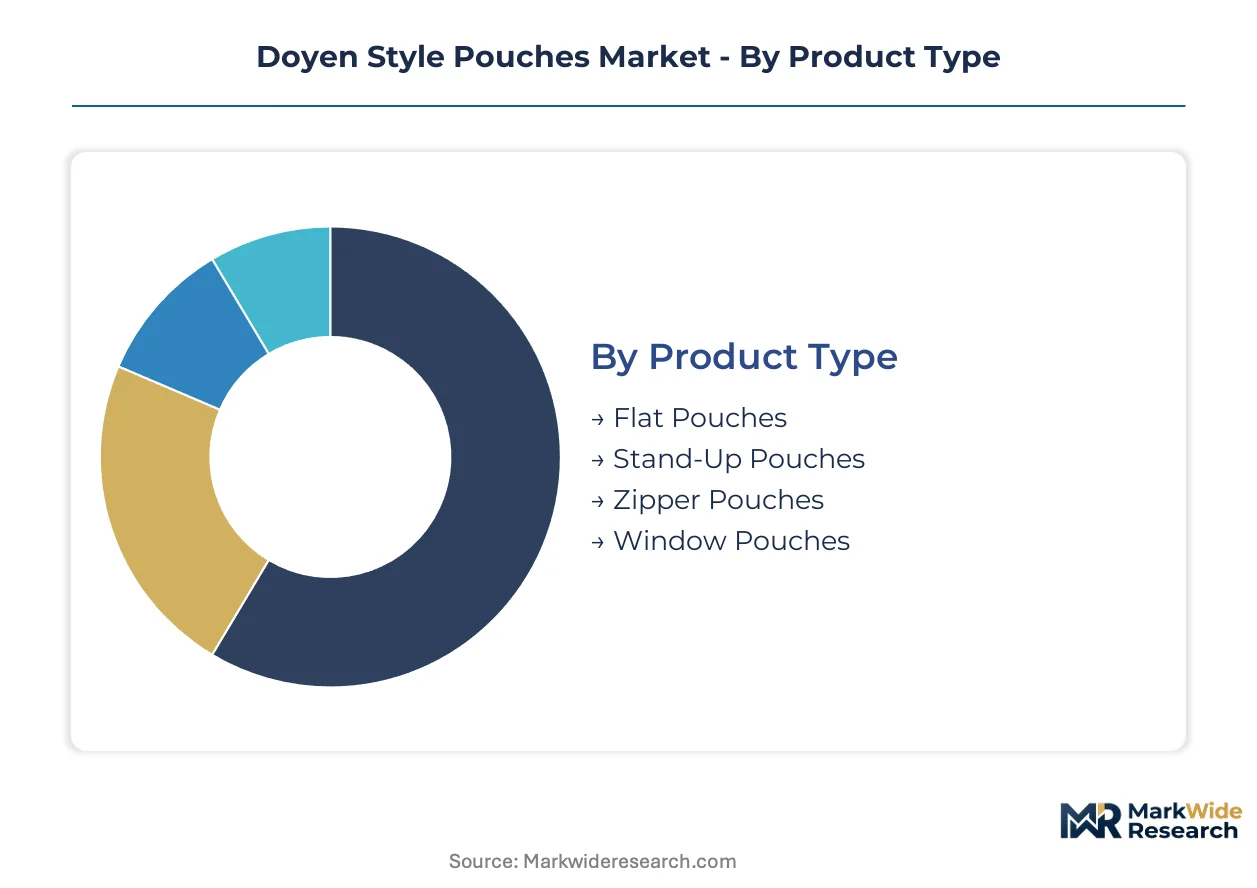
Segmentation in the Doyen Style Pouches Market reveals how format, material, and functional specifications align with distinct value chains. Food processors, cosmetic formulators, and pharmaceutical packagers each impose incompatible performance requirements that filter supplier capabilities and pricing power.
Product Type:
Mature formats dominate shelf presence while emerging structures address automation and visibility demands.
- Stand-Up Pouches:Bottom-gusseted construction enables vertical display without secondary support, maximizing retail billboard space. German discounters and French hypermarkets specify this format for private-label dry goods and pet food where shelf efficiency drives category management decisions.
- Zipper Pouches:Integrated interlocking profiles provide resealability for multi-use consumption occasions. Premium snack brands in the United States and resealable pet food lines in Canada concentrate procurement here, justifying 15-25% unit cost premiums through reduced food waste claims.
- Flat Pouches:Two-dimensional sealed-edge construction serves single-serve condiments and sample sachets where shipping cube efficiency outweighs display requirements.
- Window Pouches:Die-cut transparent panels or high-clarity film windows enable product visibility for bakery items and fresh pasta where visual quality inspection substitutes for printed graphics.
Stand-Up Pouches handles the majority of throughput; Window Pouches is gaining share fastest among specialty food entrants.
Material:
Cost tiers separate commodity multi-layer films from certified sustainable alternatives with divergent margin profiles.
- Plastic:Multi-layer polyethylene and polyethylene terephthalate laminates provide tunable barrier performance against oxygen and moisture migration. Conventional structures face EPR fee escalation under EU Green Deal modulation rules, pressuring brand owners toward mono-polymer redesigns.
- Biodegradable Film:Polylactic acid and polyhydroxyalkanoate formulations enable compostability claims for organic food and premium cosmetic positioning. Moisture sensitivity and seal-strength limitations currently exclude retort applications, constraining addressable market scope.
- Paper:Fiber-based substrates with barrier coatings serve dry goods and confectionery where grease resistance and printability outweigh moisture protection requirements.
- Aluminum Foil:Ultra-high barrier metalized layers preserve coffee aroma and pharmaceutical stability across extended distribution cycles in tropical climates.
Plastic retains volume leadership; Biodegradable Film climbs the fastest as regulatory deadlines approach.
End User:
Application-specific compliance requirements create non-overlapping supplier qualification pools.
- Food Industry:Shelf-stable, refrigerated, and frozen formats each demand validated seal integrity and migration-compliant laminates. BRCGS certification and FDA food contact substance notifications filter supplier bases for multinational processors.
- Pharmaceuticals:Unit-dose and bulk API containment require ISO 15378 compliance, child-resistant closure integration, and documented extractables testing. Blow-fill-seal alternatives currently dominate sterile liquid formats.
- Cosmetics:Cream, lotion, and serum dispensing emphasizes pump compatibility and chemical resistance to surfactant formulations.
- Retail:Private-label sourcing consolidates through centralized procurement functions at Aldi, Lidl, and Rewe, mandating recyclable format transitions ahead of statutory phase-in.
Food Industry commands the dominant share of pouch throughput; Pharmaceuticals presents the steepest expansion trajectory as unit-dose adoption accelerates.
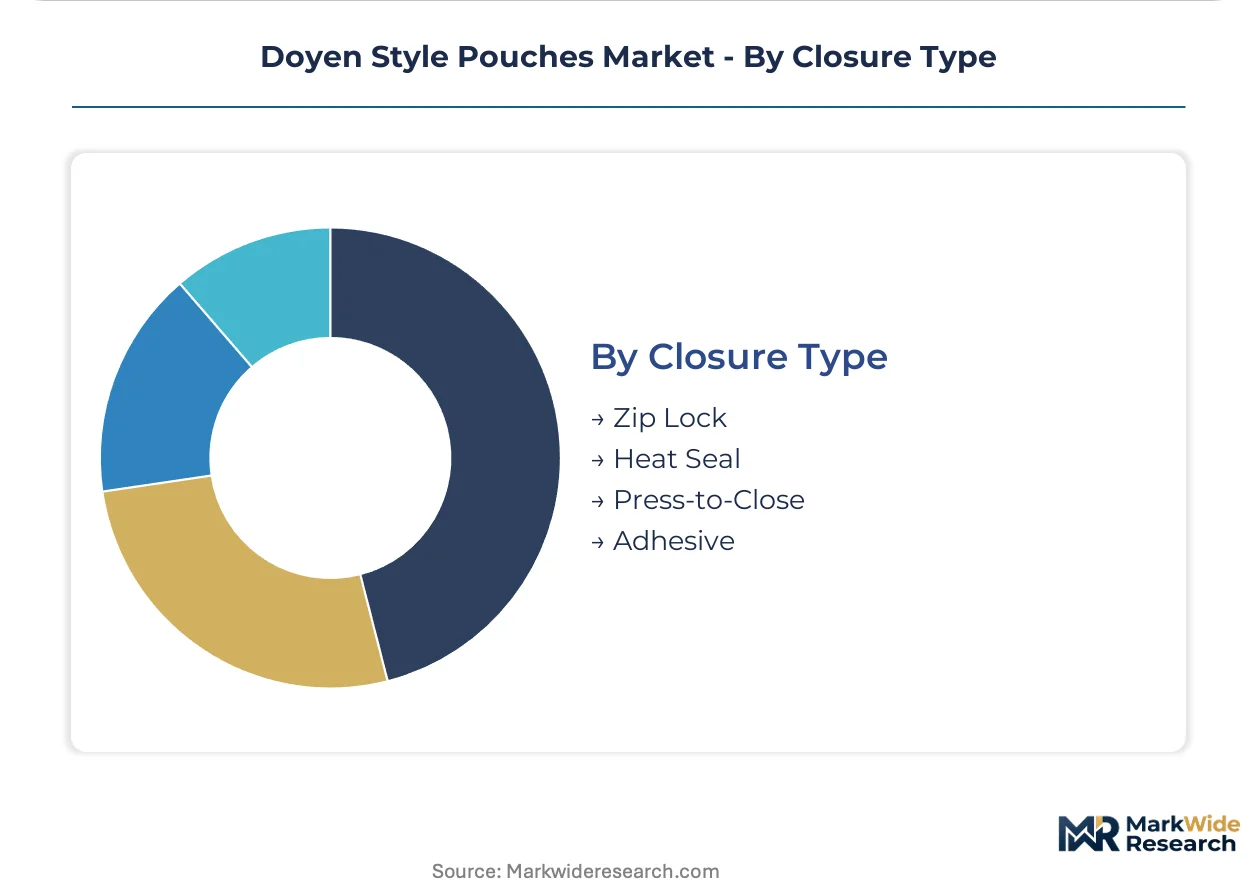
Closure Type:
Customer type differentiation separates repeat-use functionality from single-open disposability.
- Heat Seal:Permanent fusion bonding provides tamper evidence and hermetic integrity for retort and aseptic applications. High-speed form-fill-seal lines in coffee and infant nutrition facilities specify this as the default closure mechanism.
- Zip Lock:Reclosable interlocking profiles extend product freshness across multiple consumption occasions. Pet food and snack brands in North American and European markets specify this for premium tier positioning.
- Press-to-Close:Simplified profile designs reduce per-unit cost while maintaining basic resealability for mid-market dry goods.
- Adhesive:Pressure-sensitive tape closures serve promotional samples and single-use medical device packaging where resealability is irrelevant.
Heat Seal processes the highest unit volumes; Zip Lock captures the fastest share growth as resealability becomes standard in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging mandates and REACH substance restrictions are accelerating material transitions across major economies, with brand owners redesigning multi-layer laminates ahead of compliance deadlines. Germany, the United States, China, France, and Japan concentrate the highest procurement volumes for doyen style pouches.
Germany
Aldi and Rewe sustainability commitments cascade through private-label supply chains, mandating recyclable formats by specified transition windows. The country's extended producer responsibility fee modulation under EU Green Deal rules penalizes non-recyclable multi-material structures. Düsseldorf and Hamburg host major converting clusters where converters retrofit heat-seal equipment for mono-polymer compatibility.
United States
Robotic filling line deployment by food processors demands pouch formats with dimensional consistency and real-time quality monitoring. FDA food contact substance notifications govern material safety for packaged goods, filtering permissible constructions. Chicago and Wisconsin converting corridors supply snack and pet food brands specifying zip lock closures for premium positioning.
China
Domestic food brands expand shelf-stable and convenience format adoption, driving stand-up pouch volume growth. The country's national packaging standards and dual carbon goals pressure converters toward material efficiency improvements. Yangtze River Delta manufacturing clusters supply both domestic processors and export markets with multi-layer laminated films.
France
Hypermarket category management decisions favor bottom-gusseted constructions maximizing retail billboard space for private-label dry goods. EFSA chemical migration limits and REACH authorization requirements filter permissible pouch constructions for food contact applications. Lyon and Paris basin converting facilities serve cosmetic and pharmaceutical unit-dose segments requiring high-barrier performance.
Japan
Thin-film barrier coating feedstock concentrates among domestic and Korean chemical suppliers, exposing converters to yen-denominated volatility. METI industrial standards and JIS certification requirements condition market access for suppliers serving multinational clients. Osaka-Nagoya industrial corridors specialize in ultra-high barrier metalized layers preserving coffee aroma across tropical distribution cycles.
Doyen Style Pouches Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidated film supply networks anchor cost positions for integrated multinationals, while mid-tier converters leverage asset-light equipment leasing to limit capital exposure. Three archetypes dominate: global film suppliers with captive resin access, integrated paper-based barrier specialists, and automated packaging system integrators. Capacity expansion in mono-polymer lines and strategic partnerships for digital watermarking technologies represent the dominant competitive moves reshaping supplier relationships.
Within the integrated multinational tier, Amcor plc and Mondi Group exemplify divergent strategic anchors. Amcor occupies a position sustained by global film supply network scale across multiple geographies. Mondi Group sits within the paper-based barrier specialization vector, differentiating against conventional plastic formats through integrated fiber solutions. Sealed Air Corporation represents the automation-integrated archetype, competing via packaging systems that extend pouch throughput for food processors. These three entities collectively illustrate how material access, substrate innovation, and equipment integration define competitive positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Sealed Air Corporation |
| Berry Global Inc. |
| ProAmpac LLC |
| Sonoco Products Company |
| Constantia Flexibles GmbH |
| Coveris Holdings S.A. |
| Glenroy Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese multi-layer film production is compressing converter margins across export markets while accelerating price competition for commodity-grade stand-up pouches. This utilization imbalance forces European and North American buyers to leverage volume commitments against Asian suppliers, reshaping procurement postures toward contract-based offtake structures.
Pricing Analysis
Certification level creates the primary spread between commodity converters and qualified suppliers, with BRCGS and ISO 15378-certified producers commanding 15-25% premiums over uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels reflects this segmentation, where premium tiers bundle technical support and compliance documentation. Pricing pressure stems from EU Green Deal EPR fee modulation, which penalizes non-recyclable multi-material structures and forces brand owners to absorb escalating compliance costs or switch suppliers. Food processors exhibit highest price sensitivity due to thin operating margins, while pharmaceutical packers prioritize barrier performance over unit economics.
Supply Chain Analysis
Upstream resin and barrier coating feedstock concentrates among Chinese, Japanese, and South Korean chemical suppliers, exposing converters to yen-denominated volatility and allocation risk during supply crunches. Raw material dependencies center on polyethylene terephthalate, ethylene-vinyl alcohol copolymers, and aluminum oxide vapor-deposition coatings. Single-source vulnerability in thin-film barrier technology creates structural exposure when Japanese suppliers institute force majeure declarations. Distribution runs through regional converting clusters in Germany, the United States, and China that serve brand owner specifications with localized finishing and printing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified converter capacity is tightening faster than demand expansion, creating a capability gap around mono-polymer production lines and digital printing infrastructure that rewards early movers with locked-in volume commitments.
For Market Incumbents: Entrench market position through captive resin supply agreements and accelerated mono-polymer line retrofitting ahead of REACH compliance deadlines. Threats from asset-light mid-tier converters leasing automated equipment demand defensive capacity additions in Germany and the United States. Certification investment in digital watermarking partnerships with AI-sorting technology providers secures recyclability claims that brand procurement teams now mandate. For New Entrants and Emerging Players: Build out specialized capabilities in pharmaceutical unit-dose sterilizable pouches and child-resistant closure integration, segments where incumbent qualification timelines create entry windows. White space concentrates in blow-fill-seal alternatives for oral-solid-dose packaging and cosmetic pump-compatible barrier structures. Go-to-market positioning through certified recycled content offerings targets sustainability-committed private-label buyers at German retailers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fragmented regional converter bases face margin compression from material transitions and equipment upgrade cycles. Acquisition targets with verified mono-polymer production lines and established testing partnerships with Interseroh or cyclos-HTP certification bodies capture pricing power. Signal to monitor: German DRS expansion implementation timelines and corresponding infrastructure investment announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Polymer Line Retrofit | REACH compliance deadlines force equipment replacement for European converter survival. |
| Digital Watermarking Partnership | AI-driven sorting integration unlocks recyclability claims blocked by format complexity. |
| Certified Recycled Content Sourcing | German EPR fee modulation rewards verified circularity with cost avoidance. |
| Pharmaceutical Unit-Dose Expansion | Blow-fill-seal alternatives present white space in oral-solid-dose sterilizable formats. |
| Asset-Light Equipment Leasing | Mid-tier converters limit capital exposure while accessing automated throughput capabilities. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA food contact substance notifications, EFSA migration limit databases, EU Green Deal regulatory filings, and customs trade data for flexible packaging imports. Converting equipment manufacturers, brand owner packaging engineers, retail private-label procurement directors, and film resin suppliers provided operational perspectives. Bottom-up volume estimates from named country production clusters triangulate against top-down demand aggregation across food, pharmaceutical, and cosmetic end-use segments.
Forecast inputs incorporate material transition timelines under REACH authorization schedules, robotic filling line deployment rates at food processors, and EPR fee modulation implementation across EU member states. Segmentation dimensions span product type, material substrate, closure mechanism, end-use industry, and regional regulatory cluster. CAGRs derive from slope-intercept modeling of historical volume trajectories adjusted for policy-driven inflection points, with cross-validation against resin consumption patterns and converting equipment order backlogs.
Sensitivities concentrate around REACH substance restriction enforcement timelines, aluminum oxide supply allocation decisions by Japanese chemical suppliers, and German DRS expansion scope definitions. Forecasts reflect assumptions about mono-polymer adoption rates and mechanical recycling infrastructure buildout that industry stakeholders provided. Cross-checking against ECHA pre-registration data and Cefic plastics industry reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Poland Pouch Packaging Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Heat Seal Pouch Market
Pouch
Feminine Care Pouch Film Market
Pouch
Brazil Pouch Packaging Market
Pouch
Retort Pouch Packaging Market
Pouch
Spain Pouch Packaging Market
Pouch
Open Mouth Sacks Market
Pouch
Dual-Chamber Pouches Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Self-Seal Pouches Market
Pouch
Kraft Paper Pouch Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market