
 Stand-Up Pouches Market | 2026-2036
Stand-Up Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Stand-Up Pouches Market Intelligence
The BRCGS Global Standard for Packaging Materials is redrawing competitive positioning by setting stringent requirements for food-safe manufacturing processes. Global leader Amcor leverages its vast R&D capabilities and production scale to meet these standards for multinational clients. Mondi differentiates with its focus on sustainable paper and flexible plastic solutions, while ProAmpac specializes in custom-engineered pouches for specific end markets like pharmaceuticals and personal care.
Stand-up pouches are flexible packaging containers constructed with a gusseted bottom, allowing them to stand upright for retail display. They are typically made from multi-layer laminates, combining materials like Polyethylene and Foil to achieve specific barrier properties against moisture and oxygen. Food Packaging represents the dominant application, with demand for consumer convenience driving innovation in closure types. The integration of resealable zippers and spouts is particularly prevalent in high-growth pet food and beverage packaging segments.
Regulations from the US FDA and the European Food Safety Authority (EFSA) govern food contact materials, directly influencing polymer and adhesive selection. Concurrently, sustainability mandates, including the EU's Packaging and Packaging Waste Regulation and China's dual carbon goals, are pushing for designs that improve end-of-life outcomes. Stakeholders must now navigate the technical trade-offs between high-barrier protection for shelf life and the market shift toward simpler, monomaterial structures for recycling.
Market Dynamics
The central dynamic shaping the stand-up pouch market is the technical and commercial tension between sustainability mandates and performance requirements. Regulatory pressures from bodies like the European Commission are accelerating the shift to monomaterial structures, challenging the dominance of traditional multi-layer laminates.
Growth Catalysts
- Regulatory Alignment:Initiatives like the EU Green Deal are creating a clear demand path for recyclable monomaterial pouches, compelling brand owners to redesign packaging to meet future circular economy targets.
- Premiumization in Pet Food:The migration of premium and specialty pet food brands from rigid cans and bags to stand-up pouches with resealable zippers enhances consumer convenience and product freshness, driving volume growth.
- Organized Retail Expansion:The rapid development of supermarket chains and e-commerce platforms in economies like India creates new channels for products packaged in shelf-stable, retail-ready stand-up pouches.
Market Restraints
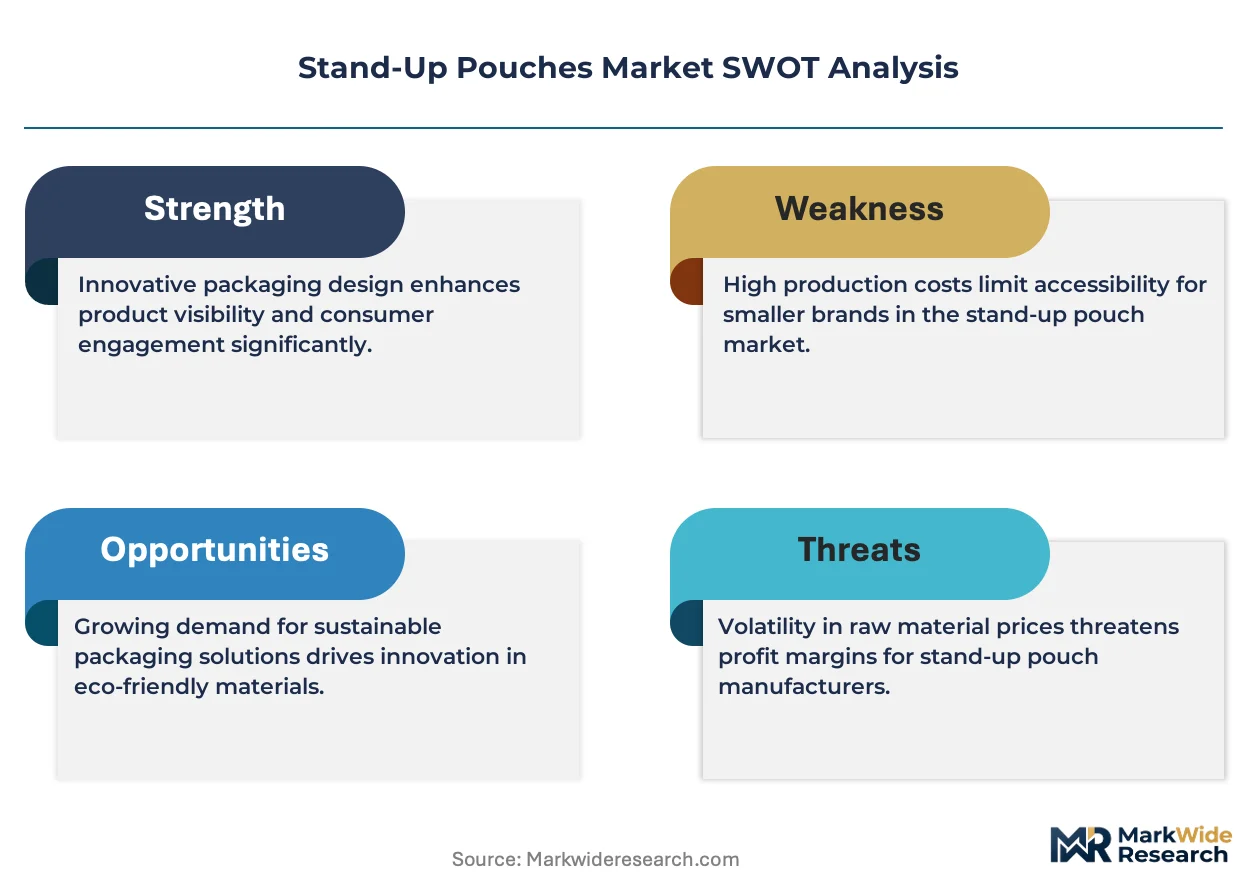
- Input Cost Volatility:Fluctuations in the price of key raw materials, particularly petroleum-derived polymers like PE and a-PET, as well as aluminum foil, directly impact converter margins and final product pricing.
- Barrier Performance Trade-offs:Monomaterial pouch structures often exhibit lower barrier properties against oxygen and moisture compared to multi-material laminates, limiting their use for products with long shelf-life requirements.
- Competition from Alternative Formats:In certain product categories, stand-up pouches face substitution threats from lower-cost flexible formats like pillow packs or rigid containers that offer superior stackability or durability.
Strategic Opportunities
- Non-Food Application Growth:Significant white space exists in segments like liquid detergents, automotive fluids, and garden supplies, where pouches offer dispensing convenience and a lower packaging weight-to-product ratio.
- Smart Packaging Integration:Incorporating digital technologies such as QR codes for supply chain traceability or NFC tags for brand authentication can create value-added differentiation in crowded consumer goods markets.
- Chemical Recycling Advancement:The scaling of advanced recycling technologies that can process mixed-plastic waste into virgin-quality resins presents a long-term opportunity to create a circular supply chain for flexible packaging.
Industry Challenges
- Recycling Infrastructure Gaps:A lack of standardized collection, sorting, and reprocessing infrastructure for flexible packaging in many regions remains a primary operational barrier to achieving circularity at scale.
- Compliance for Recycled Content:Obtaining food-contact approvals from regulators like the FDA and EFSA for post-consumer recycled (PCR) materials is a complex and lengthy process, slowing their integration into food pouches.
- Capital Investment Cycles:Upgrading converting machinery to handle new sustainable laminates, which may have different sealing and processing characteristics, requires significant capital expenditure and production line requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stand-Up Pouches Market |
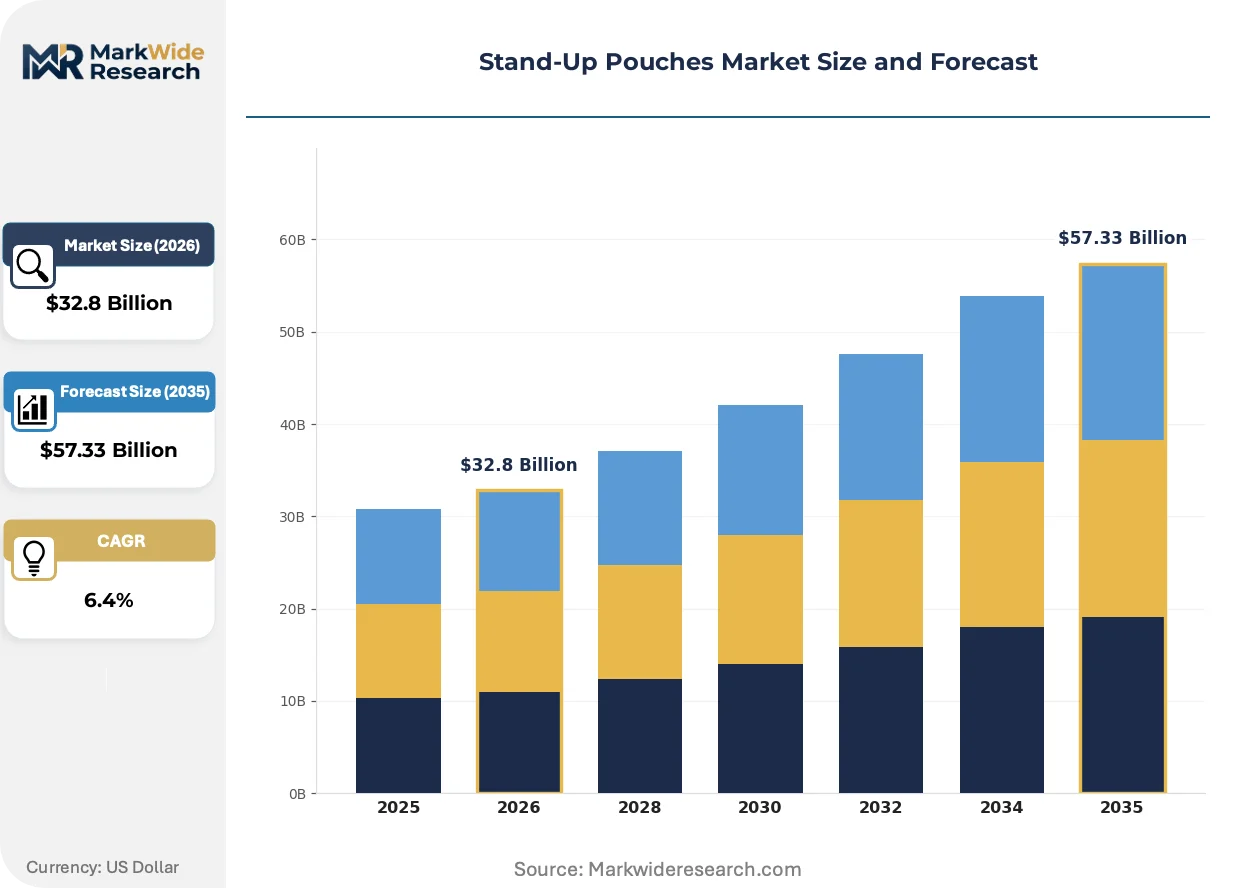
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Laminates, Foil, Aluminum, Polyester Application: Food Packaging, Beverage Packaging, Personal Care, Pharmaceuticals, Pet Food, Household Products End User Industry: Manufacturers, Distributors, Retailers, E-commerce, Wholesalers, Exporters Packaging Closure Type: Resealable Zipper, Tear Notch, Valve, Spout, Adhesive Seal, Snap Lock |
| Companies Covered | Amcor, Berry Global, Mondi, Sealed Air, Sonoco Products Company, ProAmpac, Huhtamaki, Coveris, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stand-Up Pouches Market Strategic Shifts & Innovations
Material science innovation is at the core of the market's evolution, driven by the dual objectives of enhancing pouch functionality and improving end-of-life outcomes. This push creates new design possibilities while simultaneously introducing new manufacturing and supply chain complexities for converters and brand owners.
Monomaterial film technology, particularly all-polyethylene (PE) laminates, provides a direct pathway to recyclability within existing PE film collection streams. Major consumer packaged goods companies are adopting these structures, especially for products like snacks and confectionery, to meet corporate sustainability goals. This development is bifurcating the market, creating a distinct segment for recycle-ready pouches alongside high-performance, multi-material composites for sensitive applications.
China's national dual carbon goals are influencing packaging design by promoting material reduction and circularity. These policies incentivize manufacturers to lightweight packaging and explore alternatives to non-recyclable multi-layer films. The country's vast food and personal care industries are most affected, spurring domestic R&D in bio-based polymers and simplified laminate structures to comply with evolving GB standards.
A notable shift in packaging design is occurring to meet the specific demands of e-commerce distribution channels. The need for durability to withstand rough handling and prevent leaks during transit is prioritizing functional attributes like robust seals and puncture resistance over traditional on-shelf aesthetics. This is most visible in the United States and European direct-to-consumer markets for products like liquid refills, coffee, and nutritional supplements.
Stand-Up Pouches Market Segmentation
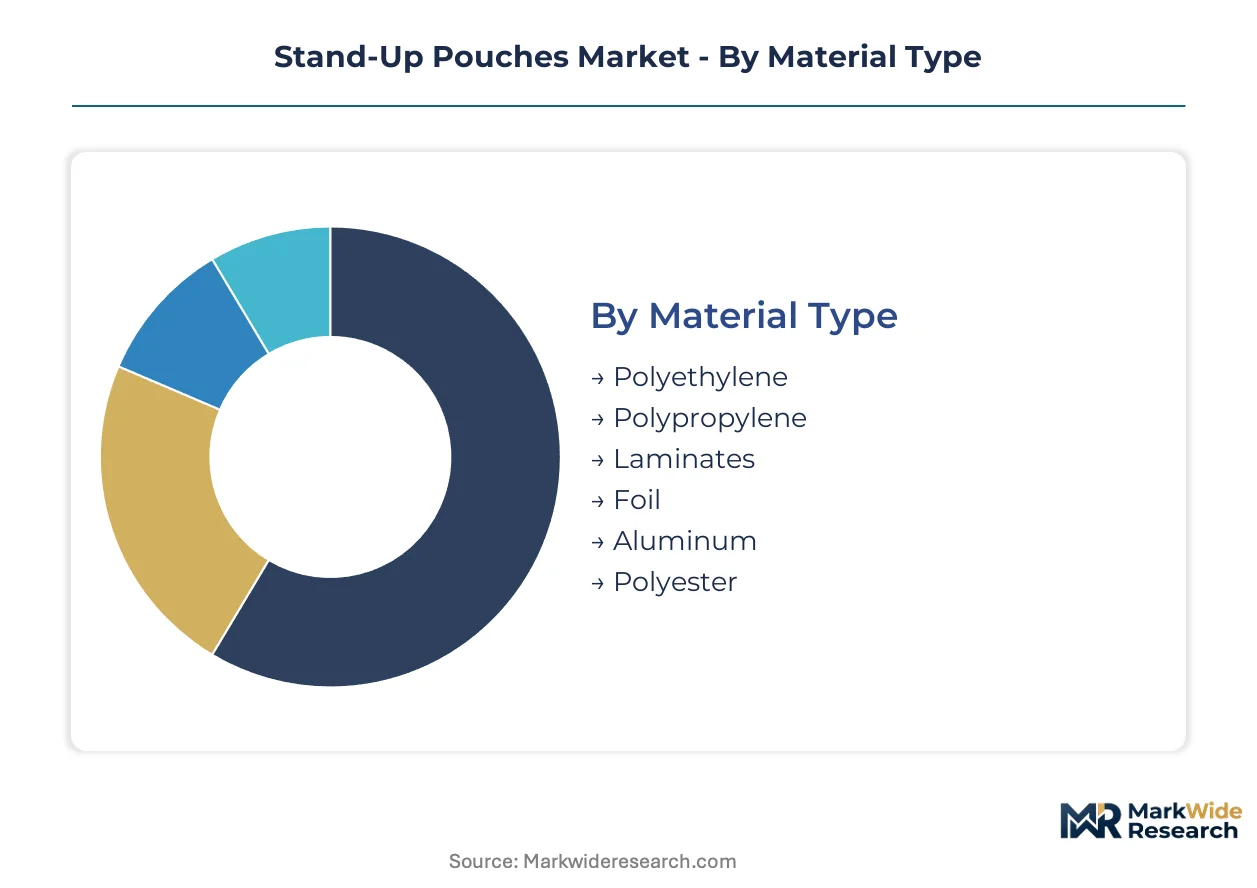
The stand-up pouches market exhibits diverse segmentation reflecting material science advancements and varied end-user requirements. Understanding these distinct categories provides clarity on product development priorities and market penetration strategies. Each segment addresses specific functional demands or distribution channels.
Material Type:
Material selection significantly influences a stand-up pouch's performance characteristics and its suitability for various distribution channels, from retail shelves to e-commerce fulfillment.
- Polyethylene:This common polymer offers excellent sealability and moisture barrier properties. Demand concentrates in food packaging, driven by the monomaterial push for recycling in Europe.
- Laminates:Multi-layer structures combine different materials for enhanced barrier performance against oxygen and moisture. Demand is high in pharmaceuticals and pet food, driven by extended shelf-life requirements in the US.
- Polypropylene:Provides heat resistance and stiffness, suitable for retort applications.
- Foil:Offers superior barrier properties against light, moisture, and oxygen.
- Aluminum:Used for high-barrier needs and lightweight packaging solutions.
- Polyester:Valued for its strength, clarity, and printability in various designs.
By volume, laminates lead the market due to their versatility. By growth pace, polyethylene is ahead, driven by sustainability mandates.
Application:
Diverse application areas dictate specific barrier properties, closure mechanisms, and aesthetic requirements for stand-up pouches, influencing material and design innovation.
- Food Packaging:Covers a wide range of products, requiring various barrier levels for preservation. Demand concentrates in snacks and ready meals, driven by consumer convenience in India.
- Pet Food:Requires strong barriers against oxygen and moisture, often with resealable features. Demand is strong for premium dry and wet pet foods, as brands shift from rigid containers in the US.
- Personal Care:Used for liquids, creams, and gels, offering portability.
- Pharmaceuticals:Requires strict barrier protection and tamper-evident features.
- Beverage Packaging:Features spouted pouches for single-serve or multi-serve drinks.
- Household Products:Includes liquid detergents and refills, reducing plastic use.
Food packaging maintains its dominant share, while pet food packaging represents the fastest-growing segment.
End User Industry:
The end-user industry determines procurement volumes, supply chain requirements, and the specific functional attributes prioritized in stand-up pouch design and delivery.
- Retailers:Focus on shelf appeal, resealability, and product visibility for consumers. Demand concentrates in supermarket chains in Europe, driven by merchandising strategies.
- E-commerce:Requires robust seals and puncture resistance to withstand transit and prevent leaks. Demand is high for liquid refills and nutritional supplements in the US, driven by direct-to-consumer sales.
- Manufacturers:Utilize pouches for in-house packaging operations and brand consistency.
- Distributors:Manage logistics and inventory for efficient product flow.
- Wholesalers:Engage in bulk purchasing for supply to smaller retail outlets.
- Exporters:Navigate international shipping requirements and diverse regulatory compliance.
Retailers remain the largest end-user segment, with e-commerce rapidly gaining share through its unique logistical demands.
Packaging Closure Type:
Closure types enhance consumer convenience and product preservation, directly impacting the functionality and market appeal of stand-up pouches across diverse product categories.
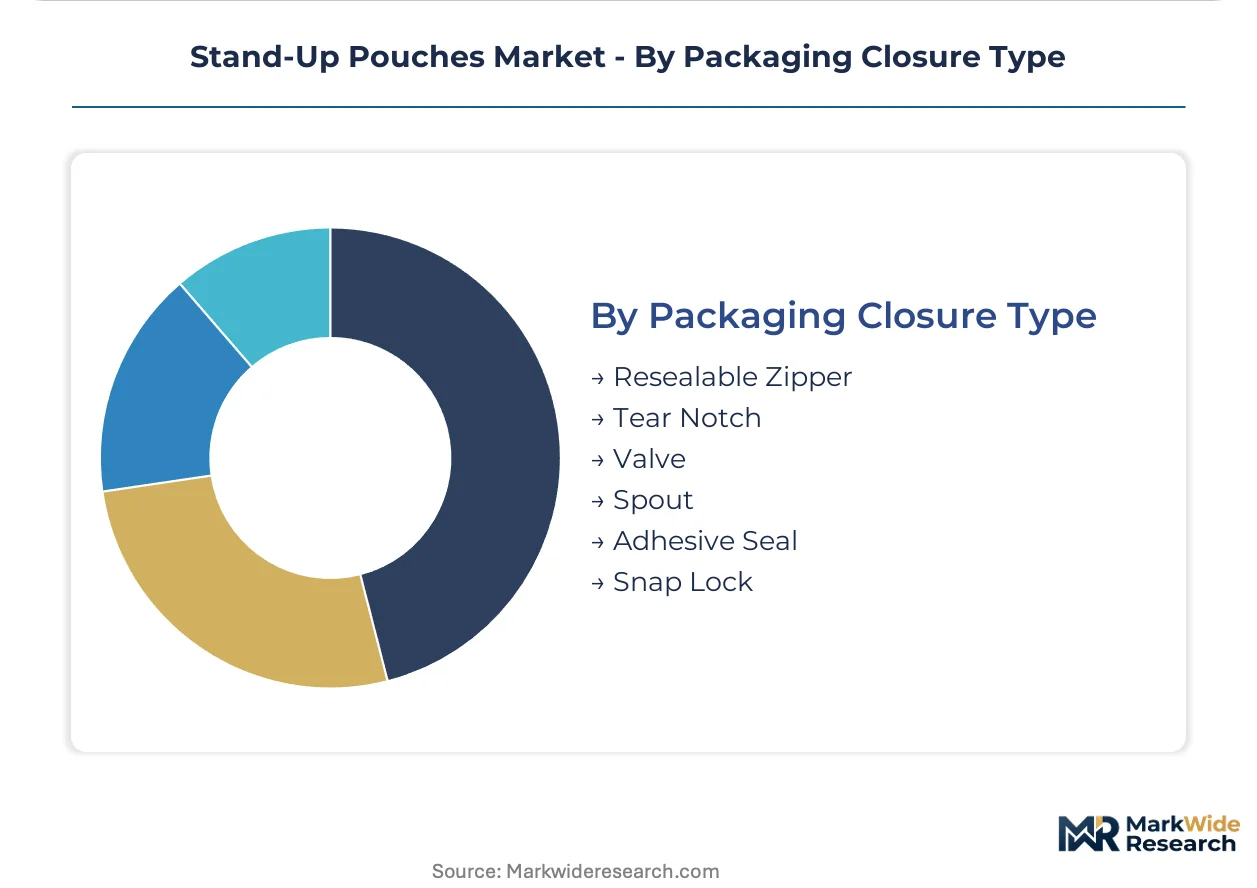
- Resealable Zipper:Allows multiple openings and reclosures, maintaining product freshness over time. Demand concentrates in pet food and snacks in Germany, driven by consumer preference.
- Spout:An integrated pouring mechanism, suitable for liquid and semi-liquid products. Demand is strong for beverages and liquid detergents in France, driven by dispensing ease.
- Tear Notch:Provides easy, single-use opening for various product types.
- Valve:Used for controlled gas release, particularly in coffee packaging.
- Adhesive Seal:Offers a basic, cost-effective closure for many applications.
- Snap Lock:Provides a secure, audible closure, often for dry goods.
Resealable zippers are prevalent for dry goods, while spouts demonstrate the steepest expansion trajectory for liquid applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory initiatives like the EU Green Deal and China's dual carbon goals are accelerating the shift towards sustainable stand-up pouch designs. These mandates compel brand owners to redesign packaging for circular economy targets. Simultaneously, organized retail expansion in India creates new channels for shelf-stable pouches.
United States
The US market sees strong demand from premium pet food brands migrating from rigid containers to stand-up pouches. FDA regulations govern food contact materials, influencing polymer selection for these applications. E-commerce platforms in major US cities like New York and Los Angeles prioritize robust, leak-proof designs for liquid refills.
Germany
Germany's market for stand-up pouches benefits from consumer preference for resealable zippers in snacks and pet food. The EU Green Deal initiatives drive demand for recyclable monomaterial pouches, aligning with circular economy goals. Packaging converters in regions like North Rhine-Westphalia are investing in machinery for sustainable laminates.
India
India's market expansion is linked to the rapid growth of organized retail and e-commerce platforms for consumer convenience. FSSAI regulations for food contact materials shape material choices for pouches across diverse product categories. Major metropolitan areas like Mumbai and Delhi show high demand for shelf-stable, retail-ready packaging.
China
China's dual carbon goals incentivize manufacturers to lightweight packaging and explore alternatives to multi-layer films. GB standards influence the design of simplified laminate structures for the country's vast food and personal care industries. Research and development clusters in the Yangtze River Delta focus on bio-based polymers for compliant packaging.
France
Demand in France is strong for spouted pouches in beverage and liquid detergent applications, driven by dispensing ease. European Food Safety Authority (EFSA) guidelines impact polymer and adhesive selection for food contact materials. Packaging innovators in cities like Lyon are developing monomaterial solutions for enhanced recyclability.
Stand-Up Pouches Market Key Industry Players
Player mix skews toward large, integrated packaging solution providers alongside specialized custom fabricators. The market exhibits a tiered structure, with global leaders, regional specialists, and niche innovators forming distinct archetypes. Dominant competitive moves include strategic partnerships for material innovation and capacity expansion to meet sustainability demands. Portfolio diversification into non-food applications also represents a key strategy.
At the scale-driven end, Amcor, a global leader, exemplifies extensive R&D capabilities and production scale to meet stringent standards for multinational clients. Mondi, another prominent player, occupies a position focused on sustainable paper and flexible plastic solutions, addressing evolving environmental mandates. ProAmpac, in contrast, represents a specialist archetype, emphasizing custom-engineered pouches for specific end markets like pharmaceuticals and personal care.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Mondi |
| Sealed Air |
| Sonoco Products Company |
| ProAmpac |
| Huhtamaki |
| Coveris |
| Smurfit Kappa |
| Others |
Cost & Logistics Intelligence
The capital-intensive nature of advanced converting machinery underwrites the pricing structure in the stand-up pouches market. This significant investment in production scale shapes both supply concentration among large players and establishes price floors for complex, high-barrier solutions.
Pricing Analysis
Certification level for food contact materials, such as BRCGS or FDA compliance, creates the primary spread in stand-up pouch pricing. Contract-based long-term offtake agreements dominate for large multinational clients. Price differentiation also stems from customization level, including specific barrier properties and integrated closure types. Pricing softness reflects input cost volatility for petroleum-derived polymers and aluminum foil. Small and medium-sized brands exhibit high price sensitivity, while global consumer packaged goods companies prioritize compliance and performance.
Supply Chain Analysis
Access to specialized polymer grades and advanced lamination technologies forms a chokepoint within the stand-up pouches supply chain. Supply concentration for base polymers like polyethylene and polypropylene centers in the US, China, and Saudi Arabia. Finished pouch converting capacity is significant in Germany, China, and India. The market relies heavily on petroleum-derived polymers and aluminum foil. Commodity price volatility for these raw materials poses a structural risk. Distribution primarily occurs through direct sales from converters to brand owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stand-up pouches market is experiencing an early-cycle expansion, driven by sustainability mandates like the EU Green Deal accelerating monomaterial adoption across diverse applications.
For Market Incumbents: Compound existing R&D capabilities for monomaterial laminate development, particularly all-PE structures, to maintain market leadership against emerging sustainable alternatives. Expand converting capacity in regions like Europe and India to meet growing demand for recyclable pouches. This proactively addresses the threat of substitution from alternative packaging formats and reinforces compliance with evolving regulatory standards. Strategic investment in new machinery for sustainable laminates represents a crucial lever.
For New Entrants and Emerging Players: Differentiate on specialized barrier properties for niche applications like pharmaceuticals or sustainable material innovation in bio-based polymers. Target non-food applications such as liquid detergents and automotive fluids, where the lightweight and dispensing advantages are pronounced. Regional food brands in emerging markets, particularly in India, present a penetrable segment. A compelling go-to-market angle involves emphasizing enhanced recyclability and a reduced carbon footprint.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated mid-cap specialists with strong intellectual property in monomaterial film technologies. The market's long-term viability remains favorable over the next decade, driven by sustained regulatory pushes for circularity and evolving consumer convenience demands. Acquisition targets include converters possessing proprietary monomaterial film formulations or those actively investing in advanced recycling infrastructure. The scalability of chemical recycling technologies for flexible plastics represents a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Monomaterials | Increases production of recycle-ready pouches to meet EU Green Deal targets. |
| Chemical Recycling Partnerships | Secures supply of post-consumer recycled content for food-contact applications. |
| Non-Food Application Diversification | Captures new revenue streams in industrial and household product categories. |
| Smart Packaging Integration | Enhances brand authentication and supply chain traceability for consumer goods. |
| Geographic Market Penetration (India) | Leverages rapid organized retail and e-commerce growth in an expanding economy. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary data involved conversations with packaging converters, brand owners across food and pet food segments, material suppliers, and recycling infrastructure operators. Secondary research encompassed regulatory reports from the EU Commission and FDA, industry association publications, and company annual reports. This approach facilitated bottom-up and top-down triangulation for robust data synthesis.
The analysis window extends across the projection horizon, utilizing a multi-dimensional analytical framework. Segmentation dimensions modeled include material type, application, end-user industry, closure type, and regional regulatory environment. Compound Annual Growth Rates were derived from historical trends, market dynamics, and projected shifts in demand and technology. Key forecast inputs included polymer price forecasts and regulatory compliance timelines for monomaterials.
Material uncertainties — including geopolitical events impacting raw material supply and unforeseen technological breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding the pace of regulatory enforcement and recycling infrastructure development. Practitioners should keep alternative scenarios live as sustainability regulations and consumer preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Kraft Paper Pouch Market
Pouch
Foam Pouch Market
Pouch
France Pouch Packaging Market
Pouch
Standcap Pouch Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Telemetry Pouch Market
Pouch
Stick Pouches Packaging Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Compostable Pouches Market
Pouch
Pouches Market
Pouch
Liquid Pouch Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Sterilization Pouches Market
Pouch
Latin America Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Global Pouches Packaging Market