
 Vietnam Plastic Caps and Closures Market | 2026-2036
Vietnam Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Plastic Caps and Closures Market Insights
Beverage packaging demand is decoupling from traditional glass and metal alternatives as Vietnam's bottled water and functional drink sectors expand. Duy Tan Plastic Company anchors domestic supply through extensive blow molding and injection molding infrastructure across northern and central provinces. Bericap Holding GmbH competes via technical closure designs for carbonated and still beverages, leveraging global R&D protocols localized for tropical storage conditions. Tetra Pak sustains its position through integrated carton-and-cap systems serving UHT dairy and juice segments where shelf stability requirements remain stringent.
Plastic caps and closures are threaded or snap-fit sealing devices manufactured through injection molding or compression molding of thermoplastic resins, typically engineered to specific torque-release values and dimensional tolerances for container integrity. Polypropylene dominates material selection for hot-fill and carbonated applications due to its creep resistance and stress-crack performance under internal pressure. Twist-off caps occupy the largest volume share across beverage and food segments, while biodegradable plastics represent the fastest-growing material category as brand owners respond to retailer sustainability mandates and consumer disposal concerns. Tamper-evident closure mechanisms command premium positioning in pharmaceutical and personal care channels where product safety verification carries regulatory weight.
Vietnam's Ministry of Natural Resources and Environment enforces circular economy roadmaps that restrict single-use plastics and mandate recycled content thresholds, directly influencing resin procurement strategies among domestic molders. The country's national standardization body applies food contact material safety protocols aligned with ASEAN harmonization frameworks, creating compliance benchmarks for exporters and import-substituting suppliers. Stakeholders must monitor how extended producer responsibility implementation affects cost structures and whether bioplastic scale-up investments outpace conventional polyolefin capacity additions in the Red River and Mekong deltas.
Market Dynamics
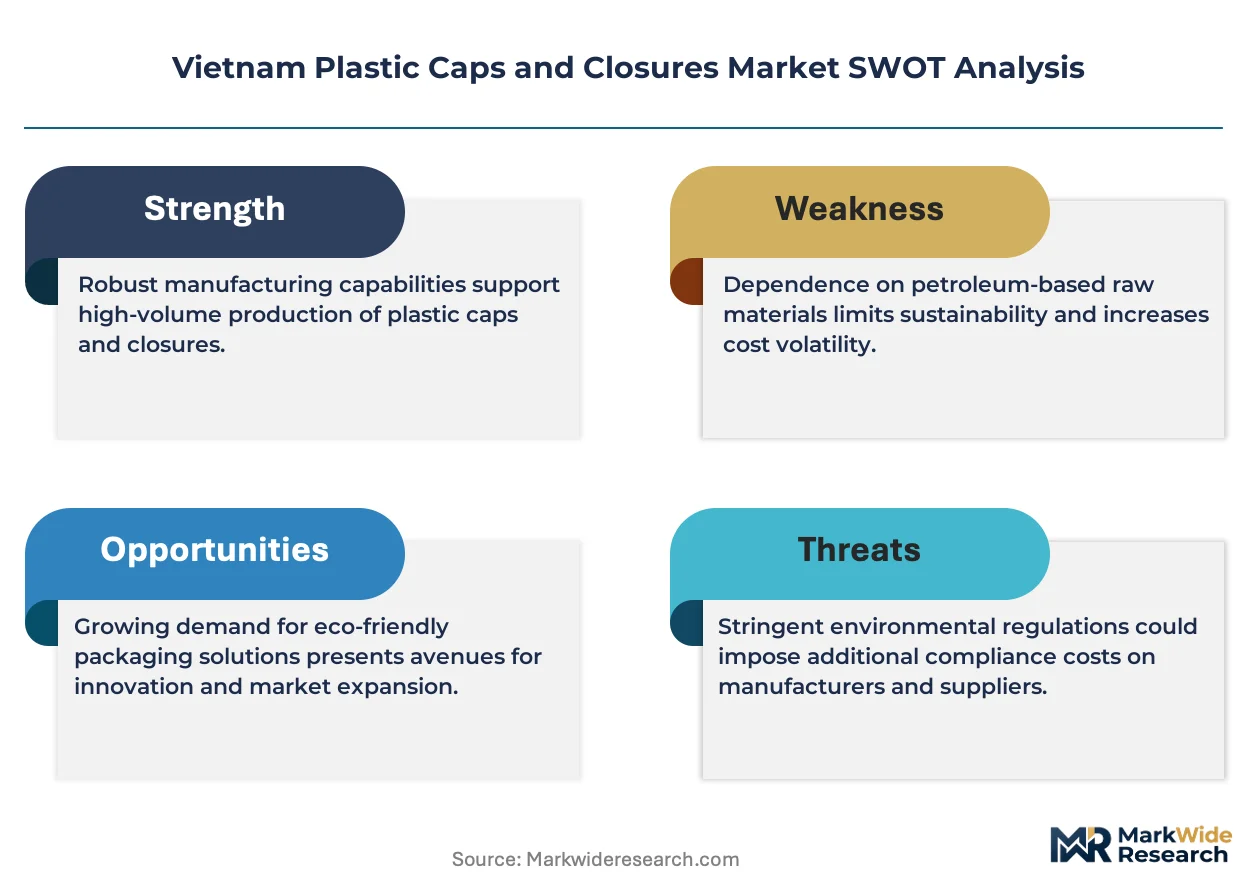
Vietnam's Ministry of Natural Resources and Environment is tightening circular economy mandates that force domestic molders to reconfigure resin sourcing and recycling infrastructure. This regulatory pressure is compressing margins for conventional polyolefin converters while accelerating bioplastic pilot investments.
Growth Catalysts
- Beverage Sector Expansion:Bottled water and functional drink producers in the southern industrial corridor around Ho Chi Minh City are displacing glass packaging with lightweight polypropylene closures. Conversion capacity clusters in Binh Duong province support just-in-time supply to these bottling plants.
- Extended Producer Responsibility Mandates:Vietnam's circular economy roadmap imposes recycled content thresholds on single-use packaging. Brand owners sourcing closures must now verify post-consumer resin traceability through certified domestic recyclers.
- Hot-Fill Processing Advances:Injection molding of creep-resistant polypropylene for carbonated applications is displacing polyethylene terephthalate closures in tropical storage conditions. Technical specifications from ASEAN harmonization frameworks guide torque-release engineering.
Market Restraints
- Feedstock Price Volatility:Naphtha-derived polypropylene resin costs fluctuate with regional petrochemical pricing, squeezing converter margins when oil benchmarks spike. Domestic molders lack long-term offtake agreements with integrated refiners.
- Import Dependency for Specialty Grades:Food-contact-compliant recycled polypropylene remains concentrated among Thai and Singaporean compounders. Vietnamese converters face extended lead times and currency exposure when sourcing these materials.
- Bioplastic Performance Gaps:Polylactic acid closures exhibit insufficient barrier properties for carbonated beverages under Vietnam's high-humidity storage conditions. Shelf stability failures limit adoption in premium beverage segments.
Strategic Opportunities
- Central Highlands Beverage Bottling:Underpenetrated provinces around Da Nang and Quy Nhon lack localized closure supply despite expanding mineral water extraction. First-mover molders can capture logistics savings over Ho Chi Minh City-based competitors.
- Pharmaceutical Tamper-Evident Demand:ANSM-aligned safety protocols for over-the-counter medicines create specification premiums for break-band closures. Domestic converters with cleanroom certification can displace European imports in this channel.
- Digital Printing Integration:Laser-etched QR codes on closures for traceability are converging with Vietnam's national product authentication database. Brand owners in the personal care segment are piloting these for anti-counterfeiting verification.
Industry Challenges
- Tooling Engineer Scarcity:Compression molding expertise for high-speed beverage closure production remains concentrated among technicians trained at foreign joint ventures. Domestic molders struggle to retain this talent against multinational compensation packages.
- Recycled Content Verification Lag:Third-party certification for post-consumer resin claims requires six-to-nine-month audit cycles. Brand owners launching sustainability SKUs face launch delays while documentation clears Vietnam's national standardization body protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Plastic Caps and Closures Market |
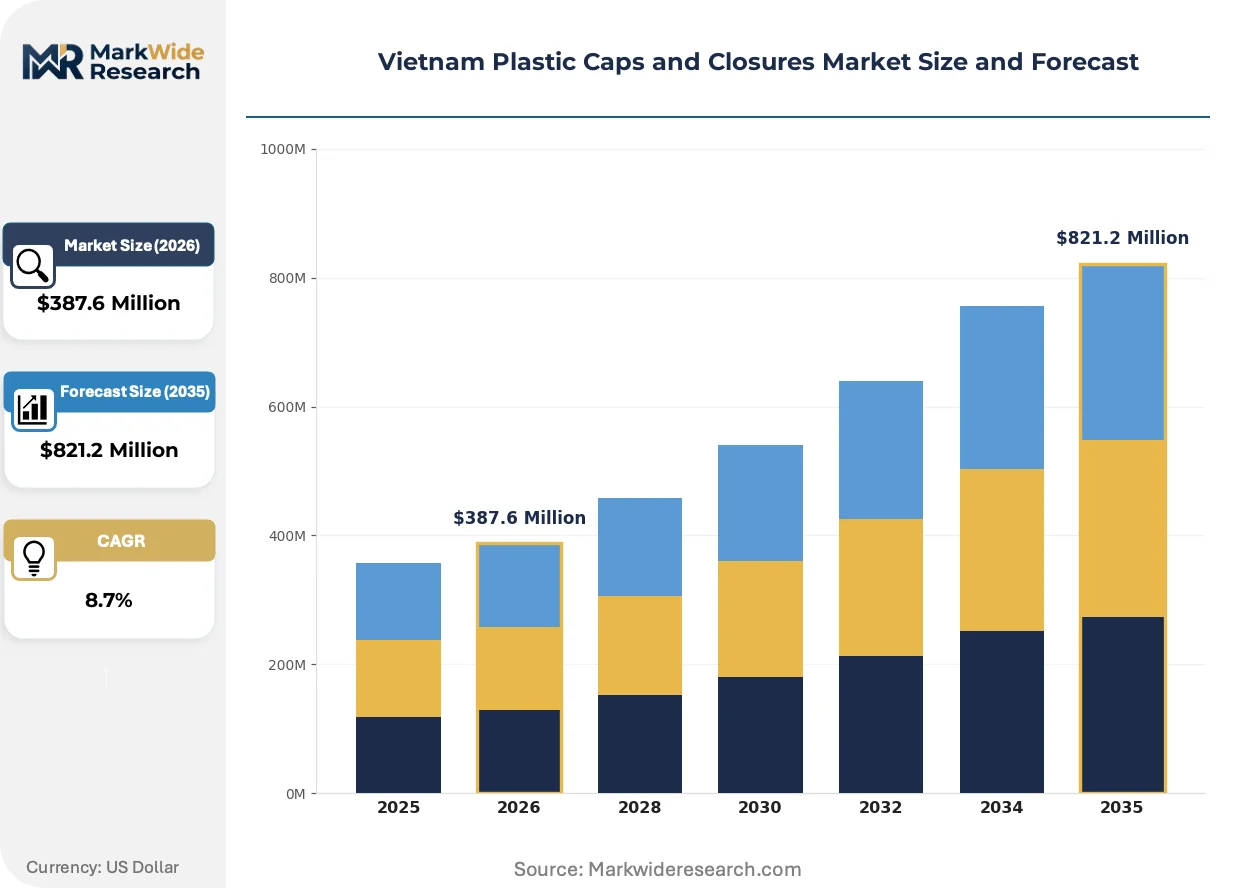
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Twist-off Caps, Snap-on Caps, Dropper Caps, Sports Caps Material: Polyethylene, Polypropylene, PVC, Biodegradable Plastics Application: Beverage Packaging, Pharmaceutical, Personal Care, Food Packaging Closure Mechanism: Child-resistant, Tamper-evident, Easy-open, Standard |
| Companies Covered | Duy Tan Plastic Company, Tetra Pak, Bericap Holding GmbH, Inplas Vietnam JSC, Indorama Ventures Vietnam, Vietnam Umano Co Ltd, Pavico Vietnam Joint Stock Company, VPP Co Ltd, Sai Gon Plastic Packaging JSC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Plastic Caps and Closures Market Trends and Innovations
Material science advances and regulatory compliance automation are restructuring how Vietnamese converters engineer closure performance and document supply chain provenance. Technical differentiation now hinges on tropical-condition durability and digital traceability integration.
Biodegradable closure compounds engineered from cassava-derived starch blends are expanding into premium bottled water segments where disposal visibility matters. Danang-based brand owners targeting eco-conscious urban consumers are specifying these for hotel and airport retail channels. The technology is compressing conventional polypropylene volumes in gift-packaged mineral water SKUs where unit economics tolerate material premiums.
Vietnam's Ministry of Natural Resources and Environment is phasing in mandatory recycled content percentages for plastic packaging through 2030 decrees. Domestic compounders must now establish post-consumer collection partnerships with municipal waste operators to secure feedstock. Food and beverage exporters to EU markets face dual compliance pressure from these national mandates and EU Green Deal border adjustment mechanisms.
Direct procurement relationships between beverage bottlers and specialized closure molders are displacing distributor-mediated supply in the Mekong Delta region. Large-format retail chains in Can Tho and Long An are demanding lot-level traceability that intermediaries cannot document. This channel compression is most visible among dairy processors requiring integrated carton-and-cap certification for UHT shelf-stable products.
Vietnam Plastic Caps and Closures Market Segmentation
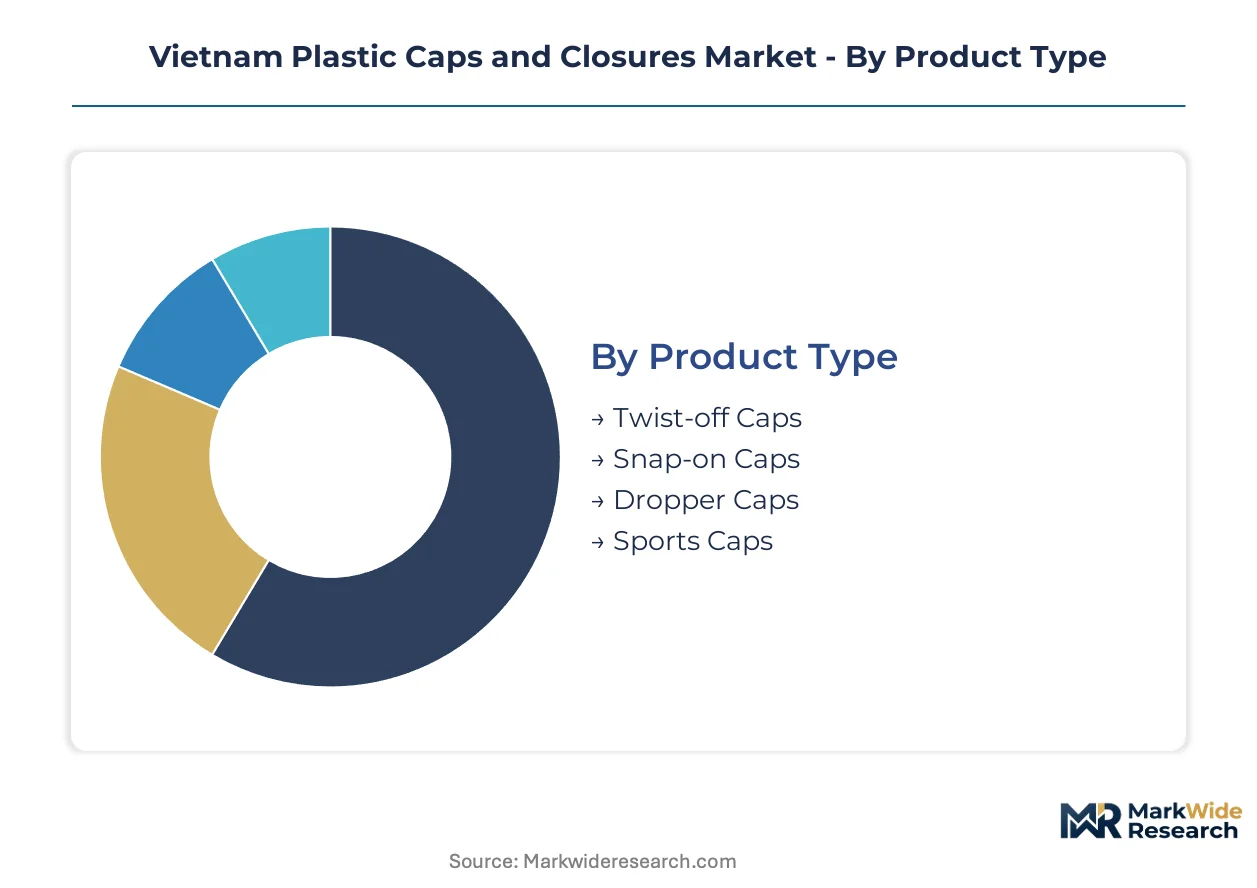
Segmentation in Vietnam's plastic caps and closures market reveals how converter investments align with regulatory pressure points and end-use performance requirements. Each dimension exposes different margin structures and compliance burdens that shape competitive positioning.
Product Type:
Supply concentration in southern Vietnam favors high-volume formats with standardized tooling and rapid changeover capabilities.
- Twist-off Caps:Threaded aluminum-plastic hybrid designs dominate carbonated beverage and sauce bottle applications. Demand clusters around Ho Chi Minh City bottling corridors where torque-release consistency under tropical humidity commands specification premiums.
- Snap-on Caps:Single-motion closure systems serve water and juice segments requiring frequent consumer access. Conversion lines in Binh Duong province run these at highest throughput rates, amortizing capital costs across billion-unit annual volumes.
- Dropper Caps:Precision-molded dosing closures serve pharmaceutical and essential oil packaging with tight dimensional tolerances.
- Sports Caps:Flip-top drinking spouts target functional beverage and bottled water segments with active lifestyle positioning.
Today's leader: Twist-off Caps. Tomorrow's challenger: Sports Caps.
Material:
Resin selection determines compliance pathways under Vietnam's circular economy mandates and tropical storage performance requirements.
- Polypropylene:Semi-crystalline thermoplastic with creep resistance under carbonation pressure and hot-fill sterilization cycles. Southern Vietnam's beverage bottlers specify this for shelf-stable products stored in unconditioned warehouses through monsoon seasons.
- Biodegradable Plastics:Cassava-starch and polylactic acid compounds are expanding in premium bottled water gift packs where disposal visibility influences purchase decisions. Danang-based brand owners specify these for hotel and airport retail channels despite unit cost premiums.
- Polyethylene:Flexible resin grades serve squeeze bottles and dairy applications with moderate barrier requirements.
- PVC:Rigid formulation closures persist in chemical and industrial container segments with established tooling investments.
Polypropylene captures current volume leadership. Biodegradable Plastics are climbing the fastest as Ministry of Natural Resources and Environment mandates tighten.
Application:
End-use concentration in Vietnam's southern economic corridor drives logistics optimization and just-in-time delivery investments.
- Beverage Packaging:Carbonated soft drink and bottled water producers in Binh Duong and Long An provinces consume closure volumes at scale. Duy Tan Plastic Company anchors supply through integrated blow molding and injection molding infrastructure with direct pipeline connections to bottling plants.
- Pharmaceutical:Over-the-counter medicine and supplement packaging demands tamper-evident and child-resistant mechanisms. Cleanroom-certified domestic converters are displacing European imports as ANSM-aligned safety protocols localize compliance verification.
- Personal Care:Shampoo and conditioner bottles specify flip-top and disc-top closures with cosmetic-grade surface finishes.
- Food Packaging:Condiment and cooking oil containers require oxygen barrier performance for shelf stability in tropical retail conditions.
Beverage Packaging commands installed capacity. Pharmaceutical applications are gaining share fastest on safety premium pricing.
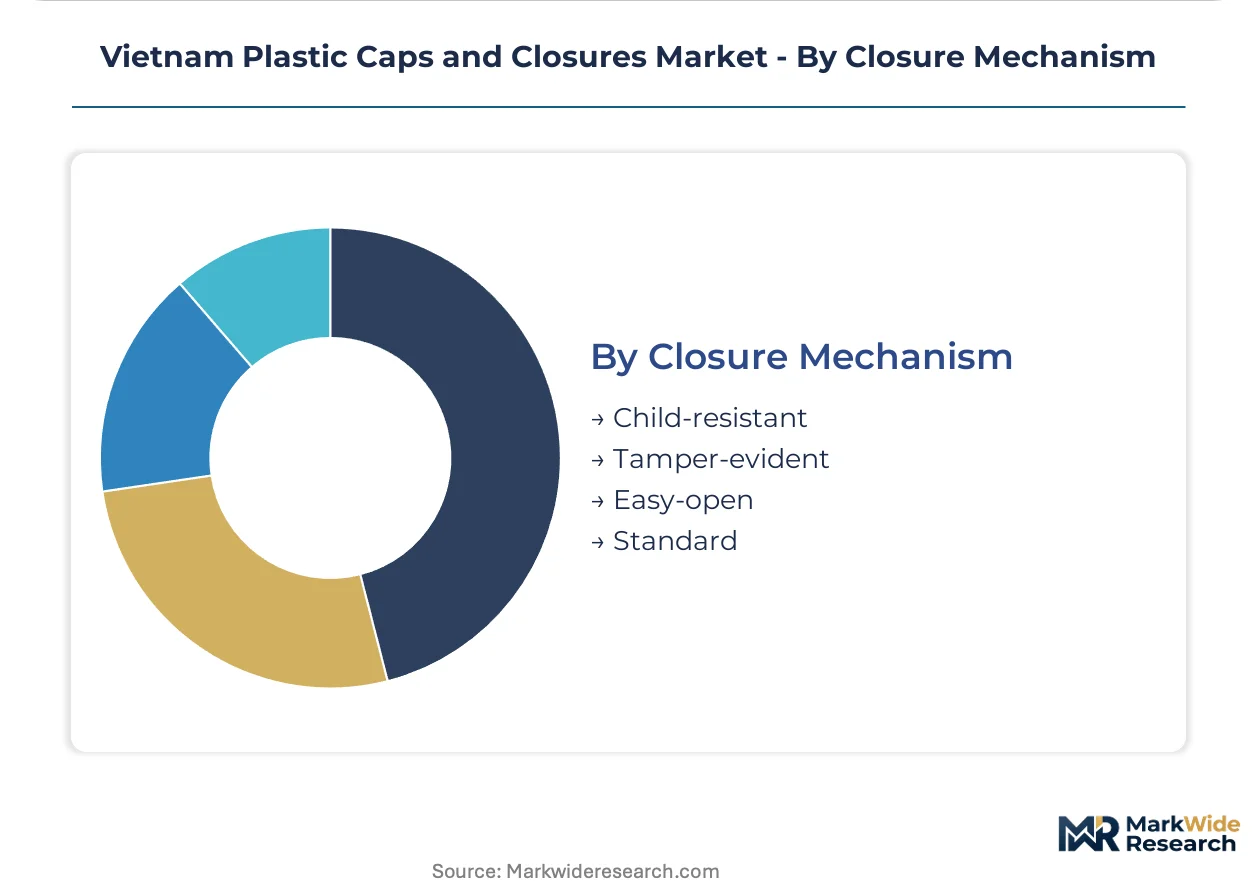
Closure Mechanism:
Mechanism complexity correlates with regulatory scrutiny and margin capture potential across end-use channels.
- Tamper-evident:Break-band and shrink-sleeve systems provide visible integrity verification for pharmaceuticals and premium beverages. Vietnam's national standardization body mandates these for export-oriented food and beverage producers seeking EU market access under Green Deal compliance frameworks.
- Child-resistant:Push-and-turn or squeeze-and-turn mechanisms serve pharmaceutical and household chemical segments. Domestic tooling engineers trained at foreign joint ventures retain scarce expertise for high-speed compression molding of these multi-component designs.
- Easy-open:Reduced torque specifications address aging demographics and accessibility requirements in personal care applications.
- Standard:Basic threaded and snap-fit designs serve cost-sensitive commodity segments with minimal regulatory burden.
Tamper-evident mechanisms lead on value per unit. Child-resistant designs are expanding most quickly on pharmaceutical safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward Vietnam's southern industrial corridor where compliance costs for circular economy mandates remain lower than northern provinces facing stricter provincial enforcement. This regulatory-arbitrage dynamic concentrates molding capacity around Ho Chi Minh City while central regions attract first-mover investments.
Southern Industrial Corridor
Beverage bottlers in Binh Duong and Long An provinces drive closure demand through just-in-time supply contracts. The Ministry of Natural Resources and Environment's recycled content thresholds apply here with delayed enforcement timelines. Conversion clusters along Highway 13 connect directly to Mekong Delta distribution networks.
Central Coast Region
Mineral water extraction around Da Nang and Quy Nhon creates underpenetrated demand without localized supply. Vietnam's national standardization body audits food-contact compliance for exporters targeting ASEAN markets. Danang-based brand owners pilot biodegradable closures for hotel retail channels.
Northern Red River Delta
Hanoi-centric pharmaceutical packaging demands tamper-evident mechanisms with cleanroom certification. Provincial environmental departments enforce circular economy decrees earlier than southern counterparts. Bac Ninh and Hai Duong host foreign joint ventures training scarce compression molding technicians.
Mekong Delta Sub-Region
Dairy processors in Can Tho require integrated carton-and-cap certification for UHT shelf-stable products. Extended producer responsibility implementation lags here, reducing compliance burdens for entry-level molders. Direct procurement relationships bypass distributor networks for lot-level traceability.
Central Highlands
Expanding mineral water extraction around Pleiku and Buon Ma Thuot lacks closure manufacturing proximity. The country's circular economy roadmap mandates eventual recycled content parity across all provinces. Logistics costs disadvantage Ho Chi Minh City-based suppliers serving this emerging cluster.
Vietnam Plastic Caps and Closures Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with beverage packaging favoring scale-driven OEM suppliers while pharmaceutical channels reward certified specialists. The structure fragments across three tiers: multinational technical designers, integrated domestic converters, and regional job-shop molders. Strategic archetypes include circular-economy-compliant compounders, tropical-condition engineering specialists, and traceability-integrated solution providers. Capacity expansion and backward integration into resin sourcing dominate competitive moves as converters secure feedstock against import volatility.
Among Vietnam-based integrated manufacturers, Duy Tan Plastic Company anchors domestic supply infrastructure across northern and central provinces. German-structured Bericap Holding GmbH occupies a position among technical closure designers serving carbonated applications. Tetra Pak exemplifies the integrated carton-and-cap systems archetype for UHT dairy segments. These three represent distinct competitive vectors: geographic coverage breadth, technical specification depth, and packaging system integration.
| Leading Market Players |
|---|
| Duy Tan Plastic Company |
| Tetra Pak |
| Bericap Holding GmbH |
| Inplas Vietnam JSC |
| Indorama Ventures Vietnam |
| Vietnam Umano Co Ltd |
| Pavico Vietnam Joint Stock Company |
| VPP Co Ltd |
| Sai Gon Plastic Packaging JSC |
| Others |
Pricing and Supply Chain Analysis
Large-format beverage bottlers in the southern industrial corridor command direct procurement relationships that compress distributor margins and enforce volume-based contract pricing. Vietnam's Ministry of Natural Resources and Environment recycled content mandates are layering compliance premiums onto resin costs, forcing converters to absorb or pass through these certification burdens.
Pricing Analysis
Distributor margins face compression as direct-to-OEM supply contracts displace intermediary layers in the Mekong Delta region. Pricing stratifies across premium, standard, and economy tiers based on certification grade for food-contact compliance and volume scale for annual offtake commitments. Cost compression in the standard tier is intensifying because naphtha-derived polypropylene resin fluctuates with regional petrochemical benchmarks. Small-scale dairy processors exhibit highest price sensitivity, while pharmaceutical brand owners sourcing tamper-evident mechanisms show lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Tooling engineer scarcity in Bac Ninh and Hai Duong provinces constrains compression molding capacity expansion for high-speed beverage closure production. Raw material sourcing draws from Thai and Singaporean compounders for food-contact-compliant recycled polypropylene, while virgin resin feeds from integrated Southeast Asian petrochemical complexes. Single-source vulnerability persists for specialty resin grades subject to currency exposure and extended lead times. Distribution runs through Highway 13 corridor networks connecting Binh Duong conversion clusters to Mekong Delta bottling plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's plastic caps and closures market functions as a regulatory compounder where circular economy mandates from the Ministry of Natural Resources and Environment are accelerating compliance-driven procurement decisions and reshaping converter investment priorities.
For Market Incumbents: Anticipate margin compression from bioplastic pilot investments and extended producer responsibility implementation by securing backward integration into post-consumer resin collection partnerships with municipal waste operators. Duy Tan Plastic Company and integrated domestic converters should prioritize cleanroom certification investments to defend pharmaceutical tamper-evident positioning against European import displacement. For New Entrants and Emerging Players: Underpenetrated mineral water bottlers in the Central Highlands around Pleiku and Buon Ma Thuot represent the most accessible buyer archetype for first-mover closure molders seeking logistics advantages over Ho Chi Minh City-based competitors. Target direct procurement relationships with dairy processors in Can Tho requiring integrated carton-and-cap certification, leveraging lot-level traceability capabilities that distributor networks cannot document. For Investors and Strategic Acquirers: Beverage packaging OEMs seeking captive supply security represent the most active acquirer in this space, with strategic buyer windows opening for compounders demonstrating circular-economy-compliant resin sourcing. Acquisition targets should exhibit tropical-condition engineering expertise and ASEAN harmonization framework certification. Practitioners should monitor bioplastic scale-up investment pacing against conventional polyolefin capacity additions as inflection signals for material substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Secures polypropylene feedstock against Thai and Singaporean import volatility for domestic molders. |
| Cleanroom Certification Investment | Enables ANSM-aligned pharmaceutical closure production displacing European import dependency. |
| Bioplastic Pilot Scale-Up | Positions converters for Ministry of Natural Resources and Environment recycled content mandates. |
| Direct Procurement Relationship Building | Bypasses distributor networks for lot-level traceability demanded by Mekong Delta dairy processors. |
| Geographic Expansion to Central Highlands | Captures logistics savings serving underpenetrated mineral water extraction around Pleiku and Buon Ma Thuot. |
Research Methodology
Multiple input streams — structured interviews with plant managers at conversion facilities, procurement leads at beverage bottlers, and technical R&D directors at resin compounders — were reconciled against customs and trade data, SEC filings from multinational packaging groups, and ASEAN harmonization framework documentation. Bottom-up capacity assessments across Binh Duong and Long An provinces were triangulated with top-down demand modeling from national beverage production statistics.
Data-stream reconciliation across product type, material grade, application vertical, and closure mechanism dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating hot-fill processing adoption curves and circular economy compliance phase-in schedules. Forecast inputs included naphtha price volatility assumptions and bioplastic performance gap resolution timelines.
Inputs from converter facility audits and regulatory filing databases were available through the study window; gaps in real-time post-consumer resin certification audit cycles introduce uncertainty bands around sustainability SKU launch timing assumptions. Forecasts reflect documented assumptions regarding Ministry of Natural Resources and Environment enforcement timelines and EU Green Deal border adjustment mechanism implementation. Practitioners should monitor bioplastic barrier property improvements and extended producer responsibility decree specifics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Drop Sealers Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
PCR Closures Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
PET Dome Lids Market