
 GCC Retort Pouches Market | 2026-2036
GCC Retort Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Retort Pouches Market Intelligence
Saudi polymer compounding capacity is shifting toward high-barrier coextrusion grades suited for retort applications. Amcor plc leverages regional toll manufacturing partnerships to sustain supply continuity across Gulf food processors. Huhtamaki anchors its position through specialized lidding and pre-made pouch formats designed for Middle Eastern ambient meals. Mondi competes on vertically integrated kraft-paper hybrid structures that address sustainability mandates without sacrificing thermal resistance.
Retort pouches are multilayer flexible packages engineered from polyester, aluminum foil, and polypropylene laminates that withstand sterilization temperatures between 121°C and 135°C while maintaining oxygen transmission rates below 0.1 cc per square meter per day. Their primary commercial purpose is to replace metal cans and glass jars for shelf-stable food and pharmaceutical products requiring extended ambient storage without refrigeration. Stand-up pouches command premium positioning in the GCC due to enhanced retail shelf presence and consumer convenience for rehydrated rice and curry products. Aluminum foil laminates retain dominant share in high-acid and long-life applications where absolute barrier integrity determines shelf life. Flat pouches persist in institutional catering and military ration packs where cost minimization outweighs display requirements.
Gulf Standards Organization (GSO) food-contact material standards and Saudi Food and Drug Authority (SFDA) sterilization validation protocols govern laminate composition, migration limits, and label claims across the six member states. UAE's Ministry of Industry and Advanced Technology enforces conformity assessment procedures that delay market entry for uncertified imported films. Stakeholders must monitor evolving extended producer responsibility frameworks and local content thresholds that could redirect procurement toward Gulf-based extrusion and conversion assets.
Market Dynamics
High-barrier coextrusion capacity expansion across Saudi Arabia and the UAE is compressing lead times for Gulf food processors while reshaping supplier qualification protocols. Local polymer compounding investments now determine which laminate converters capture share in ambient halal meal packaging.
Growth Catalysts
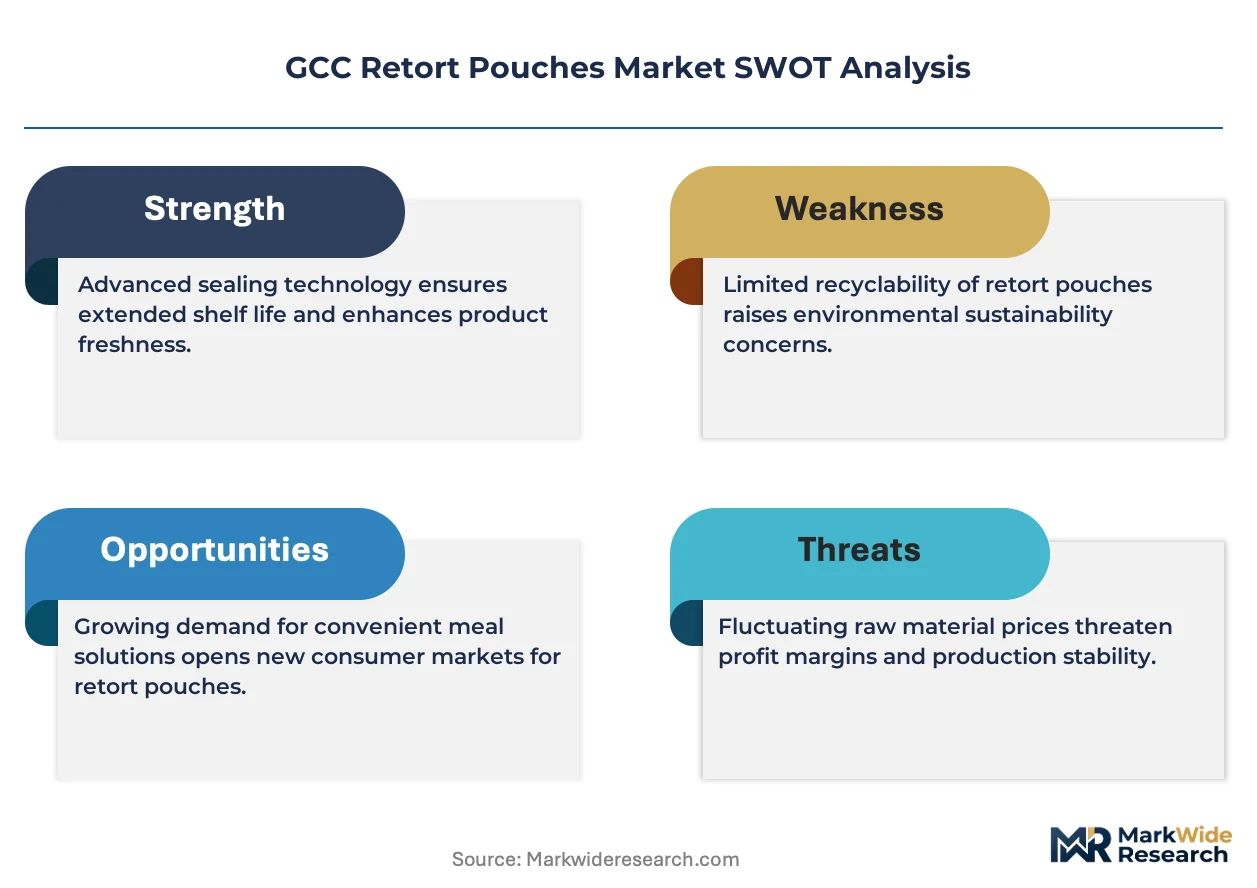
- SFDA Sterilization Validation:Saudi Food and Drug Authority protocols for thermal process verification are standardizing retort pouch specifications across the Kingdom's centralized food processing zones.
- Ready-to-Eat Halal Meals:Saudi Arabia's domestic catering sector and military ration programs are displacing metal cans with flat and stand-up pouch formats for field-deployable protein dishes.
- Polypropylene Supply Localization:Petrochemical feedstock integration in Jubail Industrial City is shortening film supply chains for converters serving Riyadh and Jeddah food manufacturers.
Market Restraints
- Aluminum Foil Price Volatility:Gulf converters remain exposed to LME aluminum fluctuations and rolling mill capacity constraints in European and Asian supply bases.
- GSO Conformity Assessment Delays:UAE Ministry of Industry and Advanced Technology certification timelines extend market entry for imported high-barrier films by 4-8 months.
- Metal Can Substitution Resistance:Traditional date paste and condensed milk packers in Saudi Arabia's Eastern Province maintain capital-intensive canning lines with sunk cost inertia.
Strategic Opportunities
- Oman and Bahrain Underpenetration:These smaller GCC states lack domestic retort pouch conversion capacity, creating toll manufacturing openings for Saudi and UAE-based laminators.
- Kraft-Paper Hybrid Structures:Mondi's vertically integrated fiber-based laminates align with emerging extended producer responsibility frameworks across Gulf municipal waste systems.
- E-Commerce Ambient Meal Channels:Direct-to-consumer halal meal subscriptions in Dubai and Riyadh are generating demand for individually portioned retort pouches with resealable features.
Industry Challenges
- Multi-Layer Extrusion Technician Scarcity:Gulf technical institutes produce insufficient operators capable of calibrating seven-layer coextrusion lines for oxygen transmission specifications below 0.1 cc per square meter per day.
- Legacy Canning Line Integration:Food processors retooling from metal to flexible formats face conveyor system incompatibility and retort basket reconfiguration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Retort Pouches Market |
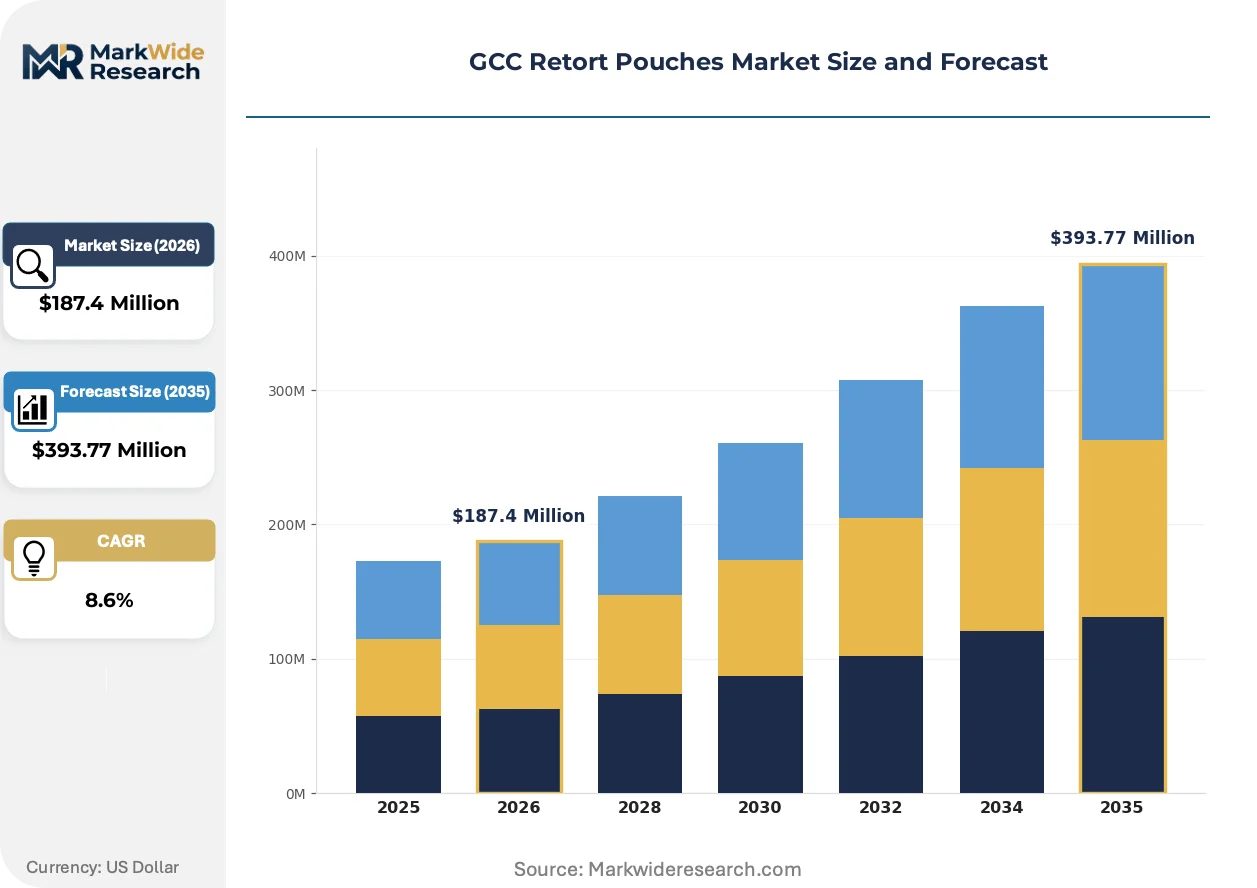
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Zipper Pouches, Spouted Pouches Material: Polyester, Polypropylene, Nylon, Aluminum Foil End User: Food & Beverage, Pharmaceuticals, Pet Food, Household Products Capacity: 100ml, 250ml, 500ml, 1L |
| Companies Covered | Sealed Air, Coveris, Amcor plc, Constantia Flexibles, Huhtamaki, ProAmpac, Sonoco Products Company, HPM Global, Mondi, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Retort Pouches Market Strategic Shifts & Innovations
Material science advances and regulatory stringency are converging to redefine barrier performance benchmarks across Gulf food packaging. Three developments are compressing technology adoption cycles and reshaping procurement criteria.
High-barrier coextrusion grades with ethylene vinyl alcohol (EVOH) core layers are rewriting the economics of aluminum-free retort structures. Saudi polymer compounders in SABIC's ecosystem are qualifying these films for 135°C sterilization cycles. Regional food processors in Riyadh's Sudair Industrial City are trialing foil replacement for acidic sauce applications previously requiring absolute oxygen barrier integrity.
GSO 2231 food-contact material standards are mandating migration testing protocols that exceed legacy Gulf technical regulations. The standard's heavy metal and primary aromatic amine limits are disqualifying legacy adhesive systems from China and Southeast Asia. UAE-based laminate importers are restructuring supplier audits to capture conformity assessment documentation prior to customs clearance.
Consolidated procurement by Saudi Arabia's National Food Security Program is compressing supplier qualification timelines while elevating technical service requirements. Single-source contracts for military and institutional ration packs now specify 24-month shelf life validation with accelerated aging protocols. This buyer concentration is visible in Riyadh's Al-Kharj Road corridor, where three processors account for the majority of ambient halal meal pouch demand.
GCC Retort Pouches Market Segmentation
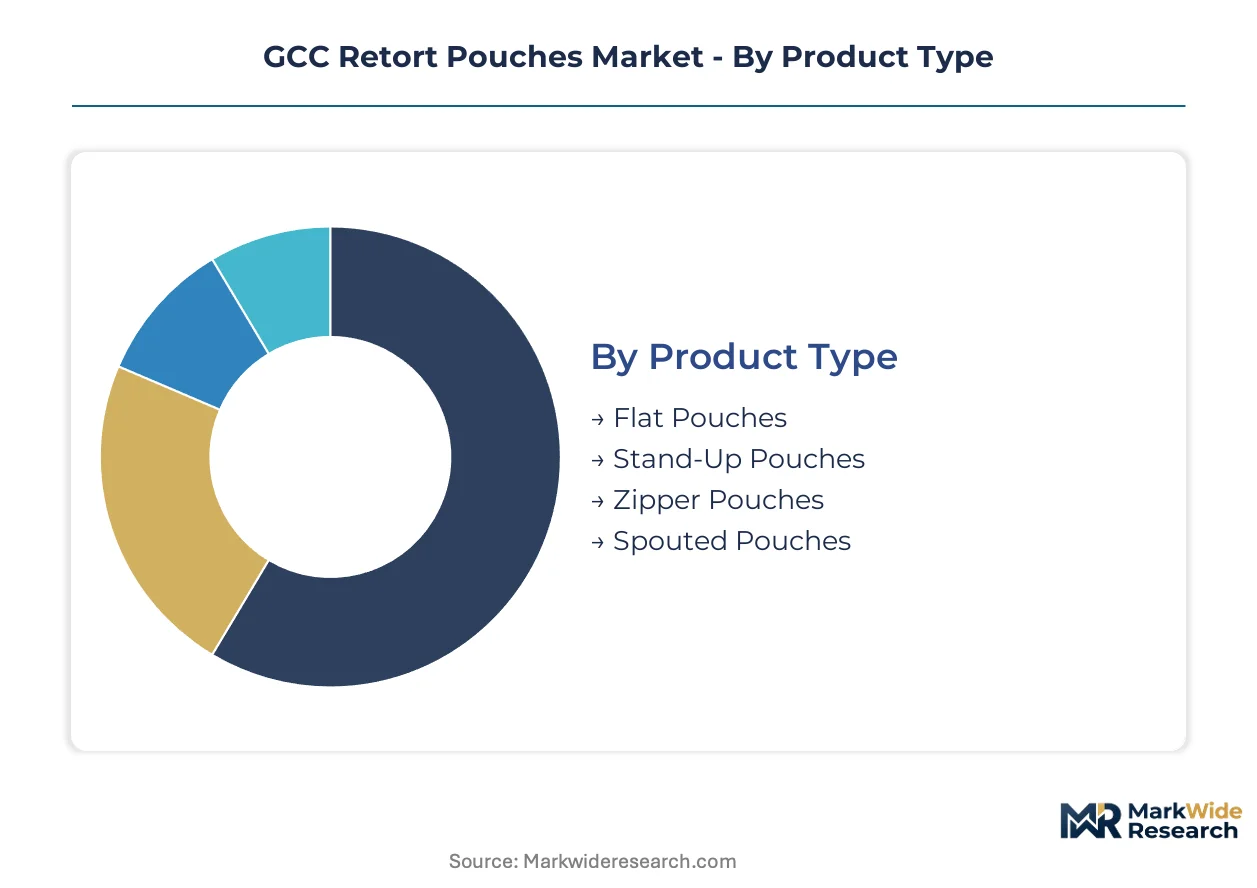
Retort pouch segmentation in the GCC reflects divergent technical requirements across sterilization protocols, barrier specifications, and filling line compatibility. Each dimension shapes procurement decisions differently for Saudi military ration contractors versus UAE pharmaceutical packers.
Product Type:
Standalone pouch formats dominate ambient meal applications, while embedded spout and zipper systems serve specialized dispensing needs.
- Flat Pouches:Two-dimensional laminates with three-side seal construction optimize pallet density for institutional catering and military field rations. Saudi Arabia's National Food Security Program procurement concentrates demand in Riyadh's Al-Kharj Road corridor, where cost minimization outweighs retail display requirements for bulk halal protein dishes.
- Stand-Up Pouches:Doyen-style bottom gussets create vertical shelf presence for rehydrated rice and curry products in Saudi hypermarkets and UAE convenience retail. Premium positioning in Dubai's e-commerce ambient meal channels drives specification for resealable fitments and matte finish laminates.
- Zipper Pouches:Press-to-close interlocking strips enable multi-serve consumption for household sauce and paste applications.
- Spouted Pouches:Fitment-integrated formats target controlled dispensing of condensed milk and date syrup in Saudi Arabia's Eastern Province.
Volume placements concentrate in flat pouches; the faster expansion belongs to stand-up pouches.
Material:
Cost tiers separate commodity polyolefins from engineered barrier laminates with metalized or foil layers.
- Polyester:Biaxially oriented polyethylene terephthalate provides dimensional stability and print receptivity as the outer structural layer in multilaminates. Saudi converters in Jubail Industrial City specify 12-micron grades for high-speed form-fill-seal lines serving Riyadh food processors.
- Aluminum Foil:7-9 micron rolled aluminum delivers absolute oxygen and light barrier for long-life acidic sauces and pharmaceutical sterilization. Gulf converters remain exposed to LME price volatility and European rolling mill capacity constraints.
- Polypropylene:Cast and oriented grades seal against themselves and accept retort sterilization without delamination.
- Nylon:Polyamide layers provide puncture resistance for bone-in meat and abrasive spice formulations.
Polyester and aluminum foil command premium positioning; polypropylene represents the fastest-growing trajectory as SABIC ecosystem compounders localize supply.
End User:
Application maturity separates established food sterilization from emerging pharmaceutical validation.
- Food & Beverage:Ambient halal meals, shelf-stable sauces, and ready-to-eat rice dishes constitute the volume anchor across Saudi centralized processing zones and UAE free zone manufacturing. SFDA sterilization validation protocols standardize laminate specifications for thermal process verification.
- Pharmaceuticals:Parenteral nutrition and enteral feeding solutions require sterile barrier validation exceeding food-grade migration limits. UAE's MOHAP enforcement creates qualification delays for uncertified imported films.
- Pet Food:Wet and semi-moist formulations in premium positioning target expatriate households in Dubai and Abu Dhabi.
- Household Products:Aggressive chemical compatibility limits penetration to specialty industrial cleaners.
Food and beverage absorbs dominant placement; pharmaceuticals are climbing the fastest as Gulf health systems expand enteral nutrition programs.
Capacity:
Customer type stratification separates individual portion control from foodservice scale.
- 100ml:Single-serve condiment and pharmaceutical dose formats align with airline catering and hospital tray specifications. Dubai's direct-to-consumer halal meal subscriptions generate specification for portion-controlled curry and sauce sachets.
- 500ml:Family-size rice and stew formats match Saudi household consumption patterns for communal dining.
- 250ml:Personal meal solutions target office worker lunch segments in Riyadh and Jeddah.
- 1L:Institutional scale for catering and military field kitchens.
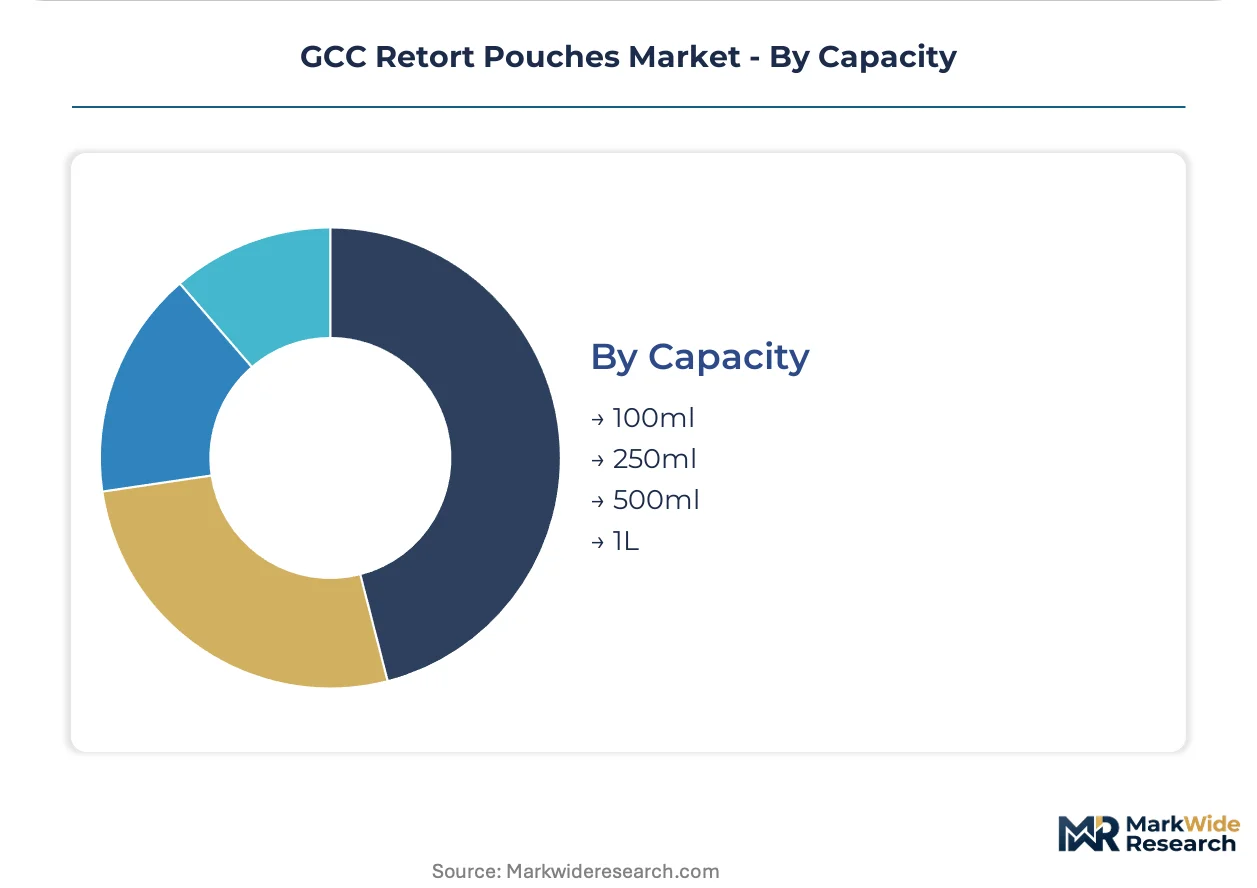
500ml placements lead current volume; 100ml formats gain share fastest through e-commerce subscription channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City's petrochemical integration anchors polymer feedstock supply for GCC retort pouch converters. Saudi Arabia and the UAE concentrate conversion capacity near their respective processing corridors. Smaller Gulf states rely on cross-border toll manufacturing from these centers.
Saudi Arabia
SFDA sterilization validation protocols standardize laminate specifications for Riyadh's Al-Kharj Road food processors. The National Food Security Program consolidates procurement for military and institutional ration packs. Sudair Industrial City hosts trials of EVOH-core coextrusion films for acidic sauce applications.
United Arab Emirates
Dubai's direct-to-consumer halal meal subscriptions generate specification for resealable stand-up pouches. MOHAP enforcement creates qualification delays for uncertified imported pharmaceutical films. Jebel Ali free zone manufacturing clusters serve as re-export hubs for Omani and Bahraini markets.
Oman
Domestic retort pouch conversion capacity remains underdeveloped across Muscat and Sohar industrial zones. Food manufacturers import pre-made pouches through UAE-based toll arrangements. The country's national investment authority targets packaging localization under downstream diversification mandates.
Bahrain
Pharmaceutical packaging demand from Bahrain's health ministry outpaces local barrier film supply. Convertors in Saudi Arabia's Eastern Province capture cross-border toll contracts. Sitra industrial area hosts limited pre-made pouch finishing operations without extrusion capability.
Kuwait
Ministry of Commerce and Industry import regulations prioritize Gulf-origin packaging materials for food security stockpiles. Shuaiba industrial zone lacks multilayer coextrusion infrastructure. Local processors source laminates through Dubai trading houses with GSO conformity pre-certification.
GCC Retort Pouches Market Key Industry Players
Global majors compete with regional champions across high-barrier laminate supply and toll conversion services. Market structure tiers between integrated petrochemical players, specialized converters, and trading intermediaries. Three archetypes dominate: SABIC ecosystem compounders supplying base films, European multinationals with Gulf toll partnerships, and regional distributors managing GSO certification logistics. Capacity expansion and backward integration into polymer compounding represent the primary competitive moves reshaping supplier qualification protocols.
Among European-based packaging multinationals, Amcor plc and Huhtamaki occupy positions exemplifying toll manufacturing and specialized format strategies respectively. Mondi represents the sustainability-driven archetype through fiber-based hybrid structures. These three companies anchor the premium tier where technical service capabilities and GSO conformity documentation determine contract awards from Saudi Arabia's consolidated food security procurement.
| Leading Market Players |
|---|
| Sealed Air |
| Coveris |
| Amcor plc |
| Constantia Flexibles |
| Huhtamaki |
| ProAmpac |
| Sonoco Products Company |
| HPM Global |
| Mondi |
| Others |
Cost & Logistics Intelligence
Multi-layer coextrusion technician scarcity in Saudi Arabia's Eastern Province widens labor-cost differentials between Gulf-based converters and Asian import suppliers, compressing pricing-tier spreads for standard-grade laminates while sustaining premiums for validated high-barrier structures.
Pricing Analysis
Technical service bundling separates Gulf-based converter pricing from Asian import quotes, with sterilization validation support and SFDA documentation included in domestic contracts but unbundled from offshore supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance and certification completeness. Pricing pressure stems from SABIC ecosystem compounders localizing polypropylene feedstock and compressing base film margins. Military and institutional ration packers under the National Food Security Program exhibit lowest price sensitivity, while small-scale sauce processors in Saudi Arabia's Eastern Province prioritize unit cost minimization.
Supply Chain Analysis
Container freight rates from European rolling mills and Asian adhesive suppliers feed directly into landed cost structures for aluminum foil and specialty lamination chemistries. Raw material supply draws from Saudi petrochemical complexes in Jubail Industrial City, European aluminum rolling capacity, and Chinese adhesive manufacturing. Single-source vulnerability concentrates in 7-9 micron foil grades where European mill allocations determine Gulf converter throughput. Distribution runs through Dubai trading houses with GSO pre-certification for re-export to Oman, Bahrain, and Kuwait.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around sterilization validation capabilities, with SFDA protocol complexity forcing undercapitalized trading intermediaries toward exit or acquisition.
For Market Incumbents: Cement barrier film supply relationships with SABIC ecosystem compounders to secure feedstock priority as polypropylene localization accelerates. Acquire toll manufacturing capacity in Oman's underdeveloped industrial zones before national investment authority mandates force local content thresholds. SFDA sterilization validation documentation represents the critical lever for defending military and institutional procurement share against Asian import competition.
For New Entrants and Emerging Players: EVOH-core coextrusion technology without aluminum foil layers offers a defensible wedge for acidic sauce applications previously requiring absolute oxygen barriers. Target Bahrain's pharmaceutical packaging demand where MOHAP-equivalent validation requirements create qualification delays for uncertified imports. Pursue toll manufacturing partnerships with Saudi Eastern Province converters seeking foil-free laminate trials for cost reduction.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale laminators possessing existing GSO conformity assessment documentation given UAE Ministry of Industry and Advanced Technology enforcement timelines extending market entry for uncertified competitors. Acquisition focus should center on converters with validated 135°C sterilization protocols and established relationships with Riyadh's Al-Kharj Road food processors. Watch for National Food Security Program single-source contract awards as inflection indicators for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | SABIC ecosystem partnerships in Jubail Industrial City shorten lead times for Riyadh food processors. |
| GSO Conformity Pre-Certification Investment | UAE Ministry of Industry and Advanced Technology documentation accelerates customs clearance for Dubai trading houses. |
| EVOH-Core Coextrusion Qualification | Sudair Industrial City trials validate aluminum-free structures for 135°C acidic sauce sterilization cycles. |
| Toll Manufacturing Network Expansion | Omani and Bahraini demand capture without domestic extrusion infrastructure investment requirements. |
| Technical Service Capability Buildout | SFDA sterilization validation support differentiates Gulf-based converters from Asian import suppliers. |
Research Approach
Trade databases, petrochemical industry associations, and Gulf regulatory filings formed the secondary backbone, supplemented by primary interviews with multi-layer extrusion technicians, SFDA compliance officers at Saudi food processors, procurement managers within the National Food Security Program, and Dubai-based laminate trading house operators. Bottom-up and top-down triangulation validated volume estimates across product type, material composition, and end-use segments.
Bottom-up modeling anchored projections across the analysis window, with top-down macro checks against regional food processing capacity expansion and military ration procurement budgets. Segmentation dimensions included pouch format, barrier technology tier, sterilization protocol, and customer scale. CAGRs derived from fitted growth curves incorporating SABIC polymer supply localization timelines and GSO regulatory enforcement trajectories. Forecast inputs incorporated aluminum foil price volatility assumptions and extended producer responsibility framework adoption patterns across Gulf municipal waste systems.
Several conditions sit outside the modeled scope, including sudden LME aluminum price spikes, unilateral GSO standard revisions, and military procurement budget reallocations. Forecasts reflect documented assumptions about sterilization validation timeline stability and polymer compounding capacity ramp schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Inflatable Pouches Market
Pouch
Vietnam Pouch Packaging Market
Pouch
High-Barrier Pouches Market
Pouch
Foil Zipper Bags Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Stand Up Paper Pouches Market
Pouch
Stand-Up Pouches Market
Pouch
Spouted Pouches Market
Pouch
MAP Flow Wrappers Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Flat Bottom Pouch Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Feed Pouches Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Compostable Pouches Market