
 Morocco Pouch Packaging Market | 2026-2036
Morocco Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Pouch Packaging Market Insights
REACH compliance is realigning the cost-of-entry calculus for imported laminate substrates, forcing domestic converters to certify supply chains or absorb border-testing penalties. Amcor Group GmbH leverages its European regulatory infrastructure to pre-qualify multi-layer films for Moroccan food-contact applications. Mondi PLC anchors its Maghreb position through integrated kraft paper sourcing that bypasses volatile resin import duties. Sealed Air Corporation differentiates via vacuum-shrink barrier technologies tailored to Morocco's expanding processed meat and dairy segments.
Pouch packaging denotes flexible primary containers formed from heat-sealed films or laminates, typically ranging from 50 microns to 250 microns in total caliper, engineered to provide moisture barriers, oxygen scavenging, or resealability for shelf-stable goods. Stand-up pouches with spouted fitments dominate beverage and liquid food formats due to their retail shelf presence and reduced material intensity versus rigid alternatives. Plastic laminates lead material value given their prevalence in retort and high-barrier applications, though paper-based composites are gaining structural share as Moroccan retailers impose plastic-reduction targets. FMCG end users command the volume anchor, with pharmaceutical-grade barrier pouches representing a concentrated margin pool served by certified cleanroom converters.
Morocco's Ministry of Industry and Trade enforces conformity assessment protocols aligned with UNECE packaging standards, while the country's national standards body (IMANOR) certifies food-contact material migration limits under regional harmonization with CODEX principles. These frameworks elevate testing costs for imported substrates but create protected terrain for locally certified converters. Stakeholders must monitor imminent revisions to Morocco's packaging waste decree, as deposit-return pilots for flexible formats could restructure collection economics and reshape supplier-producer contractual risk allocation.
Market Dynamics
Morocco's extended producer responsibility framework is compressing supply chains toward certified local converters, while Atlantic coastal processors accelerate flexible format adoption to meet retailer plastic-reduction mandates.
Growth Catalysts
- Retailer plastic-reduction targets:Major Moroccan grocery chains are imposing packaging material intensity caps, pulling demand toward paper-based composites and thinner-gauge laminates that reduce per-unit polymer load.
- UNECE-aligned conformity assessment:IMANOR's certification protocols for food-contact migration limits create protected terrain for domestic converters who can absorb testing costs that disqualify informal importers.
- Processed meat and dairy expansion:Vacuum-shrink barrier technologies are capturing volume as Moroccan protein processors scale shelf-stable retail distribution beyond traditional ambient formats.
Market Restraints
- Resin import duty volatility:Polymer feedstock costs swing with dirham-euro exchange rates and EU tariff schedules, squeezing margin on multi-layer film production.
- REACH compliance friction:Border-testing penalties for uncertified laminate substrates force converters to either pre-qualify European supply chains or absorb 15-20 day customs delays.
- Collection infrastructure gaps:Deposit-return pilots for flexible formats remain unfunded, leaving post-consumer film recovery economics unresolved and EPR obligations unfulfilled.
Strategic Opportunities
- Pharmaceutical-grade barrier pouches:Certified cleanroom conversion capacity is concentrated in Casablanca-Rabat corridor, creating margin pools for sterile primary packaging serving regional drug exporters.
- Kraft paper composite convergence:Integrated pulp-to-paper sourcing bypasses resin exposure entirely, positioning Maghreb-anchored producers for retailer sustainability scorecards.
- Spouted fitment beverage formats:Stand-up pouches with resealable closures are displacing glass and rigid PET in Moroccan juice and dairy segments, opening equipment upgrade cycles for mid-scale converters.
Industry Challenges
- Multi-layer delamination expertise:Retort-compatible adhesive lamination requires polymer chemistry specialization scarce in Moroccan technical training pipelines.
- Cleanroom certification timelines:IMANOR pharmaceutical-grade audits extend 8-14 months, freezing capex deployment until qualification locks.
- Legacy rigid converter retooling:Glass and metal can producers face 3-5 year payback periods on flexible format conversion lines, delaying format switch decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Pouch Packaging Market |
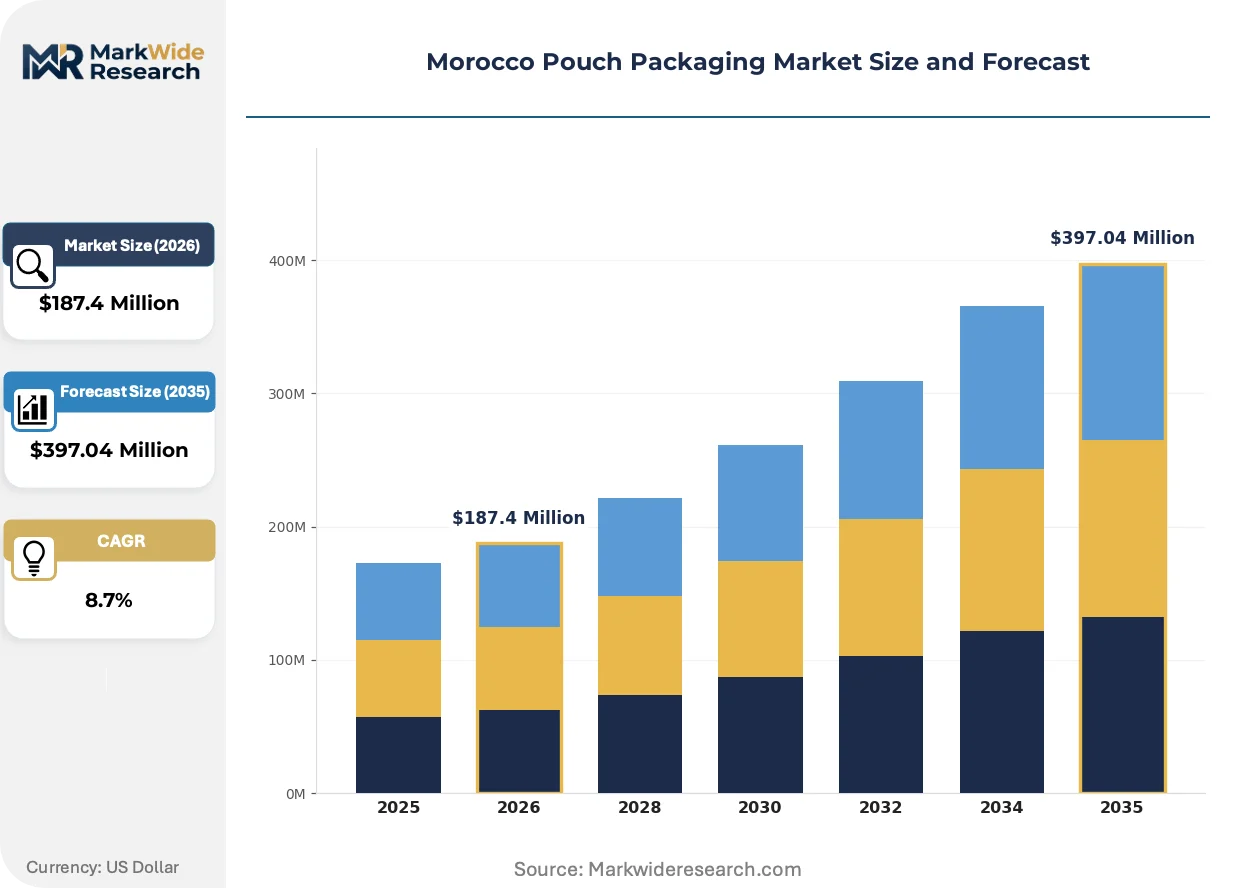
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Zip Lock Pouches Material: Plastic, Paper, Aluminum, Composites Application: Food Packaging, Beverage Packaging, Personal Care, Household Items End User: FMCG, Pharmaceuticals, Chemicals, Others |
| Companies Covered | Amcor Group GmbH, ALPLA Werke Alwin Lehner GmbH & Co KG, Mondi PLC, Hotpack Packaging Industries LLC, Almapack, Tetra Pak, Sealed Air Corporation, Afrimag Glue, Huhtamaki Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Pouch Packaging Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape competitive positioning in Moroccan flexible packaging, with sustainability mandates and barrier performance requirements pulling in parallel directions.
High-barrier paper laminates are expanding into retort applications previously reserved for aluminum-foil composites. Moroccan dairy processors are piloting these substrates for UHT milk pouches, lured by 40% weight reduction and retailer shelf-ready aesthetics. The technology is expanding into ambient beverage segments as oxygen scavenger adhesives mature.
Morocco's Ministry of Industry and Trade is tightening alignment with CODEX food-contact principles ahead of anticipated EU association agreement revisions. IMANOR migration limit certifications now require third-party laboratory verification, elevating testing costs but creating regulatory moats for qualified domestic suppliers. Processed food exporters to European markets face the steepest compliance ramps.
Brand procurement teams are consolidating supplier panels around dual-certified converters who can service both food-contact and pharmaceutical barrier requirements. This concentration is displacing fragmented spot-buying relationships that dominated Moroccan flexible packaging through 2020. The Casablanca-Kenitra manufacturing belt exhibits the most visible supplier consolidation.
Morocco Pouch Packaging Market Segmentation
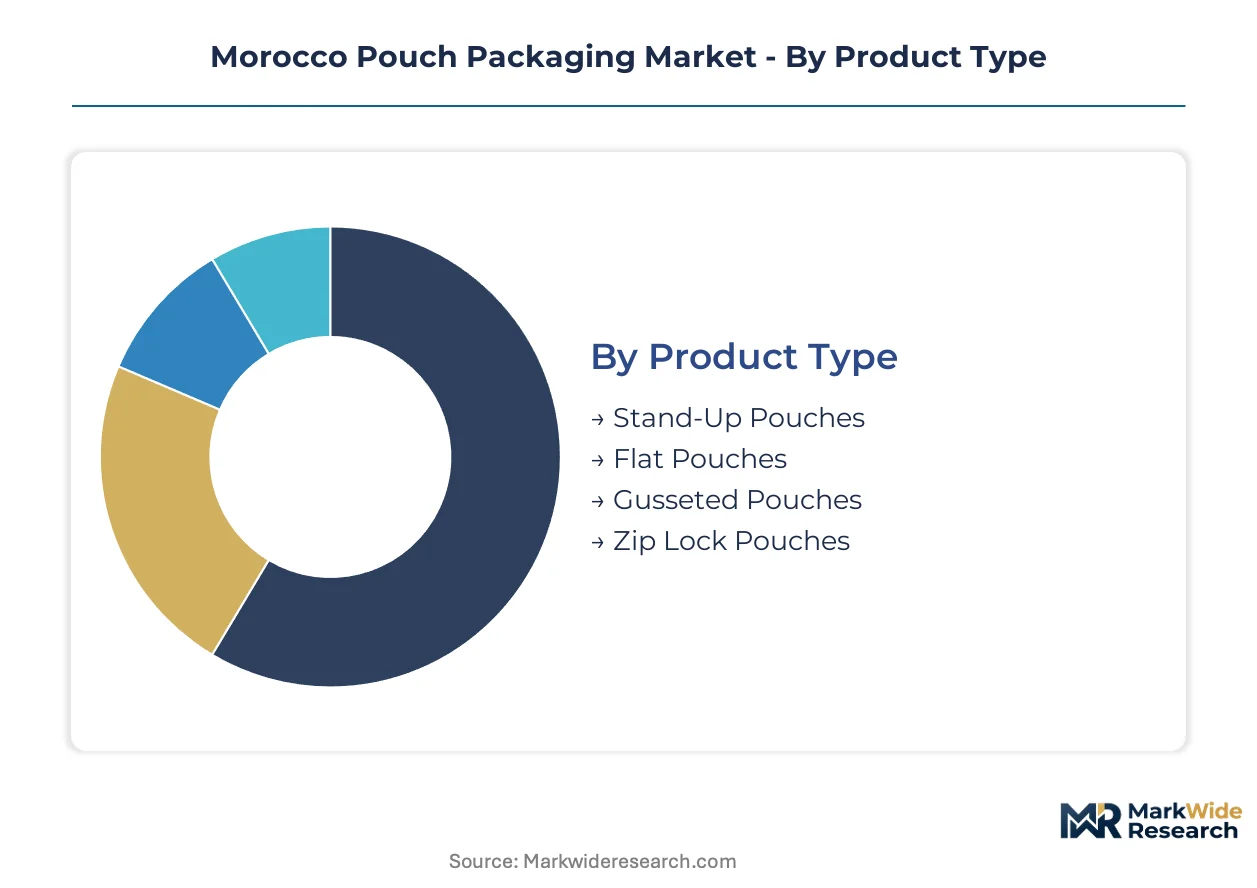
Pouch format selection in Morocco tracks retailer shelf-space economics and EPR compliance costs. Material choices increasingly split between high-barrier laminates for shelf-stable foods and paper-based composites responding to plastic-reduction mandates. End-user procurement is consolidating around dual-certified converters capable of spanning food-contact and pharmaceutical barrier specifications.
Product Type:
Equipment upgrade cycles across the Casablanca-Kenitra corridor are pulling converters toward formats that reduce material intensity while preserving barrier performance.
- Stand-Up Pouches:These self-supporting formats employ bottom gusset construction enabling vertical retail display. Moroccan juice and dairy processors in Mohammedia are displacing rigid glass and PET with spouted variants that cut per-unit shipping weight by 60%. The format commands premium placement in Atlantic coastal supermarket chains.
- Flat Pouches:Two-dimensional sealed envelopes ranging from 50-120 microns total caliper serve ambient dry goods and single-serve condiments. Kenitra-based spice packers favor three-side-seal configurations for their compatibility with legacy vertical form-fill-seal lines, delaying capital expenditure on stand-up pouch equipment.
- Gusseted Pouches:Side-folded expansion panels accommodate bulk dry goods and agricultural inputs. Moroccan olive oil cooperatives utilize these for export-format retail packs balancing volume efficiency with pallet density.
- Zip Lock Pouches:Integral resealable interlocking strips extend product life after initial opening. Casablanca processed meat processors are piloting these for deli-format retail distribution, though zipper fitment costs remain prohibitive for mass-market adoption.
Volume placements concentrate in Stand-Up Pouches; the faster expansion belongs to Zip Lock Pouches as resealability premiums justify fitment economics.
Material:
Raw material exposure diverges sharply between resin-dependent laminates and integrated pulp-to-paper supply chains, with import duty volatility driving sourcing strategy fragmentation.
- Plastic:Multi-layer polyethylene, polypropylene, and polyester laminates dominate retort and high-barrier applications through coextrusion or adhesive lamination. Mohammedia dairy processors rely on these for UHT milk pouches requiring oxygen transmission rates below 0.5 cc/m²/day.
- Paper:Kraft and glassine substrates combined with moisture-barrier coatings are capturing share in dry goods and confectionery. Mondi PLC's integrated Maghreb pulp sourcing bypasses resin import exposure entirely.
- Aluminum:Foil laminates provide near-zero oxygen and moisture transmission for pharmaceutical blister packs and premium coffee. IMANOR migration limit certifications restrict foil sourcing to pre-qualified European suppliers.
- Composites:Paper-plastic-aluminum tri-laminates balance sustainability aesthetics with functional barrier requirements. Casablanca-Rabat converters are developing these for retailer private-label shelf-ready formats.
Plastic retains the dominant volume position; composites are climbing the fastest as sustainability scorecards reshape procurement criteria.
Application:
End-use demand splits between shelf-stable food processing clusters and emerging beverage format conversion, with personal care representing a concentrated margin pool.
- Food Packaging:Retort pouches for canned fish, olives, and prepared couscous dominate Atlantic coastal processor demand. Vacuum-shrink barrier technologies from Sealed Air Corporation are penetrating processed meat segments previously served by rigid thermoformed trays.
- Beverage Packaging:Spouted stand-up pouches for juice, dairy, and functional drinks are displacing brick-carton and PET bottle formats. Equipment upgrade cycles at mid-scale Rabat converters are accelerating this transition.
- Personal Care:High-barrier pouches for creams, shampoos, and sachet-format samples serve Moroccan beauty exporters targeting European markets. Cleanroom conversion requirements limit qualified supplier pools.
- Household Items:Detergent pods, cleaning wipes, and air freshener refills utilize multi-chamber pouch constructions. Price sensitivity in mass-market retail constrains material specification upgrades.
Food Packaging anchors current volume; Beverage Packaging is gaining share fastest as format substitution economics improve.
End User:
Procurement consolidation is favoring converters with dual food-contact and pharmaceutical certifications, squeezing spot-buying relationships that dominated pre-2020 market structure.
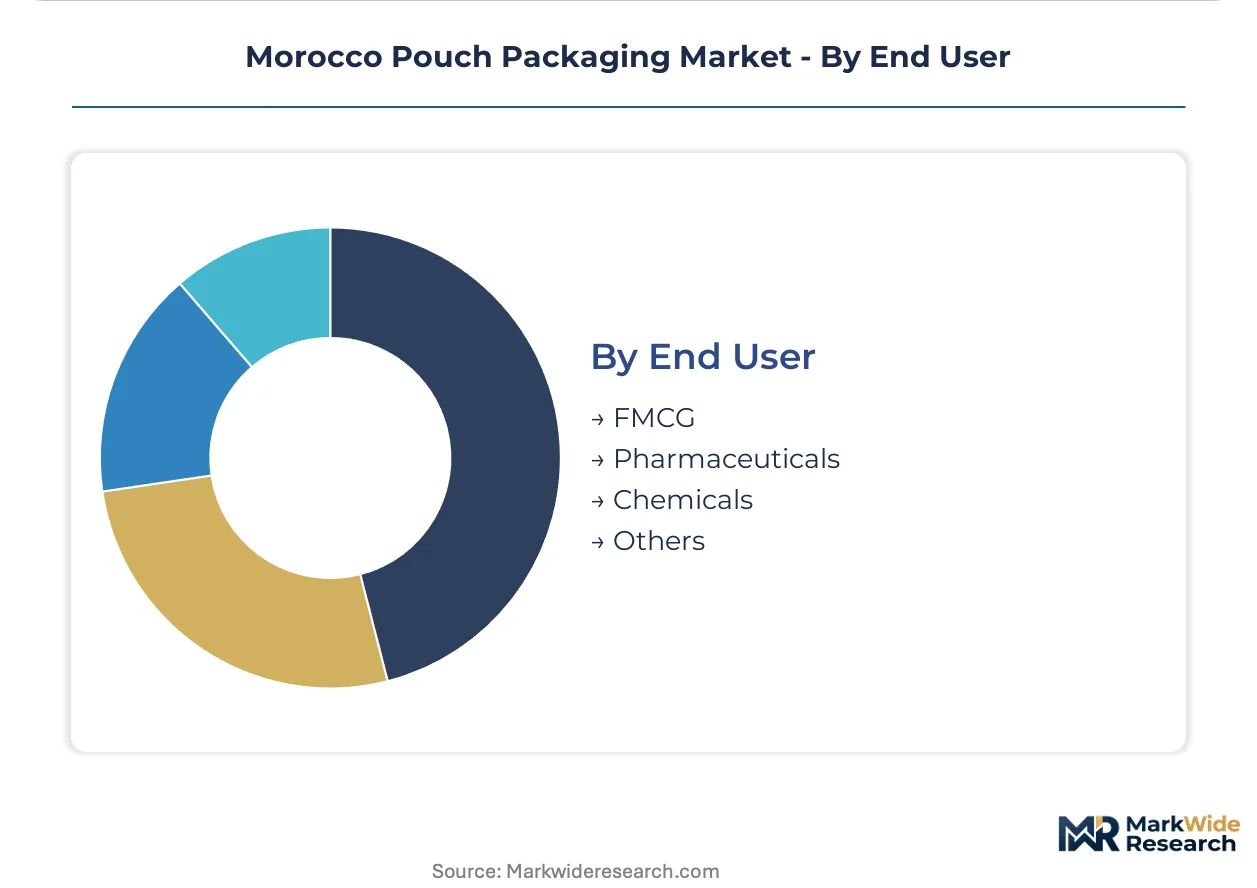
- FMCG:Multinational and domestic packaged food producers command the volume anchor, with annual contract structures replacing fragmented quarterly purchasing. Major Moroccan grocery chains are imposing packaging material intensity caps that cascade through supplier tiers.
- Pharmaceuticals:Sterile barrier pouches for regional drug exporters represent the steepest margin pool. IMANOR pharmaceutical-grade audits extending 8-14 months create regulatory moats for qualified Casablanca-Rabat converters.
- Chemicals:Agricultural inputs, lubricants, and industrial adhesives require chemical-resistant laminates with specialized adhesive systems. Demand concentrates in bulk formats with lower per-unit value capture.
- Others:Pet food, automotive fluids, and specialty electronics packaging represent fragmented spot-market demand with irregular volume patterns.
FMCG retains volume concentration; Pharmaceuticals shows the steepest expansion trajectory as regional drug export volumes climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible packaging demand concentrates along Morocco's Atlantic manufacturing corridor, where processed food and beverage clusters drive format adoption. IMANOR certification requirements and retailer plastic-reduction mandates are restructuring supplier geography toward certified domestic converters.
Casablanca-Rabat Corridor
Processed meat and dairy processors anchor pouch demand in this coastal belt. IMANOR's food-contact migration protocols elevate testing costs that informal importers cannot absorb. Mohammedia-based converters are scaling spouted stand-up pouch capacity for juice and UHT milk formats.
Kenitra-Tangier Axis
Spice packers and olive oil cooperatives favor flat pouch configurations compatible with legacy vertical form-fill-seal equipment. The Ministry of Industry's UNECE-aligned conformity assessments restrict foil laminate sourcing to pre-qualified European suppliers. Kenitra converters are piloting paper-plastic composites for retailer private-label formats.
Marrakech-Safi Hinterland
Agricultural input distributors utilize gusseted pouches for bulk fertilizer and seed packaging. Morocco's extended producer responsibility framework lacks funded collection infrastructure for flexible formats. Safi-based chemical-resistant laminate specialists serve fragmented spot-market demand with irregular volume patterns.
Fez-Meknes Industrial Zone
Confectionery and dry goods packers are adopting kraft paper composites to meet grocery chain sustainability scorecards. The national packaging waste decree anticipates deposit-return pilots that could restructure collection economics. Fez converters face 8-14 month IMANOR pharmaceutical-grade audit timelines that freeze capex deployment.
Agadir Souss-Massa
Canned fish and prepared couscous exporters drive retort pouch specifications for European market access. CODEX-aligned migration limit certifications create regulatory moats for qualified suppliers. Agadir-based processors are consolidating supplier panels around dual-certified converters capable of spanning food-contact and pharmaceutical barriers.
Morocco Pouch Packaging Market Competitive Landscape
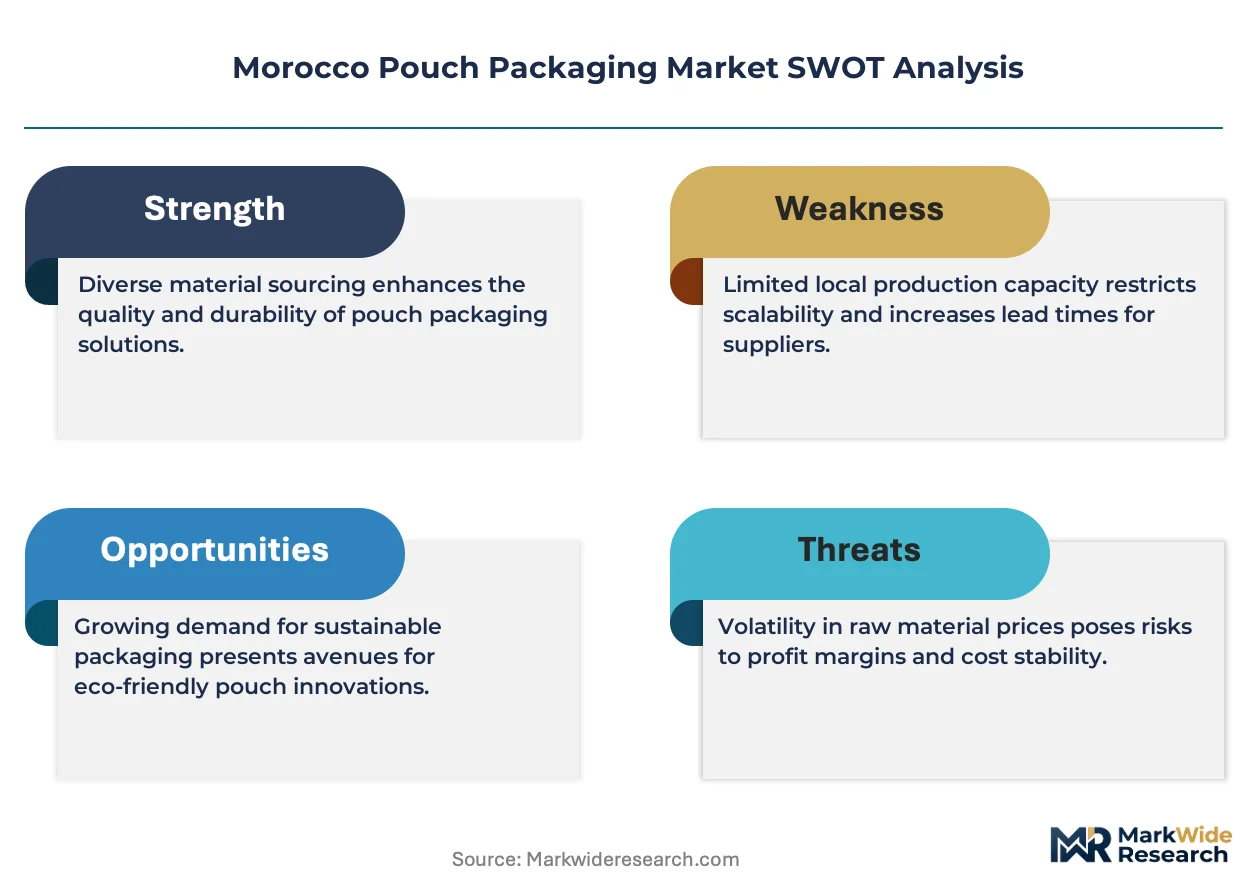
European producers anchor one tier; Maghreb-anchored specialists hold differentiated positions through integrated material sourcing. The vendor base exhibits moderate concentration, with multinational laminate suppliers competing against domestic converters certified for IMANOR food-contact protocols. Three archetypes dominate: integrated pulp-to-paper operators, multi-layer film specialists with European regulatory infrastructure, and certified cleanroom converters serving pharmaceutical barrier requirements. Competitive moves center on strategic partnerships for resin supply security and capacity expansion in spouted fitment beverage formats.
Among European-anchored multinationals, Amcor Group GmbH, Mondi PLC, and Sealed Air Corporation exemplify distinct strategic positioning. Amcor leverages pre-qualified European supply chains to navigate REACH compliance friction at Moroccan borders. Mondi represents the integrated pulp-to-paper archetype, bypassing resin import exposure through captive Maghreb fiber sourcing. Sealed Air occupies the high-performance barrier tier, with vacuum-shrink technologies aligned to processed protein expansion in Atlantic coastal manufacturing clusters.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Mondi PLC |
| Hotpack Packaging Industries LLC |
| Almapack |
| Tetra Pak |
| Sealed Air Corporation |
| Afrimag Glue |
| Huhtamaki Oyj |
| Others |
Pricing and Supply Chain Analysis
FMCG procurement consolidation along the Casablanca-Rabat corridor anchors Morocco's pouch packaging pricing model, with annual contract structures displacing fragmented spot-buying and compressing margin capture for uncertified converters.
Pricing Analysis
Short lead-time premiums for IMANOR-certified laminates command pricing separation from spot-market imports facing 15-20 day customs delays. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and uncertified economy levels reflects testing cost absorption and migration limit compliance. Pricing pressure stems from dirham-euro exchange volatility squeezing resin-dependent converters. Bulk spice packers in Kenitra exhibit highest price sensitivity; sterile barrier pharmaceutical buyers show least.
Supply Chain Analysis
Post-consumer film recovery flows remain unfunded under Morocco's extended producer responsibility framework, leaving collection infrastructure gaps unresolved and EPR obligations unfulfilled. Raw material sourcing draws from European laminate suppliers for aluminum foil and high-barrier films, Maghreb pulp operations for kraft paper, and resin imports for multi-layer plastics. Single-source vulnerability concentrates in REACH-compliant adhesive suppliers. Distribution runs through Atlantic coastal manufacturing clusters anchored by Mohammedia dairy processors and Casablanca meat packers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's pouch packaging market represents a consolidation play as IMANOR certification timelines and retailer plastic-reduction mandates force informal importers and uncertified converters toward exit.
For Market Incumbents: Anticipate margin compression from paper-based composite substitution by securing integrated pulp-to-paper supply chains or captive kraft sourcing. Defend position by accelerating spouted fitment capacity expansion in Mohammedia to capture beverage format displacement from rigid PET. Certification moats around pharmaceutical-grade cleanroom conversion protect against European multi-layer specialists. For New Entrants and Emerging Players: Enter via pharmaceutical-grade barrier pouch production in the Casablanca-Rabat corridor, where 8-14 month IMANOR audit timelines create protected terrain. Target personal care exporters serving European markets with high-barrier sachet formats. Partner with established European laminate suppliers to bypass REACH compliance friction at Moroccan borders. For Investors and Strategic Acquirers: The window for entry favors dual-certified converters with existing food-contact and pharmaceutical barrier qualifications. Long-term viability hinges on EPR framework evolution and deposit-return pilot funding. Monitor Morocco's packaging waste decree revisions for collection economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IMANOR Certification Investment | Creates regulatory moats against informal importers facing border-testing penalties. |
| Kraft Paper Composite Development | Bypasses resin import duty volatility through Mondi-style integrated pulp sourcing. |
| Spouted Fitment Capacity Expansion | Captures juice and dairy format substitution away from rigid glass and PET. |
| Pharmaceutical Cleanroom Qualification | Accesses sterile barrier margin pools serving regional drug exporters. |
| Retort-Compatible Adhesive Partnership | Secures polymer chemistry expertise scarce in Moroccan technical training pipelines. |
Research Methodology
Independent corroboration across converter operations managers, FMCG procurement directors, and IMANOR certification auditors underwrites the qualitative findings in this study. Primary interviews with equipment suppliers, resin distributors, and retailer sustainability officers combined with secondary validation from customs records, UNECE packaging standard filings, and trade flow databases. Bottom-up capacity assessments triangulate against top-down demand estimates from processed food and beverage production clusters.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by pouch format, material substrate, and end-use certification tier. Modeled dimensions include stand-up versus flat pouch configurations, plastic-laminate versus paper-composite material splits, and food-contact versus pharmaceutical barrier applications. CAGRs derive from equipment installation timelines, retailer plastic-reduction mandate compliance deadlines, and EPR framework evolution scenarios.
Revisions become necessary when Morocco's packaging waste decree introduces funded deposit-return infrastructure, EU association agreement revisions alter REACH alignment requirements, or dirham-euro exchange rate volatility shifts resin import economics. Practitioners should monitor IMANOR audit queue lengths, retailer sustainability scorecard implementation, and European laminate supplier pre-qualification expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Slider Zipper Pouch Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Retort Pouch Packaging Market
Pouch
Kraft Paper Pouch Market
Pouch
Stand-Up Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Foil Pouch Packaging Market
Pouch
Pillow Pouch Packaging Market
Pouch
Benelux Pouch Packaging Market
Pouch
2 Seal Pouches Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Compostable Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
France Pouch Packaging Market
Pouch
Inflatable Pouches Market