
 Thermal Film Laminating Machines Market | 2026-2036
Thermal Film Laminating Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Film Laminating Machines Market Analytics
ISO 9001 quality management certification is redrawing competitive boundaries in thermal film laminating equipment manufacturing. GBC leverages its North American service infrastructure to sustain aftermarket revenue streams. Fellowes Brands anchors its position through office-channel distribution density. Komfi differentiates via European-built precision engineering for narrow-web applications.
Thermal film laminating machines apply heat-activated adhesive films to substrates using controlled temperature zones, typically operating between 100°C and 160°C depending on film thickness and substrate sensitivity. These systems serve primarily to protect printed surfaces from moisture, abrasion, and UV degradation while enhancing visual finish. Roll-to-roll configurations command the largest installed base due to continuous throughput advantages in high-volume packaging environments. Hot melt technology leads technology adoption for its energy efficiency and elimination of solvent emissions. Double-sided equipment represents the fastest-growing product configuration as premium packaging demands dual-surface protection.
CE marking requirements under the EU Machinery Directive shape European market access protocols for thermal laminating equipment. The EPA's National Emission Standards for Hazardous Air Pollutants influence solvent-based system viability in US manufacturing facilities. China's SAMR enforces GB standards that govern electrical safety and electromagnetic compatibility for imported equipment. Stakeholders must monitor evolving regional energy-efficiency mandates that threaten to obsolete legacy heating architectures.
Market Dynamics
ISO 9001 quality management certification is redrawing competitive boundaries in thermal film laminating equipment manufacturing, forcing mid-tier producers to invest in documented process controls or exit premium contract bidding. Heating architecture upgrades and electromagnetic compliance testing now consume disproportionate engineering resources relative to mechanical design.
Growth Catalysts
- Food and beverage localization:India's packaging conversion sector is absorbing equipment as multinational brands relocate supply chains from Southeast Asian hubs to domestic facilities.
- CE marking alignment:European-built precision engineering for narrow-web applications is capturing share among specialty label converters seeking documented Machinery Directive compliance.
- Hot melt technology:Energy-efficient adhesive systems are displacing solvent-based alternatives in US manufacturing facilities facing EPA National Emission Standards enforcement.
Market Restraints
- Copper and silicon component costs:Heating element and control circuitry inputs face price volatility from concentrated East Asian semiconductor foundry capacity.
- GB standards friction:China's SAMR electromagnetic compatibility testing requirements extend equipment import timelines by four to six months for non-domestic manufacturers.
- Digital finishing substitution:UV-cured inkjet protective coatings are capturing short-run packaging work previously routed to film lamination.
Strategic Opportunities
- Secondary cities penetration:India's tier-2 packaging clusters in Ahmedabad and Coimbatore remain undersupplied with service-capable equipment distributors.
- Dual carbon goals alignment:China's MEE energy-efficiency mandates are creating replacement demand for legacy heating architectures in Shandong and Jiangsu provinces.
- Retrofit control systems:IoT-enabled temperature zone monitoring is opening aftermarket revenue streams among installed base operators seeking predictive maintenance capabilities.
Industry Challenges
- Electromechanical technician scarcity:Servo-controlled nip adjustment and PLC programming skills command wage premiums that compress field service margins.
- Legacy system integration:Roll-to-roll configurations from the 1990s lack communication protocols compatible with modern MES and ERP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Film Laminating Machines Market |
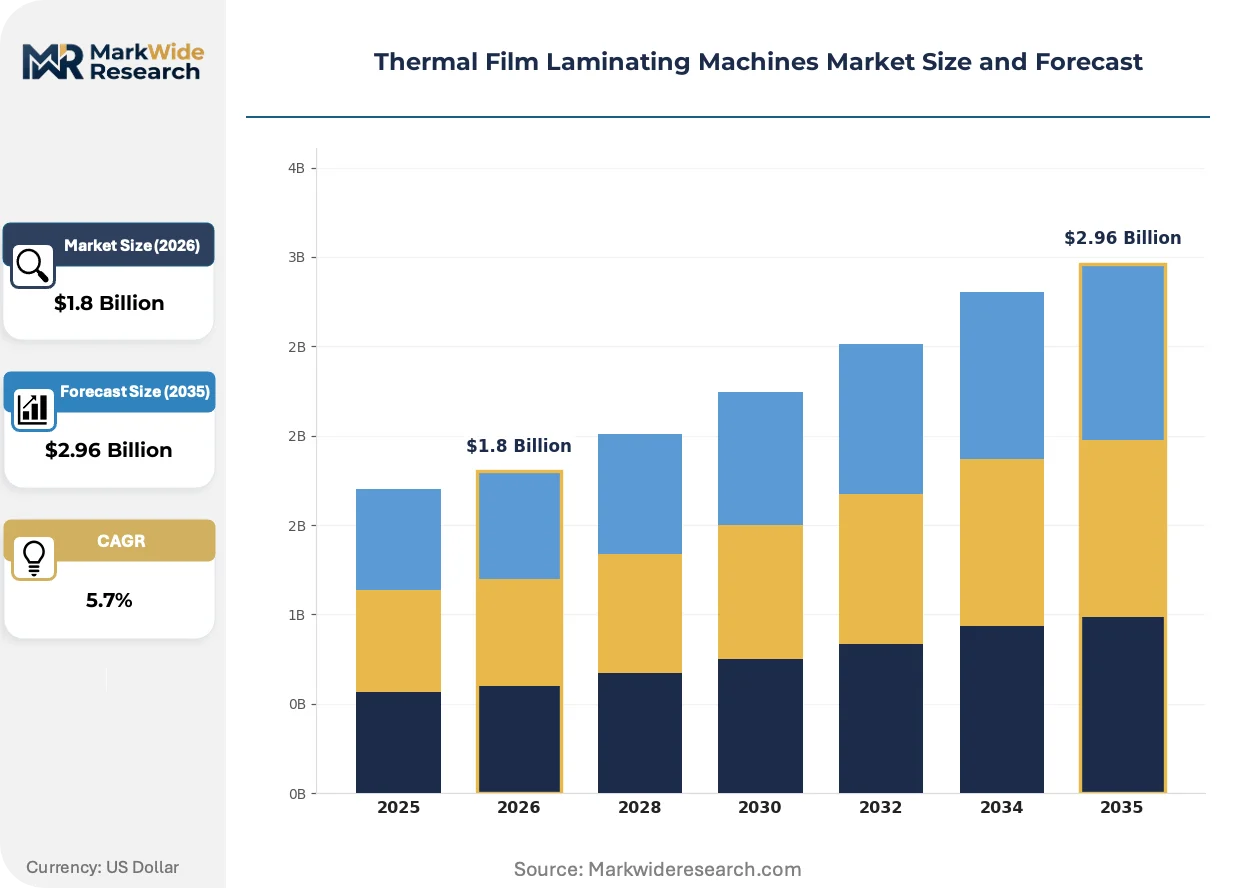
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Roll-To-Roll, Sheet Feed End User: Commercial Printing, Packaging Industry, Photo Processing, Office Supplies Technology: Hot Melt, Cold Laminating, Dry Laminating, Solvent-Based Application: Business Cards, Labels, Book Covers, Menu Boards |
| Companies Covered | GBC, Fellowes Brands, D&K Group, Royal Sovereign, Black Bros. Co., Komfi, Vivid Laminating Technologies, Fujipla, Hangzhou Taifu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Film Laminating Machines Market Evolving Landscape
Active heating zone segmentation and adhesive chemistry advances are fragmenting the historically uniform equipment specification landscape. Buyers now demand application-specific configurations rather than general-purpose platforms.
Infrared pre-heating modules with zoned temperature control are fragmenting the traditional single-roller thermal architecture. High-end cosmetic and pharmaceutical packaging converters in Germany and Switzerland are specifying these systems for heat-sensitive substrates. The technology is compressing standard equipment margins while creating premium tier pricing power for engineered-to-order configurations.
REACH restrictions on perfluorinated compounds are forcing adhesive reformulation across European supply chains. Film manufacturers must recertify bond strength and thermal stability profiles under revised chemical safety dossiers. Narrow-web label producers in Northern Italy and Catalonia are absorbing extended qualification timelines as they validate alternative hot melt chemistries.
Service contract unbundling is altering buyer-supplier relationships in North American installed base markets. Large commercial printers in Chicago and Toronto are separating maintenance agreements from parts supply, sourcing consumables through independent distributors. Equipment OEMs are responding with certified pre-owned programs and remote diagnostics subscriptions to recover recurring revenue erosion.
Thermal Film Laminating Machines Market Segmentation
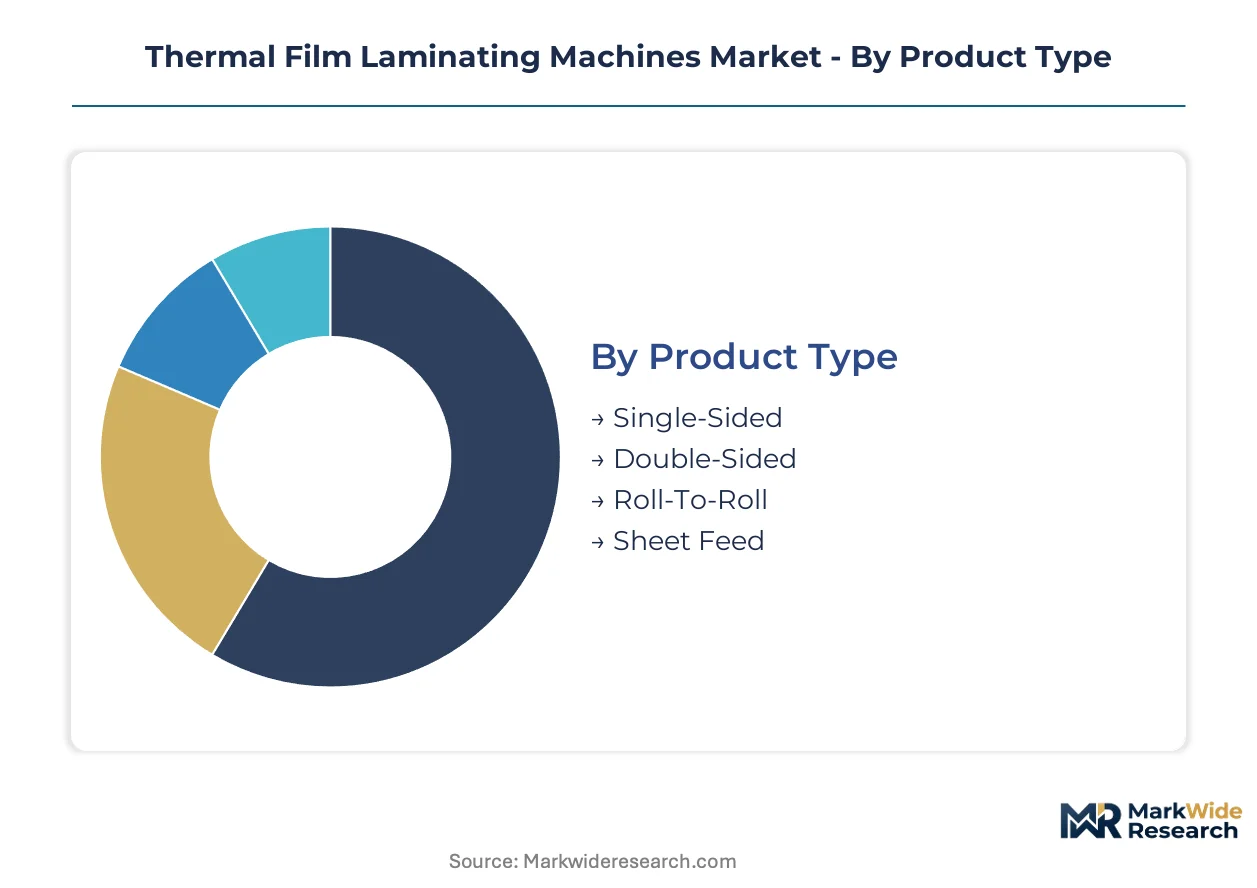
Thermal film laminating equipment specification varies sharply by throughput architecture and adhesive chemistry, with each configuration imposing distinct thermal control requirements and regulatory compliance burdens. Buyers segment procurement decisions around substrate sensitivity, volume economics, and regional emission standards rather than generalized performance claims.
Product Type:
Domestic packaging converters in India and China favor roll-to-roll and double-sided configurations for continuous throughput, while North American and European commercial printers disproportionately specify single-sided and sheet-feed units for short-run flexibility.
- Roll-To-Roll:Continuous web processing through heated nip stations enables throughput rates exceeding 100 meters per minute for flexible packaging converters. Demand concentrates in China's Shandong province where food packaging contract volumes are absorbing fleet expansions from domestic equipment manufacturers.
- Double-Sided:Simultaneous top-and-bottom film application requires precision-aligned heating zones and servo-controlled nip pressure for substrate stability. Premium cosmetic and pharmaceutical packaging producers in Switzerland and Germany are specifying these systems for dual-surface protection of sensitive printed materials.
- Single-Sided:Entry-level configuration for commercial print shops processing business documents and promotional materials with moderate durability requirements.
- Sheet Feed:Discrete substrate handling for variable-format applications in photo processing and specialty label production.
Roll-To-Roll commands the established base. The steepest expansion runs through Double-Sided.
End User:
Cost tier separation is pronounced: packaging industry buyers prioritize energy efficiency and emission compliance, while commercial printers and office supply channels optimize for capital expenditure minimization.
- Packaging Industry:High-volume converters operating 24-hour production schedules specify hot melt thermal systems with zoned temperature control for food-grade film compatibility. India's Ahmedabad and Coimbatore clusters are absorbing equipment as multinational brands localize supply chains from Southeast Asian hubs.
- Commercial Printing:Mid-volume operations serving marketing collateral and publication finishing balance throughput against job changeover flexibility. Chicago and Toronto print service providers are unbundling maintenance contracts from parts supply, pressuring OEM recurring revenue models.
- Photo Processing:Declining segment concentrated in legacy retail minilab operations and specialty fine-art reproduction studios.
- Office Supplies:Low-duty-cycle equipment for document protection in corporate and educational settings, distributed through channel partners.
Packaging Industry absorbs the premium tier. Commercial Printing faces the sharpest margin compression.
Technology:
Application requirements and regulatory pressure are fragmenting adoption: hot melt systems dominate emission-sensitive geographies while solvent-based retains niche share in cost-driven markets.
- Hot Melt:Thermoplastic adhesive activation eliminates solvent emissions and reduces energy consumption versus thermal drying systems. US manufacturing facilities facing EPA National Emission Standards for Hazardous Air Pollutants enforcement are displacing legacy solvent-based equipment with these configurations.
- Solvent-Based:Traditional adhesive systems requiring volatile organic compound recovery infrastructure face regulatory obsolescence in European and North American markets.
- Cold Laminating:Pressure-sensitive adhesive films for heat-sensitive substrates including inkjet prints and thermal paper receipts.
- Dry Laminating:Pre-coated films activated by heat and pressure without wet adhesive application, common in narrow-web label converting.
Hot Melt claims the technology transition. Cold Laminating holds defensive share in substrate-sensitive applications.
Application:
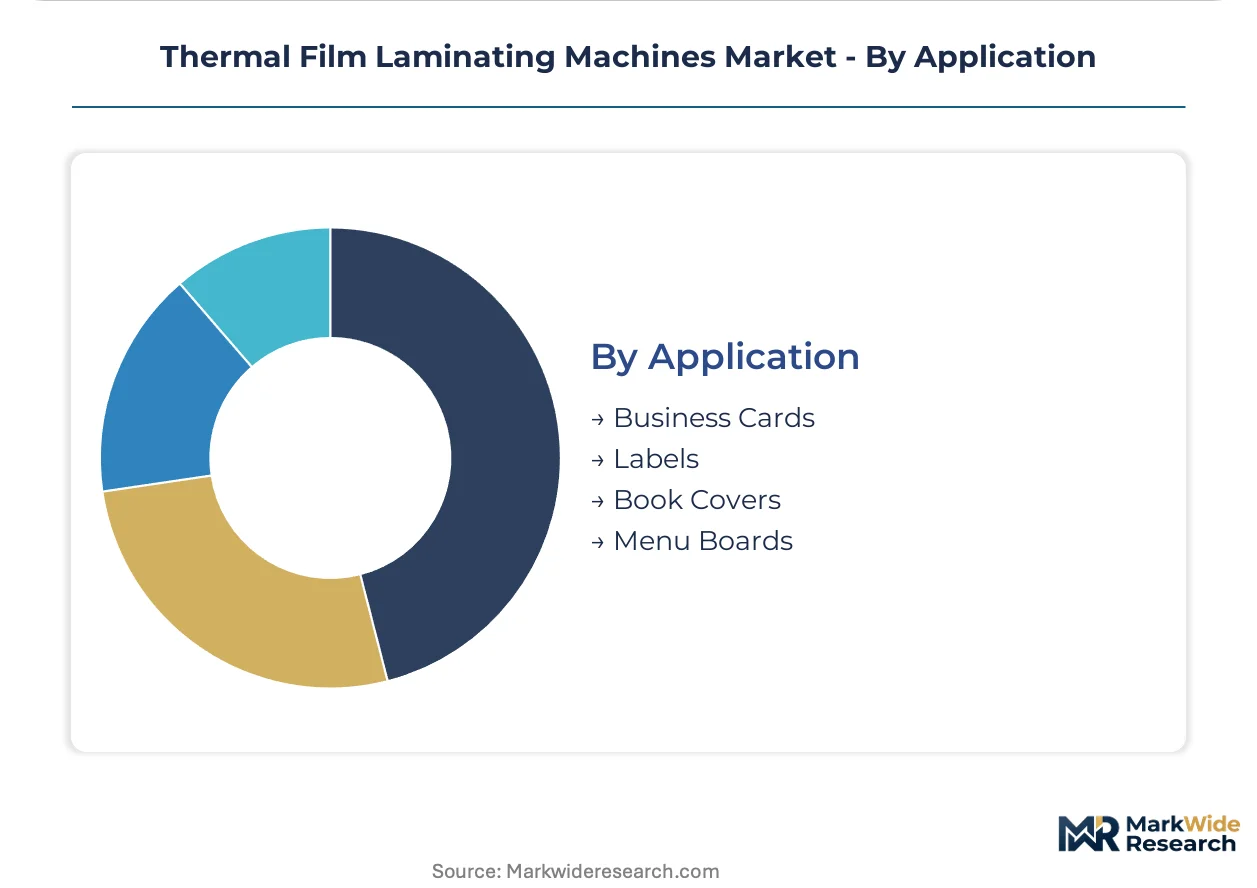
Volume scale separates segments: labels and book covers run through continuous production, while business cards and menu boards demand format flexibility.
- Labels:Narrow-web roll-to-roll processing for adhesive label stock dominates pharmaceutical and logistics applications. Northern Italian and Catalan converters are absorbing extended qualification timelines as REACH restrictions on perfluorinated compounds force adhesive reformulation.
- Book Covers:Hardcover and softcover binding protection for educational and trade publishing, requiring precise film tension control to prevent substrate curl.
- Business Cards:Short-run premium finishing for corporate identity materials, sensitive to registration accuracy.
- Menu Boards:Durable surface protection for hospitality sector point-of-purchase displays, emphasizing moisture and abrasion resistance.
Labels anchor production volume. Book Covers retain stable replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and tightening GB standards are redirecting equipment procurement toward energy-efficient architectures. India's packaging localization policies are absorbing fleet expansions from multinational brand relocations. European REACH restrictions are forcing adhesive chemistry recertification across Northern Italy and Catalonia.
China
Shandong and Jiangsu provinces are replacing legacy heating systems as MEE energy-efficiency mandates accelerate equipment obsolescence. SAMR electromagnetic compatibility testing extends import timelines for non-domestic manufacturers. Domestic packaging converters in the Yangtze River Delta are absorbing fleet expansions to serve rising food contract volumes.
India
Ahmedabad and Coimbatore packaging clusters are absorbing equipment as multinational food and beverage brands relocate supply chains from Southeast Asian hubs. BIS certification requirements are tightening quality benchmarks for imported machinery. Tier-2 cities remain undersupplied with service-capable distributors, creating penetration opportunities.
Germany
CE marking alignment under the EU Machinery Directive is capturing share among specialty label converters seeking documented compliance. High-end cosmetic and pharmaceutical packaging producers are specifying infrared pre-heating modules with zoned temperature control. ECHA REACH restrictions on perfluorinated compounds are forcing extended adhesive qualification timelines.
United States
EPA National Emission Standards for Hazardous Air Pollutants enforcement is displacing solvent-based systems with hot melt configurations. Chicago and Toronto commercial printers are unbundling maintenance contracts from parts supply, pressuring OEM recurring revenue models. Midwest packaging facilities face copper and silicon component cost volatility from concentrated East Asian semiconductor foundry capacity.
Switzerland
Precision-engineered narrow-web applications are commanding premium pricing for dual-surface protection systems. Swissmedic-aligned pharmaceutical packaging standards are driving specification rigor for heat-sensitive substrate handling. Basel and Zurich converters are absorbing REACH-mandated adhesive reformulation costs while validating alternative hot melt chemistries.
Thermal Film Laminating Machines Market Competitive Landscape
Player mix skews toward diversified office equipment conglomerates and specialized narrow-web engineering houses. The competitive terrain splits between aftermarket service infrastructure builders and precision manufacturing specialists. Two dominant strategic archetypes have emerged: North American channel-dense distributors leveraging service contract unbundling, and European precision engineers capturing premium tier pricing through Machinery Directive compliance documentation. Competitive moves concentrate on certified pre-owned program launches and IoT-enabled retrofit control system development.
Within the diversified equipment tier, GBC leverages its North American service infrastructure to sustain aftermarket revenue streams against contract unbundling pressures. Fellowes Brands anchors its position through office-channel distribution density, representing the capital-expenditure-minimization archetype for low-duty-cycle applications. Komfi occupies a position exemplifying European-built precision engineering for narrow-web applications, capturing share among specialty label converters seeking documented CE marking alignment.
| Leading Market Players |
|---|
| GBC |
| Fellowes Brands |
| D&K Group |
| Royal Sovereign |
| Black Bros. Co. |
| Komfi |
| Vivid Laminating Technologies |
| Fujipla |
| Hangzhou Taifu |
| Others |
Value Network & Pricing Analysis
CE marking alignment under the EU Machinery Directive gates both supply qualification and price differentiation simultaneously, forcing non-compliant manufacturers into discount positioning while certified European engineers capture premium tier pricing power through documented compliance documentation.
Pricing Analysis
Copper and silicon component cost-plus contracts with London Metal Exchange indexation dominate equipment procurement between OEMs and packaging converters. Pricing stratifies across premium, standard, and economy tiers based on ISO 9001 certification status and after-sales service bundling. Cost compression in the standard tier is intensifying because Chinese domestic manufacturers are absorbing GB standards compliance costs to displace European imports. Commercial printers in North America exhibit the highest price sensitivity, while pharmaceutical packaging converters in Switzerland demonstrate the lowest.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and container availability constraints on Asia-Europe trade lanes are compressing margins for equipment importers. Heating element manufacturing concentrates in China, Germany, and Japan. Control circuitry draws from Taiwanese and South Korean semiconductor foundries. Single-source vulnerability in precision servo motor supply creates procurement risk. Distribution runs through authorized dealer networks with regional service capability certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot melt technology displacement of solvent-based systems constitutes a high-growth disruption, with EPA National Emission Standards enforcement accelerating equipment replacement cycles across US manufacturing facilities.
For Market Incumbents: Secure aftermarket revenue streams by launching IoT-enabled retrofit control systems for 1990s-era roll-to-roll installed bases facing legacy system integration failures. Defend against contract unbundling pressures from Chicago and Toronto commercial printers through certified pre-owned programs that recapture parts supply margins. For New Entrants and Emerging Players: Tier-2 packaging cluster service gaps in Ahmedabad and Coimbatore represent the most penetrable geography, as multinational brand supply chain localization outpaces distributor capability deployment. Target these clusters with hot melt technology demonstration units and localized spare parts inventory to establish foothold before incumbent response. For Investors and Strategic Acquirers: China's MEE energy-efficiency mandate reshapes the acquisition landscape toward heating architecture specialists with documented dual carbon goals alignment. Long-term viability centers on equipment OEMs with captive control system engineering capabilities. Monitor Shandong and Jiangsu province replacement demand signals as inflection indicators for legacy system obsolescence velocity.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Retrofit Control Launch | Predictive maintenance subscriptions recover revenue erosion from contract unbundling among Chicago commercial printers. |
| Backward Integration into Heating Elements | Captive copper and silicon component supply mitigates East Asian semiconductor foundry price volatility exposure. |
| CE Marking Fast-Track Certification | Documented Machinery Directive compliance captures share among Northern Italian label converters facing REACH adhesive reformulation. |
| Secondary Cities Service Network Expansion | Ahmedabad and Coimbatore distributor capability addresses undersupply from multinational brand supply chain localization. |
| Certified Pre-Owned Program Launch | Refurbished roll-to-roll systems penetrate capital-expenditure-minimized commercial printing segments in Toronto. |
Research Methodology
Operator-level perspectives from packaging plant engineers, aftermarket service technicians, OEM procurement managers, and commercial print shop owners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC equipment manufacturer filings, and BIS certification registries. Bottom-up equipment shipment analysis and top-down packaging industry capex triangulation established volume estimates.
Sensitivity analysis across heating technology adoption scenarios, copper price volatility bands, and regional regulatory enforcement intensity informed projection robustness. Segmentation dimensions modeled include product architecture, adhesive chemistry, end-use industry, and regional certification cluster. CAGRs derived from equipment replacement cycle analysis and packaging contract volume elasticity to macroeconomic indicators.
Underlying assumptions cover EPA enforcement continuity, REACH perfluorinated compound restriction timelines, and China dual carbon goals implementation pace, with deviation risk concentrated in semiconductor supply chain disruption and alternative UV-cured protective coating substitution velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Global Tissue Paper Converting Machines Market