
 Global Boil-In Bags Market | 2026-2036
Global Boil-In Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boil-In Bags Market Analysis
The EU Green Deal's packaging sustainability targets is realigning material sourcing priorities across European supply chains. ProAmpac leverages its multi-layer film expertise to serve food manufacturers seeking compliant barrier structures. Sealed Air Corporation anchors its position through advanced vacuum and modified-atmosphere packaging systems for boil-in applications. Amcor plc competes with vertically integrated resin-to-film capabilities that reduce lead times for high-volume restaurant chains.
Boil-in bags are heat-resistant flexible pouches engineered from multi-layer polymer laminates—typically polyethylene, nylon, or polyester composites—designed to withstand sustained temperatures above 100°C without structural failure or leaching. These bags enable precise temperature-controlled cooking, pasteurization, and shelf-stable meal preparation across commercial and consumer food systems. Standard bags occupy the largest volume share due to entrenched penetration in institutional catering and frozen meal manufacturing, while single-serve formats are gaining fastest in meal-kit subscription channels where portion control and cooking convenience drive repeat purchase. Composite films command premium positioning because their oxygen and moisture barrier properties extend protein shelf life, though polyethylene dominates unit economics in price-sensitive wholesale segments.
FDA food-contact substance notifications govern resin approvals and migration limits in the United States, while REACH and the EU Packaging and Packaging Waste Regulation shape material recyclability mandates across European markets. Japan's Food Sanitation Act and METI guidelines on plastic resource circulation impose additional compliance layers for exporters targeting East Asian commercial buyers. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based film certification standards to secure future market access.
Market Dynamics
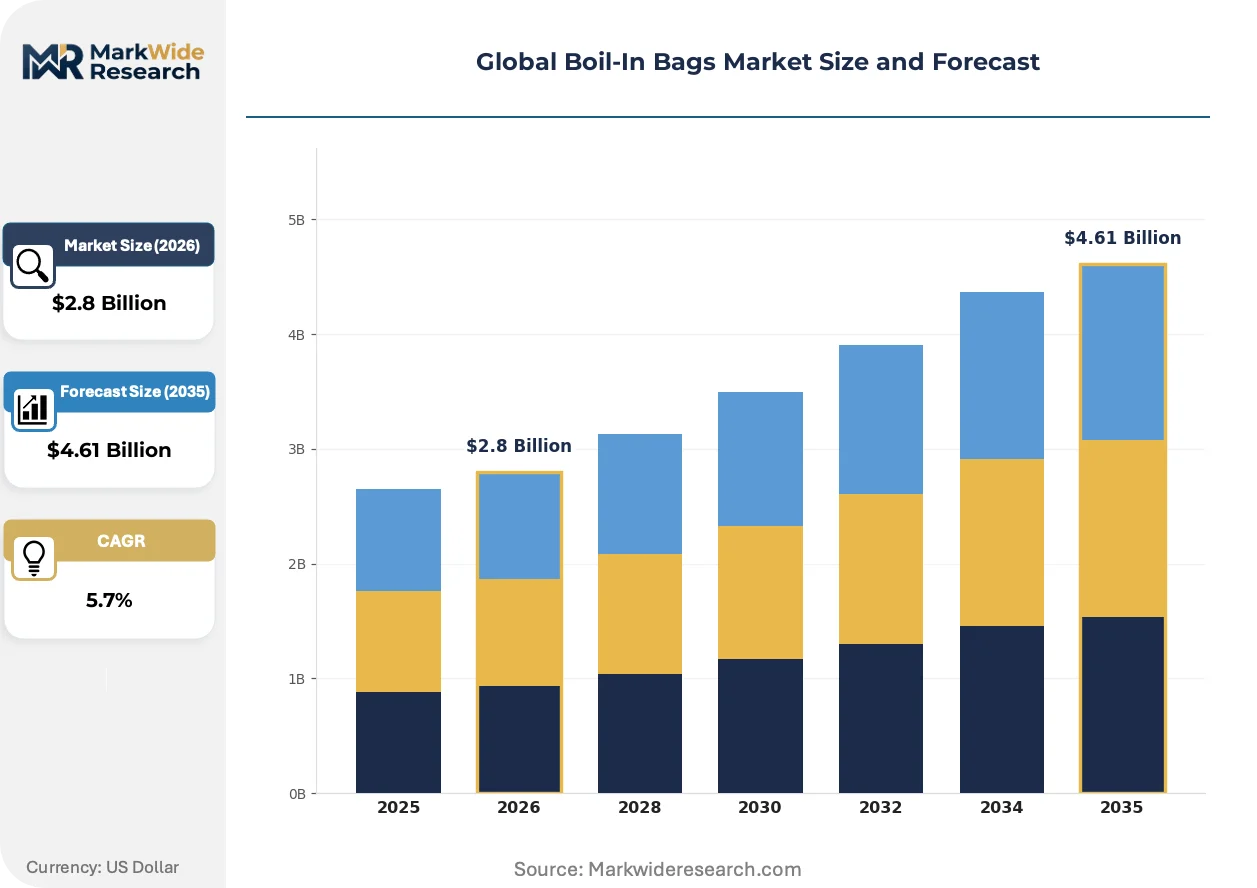
Precision cooking adoption in commercial kitchens is compressing cooking cycle times and demanding polymer laminates that withstand sustained thermal stress without barrier degradation. This operational shift is forcing material suppliers to validate oxygen transmission rates under hydrostatic pressure conditions previously outside standard test protocols.
Growth Catalysts
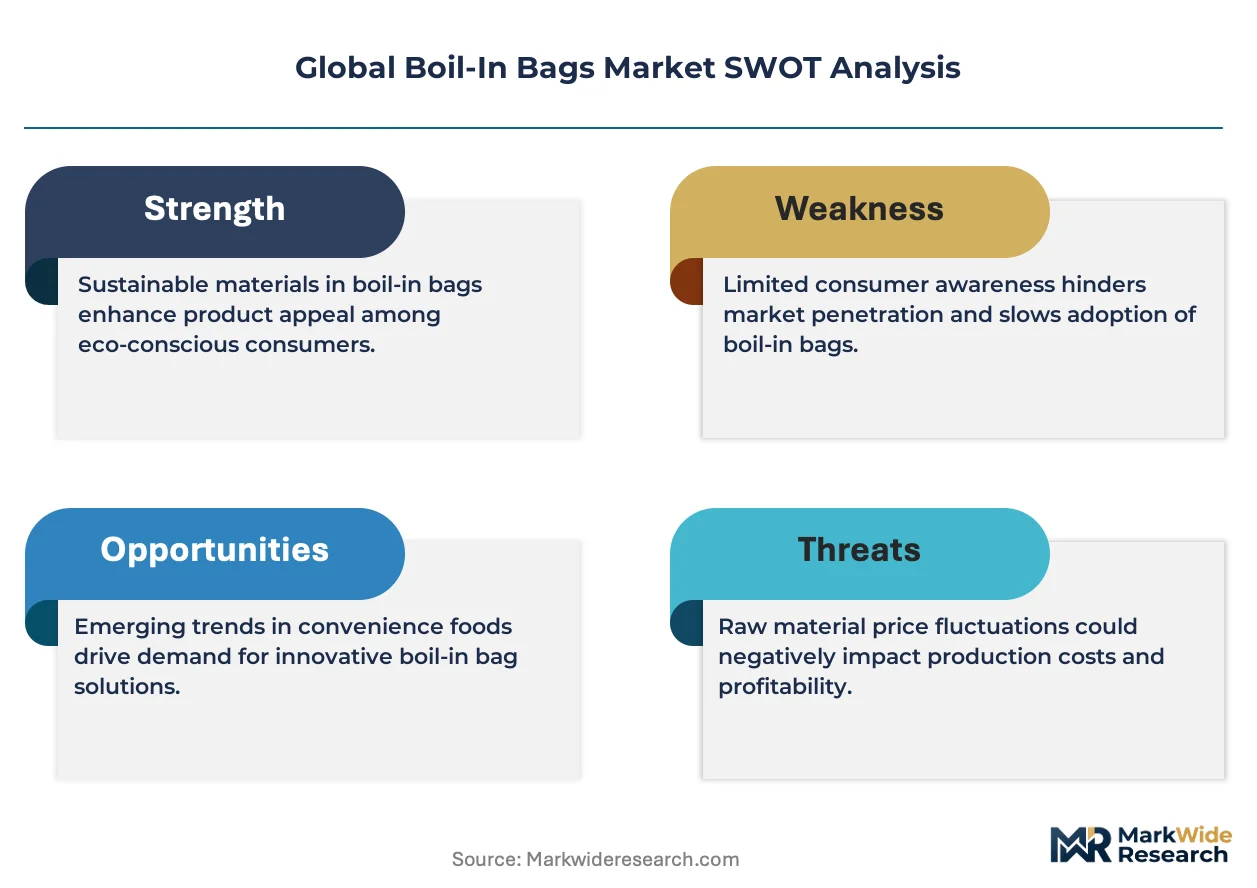
- Sous-vide expansion:Restaurant chains in Germany and the United States are standardizing vacuum-sealed protein preparation, pulling demand for nylon-polyethylene composite structures rated for 85°C+ water bath immersion.
- EU Green Deal packaging mandates:Recyclability targets under the EU Packaging and Packaging Waste Regulation are accelerating mono-material polyethylene developments that maintain barrier performance without adhesive lamination layers.
- Meal-kit subscription velocity:Portion-controlled single-serve formats are displacing bulk frozen bags in direct-to-consumer channels where cooking convenience drives retention metrics.
Market Restraints
- Nylon resin concentration:Caprolactam supply tightness in Northeast Asian petrochemical corridors creates input cost volatility for multi-layer barrier films.
- Migration testing burden:FDA food-contact substance notification timelines extend 180-270 days for novel coextrusion adhesives, freezing formulation innovation cycles.
- Alternative rigid tray competition:Crystallized polyethylene terephthalate ovenable trays are capturing shelf-stable meal applications where dimensional rigidity outweighs flexible packaging cost advantages.
Strategic Opportunities
- Japan commercial kitchen penetration:METI guidelines on plastic resource circulation are creating first-mover advantages for suppliers offering mechanically recyclable mono-PE structures validated under JIS standards.
- Retort pouch convergence:Integration of boil-in bag thermal tolerance with retort sterilization protocols is opening shelf-stable ambient meal categories previously reserved for metal cans.
- Extended producer responsibility frameworks:Deposit-return schemes emerging in France and Germany reward packaging designs with verified recycling pathways, favoring simplified polymer stacks.
Industry Challenges
- Barrier engineer scarcity:Formulation chemists capable of modeling moisture vapor transmission across temperature gradients remain concentrated at legacy film converters, constraining R&D scaling.
- Legacy equipment retrofit costs:Converting lines optimized for two-ply laminates require seven-figure capital outlays to handle sealant coextrusion upgrades demanded by mono-material specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boil-In Bags Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Reusable Bags, Single-Serve Bags, Bulk Bags Material: Polyethylene, Nylon, Polyester, Composite Films End User: Households, Restaurants, Catering Services, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | ProAmpac, UltraSource, Granitol, M and Q Packaging, Packit Gourmet, US Poly Pack, Synpac, Sealed Air Corporation, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boil-In Bags Market Emerging Trajectories
Active packaging intelligence and material stream simplification are converging to redefine performance benchmarks. Suppliers are racing to deliver thermal resilience without sacrificing end-of-life circularity credentials.
Digital printing with solvent-free inks is automating short-run customization for regional meal-kit brands. Contract manufacturers in the Netherlands and California are adopting UV-cured inkjet systems that eliminate plate costs for seasonal promotional designs. This technology is automating the collapse of minimum order quantities that previously locked out mid-sized food startups from branded flexible packaging.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated polymer options for high-fat barrier applications. The European Chemicals Agency substance evaluation process is accelerating substitution timelines for grease-resistant coatings. Manufacturers serving French and German retail channels are pivoting toward clay-based mineral coatings that achieve comparable lipid barrier performance.
Direct sourcing from film converters is consolidating procurement decision-making at central technical teams within multinational restaurant chains. Category managers at these buyers are unbundling legacy distributor markups and negotiating resin-indexed contracts. This pattern is most pronounced in the United States, where three national fast-casual chains now specify exact multi-layer structures rather than accepting converter-recommended standards.
Global Boil-In Bags Market Segmentation
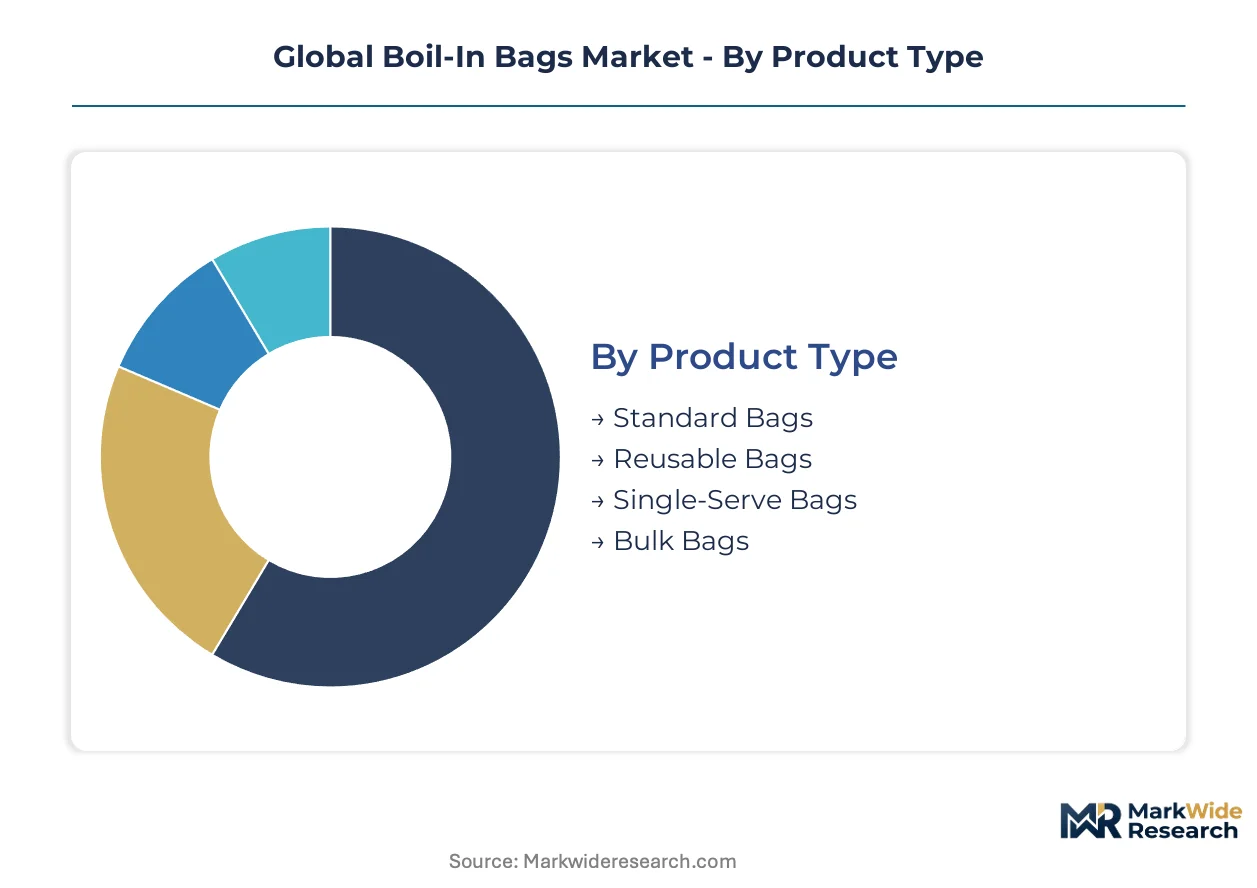
Boil-in bag procurement decisions diverge sharply between standalone consumer purchases and embedded supply chain integrations. Material specifications and format dimensions must align precisely with thermal processing equipment and portion-control protocols across each channel.
Product Type:
Integration depth separates single-use disposable formats from capital-equipment-linked reusable systems in commercial deployments.
- Standard Bags:Multi-layer polyethylene-nylon laminates rated for 100°C+ immersion dominate institutional catering and frozen meal manufacturing. German hospital networks and U.S. correctional facilities specify these for high-volume protein preparation with minimal labor intervention.
- Single-Serve Bags:Precision-portioned formats with pre-measured ingredients integrate into meal-kit subscription fulfillment workflows. These bags compress cooking time for time-constrained households in Japan and the United States while reducing food waste through exact portioning.
- Reusable Bags:Silicone-composite constructions withstand 500+ thermal cycles for commercial kitchen capital equipment programs.
- Bulk Bags:High-capacity formats serve food manufacturers processing institutional quantities of grains and proteins.
Volume placements concentrate in Standard Bags; the faster expansion belongs to Single-Serve Bags.
Material:
Cost tier stratification runs from commodity polyethylene through engineered composite structures commanding formulation premiums.
- Composite Films:Coextruded nylon-polyethylene-EVOH laminates deliver sub-1 cc/m²/day oxygen transmission rates for extended protein shelf life. Sous-vide operators in France and the United States specify these for premium protein programs where barrier integrity spans 45+ day refrigerated distribution.
- Polyethylene:Mono-material and multi-layer PE structures dominate unit economics in price-sensitive wholesale segments. FDA food-contact substance notifications for recycled content PE are accelerating under the EU Packaging and Packaging Waste Regulation's recyclability mandates.
- Nylon:Caprolactam-based polyamide layers provide puncture resistance and thermal stability for bone-in protein applications.
- Polyester:PET films contribute dimensional stability and printability for retail-facing branded applications.
Price-sensitive procurement favors Polyethylene; composite structures claim the steepest expansion trajectory in premium channels.
End User:
Customer type determines specification complexity, with food manufacturers imposing the most rigorous barrier and migration testing protocols.
- Food Manufacturers:Industrial buyers specify exact multi-layer structures with validated oxygen transmission rates under hydrostatic pressure. These stakeholders negotiate resin-indexed contracts and unbundle legacy distributor markups through direct converter relationships.
- Restaurants:Fast-casual chains standardize vacuum-sealed protein preparation, pulling demand for nylon-polyethylene composites rated for precision cooking equipment. German and U.S. restaurant groups lead this operational shift.
- Catering Services:Institutional foodservice operators prioritize thermal resilience and labor efficiency over premium barrier specifications.
- Households:Consumer purchases through retail and subscription channels emphasize cooking convenience and portion control.
Food Manufacturers anchor volume demand; Restaurants are gaining share fastest as precision cooking adoption accelerates.
Distribution Channel:
Supply concentration varies from fragmented specialty retail through consolidated wholesale procurement with direct technical specification.
- Wholesale:Distributor networks serving food manufacturers and restaurant chains consolidate procurement at central technical teams. These channels handle bulk polyethylene formats where price indexing to resin contracts dominates negotiation.
- Online Retail:Direct-to-consumer subscription platforms collapse minimum order quantities for mid-sized meal-kit brands. UV-cured inkjet digital printing systems in California and the Netherlands enable short-run seasonal customization previously locked out by plate costs.
- Supermarkets:Mass retail channels stock standard and single-serve formats for household consumers.
- Specialty Stores:Culinary equipment retailers serve enthusiast consumers with premium reusable and precision-cooking compatible formats.
Wholesale channels capture the largest volume throughput; Online Retail is climbing the fastest as subscription meal-kit penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhineland-Palatinate's polymer corridor near Ludwigshafen anchors European resin supply for boil-in bag converters serving sous-vide operators across the continent.
United States
Fast-casual restaurant chains in Chicago and Dallas-Fort Worth metro areas standardize vacuum-sealed protein preparation protocols. FDA food-contact substance notifications govern resin approvals and migration limits for multi-layer structures. California contract manufacturers deploy UV-cured inkjet digital printing systems that collapse minimum order quantities for regional meal-kit brands.
Germany
Hospital networks in Berlin and Munich specify multi-layer polyethylene-nylon laminates for high-volume institutional catering with minimal labor intervention. EU Green Deal packaging sustainability targets accelerate mono-material polyethylene developments under the EU Packaging and Packaging Waste Regulation. Bavarian film converters validate oxygen transmission rates under hydrostatic pressure conditions for precision cooking equipment manufacturers.
Japan
Commercial kitchen operators in Tokyo and Osaka adopt portion-controlled single-serve formats for time-constrained households. METI guidelines on plastic resource circulation create first-mover advantages for suppliers offering mechanically recyclable mono-PE structures validated under JIS standards. Kanto region meal-kit fulfillment centers compress cooking time while reducing food waste through exact portioning.
France
Sous-vide operators in Lyon and Paris specify coextruded nylon-polyethylene-EVOH laminates for premium protein programs requiring 45+ day refrigerated distribution. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorinated polymer options for high-fat barrier applications. French retail channels pivot toward clay-based mineral coatings that achieve comparable lipid barrier performance without adhesive lamination layers.
Netherlands
Contract manufacturers in Rotterdam and Eindhoven adopt digital printing automation for short-run seasonal customization previously locked out by plate costs. ECHA substance evaluation processes accelerate substitution timelines for grease-resistant coatings. Randstad region converters consolidate procurement decision-making at central technical teams within multinational restaurant chains through direct resin-indexed contracts.
Global Boil-In Bags Market Vendor Landscape
Premium-margin players sit above commodity-margin players across barrier technology tiers, with consolidated converters commanding formulation premiums while fragmented regional fabricators compete on polyethylene unit economics. The vendor base stratifies into three archetypes: vertically integrated resin-to-film operators, specialized multi-layer laminators, and private-label contract manufacturers. Capacity expansion and portfolio diversification toward mono-material recyclable structures dominate competitive moves as extended producer responsibility frameworks mature.
Among North American packaging conglomerates, Sealed Air Corporation and ProAmpac exemplify the integrated barrier technology tier, while Amcor plc anchors the resin-to-film vertical integration archetype. These three entities occupy positions that reflect distinct strategic postures toward regulatory compliance and direct converter relationships with multinational restaurant chains.
| Leading Market Players |
|---|
| ProAmpac |
| UltraSource |
| Granitol |
| M and Q Packaging |
| Packit Gourmet |
| US Poly Pack |
| Synpac |
| Sealed Air Corporation |
| Amcor plc |
| Others |
Supply Flow & Price Mechanics
Direct converter relationships demanded by multinational restaurant chains are forcing material suppliers to absorb legacy distributor markups and negotiate resin-indexed contracts, compressing margins across polyethylene unit economics while elevating premium positions for validated barrier structures.
Pricing Analysis
Outcome-based pricing anchored to oxygen transmission rate guarantees separates composite film suppliers from commodity polyethylene producers. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance certification and migration testing completion. Pricing pressure stems from caprolactam supply tightness in Northeast Asian corridors, which feeds volatility into nylon-polyethylene laminates. Food manufacturers exhibit highest price sensitivity in bulk polyethylene procurement, while sous-vide operators in France and Germany accept premiums for sub-1 cc/m²/day barrier ratings.
Supply Chain Analysis
FDA food-contact substance notification and EU REACH compliance certifications gate market access for resin suppliers and film converters alike. Raw material flows draw from caprolactam production in Germany and Belgium, polyethylene resin complexes along the US Gulf Coast, and EVOH barrier resin manufacturing in Japan. Single-source vulnerability concentrates in specialty adhesive formulations for multi-layer lamination. Distribution runs through converter-direct contracts with central technical teams at multinational restaurant chains, bypassing traditional wholesale distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Boil-In Bags Market functions as a cost-of-compliance arena where EU Packaging and Packaging Waste Regulation recyclability mandates erect barrier-to-entry moats favoring players with validated mono-material pathways and completed migration testing protocols.
For Market Incumbents: Lock in converter-direct relationships with resin-indexed contracts to neutralize distributor disintermediation threats from fast-casual chains in Germany and the United States. Prioritize mono-polyethylene R&D investment to capture extended producer responsibility rewards in France and Germany, while defending against crystallized PET ovenable tray substitution in shelf-stable meal applications. For New Entrants and Emerging Players: The price-point gap between premium composite laminates and commodity polyethylene structures offers white-space entry through mechanically recyclable mono-PE formats validated under JIS standards for Japan commercial kitchens. Target meal-kit subscription fulfillment centers in California and the Netherlands with digital-print-enabled short-run capabilities, bypassing plate-cost barriers that previously excluded mid-sized brands. For Investors and Strategic Acquirers: The window for entry favors specialized multi-layer laminators with FDA notification completion and EU Green Deal alignment. Long-term viability centers on acquisition of formulation chemistry capabilities concentrated at legacy film converters. Monitor caprolactam supply normalization as the inflection signal for margin recovery in nylon-dependent barrier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Film Development | EU Packaging and Packaging Waste Regulation recyclability targets reward simplified polymer stacks with verified mechanical recycling pathways. |
| Migration Testing Investment | FDA food-contact substance notification completion accelerates formulation innovation cycles previously frozen by 180-270 day timelines. |
| Digital Printing Adoption | UV-cured inkjet systems in Rotterdam and California collapse minimum order quantities for regional meal-kit brand customization. |
| Direct Converter Relationships | Resin-indexed contracts with central technical teams unbundle legacy distributor markups at multinational restaurant chains. |
| Japan JIS Standard Validation | METI guidelines on plastic resource circulation create first-mover positioning for mechanically recyclable mono-PE structures. |
Methodological Framework
Document review covered FDA food-contact substance notifications, EU REACH substance evaluations, and METI plastic resource circulation guidelines, complemented by interviews with film converter technical directors, restaurant chain procurement leads, and meal-kit fulfillment operators. Secondary validation drew from customs trade data, SEC filings of packaging conglomerates, and ECHA regulatory databases. Bottom-up modeling of segment volumes triangulated against top-down market sizing from resin production and converter capacity estimates.
Market value and volume outputs across the projection horizon reflect segment-level modeling by product type, material composition, end-user category, and distribution channel. CAGRs were derived from regression analysis of historical penetration rates and forward-looking regulatory compliance timelines. Key forecast inputs included caprolactam supply elasticity, FDA notification approval velocity, and EU extended producer responsibility scheme implementation schedules.
Underlying measurement precision varies by segment; standard bag and polyethylene material categories carry tighter precision than emerging single-serve and reusable format segments where adoption curves remain less certain. Forecasts reflect assumptions about regulatory enforcement consistency and resin price normalization that could shift materially with petrochemical corridor disruptions or accelerated EU Green Deal packaging mandate revisions. A model refresh is warranted upon material change in FDA food-contact substance notification timelines or caprolactam supply contract renegotiations in Northeast Asia.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Paper Pouch Market
Pouch
Morocco Pouch Packaging Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Global Pouches Packaging Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Foil Pouch Packaging Market
Pouch
Dual-Chamber Pouches Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Clear Pouches Market
Pouch
Stick Pouches Packaging Market
Pouch
Digital Printed Pouch Market
Pouch
Box Pouch Market
Pouch
Pouches Market
Pouch
Benelux Pouch Packaging Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market