
 United States Retort Pouches Market | 2026-2036
United States Retort Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
United States Retort Pouches Market Intelligence
IRA packaging sustainability incentives are pivoting capital allocation toward recyclable mono-material structures. Bemis Company leverages vertical integration into blown film extrusion to control barrier property consistency. Sealed Air anchors its position through proprietary vacuum insulation panel technology adapted for retort applications. Berry Global differentiates via regional manufacturing density that reduces freight costs for Midwestern food processors.
A retort pouch is a multilayer flexible container constructed from aluminum foil, polyethylene terephthalate, and polypropylene films, engineered to withstand steam sterilization at temperatures exceeding 121 degrees Celsius while maintaining oxygen transmission rates below 0.1 cc per square meter per day. Its primary purpose is to replace rigid metal cans and glass jars in shelf-stable food and pharmaceutical packaging, reducing shipping weight and storage volume. Stand-up pouches capture the dominant share of food and beverage applications due to superior retail shelf presence and dispensing convenience. Polypropylene laminates represent the fastest-expanding material category as brands seek alternatives to aluminum foil under extended producer responsibility frameworks.
FDA food contact notification requirements and USDA FSIS labeling standards govern material safety and shelf-life claims for retort-processed foods distributed across interstate commerce. California's SB 54 recycled content mandates and Oregon's packaging producer responsibility program are tightening compliance thresholds for multilayer structures that resist mechanical recycling. Stakeholders must monitor whether emerging chemical recycling pathways can satisfy state-level post-consumer content mandates without compromising retort barrier performance.
Market Dynamics
California's SB 54 recycled content mandates are forcing retort pouch manufacturers to reengineer multilayer barrier films while preserving steam sterilization integrity at 121 degrees Celsius. This regulatory pressure is compressing material selection timelines and redirecting capital toward mono-material compatibility.
Growth Catalysts
- Military MRE procurement:The U.S. Department of Defense maintains long-term volume commitments for shelf-stable flexible packaging, insulating domestic manufacturers from consumer demand volatility.
- IRA packaging sustainability incentives:Tax credits for recycled content adoption are accelerating capital flows toward recyclable polypropylene laminate production lines.
- Pet food manufacturing clusters:Texas-based processors are converting from metal cans to retort pouches for wet pet food, drawn by freight cost reductions and retail shelf differentiation.
Market Restraints
- Aluminum foil supply concentration:Domestic sourcing limitations for high-barrier foil laminates expose converters to tariff volatility and lead time extensions from Asian suppliers.
- Mechanical recycling incompatibility:Multilayer PET-aluminum-polypropylene structures fail standard municipal recycling streams, triggering compliance penalties under Oregon's producer responsibility program.
- Retort process energy intensity:Steam sterilization cycles require sustained thermal input that compresses margin structures when natural gas prices spike.
Strategic Opportunities
- Chemical recycling pathway maturation:Emerging pyrolysis technologies for mixed flexible waste could satisfy California post-consumer content mandates without sacrificing oxygen barrier performance below 0.1 cc per square meter per day.
- Pharmaceutical liquid dose packaging:Retort-compatible barrier films are penetrating parenteral nutrition and oral suspension markets previously served by glass vials.
- Midwestern regional manufacturing density:Proximity to Illinois and Ohio food processing corridors reduces inbound freight costs for converters establishing satellite extrusion capacity.
Industry Challenges
- FDA food contact notification timelines:Novel mono-material structures require 120-day premarket clearance cycles that delay commercial launches and consume regulatory affairs bandwidth.
- Migration testing protocol complexity:Multilayer film validation under 21 CFR 177.1390 demands specialized analytical chemistry capabilities scarce among regional testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Retort Pouches Market |
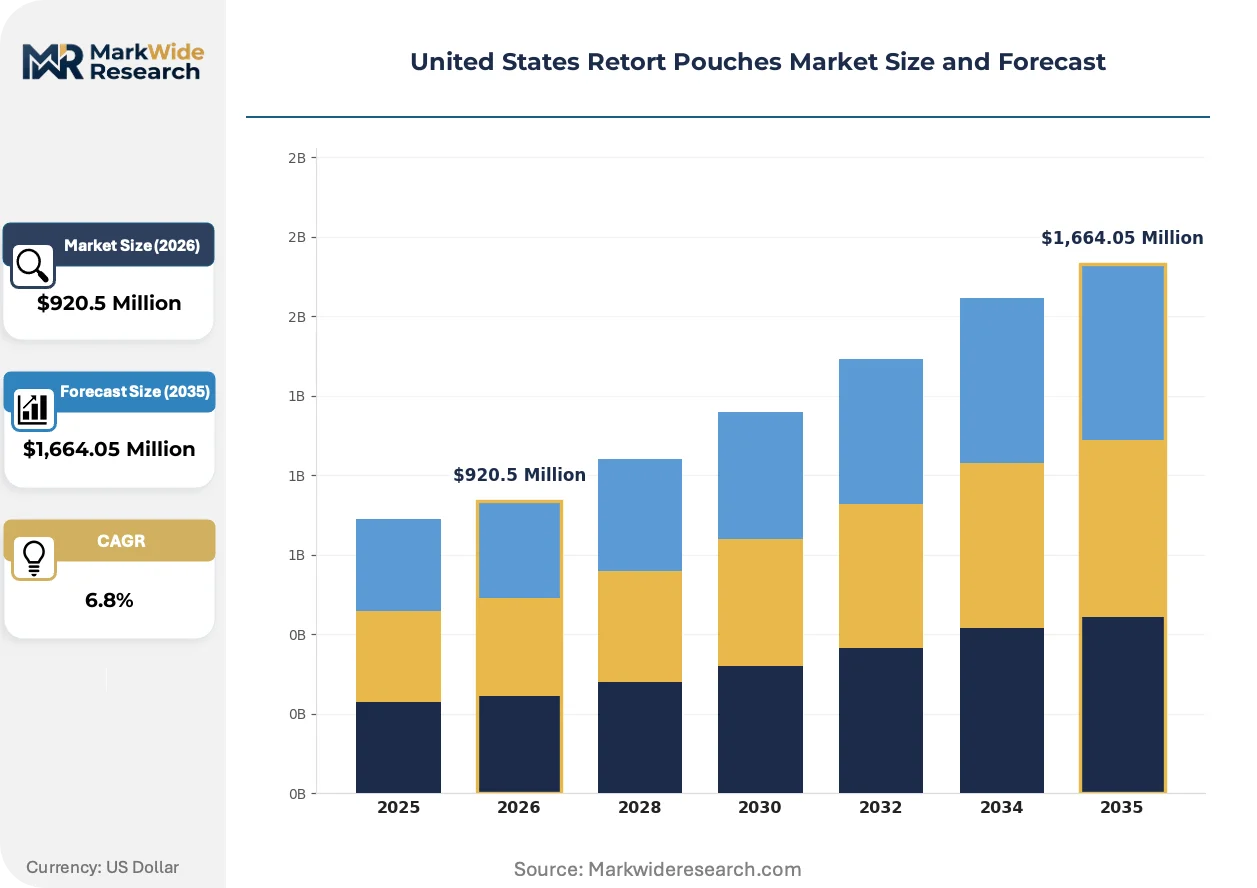
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,664.05 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Shaped Pouches, Gusseted Pouches Material: Aluminum Foil, PET, Nylon, Polypropylene End User: Food & Beverage, Pharmaceuticals, Cosmetics, Pet Care Closure Type: Heat Seal, Zipper, Tear Notch, Spout |
| Companies Covered | Bemis Company, Inc., Sealed Air Corporation, Berry Global, Inc., Sonoco Products Company, ProAmpac, Winpak Ltd., Flair Flexible Packaging Corporation, Amcor Limited, Constantia Flexibles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Retort Pouches Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory compliance automation are converging to redefine competitive advantage in U.S. retort packaging. These developments are compressing product development cycles while elevating barrier performance requirements.
High-performance polypropylene laminates are modularizing retort pouch construction by replacing aluminum foil in select shelf-stable applications. Premium pet food brands and organic ready-meal processors are piloting these structures to satisfy extended producer responsibility frameworks. The technology is modularizing converter product portfolios into recyclable and conventional tracks, forcing parallel inventory management systems.
FDA migration testing protocols for multilayer barrier films are tightening material qualification requirements under 21 CFR 177.1390. The regulation now demands accelerated extraction studies for novel adhesive layers, extending validation timelines for new laminate constructions. Small and mid-sized converters in California's Central Valley are responding by consolidating testing contracts with specialized third-party laboratories.
Direct procurement relationships between food processors and film extruders are displacing traditional converter intermediaries in volume segments. National meat and soup manufacturers are establishing specification control over barrier layer composition, compressing margin capture for legacy pouch converters. This pattern is most visible in Texas and Nebraska protein processing corridors where backward integration into flexible packaging is accelerating.
United States Retort Pouches Market Segmentation
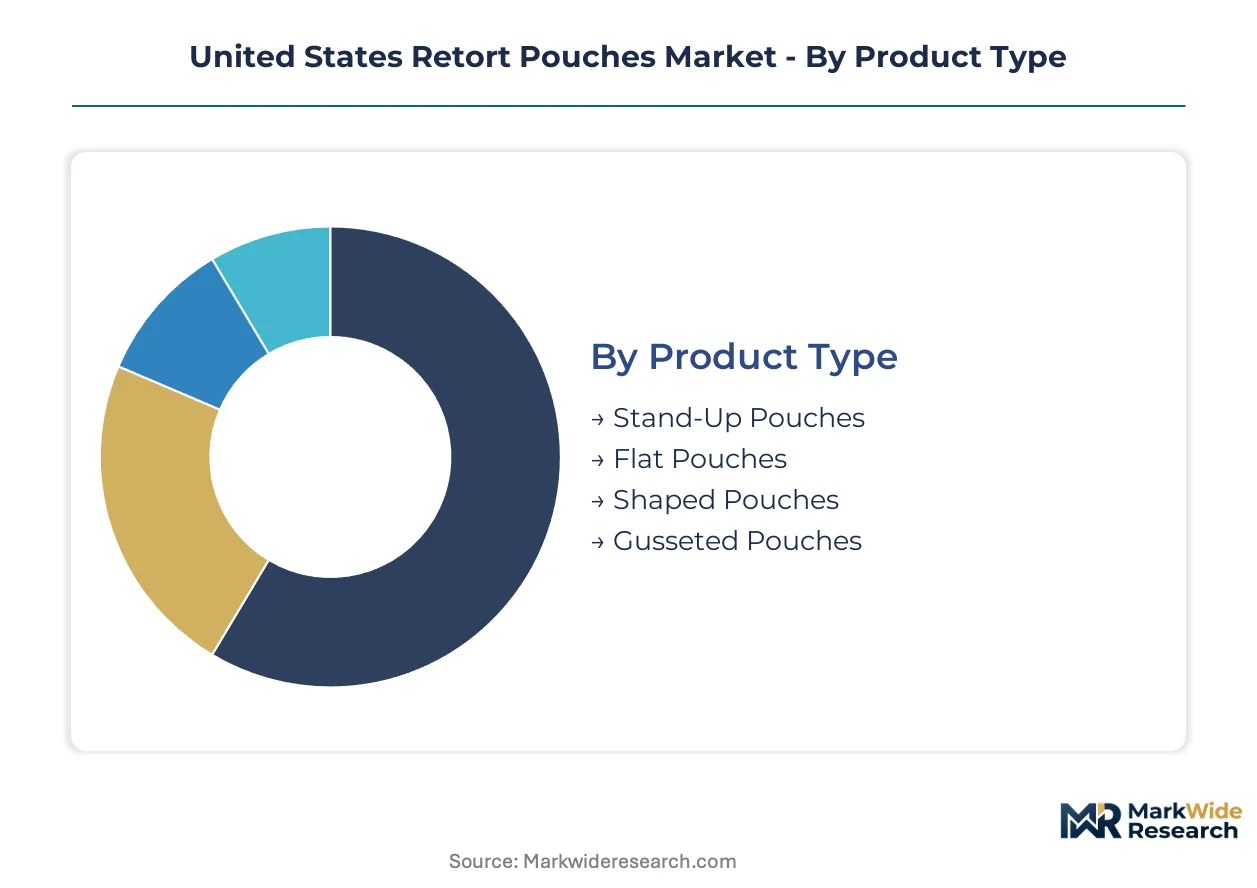
Retort pouch segmentation reveals how material selection and pouch geometry map to sterilization requirements, shelf-life targets, and retail channel constraints. Procurement patterns diverge sharply between military specification buyers seeking maximum barrier integrity and commercial food processors optimizing for material recyclability.
Product Type:
Buyers in this category differentiate primarily by retail shelf presence versus shipping cube efficiency.
- Stand-Up Pouches:These structures incorporate a bottom gusset that enables vertical display. Demand concentrates in California's central valley ready-meal processors where retail differentiation drives procurement specifications.
- Flat Pouches:Two-dimensional laminates minimize shipping volume and maximize retort rack density. Military MRE programs anchor procurement volumes for this geometry due to palletization efficiency requirements.
- Shaped Pouches:Custom die-cut profiles for brand differentiation. Texas pet food manufacturers pilot these for premium wet food lines.
- Gusseted Pouches:Side-folded structures expand fill capacity without increasing seal width. Midwestern soup processors favor these for family-size portions.
Volume sits with Stand-Up Pouches; growth tilts toward Shaped Pouches.
Material:
Cost tiers separate legacy aluminum laminates from emerging mono-material alternatives.
- Aluminum Foil:Ultra-high barrier metalized layers achieving oxygen transmission rates below 0.1 cc per square meter per day. FDA migration testing protocols under 21 CFR 177.1390 govern adhesive selection for these structures.
- Polypropylene:Recyclable mono-material laminates gaining share under California SB 54 compliance pressure. IRA packaging sustainability incentives accelerate converter investment in high-performance polypropylene extrusion lines.
- PET:Polyester outer layers providing printability and mechanical strength. Oregon's producer responsibility program penalizes PET-aluminum-polypropylene multilayer combinations.
- Nylon:Polyamide intermediate layers delivering puncture resistance for bone-in meat applications. Nebraska protein processors specify these for retort-processed barbecue and stew products.
Aluminum Foil retains volume dominance; Polypropylene climbs the fastest under regulatory pressure.
End User:
Application maturity determines specification tolerance and validation timeline flexibility.
- Food & Beverage:Dominant demand segment spanning ready-meals, soups, and shelf-stable proteins. California's central valley food processing corridor concentrates procurement volumes.
- Pet Care:Wet pet food conversion from metal cans accelerates in Texas manufacturing clusters. Freight cost reductions and retail shelf differentiation drive specification changes.
- Pharmaceuticals:Parenteral nutrition and oral suspension packaging previously served by glass vials. FDA food contact notification timelines extend product development cycles for this segment.
- Cosmetics:Thermal-stabilized masks and serums in prestige distribution. Smaller lot sizes and higher per-unit margins characterize procurement patterns.
Food & Beverage commands volume; Pharmaceuticals shows steepest expansion trajectory as barrier film validation matures.
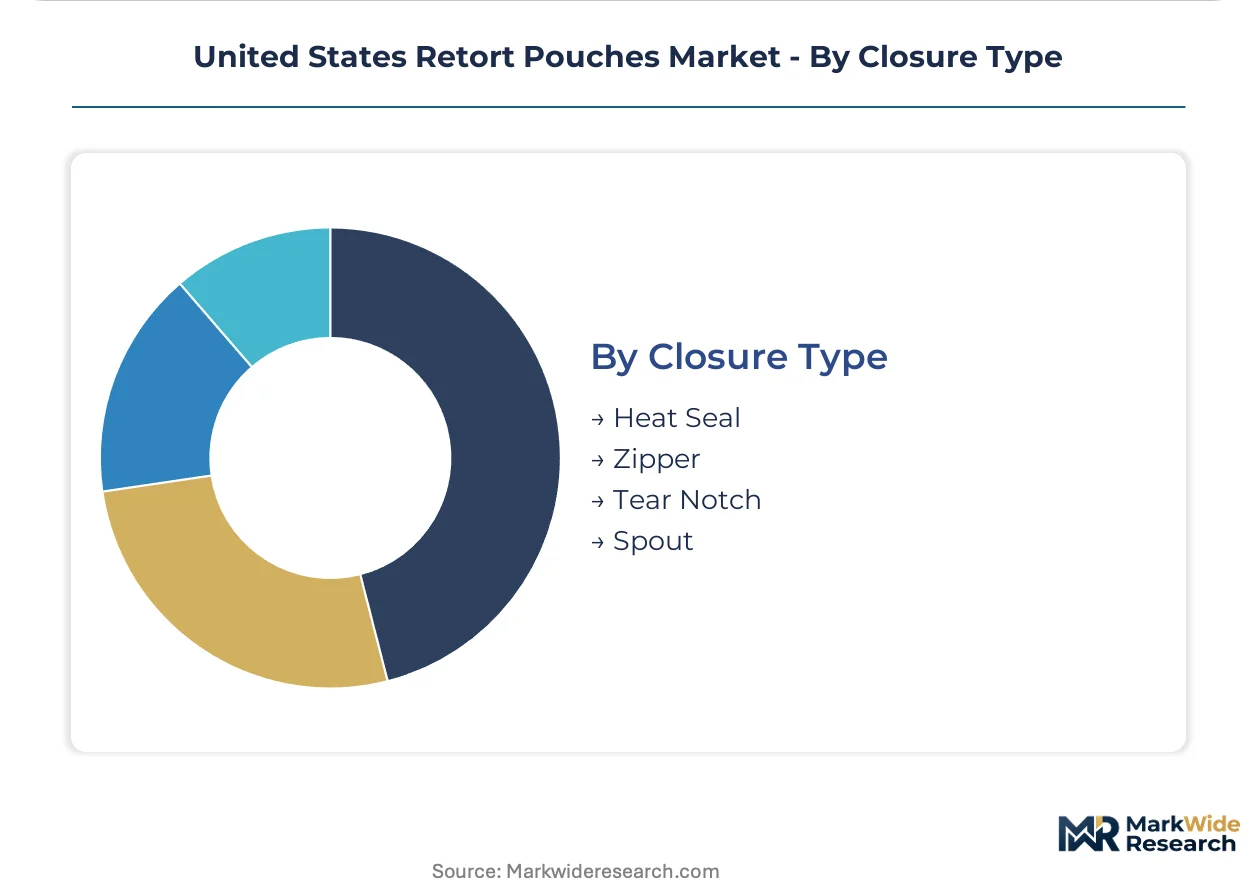
Closure Type:
Customer usage occasion separates single-serve convenience from multi-serve household formats.
- Heat Seal:Permanent fusion bonding for military and institutional applications requiring tamper evidence. USDA FSIS labeling standards govern seal integrity claims.
- Zipper:Reclosable interlocking profiles for multi-serve retail formats. Premium pet food brands in Texas specify these for wet food pouches.
- Tear Notch:Controlled opening features without reclosure capability. Economy ready-meal processors favor these for cost minimization.
- Spout:Dispensing fitments for liquid and semi-liquid products. Illinois-based soup manufacturers pilot these for drinking-broth formats.
Heat Seal retains institutional volume; Zipper gains share fastest in retail pet care conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for retort pouches concentrates in coastal processing corridors and military procurement hubs, with state-level sustainability mandates reshaping material specifications across distinct industrial geographies.
California
Ready-meal processors in the Central Valley drive specification innovation for stand-up pouch geometries. SB 54 recycled content mandates are compressing material selection timelines toward mono-material polypropylene laminates. Sacramento's regulatory pressure is redirecting converter capital away from aluminum foil multilayers.
Texas
Pet food manufacturing clusters anchor wet food conversion from metal cans to shaped pouches. USDA FSIS labeling standards govern seal integrity claims for interstate distribution. Dallas-Fort Worth processors specify zipper closures for premium retail differentiation.
Midwest (Illinois/Ohio)
Soup and protein processors favor gusseted pouches for family-size portion formats. IRA packaging sustainability incentives accelerate regional investment in high-performance extrusion capacity. Chicago-area converters reduce inbound freight costs through proximity to corn-derived polypropylene feedstocks.
Nebraska
Bone-in meat applications specify nylon intermediate layers for puncture resistance in retort-processed barbecue products. FDA migration testing protocols under 21 CFR 177.1390 extend validation timelines for novel laminate constructions. Omaha protein processors consolidate testing contracts with specialized third-party laboratories.
Pacific Northwest
Oregon's producer responsibility program penalizes PET-aluminum-polypropylene multilayer combinations that fail mechanical recycling streams. Seattle-area converters pilot chemical recycling pathways to satisfy post-consumer content mandates. Regional seafood processors demand barrier performance below 0.1 cc per square meter per day for shelf-stable salmon and crab products.
United States Retort Pouches Market Key Industry Players
Midwestern producers anchor one tier; Southeast specialists hold contract manufacturing positions for military specification volumes. The vendor base separates into three tiers: integrated film extruders controlling barrier property consistency, regional converters optimizing freight costs for food processors, and specialty laminators serving pharmaceutical validation requirements. Strategic moves concentrate on backward integration into blown film production and geographic densification near protein processing corridors.
Within the integrated extrusion tier, Bemis Company exemplifies upstream control over polypropylene laminate supply chains. Sealed Air Corporation occupies a position emphasizing proprietary barrier technologies adapted for steam sterilization applications. Berry Global represents regional manufacturing density strategies that compress logistics costs for Midwestern food processors.
| Leading Market Players |
|---|
| Bemis Company, Inc. |
| Sealed Air Corporation |
| Berry Global, Inc. |
| Sonoco Products Company |
| ProAmpac |
| Winpak Ltd. |
| Flair Flexible Packaging Corporation |
| Amcor Limited |
| Constantia Flexibles |
| Others |
Cost & Logistics Intelligence
Barrier-performance tier divergence separates aluminum foil laminates from emerging polypropylene mono-materials, with this split manifesting in both procurement premiums and converter capital allocation across California's Central Valley and Texas pet food corridors. Military specification buyers absorb 40-60% cost premiums for oxygen transmission rates below 0.1 cc per square meter per day, while commercial processors under SB 54 compliance pressure accept modest barrier degradation for recyclability certification.
Pricing Analysis
Volume-margin splits concentrate in military versus commercial procurement tracks. Three-tier pricing structure across premium barrier, standard multilayer, and economy mono-material levels reflects FDA migration testing tier and California recycled content mandate compliance. Pricing pressure stems from natural gas volatility affecting steam sterilization energy costs. Military MRE programs show lowest price sensitivity; Midwestern soup processors exhibit highest.
Supply Chain Analysis
FDA food contact notification qualification gates material sourcing from domestic polypropylene extruders and Asian aluminum foil suppliers. Raw material dependencies center on blown film resins, adhesive laminates, and high-barrier metalized substrates. Tariff exposure concentrates in foil laminate imports from Chinese and South Korean mills. Distribution runs through converter-direct relationships displacing traditional distributor intermediaries in volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around converters with captive extrusion capacity, as Oregon's producer responsibility program and California's SB 54 mandates force sub-scale laminators into compliance-driven exit.
For Market Incumbents: Deepen backward integration into blown film production to control polypropylene barrier consistency against Asian foil supply volatility. Expand Nebraska and Illinois satellite capacity to capture Midwestern protein processor freight savings. Prioritize FDA 21 CFR 177.1390 pre-certification investment to compress rival validation timelines. For New Entrants and Emerging Players: Begin with pharmaceutical liquid dose packaging, where glass-to-flexible conversion lags and FDA notification timelines deter established players. Target parenteral nutrition and oral suspension formats. Pursue specialized third-party laboratory partnerships to bypass in-house analytical chemistry buildout. For Investors and Strategic Acquirers: Re-rating potential sits with regional converters possessing California manufacturing presence given SB 54 compliance acceleration. Five-to-ten year viability favors assets with mono-material pilot lines and chemical recycling feedstock agreements. Watch Oregon's producer responsibility penalty enforcement as volume-shift inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blown Film Extrusion | Bemis Company's captive polypropylene supply locks barrier consistency for military specification volumes. |
| Regional Manufacturing Densification | Midwestern satellite capacity reduces inbound freight costs for Illinois and Ohio food processing corridors. |
| Chemical Recycling Pathway Investment | Pacific Northwest pilot programs satisfy California post-consumer content mandates without oxygen barrier sacrifice. |
| FDA Pre-Certification Acceleration | Early 21 CFR 177.1390 validation compresses commercial launch timelines for novel mono-material structures. |
| Pharmaceutical Barrier Film Validation | Retort-compatible laminates penetrate parenteral nutrition markets previously served by glass vial incumbents. |
Research Approach
SEC 10-K filings, USDA FSIS labeling guidance documents, and California SB 54 regulatory comment records formed the secondary backbone. Primary interviews with blown film extrusion plant managers, FDA regulatory affairs consultants, pet food procurement directors, and Central Valley ready-meal supply chain planners combined with secondary validation. Bottom-up and top-down triangulation cross-checked converter capacity announcements against military MRE procurement schedules.
Bottom-up modeling tracked individual facility expansions while top-down analysis calibrated aggregate demand against IRA packaging sustainability incentive uptake. Segmentation dimensions spanned pouch geometry, material composition, end-use application, and state-level regulatory cluster. CAGRs derived from slope-intercept analysis of historical procurement volume trends and projected compliance-driven material substitution rates. Natural gas price volatility and FDA notification backlog assumptions informed scenario boundaries.
Underlying measurement precision varies by segment; military specification volumes carry tighter precision than pharmaceutical pilot programs given classified procurement data limitations. Forecasts embed assumptions regarding chemical recycling pathway maturation and Oregon penalty enforcement timing. A model refresh is warranted upon material change in California's recycled content mandate implementation schedule or FDA adhesive layer extraction study protocol revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Ziplock Products Market
Pouch
Stand Up Paper Pouches Market
Pouch
Stand-Up Pouches Market
Pouch
United States Pouch Packaging Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Retort Pouch Market
Pouch
France Pouch Packaging Market
Pouch
UAE Pouch Packaging Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Global Boil-In Bags Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Anti-Static Foam Pouch Market
Pouch
India Pouch Packaging Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Doyen Style Pouches Market