
 Standcap Pouch Market | 2026-2036
Standcap Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Standcap Pouch Market Analytics
Premium-grade barrier specifications is unwinding commodity competition across the standcap pouch landscape. Glenroy Inc. leverages proprietary extrusion capabilities to supply high-performance films for inverted pouch formats. Amcor Plc anchors global supply through integrated resin-to-pouch manufacturing platforms. Berry Global Inc. differentiates via healthcare-grade cleanroom production for pharmaceutical standcap applications.
A standcap pouch combines a flexible multilayer film body with a rigid dispensing closure, typically incorporating ethylene vinyl alcohol or metallized layers to achieve oxygen transmission rates below 0.5 cc per square meter per day for shelf-stable contents. The format enables vertical shelf display, one-handed dispensing, and source reduction versus glass or rigid plastic alternatives. Stand-up pouches and spout closures capture disproportionate margin pools as CPG brands prioritize consumer convenience and dosing precision. Plastic and aluminum laminates still dominate unit volumes, though biodegradable substrates are gaining trial placement in European personal care lines where EPR fees penalize non-recyclable formats.
FDA food-contact notification requirements govern adhesive and resin selections for US-bound standcap pouches, while EU REACH restrictions on perfluorinated substances are forcing reformulation of grease-resistant barrier layers. ISO 17088 biodegradability certifications are becoming gatekeeping criteria for brands targeting German and French retail channels. Stakeholders must monitor evolving extended producer responsibility fee schedules and closure compatibility standards before committing to capital-intensive format conversions.
Market Dynamics
Mono-material film structures are displacing legacy multilayer laminates as EU packaging waste directives and EPR fee schedules force format redesigns across condiment and personal care lines. This substrate transition is compressing incumbent barrier technologies while opening supply positions for specialized extrusion houses.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility fees in Germany and France are accelerating brand migrations toward recyclable mono-material standcap formats.
- Foodservice portion-control demand:Quick-service restaurant chains are specifying inverted pouch formats for back-of-house condiment dispensing to reduce waste and improve dosing precision.
- Pharmaceutical unit-dose adoption:Healthcare-grade cleanroom production capabilities are enabling standcap pouches to replace vials for ophthalmic and topical applications.
Market Restraints
- Ethylene vinyl alcohol supply concentration:High-barrier resin production clusters in Northeast Asia create input vulnerability for oxygen-sensitive food applications.
- Closure-film compatibility limitations:Polyolefin mono-material bodies require redesigned dispensing fitments, extending qualification timelines for existing closure suppliers.
- Metallized film substitution pressure:Aluminum oxide-coated substrates are losing position to silicon oxide alternatives as EU REACH restrictions tighten on metalized layer recyclability.
Strategic Opportunities
- Indian condiment market penetration:Domestic sauce and pickle brands are initiating format trials as modern trade shelf-space allocation shifts toward flexible packaging.
- Biodegradable substrate certification:ISO 17088 compliance is becoming a gatekeeping criterion for German retail personal care lines seeking EPR fee reductions.
- Digital printing convergence:HP Indigo and UV inkjet systems are enabling short-run SKU proliferation for private-label condiment refreshes without plate costs.
Industry Challenges
- Barrier engineer talent scarcity:Formulation chemists with coextrusion and adhesive lamination expertise are concentrated among legacy flexible packaging houses.
- Mono-material requalification timelines:FDA food-contact notification cycles for new adhesive and resin combinations extend 18-24 months for shelf-stable applications.
- Legacy filling line retrofit costs:Inverted pouch formats require specialized capping and sterilization equipment incompatible with existing glass bottle infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Standcap Pouch Market |
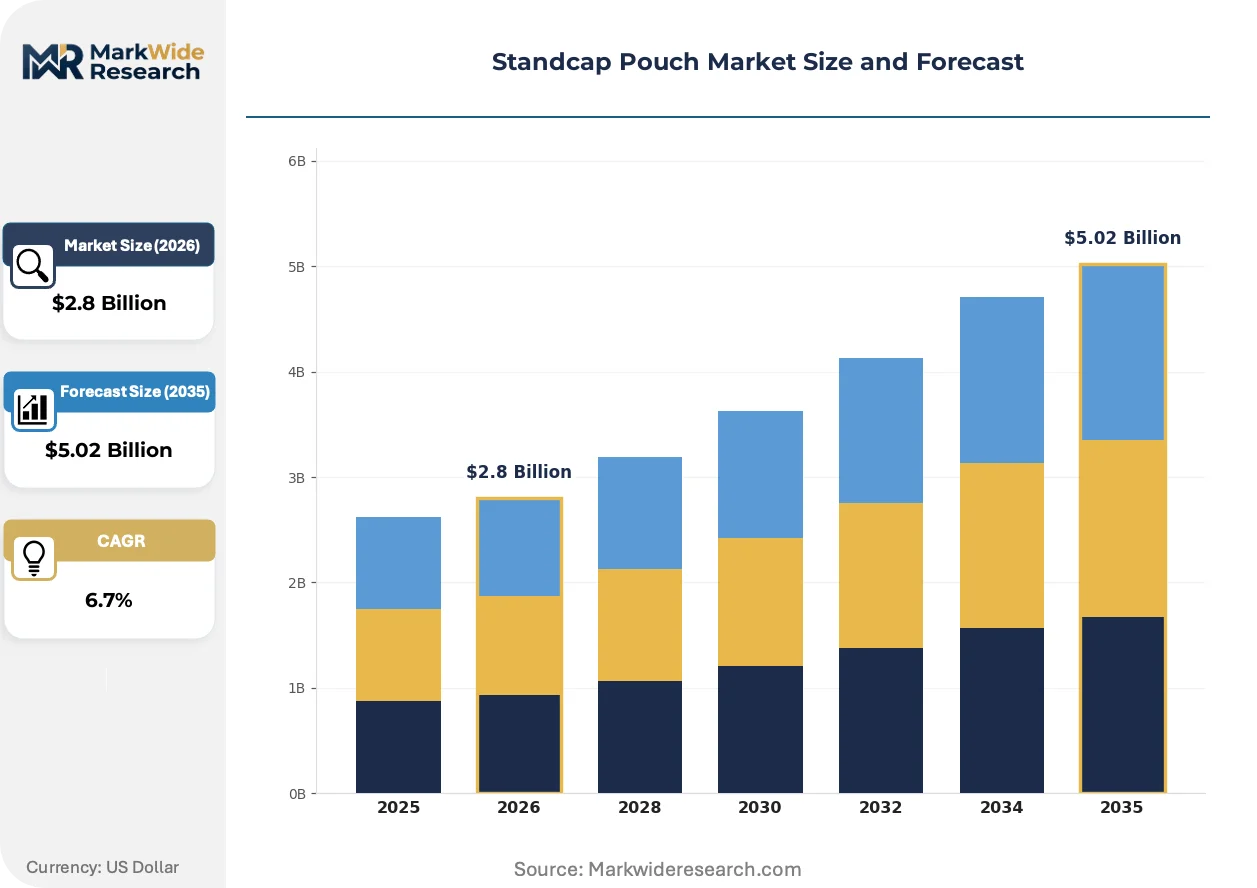
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Zipper Pouches, Window Pouches Material: Plastic, Paper, Aluminum, Biodegradable End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Closure Type: Zipper, Heat Seal, Press-to-close, Spout |
| Companies Covered | Glenroy Inc., Volpak, Aptar, Viking Masek, Amcor Plc, Berry Global Inc., Mondi Group, Sealed Air, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Standcap Pouch Market Evolving Landscape
Active barrier technologies and digital production workflows are compressing development cycles while regulatory deadlines force simultaneous substrate and closure redesigns. These shifts favor suppliers with integrated resin compounding and pouch forming capabilities.
Ethylene vinyl alcohol copolymer barrier layers are miniaturizing through nanolayer coextrusion advances that maintain oxygen transmission performance at reduced thickness. Premium sauce brands in Japan and South Korea are qualifying 11-micron EVOL structures for 18-month shelf life. This thickness reduction is miniaturizing material cost structures while preserving the high-barrier specifications required for ambient distribution.
EU REACH restrictions on perfluorinated substances are forcing reformulation of grease-resistant barrier layers in condiment applications. The industrial consequence is a qualification rush for silicon oxide and aluminum oxide vapor-deposited alternatives. German and French retail channels are most affected, with private-label brands now requiring full material disclosure documentation from film suppliers.
CPG brand procurement teams are consolidating supplier relationships around integrated resin-to-pouch platforms to compress qualification overhead. The direct material sourcing model is displacing multi-tier distribution for high-volume condiment lines. This concentration is most visible in United States private-label programs where retailers specify single-source accountability for format performance failures.
Standcap Pouch Market Segmentation
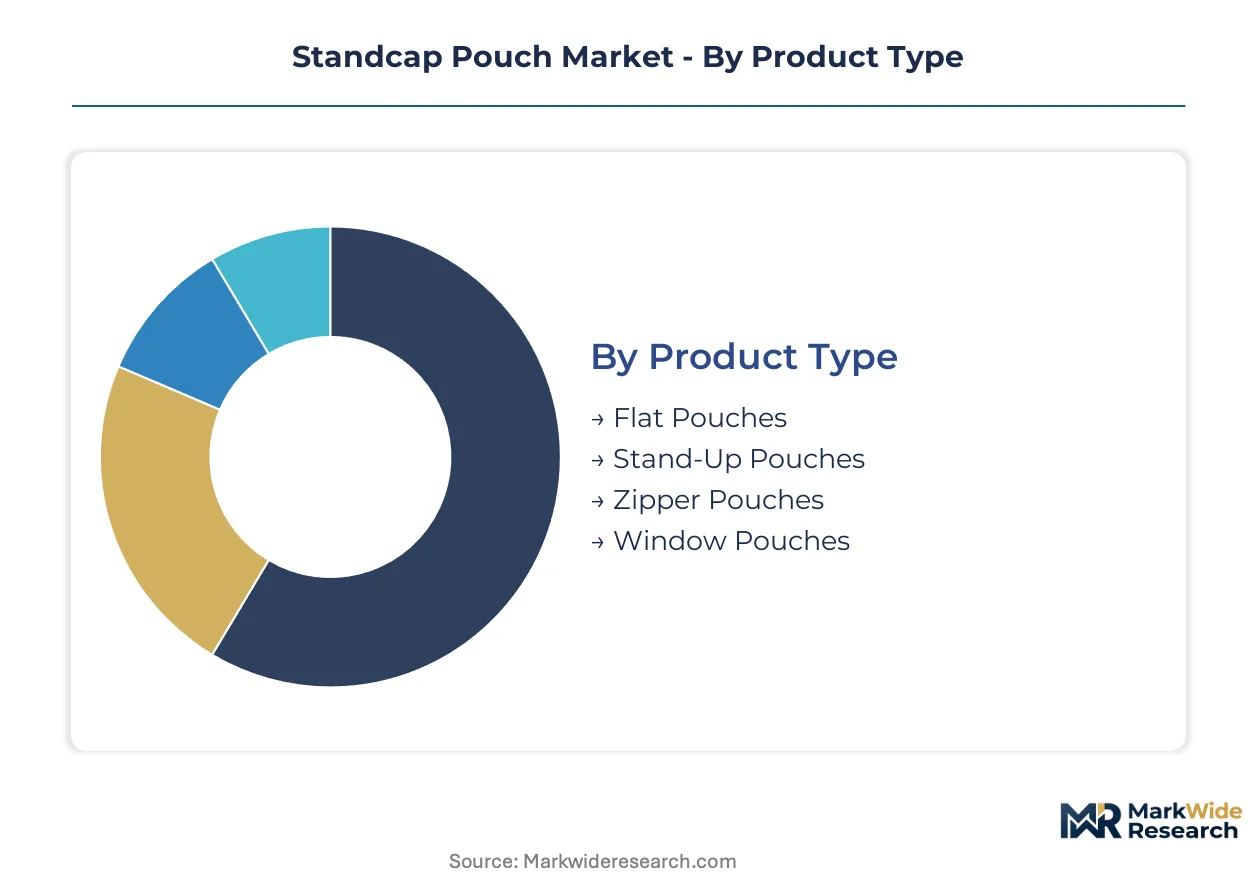
Standcap pouch procurement patterns diverge sharply across product formats and barrier specifications. Format selection hinges on shelf orientation, dispensing mechanics, and regulatory compliance thresholds rather than unit cost alone.
Product Type:
Domestic condiment lines in the United States favor inverted formats for back-of-house dispensing, while export-oriented suppliers standardize on versatile stand-up configurations for multi-channel distribution.
- Flat Pouches:Two-dimensional film constructions with minimal structural rigidity suit single-serve condiment portions and sample sachets. Quick-service restaurant chains in the United States specify flat pouches for ketchup and mustard portion control to reduce packaging weight and disposal volume.
- Stand-Up Pouches:Gusseted base configurations enable vertical shelf display without secondary cartoning. Japanese premium sauce brands are qualifying 11-micron EVOH barrier structures for 18-month ambient shelf life in this format.
- Zipper Pouches:Reclosable interlocking tracks extend product usability across multiple consumption occasions.
- Window Pouches:Die-cut transparent panels or laminated film windows provide visual product verification prior to purchase.
Stand-Up Pouches commands the established base. The steepest expansion runs through Window Pouches.
Material:
Cost tiers separate commodity polyolefin laminates from certified biodegradable substrates commanding EPR fee advantages in German and French retail channels.
- Plastic:Multilayer polyethylene and polypropylene laminates dominate unit economics through high-speed form-fill-seal compatibility. EU packaging waste directives are forcing migration toward mono-material polyolefin structures to meet recyclability thresholds and avoid extended producer responsibility penalties.
- Paper:Fiber-based substrates with polymer barrier coatings target personal care lines seeking tactile differentiation and perceived sustainability. German retail channels are qualifying paper-structured standcap pouches for ISO 17088 biodegradability certification to secure EPR fee reductions.
- Aluminum:Metallized PET and aluminum foil laminates deliver sub-0.5 cc oxygen transmission rates for oxygen-sensitive sauces.
- Biodegradable:PLA and PHA-based films certified to EN 13432 or ISO 17088 standards penetrate European personal care applications where regulatory penalties favor compostable formats.
Plastic retains volume leadership across condiment and household applications. Biodegradable substrates are gaining share fastest in EU personal care lines.
End User:
Application-specific barrier requirements and cleanroom certification standards segment supplier capabilities across food, pharmaceutical, and personal care verticals.
- Food & Beverage:Shelf-stable condiments, sauces, and ready-to-drink beverages require oxygen barriers below 0.5 cc per square meter per day and FDA food-contact notification compliance for adhesive and resin selections.
- Personal Care:Lotions, shampoos, and cosmetic formulations prioritize dispensing precision and aesthetic differentiation over extended shelf life.
- Household Products:Detergents and cleaning concentrates utilize standcap pouches for source reduction versus rigid bottles.
- Pharmaceuticals:Unit-dose ophthalmic and topical applications demand healthcare-grade cleanroom production capabilities with particulate contamination controls exceeding ISO 14644 Class 7 standards.
Food & Beverage anchors installed capacity. Pharmaceuticals is climbing the fastest as unit-dose formats displace glass vials.
Closure Type:
Customer type segmentation separates retail consumers requiring reclosability from foodservice operators prioritizing one-handed dispensing speed.
- Zipper:Interlocking plastic tracks enable repeated opening and closing for multi-use consumer products.
- Heat Seal:Permanent fusion bonds provide tamper evidence and extended shelf stability for single-serve portions.
- Press-to-close:Snap-fit mechanisms balance reclosability with manufacturing simplicity for mid-tier condiment lines.
- Spout:Rigid dispensing fitments with threaded or snap closures enable precise dosing control for inverted pouch formats. Polyolefin mono-material pouch bodies require redesigned spout geometries, extending qualification timelines for existing closure suppliers.
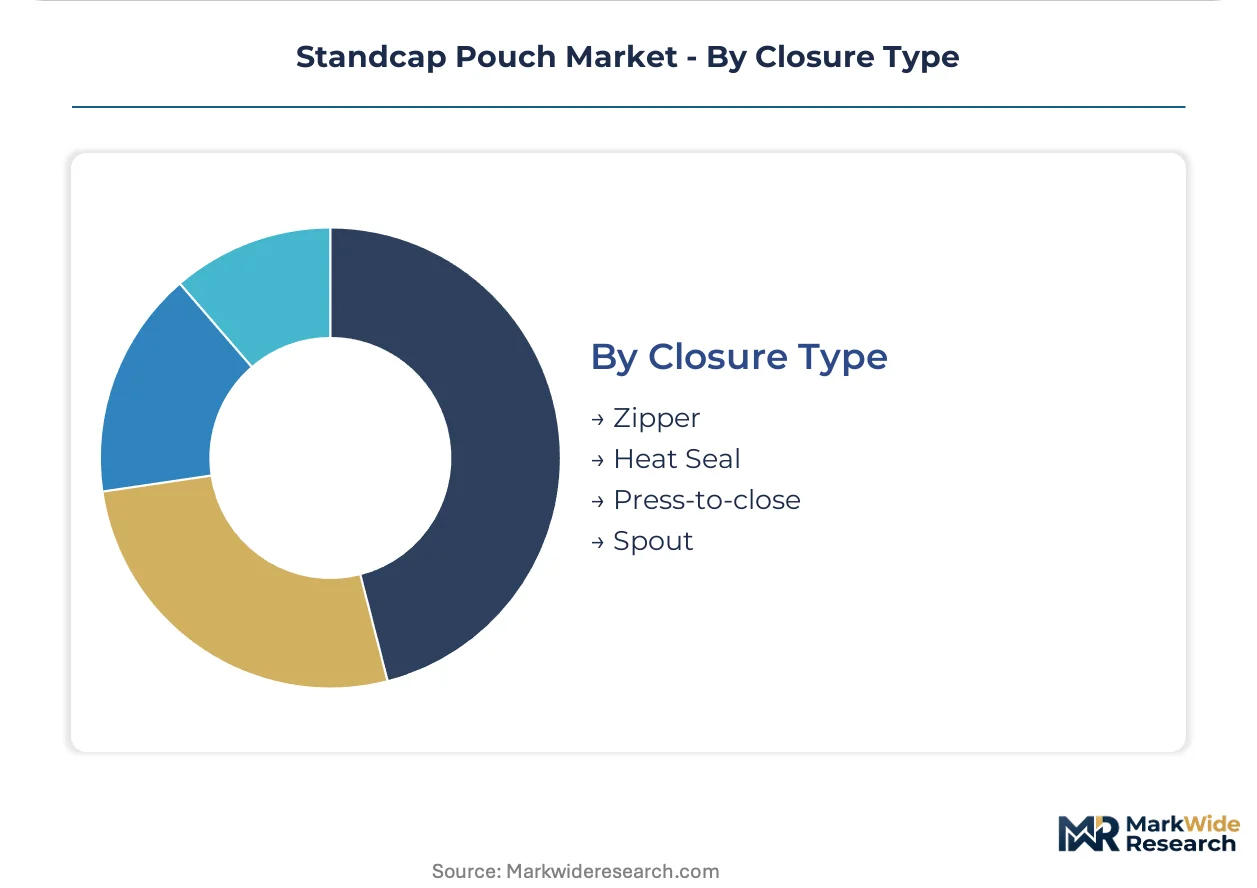
Heat Seal retains cost leadership for portion-control applications. Spout closures are expanding most quickly as inverted formats displace rigid bottles in condiment dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States exporters supply converted standcap pouches to Canadian private-label condiment lines and Mexican foodservice distributors, establishing a North American trade corridor anchored by FDA-compliant film specifications.
United States
Private-label condiment refreshes at major retailers drive inverted pouch conversions from rigid bottles. FDA food-contact notification requirements govern adhesive and resin selections for shelf-stable sauce applications. Wisconsin and Illinois host specialized extrusion houses supplying high-performance barrier films to CPG brand owners.
Germany
Extended producer responsibility fees under EU packaging waste directives accelerate brand migrations toward recyclable mono-material formats. ECHA REACH restrictions on perfluorinated substances force reformulation of grease-resistant barrier layers in condiment applications. The Düsseldorf-Cologne industrial corridor concentrates film lamination and pouch converting capacity for European distribution.
France
EPR fee schedules penalize non-recyclable formats, pushing personal care brands toward ISO 17088-certified biodegradable substrates. ANSM packaging material regulations align with EU Green Deal mandates for material disclosure documentation. The Lyon-Grenoble cluster advances silicon oxide vapor-deposited alternatives to metallized films.
Japan
Premium sauce brands qualify 11-micron EVOH nanolayer structures for 18-month ambient shelf life in stand-up configurations. METI circular economy guidelines encourage mono-material adoption across flexible packaging categories. The Nagoya industrial zone maintains coextrusion expertise for oxygen barrier miniaturization.
India
Domestic sauce and pickle brands initiate format trials as modern trade shelf-space allocation shifts toward flexible packaging. FSSAI food-contact material standards govern imported film qualifications for local converting operations. Maharashtra and Gujarat house emerging pouch converting capacity serving regional condiment processors.
Standcap Pouch Market Competitive Landscape
Listed leaders compete with private specialists across integrated manufacturing platforms, creating a tiered structure where scale-driven multinationals anchor global supply while regional extrusion houses capture niche barrier specifications. Three archetypes dominate: resin-to-pouch integrated platforms, specialized high-barrier film suppliers, and healthcare-grade cleanroom operators. Capacity expansion and backward integration into captive resin compounding represent the primary competitive vectors as brands consolidate supplier relationships.
Within the integrated platform tier, Amcor Plc and Berry Global Inc. exemplify scale-driven supply consolidation, while Glenroy Inc. occupies a specialized position among North American barrier film suppliers. These three anchors represent distinct strategic postures—global manufacturing footprint, healthcare-grade production capabilities, and proprietary extrusion technology—without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Glenroy Inc. |
| Volpak |
| Aptar |
| Viking Masek |
| Amcor Plc |
| Berry Global Inc. |
| Mondi Group |
| Sealed Air |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
Silicon oxide vapor-deposited barrier layers replacing aluminum oxide metallized films are redrawing supply geography toward Lyon-Grenoble cluster specialists while compressing pricing premiums previously attached to legacy metallized structures. This substrate transition simultaneously elevates qualification costs for new entrants and concentrates margin capture among integrated film suppliers with captive vapor deposition capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates healthcare-grade cleanroom-certified pouches from food-contact compliant formats and commodity condiment lines. Price differentiation hinges on barrier performance certification and FDA food-contact notification tier, with oxygen transmission rates below 0.5 cc per square meter per day commanding substantial premiums. Pricing pressure stems from EPR fee-driven brand migrations toward mono-material formats that sacrifice barrier performance for recyclability compliance. Private-label condiment buyers exhibit highest price sensitivity, while pharmaceutical unit-dose adopters prioritize cleanroom certification over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites ethylene vinyl alcohol resin flows from Northeast Asian petrochemical complexes to European and North American converting operations. Raw material procurement draws from South Korean and Japanese EVOH copolymer production, Chinese polyethylene resin compounding, and German adhesive formulation specialists. Single-source vulnerability concentrates in high-barrier resin supply, with limited qualified alternatives for oxygen-sensitive food applications. Distribution runs through integrated resin-to-pouch platforms that displace multi-tier distribution for high-volume condiment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The standcap pouch market operates as a rigid bottle substitution defense, with glass and rigid plastic incumbents accelerating format refreshes to retain shelf position against flexible packaging migration.
For Market Incumbents: Compound barrier technology differentiation through nanolayer coextrusion miniaturization to maintain oxygen transmission performance at reduced material thickness. Prioritize backward integration into captive EVOH resin compounding to secure input supply against Northeast Asian concentration risk. Defend against silicon oxide vapor deposition specialists by accelerating FDA notification cycles for next-generation barrier adhesives. For New Entrants and Emerging Players: Lead with ISO 17088 biodegradable substrate certification targeting German and French personal care lines seeking EPR fee reductions. White-space availability concentrates in Indian condiment format trials as modern trade shelf-space allocation shifts toward flexible packaging. Establish digital printing convergence capabilities to capture short-run private-label SKU proliferation without plate cost barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed flexible packaging roll-ups holding regional converting capacity without captive resin supply. Long-term viability over the next decade depends on successful mono-material transition completion and closure-film compatibility resolution. Watch for FDA food-contact notification approval velocity as inflection indicator for barrier technology competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive EVOH supply secures barrier film margins against Northeast Asian input volatility. |
| Healthcare-Grade Cleanroom Certification | ISO 14644 Class 7 compliance unlocks pharmaceutical unit-dose vial replacement opportunities. |
| Mono-Material Format Qualification | FDA notification approval enables EU Green Deal-compliant condiment line conversions. |
| Digital Printing Platform Deployment | HP Indigo and UV inkjet systems capture private-label SKU proliferation without plate costs. |
| Sustainability Repositioning | ISO 17088 certification secures EPR fee reductions in German and French retail channels. |
Research Methodology
The analysis maps mono-material substrate transitions, barrier technology generations, and closure-film compatibility configurations, each validated through film extrusion engineers, CPG brand procurement directors, and foodservice equipment specification managers. Primary fieldwork combined with secondary validation from FDA food-contact notification databases, EU ECHA REACH substance restrictions, and flexible packaging trade association technical reports supports bottom-up and top-down triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, material substrate, end-use vertical, and closure mechanism segmentation dimensions. CAGRs derive from modeled adoption curves for inverted pouch format conversions and mono-material substitution rates. Industry-specific forecast inputs incorporate EPR fee schedule implementation timelines and FDA notification approval cycle durations.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of EU packaging waste directives and FDA food-contact compliance thresholds would require recalibration. Forecasts reflect documented assumptions regarding barrier technology qualification timelines and closure redesign adoption rates. Practitioners should keep alternative scenarios live as EVOH supply concentration and mono-material performance trade-offs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Squeeze Pouch Market
Pouch
Stand Up Paper Pouches Market
Pouch
Self-Seal Pouches Market
Pouch
Pillow Pouch Packaging Market
Pouch
Liquid Pouch Packaging Market
Pouch
Foam Pouch Market
Pouch
Retort Pouch Packaging Market
Pouch
Spout Pouch Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Utility Pouches Market
Pouch
Four Side Flat Pouch Market
Pouch
Flat Bottom Pouch Market
Pouch
Box Pouch Market
Pouch
Feed Pouches Market
Pouch
United States Pouch Packaging Market