
 Barrier Bags Market | 2026-2036
Barrier Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Bags Market Outlook
The gap between premium multi-layer coextruded barrier bags and commodity polyethylene alternatives is broadening as end-users segment procurement by shelf-life sensitivity. Amcor plc sustains technology leadership through its pharmaceutical-grade cold-form foil laminates, while Mondi Group anchors European supply with integrated kraft paper-barrier film hybrids for dry food applications. Sealed Air Corporation differentiates via automated packaging system compatibility, embedding sensor-responsive films that reduce manual handling in cleanroom environments.
Barrier bags are engineered flexible packaging structures incorporating metallized films, ethylene vinyl alcohol copolymers, or aluminum foil layers to achieve oxygen transmission rates below 0.1 cc/m²/day and water vapor transmission rates under 0.01 g/m²/day, primarily preserving product integrity across extended distribution cycles. Polyethylene dominates volume production for frozen food and agricultural chemicals where moderate barrier performance satisfies cost constraints, while aluminum foil laminates command the highest margin pools in pharmaceutical serialization and oncology drug packaging. Nylon-reinforced structures grow fastest in electronics, protecting moisture-sensitive semiconductors during ocean freight from Asia-Pacific manufacturing hubs to European assembly plants.
US FDA enforces strict extractables and leachables testing under container closure guidance for pharmaceutical barrier bags, compelling suppliers to maintain drug master files and validate sterilization compatibility. REACH and the EU Green Deal's packaging recyclability targets are forcing substitution of multi-material laminates with mono-polymer or paper-based barrier alternatives that retain functional performance. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between reformulating legacy barrier structures or accelerating capital deployment into recyclable high-barrier platforms before compliance deadlines harden.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material redesign across the barrier bags value chain, compelling suppliers to abandon multi-material laminates in favor of recyclable mono-polymer or paper-based alternatives that retain ultra-low oxygen transmission performance.
Growth Catalysts
- Biologics packaging demand:Sterile injectables and cell therapies require aluminum foil laminates with oxygen transmission rates below 0.1 cc/m²/day, pulling pharmaceutical-grade capacity expansion.
- REACH substitution mandates:ECHA restrictions on perfluorinated compounds accelerate adoption of ethylene vinyl alcohol copolymers and metallized films as compliant barrier layers.
- Electronics freight protection:Nylon-reinforced structures are displacing desiccant-heavy packaging for semiconductors shipped from Taiwan and South Korea to European assembly plants.
Market Restraints
- Aluminum foil cost volatility:Primary aluminum price swings tied to Chinese smelter curbs compress margins for pharmaceutical-grade cold-form laminates.
- Recyclability-performance trade-off:Multi-layer coextruded films achieving sub-0.01 g/m²/day moisture barriers resist mechanical recycling under EU Green Deal targets.
- Cleanroom validation timelines:FDA container closure guidance requires 18-24 month extractables and leachables testing, delaying new material qualification.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with ICH Q1 stability guidelines creates demand for US/EU-validated barrier film suppliers in Hyderabad and Ahmedabad clusters.
- Sensor-embedded films:Integration of time-temperature indicators with metallized polyethylene terephthalate enables cold chain integrity verification for mRNA vaccines.
- Paper-barrier hybrids:Mondi Group's kraft paper-aluminum oxide laminates capture dry food segments seeking plastic reduction without shelf-life sacrifice.
Industry Challenges
- Mono-material high-barrier R&D:Developing polyethylene or polypropylene structures matching EVOH oxygen barriers requires multiyear polymer science investment with uncertain technical endpoints.
- Extended producer responsibility compliance:Germany's Verpackungsgesetz fees for non-recyclable packaging force rapid reformulation of legacy multi-layer inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Bags Market |
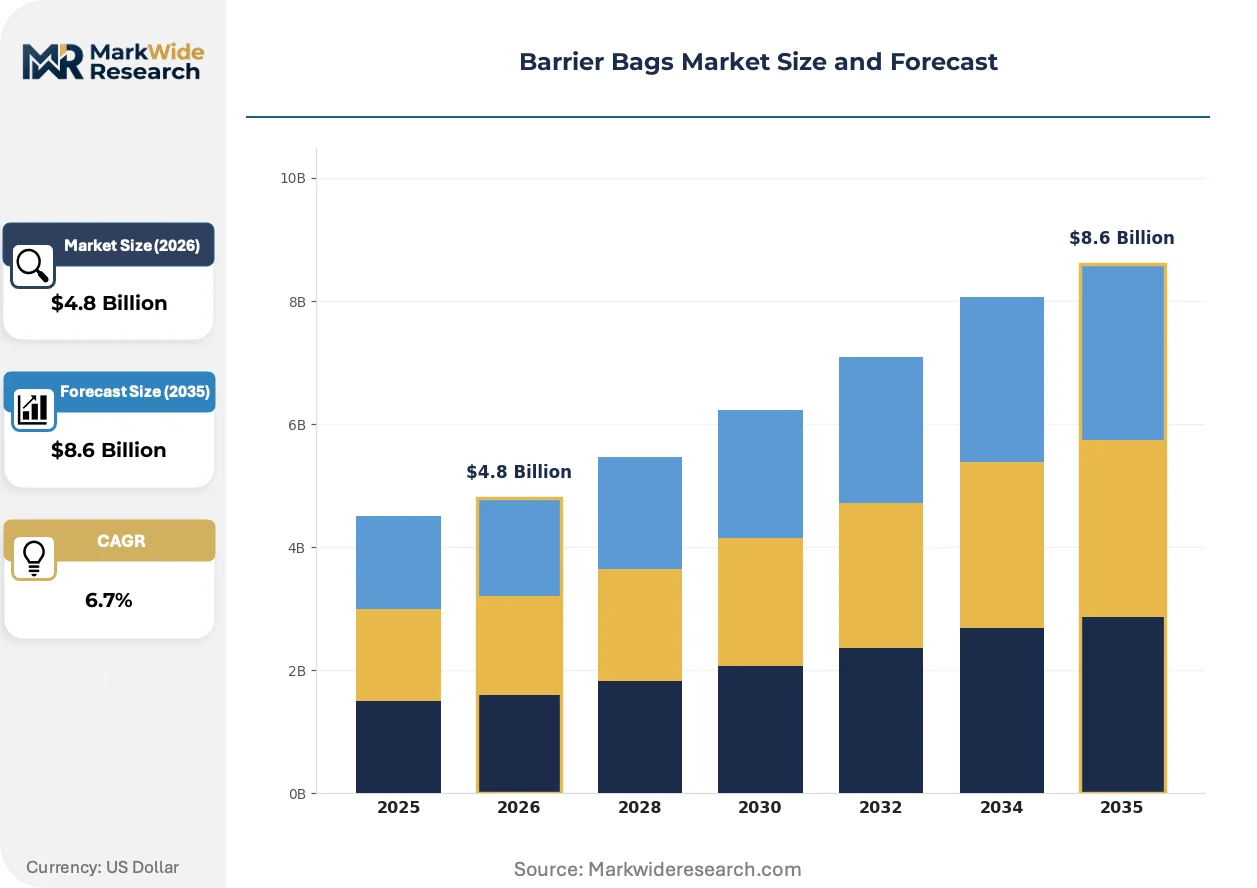
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Nylon, Aluminum Foil Closure Type: Resealable, Zipper, Heat Seal, Taped End Use: Food Packaging, Pharmaceutical Packaging, Electronics, Chemicals Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Sealed Air Corporation, Amcor plc, Mondi Group, Berry Global, WINPAK LTD., Sonoco Products Company, Viscofan Group, FLEXOPACK S.A., ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Bags Market Strategic Shifts
Active barrier technologies and circular material platforms are compressing traditional competitive advantages built on proprietary multi-layer coextrusion, while regulatory deadlines harden performance-recyclability trade-offs into binary compliance gates.
Metallized aluminum oxide coatings deposited via plasma-enhanced chemical vapor deposition are modularizing barrier film architecture. Pharmaceutical contract manufacturers in Germany and Switzerland adopt these structures to simplify sterilization validation while maintaining sub-0.1 cc/m²/day oxygen barriers. The technology compresses supplier qualification cycles from 24 months to 12 months by eliminating adhesive layers that complicate extractables profiling.
REACH Article 33 disclosure requirements for substances of very high concern are forcing full material transparency across European barrier bag supply chains. Suppliers must now document bisphenol A, phthalate plasticizer, and heavy metal content down to 0.1% concentration thresholds. Dry food and personal care segments in France and Italy are responding fastest, specifying aluminum oxide or silicon oxide ceramic coatings as drop-in replacements for metallized films with ambiguous additive profiles.
Buyer consolidation among pharmaceutical contract manufacturing organizations is compressing supplier panels from twelve to four approved vendors per therapeutic category. Tier-one CMOs in Germany and the Netherlands now demand integrated barrier film-plus-automation system packages rather than commodity film supply. This behavioral shift concentrates volume with converters capable of validating sensor-responsive films within existing cleanroom packaging lines.
Barrier Bags Market Segmentation
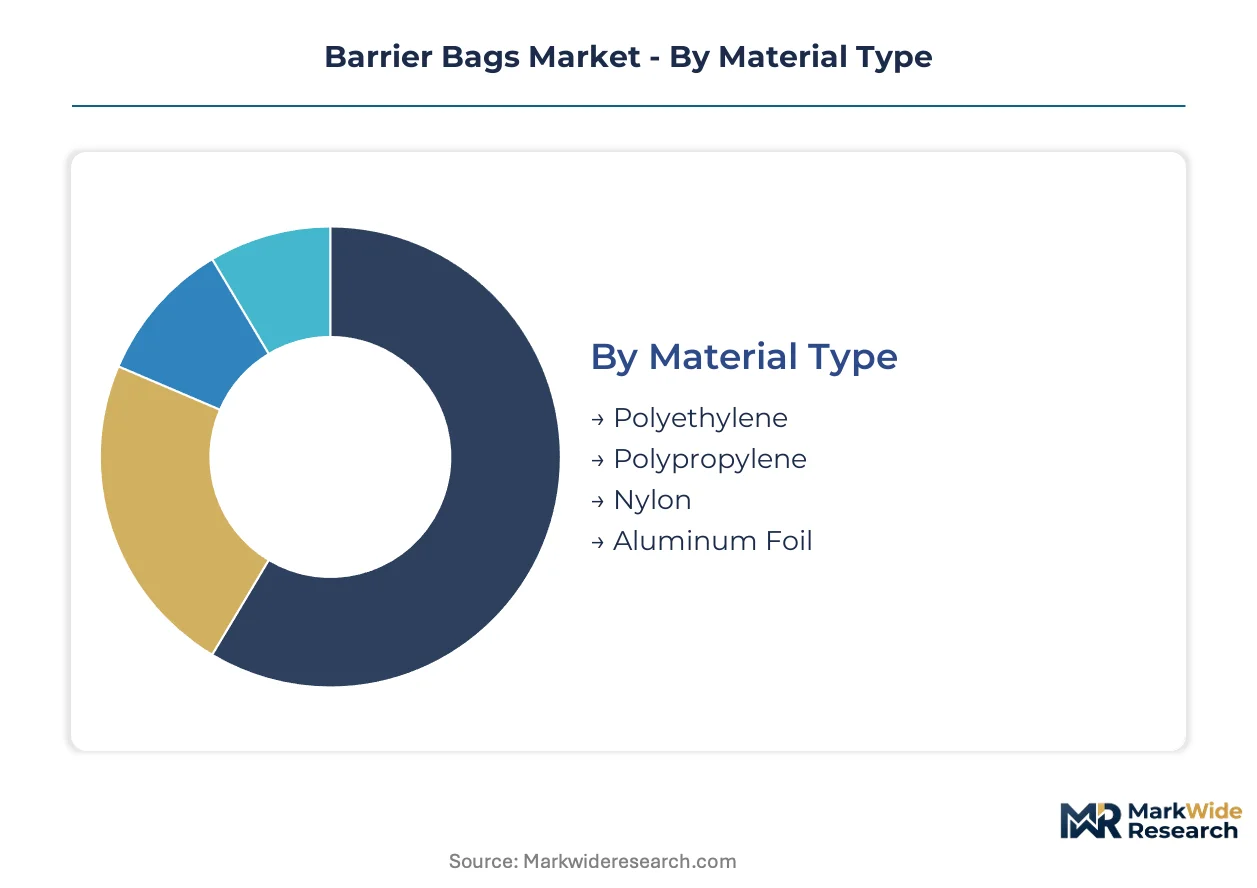
Barrier bags segment across material chemistry, closure mechanics, and channel economics. Procurement teams balance shelf-life performance against recyclability mandates and cleanroom validation requirements. Each category reveals distinct margin pools and technical barriers to entry.
Material Type:
Customization intensity ranges from commodity polyethylene to engineered aluminum foil laminates requiring drug master file validation.
- Polyethylene:Linear low-density and high-density variants dominate frozen food and agricultural chemical applications. German retailers specify mono-material PE structures to satisfy Verpackungsgesetz recyclability fees. Cost constraints limit barrier performance to moderate oxygen transmission rates.
- Aluminum Foil:Cold-form laminates achieve sub-0.1 cc/m²/day oxygen barriers essential for biologics and oncology drugs. Swissmedic and FDA extractables testing extends qualification cycles to 18-24 months. Hyderabad and Ahmedabad pharmaceutical clusters pull premium foil capacity.
- Polypropylene:Cast and oriented films serve retort pouch applications where thermal stability exceeds polyethylene limits. REACH-compliant additives substitute legacy plasticizers.
- Nylon:Biaxially oriented nylon-reinforced structures protect moisture-sensitive semiconductors during ocean freight from Taiwan and South Korea. Electronics assemblers in Bavaria specify nylon-6 for puncture resistance.
Most installed capacity flows through Polyethylene. Expansion is steepest in Aluminum Foil.
Closure Type:
Automation compatibility and cleanroom handling requirements separate premium closures from commodity alternatives.
- Heat Seal:Induction and impulse sealing dominate pharmaceutical serialization where hermetic integrity prevents contamination. German CMOs validate seal strength per USP <1207> container closure integrity guidelines. Automated packaging lines in the Netherlands demand 99.97% seal reliability rates.
- Resealable:Hook-and-loop and slider mechanisms capture dry food segments requiring repeated access without barrier degradation. Italian pasta and coffee brands specify resealable kraft paper-barrier hybrids.
- Zipper:Press-to-close profiles integrate with form-fill-seal equipment for frozen vegetables and prepared meals. French retail chains mandate mono-material zipper compatibility with existing recycling streams.
- Taped:Pressure-sensitive adhesive closures serve industrial chemical and diagnostic kit applications where one-time opening suffices. Swiss precision chemical clusters favor taped formats for batch traceability.
Heat Seal commands the largest share of pharmaceutical-grade installations. Resealable formats are climbing the fastest in food applications.
End Use:
Regulatory stringency and product value density determine specification thresholds across verticals.
- Pharmaceutical Packaging:Sterile injectables and cell therapies require aluminum foil laminates with validated sterilization compatibility. EMA and FDA container closure guidance compels suppliers to maintain drug master files. German contract manufacturing organizations consolidate supplier panels to four approved vendors per therapeutic category.
- Food Packaging:Dry goods and frozen segments drive volume demand for cost-optimized barrier structures. Mondi Group's kraft paper-aluminum oxide laminates capture plastic-reduction specifications without shelf-life sacrifice.
- Electronics:Nylon-reinforced bags displace desiccant-heavy packaging for semiconductors shipped from Asia-Pacific manufacturing hubs to European assembly plants. Moisture sensitivity level ratings dictate barrier thickness requirements.
- Chemicals:Agricultural and industrial chemical segments prioritize puncture resistance and chemical inertness over ultra-low transmission rates. REACH compliance documentation extends lead times for specialty formulations.
Food Packaging absorbs the greatest material tonnage. Pharmaceutical Packaging shows the steepest margin expansion trajectory.
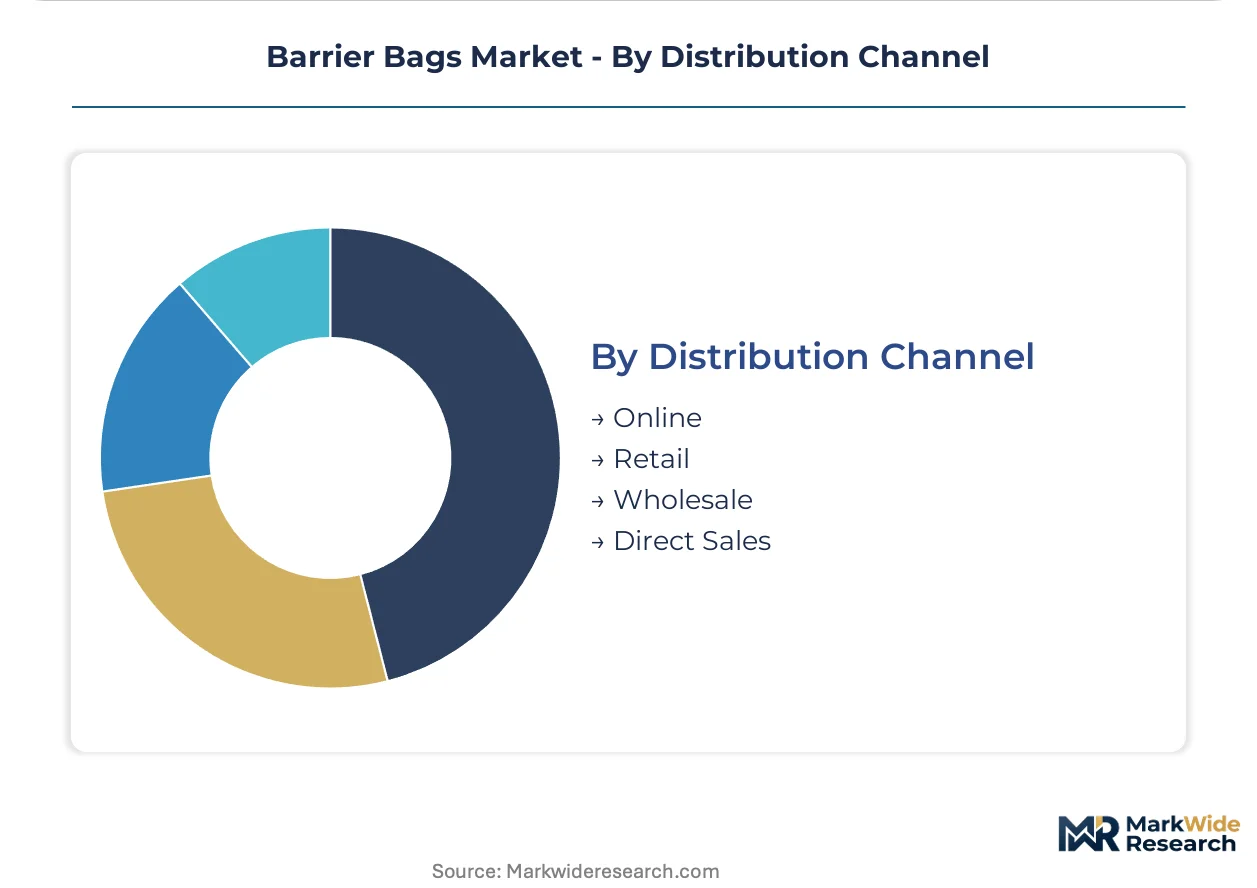
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and validation documentation needs.
- Direct Sales:Pharmaceutical and electronics manufacturers source validated barrier films through converter-direct relationships. Integrated film-plus-automation system packages dominate German and Dutch CMO procurement. Technical field support accelerates cleanroom line qualification.
- Wholesale:Industrial chemical and agricultural distributors aggregate fragmented demand across mid-tier processors. Inventory pooling reduces working capital for seasonal applications.
- Retail:Small-scale food processors and diagnostic kit assemblers purchase standardized SKUs through packaging distributors. French and Italian retail channels specify aluminum oxide coatings for SVHC transparency.
- Online:E-procurement platforms serve prototype and short-run electronics manufacturers requiring rapid material sampling. Digital specification tools compress supplier identification cycles.
Direct Sales channels carry the highest revenue concentration per transaction. Online channels are expanding most quickly for sampling and pilot-scale orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer scientists and cleanroom validation engineers concentrate in German pharmaceutical clusters and Swiss precision manufacturing hubs, anchoring premium barrier film development across the continent.
Germany
Contract manufacturing organizations in Baden-Württemberg and Bavaria pull aluminum foil laminates for sterile injectables production. Verpackungsgesetz extended producer responsibility fees force rapid reformulation of multi-layer inventory into mono-material alternatives. The Rhine-Main precision chemical corridor validates cold-form barrier films for oncology drug serialization.
United States
FDA container closure guidance drives 18-24 month extractables testing cycles for pharmaceutical-grade suppliers. Biologics manufacturing expansion in Massachusetts and North Carolina demands ultra-low oxygen transmission structures. The FDA maintains strict drug master file requirements for barrier bag sterilization compatibility.
India
CDSCO alignment with ICH Q1 stability guidelines creates pull for US-validated barrier films in Hyderabad and Ahmedabad pharmaceutical clusters. Domestic formulation of active pharmaceutical ingredients accelerates demand for aluminum foil laminates. The Telangana life sciences corridor anchors contract manufacturing capacity expansion.
Switzerland
Swissmedic enforces extractables and leachables protocols matching FDA stringency for biologics packaging. Precision chemical and diagnostics manufacturers in Basel-Stadt specify validated barrier structures with sensor integration. The country's pharmaceutical regulator maintains equivalence with EMA container closure standards.
China
Dual carbon goals and MIIT packaging recyclability directives force substitution of non-recyclable multi-material laminates. Electronics assemblers in the Yangtze River Delta specify nylon-reinforced barrier bags for semiconductor protection. NMPA pharmaceutical packaging standards increasingly align with international stability testing protocols.
Barrier Bags Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the barrier bags value chain. Integrated film converters with captive polymer compounding capabilities face specialized converters sourcing barrier resins through merchant channels. Three archetypes dominate: diversified packaging conglomerates with pharmaceutical validation infrastructure, regional specialists in mono-material recyclable structures, and automation-integrated system suppliers. Competitive moves concentrate on backward integration into polymer compounding and strategic partnerships with pharmaceutical contract manufacturers for co-development of sensor-embedded films.
Within the diversified conglomerate tier, Amcor plc and Mondi Group exemplify scale-driven positioning across pharmaceutical and food barrier applications. Sealed Air Corporation anchors the automation-integrated archetype. These three occupy positions spanning cold-form foil laminates, kraft paper-barrier hybrids, and cleanroom-compatible packaging systems respectively.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor plc |
| Mondi Group |
| Berry Global |
| WINPAK LTD. |
| Sonoco Products Company |
| Viscofan Group |
| FLEXOPACK S.A. |
| ProAmpac |
| Others |
Value Chain & Pricing Dynamics
Primary aluminum price volatility on the London Metal Exchange cascades through cold-form laminate production into three distinct procurement tiers, with pharmaceutical-grade foil laminates commanding substantial premiums over commodity polyethylene structures used in frozen food applications.
Pricing Analysis
Bundled film-plus-automation system packages separate from unbundled commodity film supply across German and Dutch contract manufacturing markets. Three-tier pricing structure across premium pharmaceutical-grade, standard food-industrial, and economy agricultural chemical levels stratifies by oxygen transmission rate certification and cleanroom validation documentation. Cost compression in standard-tier polyethylene structures intensifies because German Verpackungsgesetz recyclability fees erode margins on multi-material legacy inventory. Agricultural chemical processors show highest price sensitivity, while oncology drug contract manufacturers demonstrate lowest sensitivity due to serialization compliance requirements.
Supply Chain Analysis
Direct-to-pharmaceutical-CMO channels handle validated barrier film demand, while wholesale distributors aggregate fragmented industrial chemical procurement across mid-tier European processors. Supply concentrates in Germany, Switzerland, and the United States for pharmaceutical-grade foil laminates, with Taiwan and South Korea anchoring nylon-reinforced electronics protection films. Raw material flows draw from primary aluminum smelters, ethylene vinyl alcohol copolymer resin producers, and metallized film coating operations. Single-source vulnerability in pharmaceutical-grade adhesive supply creates qualification bottlenecks for new material introductions. Distribution runs through converter-direct relationships for validated applications and packaging distributors for standardized SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier shift toward sensor-embedded pharmaceutical films and aluminum oxide ceramic coatings that command validation premiums over commodity metallized alternatives.
For Market Incumbents: Hedge aluminum foil cost exposure through long-term smelter offtake agreements and accelerate mono-material high-barrier R&D to preempt EU Packaging and Packaging Waste Regulation compliance deadlines. Backward integration into polymer compounding secures formulation control against REACH substitution mandates. Capacity consolidation in German pharmaceutical clusters reinforces supplier panel positioning as CMOs narrow approved vendor lists. For New Entrants and Emerging Players: Mid-tier Indian pharmaceutical formulation facilities in Hyderabad and Ahmedabad represent an underserved buyer archetype seeking US-validated barrier films without incumbent converter minimum order requirements. Paper-barrier hybrid formats for Italian and French dry food brands offer white-space entry with lower cleanroom validation capital barriers. Partner with regional automation system integrators to offer bundled film-plus-equipment packages that match German CMO procurement preferences. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized converters possessing drug master file infrastructure and sensor-embedded film co-development capabilities with pharmaceutical contract manufacturers. Five-to-ten year viability hinges on regulatory compliance agility rather than commodity scale. Watch for CDSCO enforcement alignment with ICH stability guidelines as inflection signal for Indian market premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material High-Barrier R&D Investment | REACH and EU Green Deal recyclability mandates force substitution of multi-layer laminates with compliant alternatives. |
| Sensor-Embedded Film Co-Development | Integration with pharmaceutical CMO cleanroom lines creates switching costs and panel consolidation advantages. |
| Indian Pharmaceutical Cluster Expansion | CDSCO alignment with ICH Q1 guidelines pulls validated barrier film demand in Hyderabad and Ahmedabad. |
| Aluminum Oxide Ceramic Coating Scale-Up | Plasma-enhanced chemical vapor deposition simplifies sterilization validation while maintaining sub-0.1 cc/m²/day barriers. |
| Extended Producer Responsibility Compliance | Germany's Verpackungsgesetz fees for non-recyclable packaging force rapid legacy inventory reformulation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical packaging engineers, contract manufacturing procurement leads, polymer compounding technical directors, and cleanroom validation specialists with secondary analysis of FDA drug master file databases, EMA container closure guidance documents, REACH SVHC disclosure registries, and EU customs trade flows for aluminum foil and barrier resin categories. Bottom-up segment sizing and top-down market reconciliation anchored value estimates.
Segment-weighting across material type, closure mechanism, end-use vertical, and distribution channel shaped the analytical framework over the projection horizon. Material chemistry splits between polyethylene, aluminum foil, polypropylene, and nylon-reinforced structures combined with pharmaceutical, food, electronics, and chemical end-use applications to model demand composition. CAGRs derived from regression against pharmaceutical manufacturing capacity expansion, electronics freight volume growth, and regulatory compliance investment cycles.
Underlying measurement precision varies by segment; pharmaceutical packaging carries tighter precision than commodity agricultural chemical applications due to validated supplier concentration and disclosed contract manufacturing capacity data. Forecasts reflect assumptions about EU regulatory enforcement timelines, aluminum smelter capacity discipline, and polymer science breakthrough trajectories in mono-material barrier development. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Nano Sealers Market