
 Middle East and Africa Pouch Packaging Market | 2026-2036
Middle East and Africa Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pouch Packaging Market Insights
High-barrier coextrusion and digital printing integration is reconfiguring how pouch converters serve brand owners across the Middle East and Africa. Hotpack Packaging LLC leverages its UAE manufacturing base to supply foodservice and retail clients throughout the Gulf with extended shelf-life formats. Amcor plc anchors regional demand through its technical service network and pre-qualified pharmaceutical barrier structures. Mondi Group competes on kraft-paper-based flexible solutions that align with retailer sustainability mandates in South African and Kenyan markets.
Pouch packaging denotes a flexible primary container formed from laminated films, typically two to five layers, sealed on three or four sides with optional reclosure features, designed to protect contents from moisture, oxygen, and light while minimizing material weight versus rigid alternatives. Stand-up pouches with integrated spouts or sliders dominate liquid and semi-liquid food applications due to shelf presence and dispensing convenience, while vacuum pouches sustain protein and dairy shelf life in markets with limited cold-chain reach. Composite laminates lead material selection for retort and aseptic applications where aluminum oxide or ethylene vinyl alcohol barriers replace foil to enable microwave compatibility and metal detection.
Saudi Arabia's SFDA enforces food-contact compliance testing that shapes adhesive and ink selection for converters serving the kingdom's retail and foodservice sectors. South Africa's National Regulator for Compulsory Specifications and Egypt's EOS certification requirements for imported packaging materials create tiered market access conditions that favor suppliers with in-house testing laboratories. Stakeholders must monitor evolving extended producer responsibility frameworks in the UAE and Kenya, as these will determine which material recovery streams and design-for-recycling specifications become commercially viable across the region's fragmented waste infrastructure.
Market Dynamics
Converters across the Middle East and Africa are consolidating extrusion and printing capabilities to serve brand owners demanding shorter lead times and migration-compliant laminates. Saudi Arabia's SFDA enforcement and Nigeria's manufacturing corridor concentration are compressing supplier qualification timelines while expanding regional production footprints.
Growth Catalysts
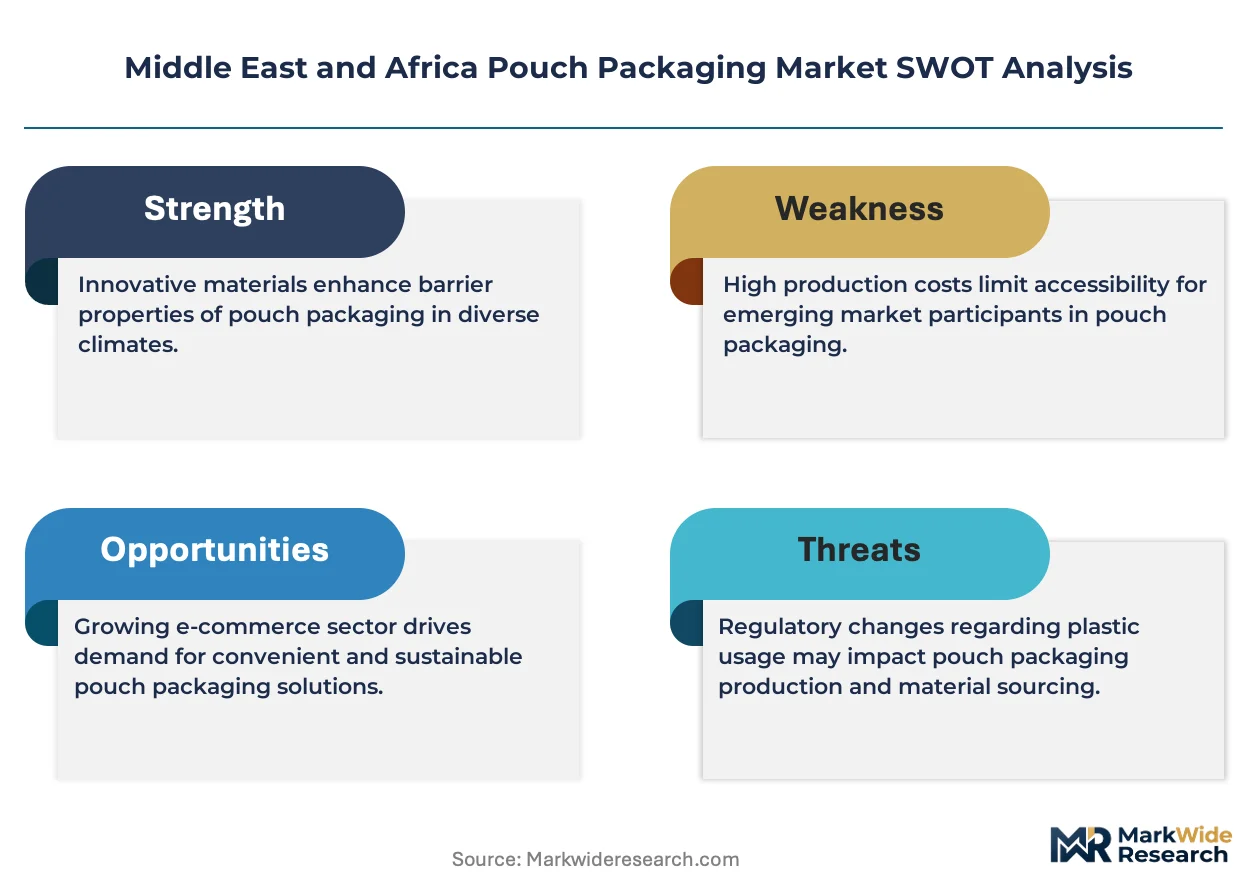
- SFDA Food-Contact Compliance:Saudi Arabia's tightened migration testing rules for adhesives and inks are pushing converters toward pre-qualified multilayer barrier films. This regulatory pressure accelerates technical upgrades among Gulf-based suppliers.
- Lagos-Ibadan Localization:Consumer goods multinationals are establishing captive pouch sourcing within Nigeria's manufacturing corridor to serve West African distribution networks. Regional production reduces import duty exposure and currency volatility.
- Retort Aluminum Oxide Barriers:Microwave-compatible barrier layers are displacing foil in ready-meal applications across UAE and South African retail channels. This material shift enables metal detection compatibility and consumer convenience.
Market Restraints
- Ethylene Vinyl Alcohol Supply Concentration:High-barrier resin availability depends on Asian petrochemical suppliers, exposing converters to freight cost volatility and extended order cycles.
- Extended Producer Responsibility Uncertainty:Evolving EPR frameworks in UAE and Kenya lack harmonized material recovery specifications, complicating long-term capital allocation for recycling-compatible designs.
- Rigid Container Substitution in Premium Segments:Glass and rigid plastics retain shelf presence advantages in Gulf luxury food and cosmetics, limiting pouch penetration in high-margin categories.
Strategic Opportunities
- Kenyan EPR Implementation:Pending extended producer responsibility regulations will create first-mover advantages for converters offering design-for-recycling specifications compatible with East African waste infrastructure.
- Kraft-Paper Flexible Hybrids:Retailer sustainability mandates in South Africa and Kenya are opening demand for fiber-based flexible solutions that balance barrier performance with renewable content claims.
- Cold-Chain-Limited Protein Packaging:Vacuum and modified-atmosphere pouches for dairy and meat applications address shelf-life extension needs in Nigerian and Egyptian markets with intermittent refrigeration coverage.
Industry Challenges
- Migration Testing Capacity Bottlenecks:SFDA and EOS certification requirements exceed available laboratory throughput in the Gulf and North Africa, extending product qualification timelines for new adhesive and ink formulations.
- Multilayer Film Reprocessing Infrastructure:Limited mechanical recycling capabilities for laminated structures force reliance on export markets or energy recovery, complicating circularity claims and EPR compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pouch Packaging Market |
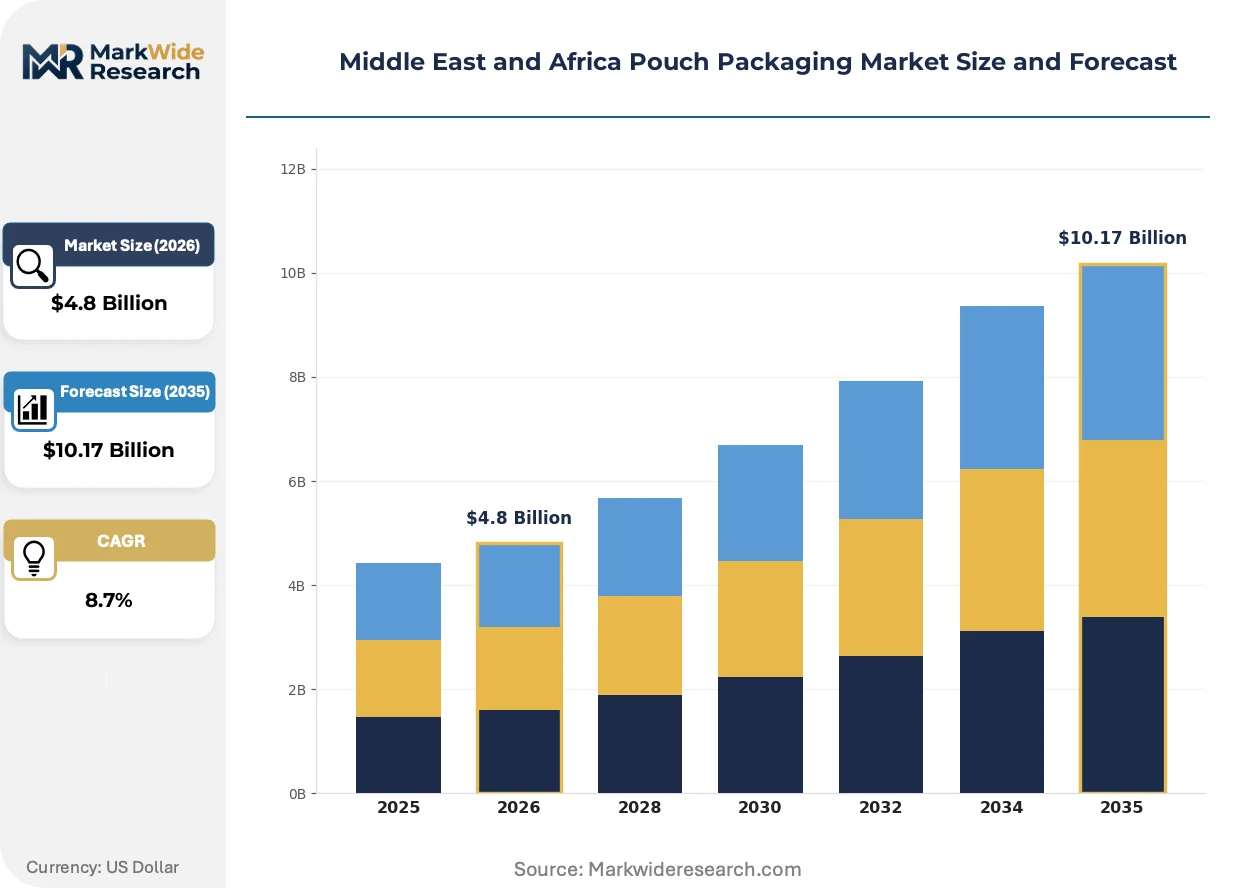
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Vacuum Pouches Material: Plastic, Aluminum, Composite, Paper End Use Industry: Food & Beverages, Healthcare, Personal Care, Household Products Closure Type: Sliding Zipper, Press to Close, Re-closable, Tear Notches |
| Companies Covered | Hotpack Packaging LLC, Gulf East Paper and Plastic Industries LLC, Amcor plc, Mondi Group, Huhtamaki Group, Constantia Flexibles, Napco National, 3P Gulf Group, ENPI Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pouch Packaging Market Trends and Innovations
Digital printing integration and barrier material virtualization are reconfiguring how converters serve fragmented demand across Middle Eastern and African markets. Technical service capabilities and rapid format changeover are becoming decisive competitive differentiators.
Digital inkjet and electrophotographic printing systems are virtualizing pre-press workflows and enabling economical short-run production for private-label and seasonal SKUs. Gulf-based foodservice distributors and Nigerian consumer goods firms are adopting these platforms to compress launch timelines from weeks to days. This capability is virtualizing the traditional minimum-order-quantity constraints that favored centralized, high-volume gravure printing.
Saudi Arabia's SFDA has implemented sequential migration testing protocols for food-contact laminates, requiring documented adhesive and ink compliance before market entry. Converters serving kingdom retail and foodservice channels must maintain in-house analytical capabilities or third-party laboratory partnerships. Pharmaceutical and infant nutrition segments face the most stringent documentation burdens, driving preference for suppliers with pre-qualified barrier structures.
Brand owners in UAE and South Africa are unbundling packaging procurement from finished goods manufacturing, establishing direct relationships with converters for format innovation and sustainability certification. This disintermediation bypasses traditional trading company intermediaries and accelerates technical collaboration on recyclable designs. The shift is most visible in South African retail private-label programs and UAE foodservice contract packaging.
Middle East and Africa Pouch Packaging Market Segmentation
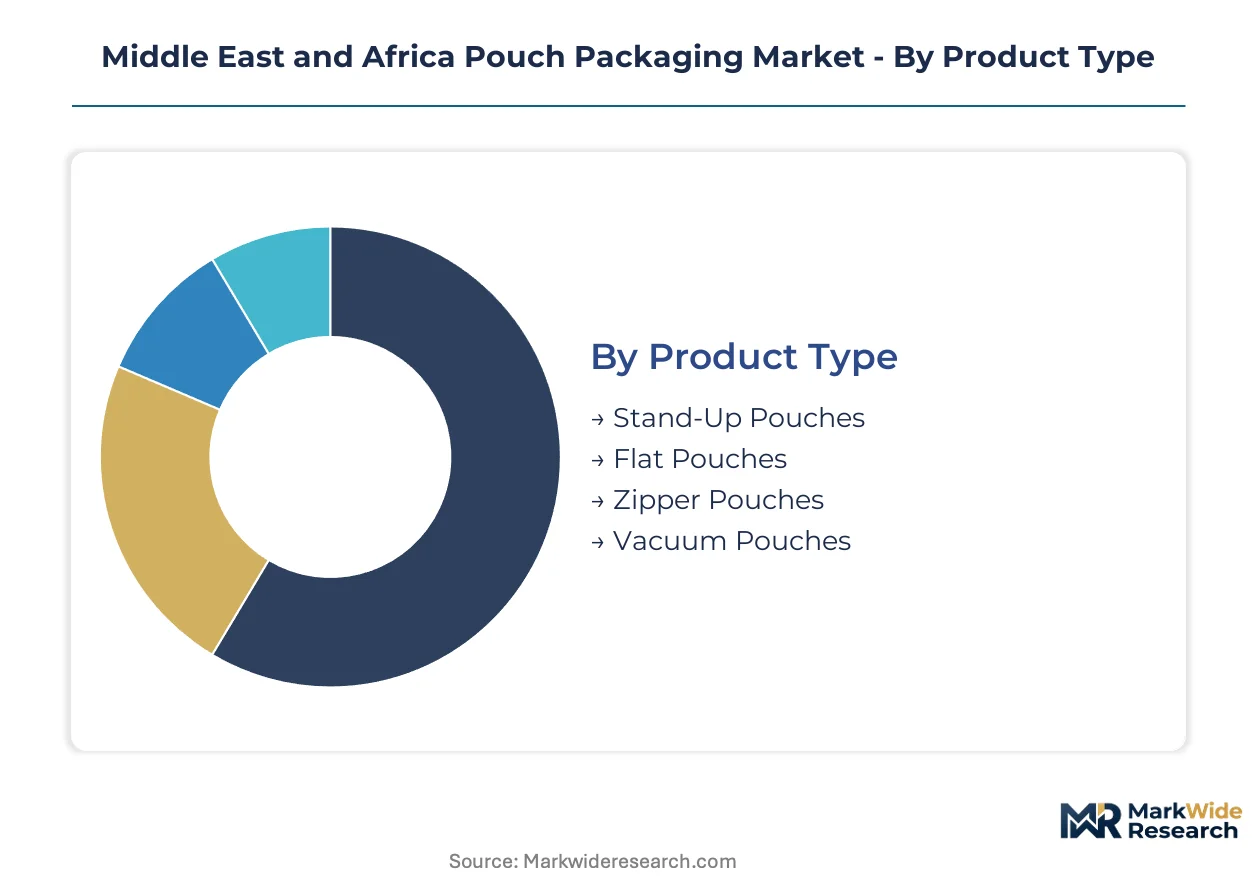
Pouch packaging configurations across the Middle East and Africa reflect divergent supply chain capabilities, regulatory exposure, and shelf-life requirements. Segment selection determines barrier investment, migration testing burden, and recycling pathway eligibility.
Product Type:
Converters align format selection with liquid handling needs, shelf presence requirements, and dispensing convenience across retail and foodservice channels.
- Stand-Up Pouches:Gusseted bottom construction enables vertical shelf display and maximizes retail facings for liquid and semi-liquid contents. Saudi Arabian dairy processors and UAE foodservice distributors specify spouted variants for ambient-stable beverages and cooking sauces.
- Flat Pouches:Three-side-seal geometry minimizes material consumption for dry goods and portion-control applications. Nigerian seasoning and soup base manufacturers in the Lagos-Ibadan corridor favor flat formats for cost-efficient West African distribution.
- Zipper Pouches:Integrated slider or press-to-close systems support multi-use consumption patterns for snack and frozen food categories.
- Vacuum Pouches:High-barrier laminates with oxygen scavenging layers extend protein shelf life in Egyptian and Nigerian markets with limited cold-chain coverage.
Established volume favors flat pouches; emerging adoption favors stand-up configurations with integrated dispensing features.
Material:
Material selection balances barrier performance against SFDA migration compliance and pending extended producer responsibility sorting requirements.
- Plastic:Polyethylene and polypropylene dominate cost-sensitive applications, though multilayer coextrusion complexity rises with SFDA adhesive qualification mandates.
- Aluminum:Foil laminates deliver absolute barrier for retort and pharmaceutical applications but face displacement by aluminum oxide coatings in microwave-compatible formats.
- Composite:Five-to-seven-layer structures combining ethylene vinyl alcohol or aluminum oxide barriers with sealant webs address the most demanding shelf-life specifications. South African retail chains specify composite laminates for private-label ready meals requiring twelve-month ambient stability.
- Paper:Kraft-paper flexible hybrids with polyethylene or biopolymer barriers respond to retailer sustainability mandates in Kenyan and South African markets.
Composite laminates command premium positioning; paper-based alternatives are climbing the fastest on sustainability credential demand.
End Use Industry:
Industry verticals impose distinct qualification timelines, barrier specifications, and volume predictability on converter operations.
- Food & Beverages:Dominant demand concentration spanning ambient dairy, cooking sauces, snacks, and ready meals across Gulf and West African markets. SFDA food-contact compliance and retort compatibility requirements drive technical investment.
- Healthcare:Pharmaceutical and medical device pouches require pre-qualified barrier structures with documented sterility assurance and child-resistance where applicable. Amcor's regional technical service network targets this segment for margin protection.
- Personal Care:Single-use sachets and multi-use pouches for cosmetics and hygiene products concentrate in UAE contract packaging operations serving Gulf retail chains.
- Household Products:Refill pouches for detergents and cleaning chemicals gain traction in South African retail channels as concentrate formats reduce plastic intensity versus rigid bottles.
Food and beverage anchors converter capacity utilization; healthcare offers the steepest expansion trajectory on regulatory barrier to entry.
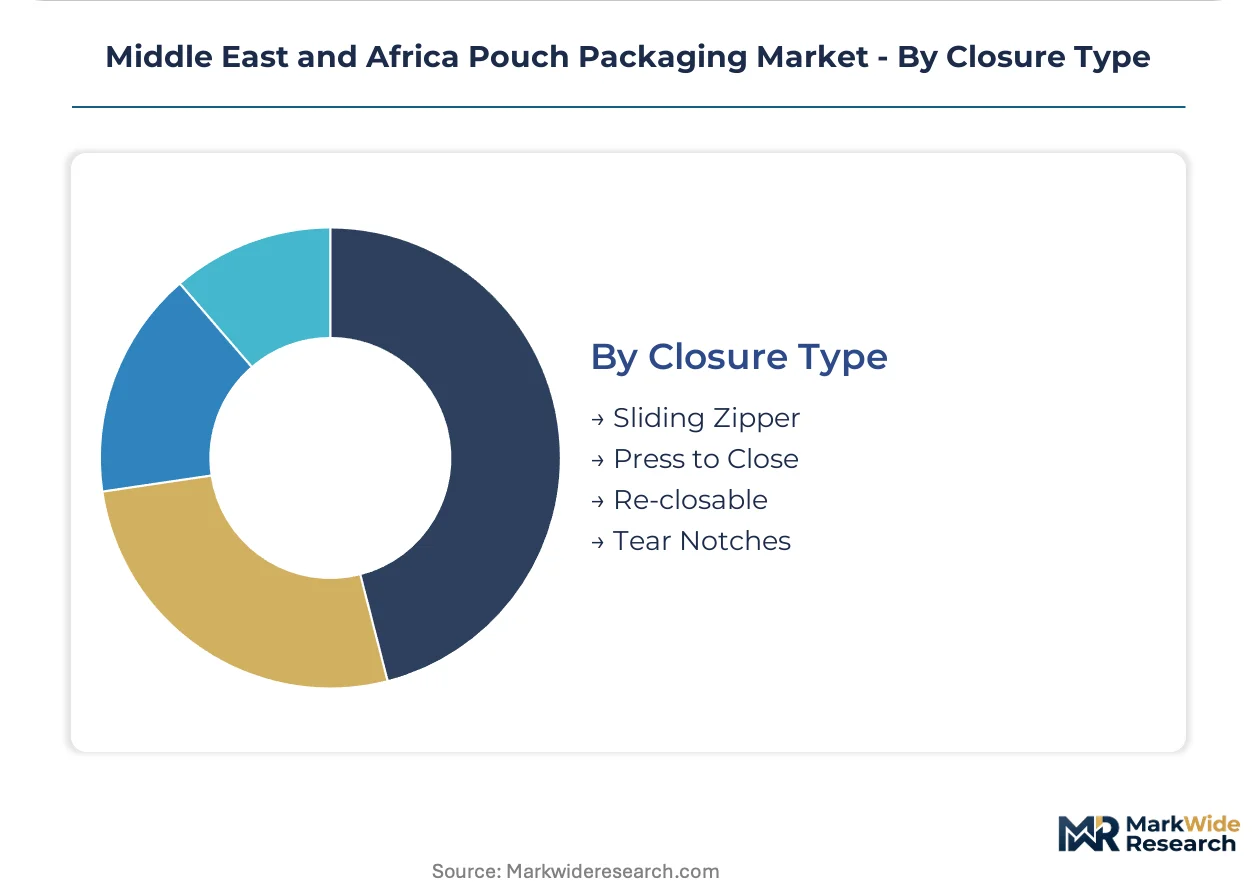
Closure Type:
Reclosure mechanism selection influences consumer convenience, line speed, and per-unit cost position across format categories.
- Sliding Zipper:Integral slider systems enable one-handed operation for large-format pet food and bulk ingredient applications. South African retail private-label programs specify sliders for competitive differentiation in premium tiers.
- Press to Close:Interlocking profile closures balance reseal performance with line efficiency for mid-volume snack and frozen food production.
- Re-closable:Hook-and-loop or adhesive strip systems serve single-reclosure needs in portion-control and sampling applications.
- Tear Notches:Simple V-cut or laser-scored openings minimize unit cost for single-use condiment, pharmaceutical, and sample sachets where reclosure provides no consumer value.
Press-to-close mechanisms dominate current volume; sliding zipper adoption is expanding most quickly in premium private-label development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports converted pouch laminates to Gulf foodservice distributors while Nigerian converters supply seasoning and soup base packaging across West African retail networks.
Saudi Arabia
SFDA migration testing mandates for food-contact adhesives and inks are accelerating technical upgrades among Riyadh-based converters. The kingdom's national food safety regulator enforces sequential compliance documentation for multilayer barrier films. Jeddah's industrial zone hosts extrusion and printing operations serving ambient dairy and cooking sauce processors throughout the peninsula.
United Arab Emirates
Dubai's foodservice distribution hubs demand microwave-compatible retort pouches with aluminum oxide barriers replacing traditional foil laminates. MOHAP pharmaceutical packaging regulations shape barrier specifications for medical device and infant nutrition applications. Sharjah's manufacturing corridor concentrates digital printing integration for private-label seasonal SKU production.
Nigeria
Consumer goods multinationals localize pouch sourcing within the Lagos-Ibadan corridor to reduce import duty exposure and currency volatility. The country's national standards body enforces packaging material certification for imported films used in food-contact applications. Lagos-based converters supply flat pouch formats for seasoning and soup base distribution across West African markets with limited cold-chain infrastructure.
South Africa
Retailer sustainability mandates in Johannesburg and Cape Town are opening demand for kraft-paper flexible hybrids with renewable content claims. The National Regulator for Compulsory Specifications governs packaging material safety for domestic and imported products. Durban's port logistics support composite laminate imports for private-label ready meals requiring twelve-month ambient stability.
Egypt
Vacuum pouch demand for protein shelf-life extension concentrates in Cairo and Alexandria markets with intermittent refrigeration coverage. EOS certification requirements for imported packaging materials create tiered market access favoring suppliers with in-house testing laboratories. The Suez Canal Economic Zone attracts barrier film converters serving North African and Levant distribution networks.
Middle East and Africa Pouch Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that consolidates around technical service capabilities and migration compliance infrastructure. Gulf-based converters with SFDA pre-qualified barrier structures capture premium food and pharmaceutical contracts. Three archetypes dominate: multinational barrier film suppliers with regional technical networks, mid-scale converters with digital printing flexibility, and paper-based flexible specialists targeting sustainability mandates. Competitive moves center on backward integration into coextrusion capacity and strategic partnerships for laboratory testing throughput.
Among multinational suppliers with regional anchoring, Amcor plc and Mondi Group exemplify divergent positioning strategies. Amcor occupies a position tied to pre-qualified pharmaceutical barrier structures and technical service density across Gulf markets. Mondi sits within the fiber-based flexible tier, representing kraft-paper hybrid solutions aligned with South African and Kenyan retailer sustainability programs. Hotpack Packaging LLC anchors the Gulf-based converter archetype, exemplifying UAE manufacturing scale serving foodservice and retail channels throughout the peninsula.
| Leading Market Players |
|---|
| Hotpack Packaging LLC |
| Gulf East Paper and Plastic Industries LLC |
| Amcor plc |
| Mondi Group |
| Huhtamaki Group |
| Constantia Flexibles |
| Napco National |
| 3P Gulf Group |
| ENPI Group |
| Others |
Pricing and Supply Chain Analysis
The Suez Canal freight corridor's cost volatility shapes converter economics across the Middle East and Africa, compressing margins for ethylene vinyl alcohol-dependent laminates while enabling Gulf-based suppliers to command premiums on SFDA-compliant barrier films. This logistics chokepoint amplifies price differentiation between migration-tested multilayer structures and standard polyethylene formats.
Pricing Analysis
Aluminum oxide barrier pricing gaps separate current-generation microwave-compatible retort pouches from legacy foil laminates and emerging bio-based alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks SFDA certification status, with pre-qualified pharmaceutical barriers commanding the widest spreads. Cost compression in standard polyethylene tiers intensifies because Asian resin oversupply and currency volatility in Nigerian import markets. Foodservice distributors in the UAE demonstrate the least price sensitivity due to contract stability, while Lagos-Ibadan seasoning manufacturers operate at the highest price elasticity.
Supply Chain Analysis
Tariff exposure between Saudi Arabia and non-GCC sourcing jurisdictions dominates supply chain risk calculus for converters serving kingdom retail channels. Raw material concentration rests on South Korean and Japanese ethylene vinyl alcohol resin suppliers, Chinese adhesive and ink specialists, and UAE-based film extrusion operations. Single-source vulnerability in high-barrier resin streams forces extended order cycles and inventory carrying costs. Distribution runs through Dubai's Jebel Ali hub for Gulf re-export, Lagos-Apapa port complexes for West African inland distribution, and Durban's container terminal for Southern African retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where SFDA compliance infrastructure creates switching costs that entrench pre-qualified suppliers. Network effects concentrate in technical service density and laboratory testing partnerships.
For Market Incumbents: Build certification moats by deepening backward integration into coextrusion capacity at Jeddah and Sharjah manufacturing zones. SFDA sequential migration testing protocols extend qualification timelines for new adhesive formulations, protecting established converters from fast-follower threats. Prioritize laboratory throughput partnerships to clear bottlenecks for pharmaceutical and infant nutrition barrier structures. For New Entrants and Emerging Players: Build out digital printing capabilities in Nigeria's Lagos-Ibadan corridor to capture private-label seasonal SKU demand from consumer goods multinationals. Kenyan extended producer responsibility implementation represents the most penetrable regulatory entry point, with fiber-based flexible hybrids offering renewable content positioning. Target South African retail sustainability mandates through kraft-paper barrier partnerships with Mondi Group's regional technical network. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging parents seeking to divest non-core Middle East and Africa flexible operations. Five-to-ten-year viability hinges on converters with captive coextrusion and in-house migration testing laboratories. Watch for EPR framework finalization in Kenya and the UAE as inflection signals for recycling-compatible design premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coextrusion Capacity | Captive barrier film production at Jeddah industrial zones reduces SFDA qualification exposure for Gulf converters. |
| Digital Printing Platform Deployment | Sharjah-based inkjet integration compresses private-label launch timelines for UAE foodservice distributors. |
| Laboratory Testing Partnership Expansion | Third-party migration testing throughput in Riyadh clears pharmaceutical barrier qualification backlogs. |
| Kraft-Paper Flexible Hybrid Development | South African retailer sustainability mandates drive renewable content claims in Johannesburg and Cape Town channels. |
| EPR-Compatible Design Certification | Kenyan extended producer responsibility preparation creates first-mover positioning in East African waste infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with converter operations managers, brand owner packaging procurement leads, and SFDA regulatory affairs specialists; and secondary validation through Saudi Food and Drug Authority filings, Egyptian Organization for Standardization certification records, and UAE customs trade data. Bottom-up triangulation against converter capacity utilization and top-down cross-checks against regional retail packaging consumption patterns anchored volume estimates.
Forecast inputs considered product type segmentation across stand-up, flat, vacuum, and zipper configurations; material tiers spanning plastic, aluminum, composite, and paper-based alternatives; and end-use industry splits between food and beverage, healthcare, personal care, and household applications. CAGRs were derived from trend extrapolation of converter capital expenditure cycles and brand owner format migration patterns, with ethylene vinyl alcohol supply elasticity and EPR implementation timelines as key industry-specific variables across the projection horizon.
Stress conditions across resin price volatility, SFDA enforcement intensity, and Nigerian currency fluctuation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about barrier technology substitution rates and regional regulatory harmonization trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Paper Pouch Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Egypt Pouch Packaging Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Four Side-Sealed Pouches Market
Pouch
UAE Pouch Packaging Market
Pouch
India Pouch Packaging Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Stand Up Paper Pouches Market
Pouch
Twin Pouch Packaging Market
Pouch
Fin Seal Pouches Market
Pouch
Mexico Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Clear Pouches Market