
 Reclosable Food Packaging Market | 2026-2036
Reclosable Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Reclosable Food Packaging Market Analysis
Packaging engineering talent scarcity is reorganizing competitive dynamics across the reclosable food packaging value chain. Amcor plc leverages its global manufacturing footprint to sustain multi-region supply contracts for zipper-based flexible formats. Mondi Group anchors European demand through integrated kraft paper and barrier film operations. Berry Global differentiates via specialization in high-throughput snap-closure systems for frozen food applications.
Reclosable food packaging comprises flexible or semi-rigid containers incorporating integrated closure mechanisms—zipper profiles, adhesive strips, or interlocking snaps—typically constructed from multi-layer polyethylene, polypropylene, or paper-based laminates with moisture and oxygen barrier properties, designed to enable repeated opening and resealing while preserving product freshness and reducing spoilage. The plastic material segment dominates current volume due to cost efficiency and seal reliability, though biodegradable alternatives are gaining structural momentum as brand owners face mounting Extended Producer Responsibility obligations. Within closure mechanisms, zipper systems occupy the premium tier with higher per-unit margins, while adhesive formats compete aggressively in dry goods where reseal frequency remains moderate.
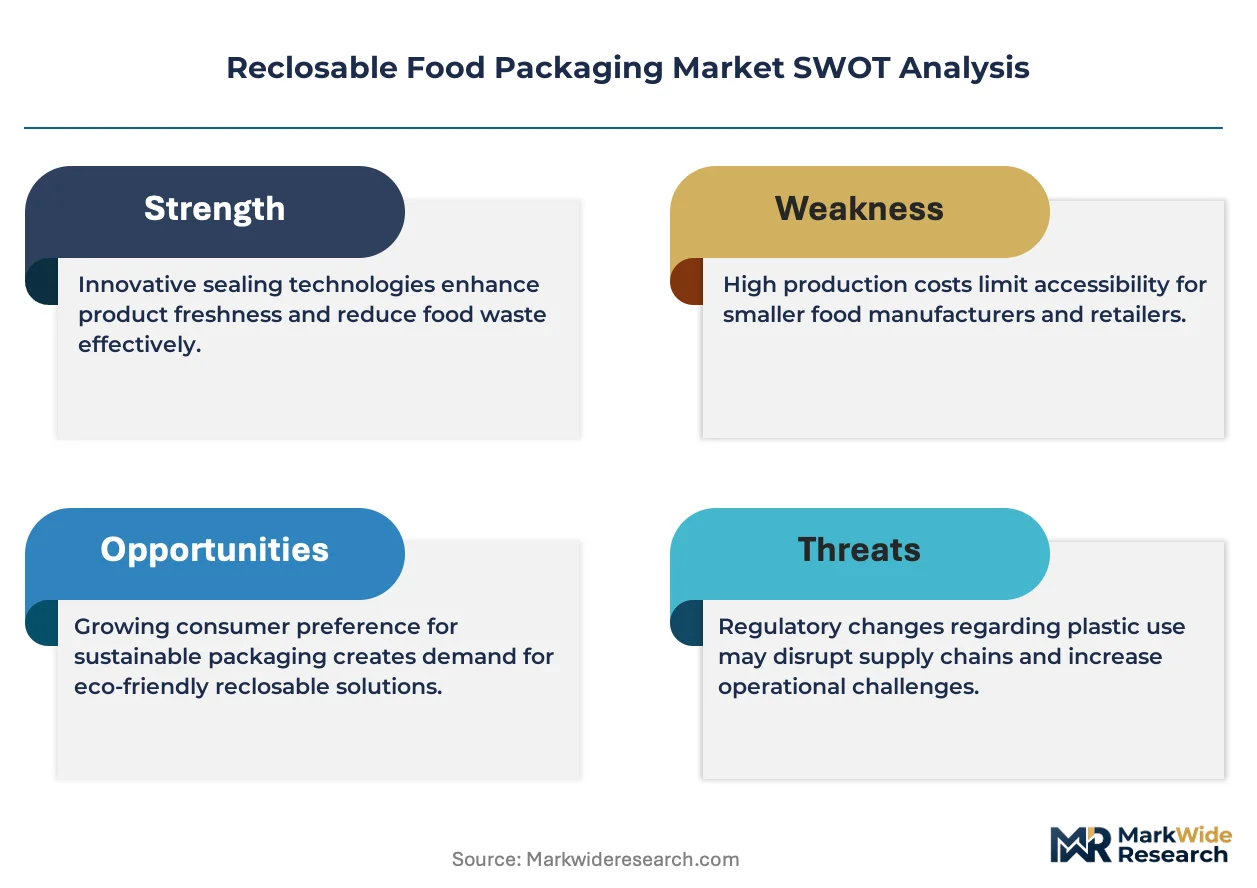
The US FDA maintains stringent migration limits for substances in food-contact plastics under 21 CFR, while the EU REACH framework restricts certain phthalates and heavy metals in packaging substrates, collectively elevating compliance costs but also screening out low-specification imports. EPA guidelines on recycled content thresholds are pressuring converters to validate post-consumer feedstock streams without compromising seal integrity. Stakeholders must monitor evolving state-level packaging EPR legislation and assess whether current material certifications will satisfy forthcoming biodegradability benchmarks.
Market Dynamics
Europe's F-Gas Regulation and single-use packaging directives are forcing substrate transitions across the reclosable food packaging value chain, compelling converters to validate alternative barrier materials without compromising seal integrity.
Growth Catalysts
- Extended Producer Responsibility mandates:EU packaging directives are accelerating demand for recyclable zipper systems as brand owners face compliance deadlines.
- Processed food sector consolidation:Large-format retailers in Germany are specifying premium reclosable formats for private-label expansion.
- Biodegradable polymer advances:PLA and PHA barrier coatings are achieving oxygen transmission rates suitable for dry goods applications.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin prices fluctuate with naphtha cracking margins, compressing converter margins on long-term contracts.
- Masterbatch supply concentration:Colorant and additive production clusters in Northeast Asia create geographic vulnerability for European converters.
- Migration testing bottlenecks:FDA 21 CFR compliance timelines for novel substrates extend commercialization cycles by 18-24 months.
Strategic Opportunities
- India organized retail expansion:Reliance Retail and D-Mart are adopting reclosable formats for private-label snacks and spices.
- Smart packaging convergence:RFID-enabled zipper tracks are integrating freshness indicators with inventory management systems.
- Direct-to-consumer channel growth:Subscription meal kit services are specifying custom reclosable pouches for ingredient portioning.
Industry Challenges
- Multilayer film recycling complexity:Current mechanical sorting infrastructure cannot separate PE/PP/EVOH laminates, limiting circularity claims.
- Barrier coating talent scarcity:Formulation chemists with vapor-deposited metal oxide expertise command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reclosable Food Packaging Market |
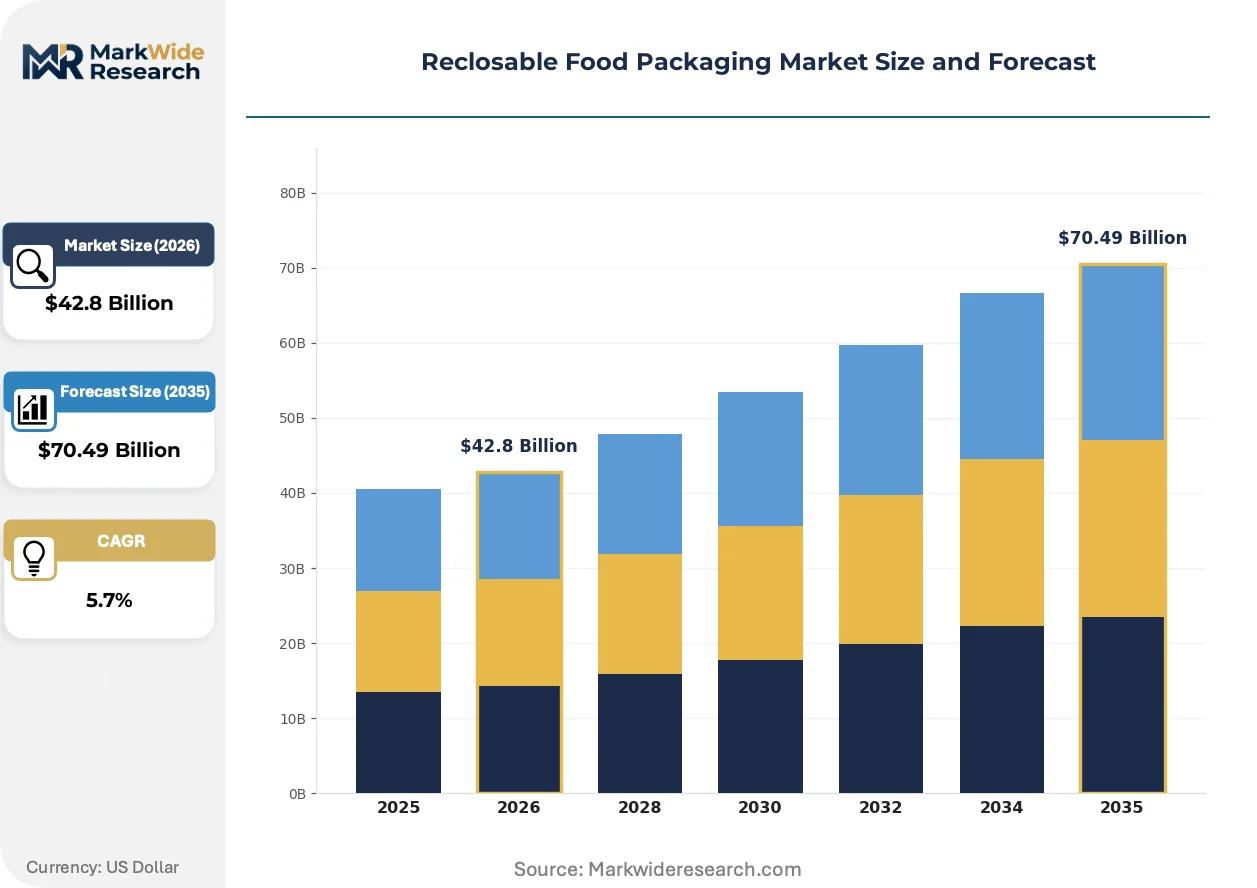
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Aluminum, Biodegradable Closure Mechanism: Zipper, Snap, Velcro, Adhesive End User: Food Service, Retail, Processed Foods, Snacks Application: Frozen Foods, Fresh Produce, Dry Goods, Beverages |
| Companies Covered | Sealed Air Corporation, Mondi Group, Amcor plc, Berry Global, Huhtamaki, Sonoco Products Company, Toray Plastics (America), Inc., Pacific Bag, Inc., Ampac Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reclosable Food Packaging Market Emerging Trajectories
Material science advances and regulatory pressure are converging to reshape closure mechanism design and substrate selection across fresh and frozen food applications.
Paper-based barrier laminates with water-based coatings are displacing conventional multilayer plastic pouches in dry goods segments. Snack food manufacturers in the Netherlands and Denmark are piloting these formats for premium nut and granola lines. The shift is displacing fossil-based flexible packaging volumes in categories where moisture sensitivity remains moderate.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from microwaveable reclosable formats. Converters must reformulate oleophobic barriers using silicone or bio-wax alternatives. Frozen food applications in France and Belgium face the most immediate compliance pressure, with reformulation deadlines accelerating qualification programs.
Retail buyers are consolidating supplier panels around converters with validated post-consumer recycled content streams. German and Austrian supermarket chains now specify minimum PCR thresholds in tender documents. This procurement compression favors larger flexible packaging groups with integrated recycling partnerships over mid-tier competitors lacking certified feedstock access.
Reclosable Food Packaging Market Segmentation
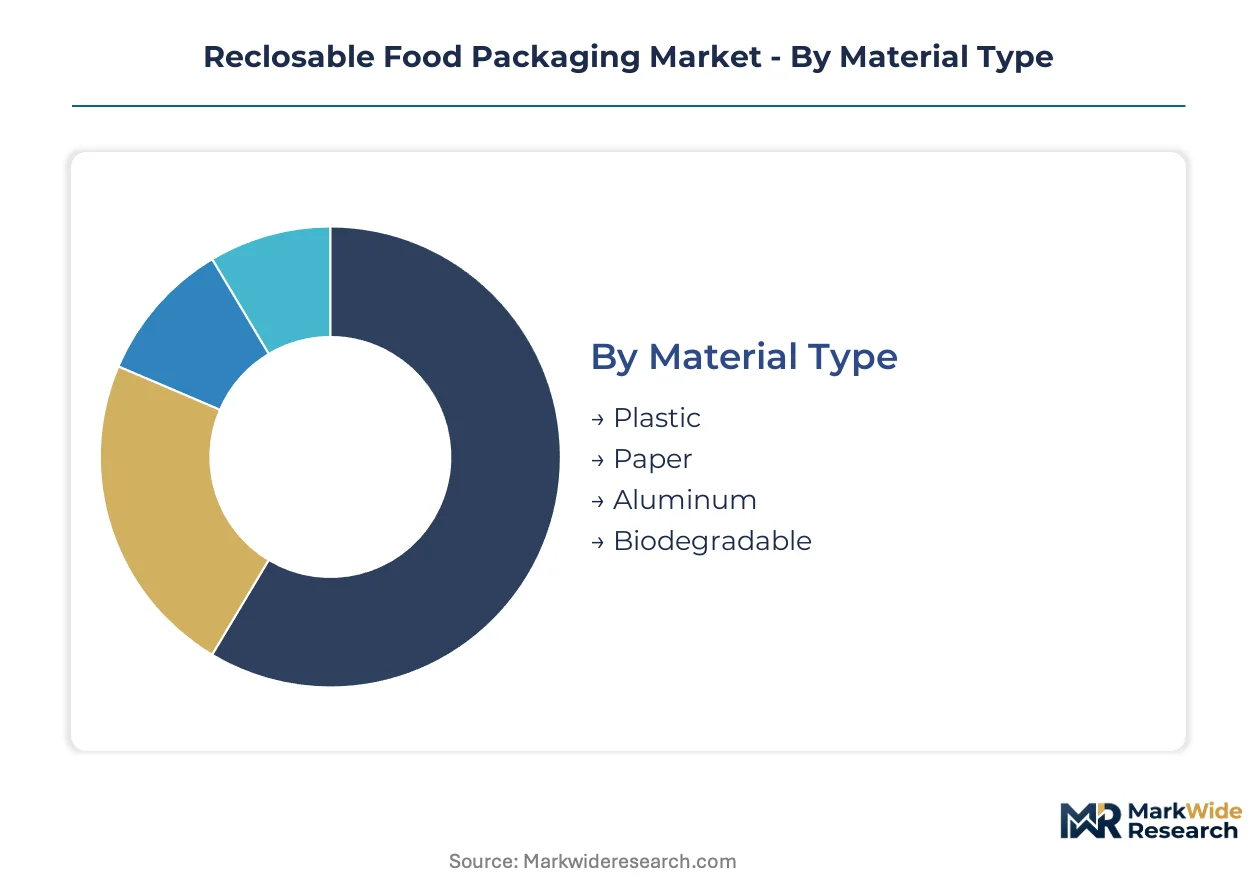
Segmentation in reclosable food packaging reveals how material selection and closure design channel into distinct price-performance tiers. Each category carries unique regulatory exposure and supply chain requirements that shape procurement decisions across food manufacturers and retail buyers.
Material Type:
Channel mix varies sharply by substrate cost and barrier performance, with premium formats flowing through branded retail and commodity grades dominating food service bulk purchasing.
- Plastic:Multi-layer polyethylene and polypropylene laminates deliver moisture and oxygen barriers at scale. Demand concentrates in frozen food applications across Germany and the United States, where FDA 21 CFR compliance and EU REACH substance restrictions elevate specification requirements for extended shelf-life formats.
- Paper:Kraft-based barrier laminates with water-based coatings displace plastic in dry goods segments. Netherlands and Denmark snack manufacturers pilot these formats for premium nut and granola lines, driven by EPR mandates and supermarket PCR content thresholds.
- Aluminum:Metallized films provide superior light and oxygen protection for coffee and nutritional powders.
- Biodegradable:PLA and PHA barrier coatings target compostable claims in fresh produce packaging.
Plastic dominates installed base. Biodegradable formats are where expansion concentrates.
Closure Mechanism:
Cost tier stratification separates premium reseal performance from economy dry-goods solutions, with zipper systems commanding three-to-four times the per-unit margin of adhesive alternatives.
- Zipper:Interlocking polymer profiles enable hundreds of open-close cycles without seal degradation. German private-label expansion and US meal-kit subscription growth drive specification upgrades, as retailers prioritize portion control and freshness signaling.
- Adhesive:Pressure-sensitive strips compete aggressively in moderate-reseal categories. Dry goods applications in India organized retail adopt these formats for spice and snack portioning, balancing cost against reseal frequency needs.
- Snap:Rigid interlocking closures suit frozen food rigid trays.
- Velcro:Hook-and-loop systems serve specialty reusable formats.
Zipper systems anchor premium tier revenue. Adhesive formats capture volume in price-sensitive channels.
End User:
Application maturity separates established processed food demand from emerging direct-to-consumer channels reshaping format specifications.
- Processed Foods:Large-format manufacturers specify multi-layer zipper pouches for ready-meal and cheese applications. German retail consolidation accelerates tender requirements around PCR content and recyclability validation.
- Snacks:Nut, granola, and confectionery brands pilot paper-based barriers in Netherlands and Denmark. EPR compliance deadlines and F-Gas Regulation substrate transitions force material qualification programs.
- Food Service:Bulk purchasing favors cost-optimized adhesive closures.
- Retail:Private-label expansion drives specification convergence.
Processed foods represents the fastest-growing trajectory. Retail channel consolidation is reshaping supplier qualification.
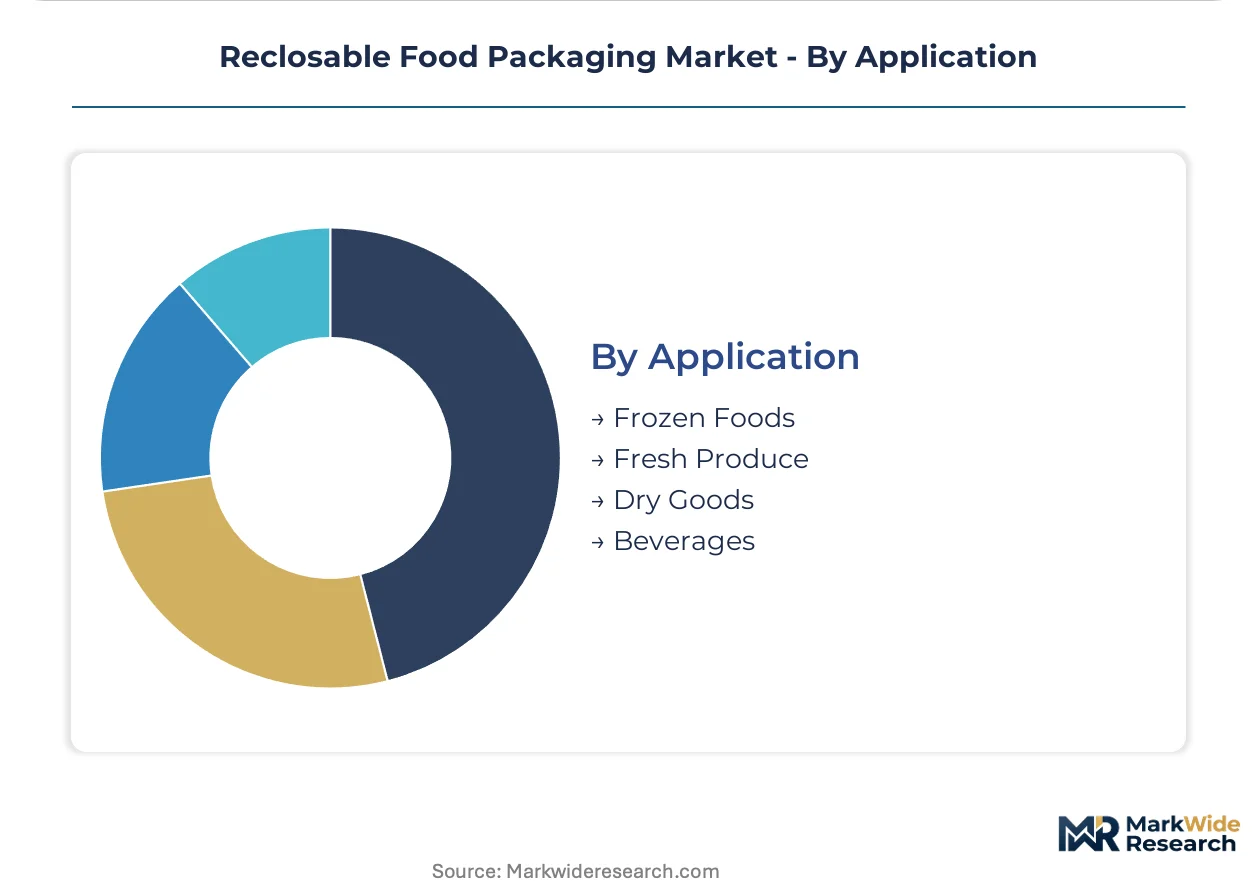
Application:
Volume concentration in frozen foods contrasts with emerging growth in fresh produce, where breathable barrier requirements create formulation complexity.
- Frozen Foods:High-throughput snap and zipper systems preserve texture through freeze-thaw cycles. France and Belgium face immediate REACH reformulation pressure on grease-resistant coatings, accelerating silicone and bio-wax alternative development.
- Dry Goods:Moderate barrier requirements enable paper laminate substitution. Netherlands snack manufacturers lead displacement of fossil-based flexible packaging in nut and granola categories.
- Fresh Produce:Modified atmosphere packaging demands breathable film engineering.
- Beverages:Spout-equipped reclosable formats serve concentrate and smoothie segments.
Frozen foods dominates contract manufacturing capacity. Fresh produce is climbing the fastest on breathable barrier innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
F-Gas Regulation enforcement across the European Union is accelerating substrate transitions toward recyclable and biodegradable alternatives, while processed food sector consolidation in Germany and private-label expansion in North America and Asia-Pacific reshape procurement specifications.
Germany
Food retail consolidation and private-label expansion drive specification upgrades for zipper-based flexible formats across the supply chain. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds, compelling converters to validate post-consumer feedstock streams. The Rhine-Ruhr industrial corridor hosts integrated flexible packaging operations serving pan-European distribution networks.
United States
FDA 21 CFR compliance requirements for food-contact plastics elevate barriers to entry for imported substrates. The EPA's recycled content guidelines pressure converters to certify post-consumer polyethylene streams without compromising seal integrity. Chicago and Milwaukee serve as contract manufacturing hubs for frozen food reclosable formats supplying national retail chains.
Netherlands
Snack food manufacturers pilot paper-based barrier laminates with water-based coatings for premium nut and granola lines. Extended Producer Responsibility mandates under the EU Green Deal accelerate displacement of fossil-based flexible packaging. The Randstad cluster concentrates pilot production facilities for recyclable dry goods formats.
India
Organized retail expansion by Reliance Retail and D-Mart drives adoption of reclosable formats for private-label spices and snacks. FSSAI food safety standards for packaging materials create compliance frameworks for imported barrier technologies. Maharashtra and Gujarat host emerging converter capacity serving domestic FMCG brand owners.
France
REACH restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant coatings from microwaveable reclosable formats. Frozen food applications in northern France face immediate reformulation deadlines for silicone and bio-wax barrier alternatives. The Hauts-de-France region concentrates frozen food manufacturing driving closure system demand.
Reclosable Food Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with global manufacturing footprints separating multi-region contract holders from regional converters. The market structure consolidates around converters with validated recycling partnerships and integrated substrate operations. Three archetypes dominate: integrated multinational groups with captive resin and film capacity, regional specialists in high-throughput closure systems, and emerging biodegradable substrate developers. Competitive moves concentrate on M&A to secure post-consumer recycled content streams and strategic partnerships with retail private-label programs.
Among the integrated multinational tier, Amcor plc and Mondi Group exemplify global manufacturing footprint strategies, with the former sustaining multi-region supply contracts and the latter anchoring European demand through integrated kraft paper and barrier film operations. Berry Global occupies a position within the high-throughput specialization archetype, differentiated via snap-closure system expertise for frozen food applications. These three companies represent distinct competitive positioning vectors: global scale integration, regional substrate integration, and application-specific throughput optimization.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Mondi Group |
| Amcor plc |
| Berry Global |
| Huhtamaki |
| Sonoco Products Company |
| Toray Plastics (America), Inc. |
| Pacific Bag, Inc. |
| Ampac Holdings |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German retailers and flexible packaging converters lock in polyethylene resin access while anchoring price visibility across volatile naphtha cracking cycles. These arrangements concentrate procurement power among integrated multinationals with validated post-consumer recycled content streams, squeezing mid-tier competitors on both input cost and compliance certification.
Pricing Analysis
Zipper-based formats command 3-4x per-unit margins over adhesive alternatives, with German private-label specifications driving premium tier expansion. Price differentiation rests on barrier performance certification and PCR content validation under EU Packaging and Packaging Waste Regulation mandates. Cost compression in commodity adhesive segments is intensifying as Indian organized retail scales private-label spice and snack packaging. Food service bulk buyers exhibit highest price sensitivity; subscription meal-kit channels show lowest sensitivity due to freshness signaling requirements.
Supply Chain Analysis
Inventory cycles for multilayer film laminates stretch 8-12 weeks as masterbatch additive production clusters in Northeast Asia, creating geographic vulnerability for European converters. Resin supply concentrates in Germany, the United States, and Saudi Arabia, with ethylene feedstock drawing from naphtha cracking and shale gas derivatives. Single-source vulnerability runs through specialty barrier coating chemists with vapor-deposited metal oxide expertise. Distribution runs through integrated converter-retailer partnerships rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reclosable food packaging market functions as a regulatory entrenchment story where EU Extended Producer Responsibility deadlines and F-Gas Regulation compliance create switching costs that cement incumbent positions. Network effects concentrate among converters with validated recycling partnerships and pan-European distribution footprints.
For Market Incumbents: Shield market position by securing exclusive PCR feedstock partnerships with German and Austrian supermarket chains before tender consolidation completes. Accelerate silicone and bio-wax barrier coating R&D to capture frozen food reformulation demand under REACH per- and polyfluoroalkyl substance restrictions. Capacity addition in the Rhine-Ruhr corridor anchors pan-European supply contracts against emerging Indian converter competition. For New Entrants and Emerging Players: Lead with biodegradable substrate specialization targeting Netherlands and Denmark snack manufacturers piloting paper-based barrier laminates. The fresh produce segment offers lowest competitive density due to breathable barrier formulation complexity. A direct-to-consumer channel partnership with subscription meal-kit services bypasses entrenched retail supplier panels and builds specification credibility. For Investors and Strategic Acquirers: Regional specialists with integrated kraft paper and barrier film operations represent the most defensible acquisition profile against resin price volatility and regulatory compliance cost escalation. Long-term viability hinges on circular economy infrastructure access rather than commodity scale. Watch for FSSAI packaging safety standard tightening in India as the signal indicating when domestic converter consolidation will accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| PCR Content Certification Program | Validates post-consumer feedstock streams for EU Packaging and Packaging Waste Regulation compliance. |
| Silicone Barrier Coating Scale-Up | Captures frozen food reformulation demand under REACH per- and polyfluoroalkyl substance restrictions. |
| Indian Converter Joint Venture | Secures position in Reliance Retail and D-Mart private-label expansion for spices and snacks. |
| RFID-Enabled Zipper Integration | Links freshness indicators with inventory management systems for smart packaging convergence. |
| Paper Laminate Pilot Production | Displaces fossil-based flexible packaging in Netherlands and Denmark premium dry goods segments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association reports covering packaging substrate flows. Interviews with flexible packaging plant managers, retail category buyers, barrier film R&D directors, and recycling facility operators informed demand and supply-side assessments. Secondary validation drew from ECHA REACH substance restrictions, EU Packaging and Packaging Waste Regulation drafts, FDA 21 CFR migration limit guidelines, and FSSAI food safety standards. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include material substrate type, closure mechanism tier, end-use application, and geographic regulatory cluster across the projection horizon. CAGRs derived from trend extrapolation of historical volume flows adjusted for regulatory mandate implementation timelines and retail consolidation patterns. Forecast inputs incorporated ethylene feedstock price volatility indices and biodegradable polymer oxygen transmission rate improvement curves.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated Indian organized retail expansion would require recalibration. Forecasts reflect assumptions around EPR deadline adherence and masterbatch supply chain stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Disposable Food Containers Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Food Punnets Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Fast Food Containers Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Self-Heating Food Packaging Market