
 North America Stand-Up Pouch Packaging Market | 2026-2036
North America Stand-Up Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Stand-Up Pouch Packaging Market Insights
Asset-light leasing and toll-manufacturing arrangements for pouch converting equipment is fragmenting competitive boundaries across the value chain. ProAmpac LLC leverages its regional plant network to sustain quick-turn contract manufacturing for mid-size food brands. Amcor PLC anchors North American supply through integrated film extrusion and pre-made pouch operations. Huhtamaki Oyj competes by specializing in fiber-based barrier pouches that target paper-forward sustainability mandates.
Stand-up pouch packaging denotes a flexible format with a gusseted base that enables self-supporting display, typically constructed from laminated films or fiber-based composites with oxygen transmission rates below 0.1 cc per square meter per day. The format serves primary containment and shelf-preservation functions across ambient, chilled, and frozen distribution chains. Spouted pouches capture premium positioning in liquid and semi-liquid applications where controlled dispensing commands higher unit economics. Plastic laminates still dominate volume, though paper and composite substrates are gaining structural share as converters reformulate seal layers to meet performance thresholds.
The U.S. FDA regulates food contact substances under 21 CFR, while the Canadian Food Inspection Agency enforces parallel safety standards for materials contacting edible contents. Both frameworks directly shape resin selection, adhesive chemistry, and migration testing protocols that pouch suppliers must satisfy for market access. Stakeholders should monitor how extended producer responsibility legislation in California and Canada alters cost allocation between converters and brand owners across the forecast horizon.
Market Dynamics
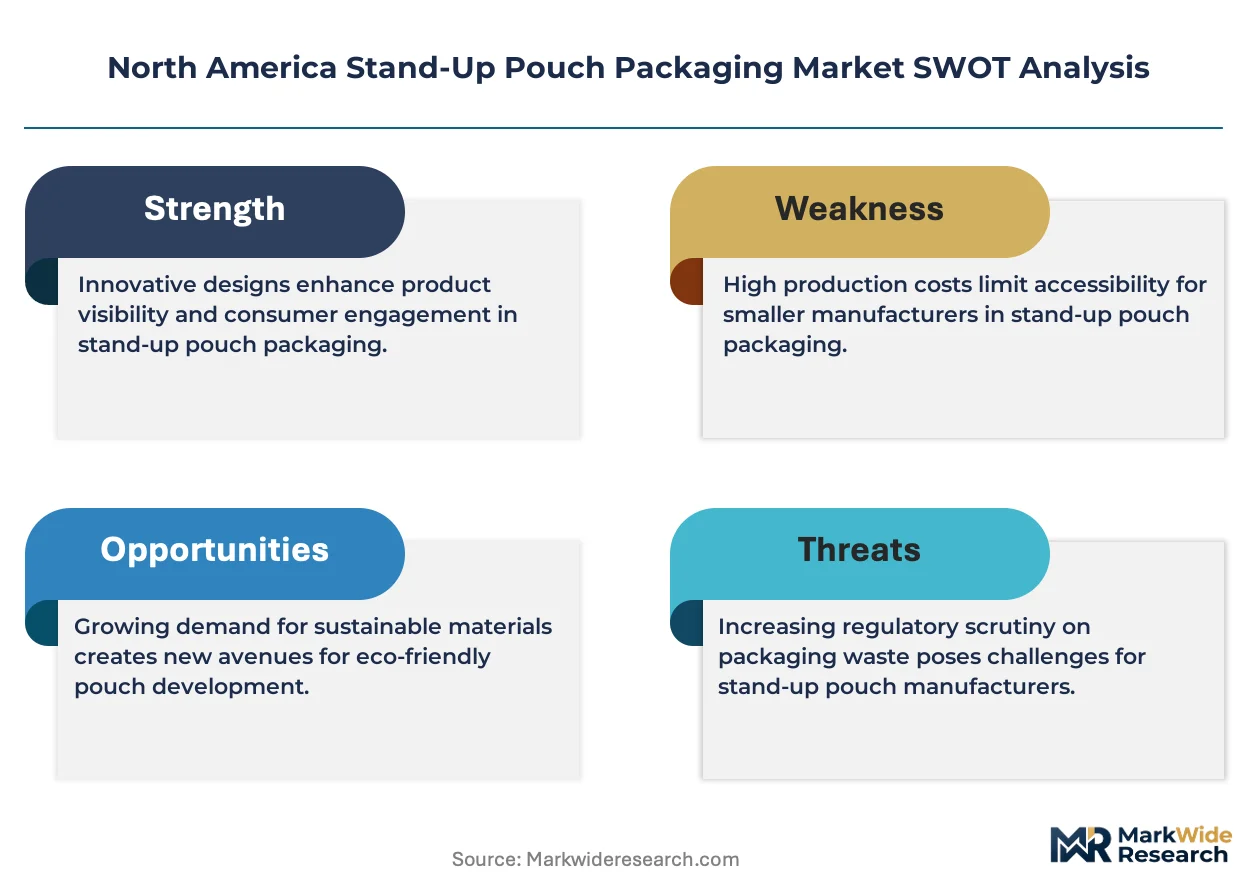
Extended producer responsibility mandates in California and Canada are redistributing end-of-life costs upstream, forcing converters to redesign multilayer structures for mechanical recyclability while maintaining barrier performance thresholds.
Growth Catalysts
- FDA Food Contact Modernization:Updated 21 CFR migration testing protocols are accelerating compliant adhesive and sealant reformulation across the U.S. converter base.
- Midwest Contract Packaging Clusters:Concentrated toll-manufacturing capacity in Illinois and Ohio enables rapid SKU proliferation for regional food brands entering e-commerce channels.
- Spouted Pouch Premiumization:Controlled dispensing formats command unit economics 40-60% above flat pouches in liquid dairy and infant nutrition applications.
Market Restraints
- Resin Supply Concentration:Ethylene-vinyl alcohol copolymer supply depends on a limited number of Gulf Coast petrochemical complexes, exposing converters to force majeure volatility.
- Multilayer Recyclability Barrier:Current mechanical recycling infrastructure cannot process laminated film structures, creating compliance friction with California SB 54 implementation timelines.
- Rigid Container Substitution Resistance:Glass and metal formats retain shelf-preservation advantages in high-acid hot-fill applications above 85°C.
Strategic Opportunities
- Canadian Prairie Expansion:Underpenetrated Saskatchewan and Manitoba markets present white space for shelf-stable protein pouch formats serving remote distribution networks.
- Paper-Forward Barrier Convergence:Fiber-based substrates paired with bio-derived seal layers can capture sustainability premiums in natural foods channels.
- California EPR Tailwinds:CalRecycle's packaging producer responsibility regulations create first-mover advantages for converters with pre-qualified recyclable structures.
Industry Challenges
- Adhesive Formulation Expertise Gap:Migration-compliant laminating adhesives require polymer chemistry specialization scarce among regional contract converters.
- Retort Certification Timelines:Thermal process validation for spouted pouch structures extends commercialization cycles 18-24 months versus conventional formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Stand-Up Pouch Packaging Market |
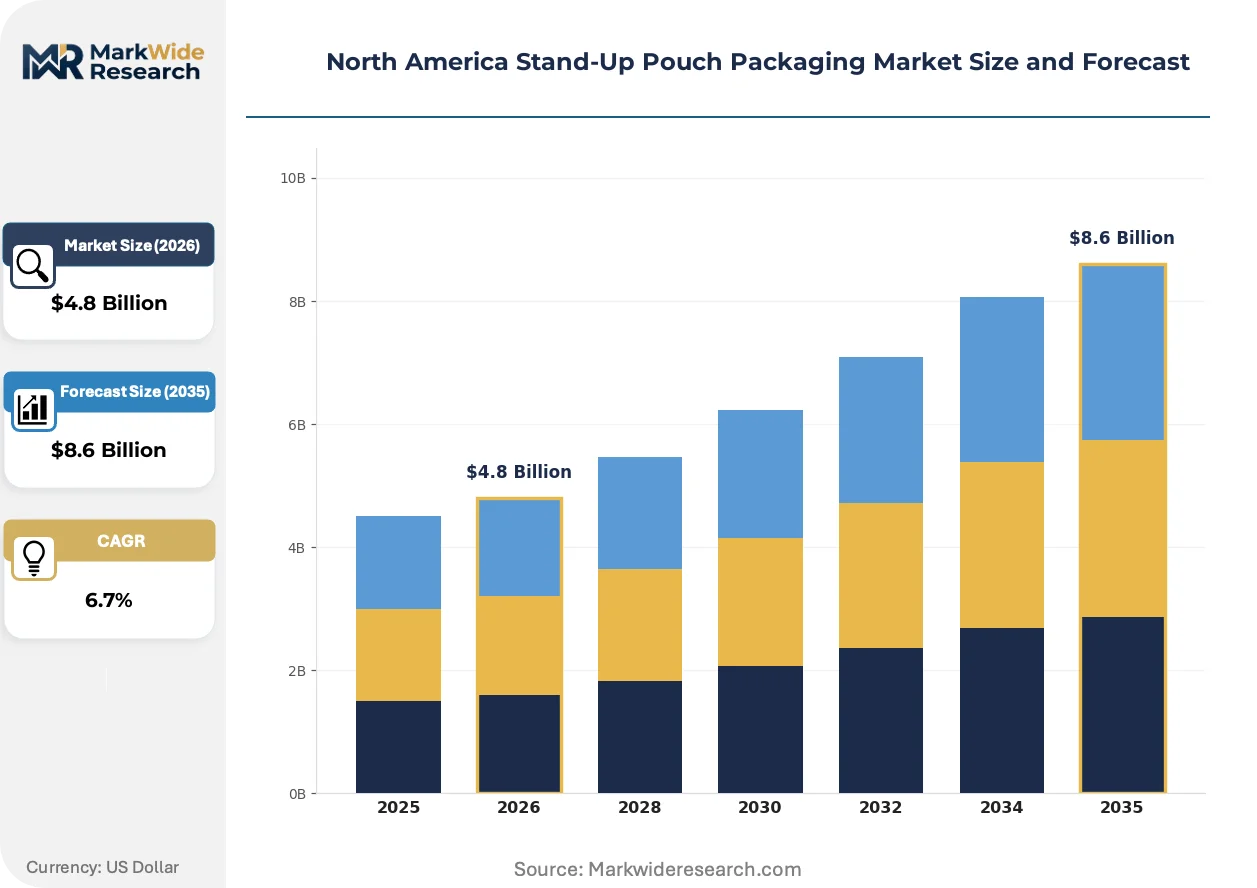
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Pouches, Vacuum Pouches, Spouted Pouches, Zip Lock Pouches Material: Plastic, Paper, Aluminum, Composites End User: Food & Beverages, Personal Care, Pharmaceutical, Household Products Application: Retail, E-commerce, Industrial, Food Service |
| Companies Covered | Smurfit Kappa Group, ProAmpac LLC, Amcor PLC, Huhtamaki Oyj, PPC Flexible Packaging LLC, Sonoco Products Company, Sealed Air Corporation, Clondalkin Group, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Stand-Up Pouch Packaging Market Trends and Innovations
Active barrier technologies and substrate convergence are compressing the performance gap between flexible and rigid packaging, enabling format substitution in preservation-critical applications previously closed to pouches.
Mono-material polyethylene structures with plasma-deposited silicon oxide coatings are hybridizing barrier performance with sort-stream compatibility. Major pet food and frozen produce brands are qualifying these structures for 24-month shelf life targets. The technology is hybridizing competitive boundaries between premium barrier laminates and entry-level recyclable alternatives.
California's SB 54 extended producer responsibility framework mandates 30% source reduction and recyclability thresholds by 2032. The regulation forces converters to eliminate non-recyclable components from multilayer designs or absorb escalating fee schedules. Mid-size food brands in the natural and organic segment are responding fastest, prioritizing pre-qualified recyclable structures in supplier scorecards.
Direct-to-consumer subscription models are compressing order cycle times and fragmenting batch sizes. Contract packagers serving meal-kit and specialty beverage channels are replacing long-run flexographic workflows with digital printing for runs below 10,000 units. This pattern concentrates in the Northeast corridor, where urban fulfillment centers demand 72-hour turnaround on seasonal SKUs.
North America Stand-Up Pouch Packaging Market Segmentation
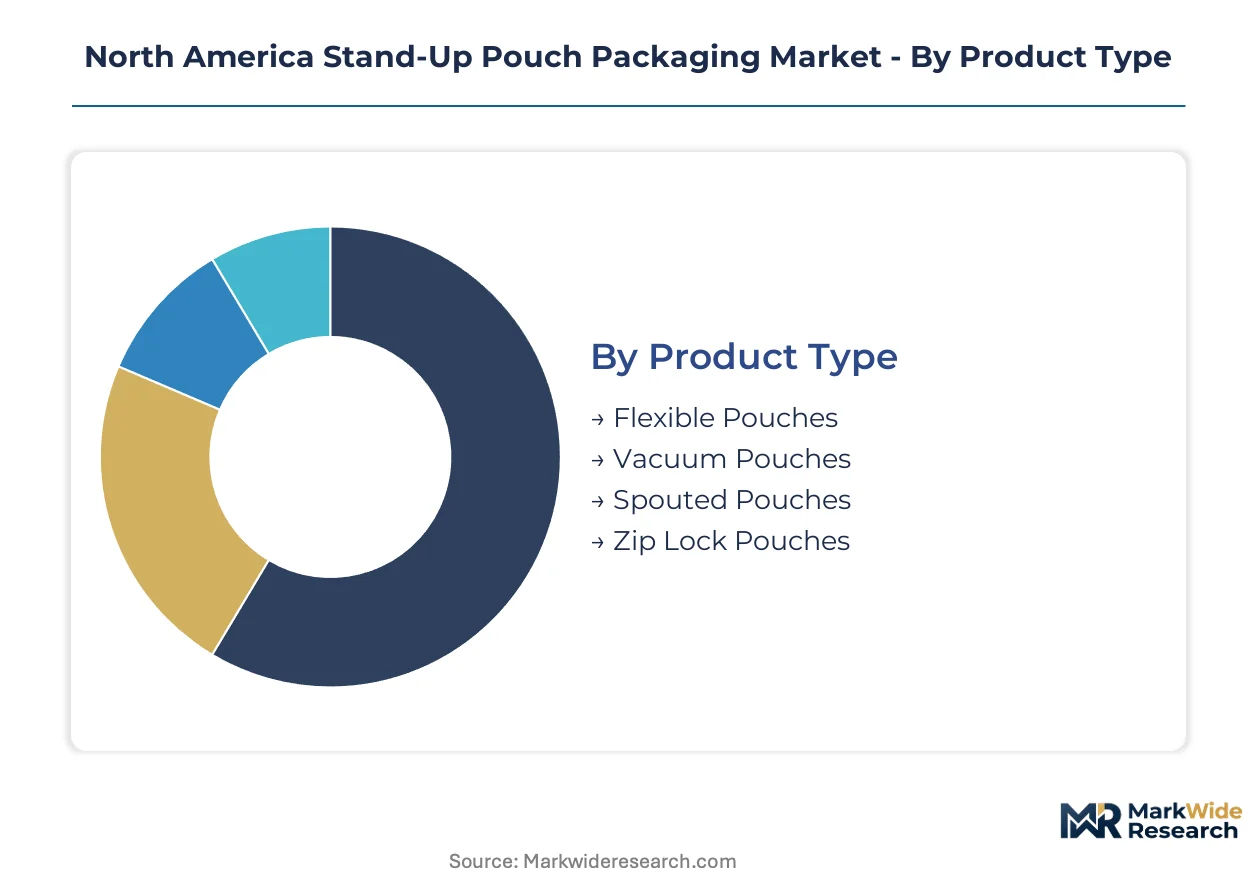
Segmentation in the North American stand-up pouch market reveals how substrate choices, dispensing formats, and channel requirements fragment procurement patterns. Understanding these divides exposes where converters must configure equipment lines and where brand owners face trade-offs between barrier performance and end-of-life compliance.
Product Type:
Mature formats dominate current volume, while emerging configurations capture premium positioning through functional differentiation.
- Flexible Pouches:Unstructured flat or gusseted bags constructed from multilayer laminates serve ambient dry goods and frozen produce. Midwest contract packaging clusters in Illinois and Ohio concentrate demand for quick-turn flexible formats serving regional food brands.
- Spouted Pouches:Integrated fitment structures enable controlled dispensing for liquid dairy, infant nutrition, and ready-to-drink beverages. FDA food contact modernization around 21 CFR migration protocols is accelerating compliant seal layer qualification timelines for spouted formats in the U.S.
- Vacuum Pouches:High-barrier structures with evacuated headspace extend shelf life for processed meats and cheese.
- Zip Lock Pouches:Reclosable interlocking profiles support multi-use consumption patterns in snacks and pet food.
Flexible pouches retain volume leadership; spouted pouches hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity substrates from engineered barrier systems.
- Plastic:Polyethylene and polypropylene laminates with ethylene-vinyl alcohol copolymer barrier layers constitute the baseline substrate. California SB 54 extended producer responsibility mandates are forcing converters to redesign multilayer plastic structures for mechanical recyclability while maintaining oxygen transmission below 0.1 cc per square meter per day.
- Composites:Fiber-plastic hybrid substrates pair paper aesthetics with polymer seal integrity. Canadian Food Inspection Agency safety standards for food contact materials shape adhesive selection and migration testing protocols for composite structures entering the Canadian market.
- Paper:Fiber-based barriers with bio-derived seal layers target natural foods channels.
- Aluminum:Metallized or foil-containing laminates deliver maximum shelf preservation for retort applications.
Plastic laminates retain volume leadership; composites hold the steepest expansion curve.
End User:
Application-specific performance requirements segment procurement by preservation criticality and regulatory exposure.
- Food & Beverages:Primary containment for ambient, chilled, and frozen distribution chains. FDA 21 CFR migration testing protocols directly shape resin selection and adhesive chemistry for U.S. food contact applications.
- Pharmaceutical:Child-resistant and senior-friendly compliance features for over-the-counter and prescription formats. Health Canada regulations enforce parallel safety standards to FDA for materials contacting pharmaceutical contents in the Canadian market.
- Personal Care:Dispensing convenience and shelf aesthetics for cosmetics and toiletries.
- Household Products:Chemical resistance for cleaners and laundry formulations.
Food and beverages retains volume leadership; pharmaceuticals holds the steepest expansion curve.
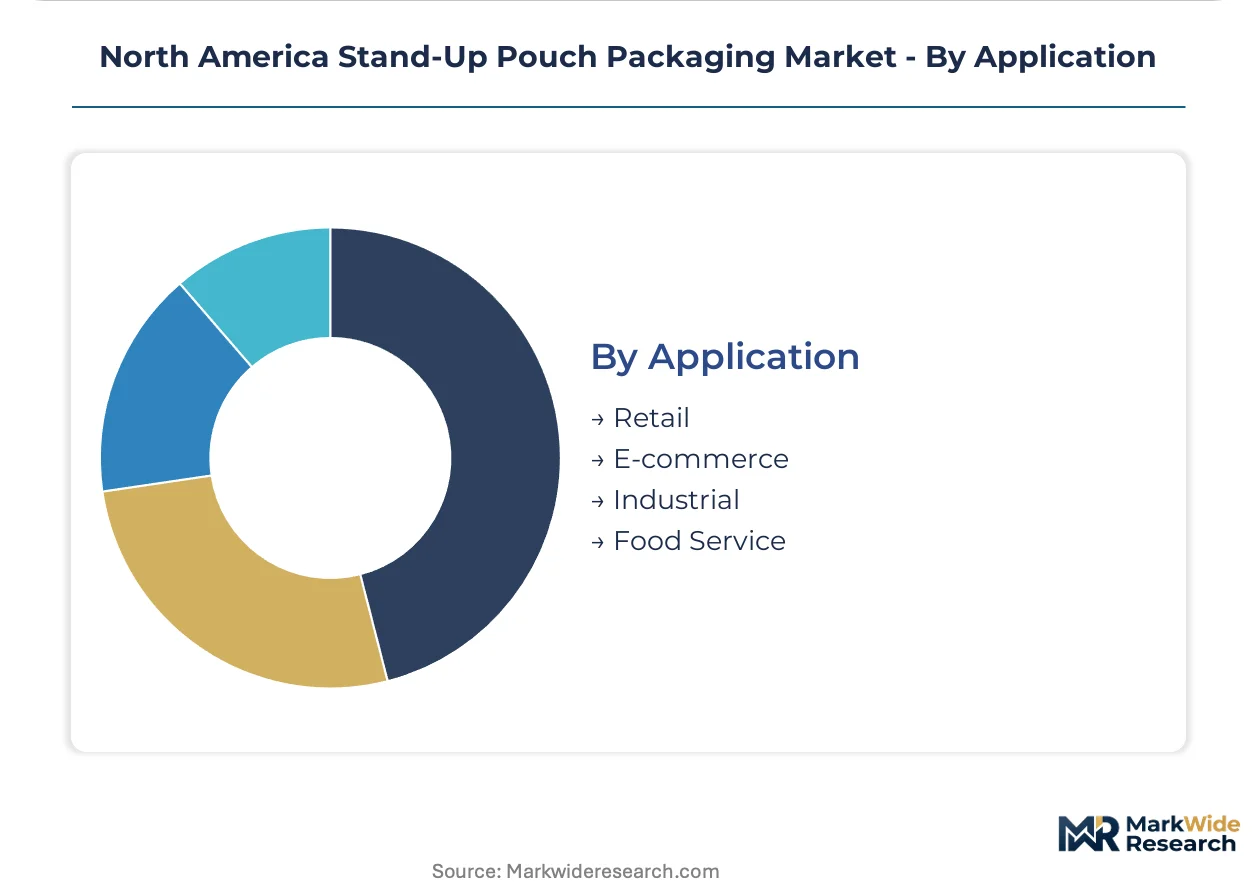
Application:
Channel-specific velocity and batch size requirements fragment converter capabilities.
- Retail:High-volume, long-run production with standardized graphics for mass merchant distribution. CalRecycle packaging producer responsibility regulations in California create first-mover advantages for converters with pre-qualified recyclable structures serving retail brand owners.
- E-commerce:Durable, right-sized formats for parcel shipment and unboxing experience. Direct-to-consumer subscription models in the U.S. Northeast corridor are compressing order cycle times and fragmenting batch sizes below 10,000 units.
- Industrial:Bulk containment and institutional food service formats.
- Food Service:Portion control and back-of-house dispensing for restaurants and catering.
Retail retains volume leadership; e-commerce holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America maintains a modest packaging trade surplus with Asia-Pacific and Europe, though Mexico imports substantial laminated film substrates from U.S. Gulf Coast petrochemical corridors. Cross-border supply chains concentrate converting capacity within 500 kilometers of major population centers to minimize freight costs and customs friction.
United States
Midwest contract packaging clusters in Illinois and Ohio process quick-turn flexible formats for regional food brands entering e-commerce channels. FDA 21 CFR migration testing protocols directly shape adhesive chemistry selection for converters serving national retail distribution. California's SB 54 extended producer responsibility framework mandates recyclability thresholds that force structural redesigns in Los Angeles-area converting facilities.
Canada
Underpenetrated Saskatchewan and Manitoba markets present expansion opportunities for shelf-stable protein pouch formats serving remote distribution networks. Health Canada and the Canadian Food Inspection Agency enforce parallel safety standards to FDA for materials contacting edible contents. Quebec's fiber-based barrier specialists target paper-forward sustainability mandates in natural foods channels.
Mexico
Central Mexican states host toll-manufacturing arrangements for pouch converting equipment serving both domestic consumption and re-export to the United States. Mexico's national standards body aligns food contact material regulations with FDA frameworks to maintain cross-border market access. Nuevo León and Jalisco concentrate flexible packaging demand from beverage and processed food multinationals operating nearshored production.
North America Stand-Up Pouch Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated film extrusion and pre-made pouch operations, with mid-size contract manufacturers occupying specialized niches. Three strategic archetypes dominate: multinational converters with captive resin supply, regional toll-manufacturing specialists, and fiber-based barrier innovators. Dominant competitive moves include asset-light leasing arrangements for converting equipment and backward integration into film extrusion to secure resin access.
Among integrated packaging conglomerates, Amcor PLC and Huhtamaki Oyj occupy positions exemplifying scale-driven barrier film and fiber-based sustainability specialization respectively. ProAmpac LLC represents the regional contract manufacturing archetype, sustaining quick-turn production networks across multiple plant locations. These three entities anchor competitive positioning across distinct capability vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| ProAmpac LLC |
| Amcor PLC |
| Huhtamaki Oyj |
| PPC Flexible Packaging LLC |
| Sonoco Products Company |
| Sealed Air Corporation |
| Clondalkin Group |
| Mondi Group |
| Others |
Pricing and Supply Chain Analysis
Ethylene-vinyl alcohol copolymer supply concentration on the U.S. Gulf Coast determines both pricing tier spreads and supply chain shape, forcing converters to absorb force majeure volatility into contract structures while mid-size brands face squeezed margins on quick-turn orders.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the North American stand-up pouch market. Premium spouted pouches with FDA-compliant seal layers command substantial markups over commodity flat pouches, while price differentiation stems from barrier certification grade and volume scale commitments. Pricing pressure stems from California SB 54 compliance costs as converters absorb redesign expenses for recyclable multilayer structures. Mid-size food brands exhibit highest price sensitivity due to limited negotiating leverage against integrated film extruders.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for laminated film substrates and converting equipment components. Raw material sourcing draws from U.S. Gulf Coast petrochemical complexes for ethylene-vinyl alcohol, Canadian prairie regions for fiber-based substrates, and Mexican toll-manufacturing clusters for equipment assembly. Distribution runs through Midwest contract packaging hubs in Illinois and Ohio before final mile delivery to retail and e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's SB 54 extended producer responsibility framework constitutes a regulatory inflection that will reshape competitive economics, rewarding early movers with pre-qualified recyclable structures while penalizing laggards with escalating fee schedules.
For Market Incumbents: Pre-empt margin erosion by backward integration into film extrusion to secure captive resin access against Gulf Coast supply disruptions. Accelerate mono-material polyethylene qualification with plasma-deposited silicon oxide coatings to defend position against emerging fiber-based barrier specialists capturing sustainability premiums in natural foods channels. For New Entrants and Emerging Players: Build out toll-manufacturing capacity in underpenetrated Saskatchewan and Manitoba markets where shelf-stable protein pouch demand exceeds regional converting supply. Target remote distribution networks with spouted pouch formats for liquid dairy, leveraging digital printing workflows to serve fragmented batch sizes below 10,000 units for direct-to-consumer subscription brands. For Investors and Strategic Acquirers: CalRecycle's packaging producer responsibility regulations reshape the acquisition landscape by privileging converters with pre-qualified recyclable structures and compliant adhesive formulation expertise. Five-to-ten year viability favors regional contract manufacturers with quick-turn capabilities and digital printing infrastructure. The signal to watch is FDA migration testing protocol updates that extend commercialization timelines for spouted pouch structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin supply insulates converters from Gulf Coast petrochemical volatility and force majeure disruptions. |
| Mono-Material Recyclable Structure Qualification | Plasma-deposited silicon oxide coatings enable California SB 54 compliance while maintaining oxygen barrier performance thresholds. |
| Digital Printing Capability Expansion | Short-run production serves e-commerce subscription models with 72-hour turnaround requirements in the Northeast corridor. |
| Spouted Pouch Retort Certification Investment | Thermal process validation extends commercialization cycles but unlocks 40-60% unit economics premiums in infant nutrition. |
| Canadian Prairie Market Entry | Underpenetrated Saskatchewan and Manitoba distribution networks present white space for shelf-stable protein formats. |
Research Methodology
Initial hypotheses were tested against primary input from pouch converting plant managers, brand owner procurement leads, food safety compliance officers, and contract packaging operations directors and refined through secondary validation against FDA 21 CFR migration testing protocols, Canadian Food Inspection Agency safety standards, CalRecycle extended producer responsibility filings, and U.S. customs trade data for laminated film substrates. Bottom-up capacity assessments across Midwest converting clusters were triangulated with top-down demand projections from retail and e-commerce channel audits.
Demand-supply balance modeling across the projection horizon incorporated substrate type segmentation, dispensing format complexity, end-use regulatory exposure, and channel velocity requirements. CAGRs were derived from installed converting equipment capacity expansion plans, brand owner SKU proliferation patterns, and substitution elasticity estimates for rigid container displacement. Industry-specific forecast inputs included ethylene-vinyl alcohol copolymer supply availability from Gulf Coast petrochemical complexes and digital printing adoption curves in contract packaging networks.
Sensitivities concentrate around California SB 54 implementation timelines, FDA food contact modernization protocol changes, and force majeure events affecting ethylene-vinyl alcohol supply. Forecasts reflect documented assumptions regarding mechanical recycling infrastructure development and brand owner willingness to absorb premium pricing for compliant structures. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
2 Seal Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Europe Pouch Packaging Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Bio PE Pouches Market
Pouch
Liquid Pouch Packaging Market
Pouch
Thailand Pouch Packaging Market
Pouch
Box Pouch Market
Pouch
Clear Pouches Market
Pouch
Open Mouth Sacks Market
Pouch
Stand-Up Pouches Market
Pouch
OPP Pouches Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Kraft Pouch Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market