
 Wrap-Around Packers Market | 2026-2036
Wrap-Around Packers Market Size, Share, and Industry Trends Forecast 2026-2036
Wrap-Around Packers Market Analytics
Asset-light leasing models for packaging automation are reshaping competitive entry barriers in the wrap-around packers space. Pro Mach leverages its modular equipment platform to serve mid-sized beverage producers seeking operational flexibility without capital-heavy purchases. KHS GmbH anchors its position through captive engineering services tied to high-speed line integration. SOMIC GmbH differentiates via specialized robotic loading systems for fragile product formats.
Wrap-around packers are secondary packaging machines that form corrugated or paperboard sleeves around grouped primary containers, typically operating at speeds of 20 to 120 cycles per minute with servo-driven folding and gluing stations. Their primary purpose is to create shelf-ready multipacks while minimizing material usage compared to traditional full-case formats. The automated installation segment leads volume deployment as food and beverage producers pursue labor reduction and throughput consistency. Paperboard material demand is accelerating fastest among sustainability-focused end users, though plastic retains dominance in moisture-critical pharmaceutical applications. Rigid product types occupy the mature core of the segment, while flexible format adaptability commands premium positioning.
The EPA enforces emissions and energy efficiency standards affecting motor and pneumatic systems in U.S.-installed equipment, while the EU Green Deal and REACH framework constrain adhesive chemistry and recyclability claims across European sales. FDA validation requirements for pharmaceutical wrap-around applications extend compliance burdens to machine surface finishes and cleanability documentation. Stakeholders must monitor how evolving extended producer responsibility laws in key states and EU member countries will redefine material specification obligations for new equipment purchases.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing equipment design cycles across European beverage bottling operations, forcing rapid retooling of servo-driven folding stations and adhesive systems to meet tightening material compliance thresholds.
Growth Catalysts
- REACH adhesive chemistry mandates:European paperboard sleeve demand accelerates as converters reformulate gluing stations to eliminate restricted substances, creating replacement equipment pull.
- Beverage bottling automation:Labor reduction imperatives in high-throughput lines drive adoption of 80-120 cycle-per-minute servo configurations for shelf-ready multipack formation.
- German engineering cluster concentration:Regional supply chain density around KHS GmbH and SOMIC GmbH reduces procurement lead times for mid-sized producers seeking line integration.
Market Restraints
- Corrugated input cost volatility:Kraft linerboard price swings compress margin predictability for packer OEMs locked into fixed-price maintenance contracts.
- Pharmaceutical plastic lock-in:Moisture-barrier requirements in FDA-validated drug packaging prevent paperboard substitution despite sustainability pressures.
- High-speed line integration complexity:Retrofitting legacy 20-40 cycle-per-minute mechanical systems to servo architectures demands extended downtime unacceptable to continuous-operation bottlers.
Strategic Opportunities
- Asset-light leasing penetration:Modular platform rentals unlock mid-tier beverage producers previously excluded by capital intensity barriers.
- Robotic fragile-format handling:Specialized loading systems for glass and premium containers command pricing premiums in craft spirits and specialty food verticals.
- Extended producer responsibility tailwinds:State-level packaging waste laws in California and New York mandate recyclability specifications that favor sleeve-format equipment over full-case alternatives.
Industry Challenges
- Servo motion programming skill scarcity:Bottling line technicians with expertise in multi-axis folding synchronization command wage premiums that inflate regional service costs.
- FDA validation documentation burdens:Pharmaceutical installations require surface finish certifications and cleanability protocols that extend commissioning timelines by 4-6 months.
- Legacy pneumatic system interoperability:Mixed-architecture bottling halls struggle to integrate new electric servo packers with existing compressed-air case sealers without custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrap-Around Packers Market |
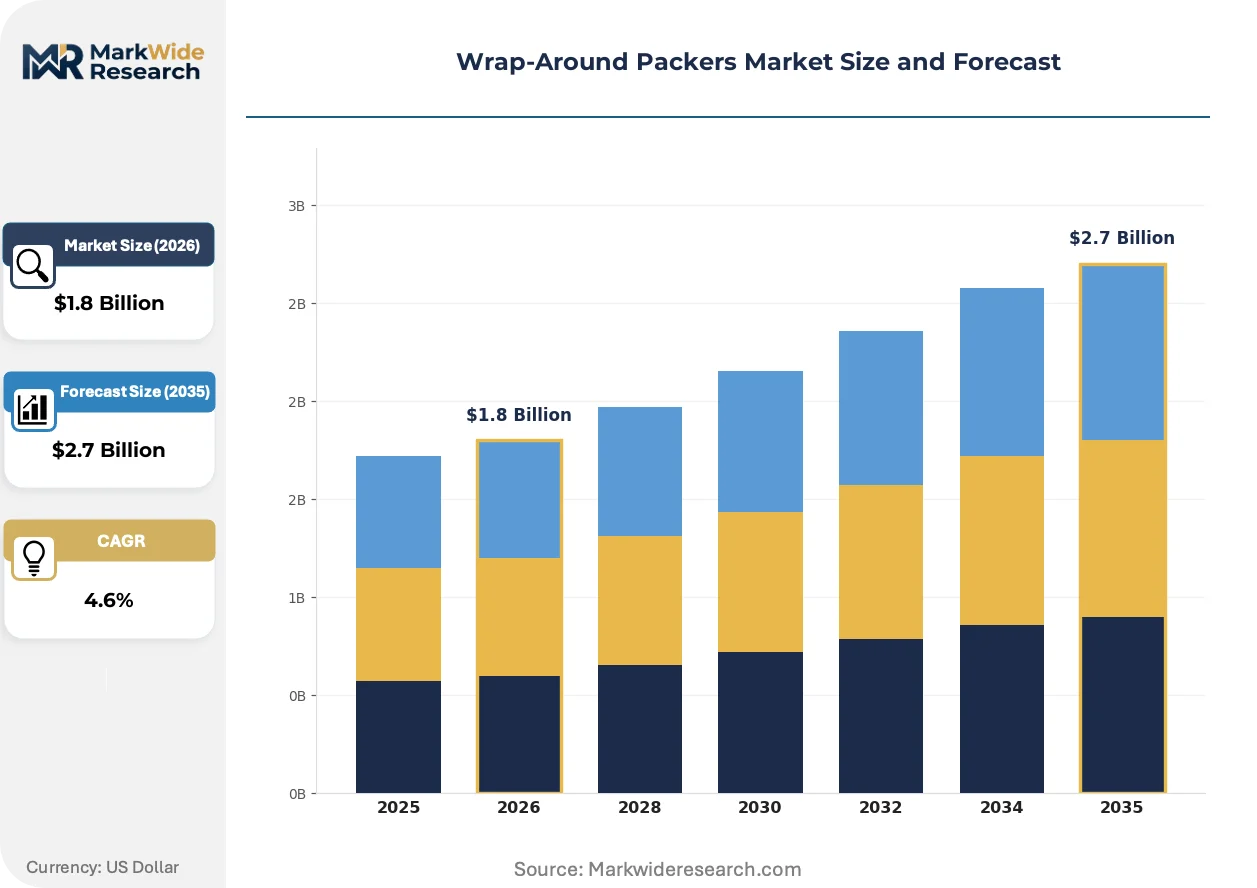
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Food, Beverage, Pharmaceuticals, Cosmetics Product Type: Rigid, Flexible, Semi-Rigid, Stand-up Installation: Automated, Manual, Semi-Automated, Mobile Material: Plastic, Paperboard, Metal, Others |
| Companies Covered | Tetra Pak, Pro Mach, KHS GmbH, SOMIC GmbH, Cama Group, A-B-C Packaging Machine Corporation, Cermex Group, Brenton Engineering, Bosch Packaging Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrap-Around Packers Market Evolving Landscape
Sustainability mandates and labor economics are simultaneously reshaping equipment specifications and ownership models across secondary packaging operations. Three distinct vectors are compressing traditional design assumptions.
Paperboard sleeve forming technology is collapsing the material efficiency gap between corrugated wrap-arounds and traditional RSC cases. Beverage producers in Germany and the Netherlands are adopting micro-flute configurations at the fastest clip, with installations doubling in two-year windows. This compression is eliminating the historical throughput penalty that kept paperboard formats confined to premium and seasonal SKUs.
The F-Gas Regulation is banning hydrofluorocarbon-based cooling in pneumatic systems across EU member states, forcing OEMs to migrate to electric servo architectures or alternative compressed-air drying methods. Equipment vendors with captive engineering services are capturing retrofit contracts from bottlers facing 2027 compliance deadlines. Pharmaceutical lines with FDA-validated pneumatic dependencies face the steepest requalification burdens.
Mid-sized beverage producers are unbundling after-sales service from capital purchases, favoring outcome-based availability contracts over traditional spare-parts-and-labor arrangements. Pro Mach's modular platform anchors this shift in North American craft brewing and regional soft-drink bottling. Germany's Mittelstand producers are replicating the model through captive maintenance subsidiaries of major OEMs.
Wrap-Around Packers Market Segmentation
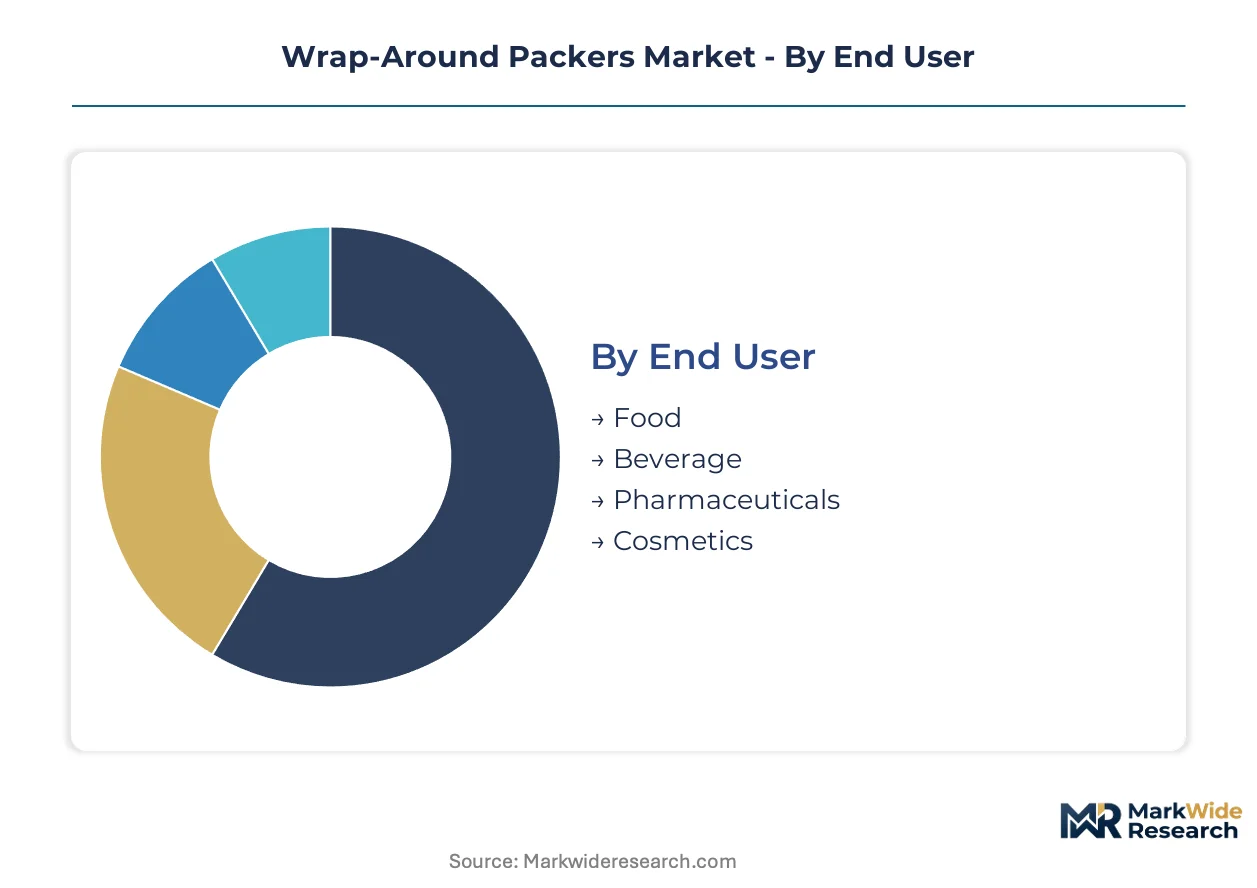
Equipment specification varies sharply across end-use environments, with pharmaceutical lines demanding FDA-validated surface finishes and beverage bottlers prioritizing cycle speed. Material selection and automation tier further fragment procurement patterns as sustainability mandates and labor economics reshape capital allocation priorities.
End User:
Application environment dictates compliance burden, throughput specification, and material compatibility requirements across four distinct demand clusters.
- Beverage:High-throughput bottling lines drive demand for 80-120 cycle-per-minute servo configurations with shelf-ready multipack formation. Germany's concentrated engineering cluster around KHS GmbH and SOMIC GmbH reduces procurement lead times for regional producers.
- Food:Secondary packaging for shelf-stable and refrigerated goods emphasizes format flexibility for seasonal SKU rotation. Extended producer responsibility laws in California and New York favor sleeve-format equipment over full-case alternatives for recyclability compliance.
- Pharmaceuticals:FDA validation requirements impose surface finish certifications and cleanability documentation that extend commissioning timelines by 4-6 months.
- Cosmetics:Premium container handling demands specialized robotic loading systems for glass and fragile formats in craft spirits and specialty verticals.
Beverage holds installed capacity. Food is rotating up the share rankings.
Product Type:
Structural rigidity determines machine architecture, with format adaptability commanding premium positioning in evolving SKU portfolios.
- Rigid:Corrugated and paperboard sleeves with fixed dimensional stability dominate high-volume beverage and food multipack formation. The mature core of the segment faces displacement pressure from flexible format innovations in premium applications.
- Flexible:Adaptive film and paper configurations enable rapid changeover for seasonal and promotional SKUs. Micro-flute paperboard technology is collapsing the throughput penalty that historically confined this format to premium and limited-run production.
- Semi-Rigid:Hybrid structures combining dimensional stability with partial conformability serve transitional applications in specialty food and personal care.
- Stand-up:Self-supporting pouch configurations require specialized forming heads and gluing stations for non-standard primary container geometries.
Rigid maintains the largest installed base. Flexible is climbing the fastest.
Installation:
Automation tier selection reflects capital intensity tolerance, labor availability, and line integration complexity in facility-specific decisions.
- Automated:Servo-driven folding and gluing stations operating at 20-120 cycles per minute anchor volume deployment as producers pursue labor reduction and throughput consistency. Pro Mach's modular platform serves mid-sized beverage producers through asset-light leasing models that bypass capital-heavy purchases.
- Semi-Automated:Hybrid configurations blending operator-fed loading with machine-controlled forming and sealing occupy transitional positions in emerging market facilities and SKU-diverse operations.
- Manual:Operator-dependent loading and forming persists in micro-breweries, artisanal food producers, and developing market installations with limited technical service infrastructure.
- Mobile:Reconfigurable skid-mounted units enable seasonal capacity augmentation and contract packaging operations requiring rapid site relocation.
Automated commands the dominant share. Mobile is gaining share fastest.
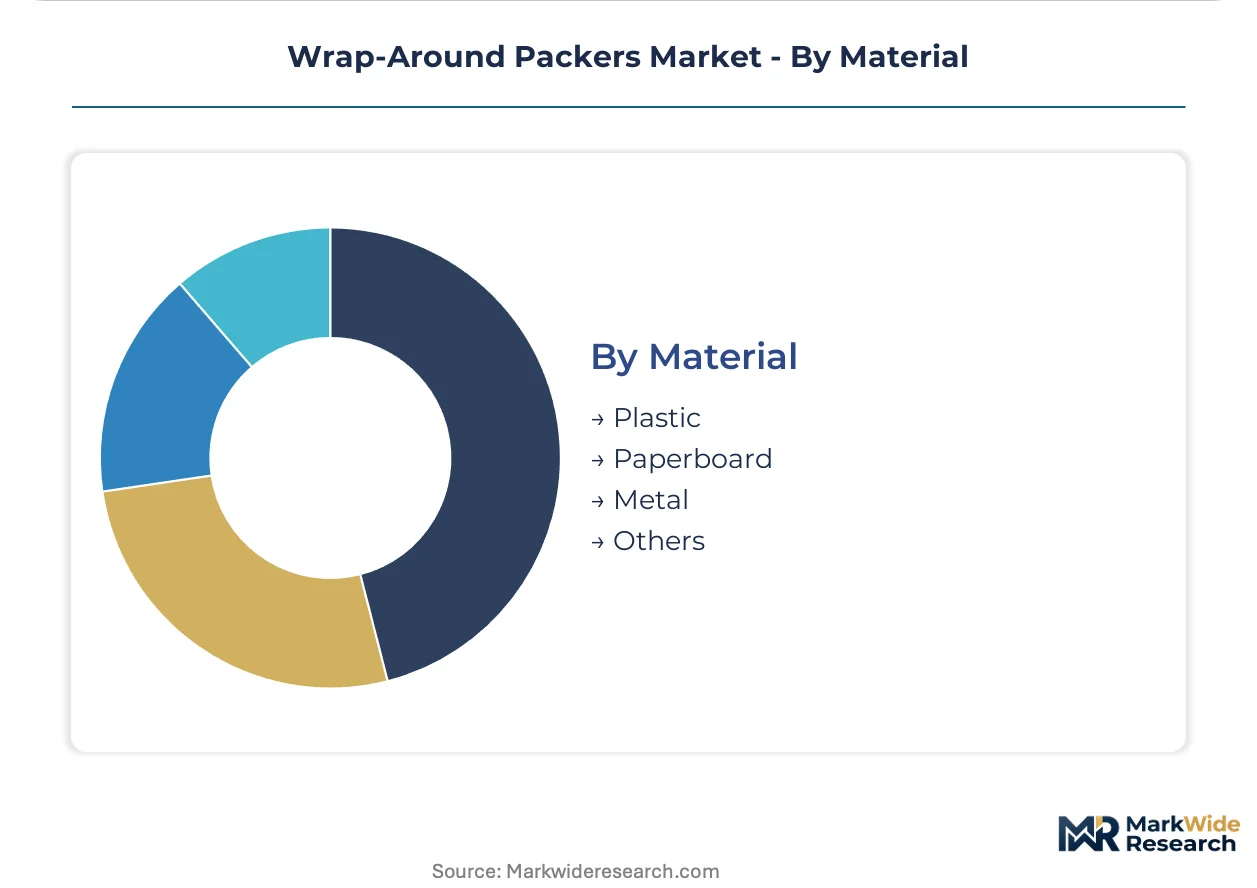
Material:
Substrate selection balances sustainability positioning, moisture protection, and regulatory compliance across divergent end-use requirements.
- Paperboard:Micro-flute and conventional fiber-based sleeves are accelerating fastest among sustainability-focused end users as EU Green Deal and REACH adhesive chemistry mandates drive converter retooling. Beverage producers in Germany and the Netherlands are adopting these configurations at the fastest clip.
- Plastic:Polyethylene and polypropylene films retain dominance in moisture-critical pharmaceutical applications where FDA-validated barrier properties prevent paperboard substitution despite sustainability pressures.
- Metal:Foil-laminated structures serve specialized pharmaceutical and high-value cosmetic applications requiring absolute light and oxygen exclusion.
- Others:Emerging bio-based and compostable substrates occupy niche positions in premium brand differentiation and pilot sustainability programs.
Plastic retains the largest installed base. Paperboard is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows in wrap-around packers tilt toward net-exporting precision engineering clusters, with Germany and the United States shipping integrated line systems to beverage bottlers in emerging production zones. Import dependency concentrates in markets lacking captive servo-motion engineering capacity.
Germany
The EU Green Deal and F-Gas Regulation compress design cycles for servo-driven folding stations, compelling rapid retooling of adhesive systems. KHS GmbH and SOMIC GmbH anchor a dense engineering cluster in North Rhine-Westphalia and Bavaria that supplies high-speed line integration across European bottling operations. Regional procurement lead times for mid-sized producers run 30-40 percent below cross-border alternatives.
United States
EPA emissions standards for motor and pneumatic systems shape equipment specifications in high-throughput beverage facilities. California and New York extended producer responsibility laws mandate recyclability specifications that favor sleeve-format equipment. Pro Mach's modular platform anchors asset-light leasing penetration in craft brewing and regional soft-drink bottling across the Midwest and Southeast.
China
Domestic beverage production scale drives demand for 80-120 cycle-per-minute automated configurations. The country's national environmental regulator enforces dual carbon goals that accelerate electric servo adoption over pneumatic architectures. Yangtze River Delta manufacturing clusters concentrate domestic OEM assembly capacity for export to Southeast Asian bottling markets.
Netherlands
REACH adhesive chemistry mandates accelerate paperboard sleeve adoption as converters reformulate gluing stations. Micro-flute configurations are penetrating mainstream beverage SKUs at twice the rate of neighboring markets. Rotterdam-area logistics hubs facilitate equipment distribution into Belgian and French bottling corridors.
India
FSSAI packaging safety regulations intersect with state-level plastic waste management rules in Maharashtra and Gujarat. Domestic food and beverage producers are importing German-engineered servo systems for premium line installations. Bangalore and Pune technical service hubs are developing localized maintenance capacity for automated secondary packaging equipment.
Wrap-Around Packers Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated line engineering houses and modular equipment specialists. Tier-one positions concentrate around firms offering captive high-speed integration services, while mid-market entry points fragment across leasing-enabled platform providers. Three archetypes dominate: full-line integrators with captive engineering services, modular platform lessors serving capital-constrained producers, and robotic handling specialists for fragile formats. Competitive moves center on M&A to secure servo-motion programming talent and geographic expansion through maintenance subsidiary networks.
Within the German engineering cluster, KHS GmbH and SOMIC GmbH exemplify the full-line integrator archetype, anchoring regional supply chains through proximity to North Rhine-Westphalia bottling corridors. Pro Mach occupies the modular platform lessor position, representing the asset-light service unbundling that is reshaping North American competitive entry barriers. These three firms collectively illustrate how equipment specification, ownership model innovation, and geographic service density are restructuring competitive positioning across beverage bottling automation.
| Leading Market Players |
|---|
| Tetra Pak |
| Pro Mach |
| KHS GmbH |
| SOMIC GmbH |
| Cama Group |
| A-B-C Packaging Machine Corporation |
| Cermex Group |
| Brenton Engineering |
| Bosch Packaging Technology |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese servo-motor manufacturing compresses component costs for European OEMs while simultaneously eroding pricing power for mid-tier packer assemblers in the Yangtze River Delta, forcing suppliers to bundle engineering services to defend margin structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the wrap-around packers market. Price differentiation hinges on servo-axis count and FDA validation tier, with pharmaceutical-grade surface finish certifications commanding substantial premiums over beverage-standard configurations. Pricing pressure stems from corrugated input cost volatility, which squeezes margin predictability for packer OEMs locked into fixed-price maintenance contracts. Mid-sized beverage producers exhibit the highest price sensitivity, while pharmaceutical lines with validated pneumatic dependencies show minimal elasticity due to requalification burdens.
Supply Chain Analysis
Kraft linerboard feedstock draws from Nordic pulp mills, German corrugated converters, and Canadian forestry operations as the primary upstream inputs for wrap-around packer materials. Servo drives and motion controllers rest on supply concentration in Germany, Japan, and Taiwan, with precision gearboxes and adhesive dispensing systems anchoring in Italy and Switzerland. Single-source vulnerability in high-torque servo motors from specific Japanese suppliers creates procurement risk for 80-120 cycle-per-minute configurations. Distribution runs through captive engineering subsidiaries of major OEMs for high-speed line integration, supplemented by regional equipment lessors serving capital-constrained mid-tier producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
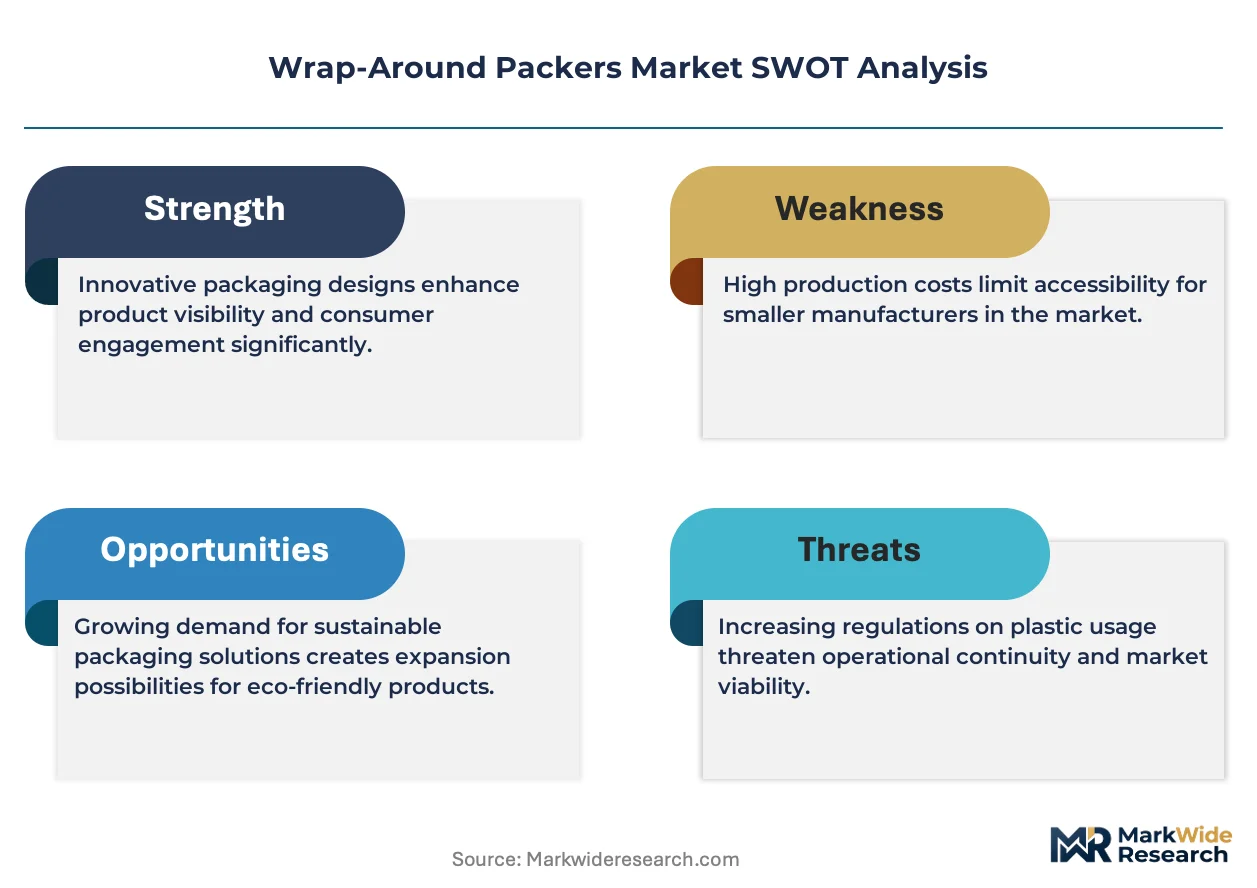
The wrap-around packers market functions as a defensive-moat arena where regulatory entrenchment around FDA validation and EU F-Gas compliance creates substantial switching costs for installed pharmaceutical and beverage bottling lines.
For Market Incumbents: Harden defensive positioning through captive maintenance subsidiary networks in German and North American bottling corridors, insulating against modular platform lessors. Deepen backward integration into servo-motion programming talent pools to offset wage premiums for multi-axis folding synchronization technicians. Prioritize certification investment in extended producer responsibility compliance for California and New York state-level mandates.
For New Entrants and Emerging Players: Pursue white-space penetration in craft spirits robotic handling for glass and premium container formats, where specialized loading systems command pricing premiums. Target mobile skid-mounted configurations for seasonal capacity augmentation and contract packaging operations requiring rapid site relocation. Deploy outcome-based availability contracts as the primary go-to-market angle, unbundling after-sales service from capital purchases to bypass capital intensity barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among modular platform lessors with asset-light leasing penetration in North American craft brewing and regional soft-drink bottling. Long-term viability favors firms with dense geographic service footprints and captive engineering capabilities rather than pure equipment manufacturers. Monitor extended producer responsibility law expansion across additional U.S. states as the signal to watch for accelerated sleeve-format equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Motion Engineering | KHS GmbH and SOMIC GmbH capture retrofit contracts from bottlers facing F-Gas compliance deadlines. |
| Asset-Light Leasing Platform Expansion | Pro Mach's modular equipment unlocks mid-tier beverage producers previously excluded by capital intensity barriers. |
| Robotic Fragile-Format Handling Specialization | Specialized loading systems for glass containers command pricing premiums in craft spirits verticals. |
| Extended Producer Responsibility Compliance Certification | California and New York state laws mandate recyclability specifications favoring sleeve-format equipment. |
| Captive Maintenance Subsidiary Network Buildout | Germany's Mittelstand producers replicate outcome-based availability contracts through OEM captive services. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage bottling line engineers, pharmaceutical packaging validation specialists, corrugated converter procurement leads, and aftermarket service heads at major OEMs. Secondary validation drew from EU F-Gas Regulation compliance filings, EPA emissions enforcement actions, FDA validation documentation databases, and trade flow records for servo-motion components. Bottom-up equipment shipment tallies by configuration tier were triangulated against top-down capital expenditure patterns across end-use industries.
Calibration against historical cycle-to-cycle variance in beverage bottling automation investments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include automation tier, material substrate, product rigidity class, and end-use regulatory environment. CAGRs were derived from slope analysis of replacement equipment pull against greenfield installation patterns, with specific inputs from REACH adhesive chemistry mandate timelines and F-Gas Regulation compliance deadlines.
Sensitivities concentrate around kraft linerboard price volatility, servo-drive import tariff exposure, and state-level extended producer responsibility law adoption pace. Forecasts reflect documented assumptions regarding equipment replacement cycles and regulatory compliance cost pass-through. Material shifts in EU F-Gas Regulation enforcement severity or unexpected REACH substance restriction expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Foam Pouch Market
Pouch
Spouted Pouches Market
Pouch
Liquid Pouch Market
Pouch
Monodose Packs Market
Pouch
High-Barrier Pouches Market
Pouch
Flexible Plastic Pouches Market
Pouch
Zipper Pouch Market
Pouch
Flexible Pouch Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
South Africa Pouch Packaging Market
Pouch
Feed Pouches Market
Pouch
Aluminum Pouches Market
Pouch
Kraft Paper Pouch Market
Pouch
Pouches Market
Pouch
Foil Zipper Bags Market
Pouch
Pre-Made Pouch Packaging Market