
 Recyclable PE Pouch Market | 2026-2036
Recyclable PE Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Recyclable PE Pouch Market Analytics
Multi-sourced resin procurement is realigning as converters seek supply security amid virgin PE volatility. Amcor Plc leverages its global film extrusion footprint to secure consistent polymer flows across regions. Mondi Group anchors its competitive stance through captive kraft paper and PE film integration in Central European mills. Constantia Flexibles specializes in pharma-grade recyclable laminates, occupying a defensible niche with higher certification barriers.
Recyclable PE pouches are mono- or multi-layer flexible containers fabricated from high-density, low-density, or linear low-density polyethylene resins, designed for mechanical recycling compatibility through density-based sink-float separation in standard polyethylene streams. These structures replace multi-material laminates in shelf-stable and refrigerated applications where barrier performance must yield to end-of-life recyclability. Stand-up pouches command the largest volume share due to retail shelf efficiency and consumer convenience, while zipper pouches represent the fastest-expanding format as reclosability becomes standard in food and personal care segments. Barrier pouches concentrate margin pools where oxygen and moisture protection justify premium positioning over basic printed structures.
The European Union's Packaging and Packaging Waste Regulation, the U.S. Federal Trade Commission's Green Guides, and Germany's Packaging Act collectively reshape product design mandates, material disclosure requirements, and recyclability claims verification across the value chain. ECHA's REACH restrictions on perfluorinated substances further narrow the additive palette available for barrier enhancement in PE-only structures. Stakeholders must monitor evolving state-level extended producer responsibility legislation in the United States and anticipate how mechanical recycling infrastructure investments in the Netherlands and Belgium will alter acceptable pouch specifications.
Market Dynamics
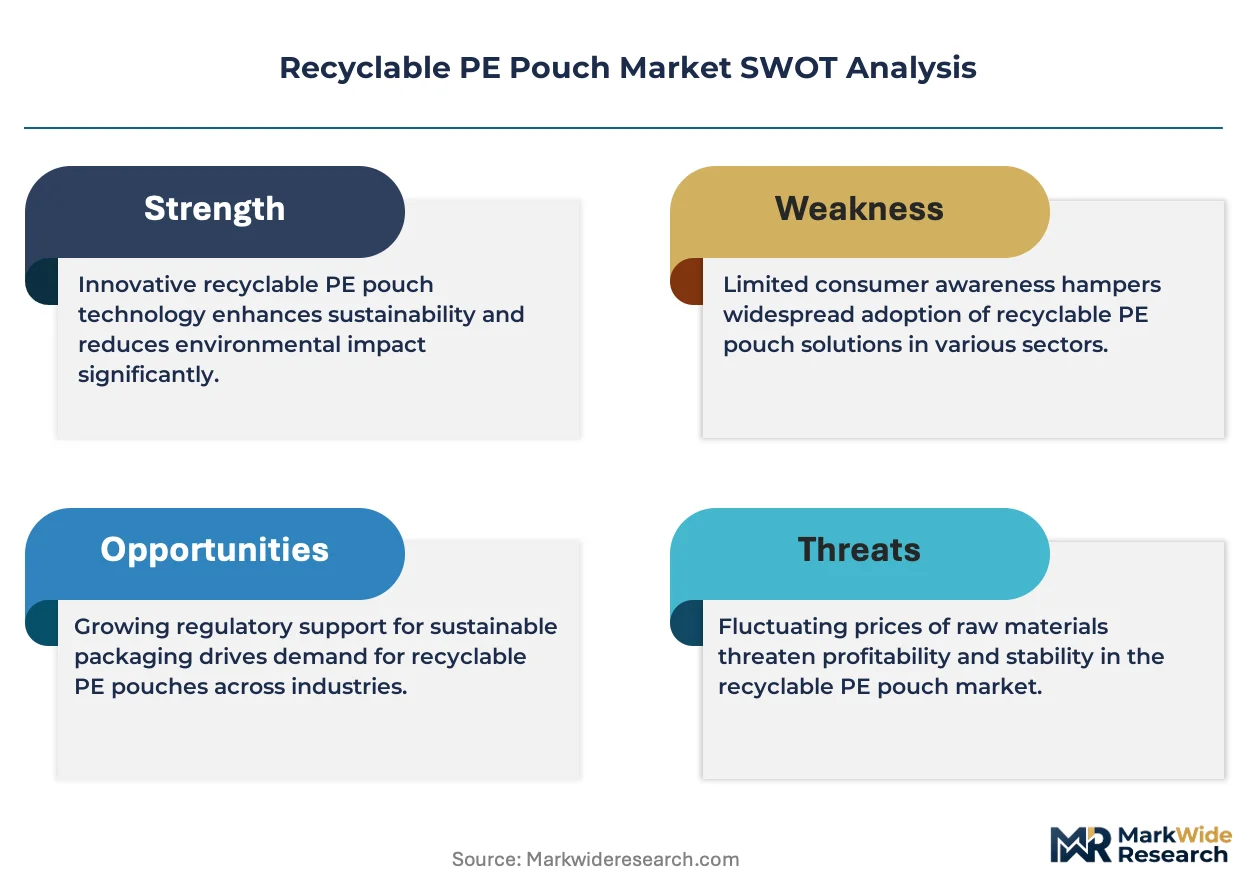
Extended Producer Responsibility frameworks are forcing brand owners to redesign packaging portfolios around mechanical recyclability, eliminating multi-material laminates that previously dominated shelf-stable food applications. This regulatory pressure is compressing converter R&D timelines and redrawing competitive boundaries between mono-material specialists and legacy laminate producers.
Growth Catalysts
- Germany's Packaging Act:Mandated recycled content thresholds compel food brands to source mono-PE structures, creating guaranteed demand pools for certified converters.
- Sink-float separation compatibility:PE-only pouch designs integrate seamlessly with existing European mechanical recycling infrastructure, lowering end-market development costs for reclaimers.
- Stand-up pouch format adoption:Retailers in France and the United Kingdom prioritize shelf-efficient formats that reduce shipping cube and damage rates versus rigid alternatives.
Market Restraints
- Virgin PE price volatility:Naphtha-linked resin costs swing converter margins unpredictably, discouraging long-term contract structures with food brands.
- Barrier performance gaps:Oxygen transmission rates in PE-only structures remain 3-5x higher than metallized laminates, limiting adoption in oxygen-sensitive applications.
- Recycling infrastructure concentration:Advanced mechanical recycling capacity clusters in the Netherlands and Belgium, creating logistics cost penalties for converters in Southern and Eastern Europe.
Strategic Opportunities
- Pharmaceutical compliance:Pharma-grade recyclable laminates face fewer certified competitors, yielding premium pricing power for converters meeting EMA stability requirements.
- Zipper integration:Reclosable mono-PE pouches penetrate personal care segments where convenience commands price premiums over basic pillow formats.
- Digital watermarking convergence:Invisible markers embedded during extrusion enable automated sorting at MRFs, expanding addressable volume beyond manually sorted streams.
Industry Challenges
- How2Recycle certification timelines:Third-party recyclability validation requires 12-18 month testing cycles, delaying product launches and locking up R&D resources.
- Extrusion coater retrofit requirements:Converting legacy solvent-based lamination lines to water-based or extrusion coating demands capital outlays that strain mid-tier converter balance sheets.
- Food contact migration testing:EFSA compliance for recycled content incorporation extends development cycles and requires specialized analytical chemistry capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recyclable PE Pouch Market |
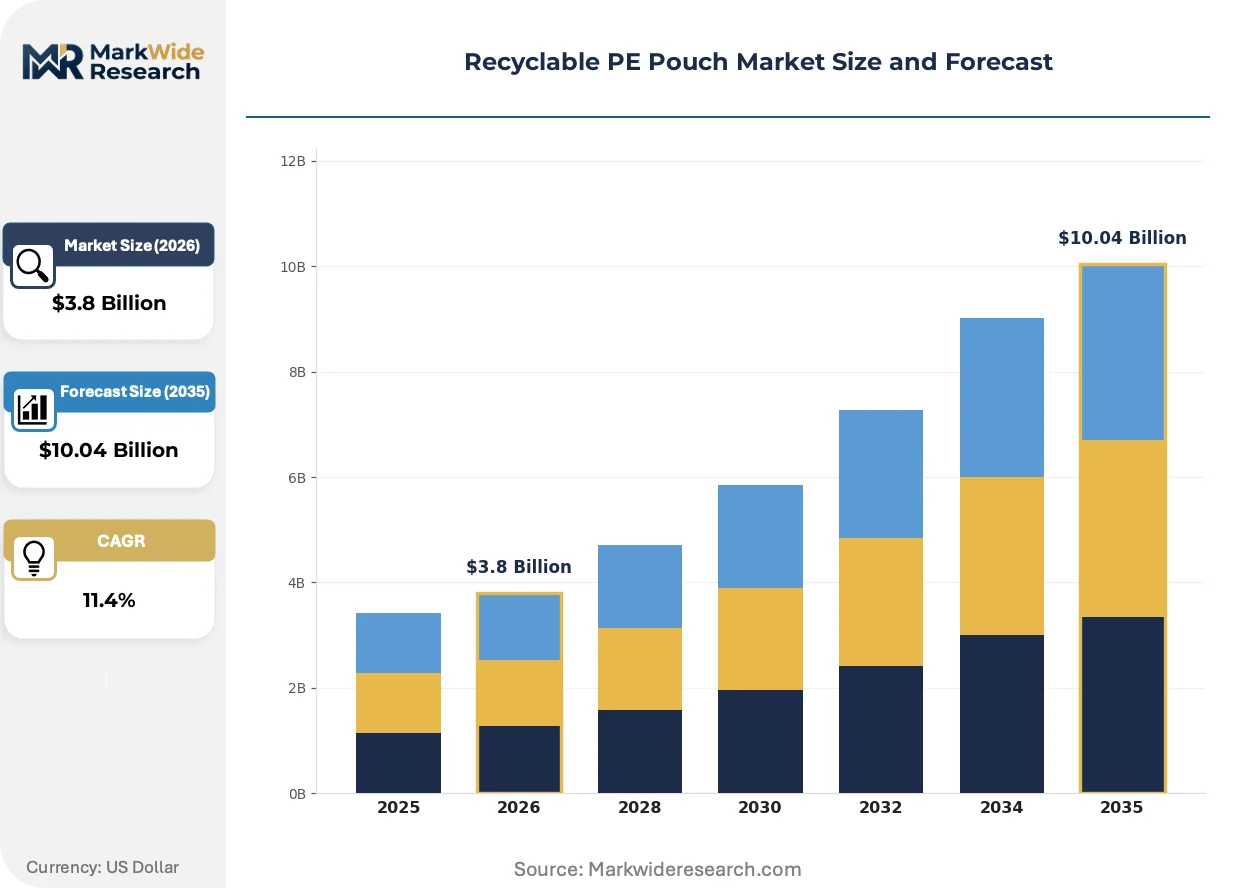
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Zipper Pouches, Pillow Pouches End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Material Grade: High-Density Polyethylene, Low-Density Polyethylene, Linear Low-Density Polyethylene, Recycled PE Packaging Technology: Printed Pouches, Barrier Pouches, Biodegradable Pouches, Eco-Friendly Laminates |
| Companies Covered | Amcor Plc, Berry Global Inc., Mondi Group, Sealed Air Corporation, Sonoco Products Company, Constantia Flexibles, Huhtamaki Group, Uflex Ltd., ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recyclable PE Pouch Market Evolving Landscape
Digital printing and advanced barrier coatings are converging to enable short-run customization without sacrificing recyclability, collapsing minimum order quantities that previously favored commodity converters. This technology stack is compressing lead times and fragmenting demand into smaller, more frequent production cycles.
High-barrier oxide coatings deposited through plasma-enhanced chemical vapor deposition are converging with flexible PE substrates to replace aluminum foil layers. Snack food brands in Germany adopt these structures for nut and coffee applications where shelf life extension justifies 15-20% material cost premiums. The technology is converging with existing extrusion lines through retrofit deposition chambers, lowering adoption barriers for mid-scale converters.
REACH restrictions on perfluorinated substances are eliminating traditional grease-resistant additives from PE pouch formulations. ECHA's 2023 PFAS restriction proposal forces converters to validate alternative barrier technologies—primarily bio-based waxes and clay nanocomposites—through accelerated migration testing protocols. Bakery and frozen food segments face the steepest compliance curves given prior reliance on fluorinated treatments.
Retailers are consolidating supplier bases around converters offering pre-approved How2Recycle labels, displacing fragmented procurement across multiple regional vendors. This concentration rewards integrated producers with in-house testing capabilities and penalizes smaller converters dependent on third-party certification timelines. The shift is most pronounced in the United Kingdom, where major grocery chains now mandate store-dropoff recyclable labeling as a listing prerequisite.
Recyclable PE Pouch Market Segmentation
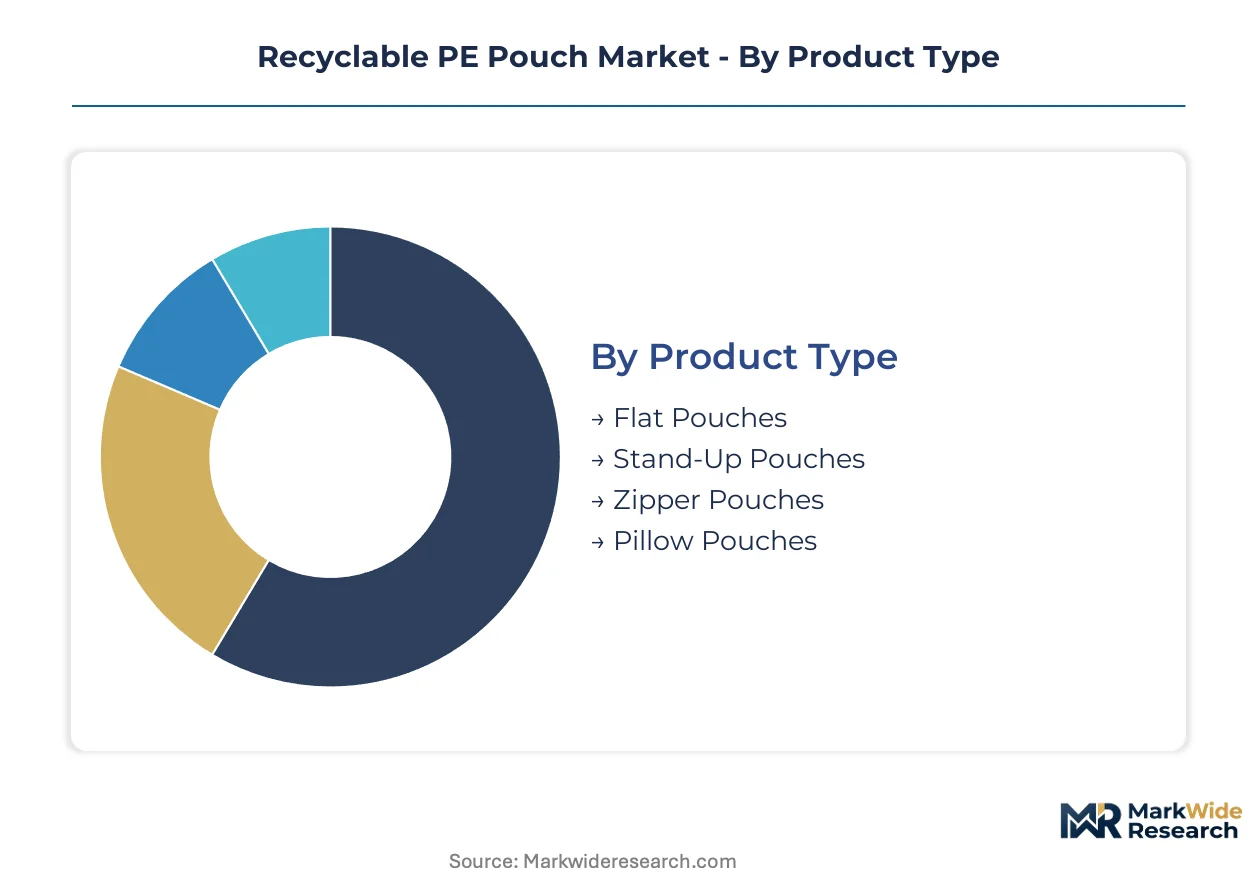
Segmentation in the Recyclable PE Pouch Market reveals how converters balance mechanical recyclability against functional performance across format, end-use, resin chemistry, and barrier technology. Each dimension carries distinct certification requirements and infrastructure dependencies that reshape procurement patterns.
Product Type:
Standardization dominates high-volume formats while customization concentrates in convenience-driven structures with integrated closures.
- Stand-Up Pouches:Self-supporting bottom-gusseted containers fabricated from coextruded PE films with optional resealable fitments. German and French retailers prioritize this format for shelf-stable snacks and grains where vertical display efficiency reduces stocking labor and damage rates versus rigid alternatives.
- Zipper Pouches:Mono-PE structures incorporating interlocking plastic tracks heat-sealed to pouch headers, enabling repeated reclosure without compromising recyclability. Personal care brands in the United Kingdom specify these for wet wipes and refills where convenience commands price premiums over basic pillow formats.
- Flat Pouches:Two-dimensional sealed bags without dimensional stability, serving cost-sensitive dry goods applications.
- Pillow Pouches:Simple center-sealed tubes common to bulk commodity packaging with minimal barrier requirements.
Most installed capacity flows through Stand-Up Pouches. Expansion is steepest in Zipper Pouches.
End User:
Regulatory pressure intensity varies sharply across end-use segments, with food contact compliance creating the steepest barriers to entry.
- Food & Beverage:Oxygen-sensitive applications requiring modified atmosphere protection drive demand for high-barrier PE structures with EVOH or oxide coatings. Germany's Packaging Act mandates minimum recycled content thresholds that force brands to redesign legacy multi-material laminates around mono-PE compatibility.
- Pharmaceuticals:EMA stability requirements for moisture and light protection create certification moats around pharma-grade recyclable laminates. Constantia Flexibles and comparable specialists occupy this niche where audit trails and migration testing capabilities deter commodity converters.
- Personal Care:Wet wipes and liquid refills favor reclosable formats with chemical resistance to surfactant formulations.
- Household Products:Concentrated detergents and cleaning agents prioritize puncture resistance over barrier sophistication.
Food & Beverage commands the dominant volume share. Pharmaceuticals delivers the highest margin expansion trajectory.
Material Grade:
Resin selection determines compatibility with existing mechanical recycling infrastructure and compliance with emerging recycled content mandates.
- Linear Low-Density Polyethylene:Co-monomer-modified resins delivering puncture resistance and seal strength for frozen food and heavy-duty applications. Dutch reclaimers favor LLDPE-dominant streams for their consistent melt flow characteristics in film-to-film recycling circuits.
- Recycled PE:Post-consumer or post-industrial PE flake incorporated at 30-50% loadings in non-food contact layers, with EFSA-approved grades entering limited food applications. Supply security concerns are accelerating converter investment in long-term offtake agreements with European mechanical recyclers.
- High-Density Polyethylene:Stiffer resins selected for standing rigidity in gusseted formats and chemical resistance in industrial applications.
- Low-Density Polyethylene:Traditional branched PE retained for clarity and softness in personal care and specialty food segments.
Linear Low-Density Polyethylene anchors current extrusion capacity. Recycled PE is climbing the fastest as brand mandates harden.
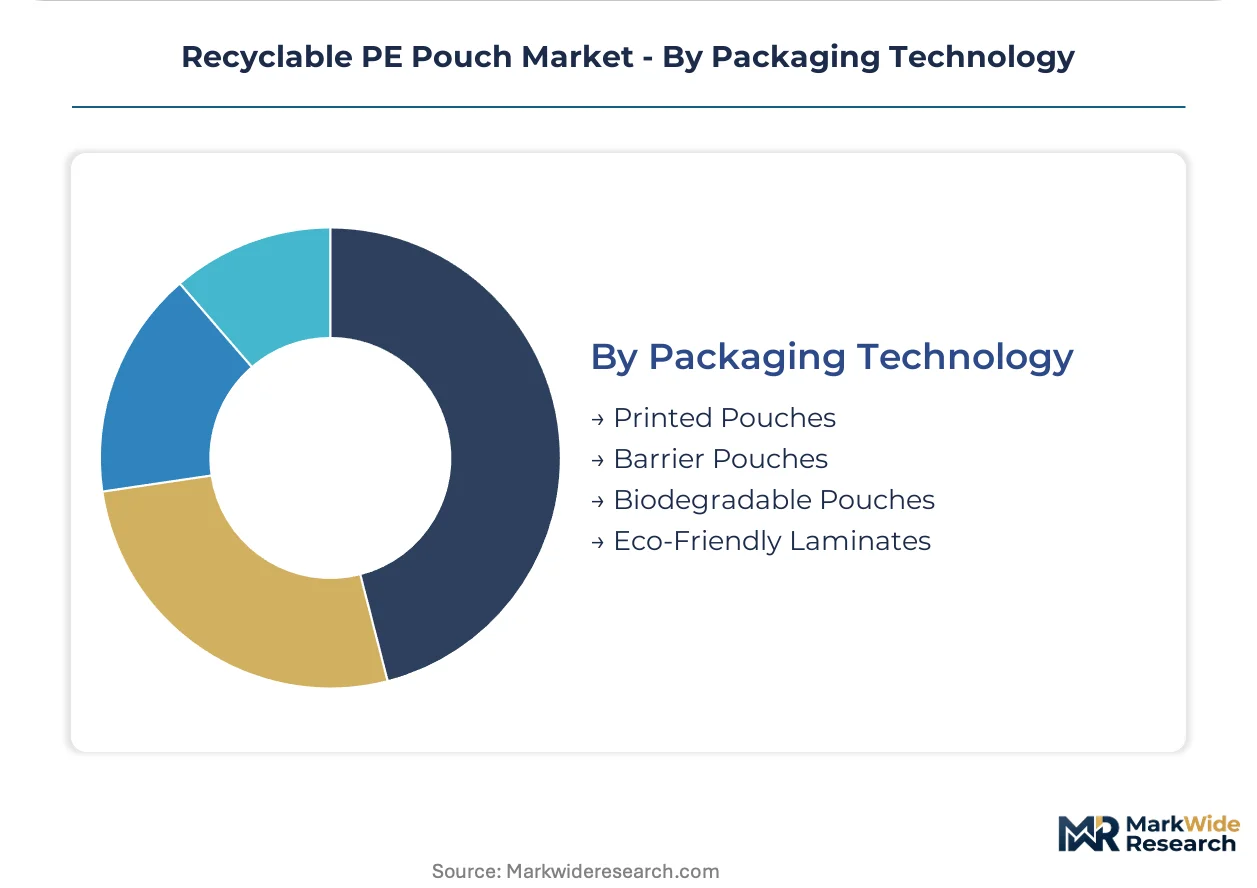
Packaging Technology:
Barrier performance and environmental claim verifiability separate premium-positioned technologies from commodity printed structures.
- Barrier Pouches:Oxide-coated or coextruded EVOH structures replacing aluminum foil in oxygen-sensitive applications. German snack brands adopt plasma-enhanced chemical vapor deposition coatings for nuts and coffee where shelf life extension justifies material cost premiums over metallized laminates.
- Printed Pouches:Surface-decorated mono-PE with water-based or UV-cured inks compatible with mechanical recycling, serving private-label retail programs where speed-to-shelf outweighs barrier sophistication.
- Eco-Friendly Laminates:Certified recyclable adhesive-free structures meeting How2Recycle store-dropoff requirements.
- Biodegradable Pouches:Additive-modified PE claiming enhanced degradation pathways, though mechanical recyclability certification remains contested under APR protocols.
Printed Pouches carry the broadest installed base. Barrier Pouches is expanding most quickly as coating technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Düsseldorf-Cologne corridor anchors European converter capacity for recyclable PE pouches, with mechanical recycling infrastructure clustering in the Netherlands and Belgium creating cross-border supply dependencies.
Germany
Food brands redesign shelf-stable packaging around mono-PE compatibility as the Packaging Act mandates minimum recycled content thresholds. ECHA's REACH restrictions on perfluorinated substances eliminate traditional grease-resistant additives, forcing validation of bio-based wax alternatives. The Düsseldorf-Cologne corridor concentrates extrusion coating capacity where converters retrofit solvent-based lamination lines.
United States
Major grocery chains mandate store-dropoff recyclable labeling as a listing prerequisite, consolidating supplier bases around pre-approved How2Recycle certifications. The FTC's Green Guides reshape recyclability claims verification requirements across flexible packaging portfolios. Chicago and Minneapolis-St. Paul host the largest mechanical recycling capacity for flexible PE streams.
France
Retailers prioritize shelf-efficient stand-up pouch formats that reduce shipping cube and damage rates versus rigid alternatives. Extended Producer Responsibility frameworks tighten disclosure requirements for packaging material composition. The Lyon-Grenoble corridor develops plasma-enhanced chemical vapor deposition coating capacity for oxygen-sensitive snack applications.
United Kingdom
Personal care brands specify reclosable mono-PE zipper pouches for wet wipes and refills where convenience commands price premiums. The Environment Agency enforces packaging waste regulations that accelerate converter investment in certified recyclable structures. Greater Manchester hosts specialized testing laboratories for EFSA food contact migration protocols.
Netherlands
Dutch reclaimers favor LLDPE-dominant streams for consistent melt flow characteristics in film-to-film recycling circuits. National circular economy programs fund advanced mechanical recycling infrastructure that accepts post-consumer flexible packaging. The Rotterdam-Antwerp port complex enables resin import logistics for converters serving German and Belgian brand customers.
Recyclable PE Pouch Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue certified specialty niches where compliance barriers deter commodity competition. The vendor base stratifies across three tiers: integrated multinationals with captive resin supply, regional converters with retrofit extrusion capabilities, and specialists in pharma-grade or high-barrier laminates. Competitive positioning depends on How2Recycle certification speed, recycled content offtake security, and barrier coating technology access. M&A activity targets mid-tier converters with approved label credentials, while capacity expansion concentrates in Central European mechanical recycling corridors.
Among integrated packaging multinationals, Amcor Plc and Mondi Group exemplify scale-driven archetypes with global film extrusion footprints securing polymer flow consistency across regions. Constantia Flexibles occupies a specialist position within pharma-grade recyclable laminates where EMA stability requirements create certification moats. These three anchors illustrate how competitive advantage separates commodity volume players from defensible niche operators in a market where regulatory compliance velocity determines contract capture.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Mondi Group |
| Sealed Air Corporation |
| Sonoco Products Company |
| Constantia Flexibles |
| Huhtamaki Group |
| Uflex Ltd. |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
Germany's Packaging Act mandates on minimum recycled content thresholds are forcing food brands to redesign procurement specifications around mono-PE compatibility, compelling converters to secure long-term resin offtake agreements and absorb virgin PE volatility through contract restructuring.
Pricing Analysis
Input-cost pass-through from naphtha-linked virgin PE resin dominates converter margin dynamics, with price differentiation resting on How2Recycle certification speed and barrier coating sophistication. Three-tier pricing structure across premium, standard, and economy levels separates pharma-grade certified laminates from commodity printed pouches and basic pillow formats. Cost compression in standard printed pouches is intensifying because retailer consolidation around pre-approved suppliers compresses contract margins. Private-label retail programs exhibit highest price sensitivity, while pharmaceutical brands with EMA stability requirements show least elasticity.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale food and beverage demand, while specialized distributors serve mid-tier personal care converters. Manufacturing concentrates in Germany, the Netherlands, and Belgium where mechanical recycling infrastructure clusters. Raw material flows draw from Saudi Arabian and Qatari ethylene feedstocks, European naphtha crackers, and post-consumer flake from Dutch reclaimers. Single-source vulnerability sits with LLDPE resin supply from Rotterdam-Antwerp port complexes. Distribution runs through converter-direct relationships with major grocery chains and pharmaceutical OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Extended Producer Responsibility frameworks in Germany, France, and the United Kingdom guarantee demand expansion through mandated redesign timelines.
For Market Incumbents: Anchor competitive position through backward integration into mechanical recycling capacity in the Netherlands and Belgium, securing post-consumer flake offtake before supply constraints harden. Accelerate How2Recycle certification velocity to capture retailer consolidation around pre-approved supplier bases. Defend against emerging oxide-coating specialists by locking exclusive plasma-enhanced chemical vapor deposition technology licenses. For New Entrants and Emerging Players: The 15-20% material cost premium gap between metallized laminates and oxide-coated PE structures opens white-space in oxygen-sensitive snack applications. Target German nut and coffee brands seeking shelf-life extension without multi-material complexity. Penetrate through digital watermarking integration partnerships with automated sorting equipment vendors, collapsing the 12-18 month certification timeline that locks out smaller competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters holding approved How2Recycle credentials but lacking scale to secure long-term resin contracts. Long-term viability favors specialists with in-house EFSA migration testing capabilities and pharma-grade certification moats. Watch for inflection when digital watermarking adoption crosses critical mass at major European material recovery facilities, expanding addressable volume beyond manually sorted streams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanical Recycling | Captures post-consumer flake supply before Germany's recycled content mandates tighten procurement competition. |
| Plasma-Enhanced Chemical Vapor Deposition Licensing | Enables oxide-coated barrier structures that replace aluminum foil in oxygen-sensitive German snack applications. |
| Digital Watermarking Technology Partnership | Embeds invisible markers during extrusion for automated MRF sorting, expanding recyclable volume capture. |
| Pharma-Grade EMA Certification Investment | Builds audit trail capabilities that deter commodity converters from entering high-margin pharmaceutical laminates. |
| Direct-to-Retailer Distribution Expansion | Bypasses fragmented regional distributors as UK grocery chains mandate store-dropoff recyclable labeling. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, the Netherlands, and the United States, with primary inputs from each market gathered through structured interviews with packaging procurement directors at food and beverage brands, converter plant managers, mechanical recycling facility operators, and regulatory affairs specialists at trade associations. Secondary validation draws from ECHA REACH restriction proposals, EFSA food contact guidance, How2Recycle certification databases, and national packaging waste statistics. Bottom-up volume estimates triangulate against top-down spending analysis across end-use segments.
Rate-of-change decomposition separates volume growth from value expansion across format type, barrier technology tier, resin chemistry grade, and end-use regulatory intensity. Modeled segmentation spans stand-up versus zipper versus flat pouch formats, printed versus barrier versus eco-friendly laminate technologies, and food versus pharmaceutical versus personal care end-uses. CAGRs derive from regression analysis against historical adoption curves for comparable regulatory mandate implementations, with inputs including virgin PE price volatility indices and mechanical recycling capacity buildout schedules.
The model assumes a particular technology adoption path; alternative pathways for plasma-enhanced chemical vapor deposition coating scale-up would alter the outlook if capital costs fail to decline through equipment retrofit compatibility. Forecasts reflect assumptions around EPR enforcement consistency, resin supply security, and sorting infrastructure investment pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Retort Pouch Packaging Market
Pouch
France Pouch Packaging Market
Pouch
Poland Pouch Packaging Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Twist Wrap Packaging Market
Pouch
Spout Pouch Market
Pouch
Peel Pouches Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Kraft Pouch Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Bio PE Pouches Market
Pouch
Standcap Pouch Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Thailand Pouch Packaging Market