
 Italy Pouch Packaging Market | 2026-2036
Italy Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Pouch Packaging Market Insights
Asset-light leasing models for high-barrier film extrusion lines is rewriting competitive entry dynamics in Italian pouch converting. Mondi PLC leverages vertical integration across kraft paper and barrier coatings to sustain margin control in sustainable formats. Constantia Flexibles GmbH anchors European pharma-grade pouch supply from its Italian operations. Sacia Flex Italy specializes in short-run digital printing for regional food brands, occupying a niche between mass converters and commodity imports.
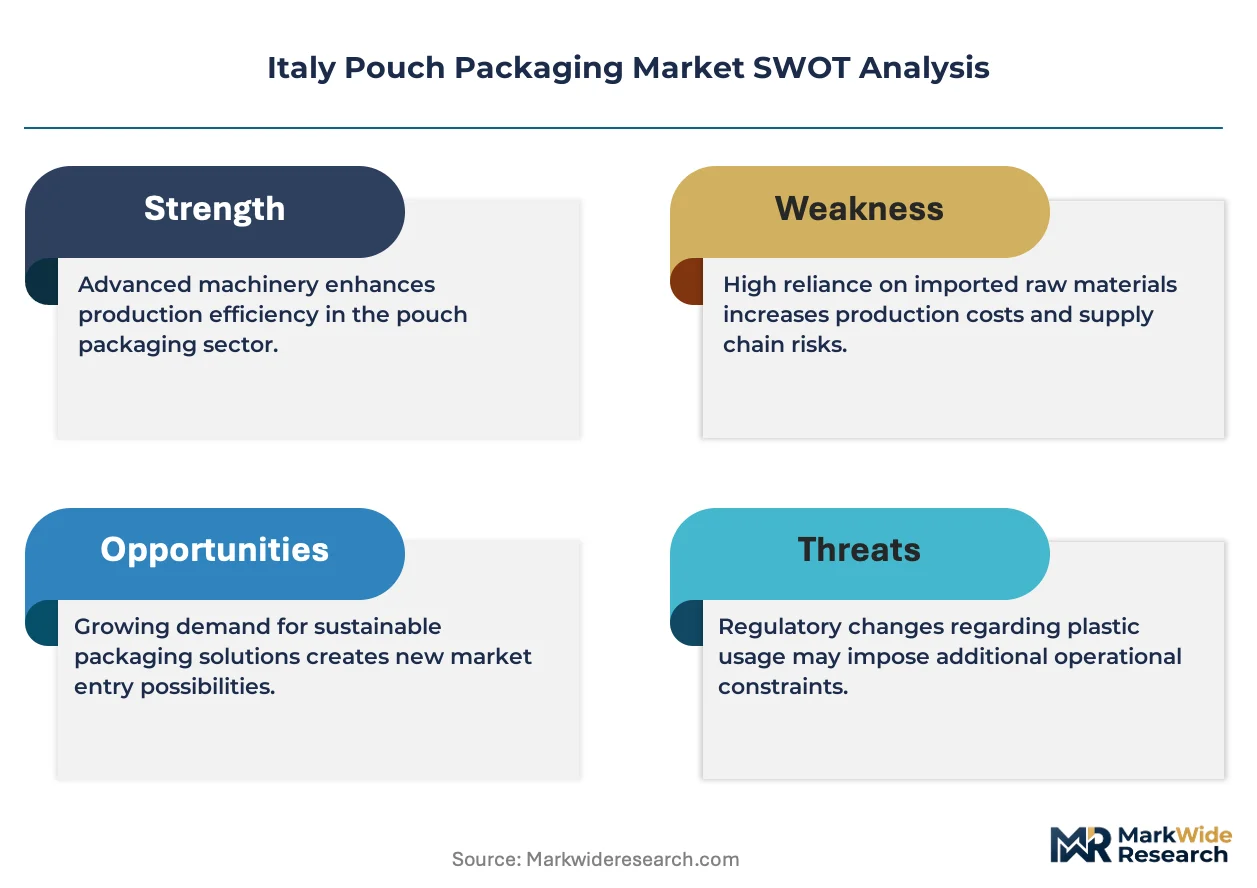
Italy pouch packaging denotes flexible, sealed containers typically constructed from multi-layer polymer, aluminum, or fiber-based laminates ranging from 50 to 200 microns in thickness, formed through flat-bed or rotary converting processes with heat-seal or zip-lock closure integration. Stand-up pouches dominate value contribution due to premium shelf presence and expanded gusset stability in liquid and granular applications. Composite materials represent the fastest-evolving segment as CONAI fees and EU Single-Use Plastics Directive compliance push brands toward paper-plastic hybrid structures with separable layers.
CONAI, Italy's national packaging consortium, enforces extended producer responsibility fees that directly shape material selection and end-of-life design requirements for all pouch formats placed on the Italian market. BIS-equivalent voluntary standards and EU REACH chemical compliance for food-contact layers create dual certification burdens that filter out smaller non-specialized importers. Stakeholders must monitor pending EU Packaging and Packaging Waste Regulation revisions, as these will likely mandate minimum recycled content thresholds and reusable format quotas before implementation timelines crystallize.
Market Dynamics
CONAI's extended producer responsibility framework is compressing material choice sets across Italian pouch converting, forcing rapid substitution of conventional multi-layer plastics toward separable paper-plastic hybrids and mono-material alternatives.
Growth Catalysts
- EU Single-Use Plastics Directive:Italy's transposition mandates elimination of certain plastic formats, redirecting food and beverage brands toward fiber-based pouch structures with barrier coatings.
- Pharmaceutical serialization requirements:Track-and-trace mandates for pharma packaging are expanding demand for high-integrity pouch formats with integrated tamper-evidence and coding surfaces.
- Northern industrial corridor concentration:Milan-Bologna-Turin logistics networks enable just-in-time film supply and same-day converting turnaround for regional food brands.
Market Restraints
- Aluminum laminate cost volatility:Energy-intensive foil production exposes converters to electricity price swings that compress margin on high-barrier pharma and retort formats.
- Barrier coating supply concentration:Specialized water-based and solvent-free coating chemistries rely on a narrow German and Austrian supplier base, creating single-source vulnerability.
- Mechanical recycling incompatibility:Legacy multi-layer pouches with incompatible polymer combinations face rejected waste streams under Italy's differentiated CONAI fee structures.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily retail modernization is creating first-mover advantage for shelf-ready pouch formats in pasta, sauce, and preserved vegetable categories.
- Reusable packaging mandates:Pending EU Packaging and Packaging Waste Regulation revisions will likely introduce format quotas that reward Italian converters with in-house design-to-recycle capabilities.
- Digital printing-web handling convergence:Integration of inkjet deposition with rotary pouch forming is collapsing minimum order quantities for regional specialty food brands.
Industry Challenges
- Polymer-to-paper lamination expertise gap:Conventional plastic-focused technicians lack fiber web tension control and moisture-management skills required for hybrid structures.
- Dual certification timeline compression:Simultaneous CONAI compliance and EU REACH food-contact layer verification extends product development cycles by four to six months.
- Legacy heat-seal line retrofit requirements:Existing converting assets require substantial modification to handle thicker paper-plastic substrates without seal integrity degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Pouch Packaging Market |
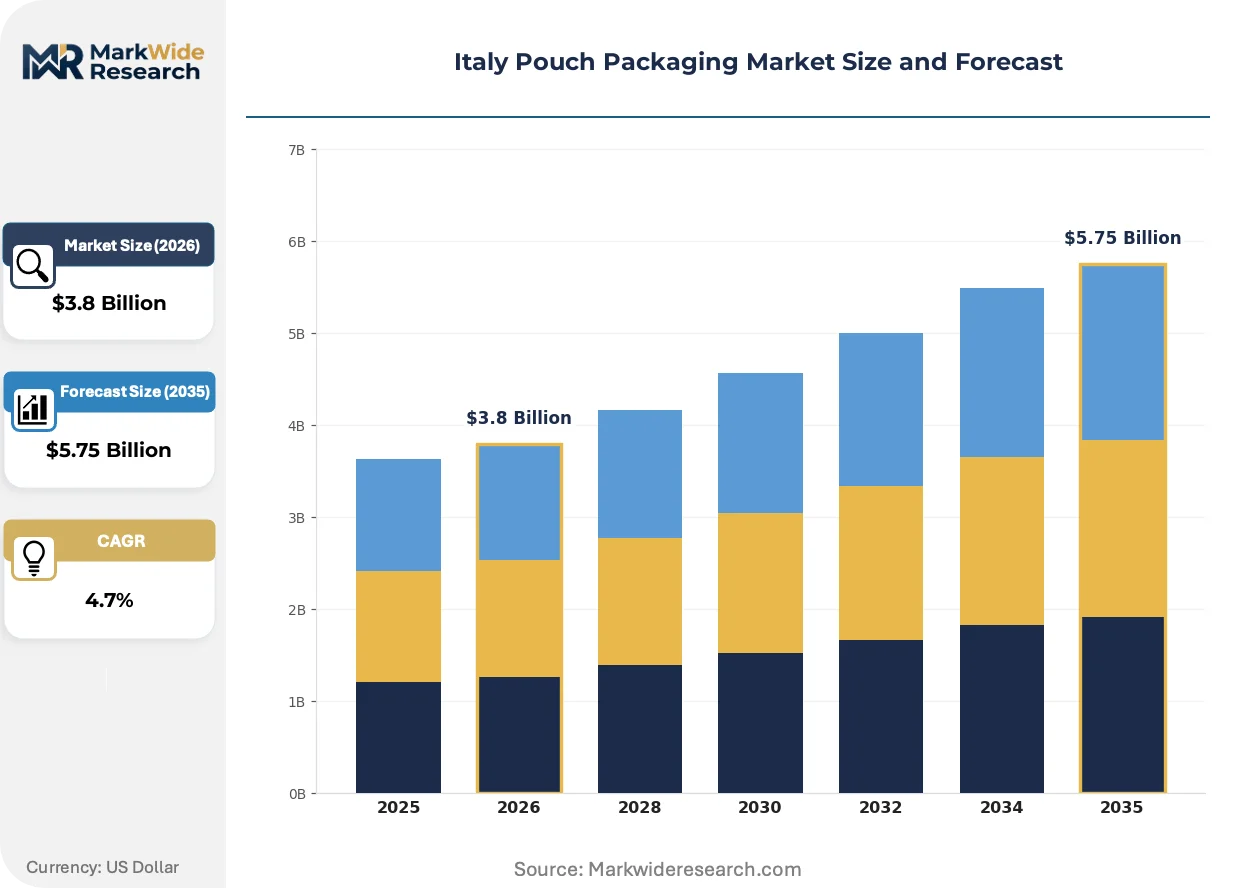
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Vacuum Pouches, Spouted Pouches Materials: Plastic, Paper, Aluminum, Composites End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Closure Type: Zip Locks, Press-to-Close, Heat Seal, Resealable |
| Companies Covered | Amcor PLC, Mondi PLC, Sonoco Products Company, Constantia Flexibles GmbH, Sacia Flex Italy, PackStyle s.r.l., Sudpack Holding GmbH, ACM S.p.A, Gualapack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Pouch Packaging Market Trends and Innovations
Material science advances and regulatory compliance pressures are converging to redefine performance benchmarks across Italian pouch converting, with sustainability credentials now inseparable from functional barrier properties.
Separable paper-plastic laminates are hybridizing conventional pouch performance with end-of-life recyclability. Food brands in the premium pasta and specialty sauce segments are adopting these structures at pilot scale ahead of anticipated EU recycled content mandates. The technology is hybridizing what were previously distinct supply chains for fiber-based and polymer-based packaging.
Italy's implementation of CONAI fee differentiation based on recyclability is forcing explicit design-for-recycling documentation across all pouch formats placed on the market. Industrial consequence includes mandatory material passports and third-party recyclability assessments for imported films. Northern Italian converters serving export-oriented food brands are most affected, responding with in-house testing laboratories and pre-certified substrate libraries.
Brand procurement teams are consolidating supplier panels around converters with integrated sustainability verification capabilities. Regional food brands previously sourcing through distributors are now contracting directly with certified converters to secure CONAI compliance documentation. This pattern is most visible in the Emilia-Romagna agri-food cluster, where cooperative brands demand batch-level traceability for export to German and French retail chains.
Italy Pouch Packaging Market Segmentation
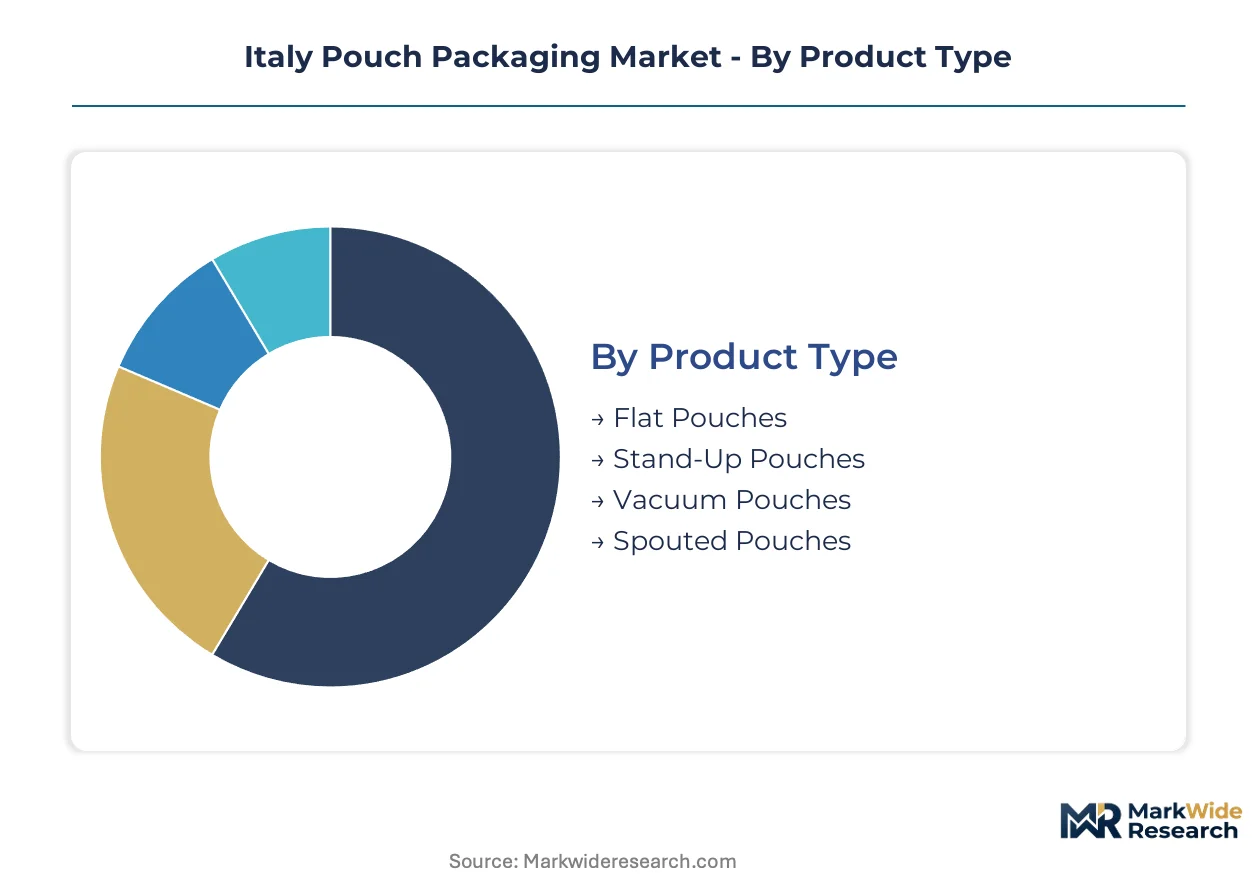
Segmentation in the Italy pouch packaging market reveals how CONAI compliance costs and shelf-ready format requirements split demand across material and structural choices. Each dimension carries distinct certification burdens and converting equipment requirements that shape supplier selection.
Product Type:
Mature formats dominate current throughput while emerging structures capture reformulation-driven switching.
- Stand-Up Pouches:Gusseted bottom structures with multi-layer barrier laminates provide vertical shelf stability for liquid and granular products. Pasta sauce and ready-meal brands in Emilia-Romagna specify these formats for retail-ready presentation despite higher CONAI fees on plastic-intensive constructions.
- Flat Pouches:Two-dimensional sealed envelopes with single or dual-layer construction serve dried pasta, coffee, and snack applications. Northern Italian converters run these at highest line speeds, though demand is plateauing as brands migrate toward stand-up alternatives for premium positioning.
- Vacuum Pouches:High-barrier coextruded or laminated films with oxygen transmission rates below 1 cc/m²/day preserve cured meats and aged cheeses. Parma and Modena processing clusters specify these for export-grade prosciutto and Parmigiano-Reggiano.
- Spouted Pouches:Fitment-attached formats for pourable sauces and baby food represent the fastest-moving innovation tier, with Campania and Sicily dairy brands piloting adoption ahead of retail modernization.
Stand-up pouches handle the majority of throughput; spouted pouches are the fastest mover on share.
Materials:
Cost tier stratification separates commodity substrates from compliance-premium alternatives.
- Composites:Paper-plastic hybrid laminates with separable layers enable mechanical recycling under CONAI fee structures. These structures require specialized tension control during converting but command procurement preference from export-oriented food brands supplying German and French retail chains.
- Plastic:Polyethylene, polypropylene, and polyester mono- or multi-layer films remain the volume baseline despite regulatory pressure. Legacy lines across Milan-Bologna corridors process these at lowest unit cost, though converters face differentiated fees for non-recyclable multi-polymer combinations.
- Paper:Fiber-based substrates with barrier coatings are displacing plastic in dry food segments. Italian kraft paper supply from Mondi's domestic operations supports regional sourcing, though moisture sensitivity limits application scope.
- Aluminum:Foil laminates provide absolute barrier for pharmaceutical and retort applications. Energy-intensive production exposes converters to electricity price volatility that compresses margin on pharma-grade formats.
Plastic retains the highest volume position; composites are climbing the fastest on regulatory-driven substitution.
End User:
Application-specific certification requirements fragment supplier relationships across customer types.
- Food & Beverage:Shelf-ready pasta, sauce, and preserved vegetable packaging drives the largest demand block. Brands in the Po Valley agri-food cluster require batch-level traceability and CONAI documentation for export compliance.
- Pharmaceuticals:High-integrity pouches with tamper-evidence and serialization surfaces serve track-and-trace mandates. Constantia Flexibles anchors European supply from Italian operations for this segment.
- Personal Care:Cosmetic and hygiene product pouches prioritize aesthetic surface printing and dispensing functionality. Short-run digital printing capabilities from specialized converters support regional brand launches.
- Household Products:Detergent and cleaning chemical pouches emphasize chemical resistance and child-resistant closures. Concentrated refill formats are gaining traction in sustainability-focused retail channels.
Food and beverage handles the majority of throughput; pharmaceuticals maintains the steepest expansion trajectory on serialization mandate expansion.
Closure Type:
Volume scale separates high-throughput permanent seals from value-added resealable alternatives.
- Heat Seal:Permanent fusion closures via impulse or constant heat sealing dominate commodity throughput. Legacy converting assets across Turin-Milan corridors are optimized for these formats at lowest unit cost.
- Zip Locks:Interlocking plastic profiles enable repeated opening and closing for multi-use food products. Premium pasta and snack brands specify these for convenience differentiation despite component cost premiums.
- Press-to-Close:Simplified resealable mechanisms with lower profile than zip locks serve mid-tier positioning. These formats balance reseal functionality with line speed compatibility.
- Resealable:Broad category encompassing adhesive strips and mechanical closures for flexible end-use adaptation. Innovation focuses on mono-material compatibility for recycling stream acceptance.
Heat seal handles the majority of throughput; zip locks are gaining share fastest on convenience-premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CONAI's extended producer responsibility framework is redistributing converting capacity across Italy's industrial geography, with northern corridors absorbing compliance investment while southern regions present untapped shelf-ready format opportunities.
Lombardy
Milan's logistics hub anchors high-throughput converting for export-oriented food brands. The region's concentration of pharmaceutical serialization mandates drives demand for tamper-evident pouch formats. Converters around Bergamo and Brescia operate just-in-time film supply networks serving German and French retail chains.
Emilia-Romagna
Pasta sauce and ready-meal manufacturers in Bologna and Modena specify stand-up pouches for retail-ready presentation. Parma's cured meat processing cluster sources vacuum pouches with oxygen transmission rates below 1 cc/m²/day. The regional agri-food cooperative network demands batch-level traceability documentation for cross-border compliance.
Piedmont
Turin's automotive-to-packaging industrial transition supports precision converting equipment manufacturing. The city's engineering base supplies tension-control systems for paper-plastic hybrid lamination. Local converters serve premium coffee brands migrating from flat to stand-up formats.
Veneto
Verona and Vicenza host specialized pharma-grade pouch operations serving EMA-tracked serialization requirements. The region's chemical coating supply chain supports water-based barrier formulation development. Wine and prosecco brands pilot paper-based pouch formats for single-serve hospitality channels.
Campania
Naples and Salerno represent emerging demand for spouted pouches in dairy and sauce categories ahead of retail modernization. Southern Italy's underpenetrated shelf-ready format adoption creates first-mover positioning for converters with digital printing-web handling capabilities. Local preserved vegetable processors test separable paper-plastic laminates for export compliance.
Italy Pouch Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around converters with integrated sustainability verification and design-for-recycling capabilities. Tiered competitive positioning separates vertically integrated multinational film producers, specialized regional converters with digital printing assets, and commodity importers facing CONAI documentation barriers. Dominant competitive moves include backward integration into barrier coating chemistry and strategic partnerships with northern Italian agri-food cooperatives for direct procurement relationships.
Within the multinational integrated tier, Mondi PLC exemplifies upstream control over kraft paper and barrier coating supply chains. Among specialized regional operators, Sacia Flex Italy occupies a position between mass converters and commodity imports through short-run digital printing capabilities. Constantia Flexibles GmbH anchors European pharma-grade pouch supply from its Italian operations, representing the high-integrity serialization-compliant archetype.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi PLC |
| Sonoco Products Company |
| Constantia Flexibles GmbH |
| Sacia Flex Italy |
| PackStyle s.r.l. |
| Sudpack Holding GmbH |
| ACM S.p.A |
| Gualapack |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Austrian barrier coating chemistries compresses margin tiers while dictating northern Italian converter clustering around Milan-Bologna logistics corridors. CONAI fee differentiation simultaneously widens pricing spreads between certified recyclable formats and legacy multi-layer plastics, reshaping procurement patterns toward documented supply chains.
Pricing Analysis
Certification level (CONAI-compliant versus legacy non-recyclable) creates the primary spread between premium and commodity tiers. Three-tier pricing structure separates pharma-grade serialization-compliant pouches, food-grade separable laminates, and standard multi-layer plastics. Cost compression in aluminum-intensive retort formats is intensifying because energy-intensive foil production exposes converters to electricity price swings. Regional food brands in Emilia-Romagna exhibit highest price sensitivity, while pharmaceutical serialization mandates render that segment least sensitive.
Supply Chain Analysis
Tariff exposure between Germany and Italy dominates raw material cost volatility for specialized water-based coatings. Supply concentrates in Germany, Austria, and domestic northern Italian film extrusion corridors. The converting ecosystem draws from kraft paper suppliers, polymer resin distributors, and narrow-base coating chemistry providers. Single-source vulnerability in barrier formulation creates chokepoint risk. Distribution runs through just-in-time networks serving Milan-Bologna-Turin industrial clusters with same-day turnaround.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pending EU Packaging and Packaging Waste Regulation revisions constitute a regulatory inflection that will mandate minimum recycled content thresholds, compressing development timelines and rewarding early design-to-recycle investment.
For Market Incumbents: Build certification moats through in-house recyclability testing laboratories and pre-certified substrate libraries. Capture CONAI documentation workflows to lock regional food brand direct procurement relationships. Defend against commodity import erosion by anchoring northern Italian cooperative networks with batch-level traceability capabilities. For New Entrants and Emerging Players: Pursue digital printing-web handling convergence to collapse minimum order quantities for Campania and Sicily dairy brands. Target southern Italy's underpenetrated shelf-ready format adoption ahead of retail modernization. Enter through spouted pouch pilot programs with preserved vegetable processors seeking export compliance documentation. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation reshapes the acquisition landscape toward converters with integrated sustainability verification. Five-to-ten-year viability favors targets with backward integration into barrier coating chemistry or captive kraft paper supply. Monitor CONAI fee structure amendments as the signal indicating acceleration of paper-plastic hybrid substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Design-for-Recycling Certification Investment | CONAI compliance documentation becomes mandatory passport for Italian market access. |
| Digital Printing-Web Handling Integration | Inkjet deposition with rotary forming collapses minimum order quantities for regional brands. |
| Southern Italy Distribution Expansion | Campania retail modernization creates first-mover positioning in pasta and sauce categories. |
| Backward Integration into Barrier Coatings | German-Austrian supplier concentration creates vulnerability for non-integrated converters. |
| Pharmaceutical Serialization Line Addition | EMA track-and-trace mandates expand addressable market for high-integrity formats. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CONAI regulatory filings, EU Packaging and Packaging Waste Regulation drafts, and Italian agri-food export statistics. Primary interviews engaged pouch converting plant managers, procurement leads at Emilia-Romagna food cooperatives, barrier coating R&D directors, and northern Italian distribution channel partners. Secondary sources included customs trade data, CONAI annual reports, and SEC filings from listed packaging multinationals. Bottom-up volume triangulation against top-down value estimates validated segment splits.
Forecast inputs span material substitution rates under CONAI fee structures, pharmaceutical serialization mandate expansion, and southern Italy retail modernization velocity. Segmentation dimensions modeled include product type, material construction, end-use vertical, closure mechanism, and regional production cluster. CAGRs derive from regression against historical substitution elasticities and regulatory compliance cost trajectories. Industry-specific inputs incorporate paper-plastic hybrid adoption curves and digital printing penetration rates.
Sensitivities concentrate around EU Packaging and Packaging Waste Regulation implementation timing and CONAI fee recalibration schedules. Forecasts reflect assumptions on mechanical recycling infrastructure deployment and coating chemistry supplier capacity expansion. Material shifts in regulatory stringency or aluminum energy cost trajectories would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
MAP Flow Wrappers Market
Pouch
Heat Seal Pouch Market
Pouch
Utility Pouches Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Europe Pouch Packaging Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Vietnam Pouch Packaging Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Portion Control Packs Market
Pouch
Bio PE Pouches Market
Pouch
Flat Bottom Pouch Market
Pouch
Monodose Packs Market
Pouch
Latin America Pouch Packaging Market
Pouch
Poland Pouch Packaging Market
Pouch
Retort Pouch Packaging Market