
 Polyethylene Terephthalate-Glycol (PETG) Market | 2026-2036
Polyethylene Terephthalate-Glycol (PETG) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Terephthalate-Glycol (PETG) Market Analytics
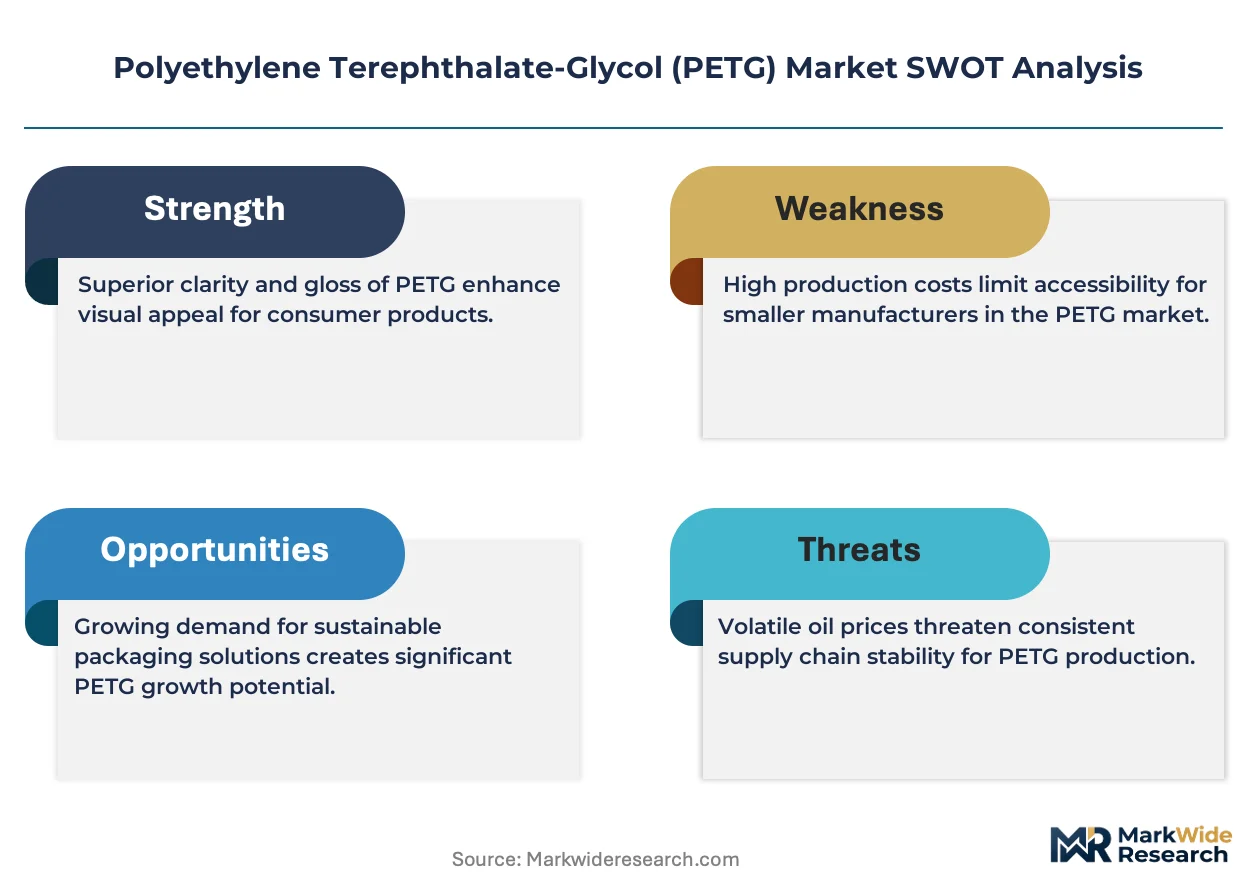
ISO 10993 biocompatibility certification is redrawing competitive boundaries in medical-grade PETG supply. Eastman leverages its Eastar copolyester platform to sustain leadership in sterilizable healthcare packaging across North American hospitals. SK Chemical anchors Asian supply through proprietary CHDM-modified resin technology, while Selenis competes in European extrusion markets with specialized glycol-enhanced formulations for pharmaceutical blister packs.
Polyethylene Terephthalate-Glycol is a glycol-modified polyethylene terephthalate copolyester produced by substituting cyclohexanedimethanol for a portion of ethylene glycol, yielding amorphous clarity, toughness, and thermoformability at processing temperatures below degradation thresholds. The material serves primarily as a drop-in replacement for polycarbonate and PVC in applications demanding optical transparency plus chemical resistance without bisphenol-A or plasticizer concerns. Clear PETG dominates packaging applications where visual product inspection drives material selection, while Medical Grade PETG commands premium positioning as FDA and EU MDR tighten qualification cycles for device housings and tray systems. Food Grade PETG maintains volume leadership in retail clamshell and blister formats, though Recyclable Grade formulations are gaining traction where brand owners face extended producer responsibility mandates.
FDA enforces 21 CFR 177.1315 for food-contact polyesters, while EU REACH and MDR frameworks restrict phthalate alternatives and mandate clinical evaluation of device materials, directly shaping PETG formulation roadmaps. China's NMPA and GB standards for medical plastics are converging toward ISO harmonization, creating dual-qualification burdens for multinational suppliers. Stakeholders must monitor how divergent biocompatibility testing protocols between FDA, EMA, and NMPA reshape regional sourcing strategies and capital allocation for dedicated production lines.
Market Dynamics
Medical device sterilization protocols are forcing PETG formulation upgrades as gamma and e-beam radiation exposure degrades standard copolyester clarity, compelling resin suppliers to invest in stabilized glycol-modified variants that withstand terminal sterilization without yellowing or embrittlement.
Growth Catalysts
- EU MDR material traceability:The European Union's Medical Device Regulation mandates device-level material documentation, accelerating hospital procurement of pre-qualified PETG tray systems over incumbent PVC alternatives.
- China NMPA harmonization:China's National Medical Products Administration is converging biocompatibility testing with ISO 10993 standards, reducing dual-qualification burdens and unlocking import substitution opportunities for domestic PETG converters.
- Cyclohexanedimethanol supply expansion:CHDM monomer capacity additions in East Asia are compressing raw material costs for glycol-modified polyester production, improving PETG cost parity against polycarbonate in transparent packaging.
Market Restraints
- Ethylene glycol price volatility:Crude oil-linked feedstock swings destabilize PETG resin pricing, squeezing converter margins and deterring long-term supply contracts in food packaging applications.
- Korean CHDM concentration:Over half of global cyclohexanedimethanol supply originates from Korean petrochemical complexes, creating single-point vulnerability for glycol-modified polyester manufacturers worldwide.
- Amorphous structure limits:PETG's non-crystalline morphology restricts continuous-use temperatures below 70°C, excluding the material from hot-fill pharmaceutical and autoclave-sterilized device applications where polycarbonate dominates.
Strategic Opportunities
- Indian medical packaging underpenetration:India's CDSCO is streamlining medical device registration, creating first-mover advantage for PETG tray suppliers establishing local thermoforming operations ahead of domestic capacity buildout.
- Chemical recycling feedstock:Glycol-modified polyesters depolymerize more readily than crystalline PET, positioning PETG as preferred input for enzymatic recycling ventures targeting pharmaceutical blister pack waste streams.
- US IRA domestic content incentives:The Inflation Reduction Act's domestic manufacturing credits favor US-based medical packaging production, rewarding PETG converters with qualified domestic supply chains for hospital system contracts.
Industry Challenges
- ISO 10993-18 analytical chemist scarcity:Extractables and leachables testing for medical-grade PETG requires specialized toxicological expertise that resin suppliers and converters struggle to recruit and retain.
- Legacy PVC equipment retrofit costs:Thermoformers transitioning from plasticized vinyl to PETG face substantial mold redesign and heating system upgrades to accommodate higher forming temperatures and different shrinkage characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Terephthalate-Glycol (PETG) Market |
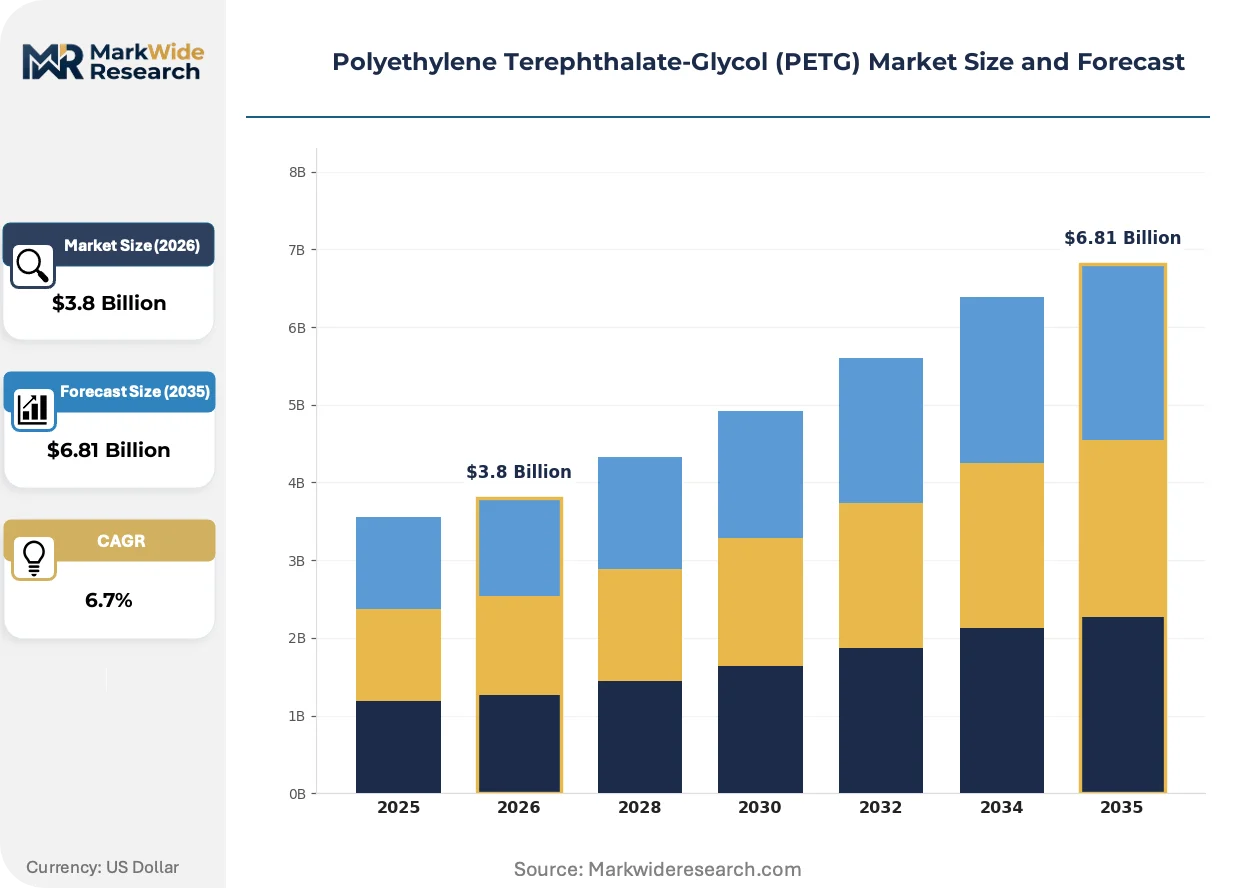
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear PETG, Colored PETG, High-Heat PETG, Anti-Fog PETG Application: Packaging, Medical Devices, Consumer Goods, Automotive Components Grade: Food Grade, Industrial Grade, Medical Grade, Recyclable Grade End User: Food & Beverage, Healthcare, Retail, Industrial Manufacturing |
| Companies Covered | Jiangsu Jinghong, Huahong Chemical Fiber, Eastman, China Resources Chemical Materials, Dragon Special Resin, SK Chemical, Liaoyang Petrochemical, Henan Yinjinda New Materials, Selenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Terephthalate-Glycol (PETG) Market Evolving Landscape
Active pharmaceutical packaging is driving PETG innovation as moisture-sensitive biologics require barrier-enhanced transparent materials that combine visual inspection capability with functional protection previously delivered by opaque laminates.
Advanced glycol stabilization chemistry is decomposing traditional tradeoffs between sterilization resistance and optical clarity in medical-grade copolyesters. Major hospital purchasing consortiums in Germany and the United States are specifying radiation-stable PETG for implantable device kits. This technology compression is decomposing polycarbonate's historical lock on high-value sterile barrier applications where yellowing after gamma exposure previously disqualified polyester alternatives.
EU REACH restrictions on intentionally added microplastics are tightening scrutiny of polymer fragmentation in healthcare waste streams. The European Chemicals Agency's 2023-2025 evaluation timeline threatens additional reporting obligations for single-use medical plastics including PETG device trays. German and French hospital systems are responding by pre-qualifying suppliers with documented end-of-life collection partnerships and chemical recycling offtake agreements.
Brand-owner sustainability scorecards are reshaping material selection in consumer packaging. Major retail chains in the United States and United Kingdom now require percentage recycled content disclosures that PETG struggles to meet given limited glycol-modified polyester recycling infrastructure. This specification pressure is compressing virgin resin premiums and redirecting converter investment toward mechanical recycling compatibility and monomer recovery process development.
Polyethylene Terephthalate-Glycol (PETG) Market Segmentation
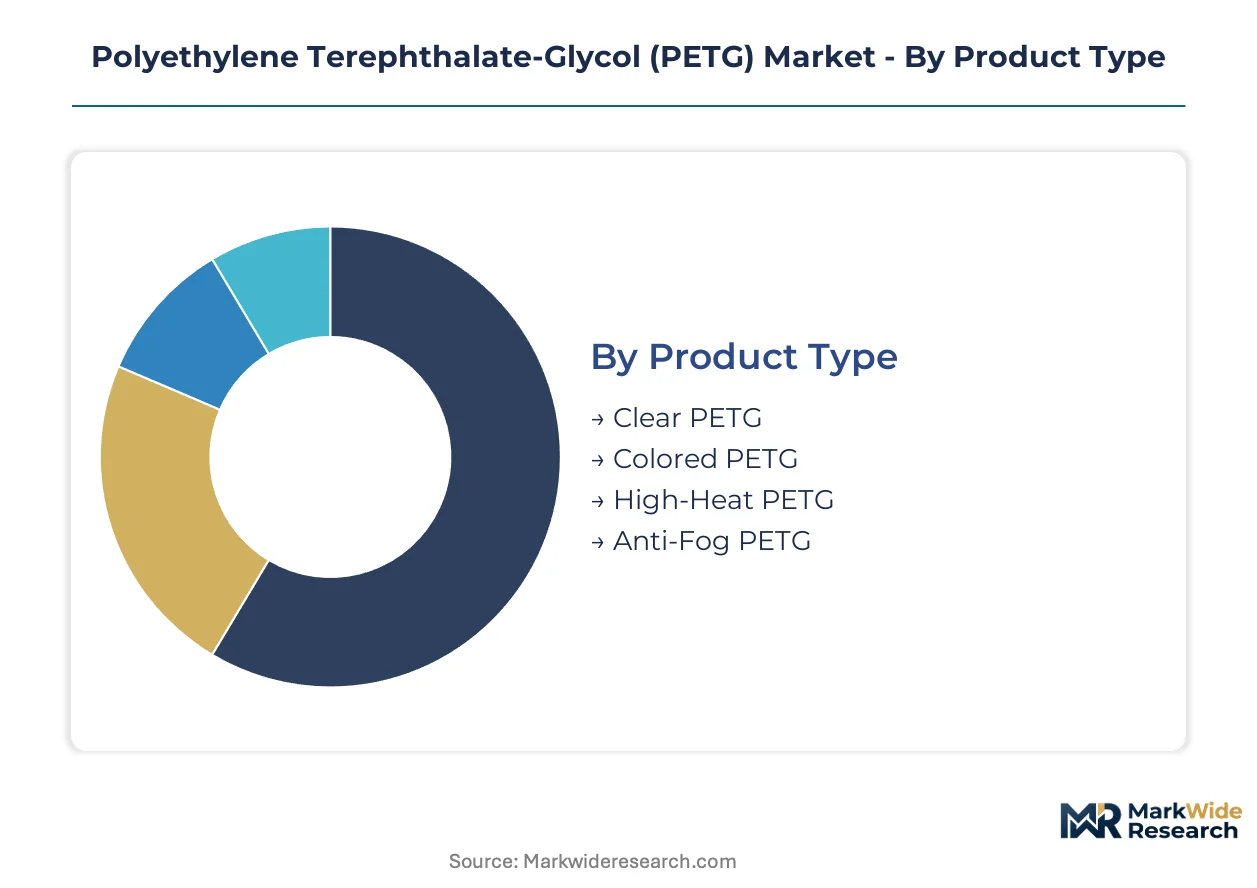
PETG segmentation reveals how glycol-modified polyester suppliers allocate technical development resources across performance tiers. Material grade and end-use specifications determine qualification protocols, sterilization compatibility, and pricing power in this copolyester market.
Product Type:
Margin pools concentrate in specialty formulations that solve processing or performance constraints standard PETG cannot address.
- Clear PETG:Amorphous glycol-modified polyester delivering optical transparency exceeding 90% light transmission. Demand concentrates in United States retail clamshell packaging where Walmart and Target sustainability scorecards favor bisphenol-A-free alternatives to polycarbonate.
- Colored PETG:Pigmented copolyester variants formulated for consistent hue stability across thermoforming temperature ranges. Cosmetic brands in Germany specify colored PETG for premium skincare packaging where visual differentiation commands shelf price premiums.
- High-Heat PETG:CHDM-enhanced formulations pushing continuous-use temperatures toward 85°C through modified glycol ratios. Automotive interior applications in China specify this grade for dashboard components requiring thermal stability.
- Anti-Fog PETG:Surface-modified copolyester with hydrophilic coatings preventing condensation in refrigerated display cases. Fresh produce packaging in France drives adoption where mist-free visibility influences purchase decisions.
The dominant share belongs to Clear PETG, while High-Heat PETG is closing the gap fastest.
Application:
Application segmentation tracks how PETG displaces incumbent materials through regulatory pressure and performance equivalence.
- Packaging:Thermoformed trays, blister packs, and clamshells exploiting PETG's toughness and clarity without plasticizer migration risks. FDA 21 CFR 177.1315 compliance positions this application for food-contact expansion.
- Medical Devices:Sterilizable barrier systems and device housings requiring ISO 10993 biocompatibility certification. EU MDR material traceability mandates are accelerating hospital procurement of pre-qualified PETG tray systems over PVC alternatives.
- Consumer Goods:Durable transparent housings for electronics and sporting equipment where impact resistance exceeds standard acrylic capabilities.
- Automotive Components:Interior trim and lighting lenses requiring UV stability and dimensional precision across temperature cycling.
Packaging maintains volume leadership, though Medical Devices delivers the steepest expansion trajectory.
Grade:
Grade differentiation reflects regulatory burden intensity and extractables testing requirements.
- Food Grade:Compliant with FDA food-contact regulations and EU 10/2011 migration limits for plastics in food contact. Retail chains in the United Kingdom now mandate percentage recycled content disclosures that this grade struggles to meet.
- Medical Grade:ISO 10993-certified copolyester with documented biocompatibility and sterilization stability. Gamma and e-beam radiation exposure degrades standard PETG clarity, compelling resin suppliers to invest in stabilized glycol-modified variants.
- Industrial Grade:General-purpose PETG for non-critical applications prioritizing cost over certification documentation.
- Recyclable Grade:Formulations optimized for mechanical recycling compatibility and monomer recovery processes. EU REACH restrictions on intentionally added microplastics are tightening scrutiny of polymer fragmentation in waste streams.
Food Grade retains the largest installed base, while Recyclable Grade is gaining specification momentum fastest.
End User:
End user segmentation maps procurement sophistication and qualification cycle length.
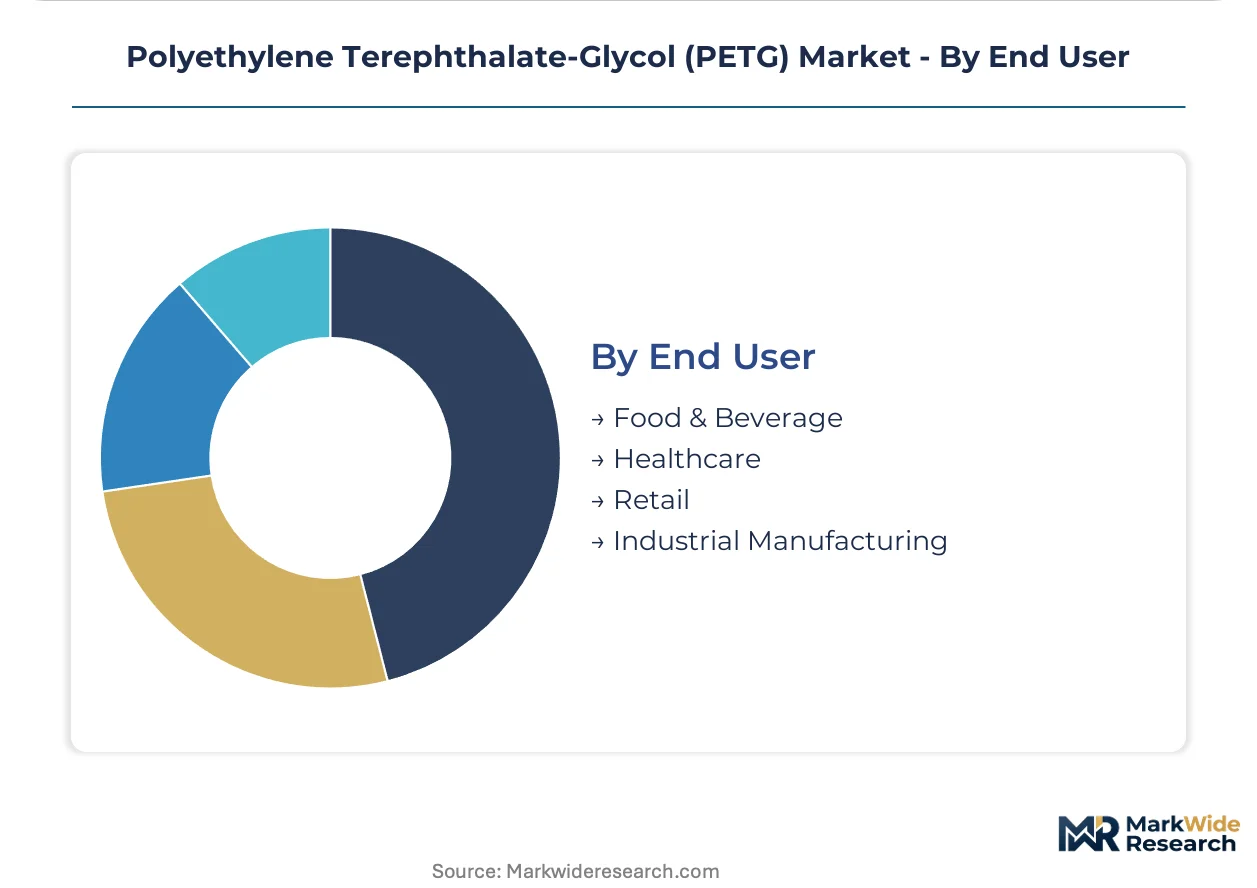
- Food & Beverage:Brand owners and contract packagers demanding optical clarity plus extended shelf-life protection. China's NMPA harmonization with ISO standards is reducing dual-qualification burdens for multinational suppliers.
- Healthcare:Hospital systems and device manufacturers requiring sterilizable barrier materials with full material documentation. The Inflation Reduction Act's domestic manufacturing credits favor US-based medical packaging production.
- Retail:Private-label and national brand merchandisers specifying transparent packaging for visual product inspection.
- Industrial Manufacturing:OEMs integrating PETG components into equipment and machinery where chemical resistance matters.
Food & Beverage commands the deepest volume, though Healthcare generates the highest margin per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and retail chains concentrate PETG procurement in jurisdictions with stringent material qualification protocols. The United States, Germany, and China anchor demand through converging regulatory investments and manufacturing scale.
United States
Hospital purchasing consortiums specify radiation-stable PETG for implantable device kits. The Inflation Reduction Act's domestic manufacturing credits reward converters with qualified domestic supply chains. Eastman anchors production in Tennessee through its Eastar copolyester platform.
Germany
Cosmetic brands specify colored PETG for premium skincare packaging where visual differentiation commands shelf price premiums. EU MDR material traceability mandates accelerate hospital procurement of pre-qualified tray systems. Selenis competes in European extrusion markets with specialized glycol-enhanced formulations.
China
Automotive interior applications specify high-heat PETG for dashboard components requiring thermal stability. NMPA harmonization with ISO 10993 standards reduces dual-qualification burdens for multinational suppliers. Jiangsu and Liaoyang petrochemical clusters host domestic resin production capacity.
India
CDSCO streamlining of medical device registration creates first-mover advantage for PETG tray suppliers establishing local thermoforming operations. Fresh produce packaging drives anti-fog grade adoption where mist-free visibility influences purchase decisions. Gujarat and Maharashtra host emerging converter investments.
South Korea
CHDM monomer capacity additions compress raw material costs for glycol-modified polyester production. Over half of global cyclohexanedimethanol supply originates from Korean petrochemical complexes. SK Chemical anchors Asian supply through proprietary CHDM-modified resin technology.
Polyethylene Terephthalate-Glycol (PETG) Market Competitive Landscape
Player mix skews toward petrochemical conglomerates with captive CHDM supply and specialized copolyester divisions. Market structure concentrates around integrated resin producers capable of ISO 10993 certification documentation. Three archetypes dominate: Korean CHDM-integrated suppliers, US-based healthcare packaging specialists, and Chinese state-affiliated petrochemical groups. Competitive moves center on capacity expansion in glycol-modified variants and strategic partnerships with thermoforming converters.
Among Korean CHDM-integrated suppliers, SK Chemical exemplifies the technology-licensing archetype through proprietary resin platforms. Eastman occupies a position within the healthcare certification tier, representing US-based qualification depth. Chinese state-affiliated groups including Jiangsu Jinghong and Liaoyang Petrochemical anchor the volume-driven segment, exemplifying scale-oriented positioning in Asian packaging markets.
| Leading Market Players |
|---|
| Jiangsu Jinghong |
| Huahong Chemical Fiber |
| Eastman |
| China Resources Chemical Materials |
| Dragon Special Resin |
| SK Chemical |
| Liaoyang Petrochemical |
| Henan Yinjinda New Materials |
| Selenis |
| Others |
Value Network & Pricing Analysis
CHDM substitution for ethylene glycol in glycol-modified polyester production simultaneously redraws supply geography toward Korean petrochemical corridors and compresses raw material cost structures that determine converter margin sustainability across medical and food packaging tiers.
Pricing Analysis
Cost-plus contracts with ethylene glycol indexation dominate resin procurement between Korean CHDM producers and Asian converters. Price differentiation separates ISO 10993-certified medical grades from standard food-contact formulations, with certification documentation commanding substantial premiums. Pricing pressure stems from crude oil-linked feedstock volatility squeezing converter margins in high-volume retail clamshell applications. Food and beverage brand owners exhibit highest price sensitivity, while hospital purchasing consortiums prioritize sterilization stability over unit cost.
Supply Chain Analysis
Inbound logistics costs from Korean ports through Shanghai and Busan trade lanes expose glycol-modified polyester converters to container availability swings and terminal congestion. Raw material supply draws from Korean CHDM complexes, Chinese ethylene glycol crackers, and Southeast Asian glycol feedstock terminals. Single-source vulnerability concentrates in cyclohexanedimethanol production anchored by SK Chemical and affiliated Korean petrochemical groups. Distribution runs through regional thermoforming hubs in Tennessee, Jiangsu, and North Rhine-Westphalia serving hospital systems and retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in extractables and leachables testing documentation expand faster than virgin resin sales as FDA and EU MDR tighten material qualification protocols for device manufacturers.
For Market Incumbents: Consolidate captive CHDM supply through backward integration into Korean or Chinese monomer production, and deepen hospital system partnerships with pre-qualified tray systems that lock out PVC alternatives. Eastman and SK Chemical face emerging pressure from Chinese state-affiliated resin producers scaling glycol-modified capacity. For New Entrants and Emerging Players: Technical service gaps in ISO 10993-18 analytical chemistry and extractables documentation present white-space targets where incumbent resin suppliers under-resource toxicological expertise. India's CDSCO streamlining offers the most penetrable geography for thermoforming operations ahead of domestic capacity buildout. Lead with regulatory qualification services bundled with resin supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European thermoforming specialists possessing hospital system contracts but lacking captive resin supply. Long-term viability over a five-to-ten year horizon depends on chemical recycling feedstock positioning as EU REACH microplastic restrictions tighten. Monitor ECHA evaluation timelines for healthcare polymer fragmentation rules as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CHDM Production | Captive monomer supply secures margin control against Korean concentration risk. |
| ISO 10993-18 Testing Laboratory Acquisition | In-house toxicological expertise accelerates medical-grade qualification cycles for device trays. |
| Chemical Recycling Feedstock Partnership | Enzymatic depolymerization ventures position PETG as preferred pharmaceutical blister pack input. |
| Hospital System Long-term Supply Agreement | Pre-qualified tray contracts lock out PVC alternatives under EU MDR traceability mandates. |
| Indian Thermoforming Facility Establishment | CDSCO registration streamlining creates first-mover manufacturing footprint ahead of domestic competition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR filings, EU MDR technical documentation, Korean petrochemical trade data, and hospital procurement databases. Interviews with resin plant managers, thermoforming procurement leads at medical device OEMs, GPO contracts managers, and regulatory affairs directors informed supply-side and demand-side validation. Bottom-up resin capacity modeling triangulates against top-down packaging demand estimates across food, medical, and industrial end uses.
Segmentation dimensions modeled span grade tier (food, medical, industrial, recyclable), application (packaging, devices, consumer goods, automotive), and regional production hub (United States, Germany, China, South Korea, India). CAGRs derive from ethylene glycol price elasticity analysis, CHDM capacity expansion schedules, and sterilization protocol adoption curves in hospital systems. Forecast inputs incorporate EU REACH microplastic restriction timelines and NMPA harmonization progress with ISO 10993 standards.
Underlying assumptions cover continued crude oil linkage for ethylene glycol feedstock pricing, stable Korean CHDM supply concentration, and progressive EU MDR enforcement without regulatory rollback, with deviation risk concentrated in feedstock price volatility and trade lane disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Disposable Straw Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Canada Plastic Packaging Market