
 Pouches Market | 2026-2036
Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Pouches Market Intelligence
Mono-material polyethylene structures is rewriting the engineering priorities across converting operations. Amcor plc leverages its global film extrusion network to anchor supply of recyclable laminates. Mondi Group specializes in paper-based barrier solutions that compete with conventional multi-layer films. ProAmpac sustains R&D intensity in high-speed form-fill-seal compatibility.
Pouches are flexible containment vessels fabricated from single or laminated substrates, typically ranging from 50 to 150 microns in total caliper, designed to protect, display, and dispense consumer and industrial goods. Stand-up pouches dominate value pools due to shelf differentiation and expanded printable surface area. Biodegradable films represent the fastest-growing material class as European brand owners face EPR fee restructuring. Spouted pouches capture premium positioning in liquid and semi-liquid applications where controlled dispensing commands price premiums.
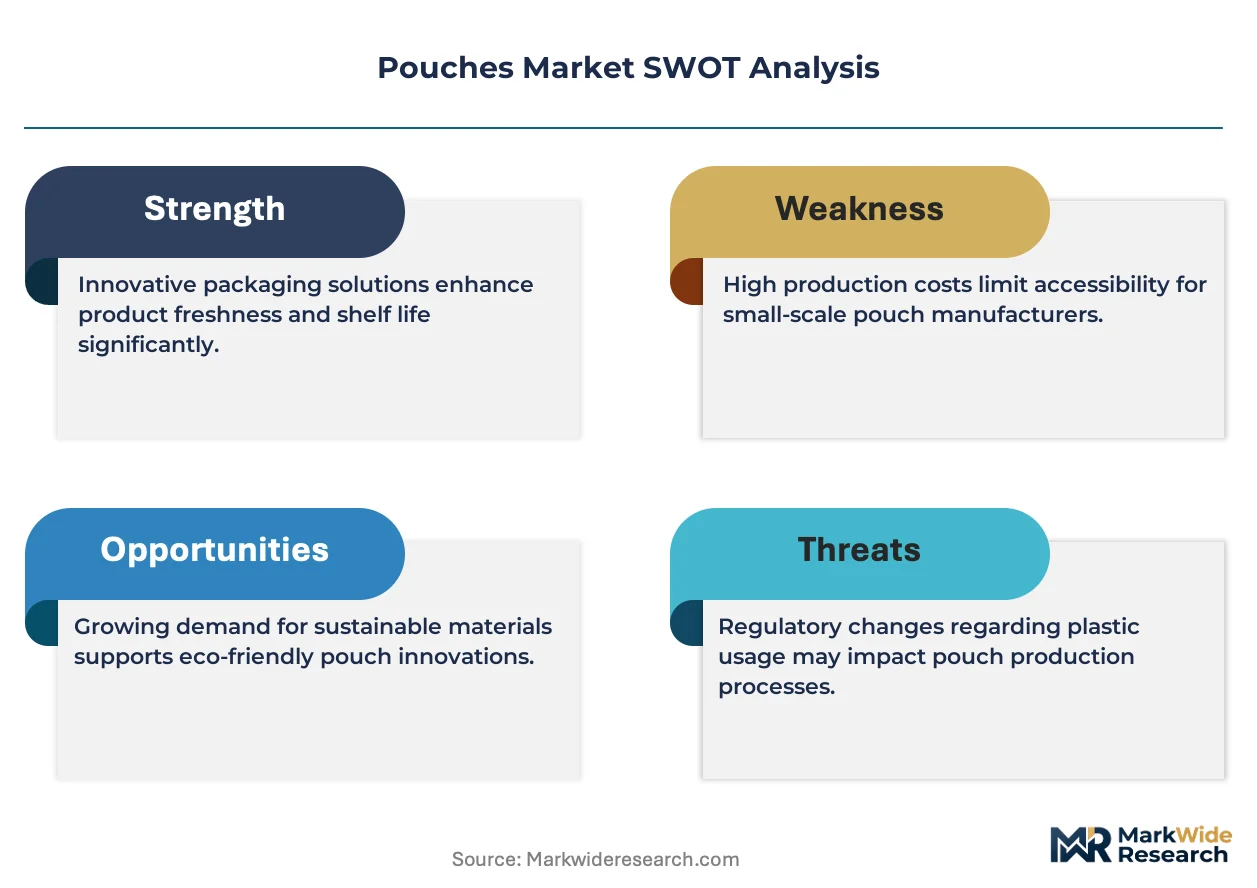
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications govern material compliance and market access across the Atlantic. ECHA REACH restrictions on perfluorinated substances are forcing reformulation of grease-resistant barrier coatings. Stakeholders must monitor recyclability certification thresholds as sorting infrastructure investments in France and Italy determine which material platforms achieve circular economy compliance.
Market Dynamics
Mono-material polyethylene structures are collapsing the established multi-layer laminate paradigm across converting operations, forcing capital redeployment toward recyclable extrusion lines and barrier coating R&D.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability thresholds are compelling brand owners to redesign legacy multi-layer pouches into mono-material formats compatible with existing sorting infrastructure.
- Ready-to-eat meal proliferation:Convenience food manufacturers in Germany and France are retrofitting retort-capable filling lines to accommodate high-barrier stand-up pouches.
- Spouted pouch premiumization:Controlled dispensing formats command price premiums in liquid and semi-liquid applications across infant nutrition and household cleaning segments.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin prices fluctuate with naphtha-cracker margins, compressing converter margins on fixed-price annual contracts.
- Barrier coating technical limitations:Water-based and bio-based barrier layers still fail to match aluminum-oxide metallization performance in oxygen transmission rates.
- Sorting infrastructure fragmentation:Inconsistent near-infrared detection capabilities across French and Italian recycling facilities block circular economy certification for certain mono-material variants.
Strategic Opportunities
- EPR fee restructuring in Germany:Extended producer responsibility schemes now penalize non-recyclable multi-layer structures, creating first-mover advantage for certified mono-material suppliers.
- Paper-based barrier convergence:Fiber-based pouches with bio-polymer coatings are penetrating dry goods segments where moisture sensitivity is moderate.
- E-commerce fulfillment channel innovation:Lightweight flexible formats reduce dimensional weight shipping penalties versus rigid alternatives in direct-to-consumer distribution.
Industry Challenges
- High-speed form-fill-seal compatibility gaps:Mono-material films exhibit different heat-seal initiation temperatures and seal strengths, requiring line-speed recalibration and operator retraining.
- REACH compliance timeline compression:ECHA restrictions on perfluorinated substances demand rapid reformulation of grease-resistant coatings without full validation of replacement chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pouches Market |
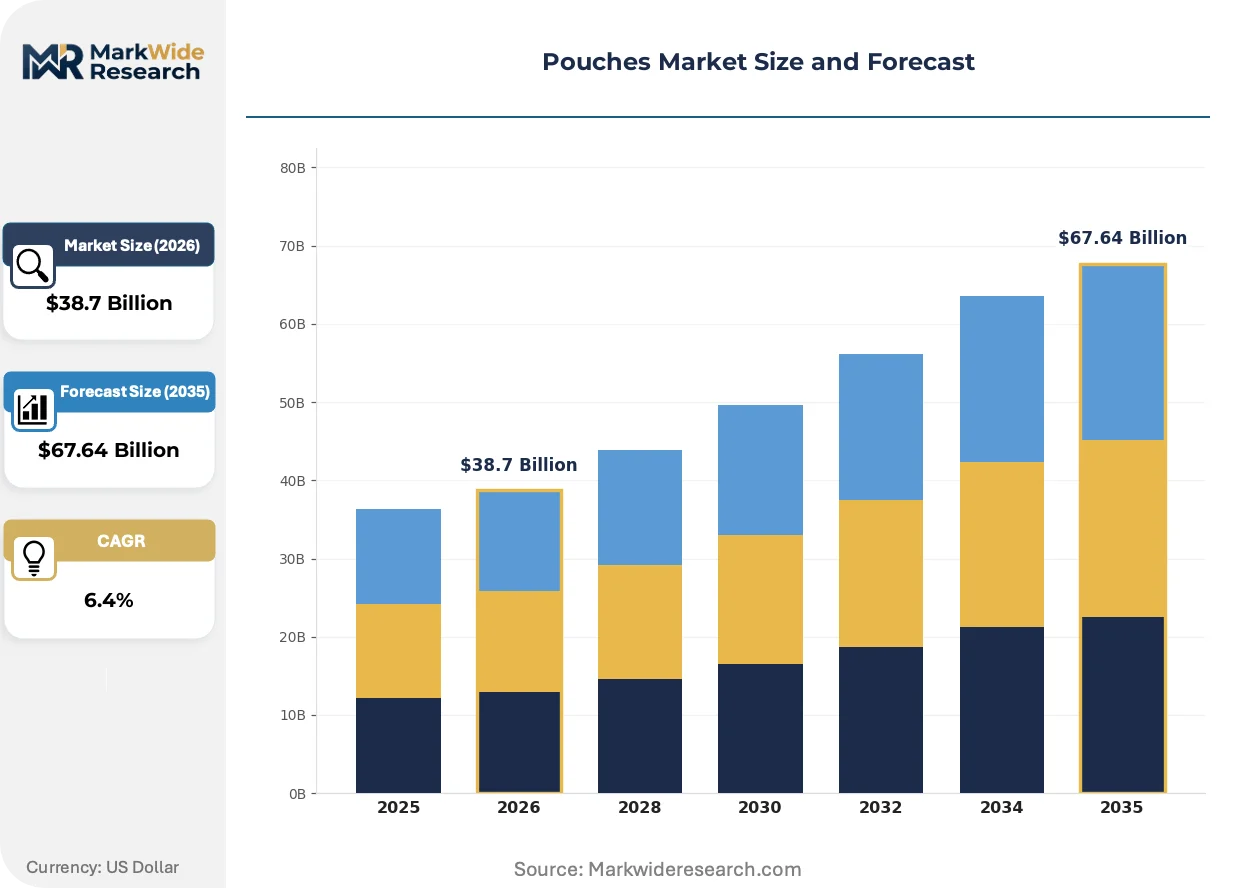
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Spouted Pouches, Gusseted Pouches Material: Plastic, Paper, Aluminium, Biodegradable Films Closure Type: Zipper, Heat Seal, Tear Notch, Press Seal Industry Vertical: Food & Beverage, Pharmaceuticals, Personal Care, Household Products |
| Companies Covered | Huhtamaki Oyj, Berry Global Group Inc., Amcor plc, Sonoco Products Company, ProAmpac, Mondi Group, Constantia Flexibles Group GmbH, Coveris, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pouches Market Strategic Shifts & Innovations
Digital printing integration and barrier coating chemistry advances are compressing development cycles from months to weeks, enabling mass customization while regulatory deadlines force material platform transitions.
Digital flexographic and inkjet systems are collapsing the minimum-order-quantity economics that historically favored gravure cylinders. Brand owners in cosmetics and specialty foods now execute seasonal SKU proliferation without plate costs. Lead times shrink from six weeks to seventy-two hours, compressing inventory carrying costs and obsoleting the forecast-driven batch model.
ECHA REACH Annex XVII restrictions on perfluorinated substances are eliminating long-chain fluorochemicals from grease-resistant food-contact applications. Converters face eighteen-month reformulation windows with incomplete performance validation for bio-based alternatives. Infant nutrition and pet food segments exhibit highest compliance urgency given direct food contact and brand liability exposure.
Retailers are consolidating supplier bases around certified circular packaging platforms, unbundling legacy procurement relationships that prioritized unit cost over lifecycle compliance. Carrefour and Tesco sustainability scorecards now weight recyclability certification above price in annual vendor negotiations. This preference shift concentrates volume with converters holding third-party recyclability certifications from France's Citeo and Germany's Der Grüne Punkt.
Pouches Market Segmentation
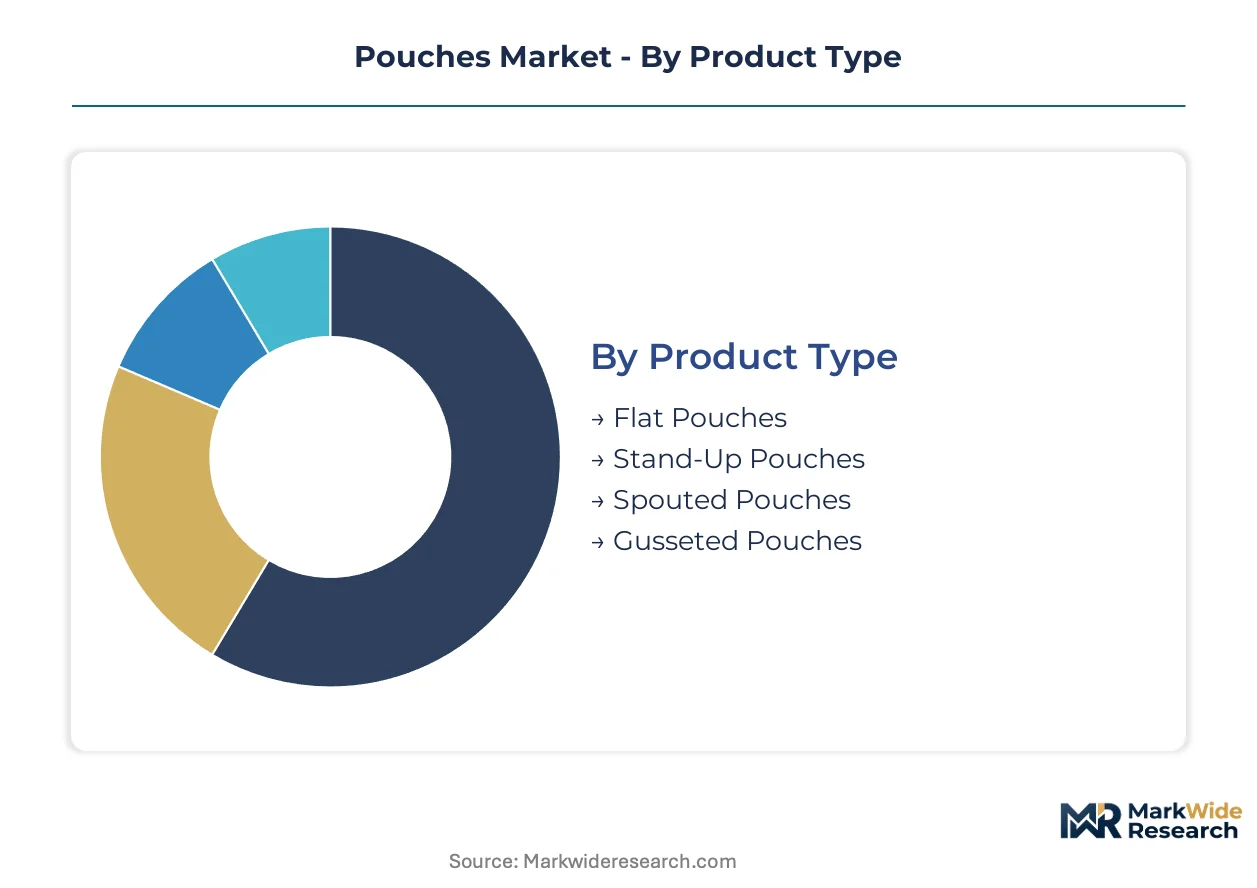
Pouch segmentation reveals how format specifications, barrier requirements, and dispensing mechanics fragment demand across converting capacity. Each dimension carries distinct tooling investments and regulatory compliance pathways that reshape supplier selection criteria.
Product Type:
Structural geometry determines shelf presence, filling line compatibility, and material yield per thousand units produced.
- Flat Pouches:Two-dimensional sealed envelopes with minimal material usage, favored for single-serve portions and sample sachets. Powdered drink mixes and condiment portions in German retail channels concentrate demand here, though limited stacking stability constrains premium positioning.
- Stand-Up Pouches:Bottom-gusseted construction creates freestanding shelf display with expanded printable surface area. Retort-capable versions dominate ready-to-eat meals in France and Germany as brand owners retrofit filling lines for high-barrier mono-material formats.
- Spouted Pouches:Integrated dispensing fitments enable controlled flow for liquids and semi-solids. Infant nutrition and household cleaning applications command price premiums where precise portioning reduces waste.
- Gusseted Pouches:Side or bottom expansion panels increase volumetric capacity without sacrificing pallet density. Industrial chemical and agricultural seed packaging in Italy leverages this format for bulk-to-retail distribution.
Stand-up pouches hold installed capacity. Spouted pouches are rotating up the share rankings.
Material:
Substrate selection governs barrier performance, recyclability certification, and EPR fee exposure under evolving European regulations.
- Plastic:Polyethylene and polypropylene structures, mono-material or laminated, deliver moisture and oxygen barriers at scale. Germany's EPR restructuring penalizes non-recyclable multi-layer variants, accelerating mono-PE adoption for Citeo certification.
- Paper:Fiber-based substrates with bio-polymer or aqueous coatings penetrate dry goods where moderate moisture protection suffices. Carrefour and Tesco sustainability scorecards now favor certified paper-based formats in annual vendor negotiations.
- Aluminium:Metallized or foil laminates provide superior oxygen and light barriers for oxygen-sensitive pharmaceuticals and coffee. ECHA REACH restrictions on perfluorinated substances complicate grease-resistant coating compatibility.
- Biodegradable Films:Polylactic acid and cellulose-derived structures decompose in industrial composting conditions. European brand owners facing EPR fee restructuring pilot these formats in limited retail tests despite sorting infrastructure gaps.
Plastic dominates current throughput. Biodegradable films are climbing the fastest.
Closure Type:
Resealability mechanics determine consumer convenience tiers and line-speed compatibility for form-fill-seal operations.
- Zipper:Interlocking plastic tracks enable repeated opening and closing for multi-use portions. Snack foods and frozen produce in French hypermarkets concentrate demand where portion control extends product life.
- Heat Seal:Permanent fusion of film layers provides tamper evidence and hermetic protection. Pharmaceutical blister packs and sterile medical devices require validated seal integrity protocols.
- Tear Notch:Pre-scored perforations enable clean opening without tools. Single-serve condiments and wet wipes prioritize low-cost access over resealability.
- Press Seal:Adhesive-based reclosure without mechanical tracks reduces material complexity. Dry pet food and baking ingredients in Italian retail channels adopt this mid-tier convenience format.
Heat seal commands legacy infrastructure. Zipper is gaining share fastest.
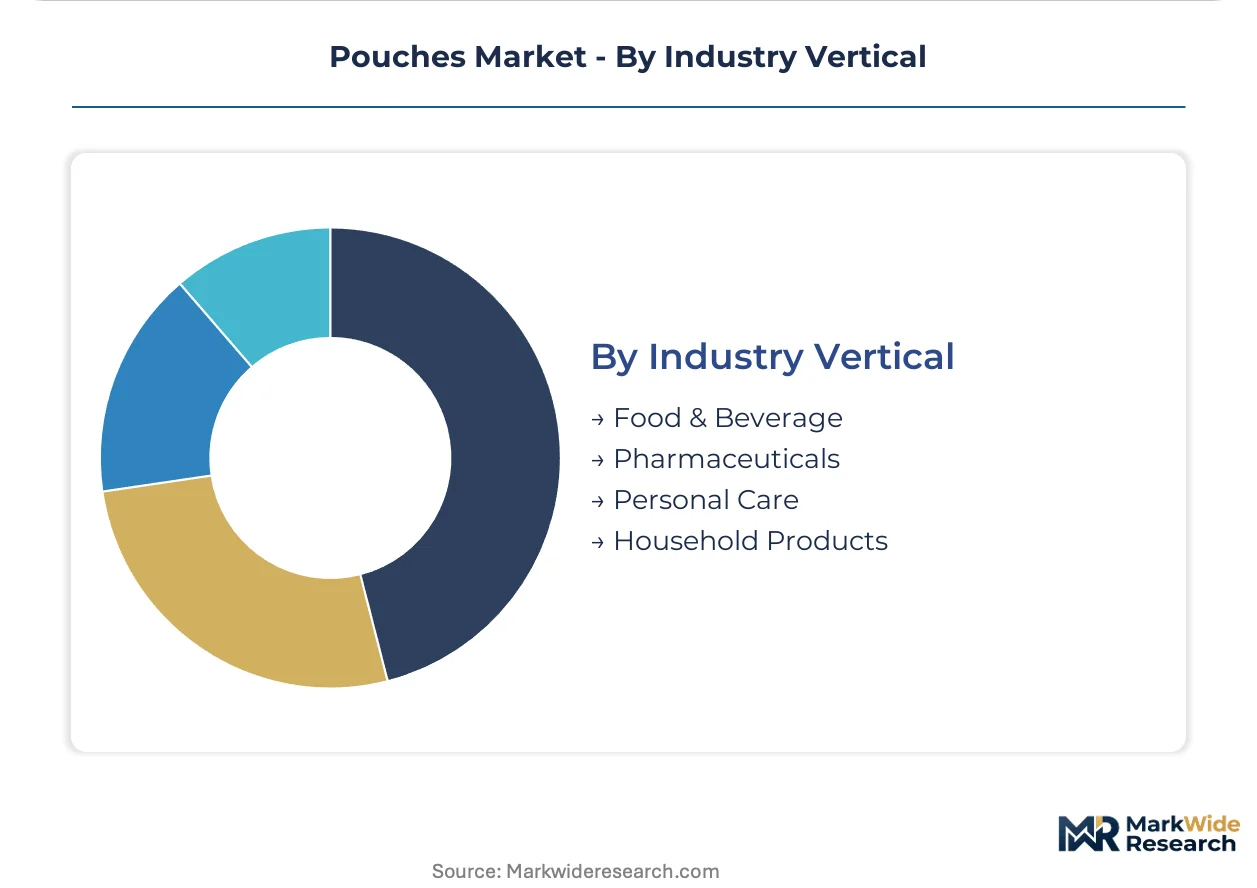
Industry Vertical:
End-use specifications dictate barrier requirements, regulatory compliance depth, and volume concentration patterns.
- Food & Beverage:Largest demand pool spanning shelf-stable meals, snacks, and beverages. Retort processing compatibility and FDA food contact substance notifications govern material selection for export-oriented European converters.
- Pharmaceuticals:Stringent barrier requirements for moisture, oxygen, and light protection. Child-resistant and senior-friendly opening mechanisms add regulatory validation layers under EMA guidance.
- Personal Care:Premium aesthetics and dispensing precision drive spouted pouch adoption. Cosmetics brands exploit digital printing for seasonal SKU proliferation without gravure cylinder costs.
- Household Products:Chemical resistance and dispensing control for detergents and cleaners. Concentrate and refill formats reduce shipping weight versus rigid alternatives in e-commerce channels.
Food and beverage anchors volume concentration. Pharmaceuticals is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters supply mono-material polyethylene laminates to French and Italian brand owners retrofitting filling lines for EU Packaging and Packaging Waste Regulation compliance. Cross-border material flows intensify as EPR fee restructuring penalizes non-recyclable imports.
Germany
Retort-capable stand-up pouch demand concentrates in ready-to-eat meal manufacturing around Hamburg and Cologne. The country's EPR scheme now penalizes multi-layer structures, accelerating Citeo certification for mono-PE suppliers. Baden-Württemberg hosts specialized barrier coating R&D clusters addressing ECHA REACH perfluorinated substance restrictions.
France
Carrefour sustainability scorecards weight recyclability certification above unit price in annual vendor negotiations. ANSM food contact substance notifications govern infant nutrition pouch compliance. The Lyon-Turin industrial corridor concentrates spouted pouch converting capacity for liquid and semi-liquid applications.
Italy
Gusseted pouch demand anchors in agricultural seed and industrial chemical packaging across Emilia-Romagna. Sorting infrastructure gaps in Northern Italian recycling facilities block circular economy certification for certain mono-material variants. Bologna-based converters pilot paper-based barrier formats for dry goods segments.
United States
FDA food contact substance notifications govern export-oriented pouch structures destined for European markets. Digital printing adoption concentrates in Chicago and Los Angeles cosmetics packaging clusters. E-commerce fulfillment channels drive lightweight flexible format substitution for rigid alternatives in direct-to-consumer distribution.
China
Polyethylene resin supply anchors pouch substrate costs for Asia-Pacific converters. GB standards and SAMR food contact regulations govern domestic market access. The Yangtze River Delta hosts high-speed form-fill-seal machinery manufacturing clusters supplying European retrofit projects.
Pouches Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base spans integrated multinational film extruders, regional converting specialists, and equipment-integrated solution providers. Three archetypes dominate: global laminate suppliers with certified recyclable platforms, paper-based barrier innovators, and high-speed form-fill-seal compatibility specialists. Competitive moves concentrate on strategic partnerships for sorting infrastructure alignment and portfolio diversification into mono-material structures.
Among integrated packaging conglomerates, Amcor plc, Mondi Group, and ProAmpac occupy positions spanning film extrusion networks and barrier coating development. Amcor represents the global laminate supplier archetype with recyclable platform certification reach. Mondi exemplifies paper-based barrier innovation competing with conventional multi-layer films. ProAmpac sits within the high-speed equipment compatibility specialist tier addressing form-fill-seal line recalibration requirements. These three entities anchor industry-level commentary on material platform transitions and regulatory compliance pathways without asserting specific strategic actions or financial positions.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Berry Global Group Inc. |
| Amcor plc |
| Sonoco Products Company |
| ProAmpac |
| Mondi Group |
| Constantia Flexibles Group GmbH |
| Coveris |
| Sealed Air Corporation |
| Others |
Cost & Logistics Intelligence
Polyethylene resin supply from German petrochemical complexes anchors cost structures for mono-material pouch converters across Europe, concentrating margin pools with extruders holding backward integration into naphtha-cracker operations while brand owners absorb EPR fee penalties for non-recyclable alternatives.
Pricing Analysis
Multi-layer laminate legacy formats trade at persistent discounts against next-generation mono-material structures, with three-tier pricing structure across premium, standard, and economy levels separating Citeo-certified mono-PE from uncertified variants from generic imports. Price differentiation hinges on recyclability certification tier and volume scale commitments, with annual contract buyers capturing 15-20 point spreads over spot purchasers. Cost compression in standard-grade laminates is intensifying because naphtha-cracker margin volatility transmits directly through polyethylene resin contracts. Private-label brand owners exhibit highest price sensitivity, while infant nutrition multinationals prioritize barrier performance over unit economics.
Supply Chain Analysis
Ethylene feedstock from Rotterdam-Antwerp refining corridors and Saudi Arabian crackers feeds European extrusion networks, with resin sourcing from Germany, the Netherlands, and Belgium dominating substrate supply. Converter operations draw from metallized film, aqueous barrier coatings, and spouted fitment components as critical inputs. Single-source vulnerability concentrates in specialized barrier coating chemistries facing ECHA REACH reformulation deadlines. Distribution runs through converter-direct relationships with filling line operators, bypassing traditional packaging distributors for high-volume food and beverage accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation has triggered a platform-transition disruption comparable to prior material-generation shifts, with EPR fee restructuring forcing brand owners into supplier consolidation around certified circular formats within a compressed compliance window.
For Market Incumbents: Pre-empt share erosion by accelerating Citeo and Der Grüne Punkt certification coverage across mono-PE product lines before 2025 EPR enforcement intensifies. Capture backward integration into barrier coating R&D clusters in Baden-Württemberg to secure grease-resistant formulation alternatives ahead of perfluorinated substance bans. Defend against paper-based barrier innovators by locking multi-year supply agreements with Carrefour and Tesco procurement teams.
For New Entrants and Emerging Players: Pursue white-space positioning in spouted pouch converting for pharmaceutical and household cleaning segments, where controlled dispensing commands price premiums and incumbent capacity remains constrained. Target Northern Italian agricultural seed packaging for gusseted pouch penetration, exploiting sorting infrastructure gaps that block circular certification for established mono-material suppliers. Anchor go-to-market through equipment-integrated partnerships with Yangtze River Delta form-fill-seal machinery manufacturers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with demonstrated high-speed line compatibility and existing third-party recyclability certifications, positioned for volume consolidation as retailer scorecards reweight procurement criteria. Long-term viability across the next decade rests on sorting infrastructure alignment and barrier coating chemistry pipelines rather than extrusion scale alone. Watch for inflection signals in French and Italian near-infrared detection capability investments, which determine which material platforms achieve circular economy compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Certification | Secures Citeo and Der Grüne Punkt approval ahead of EPR penalty phase-in across German and French retail channels. |
| Barrier Coating Chemistry Pivot | Replaces perfluorinated grease-resistant layers with bio-based alternatives validated under ECHA REACH Annex XVII timelines. |
| High-Speed Line Compatibility Investment | Recalibrates heat-seal initiation parameters for mono-PE films to maintain throughput during brand owner filling line retrofits. |
| Paper-Based Format Diversification | Captures Carrefour and Tesco sustainability scorecard preferences with fiber-based dry goods packaging alternatives. |
| Sorting Infrastructure Partnership | Aligns material specifications with French and Italian near-infrared detection capabilities to unblock circular certification pathways. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, trade association capacity surveys, and resin price benchmark data. Primary interviews spanned plant managers at German and French converting facilities, procurement leads at ready-to-eat meal manufacturers, technical R&D directors developing barrier coatings, and sustainability officers at major retailers. Secondary validation drew from ECHA REACH substance restrictions, Citeo recyclability certification registries, customs data on polyethylene resin flows, and SEC filings of integrated packaging conglomerates. Bottom-up capacity modeling triangulated against top-down demand segmentation across product types and industry verticals.
Forecast inputs incorporate segment-level growth trajectories, regulatory compliance deadline effects, and substitution elasticity between material platforms across the analysis window. Segmentation dimensions modeled include pouch format geometry, substrate material class, closure mechanism, and end-use industry vertical. CAGRs were derived from trend-line extrapolation of historical volume data adjusted for structural shift impacts. Industry-specific inputs encompass EPR fee restructuring schedules, retort processing capacity expansion at ready-to-eal meal facilities, and digital printing adoption curves in cosmetics packaging.
Macroeconomic conditions sit as an overlay; deviation in ethylene feedstock pricing, naphtha-cracker operating rates, or euro-zone consumer packaged goods demand would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timing and sorting infrastructure investment completion. Cross-checking against external resin price benchmarks and retailer sustainability scorecard weightings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Aluminum-Free Food Pouch Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Morocco Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Global Pouches Packaging Market
Pouch
Peelable Pouches Market
Pouch
Compostable Pouches Market
Pouch
Contour Pouches Market
Pouch
Bio PE Pouches Market
Pouch
PCR Pouches Market
Pouch
Self-Seal Pouches Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Open Mouth Sacks Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Japan Pouch Packaging Market
Pouch
Doyen Style Pouches Market