
 Helical Screw Blowers Market | 2026-2036
Helical Screw Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Helical Screw Blowers Market Intelligence
Composite rotor coatings and advanced polymer seals are expanding operational lifespans in high-duty helical screw blower applications. Gardner Denver leverages its vertical integration in precision machining to control rotor tolerances across global production networks. Atlas Copco anchors its position through captive supply of airend castings and magnetic bearing assemblies. Kaeser Kompressoren differentiates via intensive R&D spending on oil-free compression architectures for pharmaceutical and food-grade environments.
Helical screw blowers are positive displacement machines employing intermeshing twin rotors within a figure-eight bore to deliver pulsation-free air or gas flows at pressures typically spanning 0.5 to 4.0 bar gauge. Rotor profiles machined to micron-level clearances eliminate contact during operation, enabling dry-running oil-free designs essential for contamination-sensitive processes. Oil-free product types command premium positioning in pharmaceutical and food processing end user industries where compressed air purity standards exclude lubricant carryover. Variable speed drive technology leads growth trajectories as municipal wastewater aeration systems retrofit fixed-speed lobe blowers with demand-responsive screw packages that trim energy consumption under partial-load conditions.
EPA effluent limitation guidelines for municipal treatment plants and EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases shape equipment replacement timelines across North American and European installed bases. China's MEE enforces escalating discharge standards for chemical processing zones, compelling upgrades to higher-efficiency aeration blowers. ISO 8573-1 Class 0 certification requirements for oil-free compressed air access pharmaceutical and food manufacturing contracts. Stakeholders must evaluate magnetic bearing and high-speed motor integration roadmaps against total lifecycle cost models as energy tariffs and carbon accounting frameworks tighten.
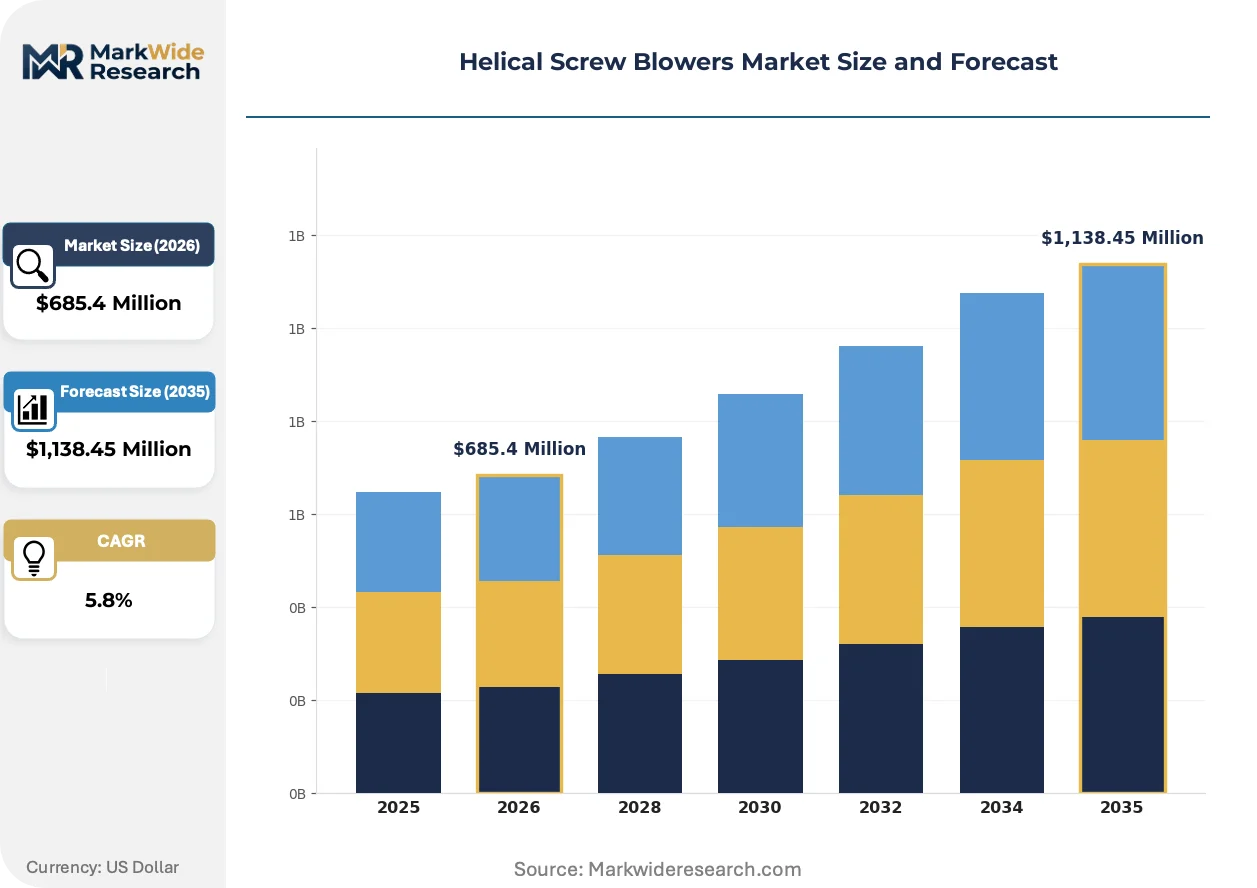
Market Dynamics
The helical screw blowers market is experiencing a fundamental restructuring as energy-efficiency mandates and carbon-accounting frameworks force replacement cycles across municipal wastewater and industrial aeration infrastructure. Fixed-speed lobe blower installed bases face accelerated obsolescence as variable-speed screw technology delivers measurable operating cost reductions under partial-load conditions.
Growth Catalysts
- EU F-Gas Regulation phase-down:Fluorinated greenhouse gas restrictions are compelling European chemical processors to abandon refrigerant-based compression systems in favor of dry-running oil-free screw architectures.
- China MEE discharge standards:Escalating effluent requirements for Yangtze River Delta industrial zones are triggering wholesale aeration blower upgrades at petrochemical and specialty chemical facilities.
- Magnetic bearing integration:Oil-free airend designs incorporating active magnetic bearing systems are eliminating mechanical wear components and extending maintenance intervals in continuous-duty pharmaceutical applications.
Market Restraints
- Precision machining concentration:Rotor profile grinding and micron-level tolerance control capabilities concentrate among German and Swiss machine tool networks, creating supply bottleneck exposure.
- High-alloy steel volatility:Specialized stainless and tool steel grades required for corrosion-resistant rotor coatings face price instability tied to nickel and molybdenum commodity markets.
- ISO 8573-1 Class 0 certification burden:Oil-free validation protocols impose extended testing timelines and third-party audit costs that disadvantage smaller regional competitors.
Strategic Opportunities
- India pharmaceutical corridors:Hyderabad and Ahmedabad bulk drug manufacturing clusters remain underpenetrated by oil-free screw technology, presenting first-mover positioning for certified suppliers.
- Digital twin convergence:Integration of airend performance modeling with predictive vibration monitoring is enabling outcome-based service contracts that capture lifecycle value.
- US IRA clean energy incentives:Municipal wastewater treatment energy-efficiency upgrade grants are creating funded replacement pipelines for aging aeration infrastructure.
Industry Challenges
- Rotordynamics engineering scarcity:Specialized expertise in high-speed rotor balance and magnetic bearing control systems remains concentrated among a narrow pool of aeromechanical engineers.
- Legacy control system integration:Retrofitting variable-speed screw packages into existing SCADA architectures at aged treatment plants requires custom protocol bridging and extended commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helical Screw Blowers Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lubricated, Oil-Free, Single Stage, Two Stage, High Speed Technology: Variable Speed Drive, Fixed Speed, Magnetic Bearing, Air Bearing, Electric Motor Application: Wastewater Treatment, Chemical Processing, Pulp & Paper, Food & Beverage, Power Generation End User Industry: Municipal Facilities, Petrochemical Plants, Manufacturing Units, Agriculture Facilities, Pharmaceutical Companies |
| Companies Covered | Gardner Denver, Zhejiang Kaishan Compressor, Atlas Copco, Swam Pneumatics, ShinMaywa Industries, Kaeser Kompressoren, Roots System, Universal Blower Pac, Aerzen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helical Screw Blowers Market Strategic Shifts & Innovations
Equipment architecture is fragmenting into standardized subsystems that permit field-configurable pressure and flow combinations. This decomposition is compressing lead times and enabling regional assembly models that bypass fully integrated manufacturing constraints.
Permanent magnet synchronous motor integration with integrated variable frequency drives is modularizing power transmission design. Municipal wastewater operators in Germany and the Netherlands are specifying these compact packages for constrained blower room retrofits. The technology is modularizing supplier ecosystems by decoupling motor sourcing from airend manufacturing.
The EU F-Gas Regulation's stepped phase-down schedule is accelerating refrigerant-dependent blower decommissioning. Chemical processing facilities face compressed replacement windows as hydrofluorocarbon service bans approach. Food-grade compressed air users in France and Italy are prioritizing dry screw technology to preempt compliance exposure.
Lifecycle cost contracting is displacing capital-purchase procurement at large industrial accounts. Water utilities in China's Jiangsu province are piloting energy-performance guarantees where suppliers retain equipment ownership. Municipal operators in this region are transferring operational risk to vendors while securing guaranteed efficiency outcomes.
Helical Screw Blowers Market Segmentation
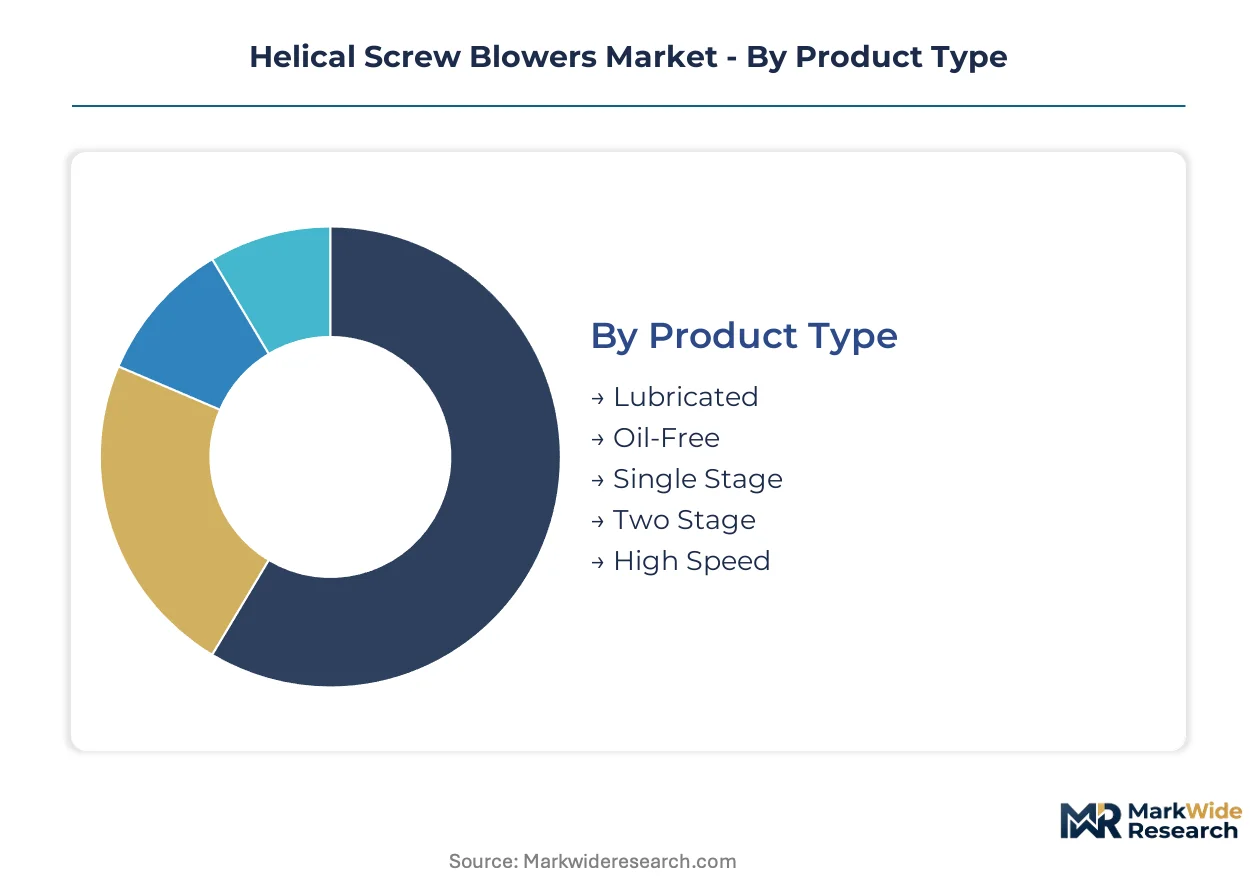
Segmentation in helical screw blowers reveals how technology choices lock into specific operational economics. Product architecture determines maintenance intervals, energy efficiency, and certification eligibility for contamination-sensitive processes.
Product Type:
Supply concentration in precision rotor grinding favors integrated manufacturers with captive machining networks.
- Oil-Free:Dry-running twin-rotor designs eliminate lubricant carryover through micron-clearance profiles. Municipal wastewater facilities across Germany and China's Yangtze River Delta specify these for effluent compliance under tightening MEE and EU discharge standards.
- Lubricated:Oil-flooded compression chambers permit higher pressure ratios and simpler sealing architectures. Petrochemical clusters in the US Gulf Coast and Rotterdam-Antwerp corridor favor these for continuous-duty process air where compressed air purity requirements are less stringent.
- Single Stage:Compact airend designs serve moderate pressure applications with minimal footprint requirements.
- Two Stage:Intercooled compression paths improve thermodynamic efficiency for high-pressure chemical processing duties.
- High Speed:Direct-drive configurations eliminate gearbox losses and reduce maintenance points in space-constrained installations.
Today's leader: Oil-Free. Tomorrow's challenger: High Speed.
Technology:
Cost tier differentiation separates premium active-bearing systems from commodity fixed-speed architectures.
- Variable Speed Drive:Integrated VFD packages modulate rotor speed against aeration demand curves. Dutch and German wastewater utilities retrofit these into aging blower rooms to capture partial-load energy savings unavailable to fixed-speed lobe blowers.
- Magnetic Bearing:Active magnetic levitation eliminates mechanical contact and extends maintenance intervals to 80,000+ operating hours. Pharmaceutical manufacturers in Basel and Boston specify these for continuous sterile air supply where downtime costs exceed equipment capital.
- Fixed Speed:Legacy architecture dominates installed base replacement cycles in budget-constrained municipal markets.
- Air Bearing:Hydrodynamic gas film bearings serve specialized high-speed, low-load applications with minimal power consumption.
- Electric Motor:Permanent magnet synchronous designs integrate directly with airend housings for compact retrofit packages.
Variable Speed Drive holds installed base dominance. Magnetic Bearing climbs the fastest as lifecycle contracting spreads.
Application:
Application concentration tracks regulatory enforcement intensity across industrial corridors.
- Wastewater Treatment:Aeration blowers represent 60-70% of facility electrical load. China's Jiangsu province pilots energy-performance guarantees where vendors retain equipment ownership and guarantee efficiency outcomes.
- Chemical Processing:Corrosive gas handling and nitrogen blanketing demand corrosion-resistant rotor coatings. EU F-Gas Regulation phase-downs accelerate refrigerant-dependent blower replacement at Antwerp and Ludwigshafen complexes.
- Pulp & Paper:Lime kiln combustion air and stock agitation require reliable continuous-duty compression.
- Food & Beverage:ISO 8573-1 Class 0 certification requirements exclude oil-carryover risk in packaging and fermentation processes.
- Power Generation:Flue gas desulfurization and pneumatic conveying of coal ash create intermittent high-duty cycles.
Wastewater Treatment anchors current volume. Chemical Processing offers steepest expansion trajectory as F-Gas deadlines approach.
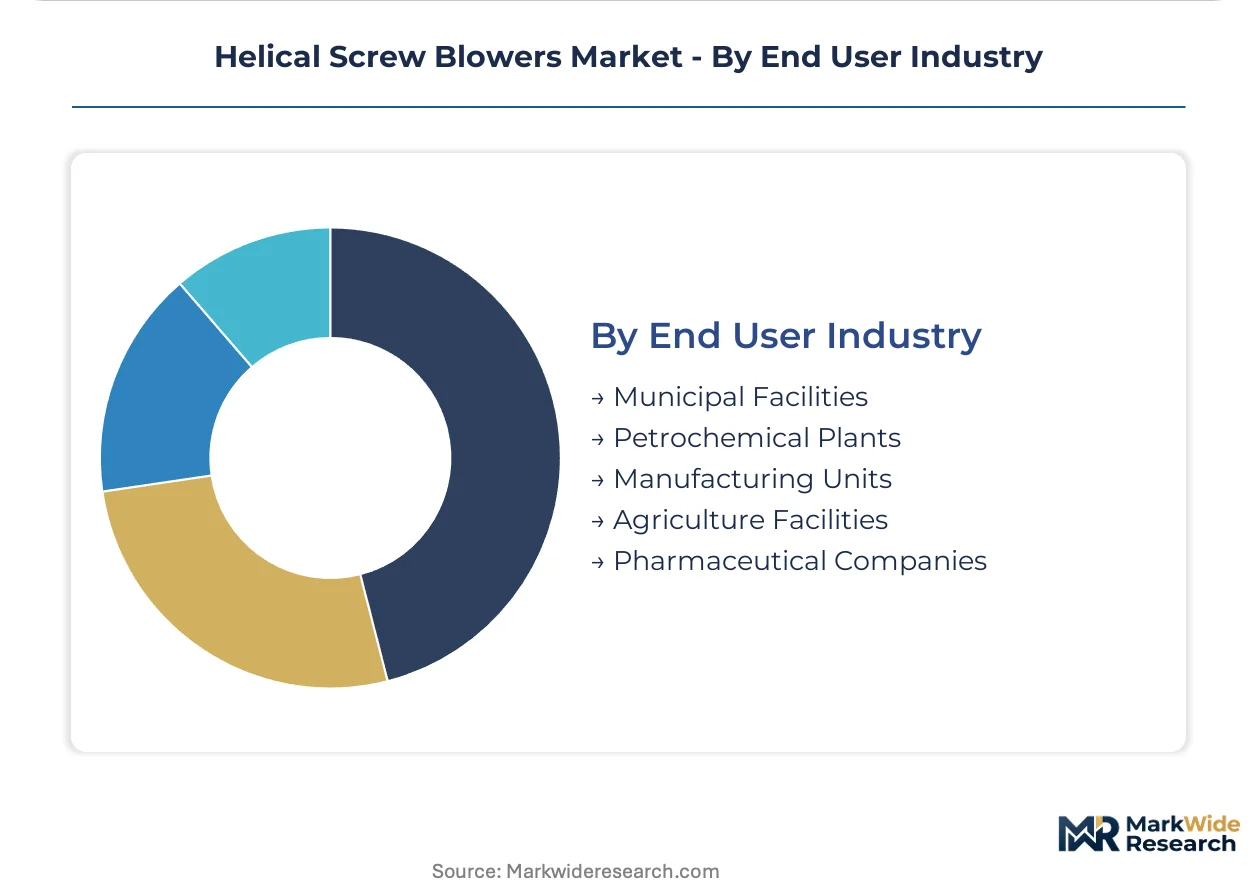
End User Industry:
Customer type segmentation separates capital-purchase procurement from emerging lifecycle contracting models.
- Municipal Facilities:Public-sector procurement cycles favor standardized specifications and extended warranty terms. US IRA clean energy incentives create funded replacement pipelines for aging aeration infrastructure.
- Petrochemical Plants:Reliability-centered maintenance programs prioritize mean-time-between-failures over first cost. Yangtze River Delta clusters drive replacement demand under MEE enforcement.
- Manufacturing Units:General industrial air supply spans automotive painting to metal forming with moderate purity requirements.
- Agriculture Facilities:Aeration for aquaculture and grain handling represents emerging demand with price-sensitive procurement.
- Pharmaceutical Companies:Validation protocols and FDA/EMA inspection readiness impose documentation burdens that favor established certified suppliers.
Municipal Facilities dominate transaction volume. Pharmaceutical Companies concentrate margin capture through certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta industrial corridor concentrates the most intensive helical screw blower replacement cycles worldwide, with petrochemical and chemical processing clusters driving demand under tightening environmental enforcement.
China
Jiangsu province wastewater utilities pilot energy-performance guarantee contracts where vendors retain equipment ownership. The Ministry of Ecology and Environment enforces escalating discharge standards for chemical processing zones. Nanjing and Suzhou petrochemical complexes are retrofitting fixed-speed lobe blowers with variable-speed screw packages.
Germany
Municipal wastewater facilities across the Ruhr and Rhine regions specify oil-free designs to meet EU F-Gas Regulation phase-down schedules. The EU Green Deal accelerates refrigerant-dependent blower decommissioning. Ludwigshafen chemical complexes are replacing legacy compression systems with dry-running screw architectures.
United States
Municipal treatment plants in the Great Lakes and Gulf Coast regions leverage IRA clean energy incentives for aeration infrastructure upgrades. EPA effluent limitation guidelines shape equipment replacement timelines. Houston petrochemical corridors favor lubricated designs for continuous-duty process air applications.
India
Hyderabad and Ahmedabad bulk drug manufacturing clusters remain underpenetrated by oil-free screw technology. CDSCO validation protocols and FDA inspection readiness impose documentation burdens favoring established certified suppliers. Pharmaceutical manufacturers in these corridors are beginning to specify ISO 8573-1 Class 0 certified equipment.
Japan
Precision machining networks in Nagoya and Osaka supply rotor grinding capabilities to regional blower fabricators. METI industrial efficiency standards promote variable-speed drive adoption in municipal wastewater applications. Kanto region treatment facilities are retrofitting aging blower rooms with compact permanent magnet synchronous motor packages.
Helical Screw Blowers Market Key Industry Players
Global majors compete with regional champions across precision machining capabilities and certification depth. The vendor base stratifies into three tiers: integrated multinationals with captive rotor production, mid-scale specialists sourcing machined components, and regional assemblers serving price-sensitive municipal procurement. Dominant competitive moves include backward integration into airend casting supply and geographic expansion through local assembly partnerships.
Among German and Swedish integrated manufacturers, Atlas Copco and Kaeser Kompressoren exemplify the premium-tier archetype through in-house control of critical component supply. Gardner Denver anchors the North American position with vertically integrated precision machining networks. Zhejiang Kaishan Compressor represents the scale-driven Chinese competitor segment. ShinMaywa Industries occupies a specialized position serving Asia-Pacific marine and wastewater applications. These named entities illustrate how competitive positioning depends on rotor tolerance control and magnetic bearing integration roadmaps rather than branding alone.
| Leading Market Players |
|---|
| Gardner Denver |
| Zhejiang Kaishan Compressor |
| Atlas Copco |
| Swam Pneumatics |
| ShinMaywa Industries |
| Kaeser Kompressoren |
| Roots System |
| Universal Blower Pac |
| Aerzen |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation phase-down mandates gate qualified supply and premium-tier pricing access for oil-free helical screw blowers, as certified manufacturers command pricing power while uncertified competitors face exclusion from pharmaceutical and food-grade procurement.
Pricing Analysis
High-alloy steel volatility in nickel and molybdenum commodity markets forces input-cost pass-through into rotor coating and precision machining tiers. Three-tier pricing structure across premium, standard, and economy levels separates magnetic bearing integrated packages from fixed-speed retrofits and basic lubricated units. Price differentiation hinges on ISO 8573-1 Class 0 certification status and captive machining capabilities. Margins are tightening in economy-tier municipal procurement as Chinese regional assemblers compress pricing, while pharmaceutical buyers show lowest price sensitivity due to downtime cost exposure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Yangtze River Delta petrochemical complexes, while distributor networks serve fragmented municipal wastewater utilities. Manufacturing gravity centers on Germany, Switzerland, and Japan for precision rotor grinding and micron-tolerance machining. Raw material dependencies span high-alloy stainless steels, rare-earth magnetic materials, and advanced polymer seal compounds. Single-source vulnerability concentrates in German and Swiss machine tool networks for profile grinding equipment. Distribution runs through authorized service centers for aftermarket parts and commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas compliance costs and China's MEE enforcement intensity create divergent replacement cycle timing and margin capture opportunities across regions.
For Market Incumbents: Lock in rotor tolerance control through backward integration into precision machining networks or exclusive equipment partnerships with German and Swiss machine tool suppliers. Defend against emerging Chinese scale competitors by deepening ISO 8573-1 Class 0 certification moats and expanding lifecycle contracting capabilities that transfer operational risk from municipal buyers. For New Entrants and Emerging Players: System integrators represent the most viable channel partner type for penetrating India's underdeveloped pharmaceutical corridors in Hyderabad and Ahmedabad. Target bulk drug manufacturing clusters where CDSCO validation protocols and FDA inspection readiness impose documentation burdens favoring certified equipment. White-space exists in energy-performance guarantee contracting models where vendors retain equipment ownership and guarantee efficiency outcomes. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale specialists with captive airend casting supply because precision machining concentration creates acquisition scarcity value and barriers to organic entry. Long-term viability centers on magnetic bearing integration roadmaps and digital twin service capabilities. Watch Jiangsu province energy-performance guarantee pilots as the inflection indicator for lifecycle contracting adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captive rotor grinding capabilities eliminate supply bottleneck exposure from German and Swiss machine tool networks. |
| Magnetic Bearing Technology Roadmap | Active magnetic levitation extends maintenance intervals beyond 80,000 hours for continuous-duty pharmaceutical applications. |
| Lifecycle Cost Contracting Model | Energy-performance guarantees transfer operational risk to vendors while securing guaranteed efficiency outcomes for Jiangsu utilities. |
| ISO 8573-1 Class 0 Certification Investment | Oil-free validation protocols create procurement barriers that exclude uncertified competitors from food and pharmaceutical contracts. |
| Regional Assembly Partnership Expansion | Field-configurable subsystems compress lead times and enable localized production bypassing fully integrated manufacturing constraints. |
Research Approach
Multiple input streams — technical interviews with blower OEM engineering directors, procurement discussions with municipal wastewater plant managers, and regulatory tracking across EU F-Gas and China MEE frameworks — were reconciled against secondary validation from customs trade data, SEC equipment supplier filings, and industrial compressor association reports. Primary fieldwork engaged maintenance directors at German Ruhr region treatment facilities, aftermarket service heads at Japanese precision machining networks, and pharmaceutical facility engineers in Basel and Boston. Bottom-up unit economics and top-down sectoral demand models were triangulated to establish market sizing.
Historical shipment trajectories were cross-referenced against panel input from aeromechanical engineering specialists and rotating equipment procurement leads to anchor growth projections. Segmentation modeling spanned product architecture, technology tier, application intensity, and end-user procurement mode across the projection horizon. CAGRs were derived from replacement cycle timing under regulatory enforcement schedules and energy tariff escalation assumptions. Forecast inputs incorporated magnetic bearing adoption curves and variable-speed drive retrofit penetration rates.
Revisions become necessary when EU F-Gas phase-down schedules accelerate, China MEE enforcement intensity shifts, or nickel and molybdenum commodity volatility disrupts rotor coating cost structures. Forecasts reflect documented assumptions regarding regulatory compliance timelines and energy-efficiency upgrade funding availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
US Commercial Water Heater Market