
 Compressed Air Treatment Equipment Market | 2026-2036
Compressed Air Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Air Treatment Equipment Market Analysis
Industrial distributor networks is reconfiguring around lifecycle service contracts rather than transactional equipment sales. Atlas Copco AB leverages its aftermarket service infrastructure to anchor long-term maintenance revenue across European manufacturing hubs. Donaldson Company, Inc. specializes in filtration media technology for high-purity compressed air streams in pharmaceutical cleanrooms.
Compressed air treatment equipment encompasses dryers, filters, regulators, and lubricators engineered to remove moisture, particulates, oil aerosols, and contaminants from compressed air streams, typically achieving pressure dew points between -40°C and +3°C depending on technology class. The primary purpose is protecting pneumatic machinery, instrumentation, and end-products from corrosion, contamination, and operational failure in continuous industrial environments. Refrigerated dryers occupy the largest installed base among product types due to their cost-efficiency in general manufacturing, while desiccant technology commands premium positioning where pharmaceutical and electronics applications require sub-zero dew point guarantees. Membrane separation is gaining traction in portable and point-of-use installations where energy minimization and compact footprint outweigh absolute drying performance.
ISO 8573-1 air purity classes, FDA Current Good Manufacturing Practice requirements, and EU F-Gas Regulation restrictions on high-GWP refrigerants are tightening compliance thresholds for new equipment procurement and retrofit decisions. OSHA respiratory air standards in the United States and REACH chemical registration obligations in Europe add overlapping compliance burdens that favor certified system integrators over component-only suppliers. Stakeholders must monitor refrigerant phase-down schedules and cross-border certification reciprocity to anticipate which technology platforms will carry regulatory preference in major procurement cycles.
Market Dynamics
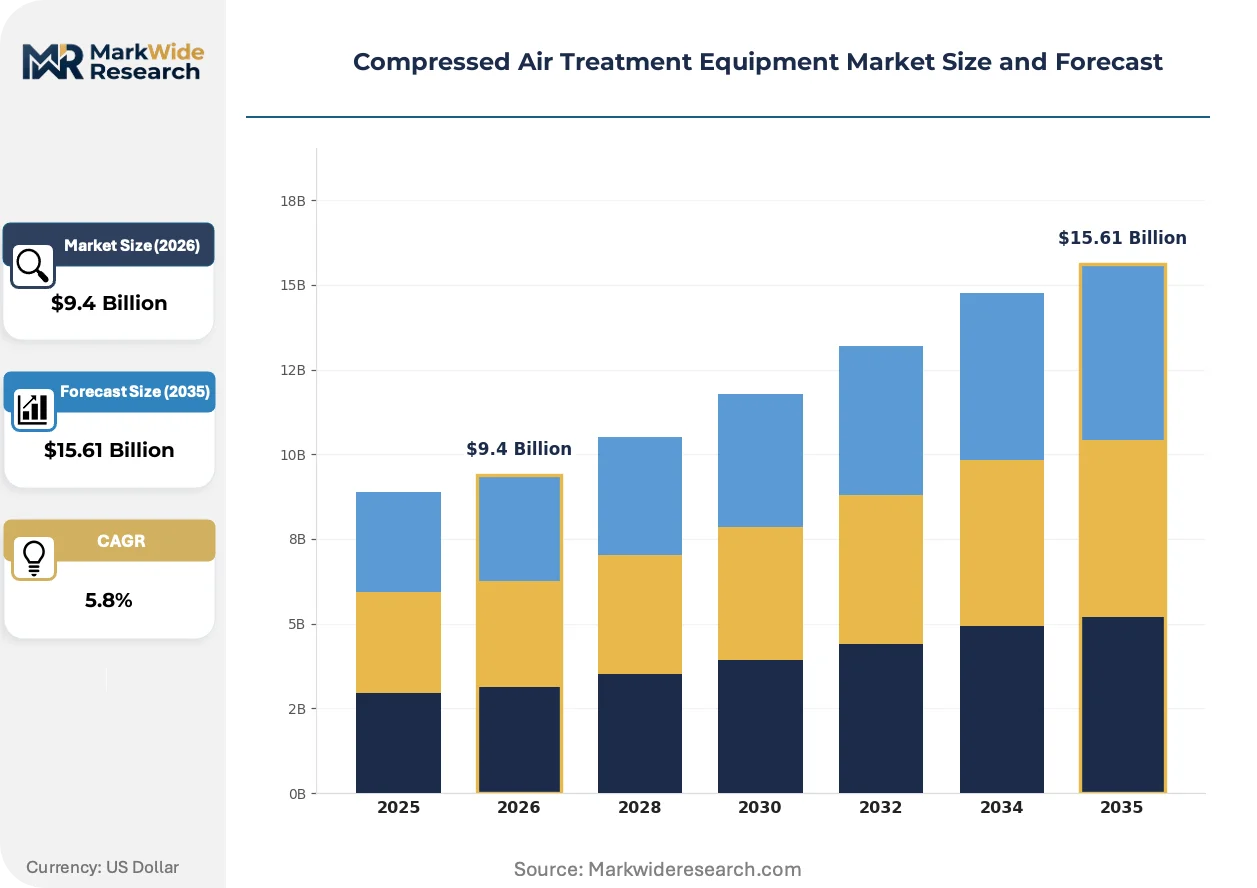
The compressed air treatment equipment market is restructuring around regulatory-driven replacement cycles, with ISO 8573-1 Class 0 oil-free mandates and EU F-Gas refrigerant phase-downs forcing technology transitions across installed bases in food processing and automotive manufacturing clusters.
Growth Catalysts
- ISO 8573-1 Class 0 oil-free mandates:Food processing facilities in Germany and the United States are replacing legacy lubricated compressors to eliminate oil aerosol contamination risks in packaging lines.
- Pharmaceutical sterile air validation:FDA Current Good Manufacturing Practice requirements for pyrogen-free compressed air are expanding desiccant dryer installations in sterile manufacturing suites.
- Automotive electrification:Battery cell manufacturing in South Korea and Germany requires ultra-dry air systems to prevent moisture-induced defects in electrode coating processes.
Market Restraints
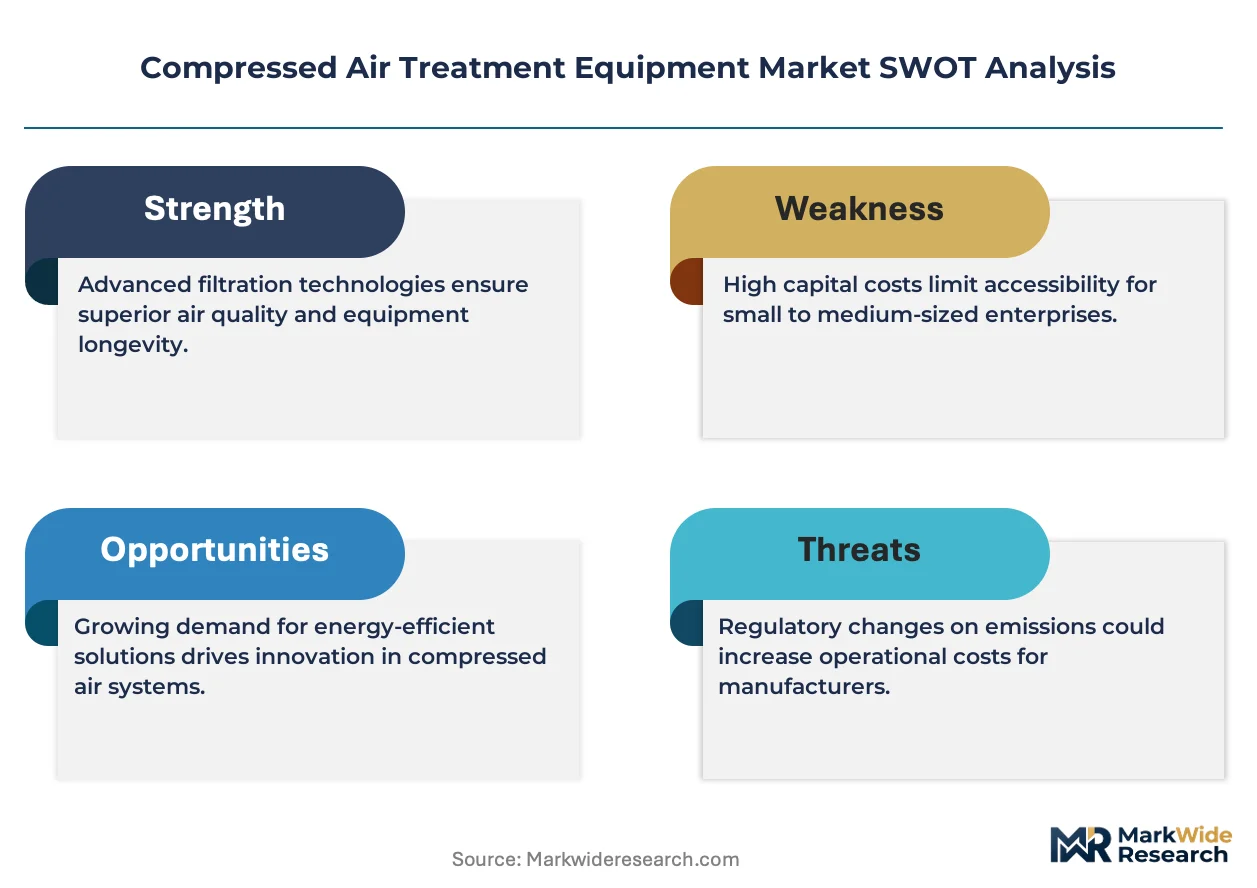
- Refrigerant input cost volatility:EU F-Gas Regulation restrictions on high-GWP refrigerants are compressing margins for refrigerated dryer manufacturers dependent on R-134a and R-410A supply chains.
- Desiccant media supply concentration:Activated alumina and molecular sieve production concentrates in Chinese industrial zones, exposing European OEMs to freight cost swings and customs delays.
- Membrane drying performance ceiling:Polymer membrane technology cannot achieve the -40°C pressure dew points required for pharmaceutical applications, limiting addressable market scope.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO compliance deadlines for sterile manufacturing facilities are creating first-time demand for validated desiccant systems in Hyderabad and Ahmedabad clusters.
- Heat-of-compression regeneration:Converging thermal management and drying functions eliminates external heater energy consumption, appealing to automotive OEMs with Science-Based Targets commitments.
- Lifecycle service contract penetration:Compressed air audits and predictive maintenance subscriptions are displacing transactional filter sales in German automotive tier-one supplier networks.
Industry Challenges
- ISO 8573-1 certification timeline compression:Third-party testing bottlenecks at TÜV and SGS laboratories are extending product launch schedules for Class 0 oil-free compressor-integrated systems.
- Legacy pneumatic infrastructure integration:Brownfield manufacturing sites in the United States Midwest require custom manifold adaptations to accommodate smart dryer monitoring retrofits without production line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Air Treatment Equipment Market |
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $15.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filters, Dryers, Regulators, Lubricators End User: Manufacturing, Food Processing, Pharmaceuticals, Automotive Technology: Membrane, Refrigerated, Desiccant, Coalescing Installation: Permanent, Portable, Modular, Custom-built |
| Companies Covered | Parker Hannifin Corporation, BOGE KOMPRESSOREN Otto Boge GmbH & Co. KG, Atlas Copco AB, SPX FLOW Inc., Sullair Corporation, Ingersoll Rand Inc., Donaldson Company, Inc., ELGi Equipments Ltd., Kaeser Kompressoren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Air Treatment Equipment Market Emerging Trajectories
Technology convergence between thermal management and air treatment is compressing equipment footprints while regulatory chemistry restrictions are forcing refrigerant architecture redesigns. Distribution economics favor integrated system providers over component specialists.
Heat-of-compression desiccant dryers are collapsing the historical separation between compressor and dryer capital equipment decisions. Automotive OEMs in Stuttgart and Munich are specifying these systems as standard for new press shop installations. The technology is collapsing energy consumption benchmarks that previously favored refrigerated dryers in general manufacturing environments.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions toward lower-GWP alternatives. Refrigerated dryer manufacturers face redesign costs for CO₂ and hydrocarbon-based systems. Food processing facilities in France and Italy are prioritizing equipment with pre-certified refrigerant compliance to avoid mid-life retrofit liabilities.
Compressed air service contracts are displacing component-only procurement in automotive supplier networks. Atlas Copco's aftermarket infrastructure in Germany anchors multi-year maintenance agreements that bundle monitoring, filtration replacement, and dew point validation. Tier-one suppliers in Wolfsburg and Ingolstadt are consolidating vendor relationships to reduce audit burden under IATF 16949 quality mandates.
Compressed Air Treatment Equipment Market Segmentation
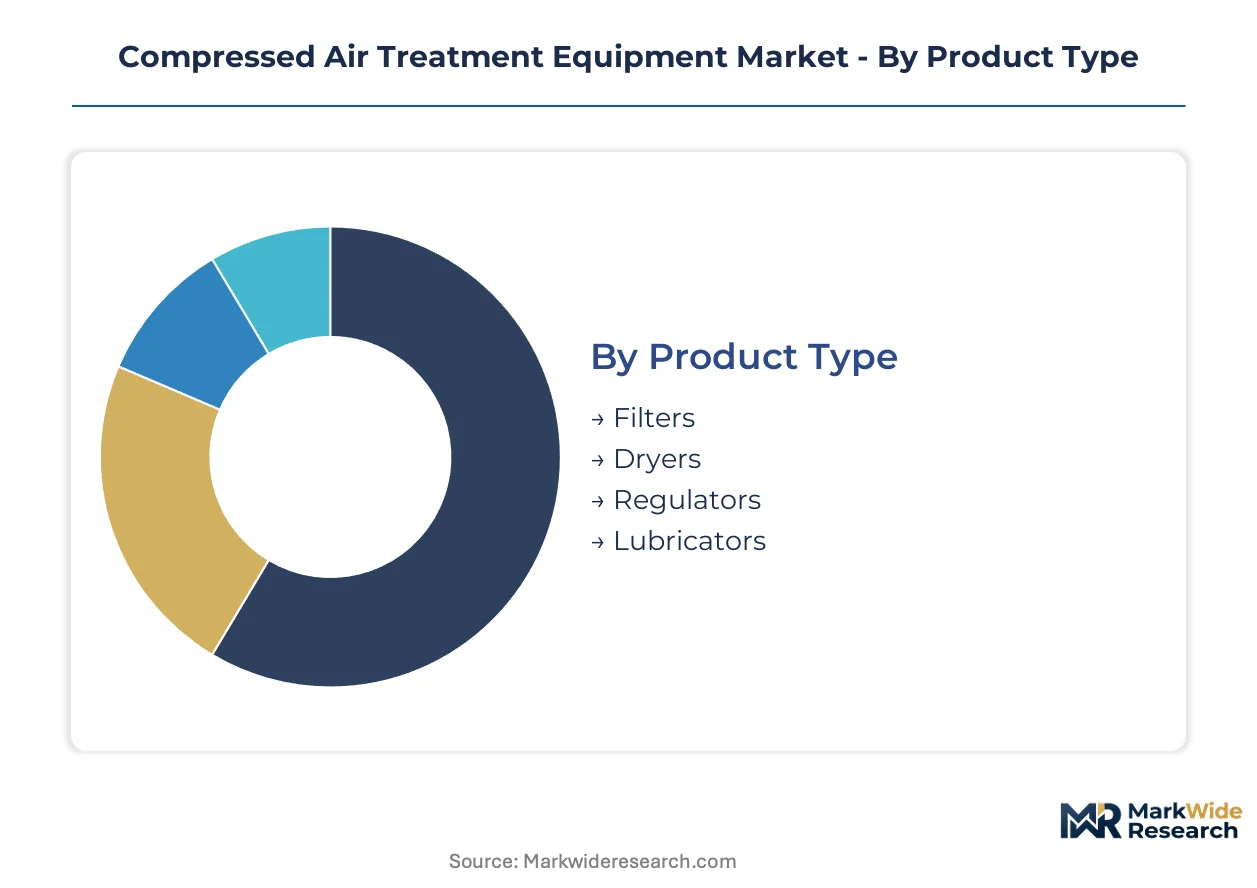
Compressed air treatment equipment serves radically different performance requirements across sterile pharmaceutical suites and general manufacturing floors. Segmentation reveals where technology premiums command pricing power versus commodity replacement cycles.
Product Type:
Equipment selection spans the moisture removal spectrum from bulk water separation to sub-zero dew point guarantees.
- Dryers:Refrigerated units achieve +3°C pressure dew points through mechanical cooling circuits, dominating general manufacturing in Germany and the United States where energy efficiency outweighs absolute dryness. Desiccant variants using activated alumina or molecular sieve media reach -40°C dew points, commanding premium positioning in pharmaceutical sterile suites and battery electrode coating lines where moisture-induced defects carry catastrophic costs.
- Filters:Coalescing and particulate filtration systems protect downstream pneumatic machinery from oil aerosols and corrosion-inducing contaminants. Demand concentrates in automotive tier-one supplier networks performing IATF 16949-mandated compressed air quality audits.
- Regulators:Pressure control devices stabilize pneumatic system performance across fluctuating demand profiles. Food processing facilities in France specify stainless steel variants for washdown compliance under EU hygiene regulations.
- Lubricators:Precision oil injection systems maintain pneumatic tool longevity in heavy-duty assembly environments. Deployment is contracting as ISO 8573-1 Class 0 oil-free mandates eliminate lubricated air from packaging and sterile applications.
The dominant share belongs to Dryers, while Filters is closing the gap fastest.
End User:
Regulatory stringency and contamination consequence determine technology investment thresholds across verticals.
- Pharmaceuticals:FDA Current Good Manufacturing Practice and EMA Annex 1 requirements mandate validated desiccant systems with continuous dew point monitoring. Sterile manufacturing suites in Hyderabad and Ahmedabad are installing first-time validated air systems ahead of CDSCO compliance deadlines.
- Automotive:Battery cell manufacturing in Stuttgart and Wolfsburg requires ultra-dry air systems to prevent lithium-ion electrode defects. Heat-of-compression desiccant technology is displacing refrigerated dryers in new press shop installations.
- Food Processing:ISO 8573-1 Class 0 oil-free mandates are forcing compressor-dryer replacement cycles across packaging lines. Facilities in Italy prioritize pre-certified refrigerant compliance to avoid EU F-Gas Regulation retrofit liabilities.
- Manufacturing:General industrial applications tolerate higher dew points, sustaining refrigerated dryer volumes. Midwest United States brownfield sites require custom manifold adaptations for smart monitoring retrofits without production shutdowns.
Pharmaceuticals captures the steepest expansion trajectory, while Automotive is gaining share fastest through electrification-driven battery investments.
Technology:
Physics-based separation mechanisms compete on energy intensity, footprint, and dew point floor.
- Desiccant:Adsorption media systems using heat-of-compression regeneration eliminate external heater energy consumption. Stuttgart OEMs specify these for Science-Based Targets compliance.
- Refrigerated:Mechanical cooling dominates installed base volumes where +3°C dew points suffice. EU F-Gas Regulation phase-downs are forcing R-134a and R-410A transitions toward CO₂ and hydrocarbon architectures.
- Membrane:Polymer separation suits portable and point-of-use installations prioritizing compact footprint. Performance ceiling at -20°C dew points excludes pharmaceutical sterile applications.
- Coalescing:Mechanical filtration removes oil and water aerosols through impaction and interception. Pharmaceutical cleanrooms demand Donaldson-specialized media technology for high-purity streams.
Refrigerated maintains volume leadership, while Desiccant is climbing the fastest on regulatory-driven replacement cycles.
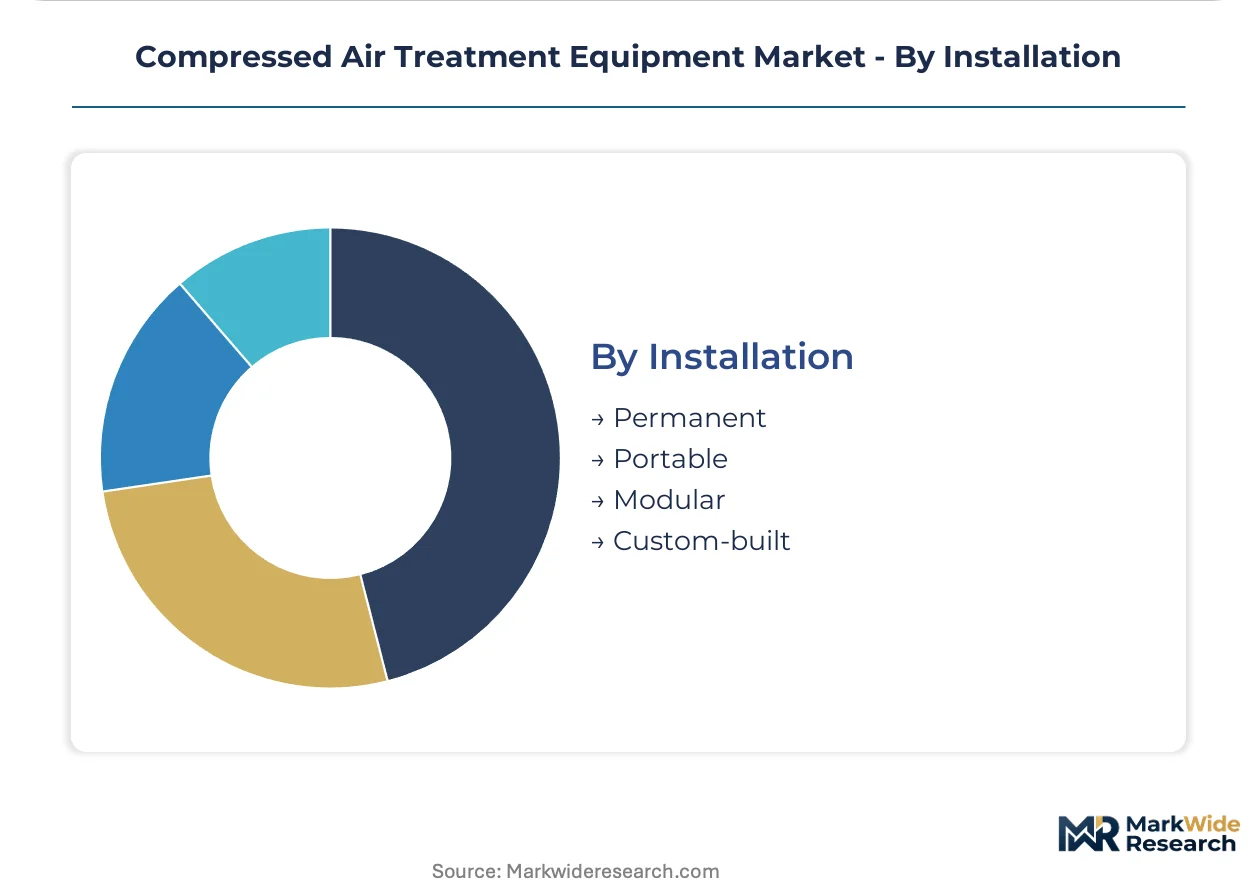
Installation:
Capital deployment models range from fixed infrastructure to flexible capacity augmentation.
- Permanent:Centralized systems anchor high-volume continuous manufacturing. German automotive OEMs specify these for new assembly line installations with 15-year depreciation horizons.
- Modular:Skid-mounted configurations enable capacity scaling without facility reconfiguration. Pharmaceutical contract manufacturers in India favor these for multi-product facility flexibility.
- Portable:Mobile units serve maintenance and construction applications. Point-of-use membrane dryers dominate this segment for energy minimization.
- Custom-built:Engineered systems address legacy infrastructure constraints. United States Midwest brownfield sites require these for smart retrofit integration.
Permanent installations hold the dominant position, while Modular is expanding most quickly through pharmaceutical contract manufacturing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs extract 40% pricing premiums for validated Class 0 systems compared to general manufacturing configurations in the United States Midwest. This asymmetry reflects regulatory stringency divergence and contamination consequence valuation across industrial clusters.
Germany
Automotive electrification and battery cell manufacturing dominate equipment procurement. EU F-Gas Regulation phase-downs accelerate refrigerant transitions toward CO₂ architectures. Stuttgart and Wolfsburg clusters specify heat-of-compression desiccant systems for new press shop installations.
United States
Food processing ISO 8573-1 Class 0 mandates and pharmaceutical sterile air validation drive replacement cycles. OSHA respiratory air standards overlay FDA Current Good Manufacturing Practice requirements. Midwest brownfield sites require custom manifold adaptations for smart monitoring retrofits without production shutdowns.
India
Pharmaceutical contract manufacturing expansion creates first-time demand for validated desiccant systems. CDSCO compliance deadlines for sterile manufacturing facilities approach in Hyderabad and Ahmedabad. These clusters prioritize modular skid-mounted configurations for multi-product facility flexibility.
France
Food processing facilities prioritize pre-certified refrigerant compliance to avoid EU F-Gas Regulation retrofit liabilities. Stainless steel regulators dominate washdown-compliant pneumatic installations. Lyon and Paris basin packaging lines lead Class 0 oil-free compressor replacement cycles.
South Korea
Battery electrode coating processes require ultra-dry air systems to prevent moisture-induced lithium-ion defects. Science-Based Targets commitments shape OEM thermal management specifications. Seoul and Ulsan manufacturing hubs anchor regional demand concentration.
Compressed Air Treatment Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in filtration media and adsorption substrates. The market structure consolidates around diversified industrial conglomerates with captive aftermarket service infrastructure. Three archetypes dominate: full-system integrators with lifecycle service contracts, filtration media specialists supplying high-purity streams, and compressed machinery OEMs with bundled treatment offerings. Competitive moves concentrate on vertical integration into monitoring software and geographic expansion through distributor network consolidation.
Among diversified industrial conglomerates, Atlas Copco AB and Ingersoll Rand Inc. exemplify the integrated platform model, while Donaldson Company, Inc. occupies a position within the filtration media specialist tier. Parker Hannifin Corporation represents the motion-and-control conglomerate archetype with cross-industrial pneumatic system penetration. These anchors demonstrate how scale-driven aftermarket infrastructure and regulatory certification depth determine competitive positioning in compliance-intensive procurement cycles.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| BOGE KOMPRESSOREN Otto Boge GmbH & Co. KG |
| Atlas Copco AB |
| SPX FLOW Inc. |
| Sullair Corporation |
| Ingersoll Rand Inc. |
| Donaldson Company, Inc. |
| ELGi Equipments Ltd. |
| Kaeser Kompressoren |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam freight corridors transmit cost volatility from activated alumina and molecular sieve production zones directly to European OEM margins, compressing configured-to-order premiums while amplifying price spreads between validated pharmaceutical systems and standard refrigerated units.
Pricing Analysis
Configured-to-order pricing for validated desiccant systems commands substantial premiums over standard refrigerated dryer configurations, with differentiation driven by ISO 8573-1 Class 0 certification depth and bundled lifecycle service contracts. Price erosion runs through general manufacturing tiers as Chinese membrane technology imports and refurbished equipment channels intensify competition. Pharmaceutical sterile suites exhibit lowest price sensitivity due to FDA validation requirements and contamination consequence valuation, while Midwest United States brownfield manufacturing sites prioritize total cost of ownership minimization above certification premiums.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk planning for desiccant media procurement, as activated alumina production concentrates in Shandong industrial zones and molecular sieve manufacturing clusters in Jiangsu province. European OEMs draw from these Chinese inputs while maintaining captive refrigerant compressor assembly in Bavaria and Baden-Württemberg. Single-source vulnerability in high-purity filtration media feeds from Donaldson's specialized production infrastructure. Distribution runs through industrial distributor networks consolidating around lifecycle service contracts rather than transactional component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward German automotive OEMs and pharmaceutical contract manufacturers as these segments consolidate vendor relationships under IATF 16949 and FDA quality mandates, extracting service bundling and validation documentation concessions from equipment suppliers.
For Market Incumbents: Pre-empt membrane technology encroachment in portable applications by accelerating heat-of-compression desiccant cost reduction programs and anchoring long-term service contracts in Stuttgart and Wolfsburg automotive clusters. Certification investment in EU F-Gas Regulation pre-compliant refrigerant architectures represents the critical defensive lever against margin compression from CO₂ system redesign costs. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical contract manufacturing by offering modular skid-mounted desiccant configurations with CDSCO validation support ahead of Hyderabad and Ahmedabad compliance deadlines. Target aftermarket service displacement in United States Midwest brownfield sites through smart monitoring retrofit packages requiring minimal production line shutdown. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward refrigerant technology specialists and heat-of-compression regeneration innovators with Science-Based Targets alignment. Long-term viability centers on service contract recurring revenue models rather than equipment transaction volumes. Monitor CDSCO enforcement intensity in Indian pharmaceutical clusters as the signal for validated system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-of-Compression Technology Scale-Up | Stuttgart OEMs specify these systems for Science-Based Targets compliance in new press shops. |
| Lifecycle Service Contract Penetration | German automotive tier-one suppliers consolidate vendor relationships under IATF 16949 mandates. |
| EU F-Gas Pre-Certification Investment | Italian and French food processors prioritize equipment avoiding mid-life refrigerant retrofit liabilities. |
| Modular Configuration Development | Indian pharmaceutical contract manufacturers demand skid-mounted flexibility for multi-product facilities. |
| Smart Monitoring Retrofit Integration | United States Midwest brownfield sites require custom manifold adaptations without production shutdowns. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, EU customs databases, and compressed air industry association reports, incorporating perspectives from maintenance directors at German automotive OEMs, pharmaceutical facility engineers in Hyderabad and Ahmedabad, and aftermarket service heads at European distributor networks. Bottom-up equipment shipment analysis triangulates against top-down manufacturing value-add estimates across the projection horizon.
Forecast inputs span product type segmentation by dryer technology class, end-user vertical regulatory intensity, and geographic cluster adoption patterns, with CAGRs derived from installed base replacement cycle modeling and electrification-driven battery manufacturing capacity expansion. Energy efficiency benchmarking and refrigerant transition cost curves inform technology mix projections throughout the forecast period.
Stress conditions across freight cost volatility, desiccant media supply concentration, and EU F-Gas enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic contraction in automotive capital expenditure, regulatory delay in Indian pharmaceutical compliance deadlines, or breakthrough membrane technology performance improvement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
US Residential Heat Pump Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Global Air Curtain Market