
 Underfloor Heating Market | 2026-2036
Underfloor Heating Market Size, Share, and Industry Trends Forecast 2026-2036
Underfloor Heating Market Analysis
European boiler manufacturers and piping suppliers is restructuring capacity around low-temperature heat distribution networks. Danfoss anchors its position through advanced mixing stations and zone controls for hydronic loops. Uponor Corporation leverages cross-linked polyethylene expertise to sustain dominance in flexible piping for embedded floor systems. Warmup competes aggressively in electric mat segments through direct-to-installer channel control across the United Kingdom and Ireland.
Underfloor heating distributes thermal energy through embedded electric resistance cables or hydronic tubing within floor substrates, operating at fluid temperatures of 35-45°C versus 60-80°C for conventional radiator systems to deliver radiant heat transfer with lower exergy loss. Hydronic systems occupy the largest installed base in new European construction due to compatibility with heat pumps, while electric heat mats represent the fastest-growing retrofit category where boiler replacement proves impractical. Thermostat and control components capture disproportionate margin pools as building automation integration becomes standard specification.
The EU Green Deal and F-Gas Regulation tighten minimum efficiency requirements for space heating systems across member states, while Ecodesign directives mandate smart controls that modulate floor circuit temperatures based on occupancy patterns. National building codes in Germany and France now require renewable-ready heating infrastructure in new residential permits. Stakeholders must monitor heat pump deployment trajectories and grid electrification timelines to calibrate product mix between hydronic and electric architectures.
Market Dynamics
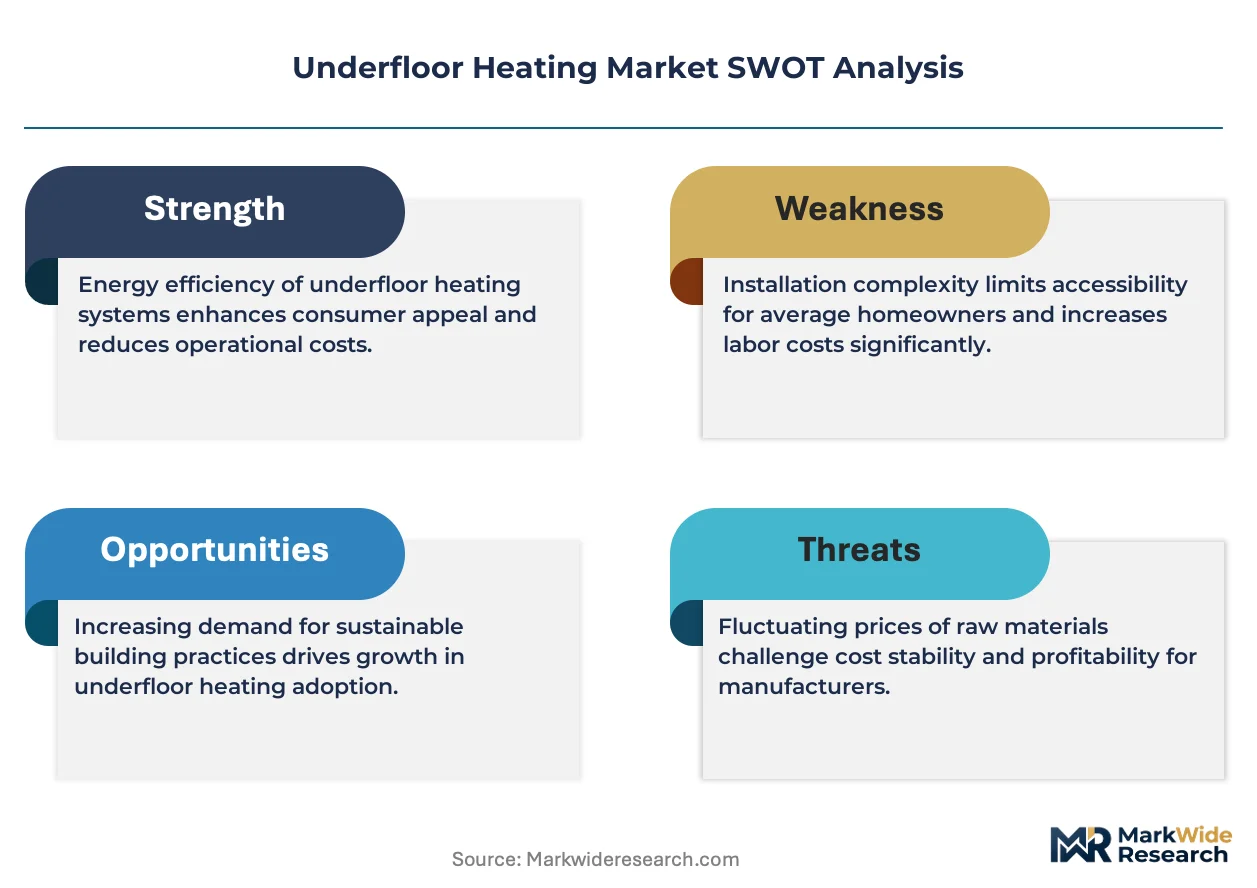
The EU F-Gas Regulation is compressing refrigerant-based heating alternatives and redirecting capital toward low-temperature hydronic distribution compatible with heat pump architectures.
Growth Catalysts
- Heat pump compatibility:Germany's renewable-ready building codes now mandate infrastructure for future heat pump connection, accelerating specification of hydronic tubing systems in new residential permits.
- EU Green Deal efficiency mandates:Ecodesign directives require smart controls that modulate circuit temperatures based on occupancy, expanding thermostat and zone control deployment across member states.
- Nordic residential retrofit concentration:Denmark, Sweden, and Norway exhibit dense demand for electric mat systems where district heating conversion proves impractical.
Market Restraints
- Copper and polymer input volatility:Cross-linked polyethylene and PEX-A resin prices fluctuate with petrochemical feedstock costs, compressing margin stability for piping manufacturers.
- Installer capacity bottlenecks:Certified wet-system installation skills concentrate in Germany and the Netherlands, limiting deployment velocity in peripheral EU markets.
- Upfront capital intensity:Hydronic system first costs exceed electric mat alternatives by substantial multiples, constraining adoption in price-sensitive renovation segments.
Strategic Opportunities
- France regulatory tailwind:RE2020 environmental regulations tighten new-build heating emissions thresholds, creating specification pull for low-temperature distribution systems.
- Building automation convergence:Integration of floor sensors with BACnet and KNX protocols enables predictive thermal mass management, opening premium specification tiers.
- Direct-to-installer channel innovation:Digital platforms bypass traditional merchant intermediaries in the United Kingdom and Ireland, capturing margin and data assets.
Industry Challenges
- Heat pump synchronization complexity:Optimizing flow temperatures across variable-speed compressors demands controls engineering capabilities scarce among traditional plumbing contractors.
- CE marking and Ecodesign compliance timelines:Smart thermostat certification requires documentation of interoperability testing that extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underfloor Heating Market |
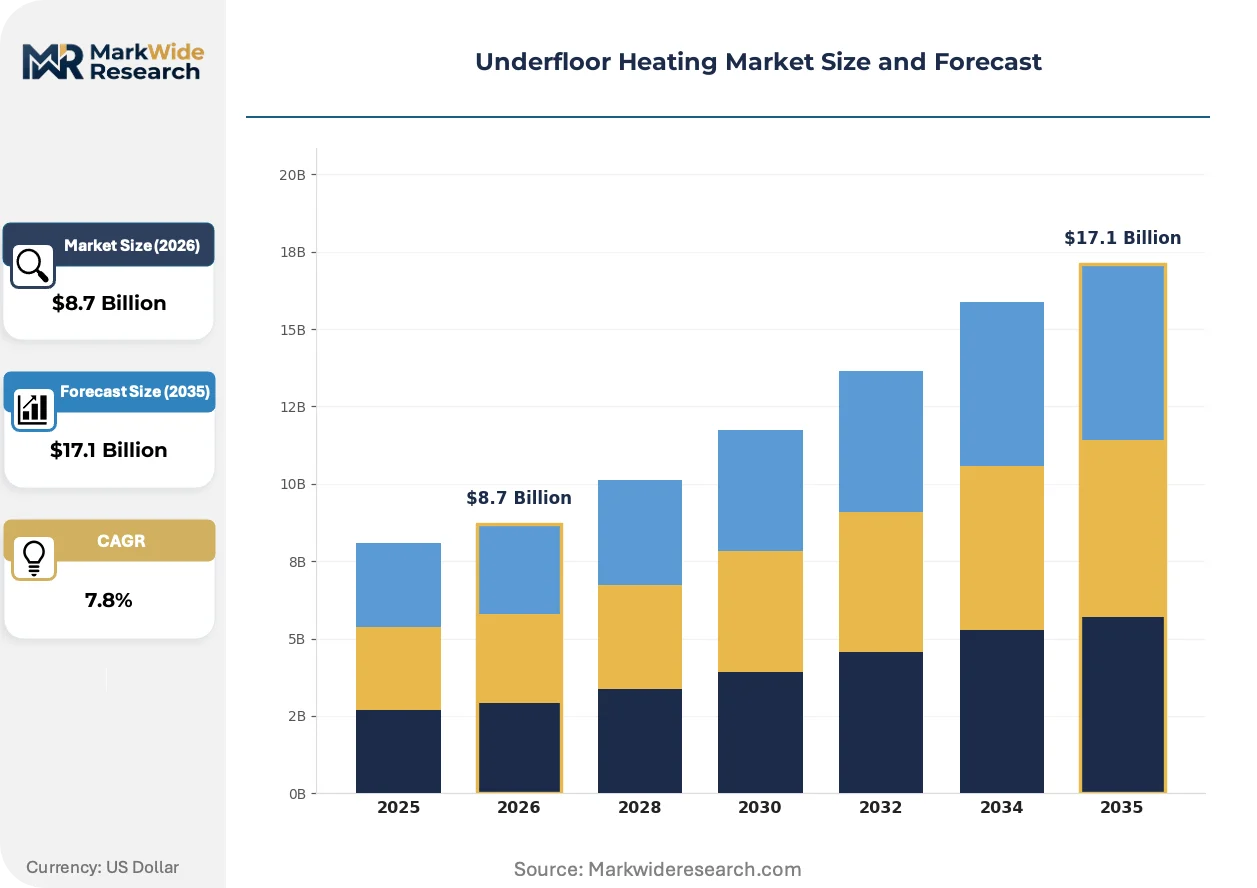
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hydronic, Radiant, Thermo-active Installation Type: Retrofit, New Construction, Commercial, Residential System Component: Thermostats, Heat Mats, Piping, Insulation End User: Homeowners, Contractors, Property Developers, Builders |
| Companies Covered | Resideo Technologies Inc, nVent Electric plc, Danfoss, Uponor Corporation, Warmup, Rehau, Emerson Electric Co, Robert Bosch, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underfloor Heating Market Emerging Trajectories
Control intelligence and material science are converging to reposition underfloor heating from passive infrastructure to active grid-responsive assets.
Phase-change materials embedded in screed substrates are absorbing excess daytime thermal energy and releasing it during peak evening demand periods. German multi-family developers are piloting these systems in Passivhaus-certified projects. The technology is absorbing conventional battery storage value propositions in grid-stabilization service contracts.
The EU F-Gas Regulation's stepped refrigerant phase-down is accelerating heat pump deployment timelines across member states. Boiler manufacturers are restructuring distribution networks around low-temperature compatibility. Residential new-build specifications in France and Germany now exclude monobloc refrigerant systems from permitted technology lists.
Installer purchasing behavior is consolidating around bundled procurement of tubing, manifolds, and controls from single-source platforms. United Kingdom merchant distributors are responding with private-label system packages that disassemble traditional brand-loyalty patterns. Channel concentration is most visible in urban renovation corridors where project velocity demands same-day fulfillment.
Underfloor Heating Market Segmentation
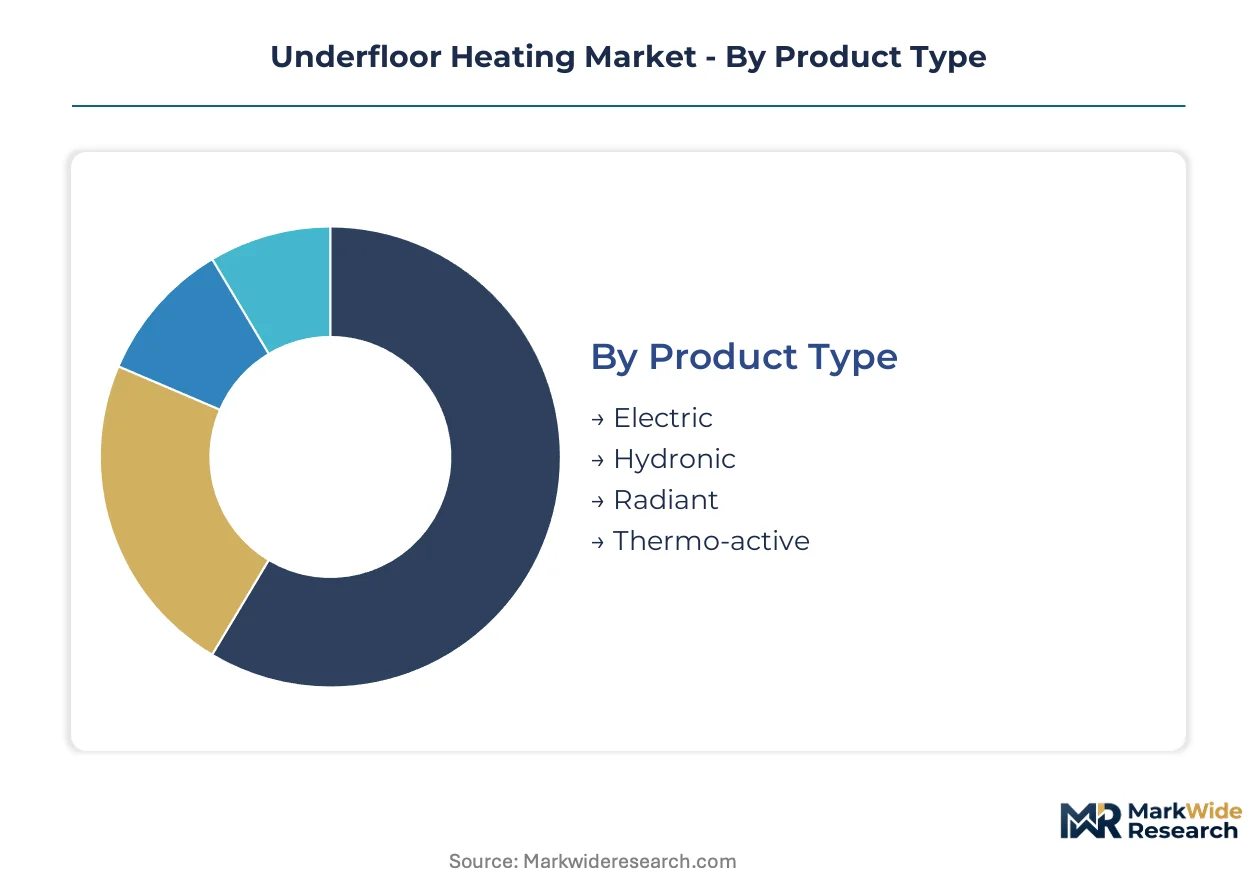
Underfloor heating architectures diverge sharply in upfront capital requirements, installation complexity, and compatibility with renewable heat sources. Product and installation type classifications determine project feasibility across new-build and renovation contexts, while component and end-user segmentation shapes procurement patterns and margin capture.
Product Type:
Hydronic systems demand the highest capital commitment due to boiler infrastructure, manifold assemblies, and wet-screed installation protocols.
- Hydronic:Fluid-based distribution networks circulate heated water through embedded polyethylene tubing at 35-45°C flow temperatures. German and French residential new-build specifications favor this architecture for heat pump compatibility under renewable-ready building codes.
- Electric:Resistance cable or thin-film mat systems install directly beneath floor finishes without wet trades. Nordic single-family retrofits concentrate demand where district heating connection proves uneconomical and boiler replacement is impractical.
- Radiant:Surface-mounted panels or ceiling-integrated elements deliver radiant asymmetry for commercial atriums and heritage buildings with structural constraints.
- Thermo-active:Phase-change material screeds absorb daytime thermal energy for evening release, piloting in German Passivhaus multi-family developments.
Hydronic systems absorb the bulk of installed capacity in new European construction; electric heat mats are expanding most quickly in renovation corridors.
Installation Type:
Volume concentrates in residential applications, though commercial specifications command premium pricing for zone control complexity.
- New Construction:Greenfield projects integrate underfloor heating at slab-pour stage, minimizing incremental labor cost. France's RE2020 regulations mandate low-temperature distribution readiness, embedding specification into foundation work.
- Retrofit:Existing building stock drives electric mat adoption where floor height constraints prohibit wet-system screed buildup. United Kingdom terraced housing and Nordic apartment conversions exhibit dense demand.
- Residential:Single-family and multi-family housing dominates unit volume, with German developers bundling hydronic infrastructure into renewable-ready permits.
- Commercial:Office and hospitality specifications prioritize BACnet-integrated zone controls for demand-responsive thermal mass management.
New construction captures the majority of hydronic system deployment; retrofit applications are climbing the fastest as building stock renovation accelerates under EU Green Deal targets.
System Component:
Control components capture disproportionate margin pools as building automation integration becomes standard specification.
- Thermostats:Smart controls with occupancy sensing and weather compensation modulate circuit temperatures per Ecodesign mandates. CE marking and interoperability testing extend certification timelines.
- Piping:Cross-linked polyethylene and PEX-A tubing form the distribution backbone, with resin price volatility compressing manufacturer margins.
- Heat Mats:Electric resistance elements in mesh or thin-film configurations suit low-profile retrofit installations with minimal floor buildup.
- Insulation:Extruded polystyrene and acoustic barrier boards reduce downward heat loss and improve system response times in multi-family construction.
Piping and insulation absorb the bulk of material volume; thermostats are gaining share fastest as smart control mandates proliferate across member states.
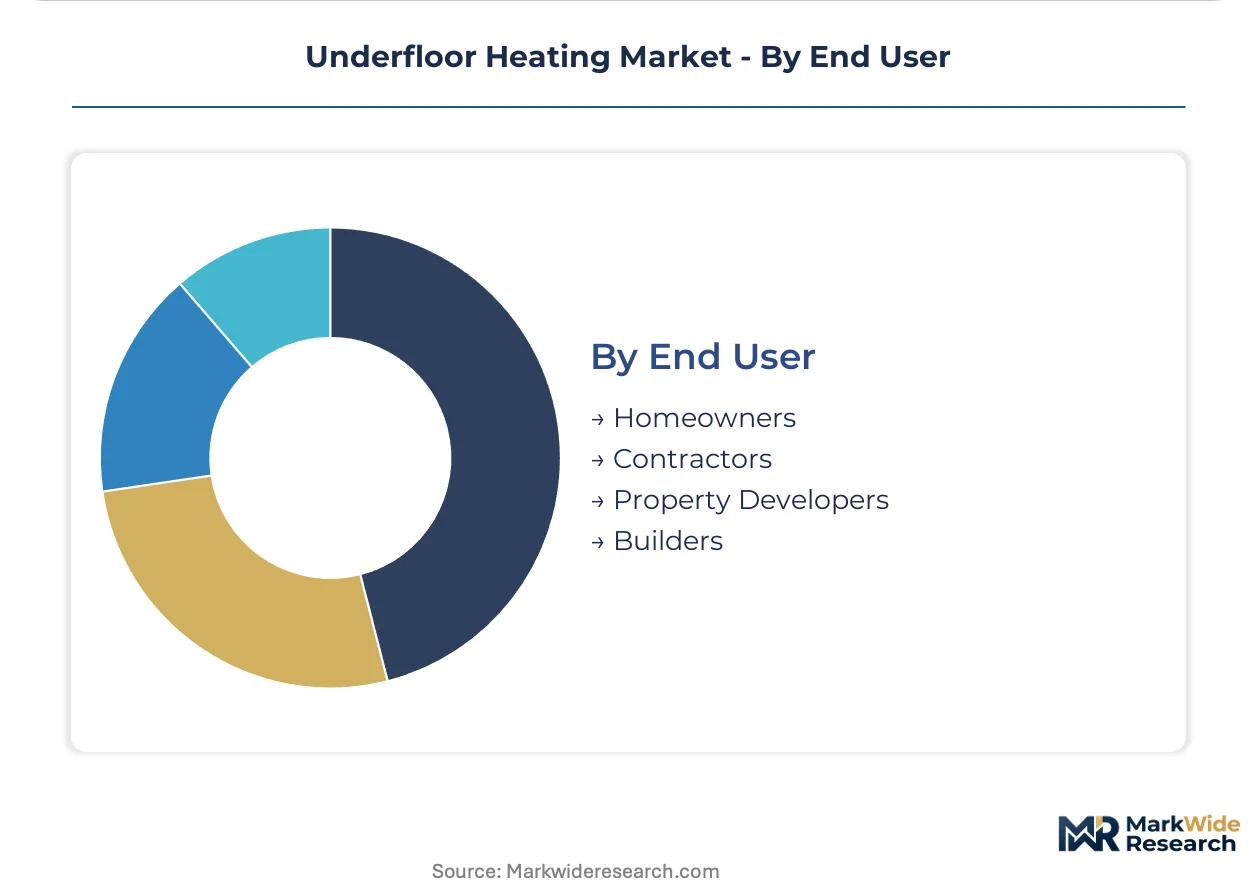
End User:
Procurement authority concentrates with contractors and developers in new-build channels, while homeowners dominate direct-to-consumer electric mat segments.
- Contractors:Plumbing and heating specialists specify integrated hydronic systems, with certified wet-system skills concentrating in Germany and the Netherlands.
- Property Developers:Multi-family project sponsors bundle underfloor heating into renewable-ready infrastructure packages to secure French and German building permits.
- Builders:Volume housebuilders negotiate system packages through merchant distributors, with UK private-label consolidation disassembling traditional brand loyalty.
- Homeowners:Direct purchasing of electric mat kits through digital platforms bypasses traditional intermediaries in UK and Irish renovation markets.
Contractors and developers absorb the bulk of specification authority; homeowners are expanding most quickly as direct-to-installer digital channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene resin production clusters in Belgium and the Netherlands anchor European supply chains for hydronic tubing systems. German and French building codes now mandate renewable-ready heating infrastructure. Nordic retrofit corridors concentrate electric mat demand where district heating conversion proves uneconomical.
Germany
Residential construction in Bavaria and North Rhine-Westphalia drives hydronic system specification for heat pump compatibility. The country's renewable-ready building codes embed low-temperature distribution requirements into new permits. Certified wet-system installer skills concentrate in Stuttgart and Munich, creating deployment bottlenecks in eastern Länder.
France
RE2020 environmental regulations tighten emissions thresholds for new-build heating across Île-de-France and Auvergne-Rhône-Alpes. The Ecodesign directive mandates smart thermostat deployment with occupancy-based temperature modulation. Lyon and Grenoble multi-family developers pilot phase-change material screeds in Passivhaus-certified projects.
United Kingdom
Terraced housing renovation in London and Manchester accelerates electric mat adoption where floor height constraints prohibit wet-system buildup. Merchant distributors respond with private-label system packages that disassemble traditional brand-loyalty patterns. Digital platforms bypass intermediaries in direct-to-installer channels across Greater London.
Denmark
Single-family retrofit demand concentrates in Copenhagen suburbs where district heating connection proves impractical for detached properties. The EU F-Gas Regulation redirects capital toward heat pump-compatible hydronic architectures. Aarhus and Odense exhibit dense specification of zone controls for demand-responsive thermal management.
Sweden
Apartment conversions in Stockholm and Gothenburg drive thin-film electric mat specification for minimal floor buildup. National building efficiency standards align with EU Green Deal targets for smart control integration. Malmö developers bundle underfloor heating into renewable-ready infrastructure packages.
Underfloor Heating Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue building automation integration and phase-change material innovation. The market structures around three tiers: multinational HVAC conglomerates with heat pump portfolios, specialized piping and control manufacturers, and regional electric mat suppliers. Three archetypes dominate: integrated system bundlers, component specialists with resin expertise, and direct-channel disruptors. Competitive moves concentrate on strategic partnerships with heat pump OEMs and capacity restructuring around low-temperature distribution networks.
Among diversified industrial conglomerates, Danfoss and Uponor Corporation exemplify the component-specialist archetype with established positions in mixing stations and cross-linked polyethylene systems. Warmup occupies a position within the direct-channel disruptor tier. These three entities represent distinct strategic postures: resin-to-tube vertical control, hydronic loop engineering, and installer-platform bypass of traditional merchant intermediaries.
| Leading Market Players |
|---|
| Resideo Technologies Inc |
| nVent Electric plc |
| Danfoss |
| Uponor Corporation |
| Warmup |
| Rehau |
| Emerson Electric Co |
| Robert Bosch |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Volume housebuilders and multi-family developers in Germany and France command project-based pricing leverage through bundled procurement of tubing, manifolds, and controls from single-source platforms. Their consolidated purchasing power compresses margins for piping manufacturers while elevating premium capture for thermostat suppliers with CE-marked smart control portfolios.
Pricing Analysis
Warranty and commissioning service bundling separates premium hydronic system suppliers from unbundled electric mat competitors in renovation channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and heat pump synchronization complexity. Cost compression in standard-tier piping is intensifying because cross-linked polyethylene resin prices fluctuate with petrochemical feedstock volatility. Renovation homeowners exhibit highest price sensitivity; commercial developers with Passivhaus mandates show lowest.
Supply Chain Analysis
Freight cost escalation from Belgian and Dutch polyethylene resin clusters to German and French construction corridors shapes inventory positioning strategies for tubing manufacturers. Supply concentrates in Belgium, the Netherlands, and Germany for PEX-A resin and extrusion capacity. The network draws from petrochemical feedstocks, copper for manifolds, and electronic components for smart thermostats. Single-source vulnerability runs through certified wet-system installer skills concentrated in Stuttgart and Munich. Distribution runs through merchant distributors in the United Kingdom and direct-to-installer digital platforms in Ireland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified wet-system installer scarcity props pricing power for qualified hydronic contractors while constraining deployment velocity in peripheral EU markets.
For Market Incumbents: Cement control over mixing station and zone control engineering capabilities before heat pump OEMs internalize hydronic loop optimization. Acquire specialist controls firms with BACnet and KNX protocol expertise. Defend against direct-channel disruptors by embedding proprietary digital platforms within installer certification programs. For New Entrants and Emerging Players: Enter via thin-film electric mat segments in Nordic single-family retrofits where district heating conversion proves uneconomical. Target Copenhagen suburbs and Stockholm apartment conversions with minimal floor buildup requirements. Pursue private-label partnerships with United Kingdom merchant distributors seeking same-day fulfillment capabilities. For Investors and Strategic Acquirers: The window for entry favors component specialists with resin-to-tube vertical control and smart thermostat interoperability portfolios. Long-term viability hinges on heat pump deployment trajectories and grid electrification timelines across member states. Monitor RE2020 regulatory enforcement in French new-build permits as inflection indicator for low-temperature distribution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PEX-A Resin | Captive supply of cross-linked polyethylene secures margin stability against petrochemical volatility. |
| Smart Control Certification Investment | CE marking and Ecodesign compliance accelerates thermostat deployment under EU Green Deal mandates. |
| Direct-to-Installer Platform Launch | Digital channel bypass of UK merchant intermediaries captures margin and behavioral data assets. |
| Heat Pump OEM Partnership | Strategic alignment with variable-speed compressor manufacturers optimizes flow temperature synchronization. |
| Phase-Change Material Screed Pilot | Passivhaus-certified German multi-family projects absorb battery storage value propositions in grid contracts. |
Methodological Framework
Independent corroboration across hydronic system manufacturers, electric mat distributors, and heat pump OEMs underwrites the qualitative findings in this study. Primary interviews with plumbing and heating contractors, multi-family developers, merchant distribution buyers, and building automation integrators combined with secondary validation from EU Ecodesign directive filings, F-Gas Regulation compliance databases, and national building permit records. Bottom-up project pipeline analysis and top-down construction spend triangulation anchored volume estimates.
Rate-of-change decomposition across product type, installation context, system component, and end-user procurement authority shaped the analytical framework. Segmentation dimensions modeled include hydronic versus electric architecture, new-build versus retrofit application, and smart control integration tier. CAGRs derived from construction permit trajectories, heat pump deployment curves, and renovation expenditure patterns across the projection horizon. Grid electrification timelines and renewable-ready building code enforcement schedules served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under F-Gas Regulation acceleration or copper and polymer input volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
China HVAC Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
France Commercial HVAC Market