
 Global Transportation Infrastructure Market | 2026-2036
Global Transportation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transportation Infrastructure Market Analysis
Market Context with Strategic Players
The divergence between premium expedited freight and commodity less-than-truckload services is repositioning capital allocation across the sector. Old Dominion Freight Line leverages its dense terminal network to sustain superior transit times in the premium tier. J.B. Hunt Transport Services anchors intermodal dominance through proprietary container fleets and rail partnerships. XPO Logistics differentiates via technology-heavy brokerage platforms that compete on digital matching speed rather than asset ownership alone.
Technical Definition and Structural Segments
Transportation infrastructure comprises the physical systems and structures enabling the movement of goods and passengers, including roadbeds designed for specific axle load ratings, bridge spans engineered to precise deflection tolerances, rail track with standardized gauge and metallurgy, and airport runways graded for aircraft weight categories. The primary purpose spans commercial freight efficiency, commuter reliability, and national supply chain resilience. Roads and railways occupy the largest share of public capital expenditure, while sustainable construction methods represent the fastest-expanding category as agencies embed lifecycle carbon accounting into procurement. Modular and precast approaches concentrate margin pools through factory-controlled quality and reduced site labor exposure.
Regulatory Frame and Forward-Looking Close
The U.S. Department of Transportation, the European Union's F-Gas Regulation and CE marking frameworks, and India's Ministry of Road Transport and Highways collectively shape material standards, emissions thresholds, and cross-border interoperability requirements. These bodies mandate recycled content minimums, safety inspection protocols, and competitive bidding transparency that filter market access. Stakeholders must monitor which regulatory jurisdictions tighten embodied carbon rules fastest, as this will determine where infrastructure OEMs must retool material sourcing and where project finance faces green premium arbitrage.
Market Dynamics
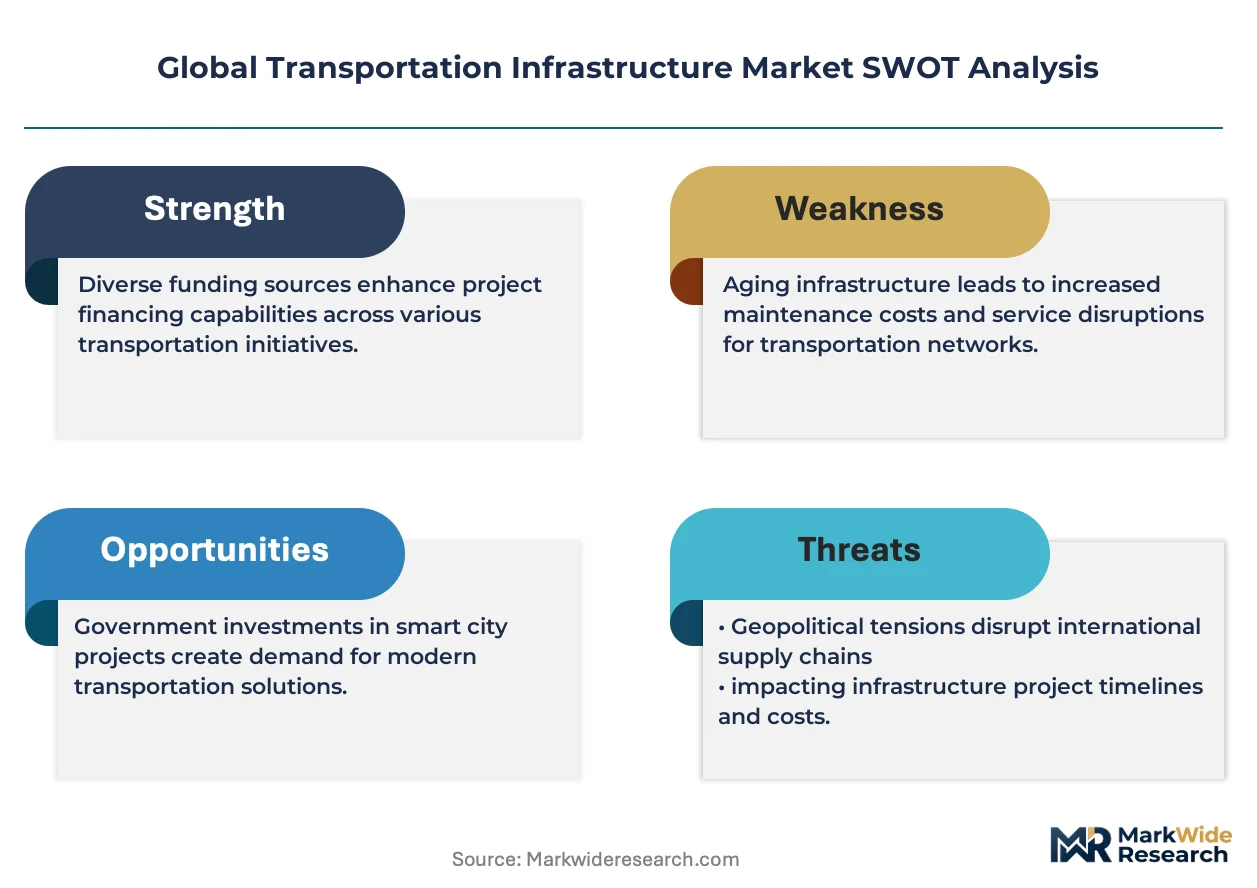
Capital allocation across transportation infrastructure is pivoting toward lifecycle carbon accounting as the EU Green Deal and India's National Infrastructure Pipeline embed embodied emissions thresholds into procurement scoring. This structural force compresses margins for conventional material suppliers while rewarding precast and modular construction methods that reduce site labor exposure and quality variance.
Growth Catalysts
- EU Green Deal procurement mandates:European transit authorities now weight recycled steel and low-carbon concrete in competitive bidding, redirecting material sourcing toward certified suppliers.
- India's dedicated freight corridor buildout:The National Infrastructure Pipeline prioritizes multimodal logistics hubs and heavy-haul rail, concentrating steel and cement demand in corridor-adjacent states.
- Intelligent traffic management adoption:Megacity transit authorities are procuring sensor-integrated signal systems to reduce intersection congestion and fuel waste.
Market Restraints
- Scrap steel supply concentration:Quality recycled steel availability clusters in industrialized port regions, creating input cost volatility for inland precast factories.
- Low-carbon concrete technical limits:Supplementary cementitious materials reduce early-strength performance, constraining deployment in fast-track bridge repairs.
- CE marking friction for modular components:Factory-controlled precast elements face multi-jurisdiction certification delays that extend project timelines.
Strategic Opportunities
- Underpenetrated African corridor development:Trans-African highway initiatives lack integrated logistics hubs, creating white space for multimodal terminal operators.
- Carbon capture concrete curing:Mineralization technology during precast production offers pathway to negative-emission structural elements for EU public tenders.
- Performance-based maintenance contracts:Brazilian state highway agencies are piloting availability-payment models that transfer pavement deterioration risk to contractors.
Industry Challenges
- Geotechnical engineer scarcity:Specialized foundation design expertise for soft-soil megaprojects concentrates in aging professional cohorts with limited training pipeline replacement.
- Legacy rail signaling integration:European corridor upgrades must interface century-old mechanical interlockings with digital ETCS, multiplying commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transportation Infrastructure Market |
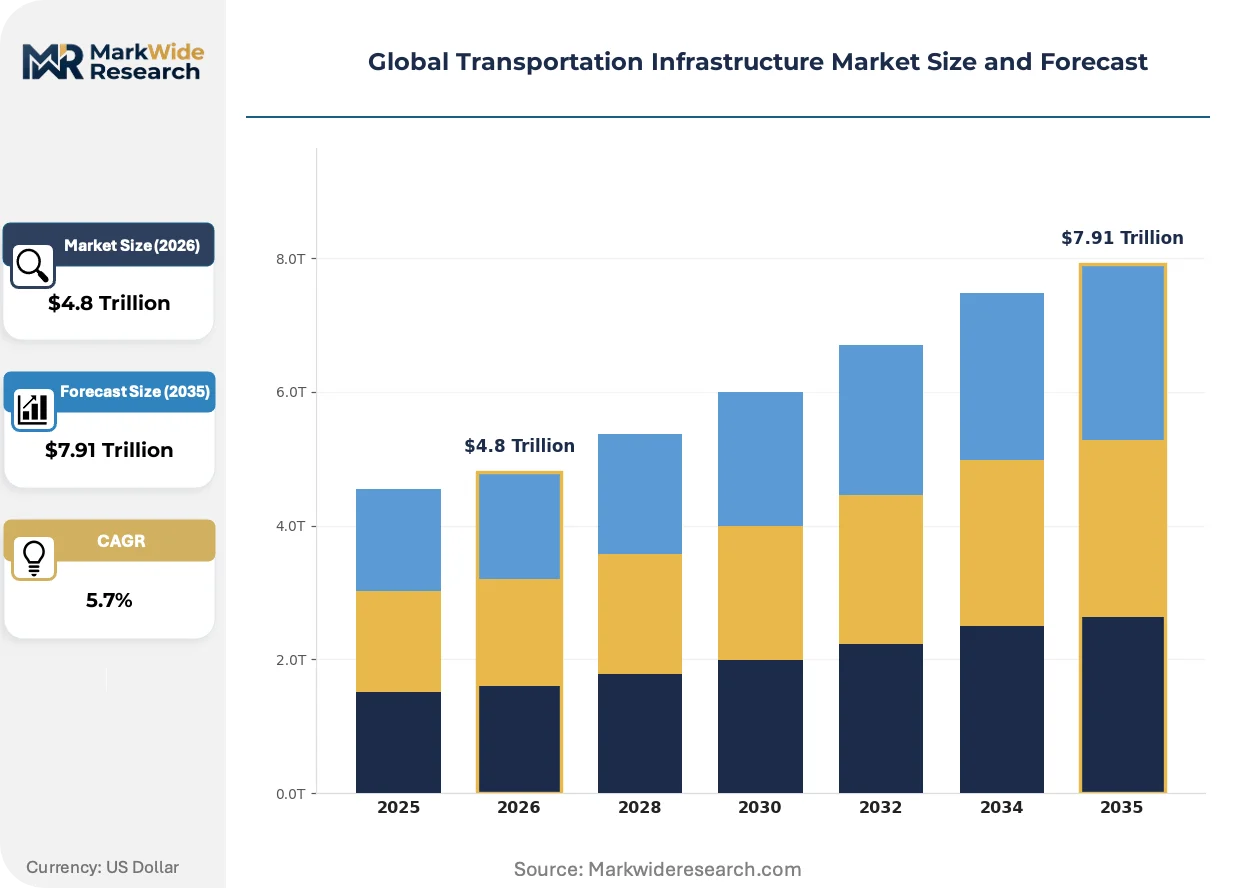
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $7.91 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Roads, Bridges, Railways, Airports Construction Method: Traditional, Modular, Precast, Sustainable Material Used: Concrete, Steel, Asphalt, Composite End User Sector: Public, Private, Government, Utilities |
| Companies Covered | Estes Express Lines, ABF Freight, FedEx Freight, J.B. Hunt Transport Services, R+L Carriers, Old Dominion Freight Line, Saia Inc, Knight-Swift Transportation, XPO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transportation Infrastructure Market Emerging Trajectories
Distributed ledger and sensor fusion technologies are compressing trust costs in infrastructure procurement while modular fabrication methods rewrite where value capture occurs in the construction value chain.
Blockchain-enabled material provenance tracking is decentralizing supplier verification across EU public works. Contractors in Germany and France now record steel heat numbers and concrete batch certificates on permissioned ledgers accessible to inspectors and financiers. This compression of documentation friction is accelerating payment cycles and reducing bond collateral requirements for certified suppliers.
REACH authorization timelines for construction chemicals are extending substitution planning horizons for European waterproofing and corrosion-protection systems. Formulators must pre-register novel admixtures years ahead of deployment, forcing earlier R&D commitment and favoring incumbent chemical majors with regulatory affairs capacity over specialty entrants.
Brazilian and Indian state transport departments are unbundling design-build-maintain contracts into separate operational and capital expenditure lots. This separation permits asset managers to bid maintenance availability without construction risk, while pure-build contractors face compressed margins and heightened surety requirements. The model is concentrating in federal highway programs where long-term pavement performance data supports predictive maintenance pricing.
Global Transportation Infrastructure Market Segmentation
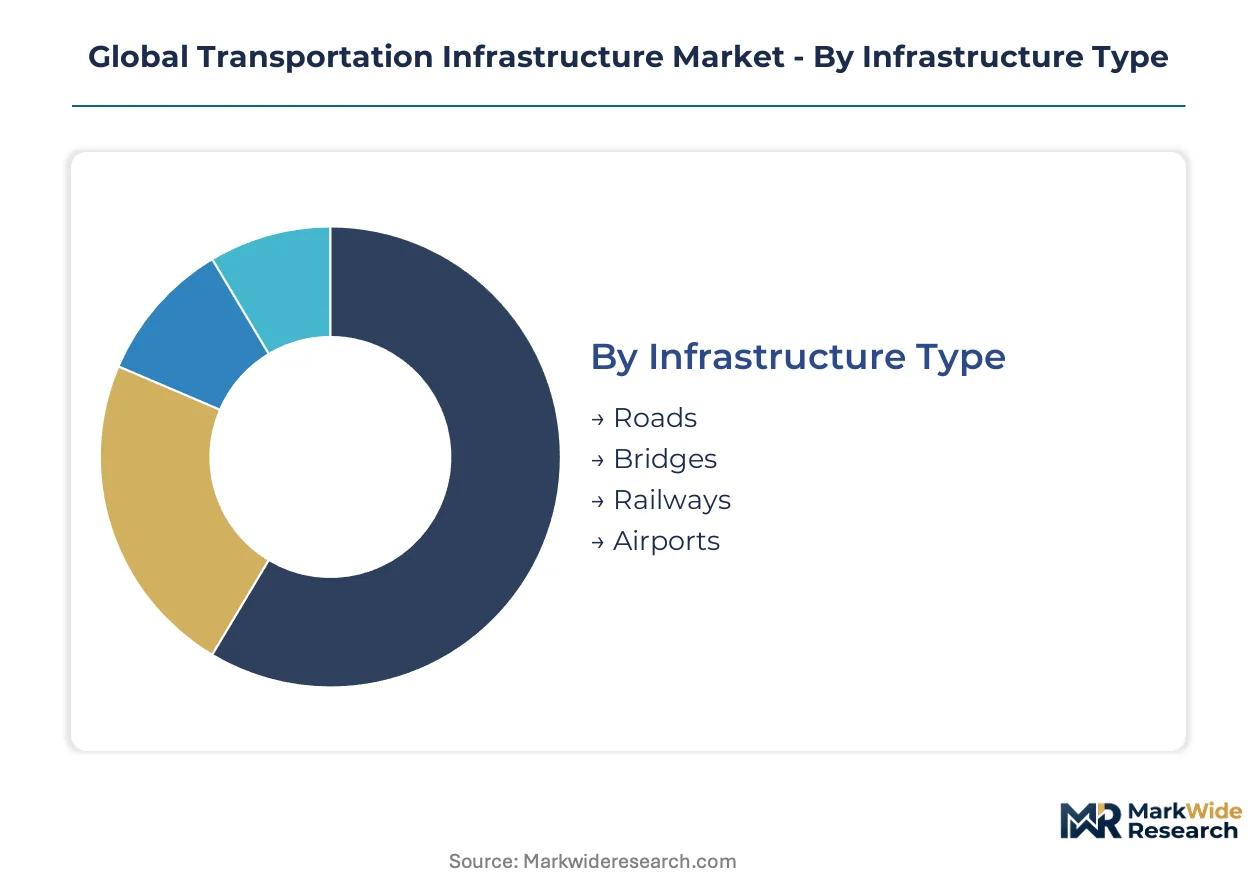
Segmentation in transportation infrastructure reveals where capital efficiency diverges from technical performance. Procurement officers weight lifecycle cost against speed-to-completion, while regulators impose material standards that reshape supplier viability across each category.
Infrastructure Type:
Roads and railways absorb the bulk of public capital expenditure, while airports command premium engineering margins due to specialized pavement and navigation system requirements.
- Roads:Flexible and rigid pavement designs serve distinct traffic load profiles, with asphalt dominating high-volume interstates and concrete anchoring heavy-haul industrial corridors. Demand concentrates in India's state highway expansion programs where the Ministry of Road Transport and Highways prioritizes lane additions in freight-intensive states.
- Bridges:Span configurations range from simple beam structures to cable-stayed systems engineered for seismic resilience and navigational clearance. European procurement under EU Green Deal frameworks now mandates recycled steel content thresholds, redirecting sourcing toward electric-arc-furnace suppliers in port-adjacent industrial zones.
- Railways:Heavy-haul track with 60E1 rail profiles and concrete sleeper systems supports dedicated freight corridors.
- Airports:Runway pavement engineered to PCN ratings and precision approach lighting systems integrate with terminal automation.
Mature deployment sits with roads. Newer deployment is concentrated in airport expansion projects across high-growth aviation markets.
Construction Method:
Speed-to-completion now dominates procurement scoring, elevating factory-controlled methods over weather-dependent site casting.
- Traditional:Cast-in-place concrete and stick-built steel erection remain standard for complex geometries and remote sites lacking precast logistics infrastructure. India's National Infrastructure Pipeline maintains traditional methods for rural road programs where modular supply chains remain underdeveloped.
- Modular:Standardized bridge deck panels and tunnel lining segments compress project schedules through parallel factory and site preparation workflows. Demand clusters in Germany's Autobahn renewal programs where overnight lane closures require rapid installation sequences.
- Precast:Factory-cured structural elements with controlled curing environments achieve consistent compressive strength and dimensional tolerance.
- Sustainable:Low-carbon concrete mixes and mass timber structural systems embed embodied carbon accounting into design specifications.
Traditional methods retain dominance in emerging economies with limited precast logistics. Modular and precast approaches are climbing the fastest in European and East Asian markets with mature supplier networks.
Material Used:
Material selection increasingly hinges on carbon intensity verification rather than first-cost optimization alone.
- Concrete:Ordinary Portland cement blends face displacement by supplementary cementitious material formulations that reduce clinker content. European transit authorities under EU Green Deal procurement rules now weight Environmental Product Declaration scores, favoring producers with vertical integration into slag and fly ash supply.
- Steel:Structural sections and reinforcing bar specifications differentiate between basic oxygen furnace and electric arc furnace production routes. India's dedicated freight corridor buildout concentrates demand for high-strength quenched and tempered rail steel from domestic integrated mills.
- Asphalt:Polymer-modified binders and warm-mix formulations reduce production temperature and extend paving seasons.
- Composite:Fiber-reinforced polymer reinforcing bars and bridge deck panels offer corrosion immunity in marine and de-icing salt environments.
Concrete and steel retain volume leadership. Composite materials are gaining share fastest in coastal and chemically aggressive exposure conditions.
End User Sector:
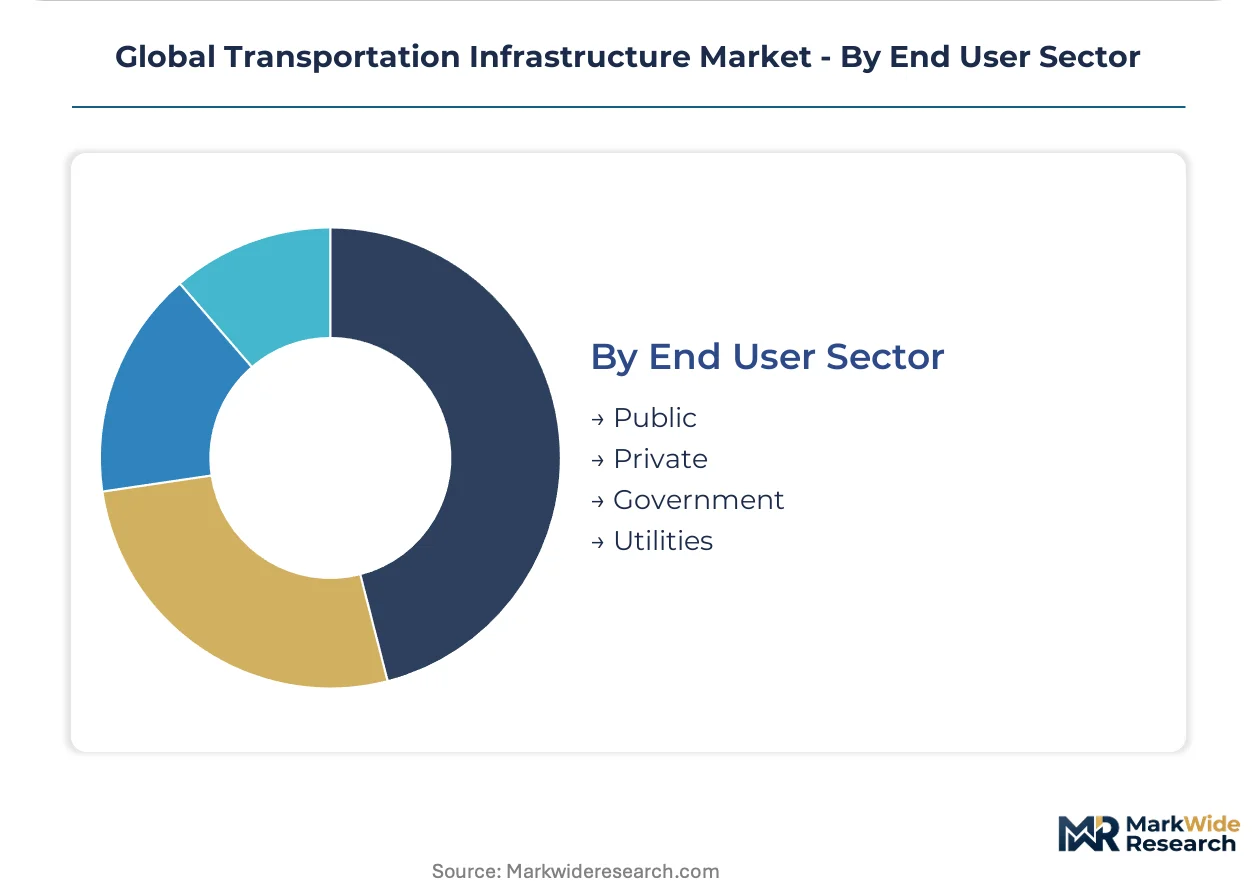
Payment security and contract duration vary sharply across ownership structures, filtering bidder pools by balance sheet capacity.
- Public:Municipal and state agencies fund road and bridge maintenance through fuel tax receipts and general obligation bonds. Procurement in Brazil's state highway programs now pilots availability-payment maintenance contracts that transfer pavement performance risk to contractors.
- Private:Industrial facility owners and logistics operators build captive road and rail spurs to secure supply chain control. Mining and port terminal operators in Australia's Pilbara region finance heavy-haul rail infrastructure with off-take agreements anchoring project finance.
- Government:Federal programs coordinate interstate and international corridor development with standardized design specifications.
- Utilities:Power transmission and pipeline right-of-way maintenance generates recurring access road and crossing structure demand.
Public sector procurement dominates mature markets. Private sector investment is expanding most quickly in resource extraction corridors and port-linked industrial zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's dedicated freight corridor terminals anchor South Asia's fastest-expanding logistics infrastructure buildout. Megacity transit authorities across four continents are accelerating intelligent traffic system procurement as carbon accounting reshapes material sourcing decisions.
United States
The Federal Highway Administration's bridge replacement backlog drives demand for modular precast systems. The U.S. Department of Transportation mandates Buy America steel content thresholds for federal-aid highway projects. Texas and California corridor expansions concentrate contractor bidding for performance-based maintenance contracts.
Germany
Autobahn renewal programs prioritize overnight lane closure sequences requiring rapid-installation bridge decks. The EU Green Deal's embodied carbon procurement scoring redirects concrete sourcing toward slag-integrated suppliers. The Rhine-Ruhr industrial corridor hosts electric-arc-furnace steel mills certifying recycled content for transit authority tenders.
India
The National Infrastructure Pipeline prioritizes multimodal logistics hubs along the Eastern and Western Dedicated Freight Corridors. The Ministry of Road Transport and Highways embeds lane addition targets in freight-intensive states. Gujarat and Maharashtra industrial zones concentrate cement and steel demand for heavy-haul rail infrastructure.
China
Provincial transport departments expand intelligent traffic management deployment across Yangtze River Delta megacities. The Ministry of Ecology and Environment tightens embodied carbon disclosure for public works procurement. The Pearl River Delta logistics cluster pilots blockchain-enabled material provenance tracking for infrastructure finance.
Brazil
State highway agencies pilot availability-payment maintenance models transferring pavement performance risk to contractors. ANVISA registration timelines for construction chemicals extend substitution planning for waterproofing systems. São Paulo's metropolitan transit authority procures sensor-integrated signal systems for congestion reduction.
Global Transportation Infrastructure Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service reliability and transit-time performance. The less-than-truckload segment exhibits tiered consolidation with density-network specialists commanding pricing power over asset-light brokers. Two archetypes dominate: integrated intermodal operators with captive container fleets, and technology-heavy brokerage platforms competing on digital matching velocity. Strategic moves concentrate on terminal network densification and proprietary data platform development.
Within the integrated intermodal tier, J.B. Hunt Transport Services and Knight-Swift Transportation occupy positions anchored by rail partnerships and container fleet control. Old Dominion Freight Line exemplifies the density-network premium model through terminal infrastructure concentration. XPO Logistics represents the technology-forward brokerage archetype competing on platform matching speed rather than physical asset ownership alone.
| Leading Market Players |
|---|
| Estes Express Lines |
| ABF Freight |
| FedEx Freight |
| J.B. Hunt Transport Services |
| R+L Carriers |
| Old Dominion Freight Line |
| Saia Inc |
| Knight-Swift Transportation |
| XPO Logistics |
| Others |
Supply Flow & Price Mechanics
Steel rebar futures on the London Metal Exchange cascade through transportation infrastructure supply chains into three-tier pricing structures across premium, standard, and economy levels. Bid premiums for EU Green Deal-certified low-carbon concrete compress margins for conventional suppliers while rewarding electric-arc-furnace steel mills with port-adjacent scrap access.
Pricing Analysis
Availability-payment contracts for pavement performance anchor value-based pricing in Brazilian and Indian state highway programs. Price differentiation hinges on Environmental Product Declaration certification tier and factory-controlled precast quality grade. Cost compression in standard-grade cast-in-place concrete is intensifying because of supplementary cementitious material supply constraints. Municipal procurement officers exhibit highest price sensitivity, while mining and port terminal operators in Australia's Pilbara region prioritize supply chain control over unit cost.
Supply Chain Analysis
CE marking and BIS certification gating restricts modular component sourcing to qualified factories in Germany, India, and China. Supply chains draw from electric-arc-furnace steel mills, slag-integrated cement plants, and polymer-modified asphalt refiners. Single-source vulnerability concentrates in quality recycled steel availability at industrialized port regions. Distribution runs through project-specific logistics corridors anchored to dedicated freight terminal networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transportation infrastructure procurement is transitioning from first-cost optimization to lifecycle carbon accounting, with blockchain-enabled material provenance tracking displacing legacy paper-based certification systems.
For Market Incumbents: Extend terminal network densification into corridor-adjacent Indian states where the National Infrastructure Pipeline concentrates steel and cement demand. Deepen backward integration into slag and fly ash supply to secure Environmental Product Declaration scores for EU Green Deal tenders. Defend against modular construction specialists by accelerating factory-cured precast capacity in Germany's Autobahn renewal zones.
For New Entrants and Emerging Players: Regional logistics operators in underpenetrated African corridor development present partnership pathways for multimodal terminal technology transfer. Target carbon capture concrete curing mineralization systems for EU public tenders requiring negative-emission structural elements. Deploy sensor-integrated signal systems through availability-based contracting models piloted in São Paulo's metropolitan transit authority.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precast and modular construction specialists with captive curing technology in India's Gujarat and Maharashtra industrial zones. Long-term viability centers on vertical integration into recycled steel sourcing and low-carbon cementitious material supply. Monitor EU Green Deal embodied carbon threshold tightening as the inflection signal for material supplier retooling requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Steel Supply | Electric-arc-furnace mill control secures EU Green Deal certification tiers for bridge and rail tenders. |
| Carbon Capture Concrete Curing Deployment | Mineralization technology during precast production unlocks negative-emission qualification in European procurement scoring. |
| Performance-Based Maintenance Contract Expansion | Brazilian availability-payment pilots transfer pavement deterioration risk from state agencies to contractor balance sheets. |
| Blockchain Material Provenance Platform Launch | Distributed ledger verification accelerates payment cycles and reduces bond collateral for certified German and French suppliers. |
| Intelligent Traffic Management System Integration | Sensor-fusion signal procurement by Yangtze River Delta megacities reduces intersection congestion and fuel waste metrics. |
Methodological Framework
Independent corroboration across procurement officers at Indian state highway departments, German Autobahn renewal program managers, and Brazilian availability-payment contract specialists underwrites the qualitative findings. Primary fieldwork with geotechnical engineers, precast factory operations directors, and electric-arc-furnace steel mill procurement leads combined with secondary validation from EU Green Deal implementation reports, National Infrastructure Pipeline project databases, and BIS certification registries. Bottom-up project pipeline aggregation and top-down macro infrastructure spend analysis triangulate volume estimates.
Comparable-period anchoring to historical dedicated freight corridor buildouts in India and Autobahn renewal cycles in Germany calibrated the projection horizon. Segmentation dimensions modeled include infrastructure type, construction method, material carbon intensity tier, and end-user ownership structure across the analysis window. CAGRs derived from weighted average of public capital expenditure trajectories and private resource-extraction corridor investment patterns incorporate embodied carbon procurement threshold adoption curves and modular construction penetration rates.
Caveats apply where EU Green Deal recycled content mandate acceleration, Indian National Infrastructure Pipeline reallocation, or geotechnical engineer supply constraints could materially shift the outlook. A model refresh is warranted upon material change in low-carbon concrete early-strength performance breakthroughs or CE marking harmonization timelines for cross-border modular components.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market