
 High Pressure Washer Market | 2026-2036
High Pressure Washer Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Washer Market Analysis
Aftermarket service revenue is rewriting profitability structures across the competitive landscape. Alfred Kärcher SE & Co. KG leverages its dealer network density to capture recurring maintenance contracts. Nilfisk Group anchors its position through specialized industrial-grade configurations. Generac Power Systems competes on gasoline-powered portability for contractor mobility needs.
A high pressure washer is a mechanical spraying device that uses an electric motor, gasoline engine, or diesel engine to drive a pump, generating water pressure typically ranging from 1,000 to 4,000 PSI for surface cleaning and material removal. The equipment serves primary industrial and commercial purposes including degreasing, paint stripping, and sanitation of hard surfaces. Electric units dominate residential adoption due to lower noise profiles and reduced maintenance, while diesel configurations lead industrial settings where sustained high-pressure output matters. Belt drive technology sustains longer duty cycles in commercial applications, and surface cleaning commands the largest application share across municipal and manufacturing end users.
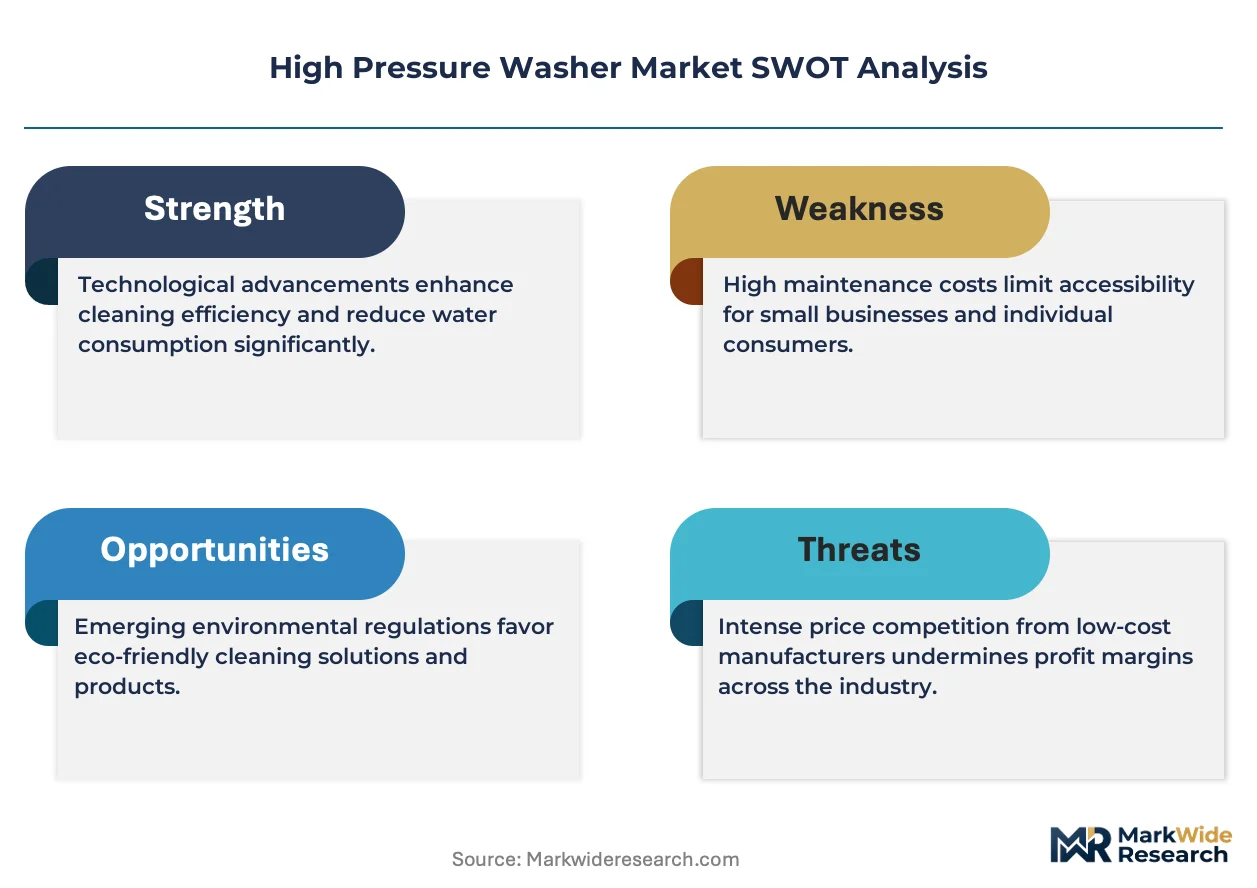
EPA WaterSense standards and European Ecodesign requirements are tightening minimum efficiency thresholds for pump systems and nozzle designs. OSHA workplace safety regulations mandate pressure-rated hoses and trigger-lock mechanisms for commercial operator protection. Stakeholders must monitor evolving carbon-emission classifications for gasoline engines and assess electric platform readiness against tightening municipal noise ordinances.
Market Dynamics
Water-efficiency mandates from EPA and European Ecodesign regulations are compressing pump system tolerances while expanding the addressable market for premium nozzle configurations. Equipment manufacturers now engineer for dual compliance across multiple jurisdictions.
Growth Catalysts
- EPA WaterSense standards:Minimum efficiency thresholds for pump systems are accelerating replacement cycles in municipal fleet operations across the United States. Contractors upgrade to certified units to maintain eligibility for public sector contracts.
- Industrial degreasing applications:Food processing facilities in China are expanding high-pressure sanitation protocols to meet export certification requirements. Belt drive configurations see elevated specification rates in these settings.
- Vehicle fleet expansion:Commercial transport operators in India are scaling wash bay infrastructure to manage larger active fleets. Diesel-powered units dominate this segment due to continuous-duty requirements.
Market Restraints
- Copper and aluminum price volatility:Pump housing and motor winding materials face commodity market swings that compress margin predictability for manufacturers.
- Gasoline engine carbon classifications:Tightening municipal emissions ordinances in California and Germany are restricting commercial deployment of portable combustion units in urban centers.
- Electric platform range limitations:Battery-powered configurations currently fail to match sustained PSI output of diesel alternatives in heavy industrial surface preparation.
Strategic Opportunities
- Brazilian agribusiness washdown:Soybean processing and livestock operations present underpenetrated demand for corrosion-resistant industrial configurations.
- Subscription maintenance models:Dealer networks are bundling scheduled service with equipment leases, capturing recurring revenue from commercial cleaning contractors.
- IoT pressure monitoring convergence:Sensor-enabled pumps that transmit duty cycle data to fleet management platforms are opening specification channels with large facility operators.
Industry Challenges
- Certified technician scarcity:Commercial operators struggle to hire personnel trained on belt drive maintenance and high-pressure hose safety protocols mandated by OSHA.
- Cross-border compliance documentation:Manufacturers face divergent testing requirements between EPA WaterSense validation and European Ecodesign conformity assessment procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Washer Market |
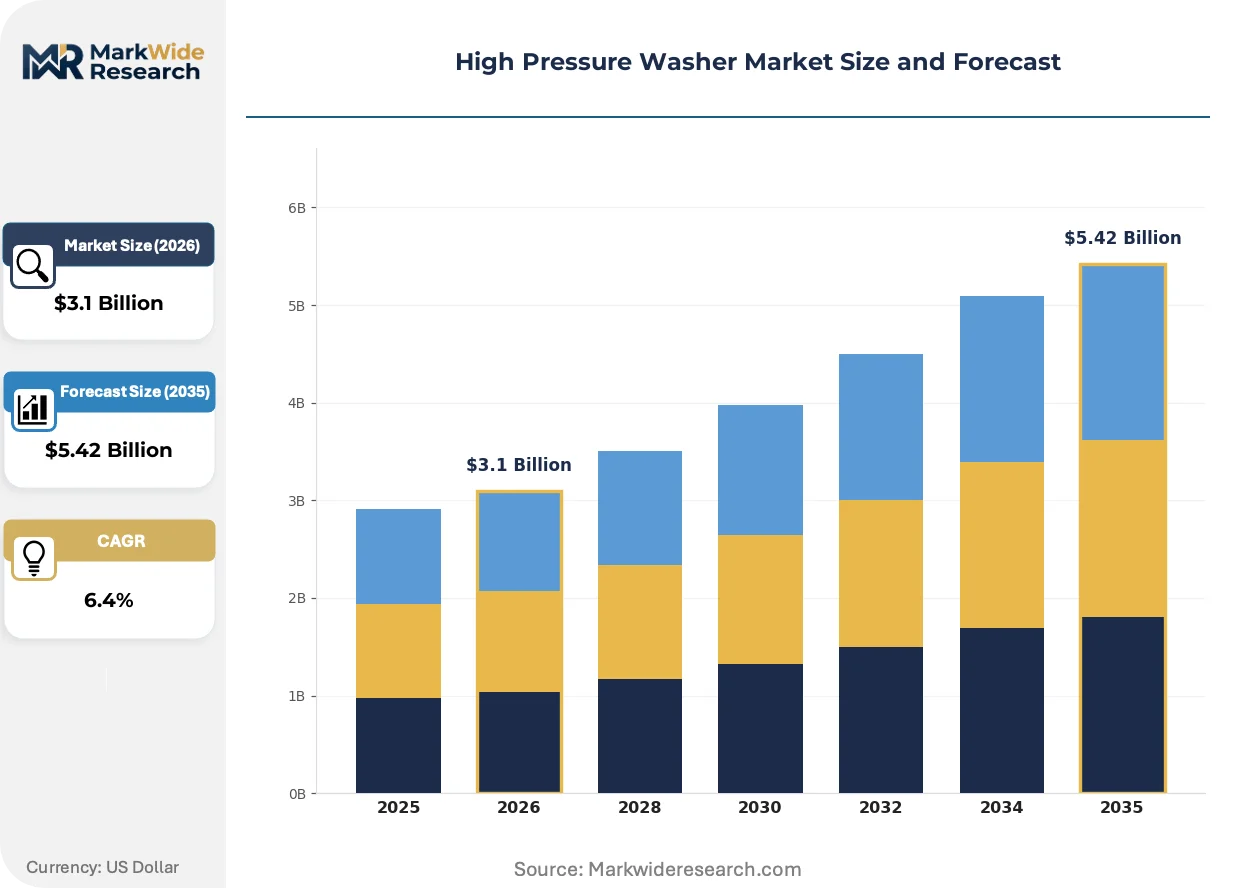
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gasoline, Diesel, Hot Water End User: Residential, Commercial, Industrial, Automotive Technology: Direct Drive, Belt Drive, Variable Pressure, Cold Water Application: Surface Cleaning, Vehicle Washing, Restoration, Graffiti Removal |
| Companies Covered | Alfred Kärcher SE & Co. KG, Nilfisk Group, Generac Power Systems, Stanley Black & Decker, Techtronic Industries, Briggs & Stratton, FNA Group, Annovi Reverberi S.p.A., Robert Bosch Power Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Washer Market Emerging Trajectories
Equipment architecture is fragmenting along power source lines as regulatory pressure and mobility requirements diverge. Manufacturers are optimizing for distinct duty cycles rather than universal platforms.
Brushless DC motor technology is hybridizing with traditional induction architectures in mid-duty electric units. Commercial cleaning contractors in Germany and Japan are specifying these configurations for noise-sensitive nighttime operations. The technology is hybridizing price-performance tiers, compressing the premium gap between residential and light-commercial segments.
European Ecodesign requirements for pump efficiency are mandating variable-frequency drive integration in units above 2.5 kW. Industrial laundries and food processing facilities face capital expenditure thresholds to maintain operating permits. Italian and Spanish manufacturers are responding with modular retrofit kits for installed base upgrades.
Facility managers are unbundling after-sales service from initial equipment procurement. Large municipal fleets in Australia and Canada now contract maintenance separately through multi-year agreements with authorized service networks. This pattern concentrates purchasing authority with procurement departments rather than operations managers.
High Pressure Washer Market Segmentation
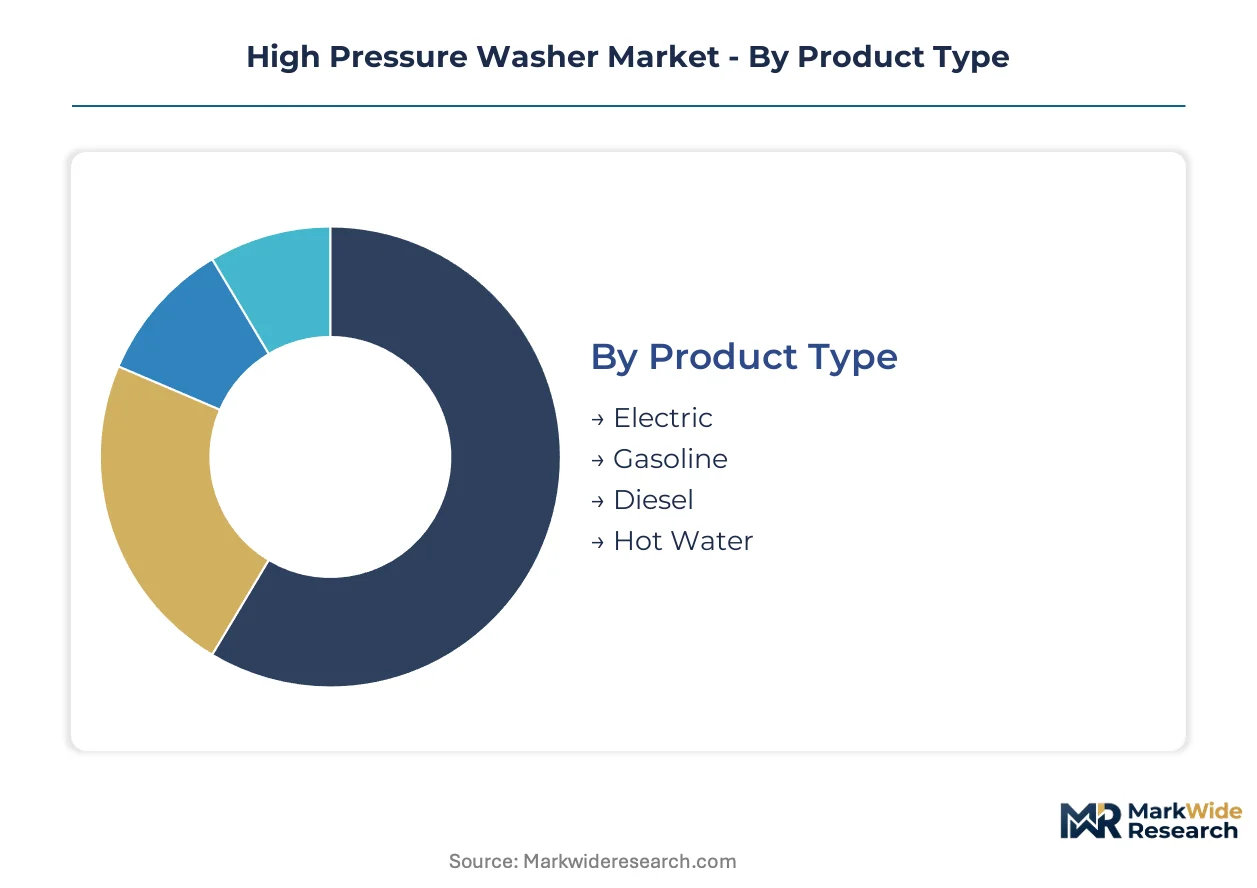
Segmentation in high pressure washers reflects divergent duty cycles and regulatory pressures across power sources and end-use environments. Equipment specifications fragment sharply between residential noise constraints and industrial continuous-output requirements.
Product Type:
Power source selection directly determines mobility range, noise compliance, and sustained PSI output capability across deployment contexts.
- Electric:Brushless DC and induction motor configurations dominate residential adoption where municipal noise ordinances restrict gasoline operation. German and Japanese commercial contractors specify these units for nighttime cleaning contracts in noise-sensitive districts.
- Gasoline:Portability drives specification among mobile cleaning contractors requiring field deployment without grid access. CARB-compliant engine architectures face tightening restrictions in California urban centers while maintaining dominance in rural North American markets.
- Diesel:Continuous-duty output for heavy industrial surface preparation and fleet wash bay infrastructure.
- Hot Water:Heated output configurations for grease-cutting applications in food processing and automotive degreasing operations.
Electric units command the established residential base. The steepest expansion runs through diesel configurations serving Chinese industrial infrastructure maintenance.
End User:
Customer type segmentation tracks capital intensity, maintenance outsourcing preferences, and specification authority concentration.
- Commercial:Cleaning contractors represent the fastest-expanding buyer segment as facility hygiene standards tighten and public sector contracts mandate EPA WaterSense certification. Australian and Canadian municipal fleets now unbundle procurement from maintenance through multi-year service agreements.
- Industrial:Food processing facilities in China deploy belt drive configurations for export certification compliance. OSHA-mandated trigger-lock mechanisms and pressure-rated hoses drive safety-specified purchasing.
- Residential:Lower-duty electric units for homeowner surface cleaning and vehicle maintenance applications.
- Automotive:Fleet wash bay infrastructure scaling with commercial transport operator expansion in India.
Industrial buyers anchor replacement cycle volume. Commercial contractors are gaining share fastest through subscription maintenance model adoption.
Technology:
Drive architecture and pressure modulation systems differentiate duty cycle endurance and operator safety compliance.
- Belt Drive:Extended duty cycle capability sustains longer operational periods in commercial degreasing applications. Food processing facilities specify these configurations to meet sanitation protocol requirements.
- Direct Drive:Compact motor-pump coupling for residential and light-commercial portability requirements.
- Variable Pressure:European Ecodesign mandates above 2.5 kW are accelerating variable-frequency drive integration for pump efficiency compliance.
- Cold Water:Standard ambient-temperature output for general surface cleaning without heated component requirements.
Belt drive systems command the installed industrial base. Variable pressure technology is climbing fastest under regulatory efficiency mandates.
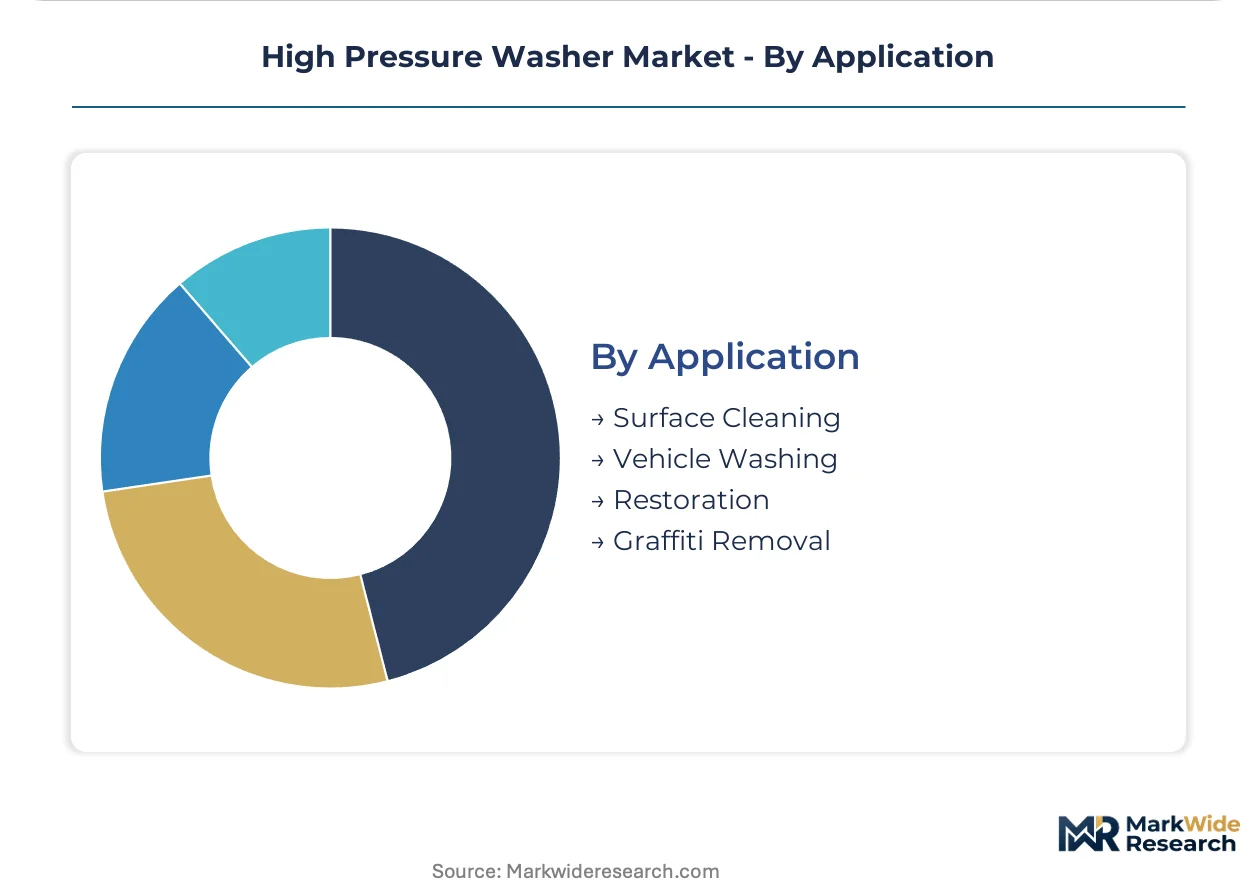
Application:
Use case segmentation determines nozzle configuration, PSI range specification, and chemical injection system requirements.
- Surface Cleaning:Municipal hardscape maintenance and manufacturing facility sanitation represent the largest application volume across end users. Brazilian agribusiness operations present underpenetrated demand for corrosion-resistant industrial configurations.
- Vehicle Washing:Fleet expansion in Indian commercial transport drives wash bay infrastructure investment with continuous-duty diesel specifications.
- Restoration:Controlled pressure output for building facade and historical structure material removal.
- Graffiti Removal:High-PSI specialized nozzle configurations for urban municipal maintenance contracts.
Surface cleaning commands the established revenue base. Vehicle washing applications are expanding most quickly with fleet infrastructure scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies. Municipal buyers in Germany and Japan absorb premium electric configurations for noise compliance, while Indian fleet operators prioritize diesel unit durability over capital cost.
United States
Commercial cleaning contractors drive specification volume as EPA WaterSense certification becomes mandatory for public sector contract eligibility. OSHA workplace safety regulations mandate trigger-lock mechanisms and pressure-rated hoses for commercial operators. California's CARB-compliant engine restrictions are compressing gasoline unit deployment in urban centers while Texas and Florida maintain open markets for portable combustion configurations.
China
Industrial infrastructure maintenance and vehicle fleet expansion anchor replacement cycle demand. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate electric platform adoption in municipal applications. Yangtze River Delta manufacturing clusters concentrate belt drive production for food processing export certification compliance.
Germany
European Ecodesign regulations mandate variable-frequency drive integration above 2.5 kW, forcing capital expenditure in industrial laundries and food processing facilities. Commercial contractors specify brushless DC configurations for nighttime cleaning contracts in noise-sensitive Munich and Hamburg districts. Bavarian pump manufacturers are engineering modular retrofit kits for installed base efficiency upgrades.
India
Commercial transport fleet expansion drives wash bay infrastructure scaling across Maharashtra and Gujarat. Diesel-powered units dominate due to continuous-duty requirements and grid reliability constraints in industrial zones. Central Electricity Authority regulations on industrial power quality are slowing electric platform adoption despite municipal noise ordinance tightening in Delhi-NCR.
Brazil
Soybean processing and livestock operations present underpenetrated demand for corrosion-resistant industrial configurations. ANVISA sanitation protocols are elevating specification standards in food processing facilities across São Paulo state. Agribusiness washdown applications in Mato Grosso and Paraná concentrate demand for heavy-duty belt drive systems.
High Pressure Washer Market Vendor Landscape
Capability concentration sits with specialized industrial-grade fabricators; scale advantage sits with diversified power-tool conglomerates. The vendor base organizes around three functional tiers: premium European engineering houses, mid-market Asian volume producers, and North American gasoline-engine specialists. Two dominant competitive moves define current positioning: dealer network density expansion for aftermarket service capture, and variable-frequency drive integration for European regulatory compliance.
Within the premium engineering tier, Alfred Kärcher SE & Co. KG and Nilfisk Group exemplify divergent strategic anchors. Kärcher leverages German fabrication heritage and dealer network density to capture recurring maintenance contracts. Nilfisk occupies a specialized industrial-grade position emphasizing belt drive configurations for food processing compliance. Generac Power Systems represents the North American gasoline-engine archetype, competing on portability for contractor mobility needs in grid-constrained environments.
| Leading Market Players |
|---|
| Alfred Kärcher SE & Co. KG |
| Nilfisk Group |
| Generac Power Systems |
| Stanley Black & Decker |
| Techtronic Industries |
| Briggs & Stratton |
| FNA Group |
| Annovi Reverberi S.p.A. |
| Robert Bosch Power Tools |
| Others |
Supply Flow & Price Mechanics
Commodity volatility in copper and aluminum pump housing materials compresses margin predictability while simultaneously widening pricing tier spreads between premium belt drive configurations and economy direct drive alternatives. This input cost instability forces manufacturers to engineer supply chain redundancy across multiple metallurgical sourcing regions, reshaping procurement geography away from single-country dependency.
Pricing Analysis
Aftermarket service revenue tiers—scheduled maintenance contracts, spare parts provisioning, and extended warranty bundles—now drive lifetime value capture exceeding initial equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates EPA WaterSense-certified configurations from baseline residential units, with price differentiation anchored in certification grade and dealer network density. Pricing pressure stems from Brazilian agribusiness buyers prioritizing corrosion-resistant specifications over brand premium, while municipal fleet operators in Germany and Japan absorb elevated electric platform costs for noise compliance.
Supply Chain Analysis
Supplier-financing facilities extended by Italian and Spanish pump manufacturers enable modular retrofit kit deployment without upfront capital burden on industrial laundries. Manufacturing concentration centers on China for electric motor assemblies, Germany for precision pump components, and India for diesel engine integration. Raw material dependencies draw from copper winding supplies, aluminum die-cast housings, and specialized polymer compounds for high-pressure hose reinforcement. Tariff exposure on Chinese electric motors threatens margin stability for North American assemblers. Distribution runs through authorized dealer networks capturing recurring service contracts alongside equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high pressure washer market sits at a platform-economics inflection where IoT pressure monitoring convergence transforms equipment vendors into data-service providers. Interoperability between sensor-enabled pumps and fleet management platforms is rewiring procurement authority toward operations technology departments.
For Market Incumbents: Pre-empt battery-powered platform displacement by securing variable-frequency drive integration patents before European Ecodesign mandates harden compliance thresholds. Consolidate dealer network density in Australian and Canadian municipal markets where maintenance unbundling concentrates recurring revenue capture. Anchor defensive positioning through backward integration into pump housing foundries to insulate against copper and aluminum price volatility.
For New Entrants and Emerging Players: Build out corrosion-resistant industrial configurations targeting Brazilian soybean processing and livestock operations in Mato Grosso and Paraná, where ANVISA sanitation protocols are elevating specification standards without entrenched incumbent relationships. Penetrate through subscription maintenance models bundling scheduled service with equipment leases, capturing commercial cleaning contractors in noise-sensitive German and Japanese districts seeking brushless DC configurations.
For Investors and Strategic Acquirers: European Ecodesign mandates above 2.5 kW reshape the acquisition landscape toward targets with variable-frequency drive engineering capabilities and modular retrofit kit portfolios. Long-term viability favors specialists with certified technician training infrastructure and IoT platform integration rather than pure manufacturing scale. Monitor EPA WaterSense certification adoption rates among municipal fleet operators as the signal indicating replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Pressure Monitoring Integration | Sensor-enabled pumps transmitting duty cycle data open specification channels with large facility operators. |
| Variable-Frequency Drive Patent Development | European Ecodesign compliance above 2.5 kW mandates pump efficiency technology for operating permit retention. |
| Dealer Network Density Expansion | Authorized service networks capture recurring maintenance contracts as Australian and Canadian fleets unbundle procurement. |
| Corrosion-Resistant Configuration Engineering | ANVISA sanitation protocols in Brazilian food processing elevate specification standards for agribusiness washdown. |
| Certified Technician Training Infrastructure | OSHA-mandated belt drive maintenance and hose safety protocols create scarcity premium for qualified service capacity. |
Methodological Framework
Initial hypotheses were tested against primary input from maintenance directors at food processing facilities, aftermarket service heads at commercial cleaning contractors, OEM procurement teams at pump manufacturers, and plant engineers at municipal fleet operations, then refined through secondary validation. Bottom-up triangulation combined trade data from customs records, SEC filings from diversified power-tool conglomerates, and Ecodesign conformity assessment documentation with top-down demand modeling. Primary fieldwork captured specification authority shifts as facility managers unbundle after-sales service from initial equipment procurement.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling power source, end user, drive architecture, and application dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from replacement cycle velocity in Chinese industrial infrastructure, fleet expansion trajectories in Indian commercial transport, and efficiency mandate compliance thresholds in European manufacturing. Forecast inputs incorporated belt drive specification rates for food processing export certification and diesel platform durability requirements in grid-constrained environments.
Stress conditions across copper and aluminum commodity bands, EPA WaterSense certification adoption velocity, and Brazilian agribusiness penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline enforcement and substitution elasticity between electric and diesel platforms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
CNC Router Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Global Welding Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Rotomolding Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
India Crane Market
Construction Equipment
GCC Crane Market