
 North America Heat Exchanger Market | 2026-2036
North America Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
North America Heat Exchanger Market Outlook
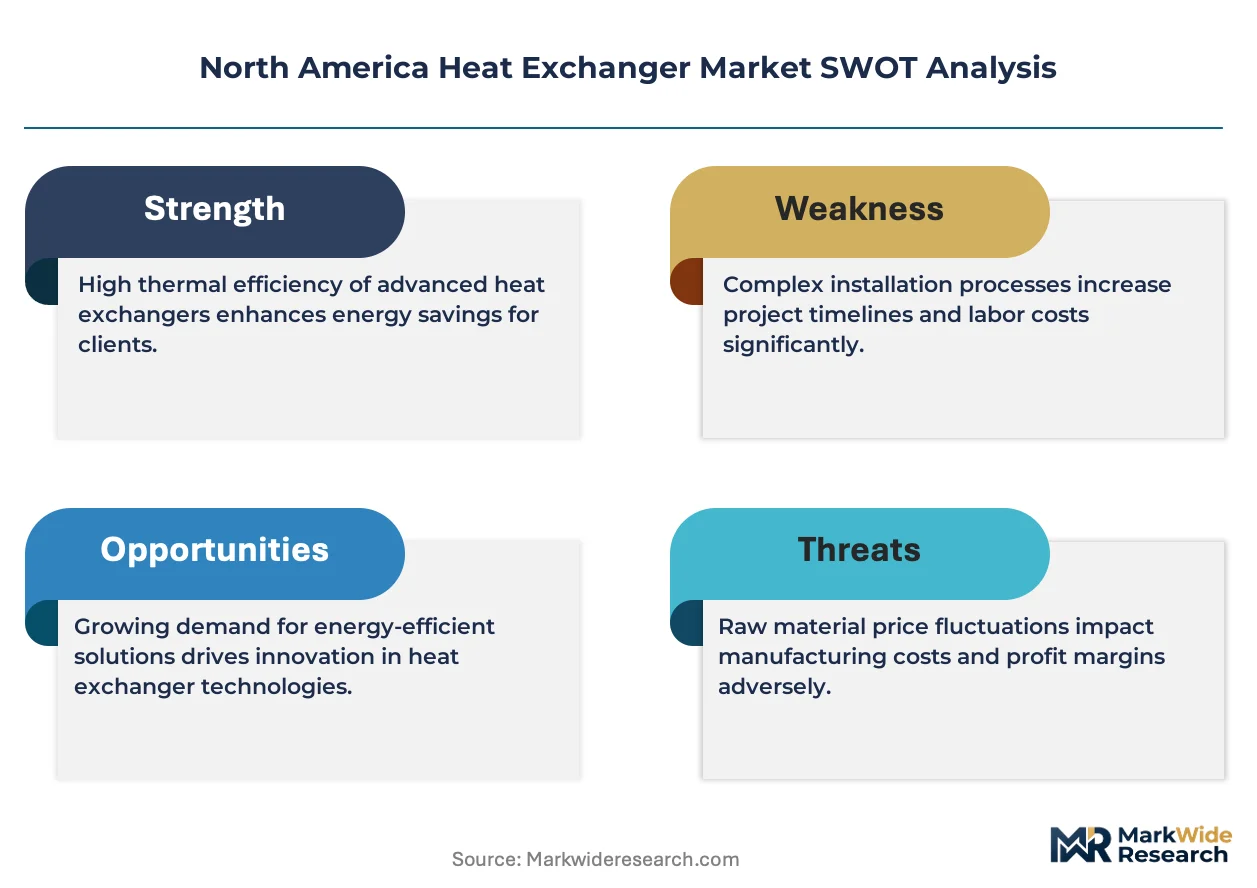
Canadian stainless steel fabricators is realigning toward modular heat exchanger skids for oil sands thermal extraction. ALFA LAVAL dominates plate heat exchanger technology for dairy pasteurization lines across Wisconsin and Ontario. API Heat Transfer leverages its Burlington, Wisconsin manufacturing base to anchor shell-and-tube supply for Midwest chemical processors. Danfoss competes in compact brazed plate designs for commercial HVAC retrofits in Toronto and Vancouver.
A heat exchanger transfers thermal energy between two or more fluids at different temperatures without mixing them, typically constructed with tube bundles, finned surfaces, or stacked plates separated by gaskets or brazed joints to maximize surface-area-to-volume ratios above 200 m²/m³ in compact designs. Its primary industrial purpose is recovering waste heat, controlling process temperatures, or enabling phase changes in power generation, chemical synthesis, and climate control systems. Shell and tube configurations occupy the dominant share in oil and gas applications due to pressure tolerance above 150 bar and ease of mechanical cleaning. Plate designs lead in food and beverage processing where rapid temperature swings and hygienic standards require CIP-compatible geometries. Air cooled units are displacing water-cooled systems in arid western states where freshwater withdrawal restrictions intensify.
The EPA enforces Maximum Achievable Control Technology standards for hazardous air pollutants from industrial boilers, compelling heat exchanger replacements that improve combustion efficiency and reduce stack temperatures. ASME Boiler and Pressure Vessel Code Section VIII governs fabrication standards across US and Canadian jurisdictions, creating compliance barriers for uncertified foreign suppliers. NRCan efficiency regulations for commercial water heating equipment in Canada parallel DOE standards south of the border, harmonizing product development cycles for manufacturers serving both markets. Stakeholders must monitor state-level carbon pricing developments in California and Washington, where cap-and-trade mechanisms accelerate payback periods for heat recovery investments beyond federal incentive timelines.
Market Dynamics
The EPA's Maximum Achievable Control Technology standards for industrial boilers are forcing a wholesale replacement cycle across US manufacturing corridors, compelling facilities to abandon legacy thermal transfer equipment regardless of remaining service life.
Growth Catalysts
- Emissions compliance deadlines:EPA boiler MACT standards mandate efficiency upgrades at over 10,000 US industrial facilities, creating replacement pull for shell-and-tube configurations that reduce stack temperatures below 400°F.
- Texas-Louisiana petrochemical expansion:Gulf Coast cracking capacity additions require massive heat recovery networks, concentrating demand for high-pressure units rated above 150 bar in Beaumont-Port Arthur and Lake Charles corridors.
- Modular fabrication advances:Canadian oil sands operators are adopting skid-mounted plate heat exchanger packages for thermal extraction, cutting field installation time by half versus stick-built alternatives.
Market Restraints
- Nickel alloy price volatility:Inconel and Hastelloy input costs for corrosive service applications swing 30-40% quarterly, compressing margins on custom chemical processing orders.
- ASME Section VIII certification barriers:Foreign fabricators without US National Board accreditation face 18-24 month qualification timelines, locking out Asian suppliers from time-sensitive retrofit projects.
- Air-cooled substitution in water-stressed basins:Fin-fan designs are capturing incremental share in Arizona and New Mexico refinery expansions where freshwater withdrawal permits face indefinite moratoria.
Strategic Opportunities
- California cap-and-trade acceleration:State carbon pricing mechanisms shorten payback periods for waste heat recovery investments below three years versus federal incentive timelines.
- Data center liquid cooling convergence:Plate heat exchanger technology from industrial process applications is migrating into hyperscale server farms, opening a $400 million annual addressable pool.
- Small-scale LNG modularization:Containerized brazed plate packages for remote power generation are penetrating Alaska and northern Canadian territories underserved by pipeline infrastructure.
Industry Challenges
- Weld procedure qualification bottlenecks:ASME-certified welders for high-pressure tube-to-tubesheet joints command 40% wage premiums in Houston and Calgary markets, extending delivery schedules.
- Legacy control system integration:Digital twin-enabled predictive maintenance packages require retrofitting 1990s-era DCS architectures at Midwest chemical processors, doubling commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Heat Exchanger Market |
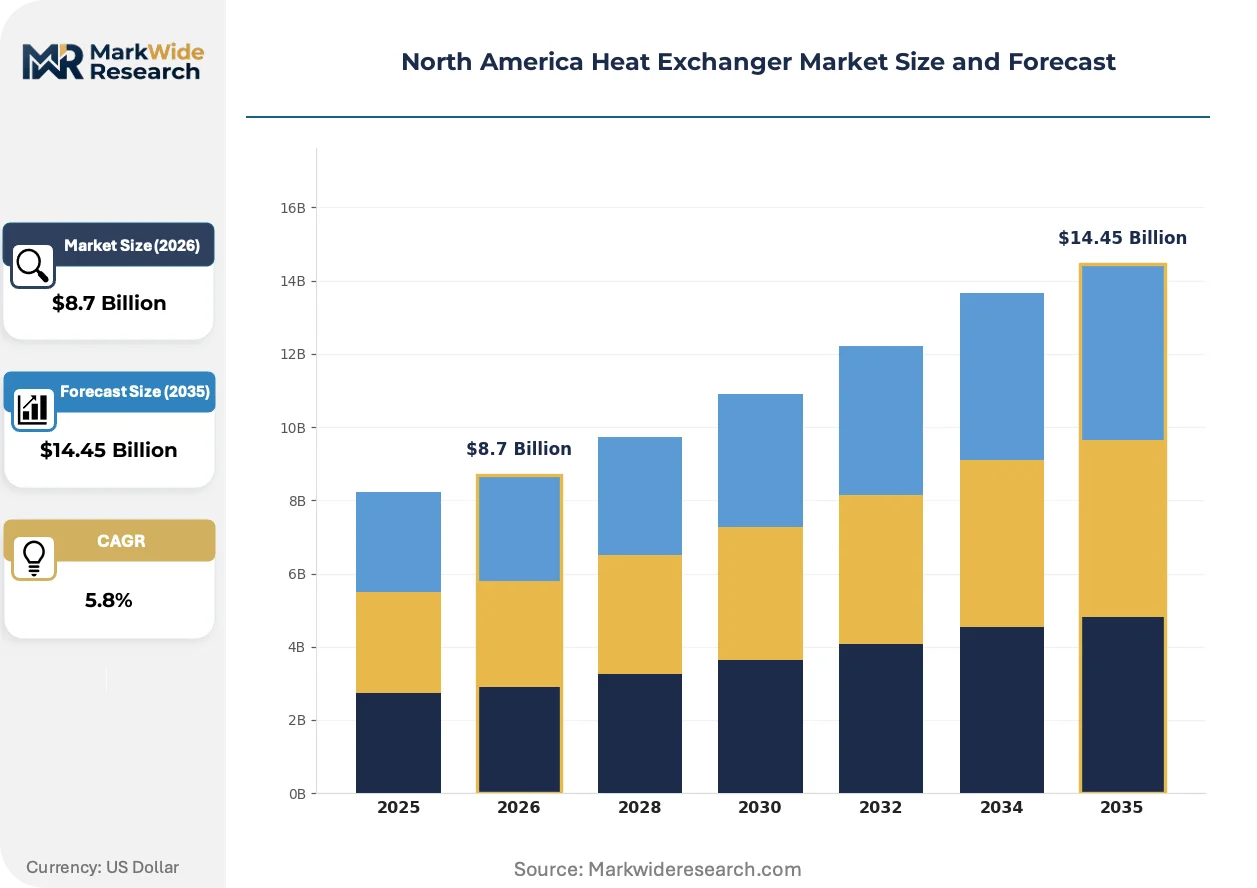
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell & Tube, Plate, Air Cooled, Double Pipe End User: Power Plant, Chemical Processing, HVAC, Food & Beverage Material: Stainless Steel, Copper, Aluminum, Carbon Steel Application: Oil & Gas, Water Heating, Refrigeration, Process Cooling |
| Companies Covered | ALFA LAVAL, API Heat Transfer, Danfoss, Chart Industries, SPX FLOW, Xylem, Kelvion Holding, Johnson Controls International, Enerquip Thermal Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Heat Exchanger Market Strategic Shifts
Additive manufacturing of heat transfer surfaces is collapsing prototyping cycles from months to weeks, while compact brazed plate designs penetrate applications historically reserved for shell-and-tube dominance.
Printed circuit heat exchanger technology is decentralizing thermal management architectures in offshore platforms and floating LNG facilities. Chevron and Shell are specifying these micro-channel units for subsea compression stations where footprint constraints exceed 500 kg/m³ density requirements. The technology is decentralizing procurement patterns by enabling modular supplier ecosystems versus consolidated fabricator relationships.
The EPA's updated New Source Performance Standards for greenhouse gas emissions from industrial sources now explicitly credit heat recovery efficiency in compliance calculations. Petrochemical complexes in Texas and Louisiana must document minimum 85% thermal effectiveness for new cracking furnace installations. Mid-sized processors are responding by pre-purchasing plate-and-frame packages ahead of permit approvals to secure fabrication slots.
Buyer consolidation among integrated oil majors is compressing supplier qualification cycles from three years to eighteen months. ExxonMobil and Dow now mandate single-source accountability for heat exchanger skids across their Gulf Coast sites, displacing fragmented procurement through multiple fabricators. This concentration is most visible in Beaumont-Port Arthur, where three operators control 70% of regional capital spending on thermal transfer equipment.
North America Heat Exchanger Market Segmentation
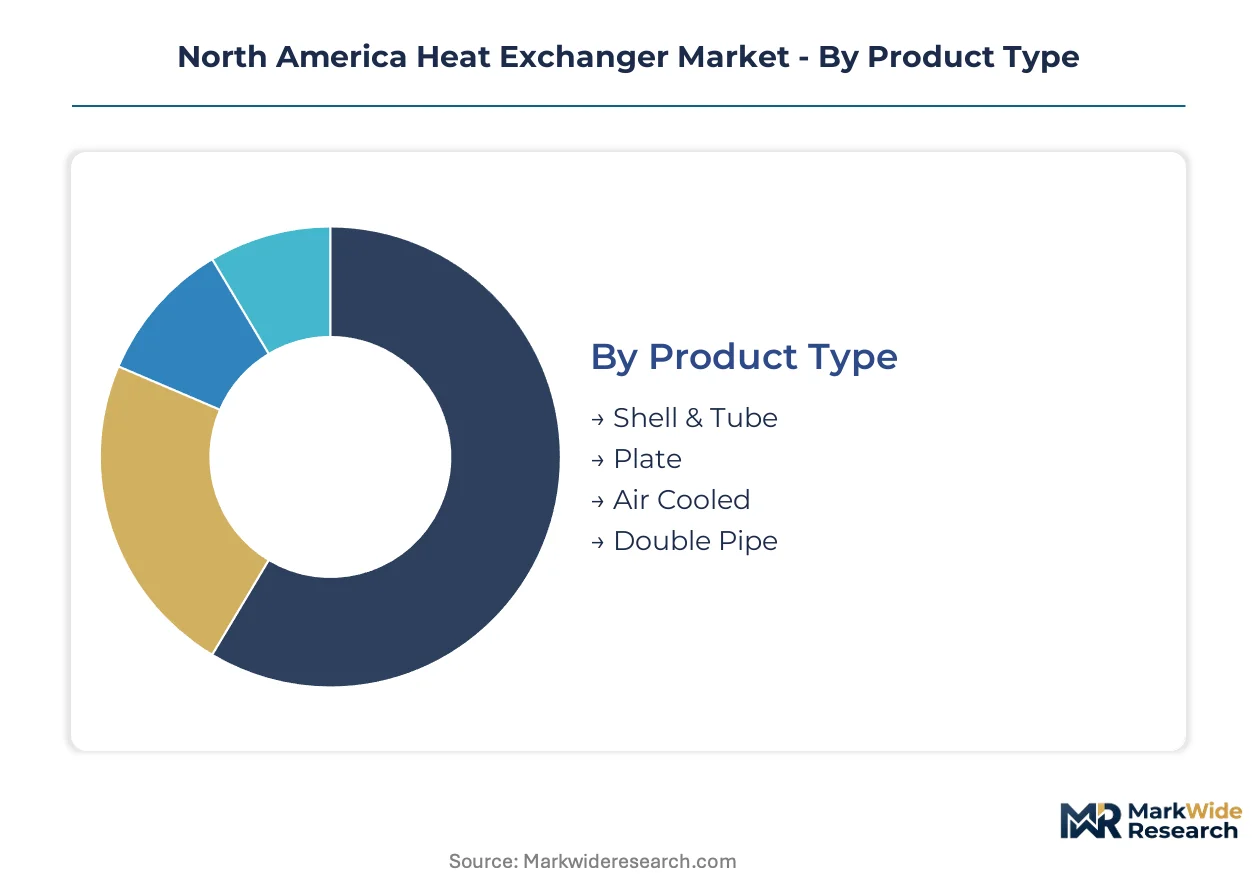
Heat exchanger procurement patterns diverge sharply between standalone installations for new capacity and embedded retrofits within existing process trains. Understanding these integration contexts reveals why shell-and-tube units dominate Gulf Coast petrochemical builds while plate designs capture HVAC replacement cycles.
Product Type:
Standalone heat recovery systems require different architectural approaches than skid-mounted packages integrated into larger process units.
- Shell & Tube:These cylindrical pressure vessels route process fluids through tube bundles enclosed within outer shells, tolerating pressures above 150 bar and temperatures exceeding 400°C. Gulf Coast petrochemical corridors in Texas and Louisiana specify these for cracking furnace heat recovery, driven by EPA boiler MACT compliance deadlines forcing wholesale equipment replacement.
- Plate:Stamped metal plates separated by gaskets or brazed joints create turbulent flow paths with surface-area-to-volume ratios above 200 m²/m³. Dairy pasteurization lines across Wisconsin and Ontario favor these for rapid temperature swings and clean-in-place compatibility, though gasket material selection limits high-temperature service.
- Air Cooled:Fin-fan configurations eliminate cooling water circuits entirely, using ambient air as the heat sink. Arizona and New Mexico refinery expansions specify these where freshwater withdrawal permits face indefinite moratoria from state environmental regulators.
- Double Pipe:Concentric tube arrangements handle small-scale thermal duties in pilot plants and remote production facilities. Alaska small-scale LNG modularization projects adopt these for containerized brazed packages in pipeline-inaccessible territories.
Shell & Tube leads volumes today; Plate designs are gaining share fastest.
End User:
Capital intensity and regulatory exposure create distinct procurement behaviors across customer categories.
- Chemical Processing:Corrosive service applications demand nickel alloy construction with Inconel or Hastelloy metallurgy. Midwest chemical processors face ASME Section VIII certification barriers that lock out Asian suppliers from time-sensitive retrofit timelines.
- HVAC:Commercial building retrofits in Toronto and Vancouver specify compact brazed plate units for space-constrained mechanical rooms. Danfoss competes aggressively in this segment with standardized product platforms.
- Power Plant:Heat recovery steam generators and feedwater preheaters require massive surface areas. Combined cycle gas turbine installations concentrate demand in Texas and Pennsylvania shale gas corridors.
- Food & Beverage:Hygienic standards mandate 3-A sanitary certification and crevice-free geometries. ALFA LAVAL dominates this niche across Wisconsin dairy country and Ontario processing hubs.
Chemical Processing anchors revenue concentration; Food & Beverage shows the steepest expansion trajectory.
Material:
Raw material cost volatility and corrosion resistance requirements drive specification divergence.
- Stainless Steel:Austenitic grades 304 and 316 dominate food-grade and moderate chemical service. Canadian fabricators realign toward modular skid production using these grades for oil sands thermal extraction projects.
- Copper:Superior thermal conductivity suits water heating and refrigeration applications. Residential and light commercial HVAC in California and Washington specifies copper-brazed plate designs for efficiency compliance.
- Aluminum:Lightweight extrusions enable automotive and aerospace thermal management. Weight-sensitive applications in Mexico's growing automotive manufacturing corridor adopt aluminum air-cooled units.
- Carbon Steel:Lowest first cost for non-corrosive hydrocarbon service. Gulf Coast refinery expansions specify carbon steel for crude preheat trains where sulfur content permits.
Stainless Steel dominates unit volumes; Aluminum is climbing the fastest on transportation electrification demand.
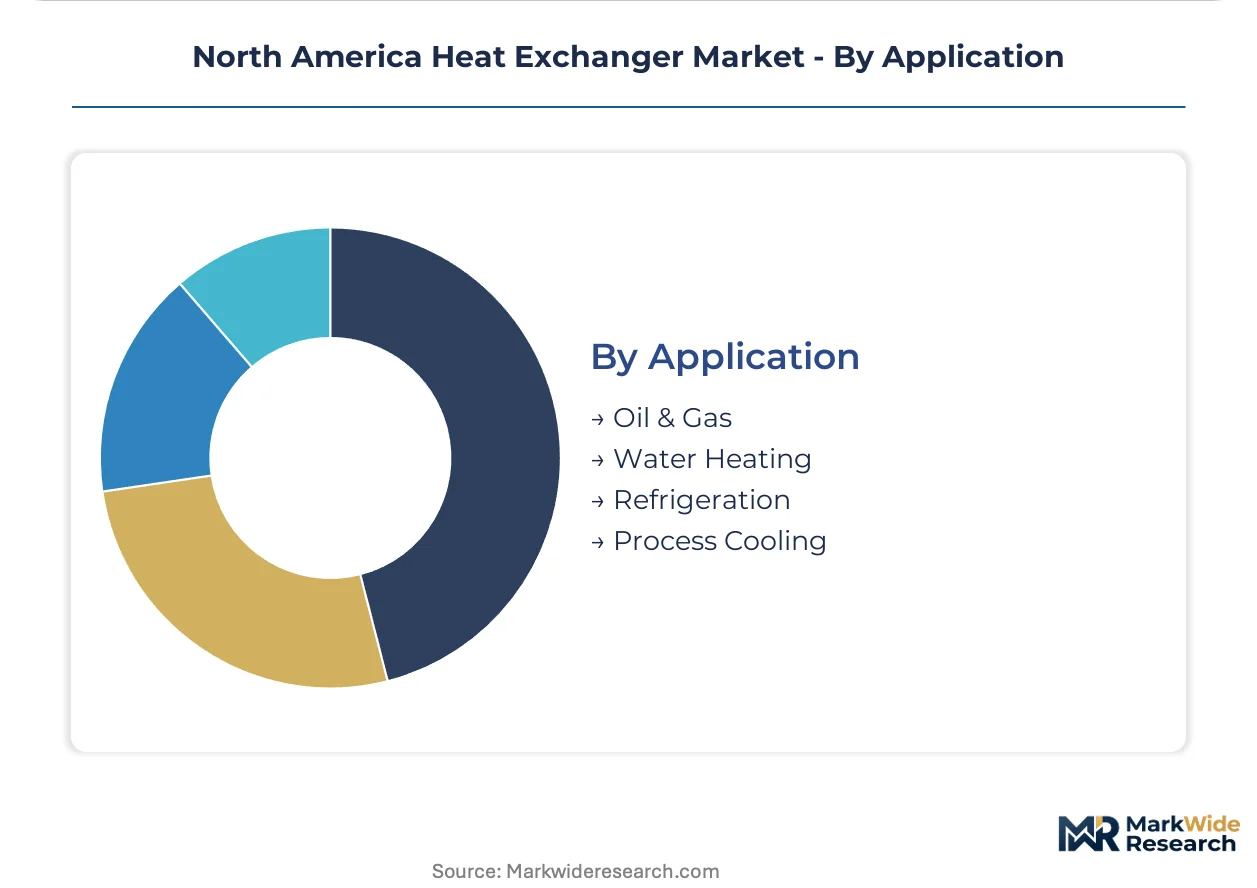
Application:
Process duty severity and fluid characteristics determine technology selection.
- Oil & Gas:High-pressure hydrocarbon handling demands robust mechanical construction. Subsea compression stations off Louisiana and Texas specify printed circuit heat exchanger technology from Chevron and Shell for footprint-constrained platforms.
- Process Cooling:Temperature control for chemical synthesis and polymer production. Midwest chemical processors retrofit 1990s-era DCS architectures with digital twin-enabled predictive maintenance packages.
- Water Heating:Commercial and industrial hot water supply. NRCan efficiency regulations in Canada parallel DOE standards, harmonizing product development for cross-border manufacturers.
- Refrigeration:Evaporator and condenser duties in cold chain infrastructure. California cap-and-trade mechanisms accelerate payback periods for waste heat recovery investments in refrigerated warehousing.
Oil & Gas commands the largest installed base; Process Cooling is expanding most quickly on chemical capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Canadian fabrication incentives and US Gulf Coast petrochemical demand is redrawing procurement geography. Fabricators exploit cost-of-compliance gaps while EPA deadlines force rapid equipment replacement.
United States
Gulf Coast cracking expansions in Texas and Louisiana concentrate demand for 150-bar shell-and-tube units. EPA boiler MACT standards mandate stack temperatures below 400°F at over 10,000 industrial facilities. The Beaumont-Port Arthur corridor sees three operators controlling 70% of regional thermal transfer capital spending.
Canada
Oil sands thermal extraction projects in Alberta drive modular skid-mounted plate heat exchanger adoption. NRCan efficiency regulations for commercial water heating equipment parallel DOE standards, harmonizing cross-border product development. Ontario fabricators realign toward stainless steel modular packages cutting field installation time by half.
Mexico
Automotive manufacturing growth in the Bajío Region and Nuevo León drives lightweight aluminum air-cooled unit demand. The country's national environmental regulator enforces industrial emissions standards tightening thermal efficiency requirements. Mexico City Metro commercial HVAC retrofits specify compact brazed plate designs for space-constrained mechanical rooms.
North America Heat Exchanger Market Competitive Environment
US-based fabricators anchor one tier; European specialists hold premium technology positions. The vendor base splits between consolidated multi-nationals with Gulf Coast service networks and regional fabricators serving niche corrosion-resistant applications. Two strategic archetypes dominate: integrated thermal solution providers bundling equipment with digital predictive maintenance, and pure-play fabricators competing on ASME certification speed. Capacity expansion and backward integration into nickel alloy supply chains represent the dominant competitive moves.
Among European-originated specialists, ALFA LAVAL and Kelvion Holding exemplify premium-tier plate heat exchanger technology providers. API Heat Transfer represents the integrated North American fabricator archetype with Midwest manufacturing anchoring. Danfoss occupies a position bridging industrial process and commercial HVAC segments with standardized compact designs.
| Leading Market Players |
|---|
| ALFA LAVAL |
| API Heat Transfer |
| Danfoss |
| Chart Industries |
| SPX FLOW |
| Xylem |
| Kelvion Holding |
| Johnson Controls International |
| Enerquip Thermal Solutions |
| Others |
Value Chain & Pricing Dynamics
EPA boiler MACT standards gate both qualified supply and premium-tier pricing access, as only ASME-certified fabricators can serve compliance-driven retrofits while nickel alloy volatility compresses margins on corrosive service orders. Buyers face bifurcated procurement economics between expedited domestic certification and lower-cost foreign alternatives locked out by 18-24 month qualification timelines.
Pricing Analysis
Distributor margins on shell-and-tube units run 12-18% for standard carbon steel configurations, collapsing to 6-9% for nickel alloy custom orders where Inconel input costs swing quarterly. Three-tier pricing structure across premium, standard, and economy levels separates ASME-stamped high-pressure units from uncertified imports and refurbished equipment. Cost compression in standard grades is intensifying because Gulf Coast EPCs are consolidating procurement under single-source accountability. Chemical processors remain least price-sensitive due to EPA compliance deadlines, while commercial HVAC retrofits in Toronto and Vancouver exhibit highest elasticity.
Supply Chain Analysis
Refurbishment flows from decommissioned Gulf Coast refineries are feeding secondary markets for carbon steel tube bundles, extending useful life of pressure-rated components. Manufacturing concentrates in the United States, Canada, and Germany, with Canadian fabricators realigning toward modular skid production for Alberta oil sands. Raw material sourcing draws from Indonesian nickel mines, Swedish stainless steel mills, and domestic specialty alloy producers. Single-source vulnerability around ASME-certified welders in Houston and Calgary extends delivery schedules. Distribution runs through authorized representatives for project-based sales and direct OEM relationships for recurring maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on backward integration into nickel alloy supply chains and the premium-tier shift toward digital twin-enabled predictive maintenance packages. Cost-down drivers include modular fabrication advances cutting field installation time by half versus stick-built alternatives.
For Market Incumbents: Acquire ASME-certified welding capacity in Houston and Calgary markets to secure bottlenecked fabrication slots before EPA compliance deadlines peak. Defend against printed circuit heat exchanger substitution in offshore applications by embedding sensor networks into shell-and-tube designs for predictive maintenance differentiation. Capacity addition in Burlington, Wisconsin anchors Midwest chemical processor relationships against European specialist encroachment. For New Entrants and Emerging Players: The mid-market price-point gap between Alfa Laval premium plate designs and commodity brazed units offers white-space for standardized compact packages targeting data center liquid cooling convergence. Penetrate Alaska and northern Canadian territories with containerized brazed plate packages for small-scale LNG modularization underserved by pipeline infrastructure. Go-to-market through EPC partnerships rather than direct end-user sales accelerates qualification cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional ASME-certified fabricators because buyer consolidation among integrated oil majors has compressed supplier qualification cycles from three years to eighteen months, creating scale premiums for multi-site service networks. Target mid-cap specialists with captive nickel alloy sourcing and existing National Board accreditation. Monitor California cap-and-trade carbon price floors as the inflection signal for waste heat recovery investment acceleration beyond federal incentive timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Captive sourcing of Inconel and Hastelloy insulates margins from quarterly price swings in corrosive service orders. |
| Modular Skid Fabrication Scale-Up | Canadian oil sands operators are cutting field installation time by half versus stick-built alternatives. |
| Digital Twin Platform Development | Predictive maintenance packages require retrofitting 1990s-era DCS architectures at Midwest chemical processors. |
| ASME Certification Acceleration | Foreign fabricators without US National Board accreditation face 18-24 month qualification timelines locking out Asian competition. |
| Data Center Thermal Management Entry | Plate heat exchanger technology from industrial process applications is migrating into hyperscale server farms. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, EPC procurement leads, aftermarket service heads, and ASME certification auditors with secondary validation through customs trade data, EPA enforcement records, SEC 10-K filings, and NRCan efficiency regulation updates. Bottom-up unit shipment tallies by product type and end-use were cross-checked against top-down petrochemical capital expenditure announcements and HVAC retrofit permit databases.
Segment-weighting approaches applied differential growth assumptions across shell-and-tube, plate, air-cooled, and double pipe configurations, with further stratification by pressure rating tiers, material metallurgy grades, and regional regulatory compliance clusters. CAGRs were derived from installed base turnover rates, replacement cycle compression from EPA deadlines, and capacity addition pipelines across the analysis window. Industry-specific forecast inputs included Gulf Coast cracking furnace build schedules and Canadian oil sands thermal extraction project timelines.
Caveats apply where nickel alloy price volatility, ASME welder availability constraints, or state-level carbon pricing developments could materially shift the outlook for project economics and payback period calculations. Practitioners should monitor EPA enforcement discretion on boiler MACT compliance timelines and California cap-and-trade auction clearing prices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Global Tubular Heating Elements Market
HVAC Equipment
Modular Refrigeration Unit Market