
 Asia Pacific Commercial HVAC Market | 2026-2036
Asia Pacific Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Commercial HVAC Market Insights
Project finance and green leasing structures is rewriting competitive access across the Asia Pacific Commercial HVAC landscape, allowing asset-light operators to bid for large commercial contracts previously reserved for balance-sheet-heavy incumbents. Daikin Industries leverages its captive compressor manufacturing to control cost curves across Southeast Asian projects. Mitsubishi Electric anchors premium positioning through VRF technology leadership in high-rise developments. Carrier Global competes on service-contract bundling that locks in multi-year maintenance revenue streams.
Asia Pacific commercial HVAC encompasses climate control systems engineered to regulate temperature, humidity, and air quality in non-residential buildings, typically operating at capacities from 5 tons to 500-plus tons with coefficient-of-performance ratings dictating energy draw. These systems serve the fundamental commercial purpose of protecting occupant productivity, equipment integrity, and regulatory compliance in enclosed working environments. Chillers dominate installed base value across the region's existing stock of large office towers, while heat pumps represent the fastest-growing product category as building operators retrofit for lower-carbon heating. Among end users, healthcare facilities command premium pricing tiers due to stringent infection-control air-change requirements that exceed standard commercial specifications.
China's MEE enforces escalating efficiency tiers under national GB standards, forcing equipment replacement cycles that favor inverter-driven systems. Japan's METI Top Runner program and India's BIS energy-labeling scheme create parallel compliance ladders that fragment product portfolios across borders. Australia's TGA-equivalent building codes and South Korea's MFDS-aligned procurement rules add further certification complexity for multinational suppliers. Stakeholders must monitor which regulatory jurisdiction tightens fastest, as that geography will set the design standard that propagates across regional supply chains.
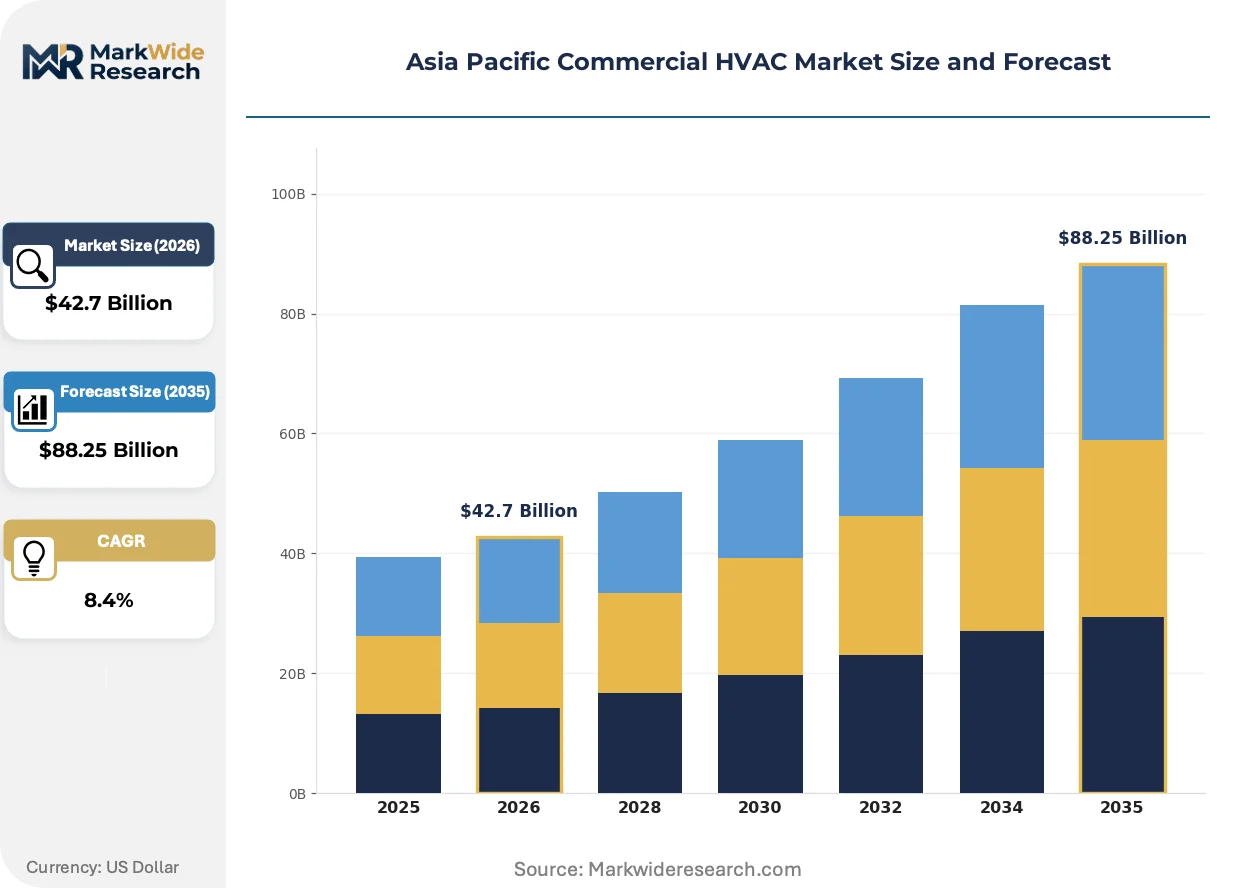
Market Dynamics
China's dual carbon goals and Japan's METI efficiency mandates are forcing equipment replacement cycles that favor inverter-driven compressor systems across the region's installed base of aging chillers.
Growth Catalysts
- Data center construction boom:Hyperscale cloud operators in India and Singapore are specifying precision cooling systems with redundant capacity configurations that exceed standard commercial specifications.
- India's BIS energy-labeling scheme:Mandatory efficiency tiers for commercial buildings in Mumbai, Delhi, and Bangalore are accelerating retrofit demand for variable refrigerant flow systems.
- Heat pump technology maturation:Building operators in South Korea and Australia are retrofitting gas-fired heating infrastructure with electric heat pumps to meet decarbonization commitments.
Market Restraints
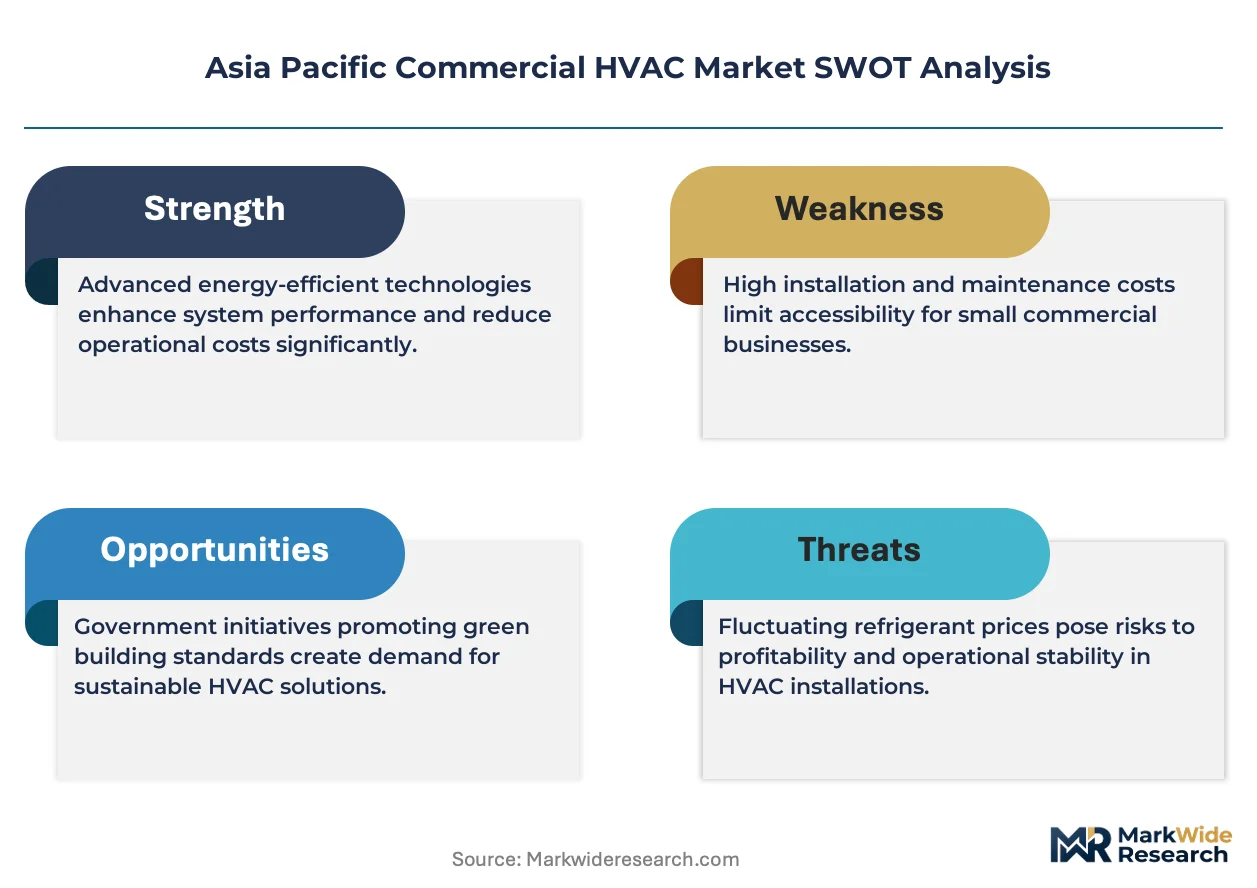
- Copper and aluminum price volatility:Compressor manufacturers face margin compression from raw material input cost swings that equipment contracts rarely index adequately.
- Refrigerant supply concentration:Production of low-global-warming-potential alternatives concentrates among Chinese chemical suppliers, creating single-source vulnerability for Japanese and Korean OEMs.
- Legacy chiller lock-in:Existing building infrastructure in Australia's commercial towers limits retrofit compatibility with next-generation heat pump architectures.
Strategic Opportunities
- Vietnam's industrial zone expansion:Manufacturing facility construction in Bac Ninh and Hai Phong is outpacing local HVAC installer capacity, creating first-mover advantage for regional service networks.
- Green leasing contract structures:Landlords in Singapore and Sydney are bundling efficiency-guaranteed climate systems into triple-net leases that transfer operational risk to equipment vendors.
- AI-driven predictive maintenance:Convergence of IoT sensors and machine learning algorithms is enabling outcome-based service contracts that replace scheduled maintenance with condition-based intervention.
Industry Challenges
- Refrigerant handling certification gaps:Technician shortages in Indonesia and Philippines are delaying installation timelines for systems requiring new fluorinated gas credentials.
- Multi-standard compliance burden:OEMs must maintain parallel product portfolios to satisfy China's GB standards, Japan's JIS specifications, and Australia's TGA-equivalent building codes simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Commercial HVAC Market |
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $88.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Air Filtration, Heat Pumps, Ductless Systems End User: Office Buildings, Retail Spaces, Healthcare Facilities, Hospitality Technology: Variable Refrigerant Flow, Geothermal, Exhaust Heat Recovery, Smart Thermostats Application: Cooling, Heating, Ventilation, Indoor Air Quality |
| Companies Covered | Mitsubishi Electric Corporation, Johnson Controls, Daikin Industries, Ltd., Gree Electric Appliances, Trane, Midea Group Co., Ltd., Samsung Electronics Co., Ltd., LG Electronics, Carrier Global Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Commercial HVAC Market Trends and Innovations
Digitalization of building management systems is compressing the traditional divide between equipment vendors and facility operators, creating integrated platforms that automate energy optimization.
Building automation software is digitizing climate control operations through real-time sensor networks that adjust airflow and temperature setpoints based on occupancy patterns. Large office developers in Shanghai and Tokyo are deploying these systems in new high-rise construction. The technology is digitizing vendor-customer relationships by embedding equipment suppliers into ongoing operational decisions rather than discrete sales transactions.
China's MEE is escalating efficiency enforcement under national GB standards that mandate inverter-driven compressor systems in all new commercial construction above specified capacity thresholds. Equipment importers face forced product redesign cycles to maintain market access. Japanese and Korean manufacturers with captive compressor production are adapting platforms fastest, while European suppliers lag in certification timelines.
Facility managers are unbundling long-term service contracts from initial equipment procurement, soliciting competitive maintenance bids separately from capital purchases. This pattern disrupts traditional OEM bundling strategies in Australia's commercial property sector. The shift is most visible in Sydney and Melbourne, where institutional landlords now separate HVAC capital expenditure from operational expenditure in board-level reporting.
Asia Pacific Commercial HVAC Market Segmentation
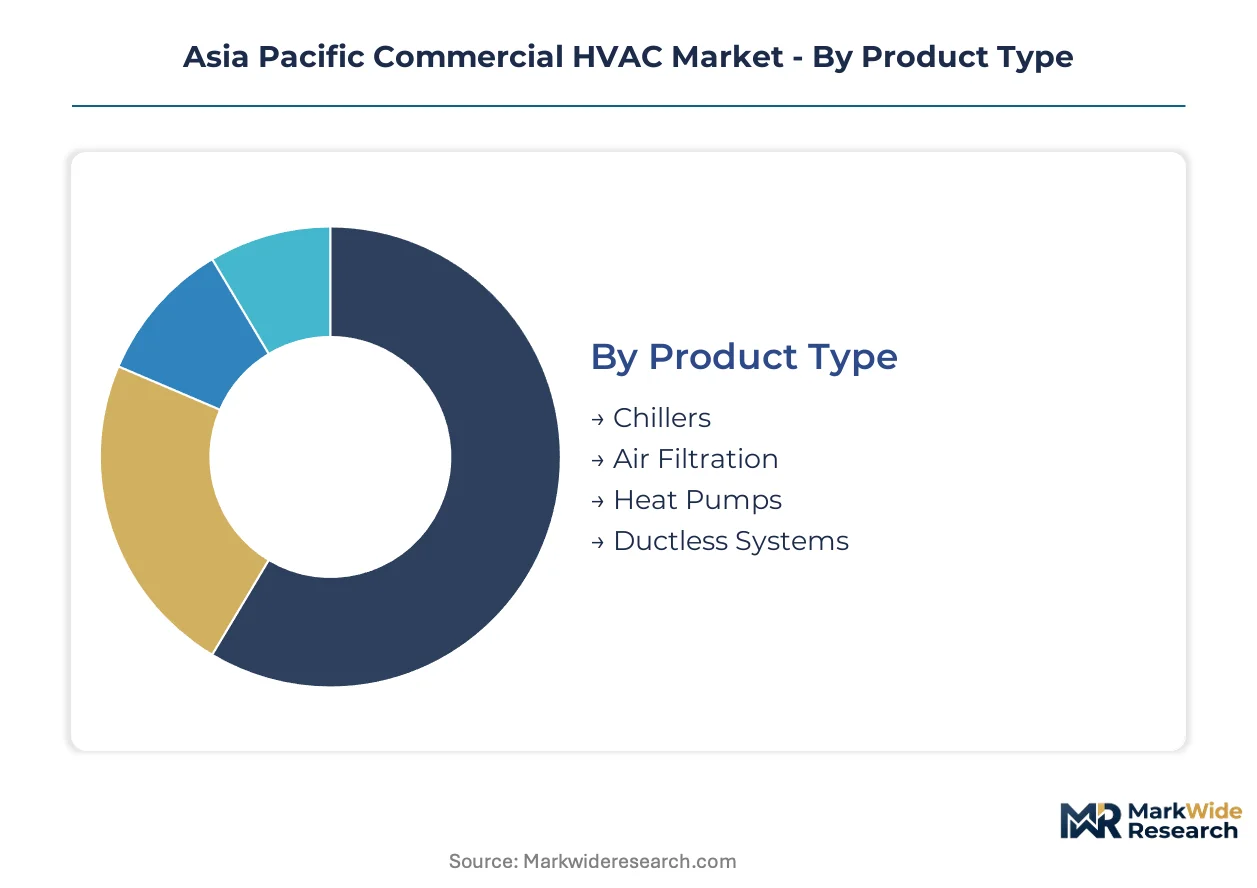
Commercial HVAC procurement in Asia Pacific fragments across equipment specifications, building typologies, and regulatory compliance tiers. Understanding these divisions reveals where capital expenditure concentrates and which technology platforms are displacing legacy infrastructure.
Product Type:
Mature cooling technologies anchor installed base value while emerging thermal solutions capture retrofit momentum across Southeast Asian and Australian markets.
- Chillers:Centrifugal and absorption chillers dominate capacity installations above 200 tons in Shanghai and Singapore office towers. China's MEE efficiency mandates are accelerating replacement of fixed-speed compressor units with magnetic-bearing variable-speed alternatives in legacy commercial stock.
- Heat Pumps:Air-source and water-source electric heat pumps are displacing gas-fired boilers in South Korean and Australian commercial retrofits. Building operators in Seoul and Sydney specify these systems to meet decarbonization commitments while maintaining heating capacity during shoulder seasons.
- Air Filtration:HEPA and activated carbon systems address particulate and VOC concerns in metro Manila and Jakarta commercial developments.
- Ductless Systems:Multi-split configurations serve small-format retail and satellite office fit-outs where central plant infrastructure is uneconomical.
Chillers handle the majority of throughput; heat pumps are expanding most quickly on share.
End User:
Cost tier stratification separates premium-specification environments from commodity climate control, with infection-control standards creating pricing premiums in medical infrastructure.
- Healthcare Facilities:Surgical suites and isolation wards require 15-25 air changes per hour with pressure cascade controls that exceed standard commercial specifications. Hospitals in Mumbai and Bangkok command premium pricing tiers for equipment meeting JIS and BIS infection-control standards.
- Office Buildings:High-rise commercial towers in Tokyo and Melbourne represent volume demand centers, with developer specifications increasingly bundling smart building automation into base mechanical contracts.
- Retail Spaces:Shopping mall operators in Ho Chi Minh City and Manila prioritize rapid-cooling recovery for high-occupancy weekend loads.
- Hospitality:Hotel chains in Bali and Phuket specify corrosion-resistant coastal-grade equipment for salt-air environments.
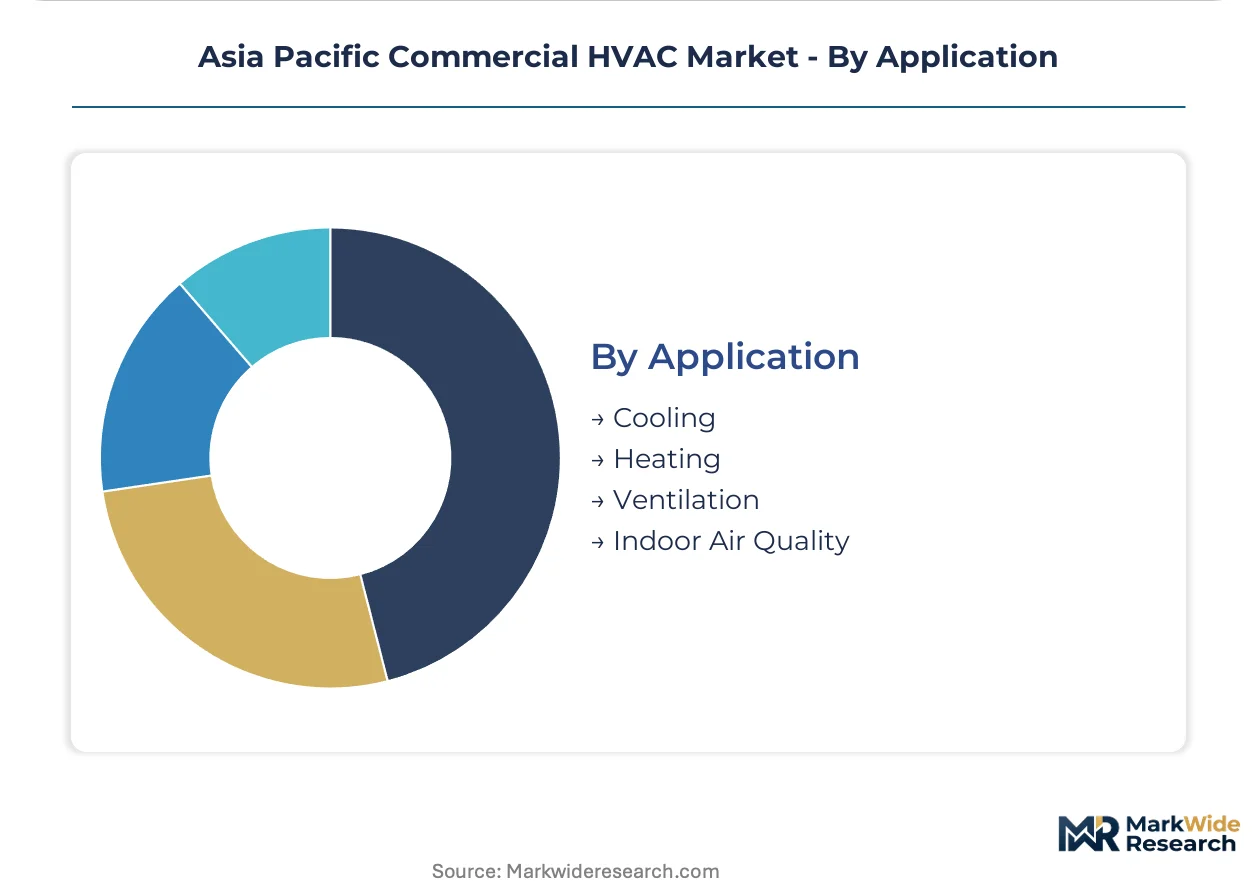
Office buildings generate the largest equipment volume; healthcare facilities sustain the steepest expansion trajectory.
Technology:
Application-specific thermal recovery and intelligent control systems are displacing conventional on-off compressor cycling in premium commercial installations.
- Variable Refrigerant Flow:VRF systems modulate refrigerant volume to match zone-level load variations, reducing energy draw in partially occupied buildings. Japanese OEMs dominate this segment through compressor manufacturing integration that controls cost curves across Southeast Asian projects.
- Smart Thermostats:IoT-enabled controls with occupancy sensing and predictive algorithms are standard in new Singapore and Sydney commercial construction. These systems digitize vendor-customer relationships by embedding suppliers into ongoing operational optimization.
- Geothermal:Ground-source heat exchange serves stable-load applications in Melbourne and Auckland where geological conditions permit.
- Exhaust Heat Recovery:Thermal wheel and run-around coil configurations capture waste energy from kitchen and data center exhaust streams.
Variable Refrigerant Flow commands the dominant share; smart thermostats are climbing the fastest on penetration.
Application:
Customer type differentiation separates capital-intensive central plant investments from distributed unitary equipment serving fragmented building ownership structures.
- Cooling:Chilled water and direct-expansion systems address latent and sensible loads in tropical and subtropical climates across India, Thailand, and Vietnam. Data center operators in Singapore and Bangalore specify precision cooling with redundant capacity configurations exceeding standard commercial specifications.
- Indoor Air Quality:Integrated ventilation and filtration systems respond to post-pandemic occupancy expectations and China's escalating GB standards for particulate and CO2 monitoring. Developers in Beijing and Shenzhen now pre-install sensor networks as standard.
- Heating:Gas and electric heating infrastructure serves seasonal demand in northern China, Japan, and South Korea.
- Ventilation:Dedicated outdoor air systems manage fresh air delivery in high-density commercial developments.
Cooling absorbs the largest capital allocation; indoor air quality is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in HVAC equipment tilt toward import dependence in Southeast Asian markets while China and Japan maintain substantial manufacturing export capacity. Component sourcing patterns concentrate compressor production in Chinese and Japanese facilities, with finished system assembly distributed across regional hubs to satisfy local content requirements.
China
Data center construction in Beijing and Shanghai drives precision cooling demand at unprecedented scale. The MEE enforces escalating GB efficiency tiers that accelerate replacement of fixed-speed chillers with inverter-driven alternatives. Manufacturing clusters in Guangdong and Jiangsu provinces export compressor units throughout Southeast Asia.
Japan
Commercial retrofit demand concentrates in Tokyo and Osaka high-rise stock aging past replacement thresholds. METI's Top Runner program mandates efficiency improvements that favor VRF system adoption in premium office developments. Nagoya-based industrial zones supply advanced control systems to regional project developers.
India
Tier-1 cities Mumbai, Delhi, and Bangalore absorb the majority of commercial real estate investment flowing into climate infrastructure. BIS energy-labeling schemes now mandate efficiency tiers for new construction permits. Hyderabad's pharmaceutical corridor commands premium specifications for infection-control HVAC systems.
South Korea
Seoul's commercial district retrofits prioritize heat pump conversion from gas-fired heating to meet municipal decarbonization timelines. MFDS-aligned procurement rules for healthcare facilities create certification barriers for non-domestic suppliers. Busan-Ulsan industrial zones manufacture specialized coastal-grade equipment for regional export.
Australia
Sydney and Melbourne institutional landlords separate HVAC capital expenditure from operational expenditure in board-level reporting structures. TGA-equivalent building codes impose stringent ventilation standards that exceed baseline commercial requirements. Perth mining headquarters drive demand for robust climate systems in remote site applications.
Asia Pacific Commercial HVAC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in compressor and control module supply. Market structure consolidates around Japanese and Korean conglomerates with captive manufacturing capabilities, while European and North American players compete through service-contract bundling. Three archetypes dominate: vertically integrated OEMs with compressor manufacturing, asset-light system integrators leveraging project finance structures, and regional specialists targeting sub-scale commercial fit-outs. Competitive moves center on backward integration into refrigerant supply chains and geographic expansion through local installer network acquisitions.
Within the integrated manufacturing tier, Daikin Industries, Ltd. and Mitsubishi Electric Corporation exemplify platform control through captive compressor production. Midea Group Co., Ltd. anchors the scale-driven archetype with substantial Chinese manufacturing capacity. Carrier Global Corporation occupies a position emphasizing service-contract bundling over equipment margin capture.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Johnson Controls |
| Daikin Industries, Ltd. |
| Gree Electric Appliances |
| Trane |
| Midea Group Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| LG Electronics |
| Carrier Global Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's compressor manufacturing belt is compressing margins for regional suppliers while simultaneously expanding pricing leverage for buyers in Southeast Asian project markets. Equipment vendors in Guangdong and Jiangsu provinces are absorbing raw material volatility to maintain utilization rates, transferring cost pressure downstream through aggressive project bidding.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Asia Pacific Commercial HVAC landscape. Price differentiation rests on certification grade under China's GB standards and Japan's JIS specifications alongside after-sales service bundling. Cost compression in the standard tier is intensifying because copper and aluminum input volatility outpaces contract indexing mechanisms. Institutional landlords in Singapore and Sydney demonstrate lowest price sensitivity due to green leasing structures that transfer operational risk to vendors, while small-format retail operators in Ho Chi Minh City and Manila exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Export-control regimes limiting advanced semiconductor flows into Chinese manufacturing are prompting HVAC control system suppliers to diversify microcontroller sourcing toward Taiwanese and South Korean foundries. Compressor production draws from Chinese and Japanese facilities, with refrigerant chemical supply anchored in Jiangsu province petrochemical clusters. Single-source vulnerability concentrates in low-global-warming-potential refrigerant alternatives where Chinese chemical suppliers dominate global output. Distribution runs through regional assembly hubs in Thailand and Vietnam that satisfy local content requirements for government procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among institutional landlords in Singapore and Sydney who now unbundle service contracts from equipment procurement, fragmenting traditional OEM bundling strategies.
For Market Incumbents: Pre-empt disintermediation by captive compressor manufacturers through accelerated certification timelines under Australia's TGA-equivalent building codes. Lock in multi-year maintenance revenue streams via AI-driven predictive maintenance platforms that embed vendors into ongoing operational decisions. Defend against asset-light system integrators leveraging project finance structures by deepening backward integration into refrigerant supply chains.
For New Entrants and Emerging Players: Pursue Vietnam's industrial zone expansion in Bac Ninh and Hai Phong where manufacturing facility construction outpaces local HVAC installer capacity. Target healthcare facilities in Hyderabad's pharmaceutical corridor where infection-control specifications command premium pricing tiers. Establish first-mover advantage through acquisition of regional service networks rather than greenfield capacity buildout.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across heat pump manufacturing as modular platform architectures reduce tooling requirements. Long-term viability favors asset-light operators with installer network control over balance-sheet-heavy equipment manufacturers. Monitor technician certification gaps in Indonesia and Philippines as the signal indicating where service-capability scarcity will concentrate pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refrigerant Supply | Reduces single-source vulnerability to Chinese chemical suppliers under MEE enforcement timelines. |
| AI-Driven Predictive Maintenance Platform | Enables outcome-based service contracts with institutional landlords in Sydney and Melbourne. |
| Regional Installer Network Acquisition | Captures first-mover advantage in Vietnam's Bac Ninh and Hai Phong industrial zones. |
| GB Standards Certification Acceleration | Maintains market access as China's MEE escalates efficiency tier enforcement. |
| Green Leasing Contract Structure Development | Transfers operational risk to vendors while locking in multi-year revenue streams. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across facility managers in Shanghai and Tokyo high-rises, compressor manufacturing engineers in Guangdong and Jiangsu provinces, procurement leads at institutional landlords in Sydney and Singapore, HVAC installation contractors in Ho Chi Minh City and Manila, and regulatory affairs specialists navigating China's MEE and Japan's METI frameworks. Secondary validation drew from customs and trade flow databases, SEC 10-K filings of listed OEMs, China's GB standards documentation, and Australia's TGA-equivalent building code registers. Bottom-up project pipeline assessment and top-down macroeconomic overlay were triangulated to establish market sizing.
Calibration against historical replacement cycles and regulatory enforcement timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, building typology, technology platform, and regulatory compliance tier alongside application-specific thermal load profiles. CAGRs were derived from installed base turnover analysis and retrofit penetration curves. Forecast inputs incorporated data center construction permits in Bangalore and Singapore, BIS energy-labeling scheme adoption rates in Mumbai and Delhi, and heat pump conversion timelines in Seoul's commercial district.
Macroeconomic conditions sit as an overlay; deviation in copper and aluminum commodity prices, construction investment flows into tier-1 Indian cities, or refrigerant supply disruptions would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology cost curves. Material shifts in China's dual carbon policy implementation pace or Japan's METI Top Runner program stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
HVAC Air Handling Units Market