
 Global Modular Chillers Market | 2026-2036
Global Modular Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Modular Chillers Market Outlook
Aftermarket service revenue is fragmenting across regional service networks and digital remote-monitoring platforms as OEMs defend recurring income streams. Johnson Controls International PLC leverages its building automation ecosystem to capture long-term service contracts. Daikin Industries, Ltd. anchors its position through in-house compressor manufacturing and refrigerant technology leadership. Midea Group Co., Ltd. competes aggressively on manufacturing scale and cost-optimized module design.
Global modular chillers are factory-assembled, skid-mounted cooling systems using scroll, screw, or centrifugal compressors with capacities typically ranging from 10 to 600 tons per module, designed for parallel installation and independent operation. They serve commercial and industrial facilities requiring scalable, redundant cooling with minimal downtime during capacity expansion. Air-cooled configurations dominate retrofit and space-constrained installations where cooling tower infrastructure is unavailable, while water-cooled variants command premium positioning in large commercial buildings and data centers where efficiency targets drive specification. Variable refrigerant flow technology is gaining specification share in hospitality and healthcare end-user segments seeking zonal temperature control with part-load optimization.
The U.S. EPA SNAP program and the EU F-Gas Regulation are restricting high-GWP refrigerants, forcing compressor redesigns and alternative refrigerant qualification cycles that extend product development timelines. China's GB energy efficiency standards and the EU Ecodesign Directive mandate minimum performance coefficients that filter out lower-tier suppliers and consolidate specification authority among technology leaders. Stakeholders must monitor refrigerant transition timelines and efficiency standard convergence to align module portfolios with compliance windows and avoid stranded product configurations.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice sets and forcing compressor architecture redesigns across the modular chiller supply base, while data center cooling loads are pulling capacity specifications upward.
Growth Catalysts
- Data center precision cooling:Hyperscale operators in the United States and China are specifying redundant modular configurations to minimize thermal downtime during capacity expansion cycles.
- EU F-Gas Regulation:The phasedown schedule for high-GWP refrigerants is accelerating qualification cycles for lower-GWP alternatives and filtering specification authority toward technology leaders.
- China's GB energy efficiency standards:The country's commercial and industrial infrastructure buildout is concentrating demand for high-COP modular systems in tier-one cities.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger material costs fluctuate with commodity indices, compressing margin buffers for cost-optimized module producers.
- Compressor supply concentration:Scroll and screw compressor manufacturing clusters in East Asia create geographic single-point vulnerability for European and North American chiller assemblers.
- Alternative refrigerant thermodynamic limits:Lower-GWP options face capacity derating and pressure envelope constraints that restrict deployment in high-ambient temperature zones.
Strategic Opportunities
- India commercial real estate:Underpenetrated modular chiller deployment in the country's emerging IT corridors and pharmaceutical manufacturing clusters offers first-mover positioning.
- Digital remote-monitoring platforms:IoT-enabled predictive maintenance contracts are unbundling traditional service relationships and creating recurring revenue streams for platform operators.
- Variable refrigerant flow convergence:Integration of VRF zoning logic with modular chiller capacity staging is opening specification pathways in hospitality and healthcare verticals.
Industry Challenges
- Refrigerant handling certification:Technician qualification timelines for flammable A2L and A3 refrigerants are extending service deployment cycles and constraining field workforce scalability.
- Legacy building automation integration:BACnet and Modbus protocol mismatches between new modular chiller controls and existing building management systems are complicating retrofit specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Modular Chillers Market |
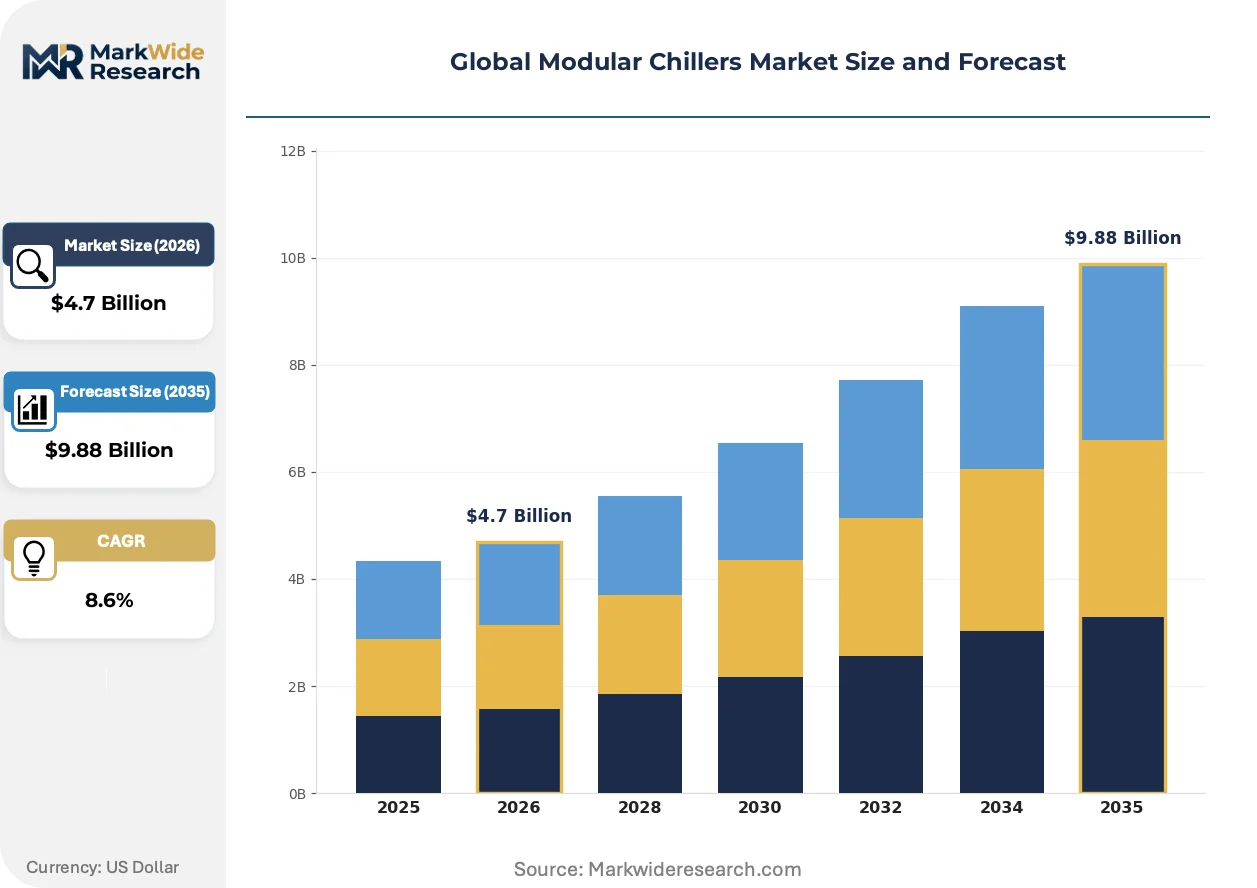
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Glycol-Cooled, Split-System End User: Commercial Buildings, Industrial Facilities, Hospitality, Healthcare Application: HVAC, Industrial Processing, Refrigeration, Thermal Energy Storage Technology: Variable Refrigerant Flow, Scroll Compressor, Screw Compressor, Centrifugal |
| Companies Covered | Johnson Controls International PLC, Mitsubishi Electric Corporation, Daikin Industries, Ltd., Frigel Firenze S.p.A., Gree Electric Appliances, Inc., Trane Technologies PLC, Midea Group Co., Ltd., Multistack International Limited, Carrier Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Modular Chillers Market Strategic Shifts
Refrigerant chemistry, compressor control logic, and thermal energy storage are converging to redefine efficiency benchmarks and operational flexibility expectations in modular cooling systems.
Magnetic bearing centrifugal compressor technology is migrating from large-tonnage custom chillers into smaller modular footprints. Data center operators in Northern Europe are piloting these configurations for part-load efficiency gains. The technology is compressing maintenance intervals and enabling oil-free operation that extends bearing life beyond traditional lubricated alternatives.
The EU F-Gas Regulation's refrigerant phasedown mandates are forcing original equipment manufacturers to requalify entire product lines with lower-GWP alternatives. Compressor displacement and heat exchanger surface area must increase to compensate for thermodynamic performance gaps. Water-cooled module variants are capturing specification share in large commercial buildings where efficiency targets offset first-cost premiums.
Outcome-based cooling service contracts are displacing traditional equipment procurement and maintenance silos. Facility managers in Singapore and the United Arab Emirates are contracting for guaranteed thermal performance rather than capital asset ownership. Energy service companies are absorbing operational risk and capturing margin through efficiency guarantees tied to real-time monitoring infrastructure.
Global Modular Chillers Market Segmentation
Modular chiller purchasing decisions fragment across technical specifications, operational requirements, and lifecycle cost structures. Procurement teams weight first-cost against service accessibility, refrigerant compliance timelines, and scalability for future capacity additions. Each segmentation dimension carries distinct margin profiles and aftermarket attachment rates that reshape vendor prioritization.
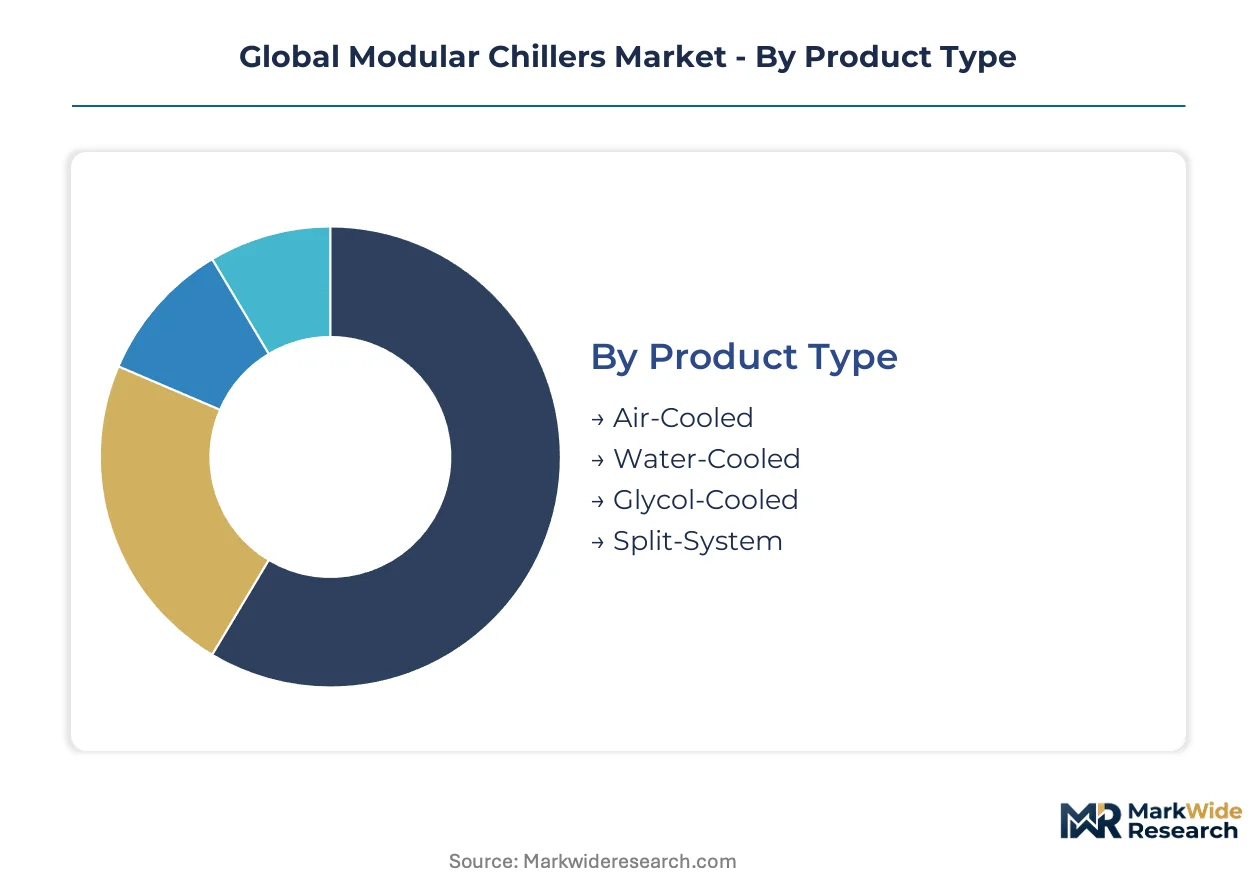
Product Type:
After-sales service intensity varies sharply across cooling configurations, with water-cooled systems demanding specialized tower maintenance and water treatment contracts that extend vendor relationships over fifteen-plus years.
- Air-Cooled:Self-contained condenser coils reject heat directly to ambient air, eliminating cooling tower infrastructure and water treatment regimes. Demand concentrates in retrofit installations across Germany and the United States where existing buildings lack mechanical room expansion capacity and municipal water costs penalize evaporative systems. The configuration dominates small-to-mid commercial deployments where installation speed outweighs efficiency premiums.
- Water-Cooled:Shell-and-tube or plate heat exchangers couple to external cooling towers, delivering higher energy efficiency ratios through lower condensing temperatures. Data center operators in Singapore and the Netherlands specify these systems for base-load thermal management where efficiency targets justify first-cost premiums and tower infrastructure already exists. The segment commands the densest service contract attach rates in the market.
- Glycol-Cooled:Closed-loop secondary fluid systems enable sub-freezing operation for process cooling and ice storage applications. Food processing facilities in Canada and pharmaceutical manufacturers in Switzerland deploy these configurations where precise temperature control and freeze protection override efficiency considerations.
- Split-System:Separated evaporator and condenser sections connected by refrigerant piping allow distributed installation across constrained mechanical spaces. Urban high-rise developments in Japan and South Korea specify split configurations where rooftop load limits or basement equipment access restrict packaged unit deployment.
Water-Cooled holds the largest share; momentum sits with Air-Cooled as retrofit activity accelerates in water-stressed municipalities.
End User:
Customer sophistication tiers separate specification authority, with data center and pharmaceutical operators demanding predictive maintenance integration while commercial real estate prioritizes capital efficiency.
- Commercial Buildings:Office complexes, retail centers, and mixed-use developments specify modular chillers for phased occupancy ramps and tenant improvement flexibility. Property developers in China's tier-one cities and India's IT corridors prioritize rapid deployment and independent module redundancy over peak efficiency optimization.
- Industrial Facilities:Manufacturing plants and process industries require continuous cooling with minimal downtime tolerance. Semiconductor fabrication in Taiwan and battery cell production in Hungary specify redundant modular arrays where individual module maintenance cannot interrupt thermal stability for sensitive production lines.
- Hospitality:Hotels and resorts demand zonal temperature control with part-load optimization across variable occupancy patterns. Integrated VRF-modular hybrid systems gain specification in Dubai and Maldives resort developments where guest comfort expectations clash with aggressive sustainability targets.
- Healthcare:Hospitals and research laboratories require precise humidity and temperature control for patient safety and equipment protection. Surgery suites and imaging departments in France and Australia specify magnetic bearing centrifugal modules for oil-free operation that eliminates contamination risk in critical care environments.
Commercial Buildings anchor volume; Healthcare delivers the steepest expansion trajectory as hospital infrastructure modernizes across Southeast Asia.
Application:
Operational duty cycles determine compressor technology matching and control system complexity, with continuous process loads demanding different architectures than intermittent comfort cooling.
- HVAC:Space conditioning for occupied environments operates across variable part-load conditions that favor staging strategies and variable speed control. District cooling networks in Saudi Arabia and district heating-cooling systems in Denmark integrate modular chillers as dispatchable capacity nodes within larger thermal grids.
- Industrial Processing:Manufacturing equipment cooling requires stable supply temperatures with tight tolerances for quality control. Plastic injection molding in Mexico and chemical synthesis in Belgium specify glycol-cooled modular systems where process continuity overrides energy efficiency in procurement decisions.
- Refrigeration:Cold storage and food processing applications operate at lower evaporating temperatures that stress compressor volumetric efficiency. Ammonia-charged industrial refrigeration in New Zealand and transcritical CO2 systems in Scandinavia create specification boundaries that modular chiller vendors must navigate through refrigerant selection.
- Thermal Energy Storage:Ice or chilled water storage systems shift electricity consumption to off-peak rate periods, requiring modules capable of extended low-temperature operation. Grid stabilization programs in California and demand response incentives in Texas drive specification of ice-making modular chillers for thermal battery installations.
HVAC dominates installed base; Thermal Energy Storage is climbing the fastest as utility rate structures reward load shifting.
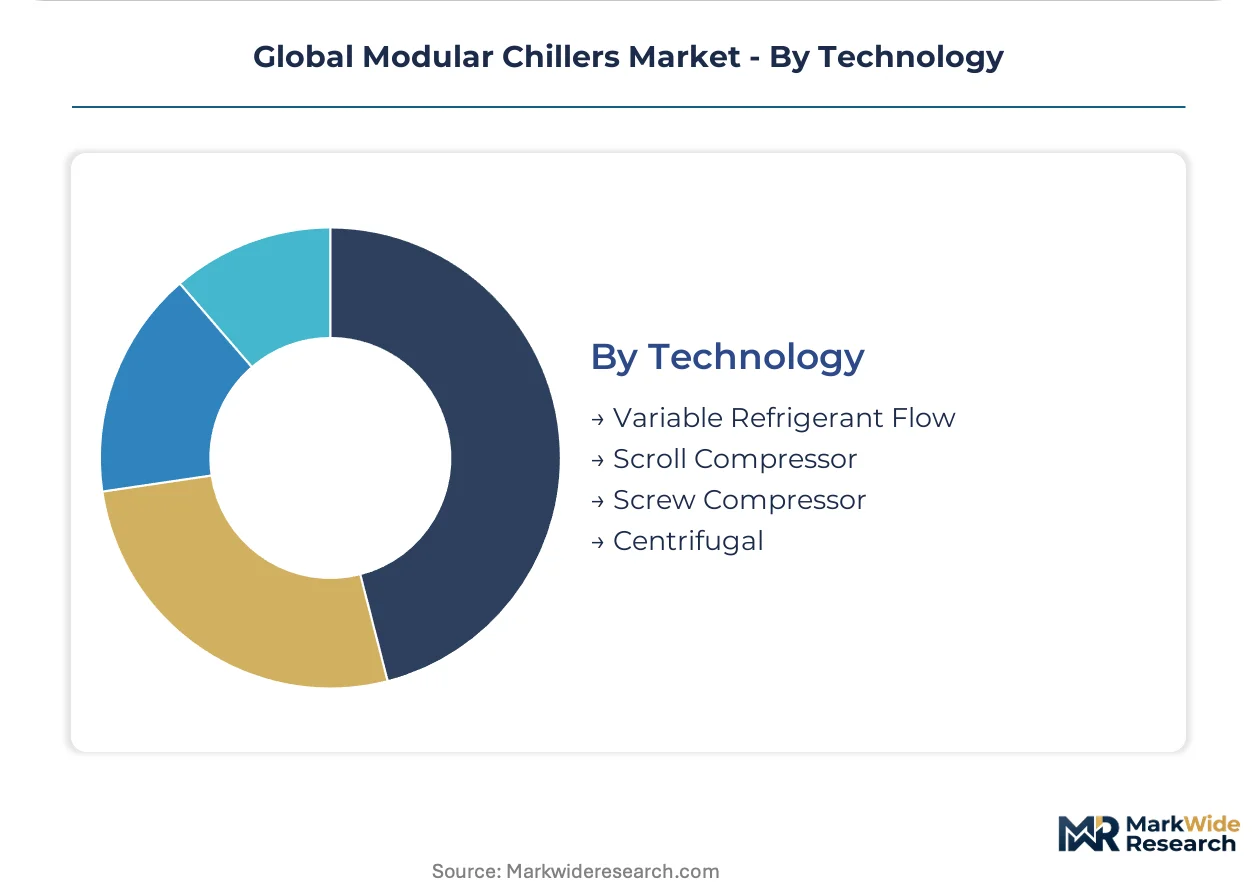
Technology:
Compressor architecture choices lock in efficiency curves, maintenance intervals, and refrigerant compatibility that constrain future retrofit options across extended equipment lifecycles.
- Variable Refrigerant Flow:Zoning logic distributes refrigerant to multiple indoor units based on real-time load detection, enabling simultaneous heating and cooling recovery. Hospitality developments in Thailand and senior living facilities in Spain specify VRF-modular hybrids where individual room control justifies system complexity premiums.
- Scroll Compressor:Hermetic orbiting scroll mechanisms deliver reliable compression for small-to-mid capacity modules with minimal moving parts. Distributed data centers in Brazil and commercial retrofits in Poland specify scroll-based systems where first-cost constraints and maintenance simplicity outweigh peak efficiency targets.
- Screw Compressor:Twin-rotor positive displacement enables efficient operation across wide pressure ratios for medium-tonnage applications. Industrial process cooling in South Africa and pharmaceutical cleanrooms in Ireland rely on screw compressors for continuous duty performance with oil management systems that extend bearing life.
- Centrifugal:Dynamic compression using impeller acceleration achieves highest efficiency at large capacities, with magnetic bearing variants eliminating oil systems entirely. Hyperscale data centers in Northern Europe and district cooling plants in the Middle East specify magnetic bearing centrifugal modules for part-load efficiency and maintenance interval extension.
Scroll Compressor holds the largest share; Centrifugal is gaining share fastest as magnetic bearing technology penetrates smaller capacity footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scroll and screw compressor manufacturing clusters concentrate in East Asia, creating geographic vulnerability for European and North American chiller assemblers. Demand fragmentation follows infrastructure buildout patterns across data center corridors, commercial real estate clusters, and industrial zones.
United States
Hyperscale data center operators in Northern Virginia and Phoenix specify redundant modular configurations for thermal uptime assurance. The EPA SNAP program restricts high-GWP refrigerant deployment, compressing product development timelines for alternative chemistry qualification. Dallas-Fort Worth and Atlanta commercial real estate developers prioritize air-cooled retrofits where cooling tower infrastructure is unavailable.
China
GB energy efficiency standards filter lower-tier suppliers while tier-one cities scale commercial and industrial infrastructure. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate refrigerant transitions in manufacturing zones. Yangtze River Delta data center clusters and Pearl River Delta pharmaceutical corridors concentrate demand for high-COP modular systems.
Germany
Industrial facilities in Baden-Württemberg and Bavaria deploy modular chillers for process cooling continuity in automotive and machinery production. The EU F-Gas Regulation mandates refrigerant phasedown schedules that force compressor architecture redesigns across the supply base. Frankfurt data center operators pilot magnetic bearing centrifugal configurations for part-load efficiency optimization.
Singapore
Tropical data center cooling loads pull capacity specifications upward as operators face land constraints and aggressive sustainability targets. The country's energy efficiency regulations mandate minimum performance coefficients for commercial cooling equipment. Jurong Island industrial corridor and Marina Bay financial district developments specify water-cooled modules where efficiency targets justify first-cost premiums.
India
Underpenetrated modular chiller deployment in emerging IT corridors and pharmaceutical manufacturing clusters offers first-mover positioning. The Bureau of Energy Efficiency implements building code standards that elevate chiller performance requirements in commercial construction. Hyderabad and Bengaluru technology parks scale precision cooling infrastructure as data center investment accelerates.
Global Modular Chillers Market Competitive Environment
Building-automation-integrated specialists and manufacturing-scale cost leaders split the market across specification tiers. The vendor base organizes around technology leadership, captive component production, and service network density rather than pure manufacturing volume. Three archetypes dominate: ecosystem-integrated building technology providers, compressor-technology-anchored refrigeration specialists, and scale-driven appliance conglomerates. Competitive positioning sharpens through vertical integration into compressor manufacturing and digital service platform deployment.
Among ecosystem-integrated providers, Johnson Controls International PLC represents the building automation convergence archetype, while Daikin Industries, Ltd. anchors the refrigerant technology leadership position. Midea Group Co., Ltd. exemplifies the manufacturing-scale competitive vector with cost-optimized module design capabilities.
| Leading Market Players |
|---|
| Johnson Controls International PLC |
| Mitsubishi Electric Corporation |
| Daikin Industries, Ltd. |
| Frigel Firenze S.p.A. |
| Gree Electric Appliances, Inc. |
| Trane Technologies PLC |
| Midea Group Co., Ltd. |
| Multistack International Limited |
| Carrier Global Corporation |
| Others |
Value Chain & Pricing Dynamics
East Asian compressor manufacturing clusters in Jiangsu province and the Pearl River Delta govern pricing power across downstream chiller assembly markets. Their concentration of scroll and screw compressor production capacity filters margin capture upstream, forcing European and North American assemblers to absorb commodity volatility or surrender pricing authority through long-term offtake agreements.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value capture across modular chiller deployments. Three-tier pricing structure across premium magnetic-bearing centrifugal systems, standard screw-compressor configurations, and economy scroll-based modules stratifies procurement budgets. Pricing pressure stems from copper and aluminum commodity index volatility compressing heat exchanger margins. Commercial real estate developers in water-stressed municipalities exhibit highest price sensitivity, while data center operators prioritize thermal uptime over capital efficiency.
Supply Chain Analysis
Export-control regimes on advanced compressor motor technologies and magnetic bearing systems constrain technology transfer to certain manufacturing zones. China, South Korea, and Japan anchor global scroll and screw compressor production. Heat exchanger fabrication draws from copper tube mills in Jiangxi province and aluminum fin stock from Henan. Single-source vulnerability concentrates in rare-earth permanent magnet supply for centrifugal compressor motors. Distribution runs through OEM direct sales for large projects and specialized HVAC distributors for retrofit specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as building automation ecosystems absorb modular chiller control logic and predictive maintenance interfaces. Interoperability standards like BACnet/IP and cloud-native API architectures enable outcome-based cooling service contracts that displace traditional equipment procurement.
For Market Incumbents: Pre-empt margin erosion from digital-native service platforms by accelerating captive compressor manufacturing investments and securing long-term refrigerant supply agreements ahead of EU F-Gas phasedown deadlines. Defend specification authority through backward integration into magnetic bearing technology and exclusive distribution partnerships with hyperscale data center operators.
For New Entrants and Emerging Players: Build out remote-monitoring platform capabilities and IoT-enabled predictive maintenance offerings to capture recurring revenue streams in India's underpenetrated pharmaceutical manufacturing corridors. White-space concentration sits with glycol-cooled modular systems for process cooling in Canadian food processing and Swiss pharmaceutical facilities. Go-to-market leverage centers on energy service company partnerships for outcome-based thermal performance contracting.
For Investors and Strategic Acquirers: Long-term, this sits as a refrigerant-transition infrastructure play because compressor architecture redesign cycles and alternative chemistry qualification timelines will consolidate specification authority among technology leaders with captive R&D and manufacturing scale. Acquisition targets should display vertical integration into compressor production or proprietary digital service platforms. The signal to watch is regulatory convergence on lower-GWP refrigerant mandates across multiple jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Centrifugal Migration | Enables oil-free operation extending bearing life beyond traditional lubricated alternatives in Northern European data centers. |
| Refrigerant Requalification Acceleration | Compresses product development timelines for lower-GWP alternatives under EU F-Gas Regulation phasedown mandates. |
| Digital Remote-Monitoring Platform Deployment | Unbundles traditional service relationships through IoT-enabled predictive maintenance contracts in Singapore and UAE. |
| Captive Compressor Manufacturing Investment | Secures supply chain control and margin capture against East Asian manufacturing cluster concentration risks. |
| Outcome-Based Cooling Service Contracting | Absorbs operational risk through efficiency guarantees tied to real-time monitoring infrastructure deployment. |
Study Parameters
The analysis maps air-cooled, water-cooled, glycol-cooled, and split-system configurations, each validated through plant engineers, HVAC contractors, data center facility managers, and aftermarket service directors. Primary interviews with OEM procurement teams and building automation integrators combined with secondary validation through EPA SNAP program filings, EU Ecodesign Directive compliance databases, China GB standard certification records, and customs trade data for compressor and heat exchanger imports. Bottom-up module shipment aggregation and top-down cooling capacity demand modeling provided triangulation across estimation approaches.
Assumptions held fixed include current EU F-Gas Regulation phasedown schedules, China dual carbon policy enforcement intensity, and copper-aluminum commodity price banding. Segmentation dimensions modeled encompass compressor technology type, cooling configuration, end-use vertical, and geographic regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle timing across the projection horizon. Forecast inputs incorporated data center power density trends and hospital infrastructure modernization pipelines in Southeast Asia.
Stress conditions across refrigerant transition timelines, commodity price volatility bands, and compressor supply disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology adoption curves. Material shifts in EU F-Gas Regulation acceleration, China energy efficiency standard stringency, or rare-earth magnet export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Global Air Conditioner Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
US HVAC Field Device Market