
 Warm Air Heater Market | 2026-2036
Warm Air Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Warm Air Heater Market Analytics
EPA furnace efficiency standards are recalibrating the cost-of-entry calculus for manufacturers serving North American commercial installations. Daikin Industries leverages its inverter-driven heat pump platforms to capture premium replacement demand in cold-climate warehouses. Lennox International anchors its position through captive distribution and contractor training networks across the Midwest and Northeast. Trane Technologies differentiates via integrated building automation tie-ins that bundle warm air heating with ventilation controls.
Warm air heaters are forced-air heating appliances that distribute conditioned air through ductwork or direct discharge at temperatures typically ranging from 40°C to 80°C, serving space heating and process drying applications across commercial and industrial environments. Gas-fired units dominate installed base value due to lower operating costs in regions with pipeline natural gas access, while electric heaters capture fastest growth in jurisdictions with aggressive building electrification mandates. The hospitality end user segment concentrates replacement demand in seasonal properties with intermittent occupancy patterns, whereas wall-mounted and ceiling-mounted installations gain share in retrofit applications where floor space commands premium value.
DOE furnace efficiency rules, EPA emissions guidelines, and ASHRAE ventilation standards collectively shape product certification requirements and installation compliance costs across the United States. The EU Ecodesign Directive and F-Gas Regulation impose parallel constraints on European manufacturers, restricting refrigerant choices in heat pump-integrated warm air systems. Stakeholders must monitor evolving electrification timelines and carbon border adjustment mechanisms to align product portfolios with diverging transatlantic compliance trajectories.
Market Dynamics
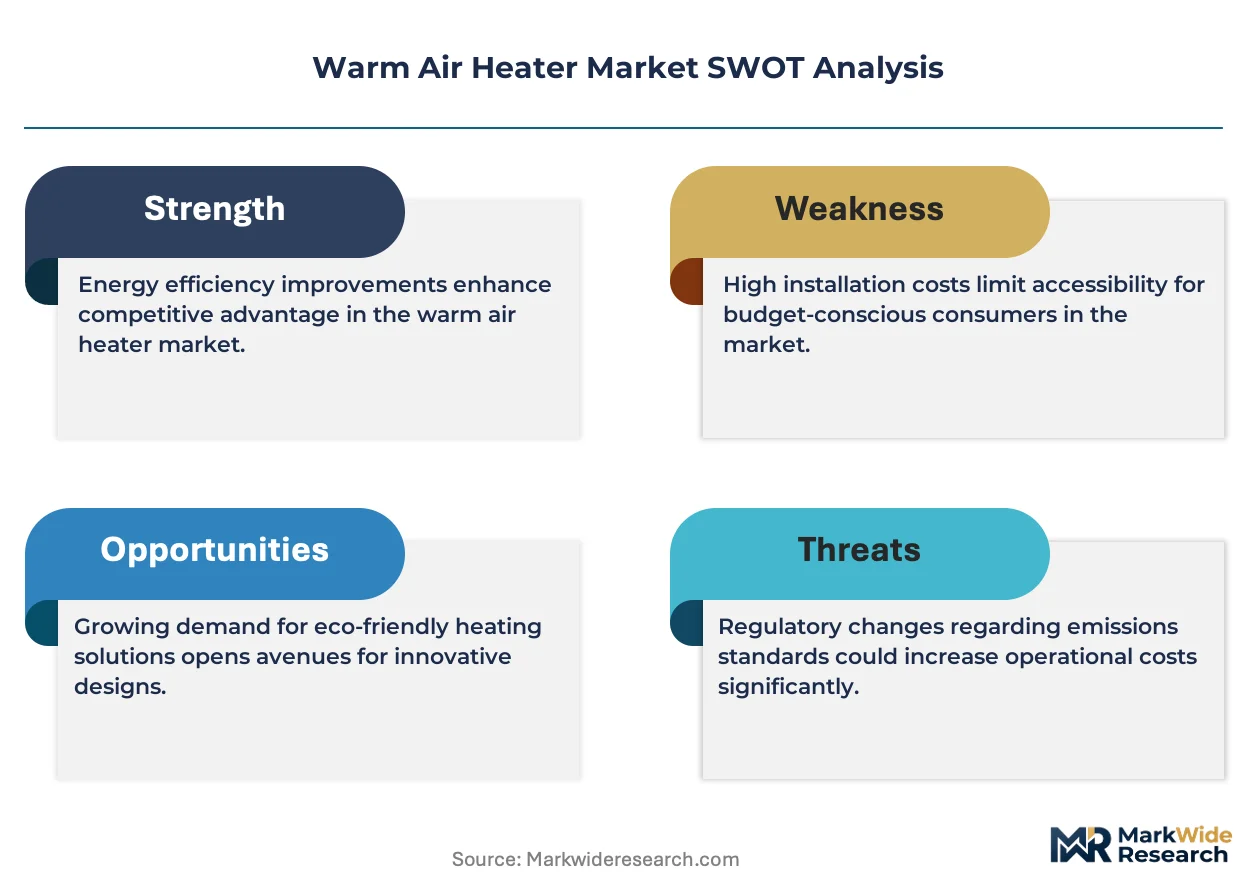
Warehouse electrification mandates and DOE furnace efficiency standards are compressing replacement cycles toward heat pump-integrated warm air systems, forcing manufacturers to reconfigure product portfolios around dual-fuel and all-electric architectures.
Growth Catalysts
- Building electrification mandates:Jurisdictions across Germany and the Netherlands are prohibiting new gas connections in commercial buildings, redirecting demand toward electric warm air heaters with integrated heat pump cores.
- Process heating integration:Industrial facilities in the Rhine-Ruhr corridor are combining space heating with low-temperature process drying applications, expanding unit utilization rates and replacement frequency.
- ASHRAE ventilation standards:Updated requirements for outdoor air delivery are driving bundled replacements of aging heating and ventilation systems in US educational and healthcare facilities.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and coil manufacturing faces margin pressure from commodity swings, compressing assembler profitability during contract bidding cycles.
- Refrigerant supply concentration:European heat pump-integrated warm air systems depend on constrained R-410A and R-32 supply chains centered on Chinese fluorochemical producers.
- Gas infrastructure lock-in:Extensive pipeline networks in the US Midwest and Northeast extend the payback period for electric retrofits, delaying conversion timelines in cost-sensitive segments.
Strategic Opportunities
- Data center thermal management:Hyperscale facilities in Northern Virginia and Frankfurt are adopting warm air heaters for humidity control and freeze protection in secondary spaces, creating a new application vertical.
- IRA commercial tax credits:The Inflation Reduction Act's 179D deduction and 48C manufacturing credit are improving project economics for heat pump installations in US warehouse and logistics properties.
- Modular retrofit packages:Ceiling-suspended and wall-mounted configurations are penetrating urban commercial retrofits where floor space constraints previously blocked warm air heater deployment.
Industry Challenges
- Heat pump technician scarcity:The shortage of certified installers for refrigerant-based systems is extending project timelines and inflating labor costs in cold-climate markets.
- Dual-certification complexity:Manufacturers must simultaneously satisfy ASHRAE 90.1, IECC, and state-level stretch codes, fragmenting product development resources and delaying regional launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warm Air Heater Market |
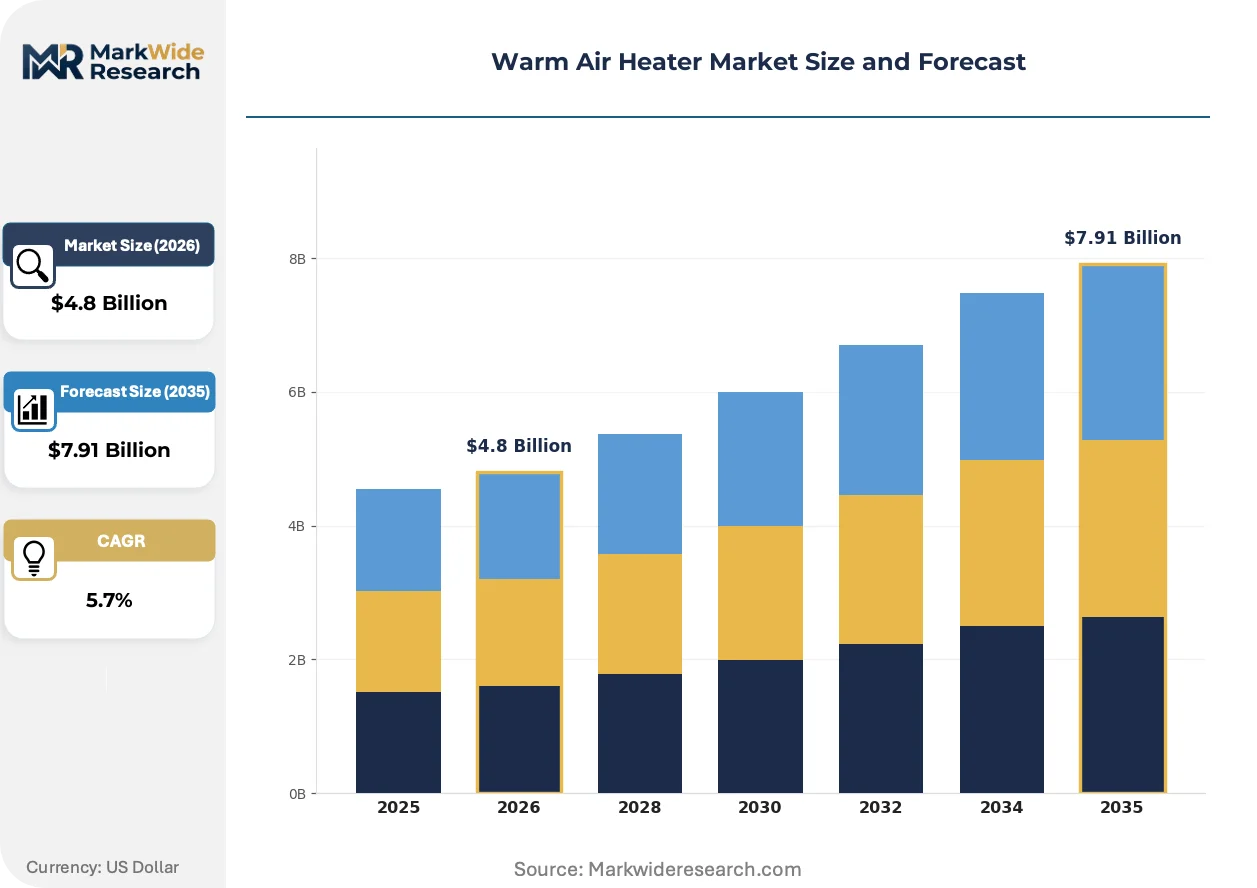
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heaters, Gas Heaters, Oil-Fired Heaters, Infrared Heaters Installation Type: Fixed, Portable, Wall-Mounted, Ceiling-Mounted Fuel Type: Natural Gas, Propane, Electricity, Wood End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Daikin Industries, Johnson Controls, Lennox International, Trane Technologies, Carrier, Modine Manufacturing, Winterwarm Heating Solutions, Kroll Energy, Powrmatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warm Air Heater Market Evolving Landscape
Digital control architectures and refrigerant chemistry advances are converging to redefine warm air heater performance benchmarks, while procurement patterns shift toward integrated building system contracts that bundle heating with ventilation and automation.
Variable refrigerant flow integration with warm air distribution is automating capacity modulation across zoned warehouse facilities. Cold-storage operators in Wisconsin and Pennsylvania are deploying these systems to match heat output against variable occupancy patterns. The technology is automating demand-response participation, allowing aggregators to curtail load during peak pricing events without comfort degradation.
The EPA's proposed stricter NOx emissions limits for commercial gas furnaces are accelerating condensing technology adoption. Manufacturers serving the US market must redesign heat exchanger geometries and combustion control systems to meet sub-14 nanogram-per-joule thresholds. The rule most affects rooftop units in the 250,000 to 400,000 BTU/h range, where non-condensing designs still dominate installed base value.
Performance contracting is displacing traditional equipment procurement in municipal and university sectors. Energy service companies in California and New York are assuming operational risk for heating system performance, shifting capital burden from facility owners to third-party operators. The model concentrates specification authority with ESCOs that prioritize verified efficiency outcomes over first-cost minimization.
Warm Air Heater Market Segmentation
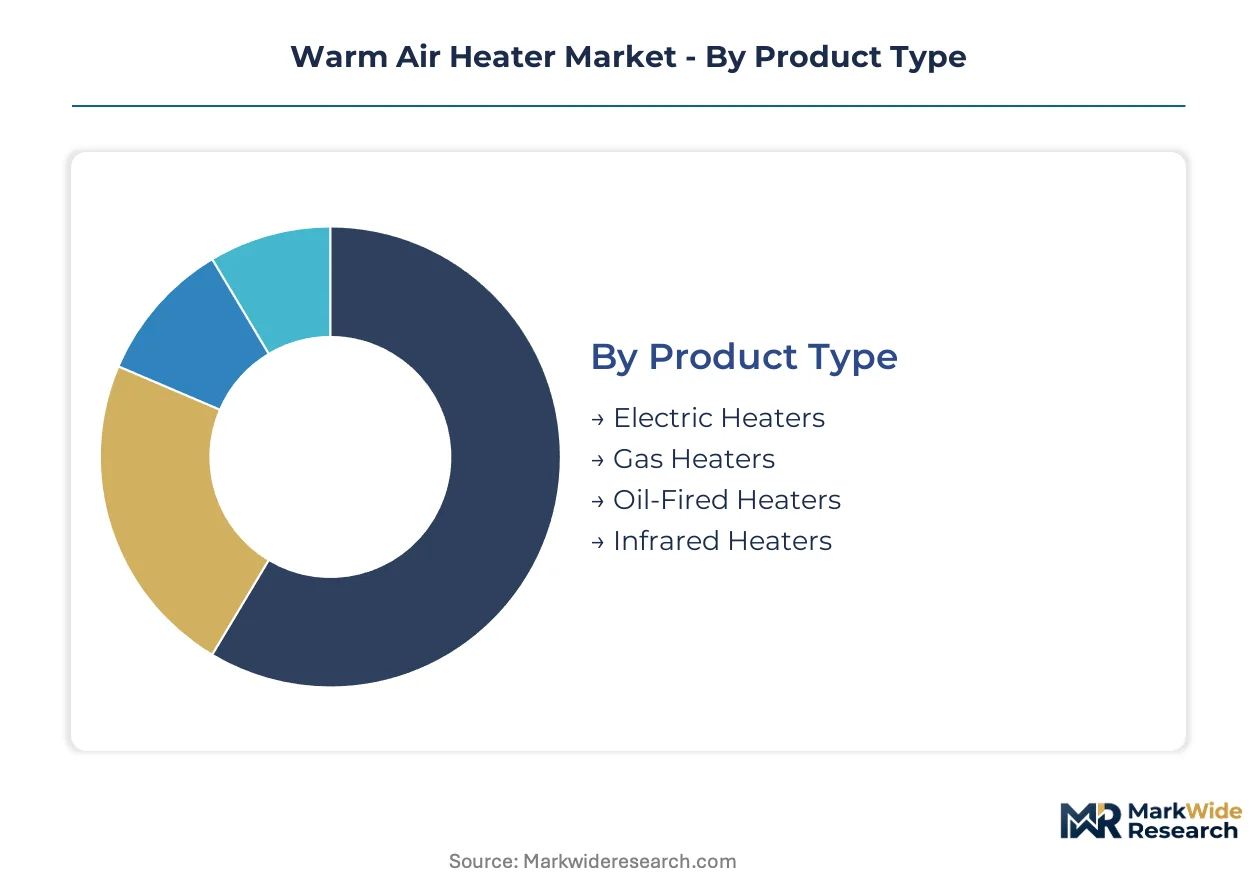
Warm air heater procurement patterns diverge sharply across product architectures and installation constraints. Certification requirements from EPA, DOE, and ASHRAE 90.1 fragment specification authority by segment, forcing manufacturers to maintain parallel compliance portfolios.
Product Type:
EPA furnace efficiency standards and DOE certification tiers impose divergent compliance burdens across thermal conversion technologies, with condensing gas and heat pump-integrated electric units facing the most stringent testing protocols.
- Electric Heaters:Resistance-element and heat pump-integrated configurations dominate building electrification retrofits. Demand concentrates in Germany's Rhine-Ruhr corridor where facility retrofits combine space heating with low-temperature process drying, driven by EU Ecodesign Directive mandates prohibiting new gas connections.
- Gas Heaters:Non-condensing and condensing forced-air systems retain installed base value in pipeline natural gas regions. US Midwest and Northeast warehouse operators prioritize these units where gas infrastructure lock-in extends electric retrofit payback periods, delaying conversion timelines.
- Oil-Fired Heaters:Forced-air systems burning distillate fuel oil serve off-grid commercial facilities in rural New England and Alaska.
- Infrared Heaters:Radiant tube and plaque configurations target spot heating in high-bay industrial spaces with minimal insulation.
Leading the category by volume: Gas Heaters. Growing fastest: Electric Heaters.
Installation Type:
Mounting configuration determines labor certification requirements and project timeline economics, with ceiling-suspended and wall-mounted systems demanding specialized rigging expertise that extends installer scarcity premiums.
- Fixed:Permanent ducted or direct-discharge installations anchor commercial and industrial baseload heating. US educational and healthcare facilities drive bundled replacements under updated ASHRAE ventilation standards, combining heating with outdoor air delivery upgrades.
- Portable:Mobile cabinet and torpedo-style units serve construction sites and emergency heating applications. Rental fleet operators in Canada and the northern United States seasonally reposition these assets to match cold-weather construction cycles.
- Wall-Mounted:Vertical configurations penetrate urban commercial retrofits where floor space commands premium value. Ceiling-suspended and wall-mounted installations gain share in constrained footprints.
- Ceiling-Mounted:Suspended unit heaters maximize clear floor space in high-bay warehouses and manufacturing facilities. Modular retrofit packages penetrate urban commercial applications previously blocked by spatial constraints.
Fixed installations dominate capital expenditure. Ceiling-Mounted configurations are climbing the fastest as warehouse operators prioritize cubic utilization.
Fuel Type:
Energy source selection locks facilities into decade-long operating cost trajectories, with electrification mandates and carbon border mechanisms recalibrating lifecycle economics across jurisdictions.
- Natural Gas:Pipeline-delivered methane retains cost advantage in US Midwest and Northeast markets. Extensive distribution infrastructure delays electric conversion in cost-sensitive segments despite IRA commercial tax credits.
- Propane:Liquefied petroleum gas serves off-grid commercial properties and seasonal hospitality operations. Rural Canadian and US Mountain West facilities rely on bulk tank storage where pipeline access remains uneconomical.
- Electricity:Grid-powered and heat pump-integrated systems capture fastest growth in jurisdictions with aggressive building electrification mandates. Netherlands and German commercial construction prohibitions on new gas connections redirect demand toward all-electric architectures.
- Wood:Biomass combustion systems serve rural industrial applications with captive fuel supply. Northern European sawmills and pellet manufacturers deploy these units where process residues offset purchased energy costs.
Natural Gas leads installed base value. Electricity is gaining share fastest under regulatory pressure.
End User:
Occupancy pattern and thermal load profile shape replacement cycle timing, with intermittent-use properties and continuous-process facilities exhibiting diverging equipment utilization rates.
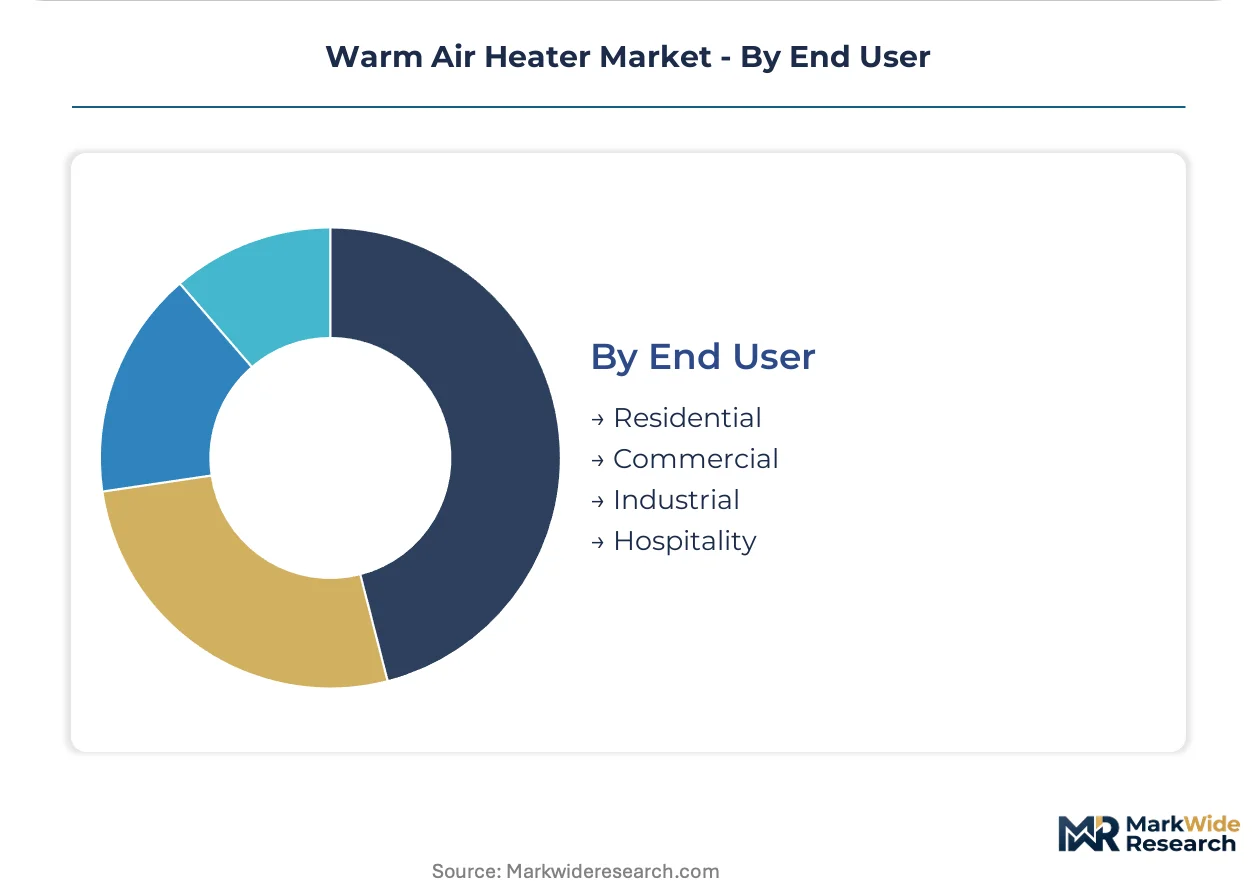
- Residential:Single-family and multi-family forced-air furnaces face replacement pressure from DOE efficiency standards. US Department of Energy rules push cycles toward condensing gas and electric heat pump configurations.
- Commercial:Office, retail, and institutional buildings drive bundled HVAC replacements. California and New York energy service companies assume operational risk through performance contracting models.
- Industrial:Manufacturing and warehouse facilities combine space heating with process applications. Rhine-Ruhr corridor retrofits expand unit utilization rates and replacement frequency through integrated process drying.
- Hospitality:Hotels and seasonal properties concentrate replacement demand in intermittent occupancy patterns. Cold-climate resorts in Wisconsin and Pennsylvania deploy variable refrigerant flow integration to match heat output against variable guest loads.
Commercial installations lead by heated floor space. Industrial applications show steepest expansion trajectory through process heating integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and IRA-designated clean energy communities are concentrating warehouse construction and HVAC retrofit investment in specific US metropolitan clusters. Germany's Rhine-Ruhr corridor combines industrial process heating with space heating mandates under EU Ecodesign Directive enforcement. Japanese manufacturing hubs face METI electrification timelines that compress gas-to-electric conversion windows.
United States
Warehouse electrification mandates in Northern Virginia and Dallas-Fort Worth hyperscale data center corridors are redirecting procurement toward heat pump-integrated warm air systems. The Inflation Reduction Act's 179D deduction and 48C manufacturing credit improve project economics for commercial installations. Midwest logistics hubs in Illinois and Ohio retain gas-fired installed base value where pipeline infrastructure delays electric conversion payback periods.
Germany
The Rhine-Ruhr industrial corridor combines facility retrofits with low-temperature process drying applications, expanding unit utilization rates. EU Ecodesign Directive prohibitions on new gas connections in commercial buildings redirect demand toward all-electric architectures. North Rhine-Westphalia manufacturing clusters face compressed replacement cycles as F-Gas Regulation restricts refrigerant choices in heat pump-integrated systems.
Netherlands
Amsterdam-Rotterdam-The Hague logistics corridors are prohibiting new gas connections in commercial construction, accelerating electric warm air heater deployment. National building codes mandate heat pump readiness in all new warehouse specifications. Port-adjacent cold storage facilities in Rotterdam deploy variable refrigerant flow integration to match heat output against variable occupancy patterns.
Japan
METI carbon neutrality roadmaps compress gas-fired equipment replacement timelines in Osaka-Kobe and Nagoya manufacturing belts. Commercial building energy codes tighten efficiency thresholds for rooftop warm air heaters in the 250,000 to 400,000 BTU/h range. Chubu region automotive suppliers combine space heating with paint-drying process applications, expanding dual-use equipment specifications.
United Kingdom
London and Southeast commercial retrofits face ASHRAE-aligned ventilation standards that drive bundled heating and outdoor air delivery replacements. Building Regulations Part L updates tighten efficiency requirements for non-domestic heating systems. Midlands distribution centers prioritize ceiling-suspended configurations to maximize cubic utilization in high-bay warehouse facilities.
Warm Air Heater Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology platforms and geographic coverage tiers. The market structures around three player clusters: full-stack HVAC integrators with building automation capabilities, captive distribution networks with contractor training infrastructure, and regional fabricators serving specific installation constraints. Consolidation pressure concentrates among mid-scale European manufacturers facing dual-certification complexity across ASHRAE 90.1 and IECC compliance regimes. Strategic moves center on refrigerant chemistry transitions and modular retrofit package development for constrained urban footprints.
Among diversified Japanese industrial conglomerates, Daikin Industries exemplifies inverter-driven heat pump platform specialization for cold-climate warehouse applications. US-based Lennox International and Trane Technologies anchor positions through contrasting approaches: captive distribution networks versus integrated building automation bundling. These three represent archetypal competitive vectors—technology-led product differentiation, channel control, and systems integration—that define strategic positioning across North American and European commercial installation markets.
| Leading Market Players |
|---|
| Daikin Industries |
| Johnson Controls |
| Lennox International |
| Trane Technologies |
| Carrier |
| Modine Manufacturing |
| Winterwarm Heating Solutions |
| Kroll Energy |
| Powrmatic |
| Others |
Value Network & Pricing Analysis
EPA NOx emissions limits for commercial gas furnaces gate qualified supply and premium-tier pricing access, compressing assembler margins for non-condensing designs while elevating certified heat pump-integrated configurations. Buyers face bifurcated procurement economics where compliance-certified units command sustained premiums against depreciating legacy inventory.
Pricing Analysis
Lead-time-driven pricing stratification separates expedited delivery premiums from spot inventory discounts across project bidding cycles. Three-tier pricing structure across condensing gas, heat pump-integrated electric, and non-condensing legacy units reflects certification grade and cold-climate performance validation. Cost compression in standard-tier gas-fired units intensifies because copper and aluminum commodity volatility squeezes heat exchanger manufacturing margins. Warehouse operators in the US Midwest exhibit highest price sensitivity due to gas infrastructure lock-in extending retrofit payback periods, while data center developers in Northern Virginia demonstrate lowest sensitivity prioritizing operational certainty over first-cost minimization.
Supply Chain Analysis
Heat exchanger coil manufacturing rests on Chinese fluorochemical producers for R-410A and R-32 refrigerant supply, Japanese specialty steel mills for corrosion-resistant alloys, and German precision component fabricators for combustion control systems. Raw material dependencies span copper tubing for thermal transfer surfaces, aluminum fins for air-side heat exchange, and rare-earth elements for inverter-driven compressor motors. Single-source vulnerability concentrates in Chinese refrigerant supply chains subject to export licensing volatility. Distribution runs through captive contractor networks in North America and specialized HVAC wholesalers in Europe with regional certification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA furnace efficiency standards and EU Ecodesign Directive enforcement create a barrier-to-entry moat for dual-certified manufacturers. Players lacking parallel ASHRAE 90.1 and IECC validation face exclusion from specification shortlists in regulated jurisdictions.
For Market Incumbents: Acquire certified installation contractor networks to secure downstream channel control against heat pump technician scarcity extending project timelines. Consolidate backward integration into refrigerant heat exchanger manufacturing to offset copper and aluminum price volatility compressing assembler profitability. Defensive positioning requires preemptive capacity in cold-climate heat pump configurations before F-Gas Regulation restrictions tighten supply.
For New Entrants and Emerging Players: The Inflation Reduction Act's 179D deduction in the United States opens a window for modular retrofit package specialists targeting warehouse electrification mandates in Dallas-Fort Worth and Northern Virginia corridors. White-space concentration sits in ceiling-suspended configurations for urban commercial retrofits where floor space constraints previously blocked warm air heater deployment. Go-to-market execution should anchor on performance contracting partnerships with energy service companies assuming operational risk for heating system outcomes.
For Investors and Strategic Acquirers: Announcement of F-Gas Regulation refrigerant quota reductions is the leading indicator that European heat pump-integrated warm air system assemblers face margin inflection requiring consolidation. Long-term viability over the next decade favors manufacturers with captive distribution and dual-certification capabilities spanning ASHRAE 90.1 and IECC regimes. Acquisition target archetype: mid-scale European fabricators with regional certification expertise but lacking scale to absorb compliance cost escalation. Watch for EPA finalization of sub-14 nanogram-per-joule NOx thresholds as the trigger accelerating condensing technology replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Transition | R-32 and R-454B migration addresses F-Gas Regulation constraints in European heat pump-integrated systems. |
| Backward Integration into Coil Manufacturing | In-house heat exchanger production insulates Daikin and Lennox from copper and aluminum commodity swings. |
| Performance Contracting Partnership | ESCO operational risk assumption shifts California and New York procurement authority toward verified efficiency outcomes. |
| Modular Retrofit Package Development | Ceiling-suspended configurations penetrate urban commercial footprints previously blocked by spatial constraints. |
| Contractor Certification Investment | Heat pump installer scarcity in cold-climate markets creates channel bottleneck for refrigerant-based system deployment. |
Research Methodology
Multi-period observation of DOE furnace efficiency standard implementation trajectories, EPA emissions guideline enforcement patterns, and EU Ecodesign Directive compliance timelines anchored the trend analysis, supplemented by interviews with plant engineers at warehouse and logistics facilities, HVAC contractor operations managers, energy service company portfolio directors, and OEM procurement specialists at data center developers. Secondary validation drew from DOE certification databases, EPA regulatory filings, ASHRAE standard revision records, customs trade data for heat exchanger components, and SEC 10-K disclosures from listed HVAC manufacturers. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across commercial building categories.
Segment-weighting across product type, installation configuration, fuel source, and end-user vertical determined revenue distribution modeling. The analytical framework applied penetration rate assumptions for heat pump-integrated systems against gas-fired installed base replacement cycles throughout the forecast period. CAGRs derived from regression analysis of historical efficiency standard impacts on replacement timing, adjusted for electrification mandate acceleration in Germany and the Netherlands. Industry-specific inputs included F-Gas Regulation refrigerant quota trajectories and IRA commercial tax credit utilization rates.
The model assumes a particular technology adoption path favoring heat pump-integrated architectures in electrification-mandate jurisdictions; alternative pathways retaining gas-fired condensing dominance in pipeline-access regions would alter the outlook. Forecasts reflect assumptions about technician training pipeline expansion, copper price stabilization, and refrigerant supply chain diversification. A small set of triggers warrants ongoing watch: EPA NOx final rule timing, EU carbon border adjustment mechanism implementation, and METI electrification timeline acceleration in Japanese manufacturing belts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
Global HVAC Filter Market