
 Wall Hung Boilers Market | 2026-2036
Wall Hung Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Hung Boilers Market Insights
Stainless steel heat exchangers is rebalancing cost-performance trade-offs across the mid-range product tier, displacing traditional copper-and-aluminum assemblies in premium system designs. Vaillant leverages in-house burner technology and captive supply of heat exchanger components to sustain margin structures in European residential channels. Bosch competes through its integrated controls ecosystem, while Navien anchors North American distribution with condensing gas specialization and direct-to-contractor digital platforms.
Wall hung boilers are self-contained, wall-mounted hydronic heating appliances engineered to deliver space heating and domestic hot water through sealed combustion and forced-draft heat exchanger configurations, typically operating at 85% to 98% thermal efficiency depending on condensing architecture. The primary commercial purpose centers on decentralized, on-demand thermal energy delivery for residential and light commercial buildings where floor space constraints and zonal control priorities dominate. Condensing units now command the value pool as efficiency regulations harden, while combi configurations capture fastest growth in urban residential retrofit where combined heating and hot water functionality eliminates separate tank requirements. Gas fuel type retains structural dominance across European and East Asian installed bases, though electric variants are gaining traction in markets with decarbonized grid profiles and heat pump hybridization mandates.
EU Ecodesign Directive and F-Gas Regulation are tightening minimum efficiency thresholds and refrigerant constraints for hybrid heat pump-boiler systems, reshaping product development roadmaps and certification burdens for manufacturers serving European markets. EPA ENERGY STAR specifications and DOE furnace efficiency standards in the United States parallel this trajectory, creating dual-compliance complexity for multinational suppliers. Stakeholders must monitor regulatory divergence between efficiency-first European frameworks and fuel-flexibility American approaches as they allocate R&D budgets and localize production footprints.
Market Dynamics
Condensing technology mandates under EU Ecodesign Directive are compressing replacement cycles and forcing supply chain reconfiguration toward stainless steel heat exchanger fabrication. This regulatory pressure is redistributing value from legacy copper-aluminum assembly suppliers toward component specialists with in-house metallurgy capabilities.
Growth Catalysts
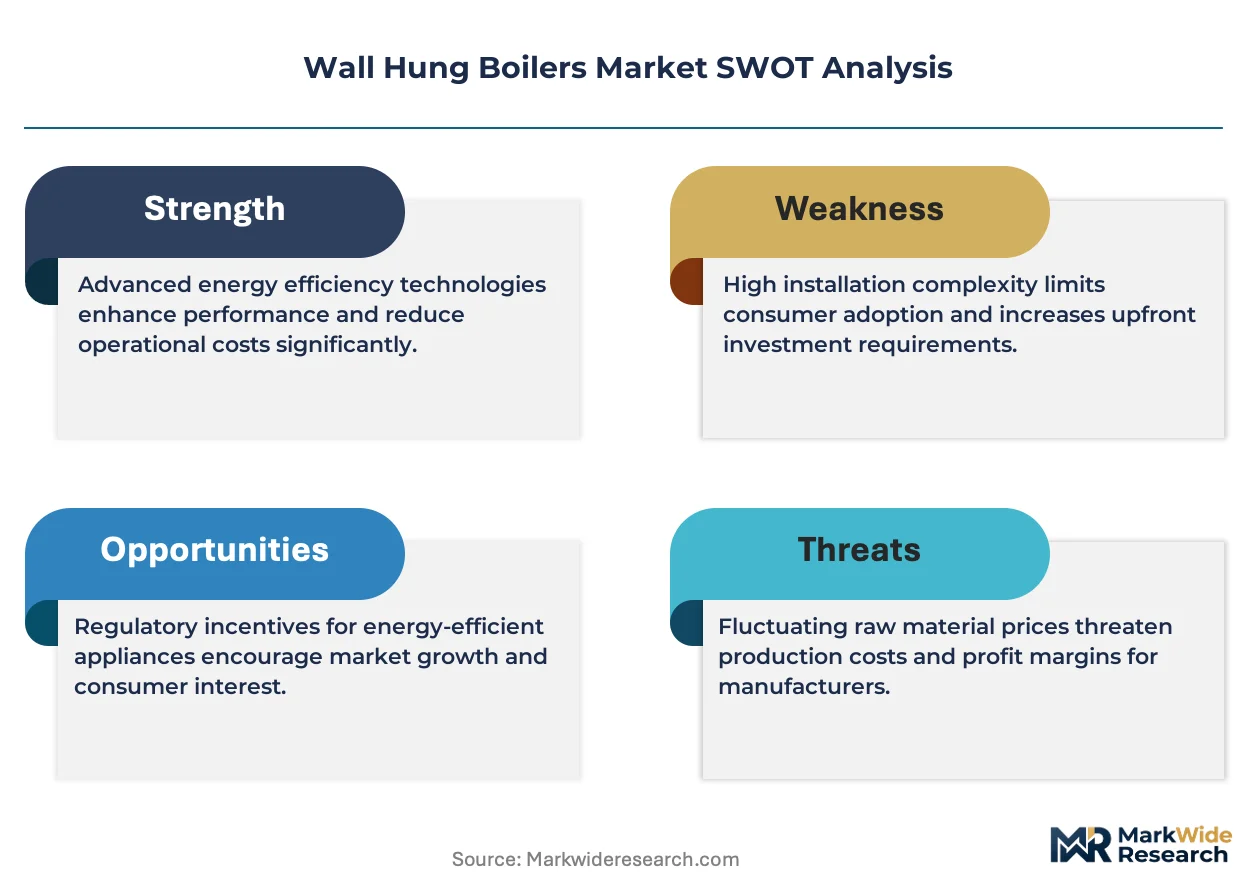
- F-Gas Regulation Phase-Down:Refrigerant constraints on hybrid heat pump-boiler systems are accelerating R&D investment in low-GWP alternatives, expanding the addressable market for gas-electric dual-fuel configurations.
- Multi-Family Housing Stock:Urban densification in China and South Korea is concentrating demand for space-constrained combi systems where wall hung units eliminate separate tank requirements.
- Stainless Steel Heat Exchangers:Corrosion-resistant metallurgy is extending service intervals and enabling higher condensing temperatures, improving lifecycle economics for residential retrofit installers.
Market Restraints
- Copper Price Volatility:Traditional heat exchanger materials face input cost instability that compresses margin structures for manufacturers without backward integration into metal sourcing.
- Gas Distribution Infrastructure Gaps:Uneven pipeline coverage in rural France and southern Italy limits addressable market penetration for gas-fired wall hung systems outside urban cores.
- Heat Pump Substitution:Air-source and ground-source electric heat pumps are capturing efficiency-conscious segments in markets with decarbonized grid profiles and renewable electricity subsidies.
Strategic Opportunities
- Hybrid System Integration:Convergence of gas condensing boilers with air-source heat pumps creates white space for bivalent control systems optimizing fuel switching based on ambient temperature and electricity pricing.
- Direct-to-Contractor Digital Platforms:North American distribution channels are fragmenting as manufacturers bypass traditional wholesaler networks to capture margin and installation data.
- Building Energy Code Tightening:Germany's Building Energy Act and France's RE2020 regulations mandate near-zero heating emissions in new construction, positioning high-efficiency condensing units as compliance pathways during transition periods.
Industry Challenges
- Combustion Engineering Talent Scarcity:Sealed combustion and forced-draft optimization require specialized expertise that is concentrating among aging European engineering workforces and specialized technical institutes.
- Dual-Compliance Certification Burden:Manufacturers serving both European and North American markets must navigate divergent testing protocols under EU Ecodesign and EPA ENERGY STAR specifications simultaneously.
- Legacy Hydronic System Integration:Retrofit installations face compatibility friction with existing radiator sizing and distribution piping originally engineered for higher-temperature non-condensing operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Hung Boilers Market |
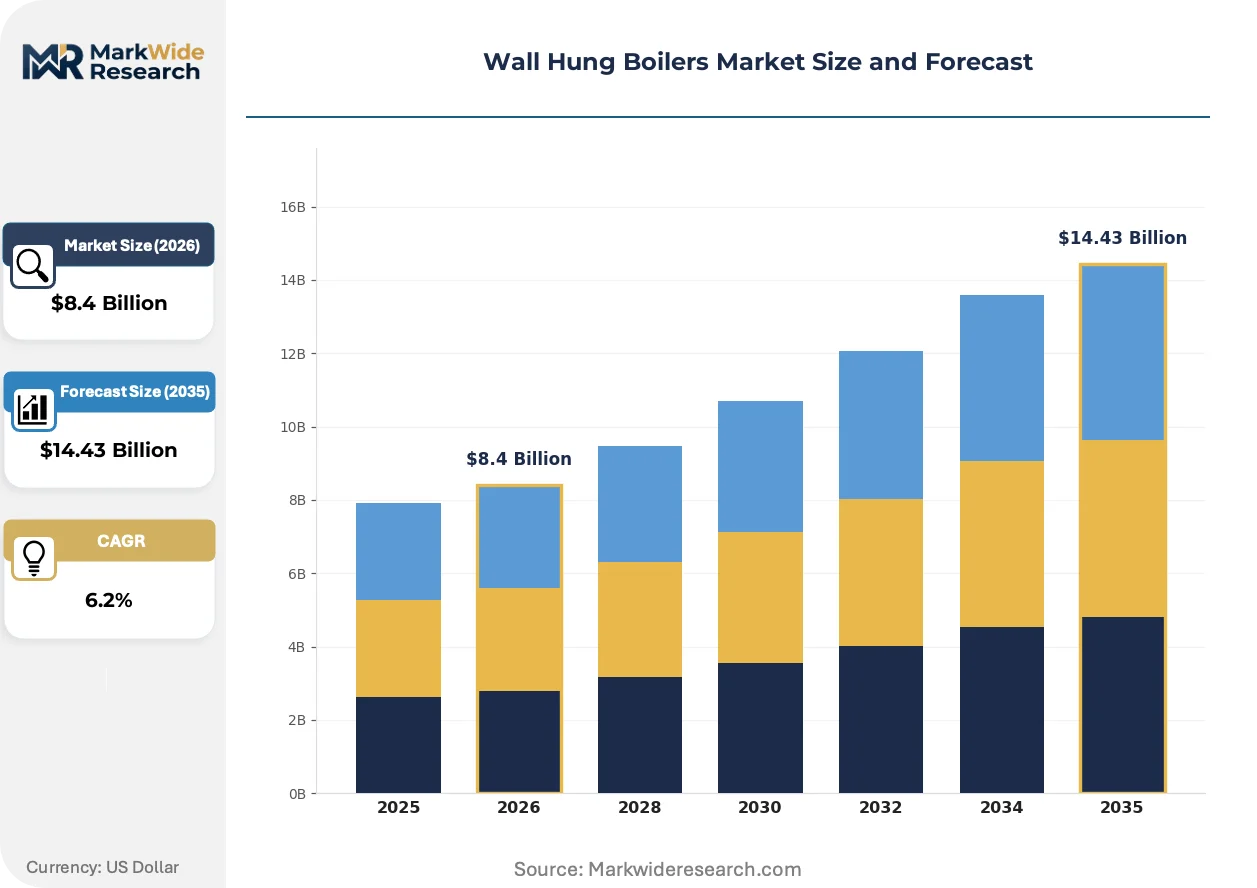
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Condensing, Non-Condensing, Combi, System Fuel Type: Gas, Electric, Oil, Biomass Application: Residential, Commercial, Industrial, Institutional Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | BAXI, Ferroli, Vaillant, Navien, Rinnai, Viessmann, Ariston, Daikin, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Hung Boilers Market Trends and Innovations
Digital control architectures and predictive maintenance capabilities are transforming wall hung boilers from passive heating appliances into networked thermal assets. This connectivity shift is enabling new service revenue models and reshaping manufacturer-customer relationships beyond the point of sale.
Modulating burner technology with 1:10 turndown ratios is rewriting efficiency performance across partial-load conditions that dominate residential operating hours. German and Austrian manufacturers are deploying these systems in multi-family retrofit projects where demand fluctuation is severe. The technology is compressing the efficiency gap between condensing and non-condensing architectures to the point where regulatory minimums are becoming competitive table stakes rather than differentiators.
EPA ENERGY STAR Version 5.0 specifications are tightening minimum annual fuel utilization efficiency thresholds and introducing standby power limits for gas-fired heating equipment. These requirements are forcing control system redesigns and pushing smaller manufacturers toward third-party electronics suppliers. The residential replacement channel in the northeastern United States is experiencing the steepest compliance cost escalation as legacy product inventories deplete.
Installer preference is consolidating around manufacturers offering integrated sizing software and remote diagnostic platforms that reduce callback frequency. French and Italian heating contractors are prioritizing suppliers with mobile applications enabling real-time combustion analysis and warranty registration. This behavioral shift is concentrating specification authority at the point of installation rather than the point of original equipment purchase.
Wall Hung Boilers Market Segmentation
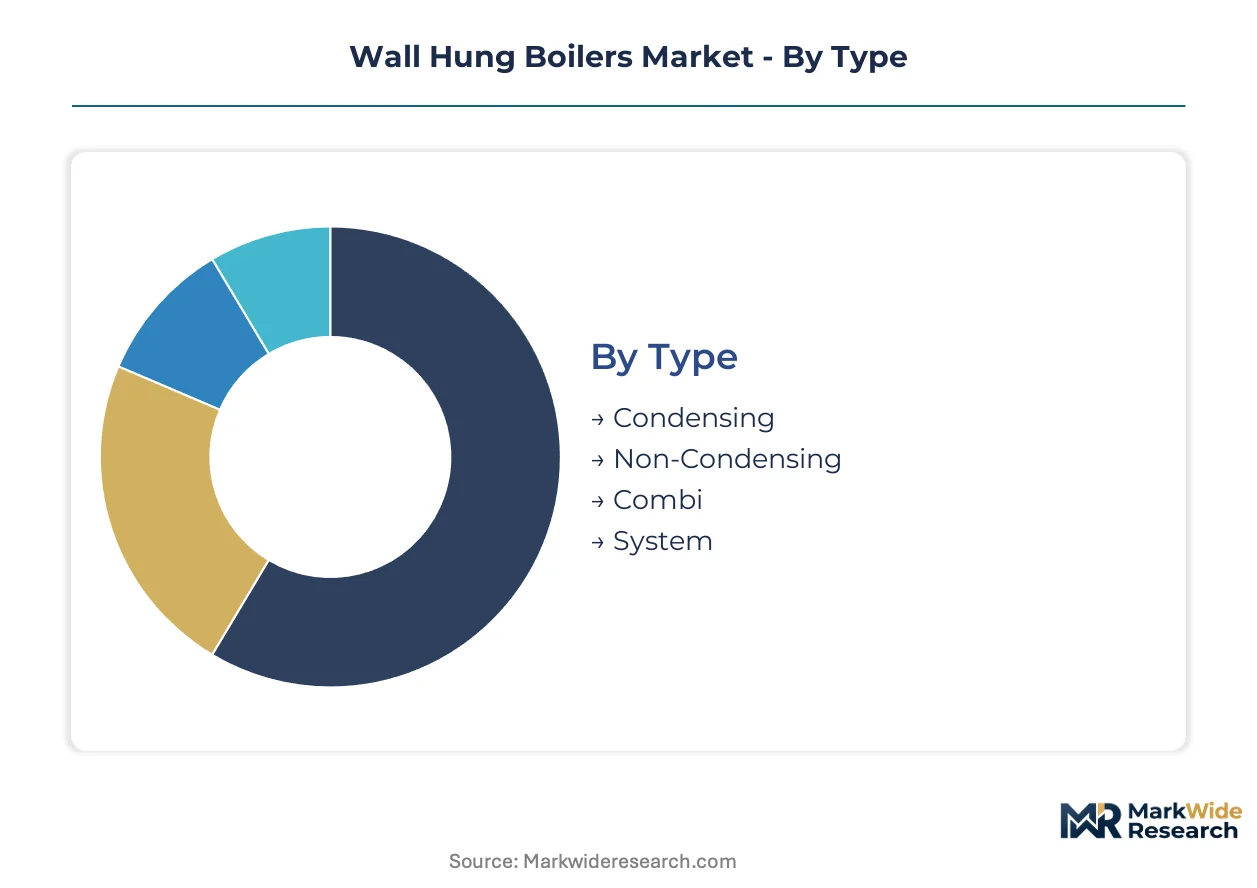
Wall hung boilers serve distinct thermal loads across building typologies and fuel infrastructures, requiring manufacturers to align product architectures with regulatory efficiency tiers and local energy availability. Segmentation reveals where condensing technology premiums command pricing power versus where legacy non-condensing units retain replacement demand.
Type:
Integration depth varies sharply: combi and system configurations embed domestic hot water production, while condensing and non-condensing architectures represent standalone efficiency tiers rather than embedded subsystems.
- Condensing:Stainless steel or aluminum-silicon heat exchangers recover latent heat from flue gases, achieving thermal efficiency above 90%. German and French residential retrofits concentrate demand as EU Ecodesign mandates eliminate non-condensing alternatives.
- Combi:Integrated domestic hot water heat exchangers eliminate separate tank requirements in space-constrained multi-family housing. South Korean urban densification and Chinese high-rise construction accelerate specification.
- Non-Condensing:Traditional cast-iron or copper heat exchanger designs persist in rural Eastern European markets with delayed regulatory enforcement.
- System:Space-heating-only configurations pair with external hot water cylinders in larger residential footprints.
Volume placements concentrate in Condensing; the faster expansion belongs to Combi.
Fuel Type:
Cost tier stratification separates premium gas-fired condensing systems from economy electric variants, with oil and biomass occupying niche positions where grid infrastructure or renewable feedstocks create local arbitrage.
- Gas:Natural gas and LPG variants dominate installed bases across EU member states and East Asian markets. Distribution network density in Germany, Italy, and China determines addressable market penetration.
- Electric:Resistance and electrode boiler configurations gain specification in Nordic markets with decarbonized grid profiles and heat pump hybridization mandates.
- Oil:Kerosene and gasoil-fired units persist in rural France, Ireland, and Alpine regions lacking pipeline connectivity.
- Biomass:Wood pellet compatibility remains marginal, constrained by fuel logistics and emissions certification complexity.
Gas retains the dominant volume position; electric variants are climbing the fastest on decarbonization policy alignment.
Application:
Customer type segmentation separates owner-occupied residential decision-makers from commercial facility managers and institutional procurement officers with divergent payback period requirements.
- Residential:Single-family and multi-family installations prioritize compact footprints and zonal control. German building energy codes and French RE2020 regulations drive replacement cycles.
- Commercial:Light commercial buildings, hotels, and small offices demand higher duty cycles and redundant configurations.
- Industrial:Process heating and auxiliary space heating in manufacturing facilities requires heavy-duty heat exchanger specifications.
- Institutional:Schools, hospitals, and government buildings impose extended warranty and service contract requirements.
Residential channels absorb the highest unit volumes; commercial applications show the steepest expansion trajectory on building stock modernization.
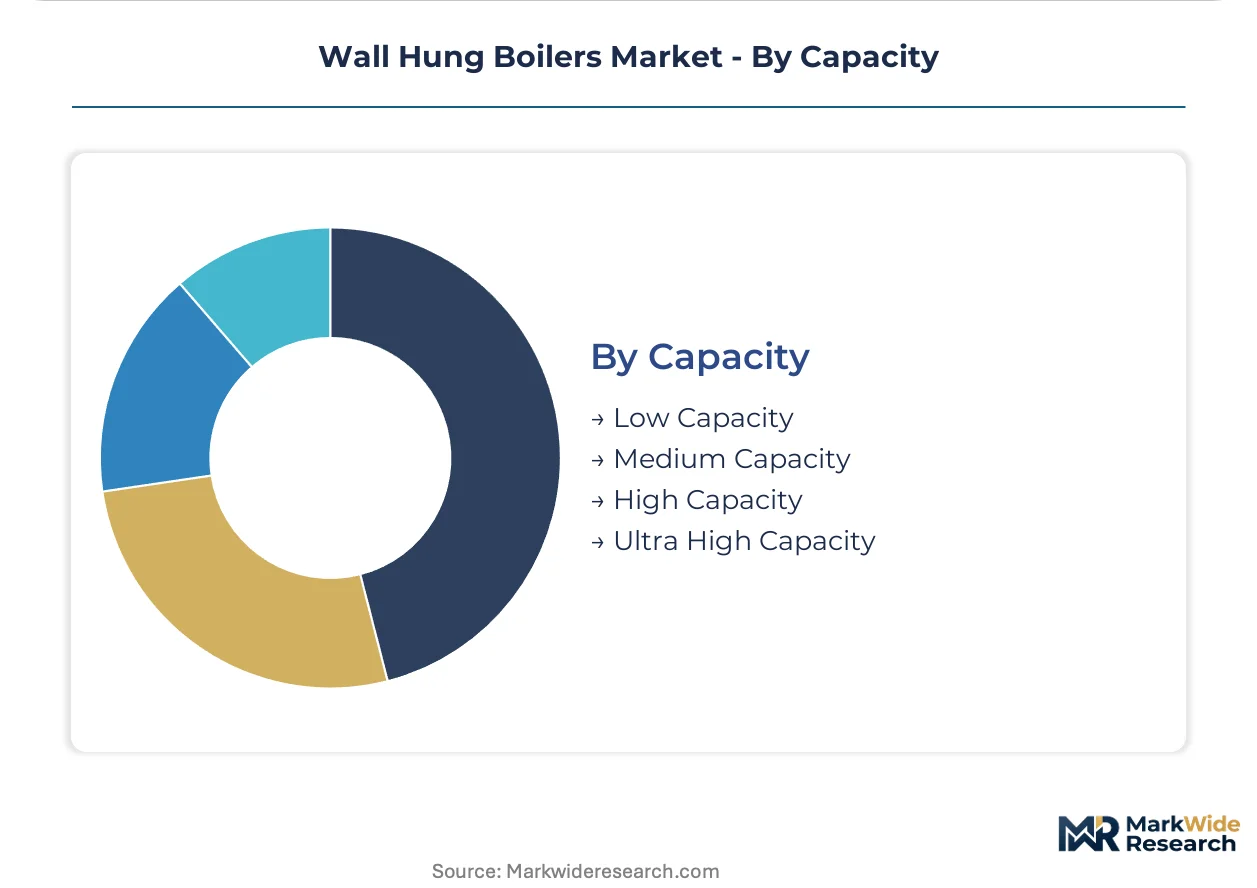
Capacity:
Maturity gradients separate established low-capacity residential segments from emerging ultra-high-capacity commercial configurations where technical validation remains incomplete.
- Low Capacity:Units below 24 kW serve apartments and small dwellings. Italian and Spanish markets concentrate replacement demand in this tier.
- Medium Capacity:24-35 kW output ranges cover standard single-family homes across Northern European climates.
- High Capacity:35-50 kW systems address large residential footprints and light commercial loads with cascade installation protocols.
- Ultra High Capacity:Above 50 kW modular configurations serve multi-unit dwellings and small commercial buildings through manifolded arrays.
Medium capacity commands the densest installation base; ultra-high capacity is gaining share fastest on multi-family construction trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German building energy zones concentrate replacement demand as retrofit subsidies accelerate condensing boiler penetration across residential districts. French RE2020 compliance corridors and Italian Superbonus tax credits channel installer capacity toward high-efficiency system upgrades.
Germany
Building Energy Act mandates near-zero heating emissions in new construction, compressing replacement cycles in Bavaria and North Rhine-Westphalia. Federal subsidies through KfW development bank cover condensing system retrofits. The Ruhr industrial corridor hosts dense networks of heating contractors specializing in hydronic system integration.
France
MaPrimeRénov renovation grants drive specification of high-efficiency combi units in Île-de-France apartment stock. RE2020 regulations tighten thermal performance requirements for new residential buildings. Lyon and Grenoble clusters concentrate HVAC engineering talent for sealed combustion system optimization.
Italy
Superbonus 110% tax credits accelerated condensing boiler installations through 2023-2024 in Lombardy and Veneto. ENEA efficiency certifications now gate subsidy eligibility for residential retrofits. Milan-Turin industrial corridor maintains specialized foundry capacity for heat exchanger component supply.
China
Dual carbon policy targets and coal-to-gas conversion programs expand gas distribution coverage in Yangtze River Delta residential zones. MIIT efficiency standards for gas appliances tighten minimum thermal performance thresholds. Shanghai and Hangzhou construction markets concentrate demand for space-constrained wall hung systems in high-rise housing.
South Korea
Building energy codes mandate high-efficiency heating equipment in Seoul Capital Area multi-family developments. KEMCO efficiency labeling programs differentiate condensing from non-condensing product tiers. Busan-Ulsan industrial corridor supplies precision metal fabrication for heat exchanger manufacturing.
Wall Hung Boilers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European heritage brands commanding premium positioning in residential retrofit channels while Asian fabricators capture volume in new construction markets. The vendor base concentrates among three tiers: integrated heating conglomerates with captive component production, specialized boiler manufacturers with regional channel depth, and diversified HVAC groups leveraging distribution synergies. Strategic moves center on backward integration into heat exchanger metallurgy and digital platform development for contractor-direct engagement.
Within the integrated heating conglomerate tier, Bosch and Vaillant exemplify archetypes combining in-house burner technology with control system ecosystems. Navien anchors the Asia-Pacific specialist position. These three represent divergent geographic origins—German, German, and South Korean respectively—each occupying distinct channel positions without overlapping core market footprints. Their competitive separation allows parallel premium pricing power in their respective home regions.
| Leading Market Players |
|---|
| BAXI |
| Ferroli |
| Vaillant |
| Navien |
| Rinnai |
| Viessmann |
| Ariston |
| Daikin |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
Captive heat exchanger production in Germany and South Korea anchors both supply security and premium pricing power for integrated manufacturers serving European and East Asian residential channels. Component backward integration insulates margin structures from copper price volatility while enabling tiered product positioning across condensing efficiency grades.
Pricing Analysis
Volume placements cluster in mid-range condensing tiers while margin capture concentrates in premium stainless steel configurations with extended warranty bundling. Price differentiation rests on metallurgy grade and combustion control sophistication, with German and Austrian heritage brands commanding installer loyalty premiums. Cost compression in economy copper-aluminum assemblies is intensifying as Chinese fabricators expand export capacity. Residential retrofit contractors in Italy and France exhibit highest price sensitivity, while commercial facility managers prioritize lifecycle service contracts over upfront equipment cost.
Supply Chain Analysis
Refurbishment flows for heat exchanger cores are emerging in Germany and the Netherlands as circular economy mandates tighten component recovery requirements. Manufacturing concentration spans Germany, Italy, and China, with precision burner assembly anchored in Baden-Württemberg and Veneto. Raw material sourcing draws from Chilean copper, Chinese aluminum, and Swedish stainless steel. Single-source vulnerability concentrates in specialized gas valve electronics sourced from Bavarian suppliers. Distribution runs through heating contractor networks in Europe and direct-to-installer digital platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecodesign Directive enforcement is compressing viable player count as certification burdens and metallurgy investments filter out sub-scale competitors. Condensing technology mandates favor integrated manufacturers with captive component production.
For Market Incumbents: Cement dominance in stainless steel heat exchanger fabrication through acquisition of Italian and Czech metallurgy specialists. Defend against heat pump substitution by accelerating hybrid system R&D and securing KfW subsidy eligibility for gas-electric configurations. Channel control through installer-facing diagnostic platforms remains critical for specification authority. For New Entrants and Emerging Players: France's RE2020 regulation opens a window for high-efficiency combi specialists targeting Île-de-France multi-family retrofit. White space exists in ultra-high-capacity modular configurations for German social housing cascade installations. Go-to-market should leverage direct digital procurement bypassing traditional wholesaler markups. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified HVAC conglomerates seeking European residential retrofit exposure. Long-term viability favors targets with in-house burner technology and established KEMCO or ENEA efficiency certifications. Monitor German Building Energy Act amendment trajectories for inflection signals on gas heating phase-out timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Metallurgy | Captive stainless steel production insulates Vaillant and Bosch from copper price volatility. |
| Hybrid System Control Platform Development | Bivalent gas-heat pump optimization addresses EU F-Gas Regulation compliance requirements. |
| Direct-to-Contractor Digital Channel Buildout | Navien's installer platform model captures margin and combustion performance data in North America. |
| Remanufacturing and Component Recovery Program | Circular economy alignment meets French RE2020 material recovery mandates for urban retrofits. |
| Extended Warranty and Service Contract Bundling | Recurring revenue streams reduce price sensitivity among German residential replacement buyers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this wall hung boilers assessment. Primary interviews with heating system contractors, HVAC procurement managers, and metallurgy component suppliers combined with ENEA efficiency certification databases and KfW subsidy disbursement records. Bottom-up unit shipment tallies by capacity tier and fuel type triangulated against top-down construction permit flows and building stock age profiles.
Data-stream reconciliation across manufacturer shipment disclosures, distributor inventory reports, and end-user installation permits produced volume and value estimates across the projection horizon. Segmentation modeling incorporated technology type, fuel architecture, application, and capacity tier dimensions. CAGRs derived from regression analysis against regulatory mandate implementation schedules and building energy code tightening trajectories, with specific inputs from gas distribution infrastructure expansion timelines and heat pump substitution elasticity parameters.
The model assumes a particular technology adoption path; alternative pathways for hydrogen-ready boiler architectures would alter the outlook if pipeline injection mandates accelerate. Forecasts reflect documented assumptions on replacement cycle compression rates and subsidy program continuity. Practitioners should monitor German coalition negotiations on heating system phase-out dates and Chinese MIIT efficiency standard revision drafts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Global Air Conditioner Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Europe Air Conditioning Equipment Market