
 Europe Residential Fan Coil Convectors Market | 2026-2036
Europe Residential Fan Coil Convectors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Residential Fan Coil Convectors Market Foresight
European HVAC component manufacturing is rebalancing toward higher-efficiency heat exchange platforms. PURMO GROUP leverages its pan-European distribution network to sustain market presence across Nordic and Continental markets. Daikin competes through technology leadership in integrated climate systems, while Systemair AB anchors its position with specialized air handling expertise.
Residential fan coil convectors are hydronic or electric terminal units that use forced convection to distribute conditioned air through finned heat exchangers, typically rated between 0.5 kW and 5 kW output for domestic spaces. These devices serve as the room-level interface in centralized heating and cooling systems, converting circulating hot or chilled water into tempered air delivered via integral fans. Water fan coils dominate installed stock across Northern Europe due to compatibility with low-temperature heat pump circuits, while smart thermostats represent the fastest-growing control layer as building codes mandate individual metering and zone optimization. Ceiling mounted installations retain share in premium renovations where floor space commands premium value, though modular systems are gaining traction in multi-unit residential construction.
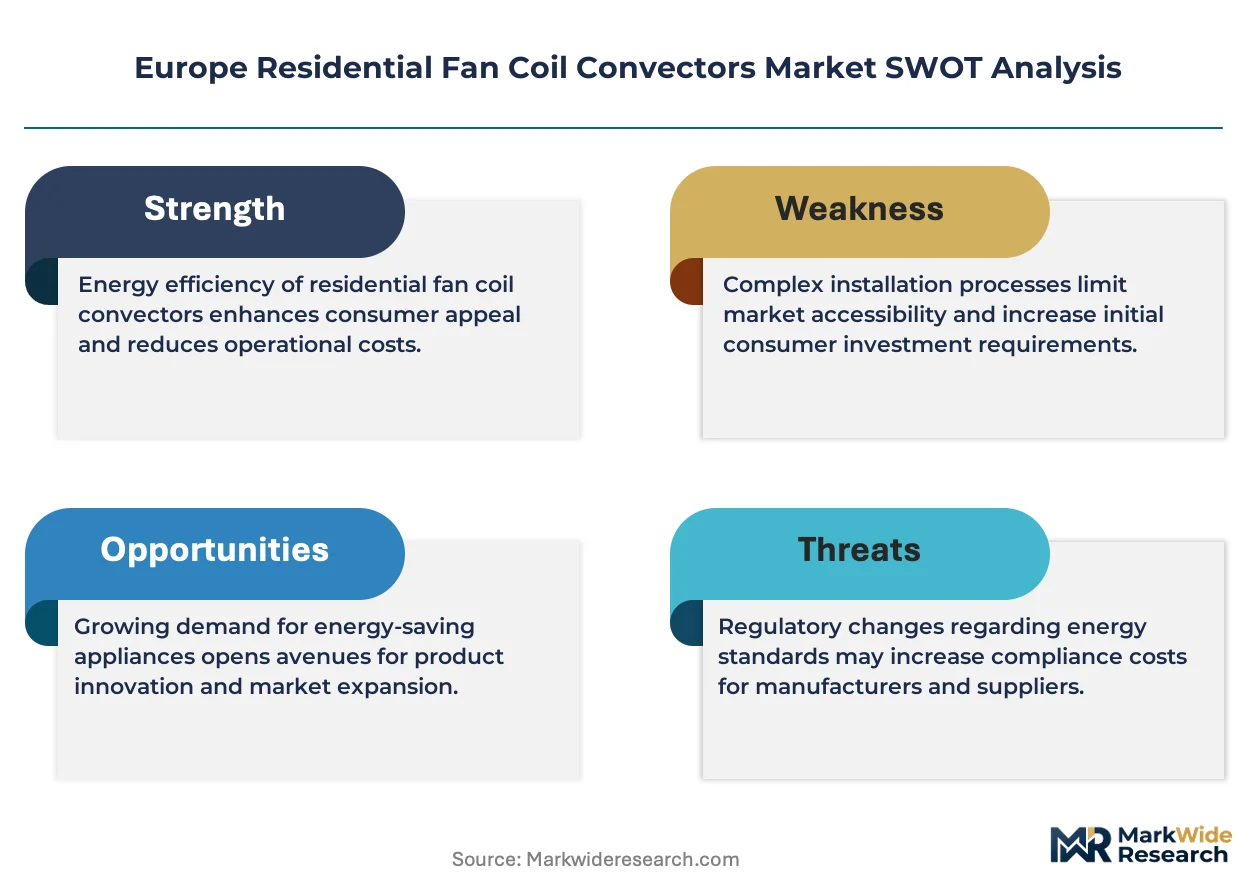
The EU Green Deal and F-Gas Regulation shape product development trajectories by mandating lower flow temperatures and refrigerant transitions that favor hydronic distribution architectures. Ecodesign requirements and CE marking protocols enforce minimum efficiency thresholds for residential heat emitters, tightening market access for non-compliant imports. Stakeholders must monitor national transpositions of the Energy Performance of Buildings Directive as these determine renovation obligations and subsidy eligibility for fan coil retrofits.
Market Dynamics
The EU Green Deal's building renovation targets are compressing replacement cycles for legacy heating terminals across European multi-family residential stock. Hydronic fan coil architectures compatible with low-temperature heat pump circuits are displacing conventional radiator systems as the dominant room-level interface.
Growth Catalysts
- EPBD Renovation Mandates:National transpositions of the Energy Performance of Buildings Directive create legally binding renovation obligations that accelerate fan coil retrofit specifications.
- Heat Pump Compatibility:Water fan coil systems integrate seamlessly with low-temperature heat pump circuits, enabling compliance with F-Gas Regulation phase-down requirements.
- Polish Multi-Family Construction:Central and Eastern European apartment complex development concentrates specification demand for modular hydronic terminal units.
Market Restraints
- Copper and Aluminum Volatility:Finned heat exchanger manufacturing faces input cost pressure from base metal price swings that compress OEM margins.
- Installer Capacity Bottlenecks:Qualified hydronic system technicians concentrate in Northern European markets, limiting deployment velocity in Southern and Eastern regions.
- Electric Panel Radiators:Plug-in electric alternatives substitute in single-zone retrofits where hydronic infrastructure proves cost-prohibitive.
Strategic Opportunities
- Romanian Residential Stock:Underpenetrated district heating connections in Bucharest and Cluj-Napoca create first-mover advantage for water fan coil retrofits.
- Smart Thermostat Convergence:Integration of IoT-enabled zone controls with fan coil units captures individual metering mandates under EU Green Deal implementation.
- Direct-to-Developer Platforms:Digital specification tools bypass traditional wholesaler channels, compressing procurement cycles for multi-unit residential projects.
Industry Challenges
- Hydronic Controls Expertise Gap:Commissioning engineers with heat pump-fan coil optimization skills remain scarce outside Nordic markets.
- CE Marking Documentation Burden:Ecodesign compliance testing timelines extend product launch schedules by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Residential Fan Coil Convectors Market |
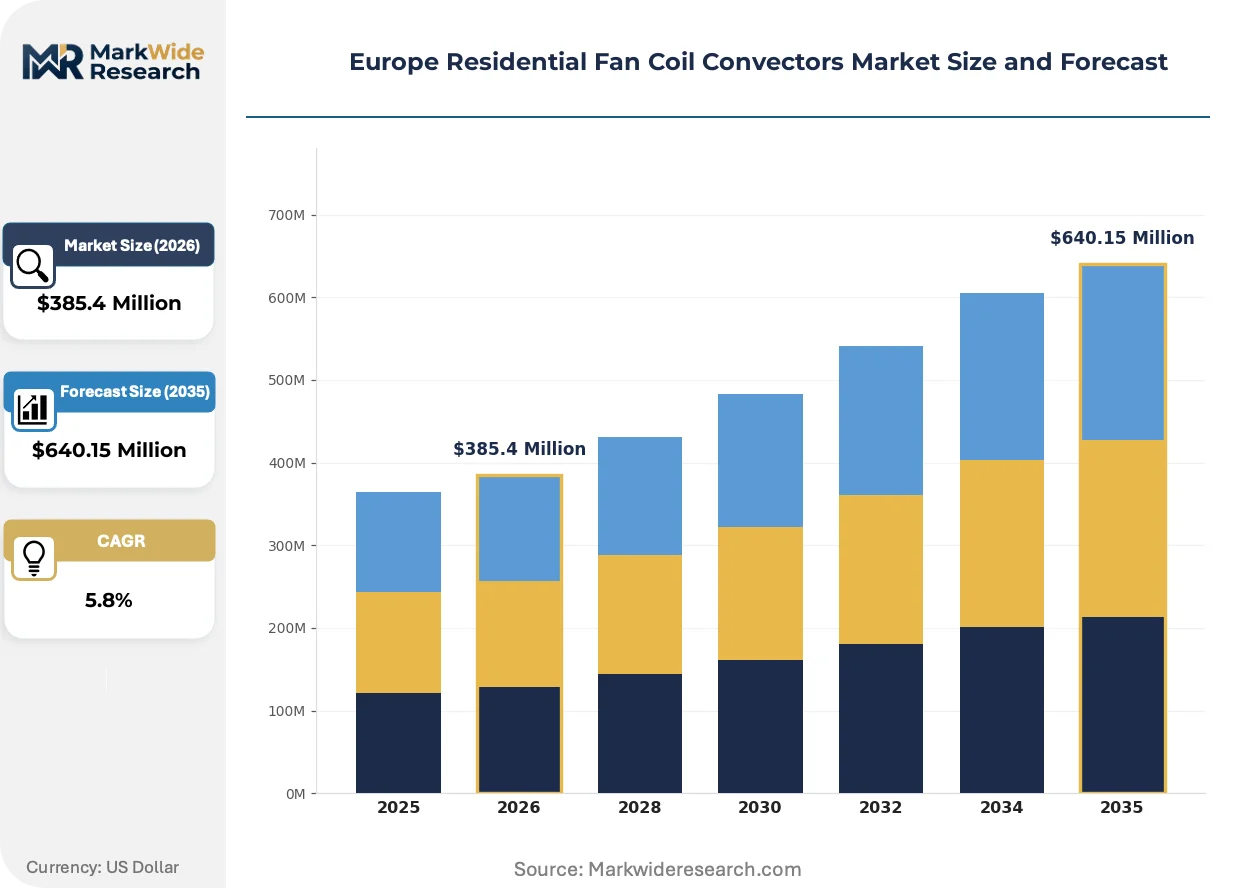
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Fan Coils, Electric Fan Coils, Multi-Purpose Coils, High Wall Units End User: Single-Family Homes, Apartment Complexes, Condominiums, Renovation Projects Installation Type: Floor Mounted, Ceiling Mounted, Wall Mounted, Modular Systems Control Technology: Manual Controls, Smart Thermostats, Wireless Systems, Centralized Control |
| Companies Covered | PURMO GROUP, Systemair AB, Daikin, VERANO EUROPE Sp. Z o.o., S & P Coil Products Limited, Smith's Environmental Products, Copperad, Dunham-Bush Limited, MINIB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Residential Fan Coil Convectors Market Shifts & Advancements
Product development trajectories center on thermal efficiency gains and digital integration layers. Manufacturers are repositioning terminal units as active nodes within building energy management architectures.
Microchannel heat exchanger technology is consolidating market share in premium fan coil segments. German and Austrian residential developers specify these compact aluminum cores for their superior heat transfer density and reduced water volume. The technology is consolidating specification standards around lower flow temperature operation that maximizes heat pump coefficient of performance.
F-Gas Regulation refrigerant phase-down schedules are accelerating hydronic distribution architecture adoption. The industrial consequence is terminal unit portfolio rebalancing away from direct-expansion systems. Multi-family residential projects in France and Belgium face the strongest compliance pressure, driving specification shifts toward water-based fan coils.
Developer procurement teams are consolidating vendor relationships around full-system accountability. Traditional component sourcing through fragmented wholesaler networks yields to direct OEM partnerships with integrated design support. This pattern concentrates in Netherlands and Danish multi-unit construction where design-build contracts dominate project delivery.
Europe Residential Fan Coil Convectors Market Segmentation
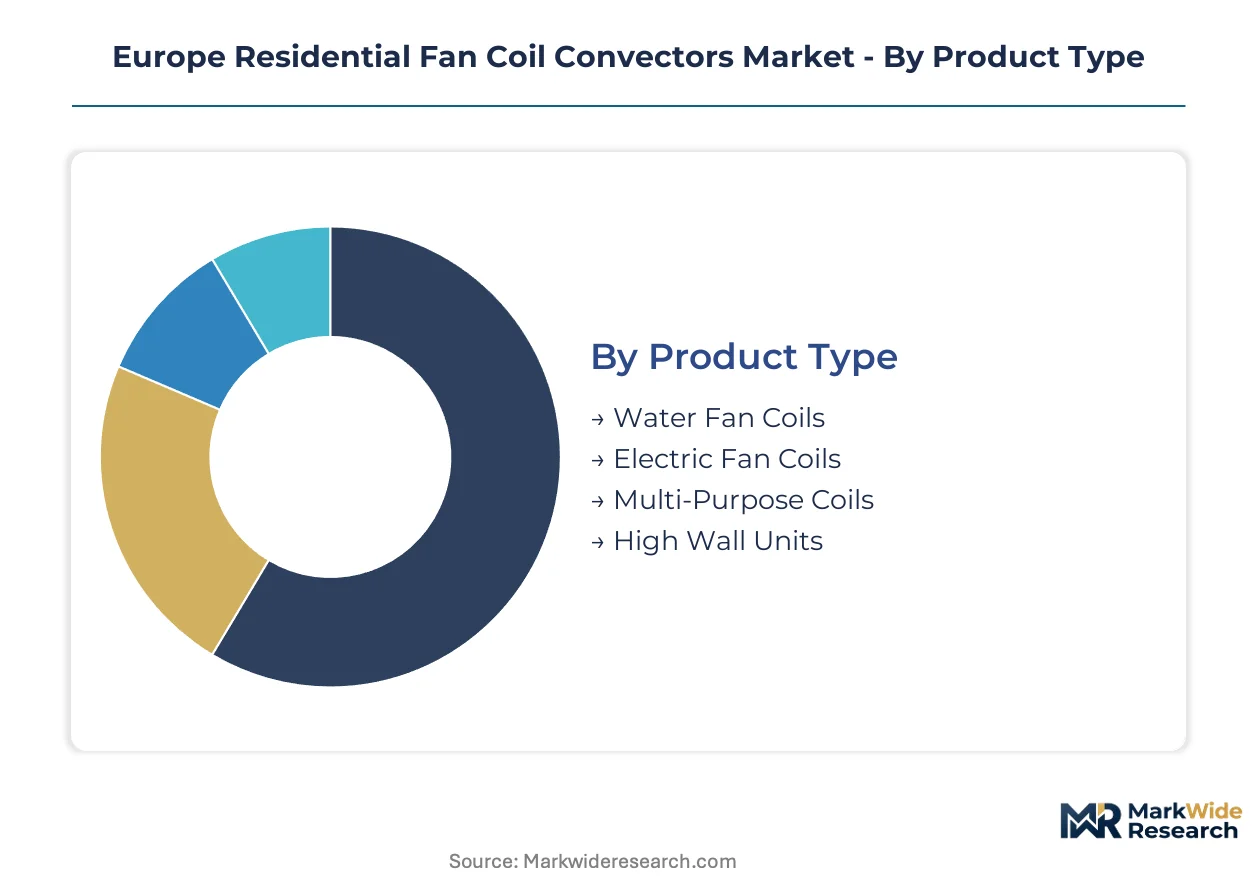
Segmentation in the Europe Residential Fan Coil Convectors Market reveals how capital deployment, regulatory compliance, and installation logistics intersect to shape procurement decisions. Developers and contractors select configurations based on heat pump compatibility, renovation constraints, and smart building mandates rather than thermal output alone.
Product Type:
Capital intensity varies sharply across product architectures, with water-based systems demanding higher upfront investment in hydronic infrastructure but delivering superior lifecycle economics under EU Green Deal efficiency standards.
- Water Fan Coils:Hydronic terminal units circulate low-temperature water through aluminum or copper finned coils, achieving optimal coefficient of performance when paired with air-source heat pumps. German and Polish multi-family developers specify these systems to comply with F-Gas Regulation phase-down requirements and secure national renovation subsidies. Demand concentrates in new apartment construction across Central Europe where district heating interconnections exist.
- Electric Fan Coils:Resistance-heated or direct-expansion electric units eliminate hydronic infrastructure requirements, reducing installed cost by 40-60% in single-zone retrofits. French and Italian renovation contractors deploy these where existing radiator piping cannot accommodate fan coil flow rates. Market share is compressing as electricity price volatility and carbon intensity regulations tilt specifications toward water-based alternatives.
- Multi-Purpose Coils:Reversible heat pump terminal units switch between heating and cooling modes through four-way valve configurations.
- High Wall Units:Vertical-mounted fan coils integrate decorative enclosures with concealed duct connections for premium residential finishes.
Most installed capacity flows through Water Fan Coils. Expansion is steepest in Multi-Purpose Coils.
End User:
Customer archetypes diverge by procurement scale, with institutional buyers commanding volume discounts and standardized specifications that reshape manufacturer portfolio priorities.
- Apartment Complexes:Multi-unit residential developers in Warsaw, Berlin, and Bucharest specify modular fan coil systems through design-build contracts that bundle terminal units with centralized heat pump plants. These projects drive 60-70% of annual volume in Central and Eastern European markets. EU Green Deal renovation mandates accelerate replacement cycles in post-socialist housing stock.
- Renovation Projects:Retrofit specifications dominate Western European demand as Energy Performance of Buildings Directive transpositions impose legally binding efficiency upgrades. Dutch and Belgian contractors prioritize compact ceiling-mounted units where floor space preservation commands premium value. Subsidy eligibility hinges on individual metering capability, favoring smart thermostat integration.
- Single-Family Homes:Detached housing specifications concentrate in Nordic markets with deep heat pump penetration.
- Condominiums:Owner-association procurement in Southern Europe favors decentralized electric units where split incentives complicate shared infrastructure investment.
Apartment Complexes absorb the greatest absolute volume. Renovation Projects are climbing the fastest as regulatory deadlines approach.
Installation Type:
Mounting configurations reflect spatial economics and labor availability, with premium renovations accepting higher material costs to recover usable floor area.
- Ceiling Mounted:Recessed or surface-mounted units suspend heat exchangers above occupied zones, preserving wall and floor space in high-value urban apartments. Austrian and Swiss developers specify these for luxury multi-family projects where square-meter economics justify 15-25% equipment premiums. Installation requires coordination with suspended ceiling trades, concentrating demand in markets with established MEP contractor ecosystems.
- Floor Mounted:Skirting-level or console units replace conventional radiators without structural modification, minimizing retrofit disruption. Polish and Romanian renovation contractors favor these for district heating conversions where existing piping routes accommodate low-temperature operation. The configuration dominates replacement demand in Central European markets with aging radiator infrastructure.
- Wall Mounted:Vertical chassis units mount at mid-height for targeted air distribution in compact dwellings.
- Modular Systems:Pre-engineered terminal unit arrays factory-commissioned for rapid multi-unit deployment.
Floor Mounted retains the largest installed base. Ceiling Mounted is gaining share fastest in premium construction segments.
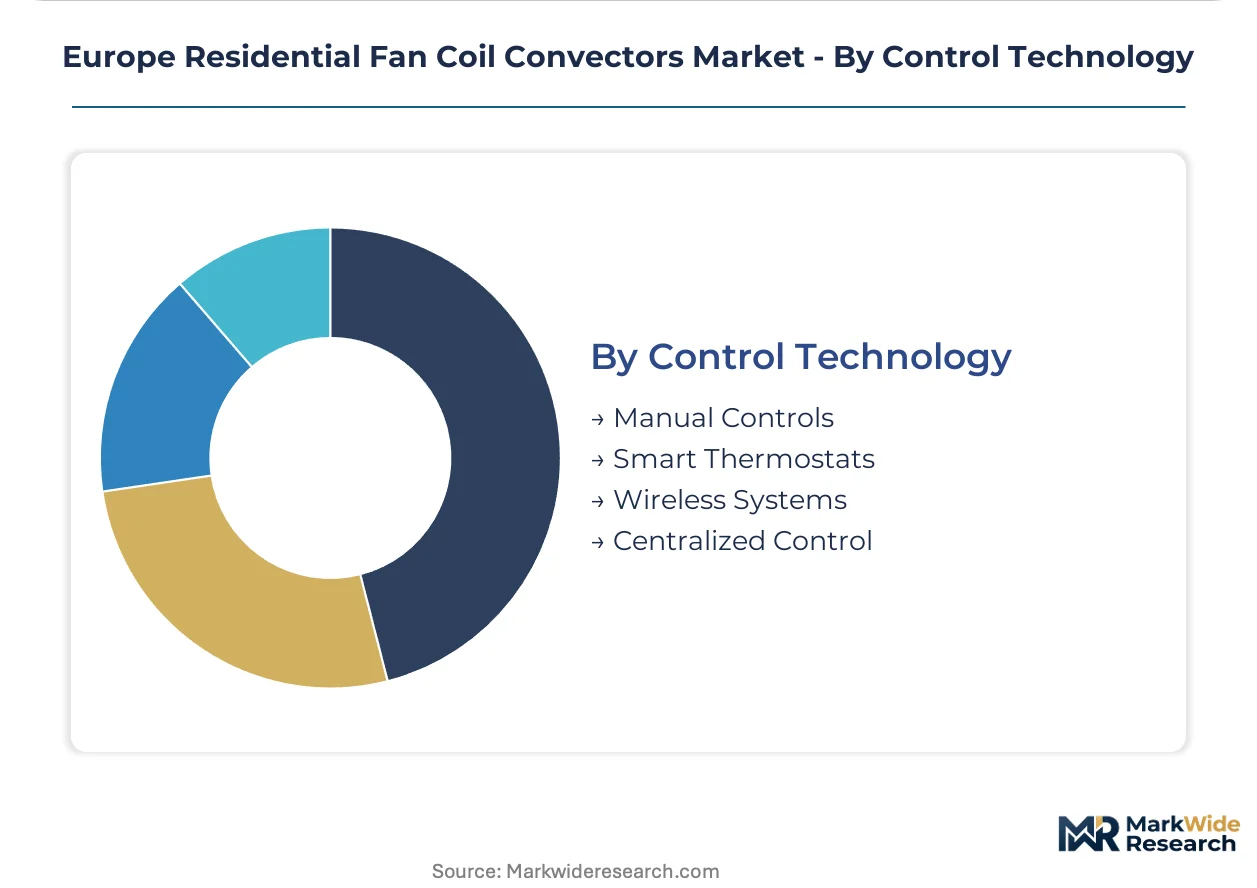
Control Technology:
Regulatory metering mandates and heat pump optimization requirements are elevating control layer sophistication from aftermarket accessory to specified system component.
- Smart Thermostats:IoT-enabled zone controllers with occupancy sensing and predictive algorithms maximize heat pump efficiency while satisfying individual metering requirements under EU Green Deal implementation. Dutch and Danish building codes now mandate connected controls for subsidy eligibility, concentrating specification demand in Northern European markets. Manufacturers are embedding Modbus and BACnet interfaces to integrate with building energy management architectures.
- Manual Controls:Basic dial or slider thermostats persist in cost-sensitive retrofits and social housing projects where digital literacy or maintenance capacity constraints apply. Spanish and Portuguese installers specify these for elderly-occupant renovations where technology complexity creates adoption barriers. Market share is eroding as national transpositions of the Energy Performance of Buildings Directive tighten minimum control requirements.
- Wireless Systems:Battery-powered or energy-harvesting sensors eliminate control wiring in renovation applications.
- Centralized Control:BMS-integrated zone optimization for large multi-unit developments with on-site facility management.
Manual Controls still equip the majority of legacy stock. Smart Thermostats are expanding most quickly as compliance deadlines activate replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for residential fan coil convectors is migrating toward jurisdictions with streamlined CE marking pathways and proximity to heat pump assembly clusters. The EU Green Deal's uneven national transpositions create regulatory arbitrage opportunities for producers locating in member states with faster building permit regimes.
Germany
Multi-family developers in Berlin and Munich specify water fan coils for low-temperature heat pump compatibility. The Federal Building Energy Act mandates individual metering for new residential units, accelerating smart thermostat integration. Bavarian HVAC contractors dominate installation capacity for ceiling-mounted systems in premium apartment construction.
Poland
Warsaw and Kraków apartment complex development drives modular hydronic terminal unit demand. National transpositions of the Energy Performance of Buildings Directive impose renovation obligations on post-socialist housing stock. Silesian manufacturing clusters supply floor-mounted units for district heating conversions across Central Europe.
Netherlands
Rotterdam and Amsterdam renovation contractors prioritize compact ceiling-mounted units where floor space economics justify equipment premiums. Dutch building codes mandate connected controls for national subsidy eligibility. Randstad design-build firms consolidate vendor relationships around full-system accountability.
France
Paris and Lyon multi-family projects face acute F-Gas Regulation compliance pressure, displacing direct-expansion systems. The RE2020 environmental regulation tightens thermal performance requirements for new residential construction. Auvergne-Rhône-Alpes industrial zones host aluminum heat exchanger fabrication for premium fan coil segments.
Romania
Bucharest and Cluj-Napoca district heating networks create first-mover retrofit opportunities for water fan coil specifications. EU cohesion funds finance building envelope improvements that enable low-temperature hydronic operation. Romanian installer capacity constraints limit deployment velocity despite subsidy availability.
Europe Residential Fan Coil Convectors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart control integration and heat pump optimization services. The vendor base stratifies between pan-European distribution networks and regional fabrication specialists. Three archetypes dominate: integrated climate system providers, component-agnostic terminal unit manufacturers, and controls-software hybrids. Competitive moves center on backward integration into aluminum heat exchanger production and direct-to-developer digital specification platforms.
Among Nordic and Continental European producers, PURMO GROUP, Systemair AB, and Daikin occupy distinct positioning vectors. PURMO GROUP leverages its pan-European distribution infrastructure to anchor presence across standardized hydronic terminal segments. Systemair AB exemplifies the specialized air handling archetype with concentrated expertise in ventilation-integrated climate solutions. Daikin represents the integrated system tier, where climate equipment portfolios span generation, distribution, and terminal components.
| Leading Market Players |
|---|
| PURMO GROUP |
| Systemair AB |
| Daikin |
| VERANO EUROPE Sp. Z o.o. |
| S & P Coil Products Limited |
| Smith's Environmental Products |
| Copperad |
| Dunham-Bush Limited |
| MINIB |
| Others |
Supply & Pricing Matrix
Aluminum and copper coil stock feed into three pricing tiers that stratify across premium microchannel systems, standard finned-tube units, and economy electric alternatives. German OEMs command premium positioning through captive heat exchanger fabrication, while Polish assemblers compete on volume throughput for Central European apartment developers.
Pricing Analysis
Distributor margins compress procurement costs for multi-unit residential developers who qualify for volume rebates on modular water fan coil specifications. Pricing stratifies across premium, standard, and economy tiers based on heat transfer density ratings and CE marking documentation completeness. Cost compression in standard-tier segments intensifies as Romanian and Bulgarian fabricators enter with simplified control architectures. Renovation contractors in France and Italy exhibit highest price sensitivity due to subsidy-dependent project economics, while Dutch design-build firms accept equipment premiums for integrated smart thermostat bundling.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Warsaw and Berlin apartment developers who specify terminal units through consolidated procurement platforms. Manufacturing gravity centers on Germany, Poland, and Romania where aluminum extrusion and coil winding capabilities cluster near heat pump assembly plants. Finned heat exchanger production draws from copper tube mills in Saxony and aluminum coil suppliers in Silesia. Single-source vulnerability concentrates in microchannel aluminum core fabrication where Austrian and German specialists control premium-tier supply. Distribution runs through pan-European HVAC wholesalers with regional stocking points in Rotterdam and Vienna.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Residential Fan Coil Convectors Market compounds steadily as EU Green Deal renovation mandates create replacement demand with regulatory certainty. Hydronic system specifications tied to heat pump deployment ensure durable volume visibility across multi-family construction and retrofit cycles.
For Market Incumbents: Extend backward integration into aluminum microchannel core production to defend margin position against emerging Polish and Romanian assemblers. Consolidate specification relationships with Dutch and Danish design-build firms through embedded engineering support. Capture smart thermostat integration layer to differentiate from component-agnostic terminal unit competitors. For New Entrants and Emerging Players: Begin with underpenetrated Romanian district heating retrofit corridors where installer capacity constraints delay incumbent deployment velocity. Target Bucharest and Cluj-Napoca housing associations with simplified floor-mounted water fan coil packages bundled with basic digital controls. Pursue direct-to-developer digital specification platforms that bypass traditional wholesaler markups in Polish multi-family construction. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale fabricators lack CE marking expertise and smart control integration capabilities. The market supports long-term compounder framing given regulatory-driven replacement cycles and heat pump compatibility requirements. Target acquisition candidates with established aluminum heat exchanger production and dormant distribution relationships in Southern Europe. Monitor national transpositions of the Energy Performance of Buildings Directive as inflection signals for renovation subsidy activation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microchannel Core Production | German OEMs secure captive supply of high-density aluminum heat exchangers for premium fan coil specifications. |
| Smart Thermostat Platform Integration | Dutch building codes mandate connected controls, elevating zone optimization software to specified system component status. |
| Direct-to-Developer Digital Specification Tools | Polish and Romanian multi-unit projects compress procurement cycles through bypassed wholesaler channels. |
| CE Marking and Ecodesign Compliance Investment | Extended product launch timelines reward early regulatory preparation against non-compliant import competition. |
| Geographic Capacity Expansion in Romania | Proximity to Bucharest district heating networks captures EU cohesion fund-financed retrofit demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and growth trajectory validation. Primary fieldwork engaged HVAC equipment procurement directors at multi-family developers, technical specification leads at design-build firms, hydronic system installers, and controls engineering specialists across Germany, Poland, Netherlands, France, and Romania. Secondary validation drew from EU Ecodesign regulatory filings, national building permit databases, heat pump shipment statistics, and CE marking notification body records. Bottom-up unit volume estimates and top-down value reconstructions were cross-referenced to anchor forecast confidence intervals.
Segment-weighting approaches distributed total market value across product type, end user, installation configuration, and control technology dimensions. CAGRs were derived from regression-adjusted trend extrapolation incorporating regulatory deadline phasing and heat pump deployment correlations across the projection horizon. Modeling incorporated F-Gas Regulation phase-down schedules, national EPBD transposition timelines, and aluminum-copper price elasticity assumptions specific to finned heat exchanger manufacturing.
Several conditions sit outside the modeled scope, including abrupt commodity price spikes beyond historical volatility bands, trade policy disruptions affecting aluminum coil supply, and technological substitution by radiant panel systems. Forecasts reflect documented assumptions about renovation subsidy continuity and heat pump adoption curves. Periodic stress-testing of base assumptions is recommended given installer capacity bottlenecks and CE marking documentation burden variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
Welded Spiral Heat Exchangers Market