
 US Commercial Water Heater Market | 2026-2036
US Commercial Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial Water Heater Market Analysis
Stainless steel is decoupling commercial water heater tank economics from traditional glass-lined carbon steel cost structures, extending product lifecycles and reducing replacement frequency in high-use environments. Rheem Manufacturing Company leverages its vertically integrated distribution network to sustain national coverage across contractor and wholesale channels. Bradford White Corporation anchors its competitive position through exclusive professional-installer channel control, limiting big-box retail exposure. A.O. Smith competes on manufacturing scale, operating multiple North American production facilities that support rapid fulfillment for large commercial projects.
A commercial water heater is a thermally insulated vessel or instantaneous heating apparatus engineered to raise and maintain water temperature between 120°F and 180°F for non-residential applications such as food service, lodging, manufacturing, and institutional sanitation. Units incorporate pressure relief valves, anode rods or coil-based heat exchangers, and combustion or electric resistance elements sized to continuous-duty cycles exceeding residential standards. Tankless water heaters command expanding share in retrofit-constrained mechanical rooms where floor space carries premium value. Heat pump water heaters represent the fastest-growing technology segment, though gas-fired systems still dominate installed base across colder climate zones. Electric resistance storage maintains maturity in regions with low natural gas penetration, particularly the Pacific Northwest and parts of the Northeast.
The Department of Energy's conservation standards under 10 CFR Part 431 mandate minimum thermal efficiency and standby loss thresholds that manufacturers must meet for federal compliance certification. EPA Energy Star specifications create a voluntary tier that influences procurement decisions by chain hospitality operators and institutional buyers seeking operational cost reduction. State-level regulations, including California's Title 24 Building Energy Efficiency Standards and Texas municipal utility rebate programs, further fragment compliance requirements across jurisdictions. Stakeholders must monitor evolving federal rulemakings and state incentive structures to align product development and inventory positioning with shifting compliance economics.
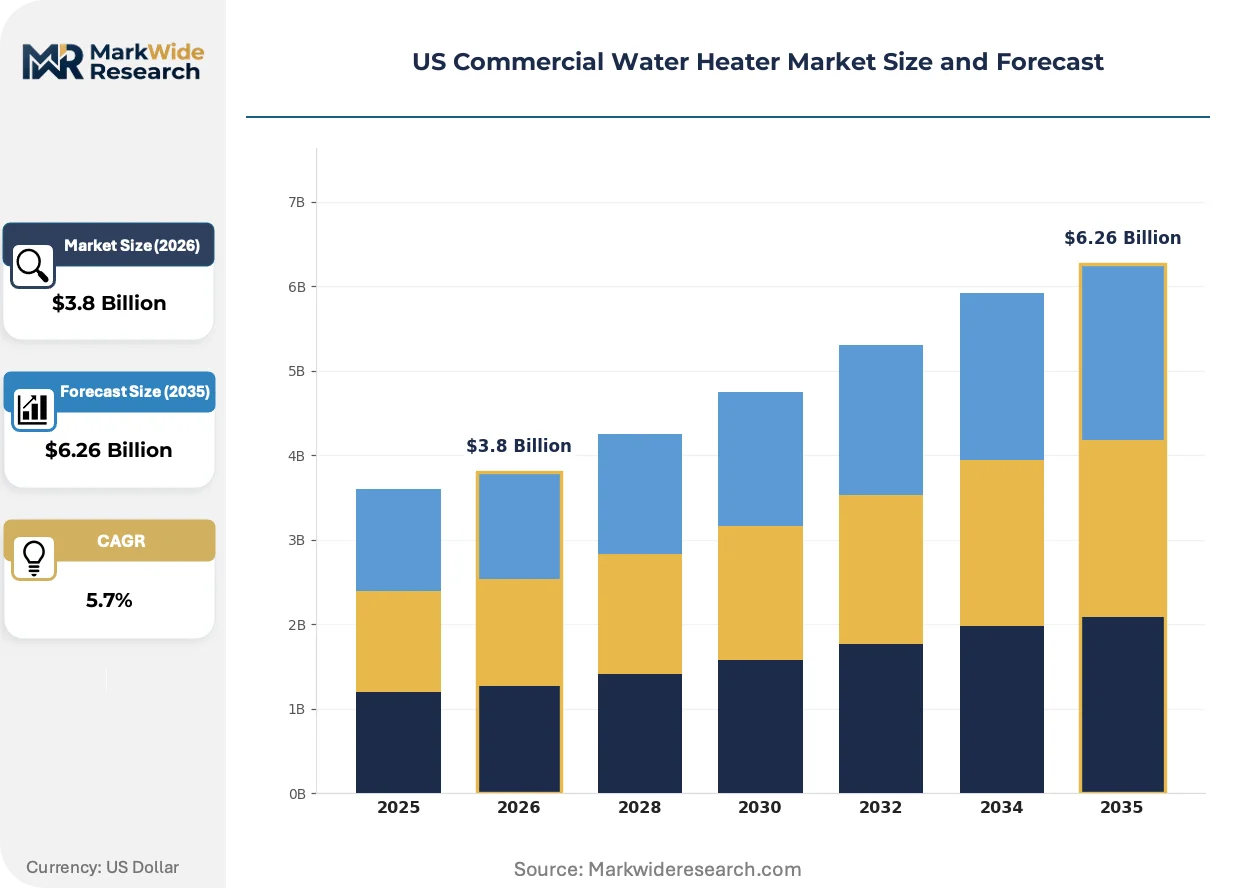
Market Dynamics
The US commercial water heater market is undergoing a technology turnover cycle driven by the Department of Energy's amended conservation standards under 10 CFR Part 431, which mandate higher thermal efficiency thresholds and accelerate replacement of legacy equipment across food service, lodging, and institutional facilities.
Growth Catalysts
- Hospitality Energy Cost Pressure:Hotel and restaurant operators are prioritizing heat pump and tankless installations to reduce operational energy spend. California and Texas building codes favor advanced systems in new construction pipelines.
- Federal Efficiency Mandates:DOE conservation standards under 10 CFR Part 431 compel equipment upgrades. Manufacturers must certify compliance, creating replacement demand across installed base.
- Stainless Steel Tank Adoption:Extended lifecycle economics from corrosion-resistant materials reduce replacement frequency in high-use environments. Food service and healthcare facilities lead conversion.
Market Restraints
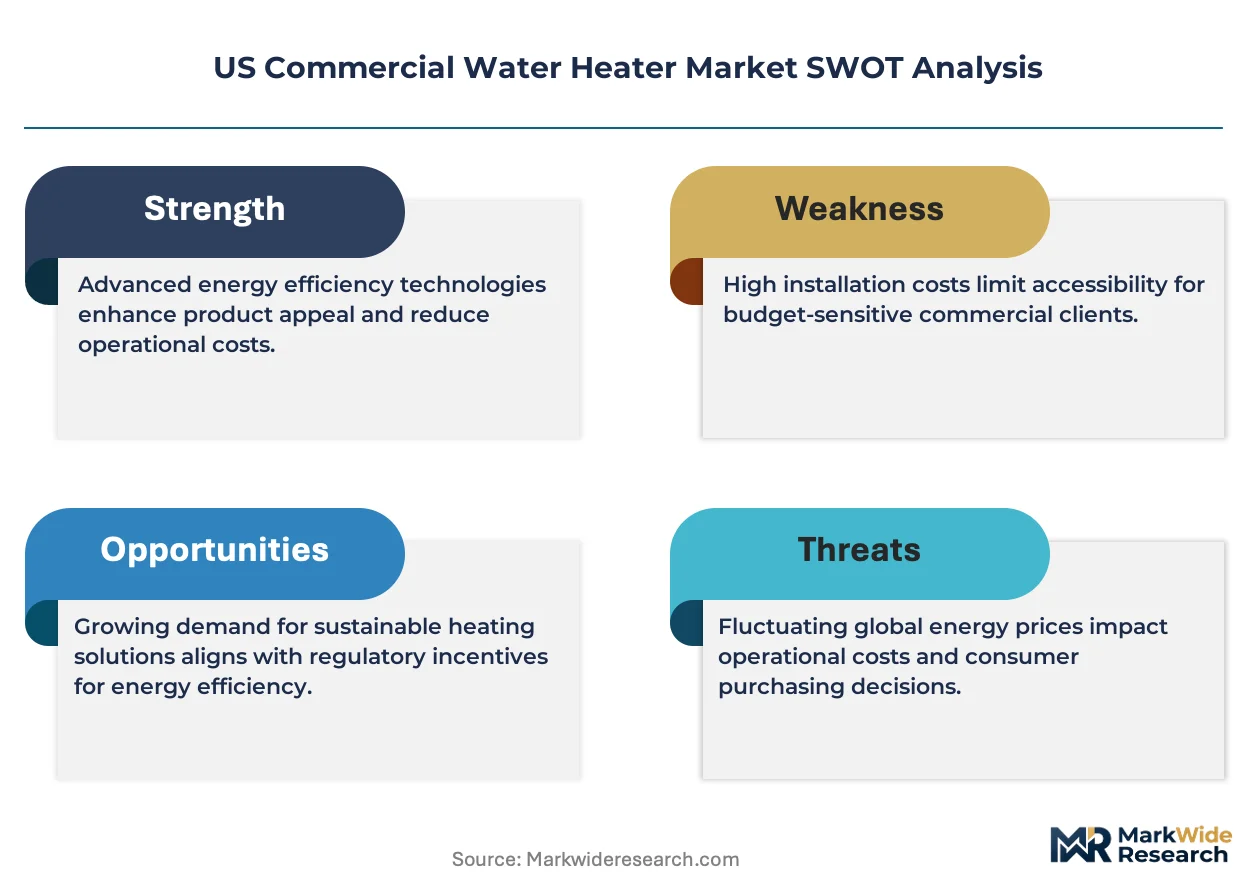
- Copper and Steel Input Volatility:Raw material price swings compress manufacturing margins. Carbon steel and copper coil costs fluctuate with commodity markets, pressuring cost structures.
- Gas Infrastructure Lock-In:Colder climate zones maintain gas-fired dominance due to heat pump performance limitations below 40°F. Electrification faces technical and infrastructure barriers in northern states.
- Professional Installer Channel Control:Bradford White and regional distributors restrict big-box retail access. End-users face limited self-install options and higher labor dependency.
Strategic Opportunities
- Texas Municipal Rebate Programs:Utility incentive structures accelerate heat pump adoption in commercial new construction. Dallas-Fort Worth and Houston metro areas show concentrated project activity.
- Retrofit-Constrained Mechanical Rooms:Tankless systems capture share where floor space carries premium value. Urban hospitality and healthcare facilities prioritize compact footprint solutions.
- California Title 24 Standards:Building energy efficiency mandates drive specification of high-performance equipment. Los Angeles and San Francisco commercial construction pipelines favor compliant systems.
Industry Challenges
- Heat Pump Technician Shortage:Refrigeration-cycle expertise lags equipment deployment. HVAC contractors face training gaps for commercial-scale heat pump water heater installation and service.
- Legacy Control Integration:Building management system compatibility issues delay upgrades. Facilities with older BACnet or proprietary protocols encounter commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial Water Heater Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Water Heaters, Tankless Water Heaters, Heat Pump Water Heaters, Solar Water Heaters Technology: Electric, Gas, Solar, Hybrid End User: Hospitality, Retail, Industrial, Educational Institutions Installation: Indoor, Outdoor, Wall-Mounted, Standalone |
| Companies Covered | A.O. Smith, Bradford White Corporation, Rheem Manufacturing Company, Rinnai America Corporation, GE Appliances, Hubbell Water Heaters, Noritz America Corporation, Navien Inc., Bosch Thermotechnology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial Water Heater Market Emerging Trajectories
Equipment architecture is shifting from monolithic tank systems toward configurable thermal platforms that adapt to space constraints and load profiles. Three developments are restructuring product development priorities and channel economics.
Heat pump water heater technology is modularizing commercial system design. Food service chains and multi-family developers are specifying scalable rack configurations rather than single large tanks. This architecture compresses mechanical room footprints and enables phased capacity expansion without full system replacement.
EPA Energy Star specifications are tightening procurement criteria for institutional buyers. Chain hospitality operators now require third-party certification for equipment standardization. California Title 24 and Texas utility rebate programs amplify this specification pressure, redirecting manufacturer R&D toward efficiency benchmarking.
Service contract unbundling is fragmenting traditional distributor relationships. Large multi-site operators are negotiating direct parts-and-labor agreements with national service networks. Texas and California healthcare systems lead this procurement model change, bypassing wholesale channel markups for predictive maintenance coverage.
US Commercial Water Heater Market Segmentation
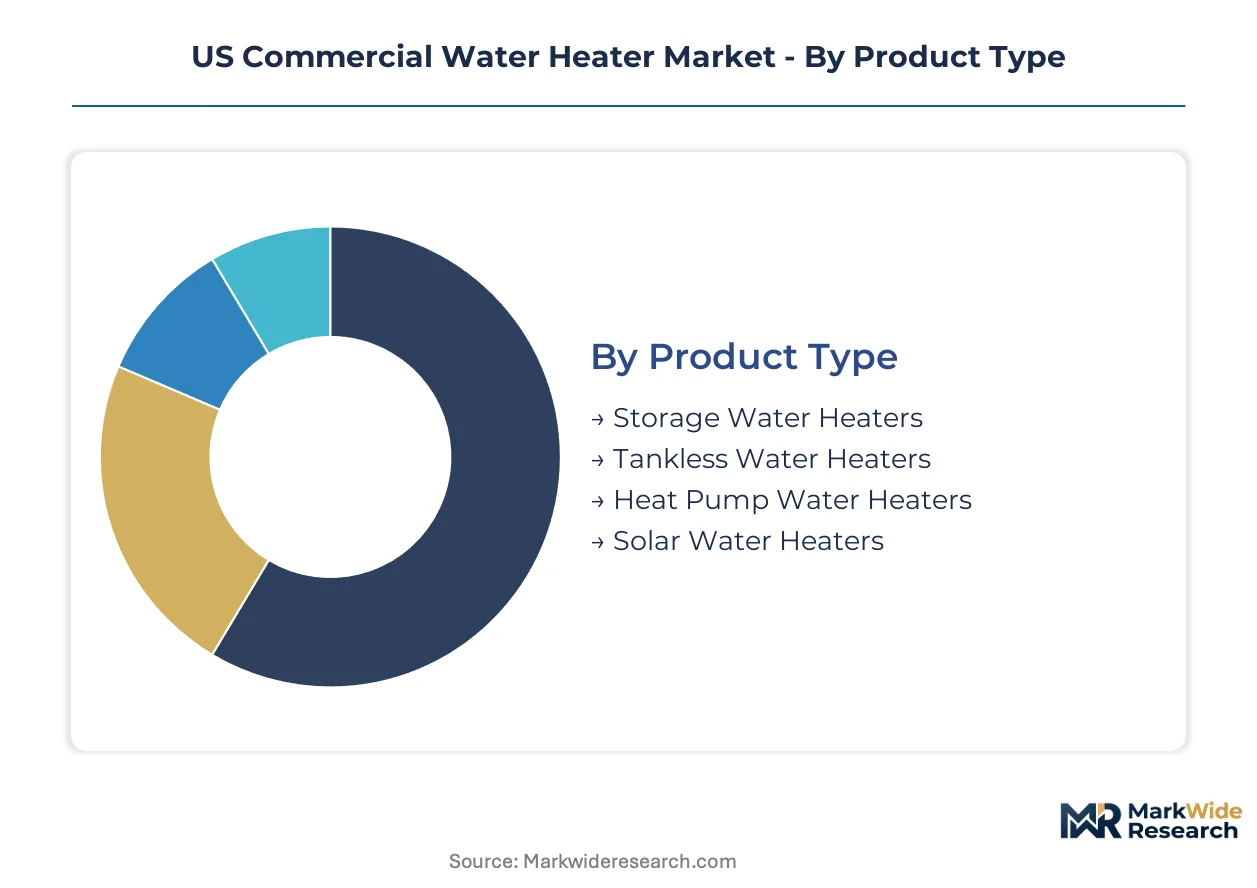
Equipment specification patterns in the US commercial water heater market diverge sharply across building types and climate zones. Procurement decisions hinge on thermal load profiles, fuel availability, and compliance with state-level efficiency mandates.
Product Type:
Upgrade cycles accelerate where legacy equipment fails to meet amended DOE conservation standards under 10 CFR Part 431.
- Storage Water Heaters:Glass-lined carbon steel and stainless steel vessels dominate food service and healthcare facilities requiring 80+ gallon capacities. California Title 24 compliance drives specification toward higher insulation values and reduced standby losses in new construction.
- Tankless Water Heaters:Gas-fired and electric instantaneous systems capture mechanical room retrofits where floor space commands premium value. Urban hospitality properties in Texas and California prioritize compact footprints for high-turnover guest laundry and kitchen operations.
- Heat Pump Water Heaters:Refrigeration-cycle systems are expanding most quickly in regions with mild winter temperatures and utility rebate support.
- Solar Water Heaters:Thermal collector systems serve niche applications in southwestern states with high insolation and municipal incentive structures.
Volume placements concentrate in Storage Water Heaters; the faster expansion belongs to Heat Pump Water Heaters.
Technology:
Cost tier differentiation separates premium heat pump and hybrid systems from standard gas-fired equipment.
- Electric:Resistance-element and heat pump configurations serve Pacific Northwest and Northeast markets with limited natural gas infrastructure. Oregon and Washington building codes favor electric systems for carbon reduction compliance.
- Gas:Condensing and standard-efficiency combustion systems retain dominance in northern climate zones where heat pump coefficient of performance degrades below 40°F ambient. Midwest and Mountain West hospitality operators specify gas for reliability in extreme cold events.
- Solar:Evacuated tube and flat-plate collectors address institutional sustainability mandates in California and Arizona.
- Hybrid:Combined heat pump and resistance-element architectures optimize operating cost across variable load conditions.
Gas technology retains the largest installed base; hybrid systems are climbing the fastest in new construction specifications.
End User:
Application-specific load patterns determine capacity sizing and redundancy requirements.
- Hospitality:Hotels and resorts require 24/7 hot water availability with N+1 redundancy for guest satisfaction. Texas and Florida resort properties favor tankless configurations for space-constrained mechanical rooms.
- Retail:Quick-service restaurants and grocery chains prioritize rapid recovery rates for sanitation compliance. California food service operators face Title 24 mandates driving heat pump adoption in new builds.
- Industrial:Manufacturing facilities specify heavy-duty storage systems for process water and washdown applications.
- Educational Institutions:K-12 and university facilities balance capital constraints against long-term operating cost reduction through efficiency upgrades.
Hospitality generates the highest unit volume; educational institutions are gaining share fastest through federal infrastructure funding deployment.
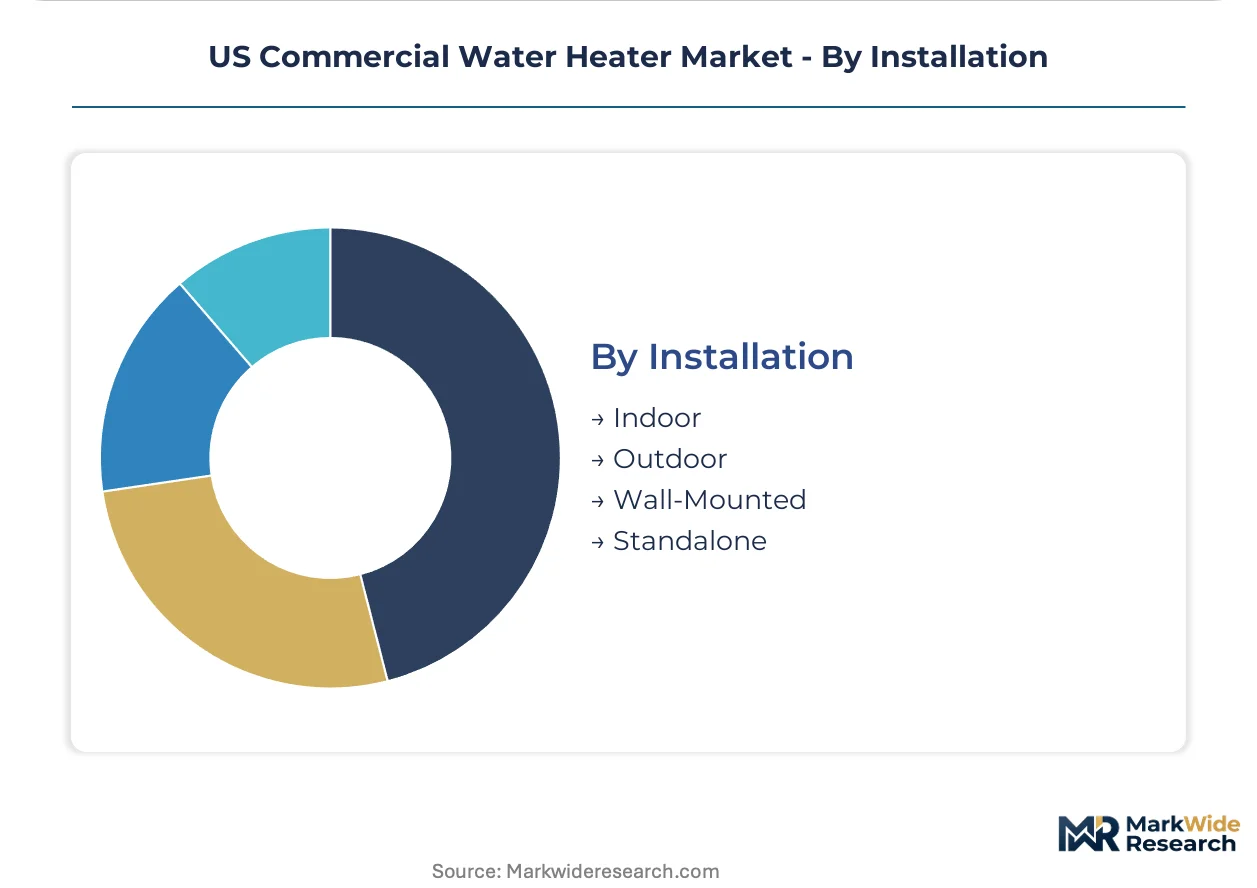
Installation:
Customer type and site constraints dictate mounting configurations and weatherization requirements.
- Indoor:Climate-controlled mechanical rooms protect combustion and electric systems from temperature extremes. Northeast and Midwest facilities specify indoor installation for freeze protection.
- Outdoor:Weather-rated enclosures serve southern states where ambient temperatures rarely threaten equipment operation. Texas and Arizona commercial properties favor outdoor mounting to reclaim interior square footage.
- Wall-Mounted:Tankless systems in vertical configurations address severe space constraints in urban hospitality and healthcare renovations.
- Standalone:Ground-mounted storage tanks with integral enclosures suit suburban and exurban sites with available pad space.
Indoor installation commands the majority of placements; wall-mounted configurations are expanding fastest in dense urban retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial water heater demand concentrates in states with stringent building codes and large hospitality construction pipelines. California and Texas together account for disproportionate specification volume driven by Title 24 mandates and municipal rebate programs.
California
Title 24 Building Energy Efficiency Standards mandate high-performance water heating in new commercial construction. Los Angeles and San Francisco metro areas lead specification of heat pump and tankless systems for hospitality and healthcare projects. The California Energy Commission updates compliance thresholds every three years, accelerating technology turnover.
Texas
Dallas-Fort Worth and Houston municipal utilities offer rebate structures that favor heat pump adoption in commercial new builds. Natural gas infrastructure remains dense, though electrification gains traction in urban core developments. State energy codes lag California stringency, but utility incentives drive advanced equipment specification.
Florida
Resort properties in Orlando and Miami-Dade prioritize tankless configurations for space-constrained mechanical rooms. High ambient temperatures year-round favor heat pump coefficient of performance. The Florida Building Code addresses hurricane resilience requirements for outdoor equipment mounting.
New York
New York City Local Law 97 carbon reduction mandates pressure commercial building electrification. Upstate facilities face heat pump performance limitations during winter extremes, preserving gas-fired storage dominance. The New York State Energy Research and Development Authority administers commercial efficiency incentive programs.
Illinois
Chicago hospitality and healthcare operators specify heavy-duty storage systems for reliability in sub-zero conditions. The Midwest climate limits heat pump deployment, sustaining condensing gas technology share. Commonwealth Edison utility programs support efficiency upgrades in institutional facilities.
US Commercial Water Heater Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with professional-installer channel control creating distinct competitive moats. The market structure consolidates around three vertically integrated national suppliers and a tier of regional specialists serving niche applications. Strategic archetypes include full-line manufacturers with captive distribution, tank-material specialists leveraging stainless steel lifecycle economics, and tankless-focused innovators capturing retrofit-constrained urban projects. Dominant competitive moves center on exclusive channel partnerships with mechanical contractors and backward integration into heat exchanger coil production.
Among the established national suppliers, Rheem Manufacturing Company, Bradford White Corporation, and A.O. Smith occupy positions that exemplify distinct strategic vectors. Rheem represents the vertically integrated archetype with broad distribution reach. Bradford White exemplifies professional-channel exclusivity, limiting big-box retail exposure. A.O. Smith anchors the manufacturing-scale position with multi-facility North American production footprint. These three companies collectively shape specification standards and pricing benchmarks across hospitality, healthcare, and institutional end-use segments.
| Leading Market Players |
|---|
| A.O. Smith |
| Bradford White Corporation |
| Rheem Manufacturing Company |
| Rinnai America Corporation |
| GE Appliances |
| Hubbell Water Heaters |
| Noritz America Corporation |
| Navien Inc. |
| Bosch Thermotechnology |
| Others |
Supply Flow & Price Mechanics
Heat pump water heater technology transitions are simultaneously compressing manufacturing cost curves and redistributing supplier power toward refrigeration-cycle component specialists. Stainless steel tank adoption redraws procurement economics by extending replacement intervals and shifting buyer total-cost-of-ownership calculations away from upfront price sensitivity.
Pricing Analysis
Volume placements concentrate in standard-efficiency gas storage systems where thin margins reward manufacturing scale, while premium pricing accrues to heat pump and hybrid configurations certified under EPA Energy Star specifications. Price differentiation hinges on thermal efficiency tier and professional-installer channel bundling, with California Title 24 compliance commanding specification premiums. Pricing pressure stems from copper and carbon steel commodity volatility that compresses margins across mid-tier equipment. Small independent contractors exhibit highest price sensitivity; chain hospitality operators prioritize lifecycle operating cost over capital outlay.
Supply Chain Analysis
Professional-installer and wholesale distributor channels handle national coverage for incumbent manufacturers, while direct-to-large-operator service contracts are fragmenting traditional markups. Manufacturing concentration rests on domestic North American production facilities for finished equipment, with compressor and heat exchanger coil supply anchored in Mexico and selected Asian manufacturing hubs. Raw material dependencies center on carbon steel sheet, copper tubing, and refrigerant gases subject to phasedown regulations. Supply chain risk centers on single-source compressor availability for commercial-scale heat pump systems. Distribution runs through exclusive mechanical contractor relationships that limit retail channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with captive control over heat exchanger coil production and refrigeration-cycle component supply emerging as the decisive cost lever.
For Market Incumbents: Anchor defensive positioning through backward integration into stainless steel tank fabrication and compressor sourcing partnerships that insulate against refrigerant supply constraints. Deepen exclusive channel control with professional installer networks to block big-box retail encroachment. Heat pump technician training capacity represents the critical bottleneck threatening equipment deployment velocity.
For New Entrants and Emerging Players: E-commerce-enabled direct procurement platforms offer bypass routes around established wholesale distributor markups for multi-site hospitality and healthcare operators. Texas municipal utility rebate programs and California Title 24 new construction pipelines represent the most penetrable demand clusters. Lead with predictive maintenance service bundling rather than equipment-only sales to differentiate from incumbent product-centric positioning.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by HVAC consolidators seeking refrigeration-cycle expertise and by building automation platforms integrating thermal systems into comprehensive energy management stacks. Viable targets display captive stainless steel tank production, established Energy Star certification portfolios, and contracted service relationships with large multi-site operators. Monitor California Energy Commission rulemaking timelines as inflection signals for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Production | Captive coil manufacturing insulates Rheem and A.O. Smith from copper price volatility and compressor supply constraints. |
| Professional Installer Channel Expansion | Bradford White's exclusive contractor relationships create switching costs that protect margin structure against retail price erosion. |
| Heat Pump Technician Certification Programs | Rheem's training investments address the refrigeration-cycle expertise gap delaying commercial heat pump deployment. |
| Direct Service Contract Negotiation | Texas and California healthcare systems bypass wholesale markups through national predictive maintenance agreements. |
| EPA Energy Star Certification Investment | Third-party efficiency benchmarking enables specification by chain hospitality operators standardizing procurement across properties. |
Methodological Framework
Independent corroboration across distributor inventory data, municipal utility rebate program disclosures, and DOE certification registries underwrites the qualitative findings. Primary interviews engaged mechanical contractor business owners, commercial facilities maintenance directors, and wholesale distribution category managers. Secondary validation drew from DOE 10 CFR Part 431 rulemaking dockets, California Energy Commission Title 24 compliance documentation, and Texas municipal utility incentive program filings. Bottom-up equipment shipment analysis triangulates against top-down construction spending attribution.
Comparable-period anchoring to historical DOE standard implementation cycles and state-level code adoption timelines structured the projection horizon. The analytical framework models demand across product type, technology, end-use application, and installation configuration dimensions. CAGRs derive from segmented growth rate blending weighted by base-year specification volumes. Forecast inputs incorporate climate zone heat pump performance degradation curves and municipal rebate program renewal probability assessments.
The model holds under continued federal efficiency mandate enforcement and stable utility incentive funding; deviation in refrigerant phasedown acceleration or natural gas infrastructure expansion would shift technology adoption trajectories. Periodic stress-testing of base assumptions against DOE rulemaking schedules and state legislative sessions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
North America Gas Water Heater Market