
 Asia-Pacific Heat Exchanger Market | 2026-2036
Asia-Pacific Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Heat Exchanger Market Analysis
Compact heat transfer technology is tilting design priorities toward smaller footprints and higher thermal density in process equipment. Alfa Laval India Private Limited leverages its plate heat exchanger specialization to serve food and beverage sterilization lines. Kelvion Private Limited anchors large-scale power plant installations across the subcontinent. Thermax Limited dominates waste heat recovery systems for steel and cement producers.
A heat exchanger is a thermal management device that transfers heat between two or more fluid streams at different temperatures through conductive surfaces, with plate configurations achieving effectiveness ratios above 85% in liquid-to-liquid duty. Its primary purpose is energy conservation, process temperature control, and fluid conditioning across industrial operations. Shell and tube designs retain the largest installed base in oil and gas refining, while compact and enhanced heat transfer technologies capture the fastest replacement cycles. Plate heat exchangers concentrate margin pools in hygienic applications where stainless steel construction and cleanability certification command premium positioning.
India's BIS enforces pressure equipment standards under the Indian Boiler Regulations, while China's SAMR oversees GB compliance for thermal efficiency in industrial equipment. Japan's METI promotes heat recovery mandates through energy conservation codes. Australia's TGA-aligned state regulators impose material traceability rules for marine and offshore deployments. Stakeholders must monitor how India's PLI scheme for capital goods and China's dual carbon goals redirect procurement toward domestic manufacturers with certified low-carbon production methods.
Market Dynamics
China's dual carbon goals are compressing procurement timelines for industrial heat recovery equipment while tightening thermal efficiency mandates across chemical processing corridors. This regulatory pressure is accelerating replacement cycles in legacy installations and redirecting capital toward certified low-carbon production methods.
Growth Catalysts
- GB Standards Compliance:China's SAMR-enforced thermal efficiency thresholds for industrial equipment are forcing facility upgrades across Shandong and Jiangsu chemical clusters.
- Waste Heat Recovery:Steel and cement producers in India's western industrial corridor are deploying recovery systems to meet energy conservation mandates under CEA guidelines.
- Plate Heat Exchanger Specialization:Hygienic applications in food and beverage sterilization lines favor stainless steel construction with cleanability certification.
Market Restraints
- Specialized Alloy Costs:Nickel and titanium price volatility compresses margins on corrosion-resistant plate packs for chemical duty.
- Domestic Procurement Bias:India's PLI scheme for capital goods redirects tenders toward certified domestic manufacturers, limiting foreign supplier access.
- Shell and Tube Entrenchment:Oil and gas refining's massive installed base of conventional designs slows adoption of compact alternatives despite superior thermal density.
Strategic Opportunities
- Marine and Offshore Deployment:Australia's TGA-aligned state regulators impose material traceability rules that create premium positioning for certified suppliers.
- Hydrogen Processing Integration:Emerging ammonia and hydrogen liquefaction facilities require cryogenic-rated heat transfer equipment with specialized metallurgy.
- Aftermarket Service Unbundling:Power plant operators are separating maintenance contracts from initial equipment procurement, opening recurring revenue channels.
Industry Challenges
- Pressure Equipment Certification:India's BIS and state boiler inspectorates enforce extended approval timelines under Indian Boiler Regulations, delaying project commissioning.
- Computational Fluid Dynamics Expertise:Shortage of thermal design engineers capable of optimizing plate geometry for non-standard process conditions limits customization capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Heat Exchanger Market |
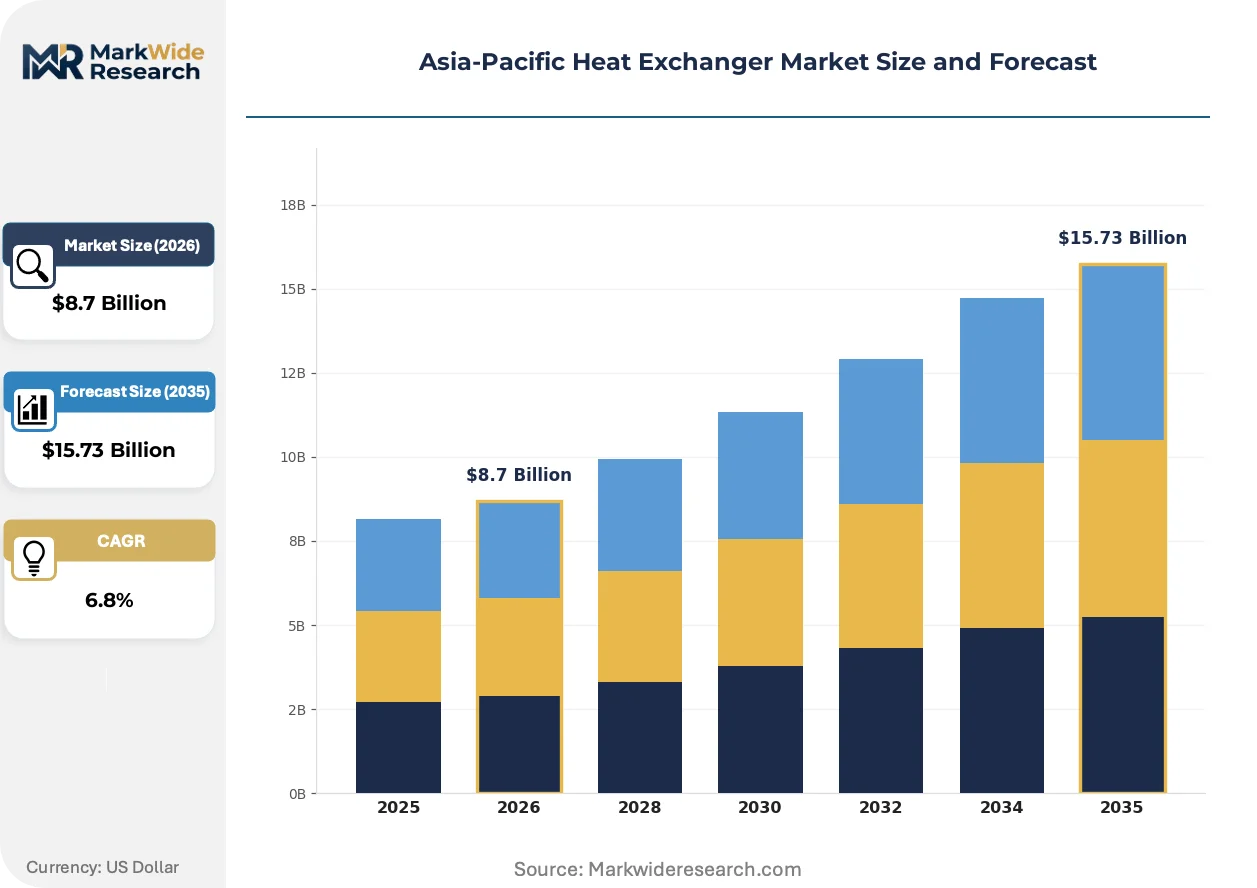
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell and Tube, Plate, Air Cooled, Double Pipe End User: Oil and Gas, Power Generation, Chemical, Food and Beverage Technology: Conventional, Natural Circulation, Compact, Enhanced Heat Transfer Application: Industrial, HVAC, Refrigeration, Marine |
| Companies Covered | Alfa Laval India Private Limited, Kelvion Private Limited, Danfoss Industries Private Limited, API Heat Transfer, HRS Process Systems Limited, Xylem Inc., Thermax Limited, Kawasaki Heavy Industries Ltd., Kurose Chemical Equipment Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Heat Exchanger Market Emerging Trajectories
Compact heat transfer architectures are compressing equipment footprints while elevating thermal density specifications across process industries. Design priorities now favor modularity and cleanability over raw capacity metrics.
Printed circuit heat exchanger technology achieves effectiveness ratios above 90% in supercritical CO2 applications through micro-channel geometries etched into diffusion-bonded stainless steel plates. Japanese heavy industrial conglomerates are piloting these units in geothermal binary cycle plants. Conventional shell and tube designs for high-pressure gas processing are rendering obsolete in space-constrained offshore platforms.
Japan's METI energy conservation codes now mandate heat recovery equipment in designated high-consumption facilities above threshold thermal loads. Industrial compliance deadlines in 2026 are accelerating retrofit procurement across Kansai and Chubu manufacturing belts. Process heat users in specialty chemicals are prioritizing equipment with verified exergy recovery performance to satisfy audit requirements.
Equipment buyers in Southeast Asian chemical processing are unbundling engineering-procurement-construction contracts to negotiate heat exchanger supply separately from installation. This disintermediation favors specialized manufacturers with direct technical service presence over bundled EPC offerings. Procurement teams in Thai and Vietnamese petrochemical complexes are most aggressive in demanding component-level sourcing transparency.
Asia-Pacific Heat Exchanger Market Segmentation
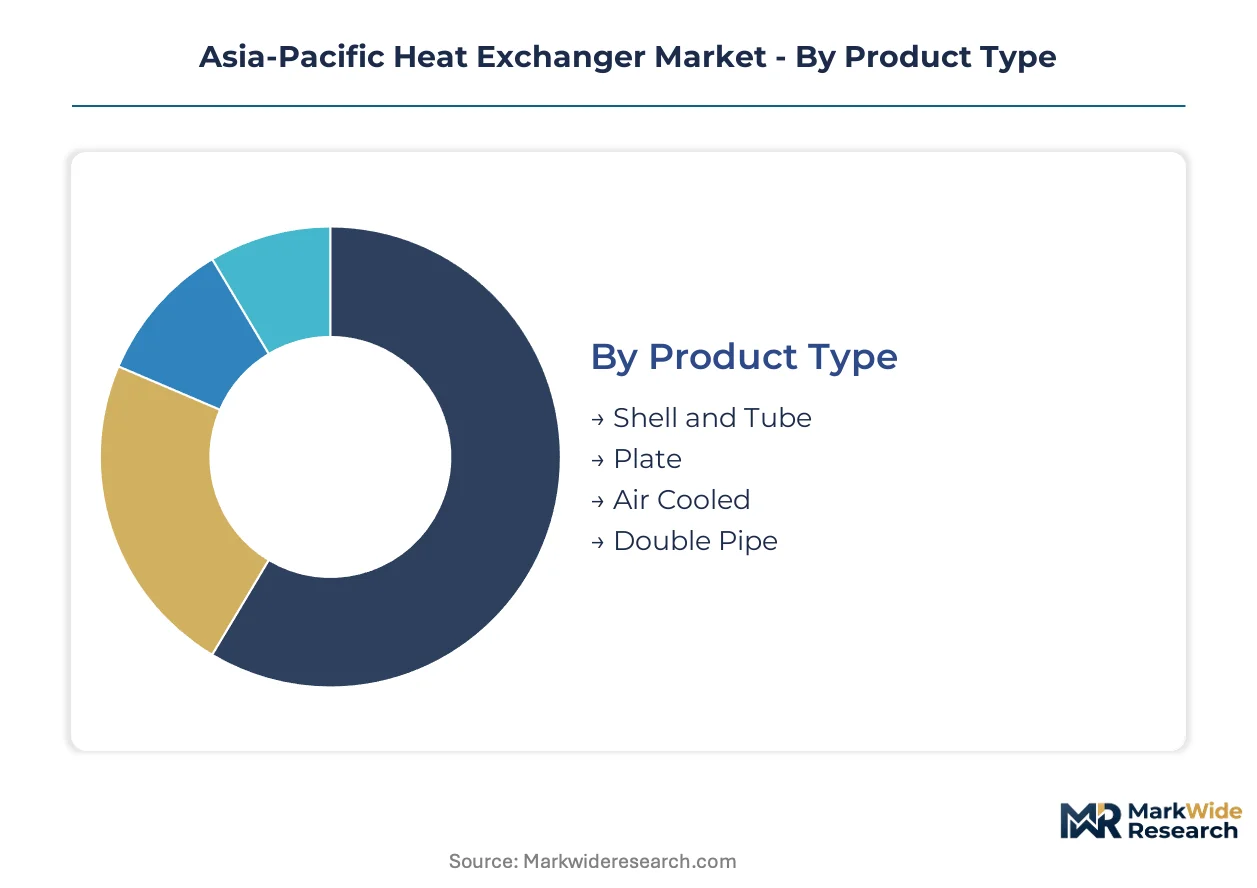
Heat exchanger procurement patterns diverge sharply across product architectures and duty cycles. Segment-specific replacement frequencies and certification requirements create distinct margin pools that reward specialized manufacturing footprints.
Product Type:
Replacement cycles stretch from fifteen-year intervals in heavy-pressure duty to three-year refresh rates in hygienic service, reshaping inventory and service revenue models.
- Shell and Tube:Steel or alloy cylindrical shells enclosing tube bundles withstand extreme pressures and thermal cycling in refinery hydrocracking units. Oil and gas operators in India's western industrial corridor favor these designs for crude preheat trains despite superior thermal density alternatives.
- Plate:Corrugated stainless steel plates separated by gaskets or brazed joints achieve effectiveness ratios above 85% in liquid-to-liquid applications. Food and beverage sterilization lines across Southeast Asia specify cleanability-certified plate packs with 3-A Sanitary Standards compliance.
- Air Cooled:Finned tube bundles with forced or induced draft fans serve cooling duties where water scarcity prohibits wet systems. Australia's mining and LNG projects deploy these in arid interior regions.
- Double Pipe:Concentric tube arrangements handle small-capacity, high-pressure applications with minimal fouling risk. Specialty chemical producers in Japan's Chubu manufacturing belt specify these for pilot-scale thermal processing.
Shell and Tube anchors the volume base while Plate gains share at the steepest rate.
End User:
Capital intensity and regulatory exposure stratify end-user segments into distinct procurement behaviors and contract structures.
- Oil and Gas:Refinery and petrochemical complexes demand pressure-rated equipment with API 660 certification and full material traceability. China's Shandong and Jiangsu chemical clusters drive replacement procurement under tightened SAMR thermal efficiency mandates.
- Power Generation:Combined cycle and thermal plants require feedwater heaters and condensers with decades-long service life. Indian power producers unbundle maintenance contracts from initial procurement, opening recurring revenue channels.
- Chemical:Processors specify corrosion-resistant alloys for aggressive fluid handling. Nickel price volatility compresses margins on titanium-clad plate packs for sulfuric acid duty.
- Food and Beverage:Hygienic design priorities elevate stainless steel construction and cleanability certification over raw thermal capacity. Dairy and beverage sterilization lines in Maharashtra and Gujarat command premium positioning.
Oil and Gas retains the largest installed base while Food and Beverage expands most quickly.
Technology:
Technology tiers separate legacy installed base from next-generation procurement, with compact architectures capturing replacement cycles at accelerated rates.
- Conventional:Established shell and tube and basic plate designs dominate maintenance spending and like-for-like replacements. India's state boiler inspectorates enforce extended approval timelines that delay commissioning of non-standard configurations.
- Natural Circulation:Thermosyphon-driven systems eliminate pumping energy in reboiler and condenser duties. Geothermal binary cycle plants in Japan's Kansai region pilot these configurations.
- Compact:Micro-channel and printed circuit architectures compress footprints by 80% versus conventional designs. Offshore platform constraints in Australia's Northwest Shelf drive specification of diffusion-bonded stainless steel units.
- Enhanced Heat Transfer:Surface augmentation techniques including twisted tape inserts and micro-finned tubes boost coefficients without footprint expansion. Steel and cement waste heat recovery systems in India's western corridor deploy these to meet CEA energy conservation guidelines.
Conventional technology retains the maintenance revenue base while Compact configurations climb the fastest.
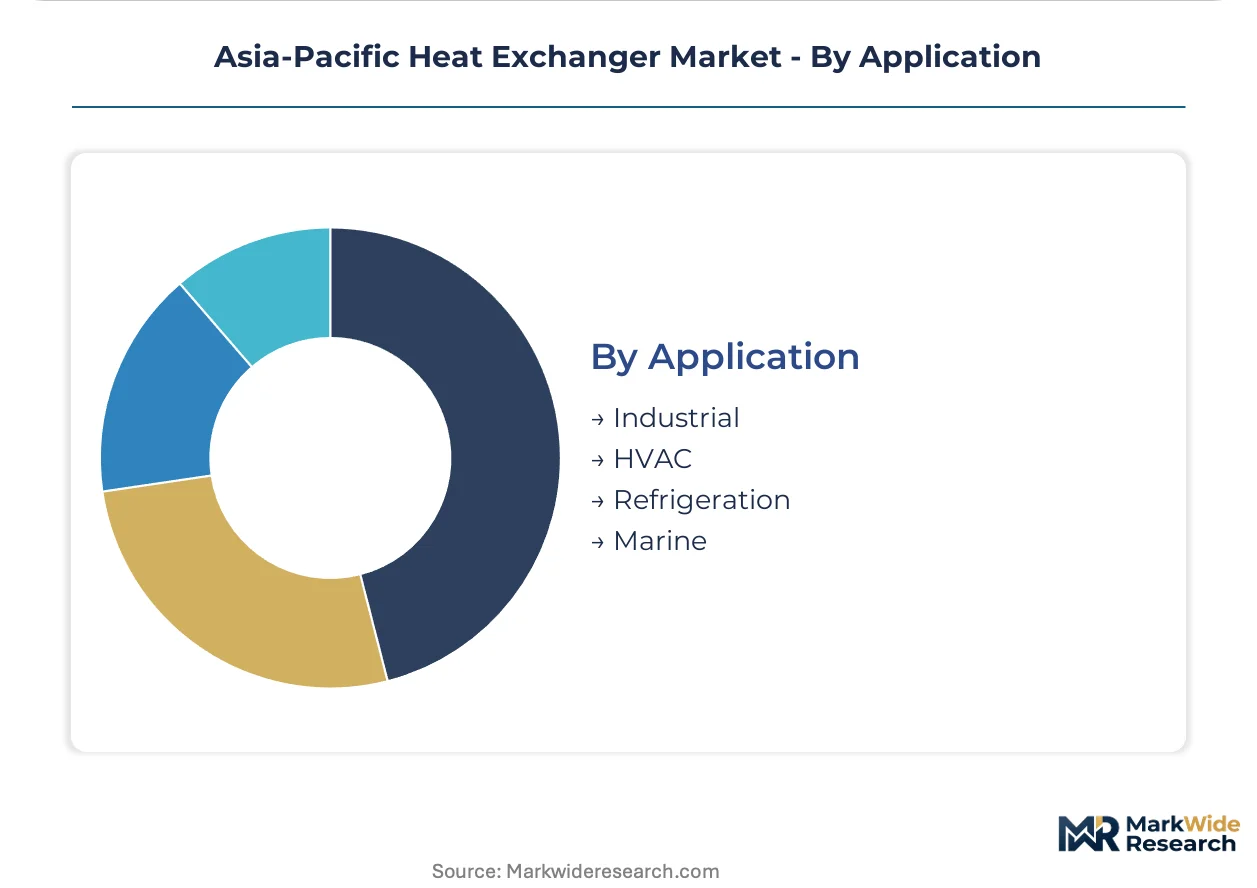
Application:
Application segments align with distinct regulatory jurisdictions and certification requirements that shape supplier qualification barriers.
- Industrial:Process heat recovery and temperature control across manufacturing operations. Chemical processing facilities across Southeast Asia expand capacity with unbundled component procurement.
- HVAC:Building climate systems favor compact plate and brazed aluminum designs. Urban commercial construction in Chinese tier-one cities specifies high-efficiency units under dual carbon procurement guidelines.
- Refrigeration:Industrial cold chain and food preservation systems require leak-tight construction with low-global-warming-potential refrigerant compatibility. Japanese METI energy conservation codes mandate heat recovery equipment in designated high-consumption facilities.
- Marine:Shipboard and offshore installations demand corrosion-resistant materials with classification society approval. Australia's TGA-aligned state regulators impose material traceability rules that create premium positioning for certified suppliers.
Industrial applications anchor the revenue base while Marine specifications are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific runs a structural trade deficit in high-specification heat transfer equipment, with regional fabrication capacity concentrated in lower-complexity shell and tube designs while cryogenic and printed circuit architectures import from European specialists. Import dependency is narrowing as domestic certification regimes mature.
China
Chemical processors in Shandong and Jiangsu provinces are replacing legacy steam systems under SAMR-enforced GB thermal efficiency mandates. The dual carbon goals compress procurement timelines for industrial heat recovery equipment. Shandong's petrochemical corridor drives replacement cycles at the steepest regional rate.
India
Steel and cement producers across Gujarat and Maharashtra deploy waste heat recovery systems to satisfy CEA energy conservation guidelines. BIS pressure equipment certification under Indian Boiler Regulations extends approval timelines for non-standard configurations. The western industrial corridor from Hazira to Pune anchors domestic demand concentration.
Japan
METI energy conservation codes mandate heat recovery installation in designated high-consumption facilities exceeding threshold thermal loads. Geothermal binary cycle developers in Kansai pilot printed circuit heat exchanger technology for supercritical CO2 applications. Chubu manufacturing belt processors prioritize verified exergy recovery performance to satisfy audit requirements.
Australia
Arid-region mining and LNG projects specify air-cooled designs where water scarcity prohibits wet systems. TGA-aligned state regulators impose material traceability rules for marine and offshore deployments. Northwest Shelf offshore platforms drive specification of diffusion-bonded compact units with classification society approval.
South Korea
Shipyard fabricators integrate corrosion-resistant heat transfer packages into LNG carrier and offshore vessel construction. The national industrial regulator enforces pressure equipment standards aligned with international classification society rules. Ulsan and Geoje maritime manufacturing clusters concentrate procurement of certified marine-grade systems.
Asia-Pacific Heat Exchanger Market Vendor Landscape
On the supply side, the industry is bifurcated between multinational specialists with established certification portfolios and domestic fabricators competing on cost-adjusted delivery timelines. Tiering separates premium-positioned players with direct technical service presence from volume-oriented suppliers serving maintenance replacement cycles. Two strategic archetypes dominate: plate heat exchanger specialists leveraging hygienic application margins, and diversified industrial conglomerates anchoring large-scale power and chemical installations. Competitive moves concentrate on geographic licensing partnerships and unbundled aftermarket service contracts.
Among India-based specialists, Thermax Limited and Alfa Laval India Private Limited occupy distinct positioning archetypes within the regional supply structure. Japanese heavy industrial interests including Kawasaki Heavy Industries Ltd. anchor premium-tier positioning through integrated project execution capabilities. Kelvion Private Limited represents the multinational specialist model with established certification depth across pressure equipment categories. These three names illustrate the competitive segmentation between domestic scale, global technology access, and integrated engineering-procurement-construction bundling.
| Leading Market Players |
|---|
| Alfa Laval India Private Limited |
| Kelvion Private Limited |
| Danfoss Industries Private Limited |
| API Heat Transfer |
| HRS Process Systems Limited |
| Xylem Inc. |
| Thermax Limited |
| Kawasaki Heavy Industries Ltd. |
| Kurose Chemical Equipment Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Singapore freight corridor's rate volatility compresses margins on nickel-alloy plate packs while amplifying price spreads between certified domestic fabricators and import-dependent specialists serving India's western industrial corridor.
Pricing Analysis
Technology-generation pricing gaps separate conventional shell and tube replacements from compact printed circuit architectures and next-generation diffusion-bonded units. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under Indian Boiler Regulations and GB compliance tiers. Cost compression in standard-duty plate packs is intensifying because nickel price volatility feeds directly into corrugated stainless steel input costs. Chemical processors in Shandong and Jiangsu provinces exhibit highest price sensitivity; marine and offshore buyers in Australia's Northwest Shelf show lowest sensitivity due to material traceability mandates.
Supply Chain Analysis
Tariff exposure between China and Australia dominates supply chain risk calculations for diffusion-bonded compact units destined for offshore platforms. Manufacturing concentration rests on China for brazed aluminum cores, India for shell and tube fabrications serving domestic refinery demand, and Japan for precision-etched micro-channel plates. Raw material dependencies draw from Indonesian nickel laterite, Australian titanium sponge, and Korean specialty steel. Single-source vulnerability concentrates in diffusion-bonding equipment for printed circuit architectures. Distribution runs through direct technical service presence for large power and chemical installations, with aftermarket parts flowing through authorized service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific heat exchanger demand sits in early-cycle expansion as METI energy conservation codes and CEA waste heat mandates force replacement procurement across installed bases exceeding fifteen-year service intervals.
For Market Incumbents: Harden certification depth under Indian Boiler Regulations and SAMR GB standards to defend against emerging domestic fabricators capturing PLI-redirected tenders. Deepen backward integration into specialty alloy supply through offtake agreements with Indonesian nickel processors, anchoring margin control against commodity volatility. For New Entrants and Emerging Players: Pursue aftermarket service unbundling in India's power generation sector where maintenance contracts separate from initial procurement. Target compact heat transfer architectures for Australia's marine and offshore segment; establish direct technical service presence in Perth to satisfy TGA-aligned material traceability rules. For Investors and Strategic Acquirers: Plate heat exchanger specialists with cleanability-certified stainless steel construction represent the most defensible acquisition archetype as food and beverage sterilization lines expand across Maharashtra and Gujarat. Watch unbundling intensity in Thai and Vietnamese petrochemical procurement as the inflection signal separating component specialists from bundled EPC players.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | Indian Boiler Regulations and SAMR GB compliance create qualification barriers against low-cost imports. |
| Backward Integration | Captive nickel alloy supply from Indonesian laterite sources hedges against price volatility in plate pack production. |
| Aftermarket Service Unbundling | Power plant operators in Gujarat and Maharashtra now separate maintenance contracts from equipment procurement. |
| Geographic Licensing Partnership | Japanese printed circuit technology licensed to Australian fabricators satisfies Northwest Shelf platform constraints. |
| Green Manufacturing Transition | CEA energy conservation guidelines and China's dual carbon goals redirect procurement toward verified low-carbon production methods. |
Methodological Framework
The analysis maps shell and tube, plate, air-cooled, and compact heat transfer architectures, each validated through maintenance directors at steel and cement plants, procurement leads at Indian power producers, technical service heads at multinational specialists, and aftermarket managers at domestic fabricators. Primary interview findings triangulate against customs and trade data for nickel and titanium flows, SEC filings from listed industrial conglomerates, Indian Boiler Regulations certification databases, and METI energy conservation compliance records. Bottom-up unit economics and top-down sectoral demand curves converge through iterative reconciliation.
Assumption sets hold SAMR enforcement intensity and CEA mandate timelines within observed regulatory patterns while varying nickel price trajectories and PLI scheme coverage across sensitivity scenarios. Segmentation dimensions span product architecture, end-use industry, technology tier, and application duty cycle across the projection horizon. CAGRs derive from replacement cycle analysis tied to pressure equipment inspection intervals and thermal efficiency upgrade mandates. Industry-specific inputs include geothermal binary cycle deployment rates in Japan's Kansai region and unbundling penetration in Southeast Asian chemical procurement.
The forecast holds incumbent behavior within observed patterns; aggressive certification acceleration by domestic Indian fabricators or sudden diffusion-bonding equipment import restrictions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Heating and Cooling Market