
 Europe HVAC Equipment Market | 2026-2036
Europe HVAC Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe HVAC Equipment Market Foresight
German boiler and heat pump manufacturing is consolidating as energy transition policy tightens supply-side requirements. Daikin Europe N.V. leverages its inverter compressor R&D center in Ostend to anchor premium residential heat pump sales across the Low Countries. Bosch Thermotechnology GmbH sustains a dense service network that dominates replacement cycles in Central European multi-family housing. Carrier Global Corporation competes through hydronic system integration for large commercial projects in Paris and Milan.
Europe HVAC equipment encompasses electromechanical systems for thermal comfort and indoor air quality management, typically operating with refrigerants at pressures between 15 and 45 bar and achieving seasonal coefficient of performance ratings above 3.0 for modern heat pumps. These systems serve residential, commercial, and industrial buildings where ventilation and temperature control protect occupant health and process integrity. Heat pumps now represent the fastest-expanding product category as gas boiler bans approach in multiple member states, while inverter technology leads margin pools due to component complexity and software differentiation. Smart controls remain a smaller revenue slice but capture disproportionate aftermarket value through energy management subscriptions and remote diagnostics.
The EU Green Deal and F-Gas Regulation are accelerating refrigerant transitions from high-GWP hydrofluorocarbons to lower-impact alternatives, forcing manufacturers to redesign compressor architectures and recertify product lines. Ecodesign requirements under the EU framework now mandate minimum seasonal efficiency thresholds that exclude conventional non-inverter equipment from new installations. REACH compliance adds material constraints on insulation foams and coatings. Stakeholders must monitor member state transposition timelines for building performance standards and position supply chains for refrigerant platform shifts before enforcement windows narrow.
Market Dynamics
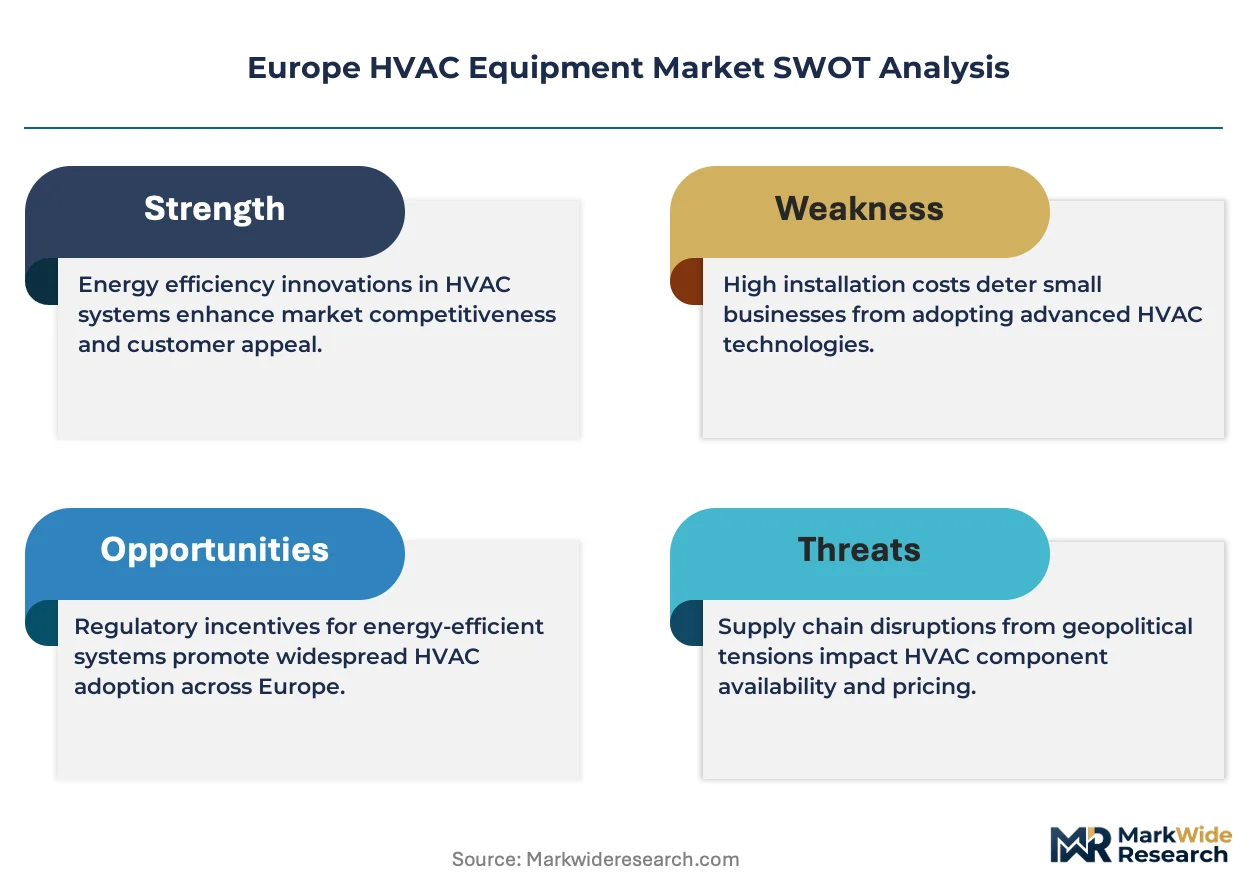
The EU F-Gas Regulation is compressing refrigerant options and forcing compressor architecture redesigns across European manufacturing bases, while national building codes in Germany and France harden heat pump deployment mandates.
Growth Catalysts
- REPowerEU heat pump acceleration targets:Member state subsidies for residential electrification are pulling forward replacement cycles in multi-family housing across the Low Countries and Scandinavia.
- Commercial real estate climate-control expansion:Developers in Paris and Milan are specifying integrated hydronic systems for new office and logistics construction.
- Inverter compressor R&D localization:Belgium-based engineering centers are anchoring premium product development for residential markets.
Market Restraints
- Copper and rare earth magnet cost volatility:Compressor motor supply chains face input price swings that compress OEM margins on mid-tier equipment.
- Refrigerant platform transition capex:Manufacturers must recertify entire product lines for lower-GWP alternatives before F-Gas phase-down enforcement windows narrow.
- Skilled installer scarcity:Heat pump deployment outpaces qualified technician availability in rural France and southern Italy.
Strategic Opportunities
- Building renovation wave in Poland and Romania:EU Recovery and Resilience Facility funds are unlocking HVAC replacement demand in underpenetrated member states.
- Smart controls and energy management subscriptions:Remote diagnostics platforms are capturing aftermarket value beyond hardware sales.
- R-290 propane refrigerant adoption:Flammable refrigerant architectures open efficiency advantages for manufacturers with certified production lines.
Industry Challenges
- CE marking and Ecodesign recertification timelines:Product approval backlogs at notified bodies delay new heat pump launches.
- Legacy gas boiler service network conversion:Established installers require reskilling for refrigerant handling and electrical integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe HVAC Equipment Market |
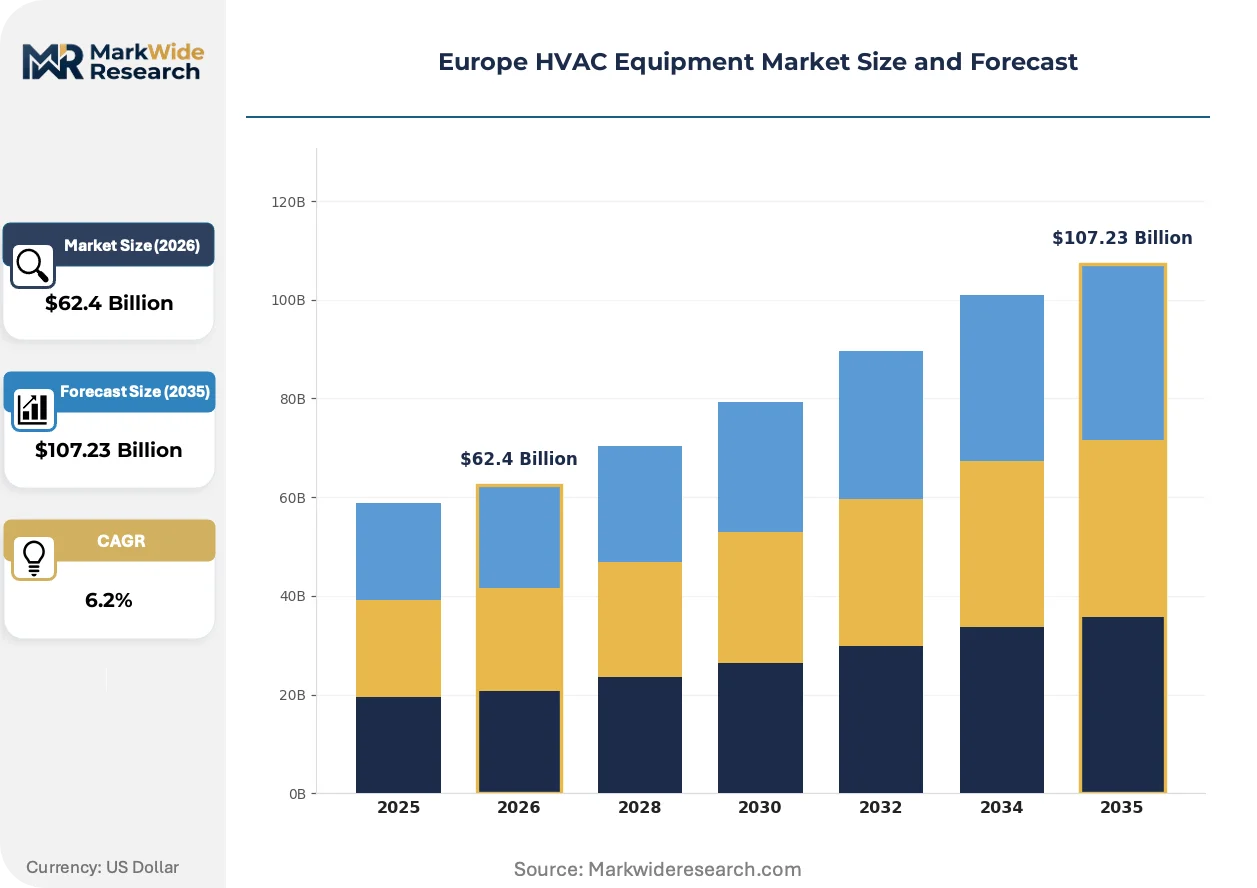
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $107.23 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioners, Heat Pumps, Furnaces, Boilers End User: Residential, Commercial, Industrial, Institutional Technology: Inverter, Non-Inverter, Smart Controls, Hydronic Systems Application: Cooling, Heating, Ventilation, Air Quality |
| Companies Covered | Viessmann Climate Solutions SE, Trane Technologies plc, Daikin Europe N.V., Danfoss A/S, Carrier Global Corporation, Bosch Thermotechnology GmbH, Mitsubishi Electric Europe, Systemair AB, Vaillant Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe HVAC Equipment Market Shifts & Advancements
Refrigerant chemistry, compressor architecture, and control systems are converging to reset equipment specifications and service models across European climate zones.
Variable refrigerant flow systems with embedded inverter drives are modularizing installation approaches for multi-zone commercial buildings. Facility managers in Madrid and Barcelona are specifying factory-charged split configurations to reduce on-site brazing and leak testing. This shift is compressing project timelines and reducing specialized labor dependencies for mid-size office retrofits.
The EU F-Gas Regulation is banning virgin HFC refrigerants above specific GWP thresholds and accelerating quota reductions through 2030. Equipment manufacturers are redesigning scroll and rotary compressors for R-32 and R-290 compatibility. Residential heat pump lines face the tightest recertification deadlines, with German and French OEMs prioritizing propane architectures for new product platforms.
Energy-as-a-service contracting is displacing capital purchase models for large commercial installations. Property investors in Stockholm and Copenhagen are procuring thermal comfort through performance guarantees rather than equipment ownership. This restructures vendor relationships toward long-term monitoring obligations and efficiency accountability clauses.
Europe HVAC Equipment Market Segmentation
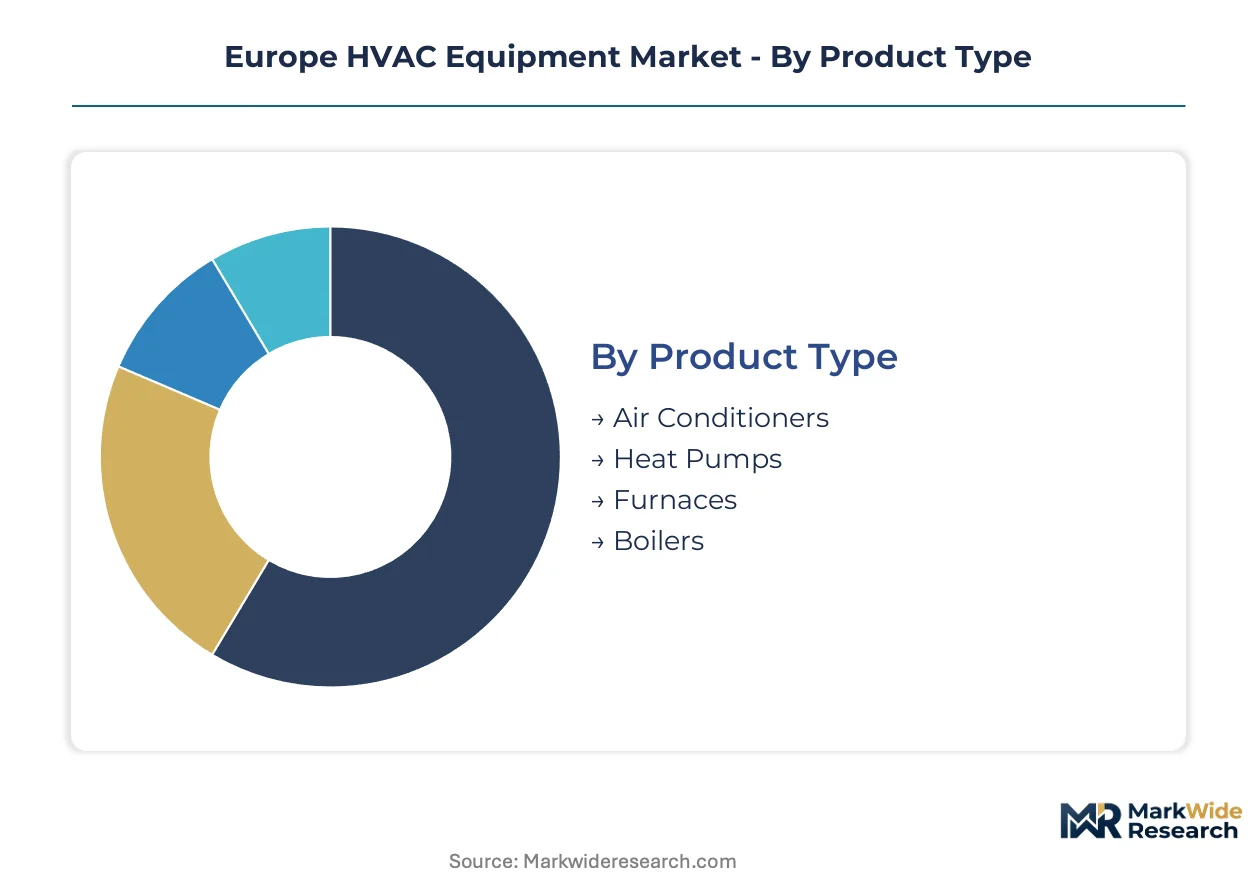
Segmentation in the Europe HVAC Equipment Market reveals how regulatory pressure and building stock characteristics reshape procurement patterns. Equipment categories diverge sharply between new construction electrification mandates and renovation-driven replacement cycles across member states.
Product Type:
Integration depth varies substantially across equipment categories, with standalone outdoor units dominating residential retrofits while fully integrated plant systems anchor commercial new builds.
- Heat Pumps:Electrified thermal systems extract ambient heat from air, ground, or water sources using vapor-compression cycles with seasonal coefficient of performance ratings above 3.0. German and French multi-family housing retrofits are concentrating demand as gas boiler bans approach in multiple jurisdictions.
- Air Conditioners:Vapor-compression cooling equipment ranges from single-split residential units to multi-zone variable refrigerant flow systems for commercial buildings. Facility managers in Madrid and Milan are specifying factory-charged configurations to compress installation timelines and reduce on-site labor dependencies.
- Furnaces:Fuel-fired forced-air heating equipment maintains installed base in legacy Central European housing stock where ductwork infrastructure exists.
- Boilers:Hydronic heat generators face phase-out timelines under national building codes, though condensing gas models persist in replacement cycles where heat pump retrofit complexity is prohibitive.
Boilers lead volumes today; heat pumps are gaining share fastest.
End User:
Customer archetypes segment by project scale, with single-unit residential purchases contrasting against multi-year service contracts for commercial portfolios.
- Residential:Single-family and multi-family dwellings account for unit-volume concentration, with electrification subsidies in the Low Countries and Scandinavia pulling forward replacement cycles.
- Commercial:Office, retail, and logistics facilities specify integrated hydronic systems with performance guarantees; Paris and Milan developers are procuring thermal comfort through energy-as-a-service contracting rather than capital purchase.
- Industrial:Process cooling and climate-controlled manufacturing environments demand specialized equipment with redundancy requirements and uptime service level agreements.
- Institutional:Schools, hospitals, and government buildings operate under public procurement frameworks that prioritize lifecycle cost analysis over first-cost minimization.
Residential commands unit volumes; commercial delivers margin expansion.
Technology:
Control sophistication and compressor architecture determine efficiency certification tiers under Ecodesign requirements, with inverter platforms capturing premium positioning.
- Inverter:Variable-speed compressor drives modulate output to match thermal loads, eliminating start-stop cycling losses. Belgian R&D centers anchor premium product development for residential markets across the Low Countries.
- Smart Controls:Networked thermostats and energy management platforms capture aftermarket value through remote diagnostics subscriptions and demand-response participation.
- Non-Inverter:Fixed-speed equipment faces exclusion from new installations under minimum seasonal efficiency thresholds, persisting only in price-sensitive replacement segments.
- Hydronic Systems:Water-based distribution architectures integrate heating and cooling through common piping infrastructure, specified for large commercial projects with zonal load diversity.
Inverter systems dominate new installation value; smart controls expand most quickly.
Application:
Functional purpose segments reveal divergent equipment specifications, with dedicated cooling systems requiring higher refrigerant pressures than heating-optimized heat pumps.
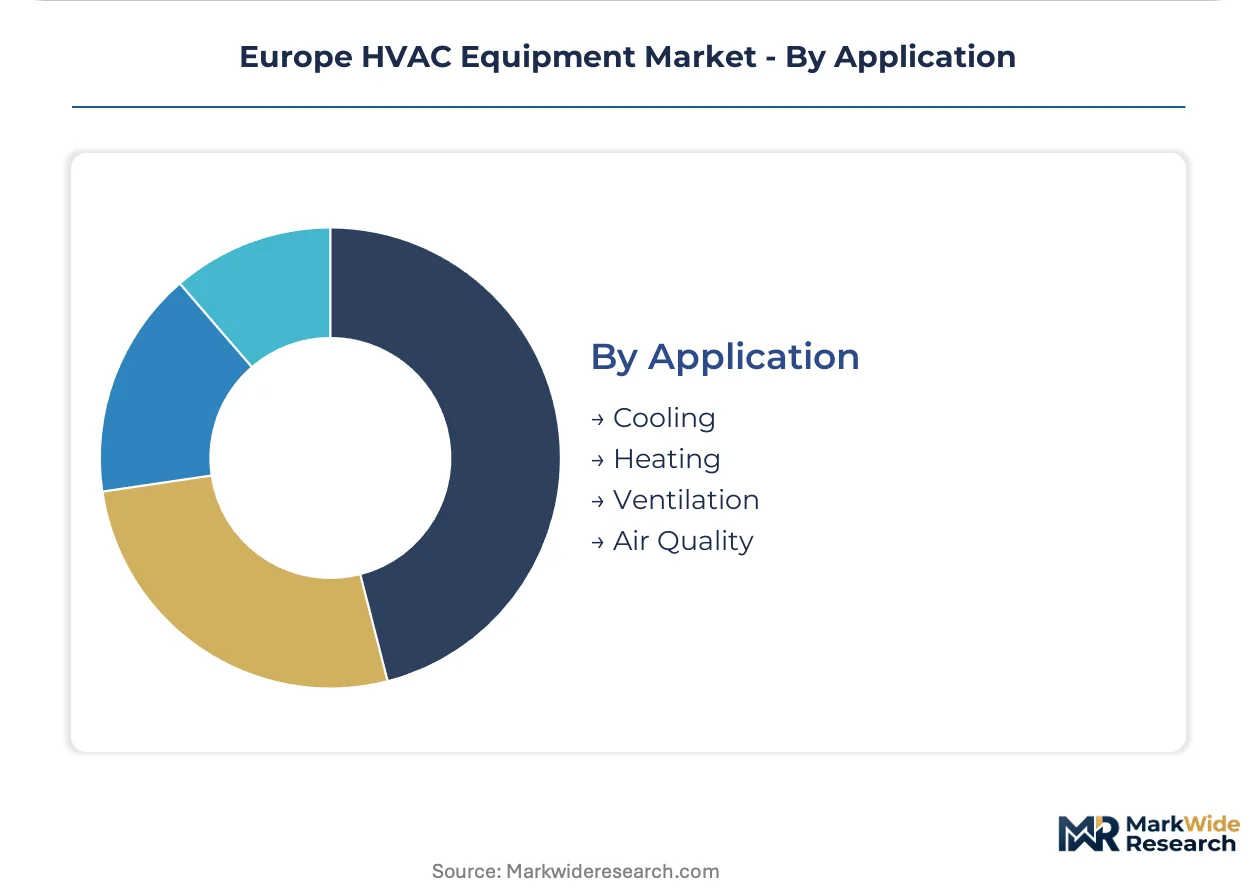
- Cooling:Comfort and process cooling applications operate at refrigerant pressures between 15 and 45 bar, with Mediterranean climates driving seasonal peak demand in Spain and southern Italy.
- Heating:Space and water heating electrification is accelerating under REPowerEU targets, with air-source heat pumps achieving operational efficiency down to minus 25 degrees Celsius ambient.
- Ventilation:Mechanical supply and exhaust systems with heat recovery are mandated in passive house construction and tightening building codes across Germany and France.
- Air Quality:Filtration, humidification, and dehumidification functions are integrating into packaged equipment as occupant health protection gains regulatory weight.
Heating leads installed capacity; air quality functions climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence across the EU creates compliance-cost arbitrage that pulls manufacturing investment toward jurisdictions with faster permitting and aligned subsidy regimes. The F-Gas Regulation applies uniformly, but member-state implementation speed varies.
Germany
The Building Energy Act mandates heat pump quotas in new construction and triggers wholesale replacement cycles in multi-family housing. KBA emissions standards for building systems tighten refrigerant containment requirements. Manufacturing clusters in North Rhine-Westphalia and Bavaria concentrate inverter compressor assembly and hydronic system integration.
France
RE2020 environmental regulations impose carbon caps on new buildings that favor electrified heating over gas infrastructure. ANSM oversees chemical safety compliance for refrigerant handling protocols. The Paris metropolitan area anchors specification-driven procurement for integrated commercial systems with performance guarantees.
Italy
Superbonus 110% tax incentives pulled forward residential renovation demand before program modification, leaving residual replacement backlogs. CE marking enforcement at notified bodies creates product approval bottlenecks for heat pump imports. Lombardy and Veneto host manufacturing bases for compact residential units serving Mediterranean climate zones.
Poland
EU Recovery and Resilience Facility disbursements unlock building modernization in underpenetrated single-family housing stock. The national energy regulator shapes grid connection standards for distributed heat pump deployment. Warsaw and Krakow concentrate distribution infrastructure for equipment imported from Western European assembly plants.
Netherlands
Natural gas extraction curtailment in Groningen accelerates building stock electrification mandates ahead of EU-wide schedules. Ecodesign requirements under Dutch transposition exclude non-inverter equipment from subsidy eligibility. The Randstad corridor hosts R&D centers for smart control integration and district heating interface technologies.
Europe HVAC Equipment Market Competitive Landscape
German producers anchor one tier; Japanese-European joint ventures hold premium positioning through inverter specialization. The vendor base stratifies across three tiers: integrated conglomerates with full climate-control portfolios, component specialists supplying compressor and control modules, and regional assemblers serving price-sensitive replacement cycles. Dominant competitive moves include capacity relocation toward Central European manufacturing corridors and technology licensing partnerships for R-290 propane system architectures.
Within the integrated systems tier, Viessmann Climate Solutions SE and Bosch Thermotechnology GmbH exemplify German engineering-origin conglomerates with dense service networks across Central European multi-family housing. Daikin Europe N.V. anchors the premium heat pump segment through Belgian-based inverter R&D localization. Carrier Global Corporation occupies a position in large commercial hydronic integration for specification-driven projects in Paris and Milan.
| Leading Market Players |
|---|
| Viessmann Climate Solutions SE |
| Trane Technologies plc |
| Daikin Europe N.V. |
| Danfoss A/S |
| Carrier Global Corporation |
| Bosch Thermotechnology GmbH |
| Mitsubishi Electric Europe |
| Systemair AB |
| Vaillant Group |
| Others |
Supply & Pricing Matrix
Family-owned German engineering conglomerates anchor manufacturing clusters across North Rhine-Westphalia and Bavaria, concentrating inverter compressor assembly and hydronic system integration. This ownership structure reinforces long-term supply relationships with copper processors and rare earth magnet suppliers while supporting pricing discipline through dense aftermarket service networks that capture replacement cycle value.
Pricing Analysis
Distributor margins compress as OEMs consolidate direct relationships with large commercial developers in Paris and Milan. Three-tier pricing structure across premium inverter systems, standard fixed-speed equipment, and economy replacement units separates certification-grade heat pumps from basic cooling-only configurations. Pricing pressure stems from copper and rare earth input volatility that squeezes mid-tier equipment margins. Residential retrofit buyers in rural France and southern Italy exhibit highest price sensitivity, while institutional procurement frameworks prioritize lifecycle cost over first-cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from major OEMs mandate multi-supplier qualification for compressor motors and electronic control modules. Manufacturing concentrates in Germany, Italy, and Belgium, with component sourcing drawing from Chinese rare earth processors and Chilean copper refiners. Supply chain risk centers on refrigerant platform transition timelines that compress recertification windows before F-Gas enforcement narrows. Distribution runs through national wholesaler networks with regional logistics hubs in Warsaw and Krakow serving Eastern European penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. REPowerEU electrification mandates and tightening Ecodesign thresholds concentrate procurement toward premium inverter platforms with embedded smart controls.
For Market Incumbents: To counter skilled installer scarcity in rural France and southern Italy, deepen captive service network coverage through reskilling partnerships with legacy gas boiler technicians. Prioritize R-290 propane refrigerant certification investment ahead of F-Gas quota reductions to secure platform leadership for new product launches. For New Entrants and Emerging Players: Specialist controls developers can anchor market entry through white-label partnerships with mid-tier equipment assemblers in Poland and Romania. Building renovation wave demand in underpenetrated single-family housing offers the most penetrable entry point, with smart thermostat integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Climate-technology conglomerates are the most active acquirer in this space, consolidating component specialists with certified refrigerant handling capabilities. Long-term viability favors targets with established CE marking pathways and inverter R&D assets. Watch F-Gas recertification backlog clearance at notified bodies as the signal for competitive capacity release.| Strategic Initiative | Industry Significance |
|---|---|
| R-290 Propane Refrigerant Certification | Secures platform positioning ahead of F-Gas quota phase-down enforcement windows. |
| Installer Reskilling Program | Addresses technician scarcity that constrains heat pump deployment velocity in Southern Europe. |
| Smart Control Platform Integration | Captures aftermarket subscription value through remote diagnostics and demand-response participation. |
| Central European Manufacturing Expansion | Aligns production with REPowerEU subsidy disbursement corridors in Poland and Romania. |
| Energy-as-a-Service Contracting | Restructures vendor relationships toward long-term performance guarantees in Stockholm and Copenhagen. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged heat pump manufacturing executives, regulatory affairs specialists at notified bodies, commercial real estate developers in Paris and Milan, and aftermarket service network managers. Secondary validation drew from EU F-Gas Regulation filings, Ecodesign directive transposition documents, REPowerEU progress reports, and national building code updates. Bottom-up equipment shipment tracking and top-down construction investment data were triangulated against subsidy disbursement records.
Segment-weighting applied product type, end user category, technology tier, and application function across the modeling period. CAGRs were derived from installed base turnover rates and replacement cycle acceleration under electrification mandates. Forecast inputs incorporated heat pump deployment targets, refrigerant platform transition timelines, and building renovation fund disbursement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas enforcement pacing and copper price trajectory. Projections reflect assumptions about subsidy continuity and installer workforce expansion. Deviation in REPowerEU fund allocation or notified body approval capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
South Korea HVAC Market