
 Pharmaceutical Material Handling Equipment Market | 2026-2036
Pharmaceutical Material Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Material Handling Equipment Market Analytics
A shortage of certified automation technicians is unwinding capacity expansion timelines at pharmaceutical logistics facilities worldwide. Daifuku Co., Ltd. leverages its cleanroom conveyor expertise to anchor high-containment installations across Asia-Pacific sterile manufacturing sites. Toyota Industries Corporation sustains competitive positioning through vertical integration into AGV navigation software and battery systems. KION Group AG dominates European pallet jack and forklift supply for GMP-certified warehouses with temperature-validated fleets.
Pharmaceutical material handling equipment encompasses mechanized systems engineered to transport, store, and control drug products and active ingredients within regulated facilities, typically constructed from 316L stainless steel with surface finishes below 0.8 micrometers Ra to prevent microbial adhesion and particle shedding. These systems serve the primary commercial purpose of maintaining product integrity, batch traceability, and operator safety through contained transfer of potent compounds and temperature-sensitive biologics. Automated Guided Vehicles represent the fastest-expanding product category as pharmaceutical manufacturers pursue lights-out intralogistics to minimize human-borne contamination in Grade A/B environments. Robotic Systems capture concentrated margin pools in aseptic filling lines where collaborative arms execute vial handling at speeds exceeding 400 units per minute. Manual Handling Solutions retain substantial installed base across contract packaging organizations where product diversity and batch sizes resist full automation economics.
FDA enforcement of 21 CFR Part 211 cGMP requirements shapes equipment validation protocols, while EMA's Annex 1 revision mandates continuous particulate monitoring during material transfer operations, directly stimulating demand for sealed conveyor enclosures and isolator-integrated handling modules. ISO 14644 cleanroom classifications further constrain equipment design, compelling suppliers to engineer fan-filter units and pressure differential controls into standard product architectures. Stakeholders must weigh total cost of ownership against contamination risk reduction when selecting between retrofitted manual systems and fully automated robotic platforms for multiproduct facilities.
Market Dynamics
Biologics manufacturing is fragmenting material handling architectures as facilities retrofit for single-use technologies and modular cleanroom layouts that demand reconfigurable conveying infrastructure rather than fixed stainless steel installations.
Growth Catalysts
- FDA Annex 1 Sterility Mandates:The 2022 revision to EU GMP Annex 1 compels aseptic facilities to install continuous particulate monitoring systems integrated into material transfer equipment, directly stimulating replacement cycles for open-conveyor systems.
- Cold-Chain Biologics Expansion:mRNA and cell therapy manufacturing sites are deploying automated guided vehicles with validated temperature control to maintain cryogenic conditions during intralogistics operations.
- 316L Stainless Steel Sourcing:German pharmaceutical exporters are modernizing distribution centers with Ra 0.4 micrometer surface finish conveyors to meet export certification requirements for high-potency compounds.
Market Restraints
- Certified Technician Scarcity:A shortage of automation engineers qualified in ISO 14644 cleanroom protocols is extending commissioning timelines for AGV installations by 30-40% at sterile manufacturing sites.
- High-Grade Steel Volatility:Nickel price fluctuations directly impact 316L stainless steel conveyor fabrication costs, compressing margins for equipment suppliers locked into fixed-price validation contracts.
- Containment Isolator Integration:Current robotic handling systems face technical limitations in achieving Grade A air classification within restricted access barrier systems without extensive custom engineering.
Strategic Opportunities
- Contract Packaging Automation:Small-batch CMOs represent underpenetrated demand for collaborative robotic arms that handle vial diversity without line changeover downtime.
- India PLI Scheme Alignment:The country's production-linked incentive scheme for pharmaceutical manufacturing is attracting greenfield facilities requiring GMP-validated material handling infrastructure.
- Digital Twin Convergence:Integration of AGV fleet management with building management systems enables predictive maintenance and energy optimization in multi-product facilities.
Industry Challenges
- Validation Documentation Burden:IQ/OQ/PQ protocol execution for automated handling systems consumes 18-24 months, delaying revenue recognition for equipment vendors and facility startups.
- Legacy System Integration:Brownfield sites struggle to interface new robotic modules with existing warehouse management software architectures without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Material Handling Equipment Market |
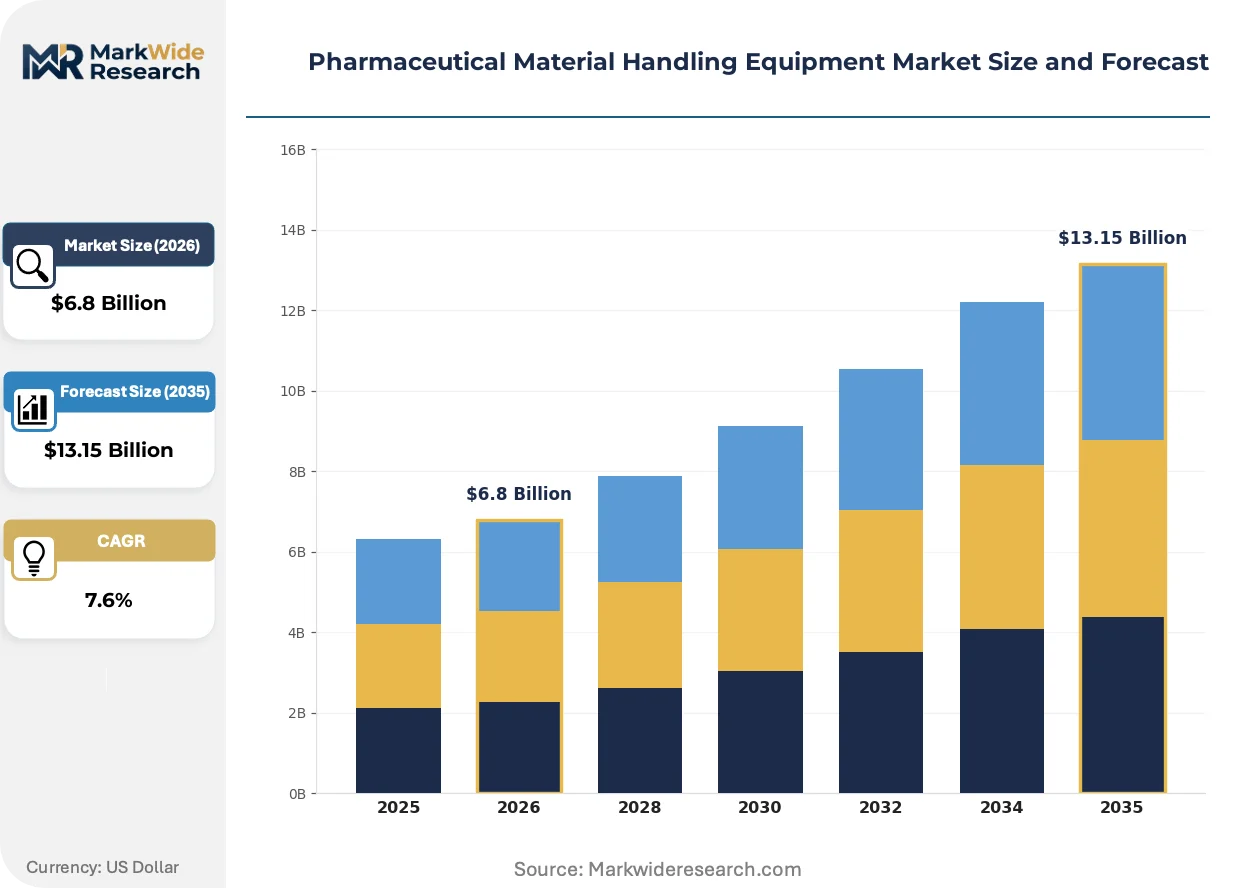
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyors, Pallet Jacks, Forklifts, Automated Guided Vehicles End User: Pharmaceutical Manufacturers, Wholesale Distributors, Research Laboratories, Contract Packaging Organizations Technology: Automation Solutions, Manual Handling Solutions, Robotic Systems, IoT Integration Application: Storage, Transportation, Inventory Management, Order Fulfillment |
| Companies Covered | Tote Systems International, Paul N. Gardner, AZO GmbH & Co. KG, David Round Company, Daifuku Co., Ltd., Toyota Industries Corporation, KION Group AG, Jungheinrich AG, Crown Equipment Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Material Handling Equipment Market Evolving Landscape
Modular cleanroom architectures are displacing fixed infrastructure as pharmaceutical manufacturers prioritize flexibility for multi-product campaigns and rapid product changeovers.
Autonomous mobile robots equipped with LIDAR navigation and HEPA filtration are fragmenting the AGV category as biologics facilities deploy smaller, more maneuverable units for confined Grade B corridors. Mid-sized manufacturers are adopting these systems faster than large multinationals due to lower capital barriers. The technology is fragmenting supplier hierarchies by enabling new entrants to compete on software differentiation rather than mechanical engineering scale.
EMA's Annex 1 revision mandating continuous viable and non-viable particle monitoring during material transfer operations is forcing conveyor enclosure redesigns across European sterile manufacturing sites. Equipment suppliers must now engineer sealed transfer ports and isolator-integrated handling modules as standard offerings. Aseptic filling line OEMs are absorbing these compliance costs into turnkey system pricing to maintain market position.
Buyer procurement patterns are compressing validation timelines as pharmaceutical companies accelerate facility commissioning to capture biologics patent cliffs. Equipment vendors are responding with pre-validated platform configurations that reduce site-specific qualification work. This behavior is most pronounced in German and Swiss manufacturing clusters where CDMO competition for biologics contracts is intensifying.
Pharmaceutical Material Handling Equipment Market Segmentation
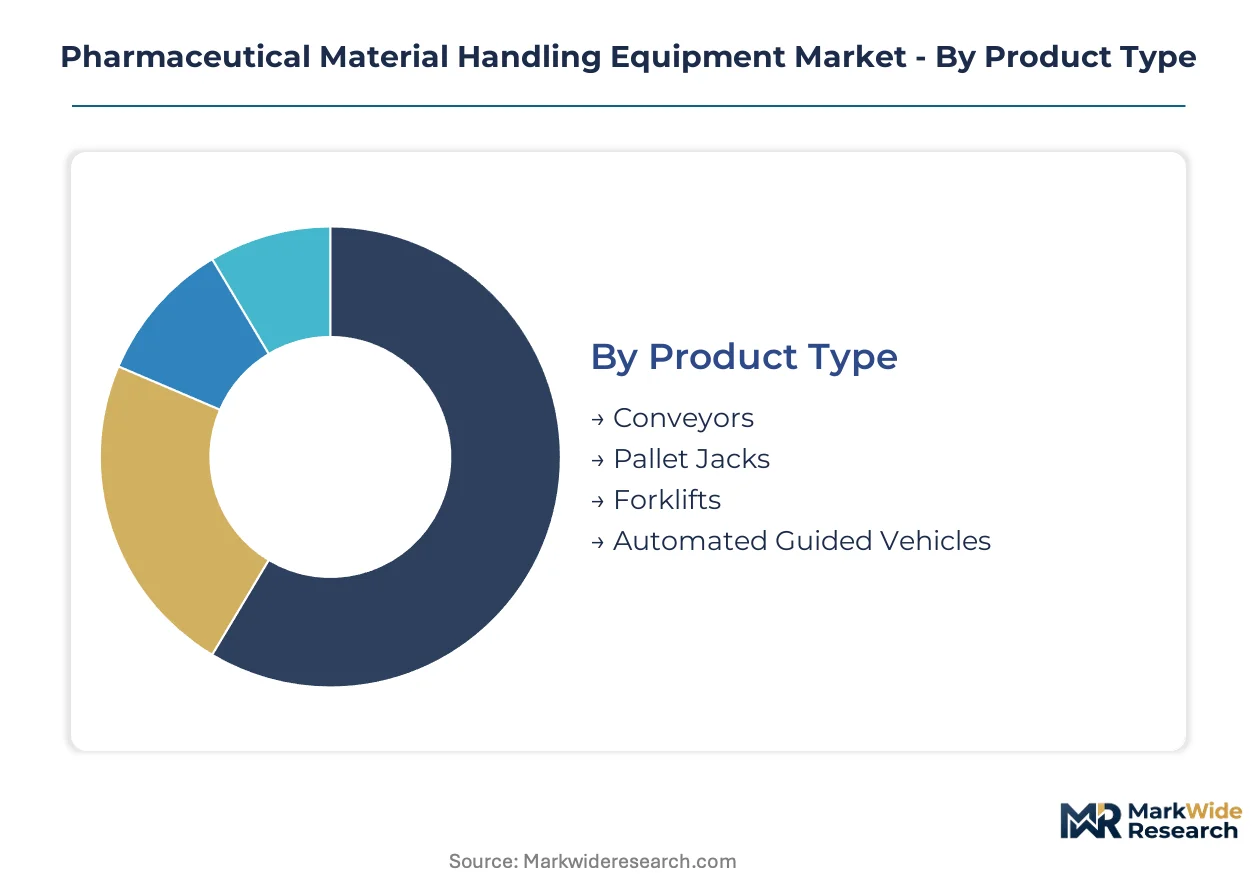
Segmentation in pharmaceutical material handling equipment reveals distinct procurement patterns across regulated manufacturing environments. Equipment specifications diverge sharply between sterile fill-finish operations and ambient distribution centers, with validation requirements and surface finish standards driving category-specific sourcing decisions.
Product Type:
Channel mix varies by contamination risk tier, with cleanroom-grade equipment flowing through specialized pharmaceutical engineering distributors while standard warehouse equipment moves through industrial supply channels.
- Conveyors:Stainless steel belt and roller systems engineered with Ra 0.4-0.8 micrometer surface finishes to prevent microbial adhesion in Grade A/B environments. German pharmaceutical exporters are modernizing distribution centers with these systems to meet export certification requirements for high-potency compounds. FDA Annex 1 sterility mandates are accelerating replacement cycles for open-conveyor architectures across European aseptic facilities.
- Automated Guided Vehicles:Battery-powered mobile platforms equipped with validated temperature control systems for cryogenic biologics transport. mRNA and cell therapy manufacturing sites in Switzerland and Germany are deploying these units to maintain cold-chain integrity during intralogistics operations. LIDAR navigation and HEPA filtration variants are fragmenting supplier hierarchies by enabling software-centric competition.
- Pallet Jacks:Manual and electric lift equipment with corrosion-resistant coatings for GMP warehouse environments.
- Forklifts:Temperature-validated fleets with stainless steel mast cladding for pharmaceutical distribution centers.
Conveyors dominate installed base across sterile manufacturing corridors. Automated Guided Vehicles are where expansion concentrates as biologics facilities pursue lights-out intralogistics.
End User:
Cost tier segmentation separates capital-intensive greenfield biologics facilities from retrofit-focused contract manufacturers with constrained automation budgets.
- Pharmaceutical Manufacturers:Integrated biologics and small-molecule producers operating captive fill-finish and packaging lines. These facilities prioritize containment-grade conveying systems and isolator-integrated handling modules to satisfy EMA Annex 1 continuous particulate monitoring mandates. Swiss and German manufacturing clusters exhibit the most intensive demand for pre-validated platform configurations.
- Contract Packaging Organizations:Multi-product service providers handling diverse batch sizes and vial formats. Small-batch CMOs represent underpenetrated demand for collaborative robotic arms that accommodate product diversity without line changeover downtime. Procurement patterns here favor flexible manual handling solutions over fixed automation.
- Wholesale Distributors:Temperature-validated warehouse operators managing regional pharmaceutical distribution networks.
- Research Laboratories:Preclinical and clinical trial material handling with emphasis on traceability and chain-of-custody documentation.
Pharmaceutical Manufacturers command the premium equipment tier. Contract Packaging Organizations are where automation vendors are gaining share fastest through collaborative robotics.
Technology:
Application maturity separates established automation platforms from emerging IoT architectures still navigating validation protocol development.
- Robotic Systems:Collaborative and industrial arms executing vial handling, capping, and labeling at speeds exceeding 400 units per minute in aseptic filling lines. Aseptic filling line OEMs are absorbing compliance costs for isolator-integrated handling modules into turnkey system pricing. Technical limitations in achieving Grade A air classification within restricted access barrier systems constrain deployment scope.
- IoT Integration:Sensor networks and fleet management software enabling predictive maintenance and energy optimization through digital twin convergence with building management systems. Multi-product facilities in Germany are piloting these architectures for AGV fleet coordination. Validation documentation burden extends commissioning timelines.
- Automation Solutions:Programmable logic controller-driven conveying and sorting systems with established IQ/OQ/PQ protocols.
- Manual Handling Solutions:Ergonomic carts, lifts, and workstations retaining substantial installed base where batch diversity resists full automation economics.
Robotic Systems capture concentrated margin pools in aseptic applications. IoT Integration is expanding most quickly as facilities seek operational visibility across multi-product campaigns.
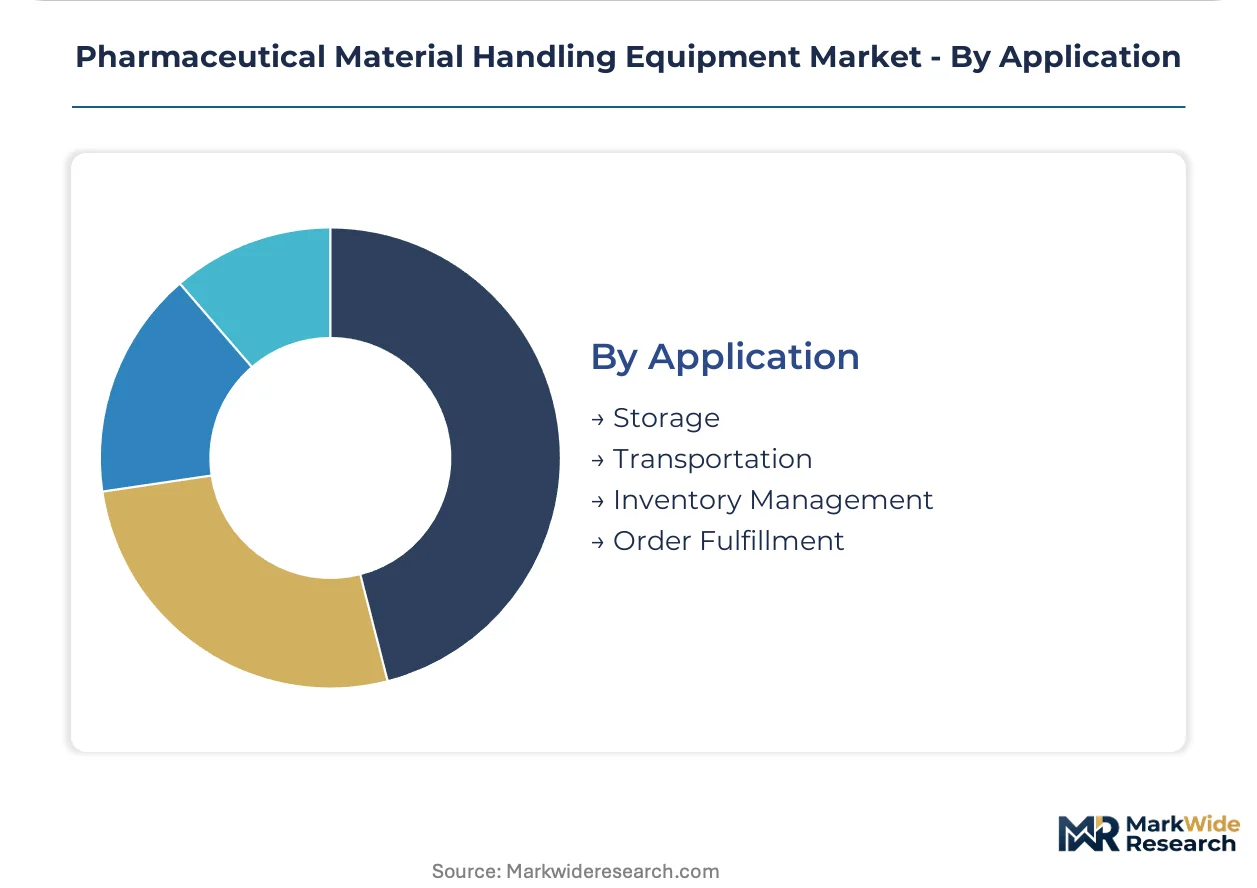
Application:
Volume concentration clusters in storage and transportation functions, with inventory management and order fulfillment representing higher-margin software-augmented opportunities.
- Storage:Automated vertical lift modules and racking systems maintaining environmental parameters for temperature-sensitive APIs and finished goods. Cold-chain biologics expansion is driving demand for cryogenic-capable storage retrieval systems with validated temperature mapping.
- Transportation:Intralogistics movement between manufacturing suites, warehouse zones, and shipping docks. AGV deployments with continuous particulate monitoring are displacing manual cart transport in Grade B corridors.
- Inventory Management:Real-time location systems and warehouse management software integration for batch traceability compliance.
- Order Fulfillment:Pick-and-pack automation for serialized pharmaceutical distribution with aggregation and verification requirements.
Storage commands the largest equipment footprint. Order Fulfillment is where technology suppliers are capturing steepest expansion trajectory through serialization compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's Annex 1 revision anchors European demand for containment-grade conveying systems, while FDA enforcement of 21 CFR Part 211 shapes validation protocols across North American sterile manufacturing sites. Biologics cold-chain expansion and single-use technology adoption are fragmenting material handling architectures in Switzerland and Germany.
Germany
Pharmaceutical exporters are modernizing distribution centers with Ra 0.4 micrometer surface finish conveyors to meet export certification requirements for high-potency compounds. The country's national pharmaceutical regulator enforces stringent GMP standards that accelerate replacement cycles for open-conveyor systems. The Rhine-Main manufacturing cluster around Frankfurt exhibits intensive demand for pre-validated platform configurations as CDMO competition for biologics contracts intensifies.
United States
mRNA and cell therapy manufacturing sites are deploying automated guided vehicles with validated temperature control to maintain cryogenic conditions during intralogistics operations. FDA enforcement of 21 CFR Part 211 cGMP requirements shapes equipment validation protocols and extends commissioning timelines. The Greater Boston biotech corridor represents concentrated demand for lights-out intralogistics in Grade A/B environments.
Switzerland
Swissmedic regulations mandate continuous particulate monitoring during material transfer operations, directly stimulating demand for sealed conveyor enclosures and isolator-integrated handling modules. The Basel pharmaceutical manufacturing cluster exhibits the most intensive procurement of containment-grade conveying systems for aseptic filling lines. Contract manufacturers here prioritize collaborative robotic arms that accommodate product diversity without line changeover downtime.
India
The country's production-linked incentive scheme for pharmaceutical manufacturing is attracting greenfield facilities requiring GMP-validated material handling infrastructure. CDSCO oversight of sterile manufacturing standards pressures facilities to upgrade containment-grade conveying systems. The Maharashtra pharmaceutical corridor around Mumbai and Pune is where automation vendors are gaining share fastest through collaborative robotics for small-batch CMOs.
Japan
PMDA guidelines on sterile manufacturing drive demand for 316L stainless steel handling systems with surface finishes below 0.8 micrometers Ra. METI industrial policy supports domestic equipment suppliers in cleanroom conveyor engineering for high-containment installations. The Kanto region around Tokyo anchors demand for AGV fleet management systems integrated with building management platforms.
Pharmaceutical Material Handling Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pharmaceutical material handling equipment. Japanese and German conglomerates with captive automation divisions control premium-tier supply for sterile manufacturing corridors. Three archetypes dominate: cleanroom conveyor specialists, AGV navigation software developers, and stainless steel fabrication houses with validation expertise. Competitive moves concentrate on backward integration into battery systems and sensor networks, plus pre-validated platform configurations that compress commissioning timelines.
Among Japanese material handling conglomerates, Daifuku Co., Ltd. and Toyota Industries Corporation exemplify the integrated-leader archetype through in-house production of navigation software and battery systems. German engineering groups KION Group AG and Jungheinrich AG occupy positions within the European pallet jack and forklift tier for GMP-certified warehouses. AZO GmbH & Co. KG represents the specialist fabricator category with expertise in contained transfer systems for active pharmaceutical ingredients.
| Leading Market Players |
|---|
| Tote Systems International |
| Paul N. Gardner |
| AZO GmbH & Co. KG |
| David Round Company |
| Daifuku Co., Ltd. |
| Toyota Industries Corporation |
| KION Group AG |
| Jungheinrich AG |
| Crown Equipment Corporation |
| Others |
Value Network & Pricing Analysis
Single-use technology substitution for fixed stainless steel infrastructure is simultaneously shifting supply geography toward modular cleanroom fabricators in Switzerland and Germany while compressing pricing power for traditional conveyor OEMs locked into validation-heavy project economics. This substitution dynamic rewards agile suppliers with reconfigurable product architectures and penalizes capital-intensive incumbents dependent on long-commissioning turnkey systems.
Pricing Analysis
German and Swiss buyers pay 15-25% premiums over Indian and Southeast Asian procurement for identical 316L stainless steel conveyors due to embedded validation documentation and local regulatory compliance support. Pricing stratifies across containment-grade isolator-integrated systems, standard cleanroom conveyors, and economy warehouse equipment without surface finish certification. Cost compression in mid-tier automation is intensifying as contract manufacturers consolidate purchasing through group procurement organizations. Small-batch CMOs exhibit highest price sensitivity due to capital constraints, while integrated biologics manufacturers prioritize total cost of ownership over upfront equipment spend.
Supply Chain Analysis
Strategic stockpiling of nickel and 316L stainless steel raw materials dominates inventory strategy among German and Japanese fabrication houses, insulating against commodity volatility that would otherwise disrupt validation timelines. Supply concentrates in Germany, Japan, and Switzerland for precision-finished conveying systems, while China and India anchor component sourcing for standard warehouse equipment. Fabrication draws from specialized steel mills in Austria and Finland, HEPA filtration suppliers in Germany, and servo motor producers in Japan. Single-source vulnerability in nickel supply from Indonesia and Russia exposes margin stability. Distribution runs through pharmaceutical engineering distributors for cleanroom-grade equipment and industrial supply channels for standard warehouse fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German and Swiss CDMOs consolidate through merger activity, compressing vendor margins and demanding pre-validated platform configurations that accelerate facility commissioning timelines.
For Market Incumbents: Compound defensive positioning through backward integration into battery systems and sensor networks to capture recurring revenue streams beyond equipment sale. Deepen captive supply of AGV navigation software to neutralize emerging software-centric entrants. Prioritize certification investment in EMA Annex 1 continuous particulate monitoring compliance to maintain access to European sterile manufacturing corridors. For New Entrants and Emerging Players: Post-installation validation support services represent the most significant service-layer gap where incumbent OEMs under-serve small-batch CMOs with constrained technical staffing. Target India's Maharashtra pharmaceutical corridor where PLI scheme greenfield facilities require GMP-validated infrastructure without legacy vendor relationships. Lead with collaborative robotic arms for contract packaging applications where product diversity resists fixed automation economics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialist fabricators with isolator engineering expertise over diversified industrial conglomerates. Long-term viability hinges on exposure to biologics cold-chain expansion rather than small-molecule distribution automation. Watch FDA enforcement intensity for 21 CFR Part 211 violations as the inflection signal indicating replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Validated Platform Development | Compresses IQ/OQ/PQ timelines for German CDMOs competing for biologics contracts. |
| Isolator-Integrated Handling Module Engineering | Addresses EMA Annex 1 continuous particulate monitoring mandates for Swiss aseptic facilities. |
| AGV Fleet Management Software Integration | Enables digital twin convergence with building management systems in multi-product facilities. |
| 316L Stainless Steel Backward Integration | Insulates margin stability against nickel price volatility from Indonesian supply concentration. |
| Collaborative Robotics for Small-Batch CMOs | Captures underpenetrated demand in India's Maharashtra pharmaceutical corridor. |
Research Methodology
Cross-validation between primary interviews with pharmaceutical manufacturing executives, cleanroom engineering directors, and regulatory affairs specialists and secondary validation through FDA 483 observation databases, EMA inspection reports, and ISO 14644 certification registries anchors the qualitative findings. Bottom-up triangulation aggregates equipment procurement data from German, Swiss, and Indian pharmaceutical clusters while top-down verification cross-checks against disclosed capital expenditure patterns in SEC filings and production-linked incentive scheme disclosures.
Sensitivity analysis around nickel price volatility, certified technician availability, and Annex 1 enforcement intensity frames the forecast uncertainty bounds across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology tier, and application function alongside regional regulatory cluster differentiation. CAGRs derive from equipment replacement cycle analysis, facility expansion pipelines, and compliance-driven upgrade mandates. Industry-specific inputs encompass 316L steel lead times, validation protocol duration benchmarks, and AGV commissioning timeline standards.
Forecasts assume regulatory continuity in FDA 21 CFR Part 211, EMA Annex 1, and Swissmedic sterile manufacturing oversight; material policy shifts would require re-modeling. Revision becomes warranted when nickel price volatility crosses thresholds that compress equipment supplier margins beyond sustainable validation service capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Industrial Pulley Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Hook Loader Market