
 Fabric Air Ducts Market | 2026-2036
Fabric Air Ducts Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Air Ducts Market Analysis
Chinese textile manufacturers is hardening supply chains for permeable membrane materials used in fabric duct production. DuctSox Corporation leverages vertical manufacturing integration across North American distribution networks. PRIHODA s.r.o. anchors European market presence through specialized textile engineering capabilities in the Czech Republic. FabricAir differentiates via proprietary permeability control technologies for precision air distribution in commercial environments.
Fabric air ducts constitute engineered textile conduits manufactured from woven polyester, micro-perforated membranes, or coated fiberglass composites, typically rated for air velocities between 1,500 and 2,500 feet per minute and operating pressures up to 4 inches water gauge. These systems distribute conditioned air through controlled surface permeability or targeted orifice patterns, replacing rigid galvanized steel or aluminum ductwork in applications requiring uniform temperature stratification, condensation prevention, or acoustic attenuation. Flexible duct configurations dominate current procurement volumes due to lower installation labor requirements and adaptability to irregular building geometries. Insulated duct variants capture expanding margin pools in cold storage and pharmaceutical processing facilities where thermal bridging prevention commands specification priority. Overhead installation types sustain widest deployment across commercial building retrofits where ceiling plenum access limits rigid duct placement.
EPA ventilation efficiency guidelines and OSHA indoor air quality standards shape product certification requirements and installation compliance protocols in the United States. REACH chemical safety frameworks and EU F-Gas Regulation restrict halogenated blowing agents in insulated duct thermal layers, redirecting specification toward water-blown or bio-based foam alternatives. Stakeholders must monitor evolving MEP contractor procurement criteria as building electrification mandates and net-zero certification schemes recalibrate HVAC system lifecycle cost models.
Market Dynamics
EU F-Gas Regulation is compressing HVAC upgrade cycles across pharmaceutical and food processing facilities, forcing specification shifts from metal to textile-based air distribution systems that eliminate thermal bridging and reduce refrigerant charge requirements.
Growth Catalysts
- REACH chemical safety frameworks:Restrictions on halogenated blowing agents in insulated duct thermal layers redirect procurement toward water-blown foam alternatives, expanding addressable market for compliant fabric systems.
- Pharmaceutical cleanrooms:Germany's sterile manufacturing sector drives specification priority for precision air distribution with uniform temperature stratification and condensation prevention.
- China's eastern manufacturing corridor:Food processing plants in Jiangsu and Zhejiang provinces are replacing galvanized steel ductwork with textile-based ventilation to reduce installation labor and adapt to irregular geometries.
Market Restraints
- Polyester fiber input volatility:Woven membrane manufacturers face margin pressure from petrochemical feedstock price swings that compress project bidding flexibility.
- Chinese textile supply concentration:Permeable membrane hardening exposes downstream fabricators to single-source risk for specialized woven substrates.
- Pressure rating limitations:Operating envelopes capped at 4 inches water gauge exclude fabric ducts from high-velocity industrial process applications served by spiral metal systems.
Strategic Opportunities
- US cold storage expansion:Insulated duct variants with bio-based foam thermal layers capture specification priority in refrigerated warehouse construction driven by e-commerce fulfillment network growth.
- Building electrification mandates:Net-zero certification schemes recalibrate lifecycle cost models toward fabric systems with lower embodied carbon and reduced fan energy demand.
- Acoustic attenuation convergence:Integration of micro-perforated membranes with active noise cancellation opens specification in open-plan commercial retrofits where ceiling plenum access limits rigid placement.
Industry Challenges
- Textile engineering skill scarcity:MEP contractors lack training in permeability-controlled installation protocols, creating field performance gaps and warranty disputes.
- Multi-standard certification timelines:Simultaneous EPA ventilation efficiency and OSHA indoor air quality compliance extends product approval cycles for new membrane formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Air Ducts Market |
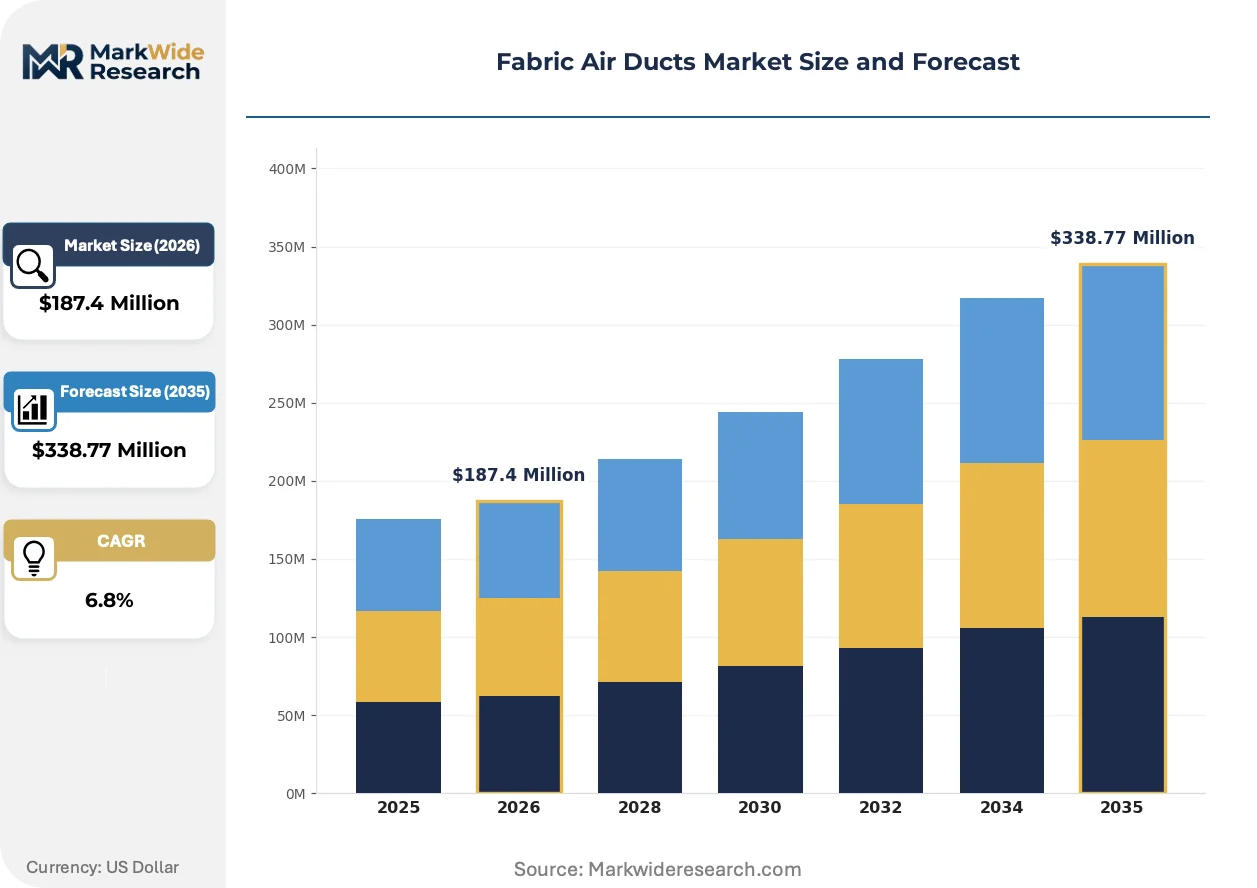
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Ducts, Insulated Ducts, Non-Insulated Ducts, Noise Reduction Ducts Installation Type: Overhead, Underfloor, Wall Mounted, Modular End User: Commercial Buildings, Industrial Facilities, Residential Houses, Warehouses Application: Heating, Ventilation, Air Conditioning, Air Distribution |
| Companies Covered | DuctSox Corporation, AIRMAX International, PRIHODA s.r.o., Clever Engineering (Kent) Ltd, Hurlstones Northern Ltd, Durkeesox, FabricAir, Lindab, KE Fibertec NA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Air Ducts Market Emerging Trajectories
Active reshaping of this market centers on material science advances in membrane permeability control, regulatory chemistry restrictions on thermal insulation, and procurement recalibration around lifecycle carbon accounting rather than first-cost bidding.
Micro-perforated polyester composites with calibrated orifice density are absorbing specification share in precision air distribution applications. Pharmaceutical cleanroom operators in Germany and the Netherlands are adopting these systems at accelerated pace to meet EU F-Gas refrigerant phase-down schedules. The technology is absorbing margin pools previously captured by aluminum spiral ductwork in temperature-critical process environments.
EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents are forcing reformulation of insulated duct thermal layers across European supply chains. Manufacturers must recertify products under REACH chemical safety documentation requirements, compressing product development timelines. Cold storage and pharmaceutical processing facilities in France and Belgium are responding by specifying water-blown foam alternatives with equivalent R-value performance.
Lifecycle carbon accounting is displacing first-cost procurement criteria among institutional buyers and net-zero-certified developers. Engineering procurement construction firms are unbundling duct system specifications from bundled HVAC packages to optimize embodied carbon scores. This behavioral shift is most visible in Nordic markets where CSRD reporting mandates require Scope 3 supply chain disclosure for commercial building portfolios.
Fabric Air Ducts Market Segmentation
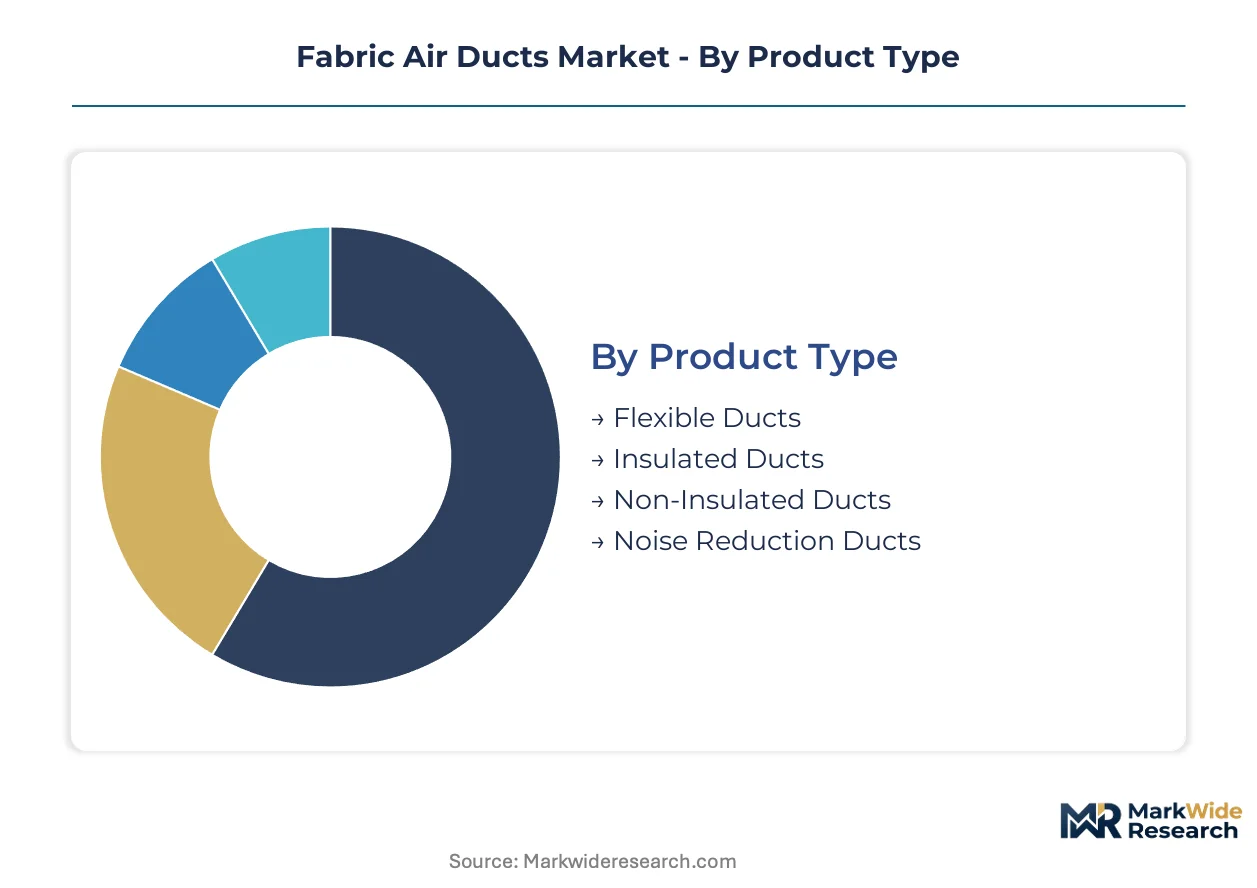
Fabric air duct procurement patterns diverge sharply across installation constraints, thermal performance requirements, and end-use regulatory exposure. Specification priorities in pharmaceutical cleanrooms differ fundamentally from those in e-commerce fulfillment warehouses, creating distinct margin pools within each segment cluster.
Product Type:
Volume procurement concentrates in flexible configurations, while premium pricing attaches to thermal and acoustic performance tiers.
- Flexible Ducts:Woven polyester or micro-perforated membrane conduits rated for 1,500-2,500 feet per minute air velocity dominate current procurement volumes due to reduced installation labor and adaptability to irregular ceiling plenums. Demand concentrates in China's eastern manufacturing corridor where food processing plants in Jiangsu and Zhejiang provinces are retiring galvanized steel systems.
- Insulated Ducts:Coated fiberglass composites with water-blown or bio-based foam thermal layers command specification priority in cold storage and pharmaceutical processing where thermal bridging prevention outweighs first-cost considerations. REACH chemical safety frameworks and EU F-Gas Regulation restrictions on halogenated blowing agents are redirecting procurement toward compliant variants.
- Non-Insulated Ducts:Standard woven polyester configurations serve cost-sensitive commercial retrofits with moderate temperature differential requirements.
- Noise Reduction Ducts:Micro-perforated membranes with acoustic attenuation properties target open-plan commercial environments where OSHA indoor air quality standards intersect with occupant comfort specifications.
Today's leader: Flexible Ducts. Tomorrow's challenger: Insulated Ducts.
Installation Type:
Overhead mounting captures the widest deployment, though underfloor and modular systems are gaining specification share in specialized applications.
- Overhead:Ceiling plenum suspension systems sustain broadest adoption across commercial building retrofits where rigid duct placement faces access constraints.
- Underfloor:Raised-floor air distribution configurations serve data centers and cleanroom environments requiring precise temperature stratification from below.
- Wall Mounted:Vertical surface installation accommodates perimeter heating applications in industrial facilities with high bay clearances.
- Modular:Reconfigurable segment systems target temporary structures and exhibition halls requiring rapid deployment and relocation cycles.
Overhead installation retains volume dominance, yet modular configurations are climbing the fastest as event infrastructure and flexible workspace markets expand.
End User:
Commercial buildings generate baseline demand, while industrial facilities and warehouses drive technology-specific premium tiers.
- Commercial Buildings:Office, retail, and institutional environments specify fabric ducts for acoustic attenuation and uniform air distribution in open-plan configurations.
- Industrial Facilities:Pharmaceutical cleanrooms in Germany and food processing plants across China's eastern corridor demand precision permeability control and condensation prevention.
- Residential Houses:Limited penetration in high-end custom construction where aesthetic concealment and quiet operation justify premium positioning.
- Warehouses:US cold storage expansion driven by e-commerce fulfillment network growth is absorbing insulated duct variants with bio-based foam thermal layers.
Industrial Facilities anchor premium specification, with Warehouses representing the steepest expansion trajectory on fulfillment infrastructure buildouts.
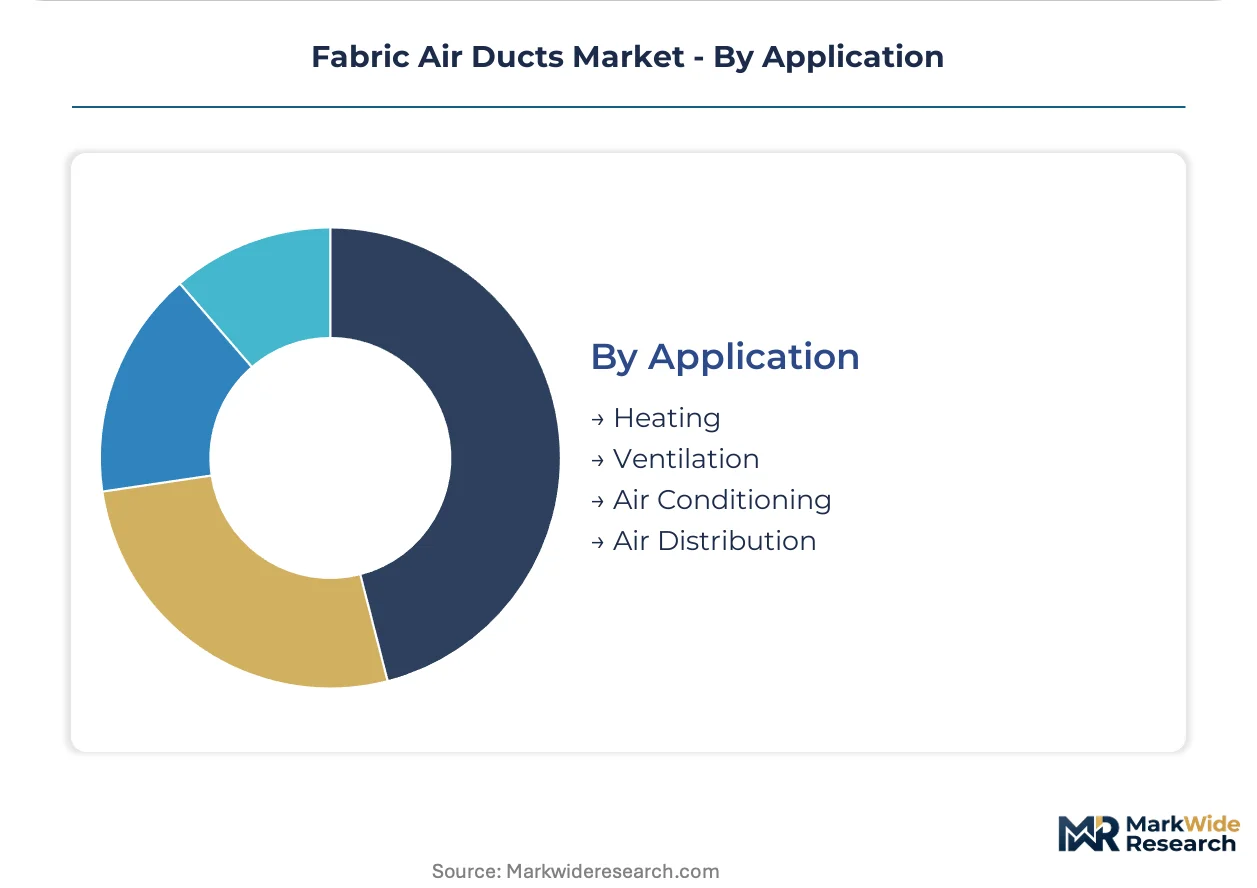
Application:
Air distribution and ventilation functions dominate procurement, though heating and air conditioning integration shapes material selection criteria.
- Heating:Low-temperature radiant and warm air applications require permeability-calibrated membranes to prevent condensation at supply points.
- Ventilation:Fresh air delivery and exhaust functions constitute the largest addressable volume, with EPA ventilation efficiency guidelines shaping product certification requirements.
- Air Conditioning:Cooling distribution applications in pharmaceutical and food processing facilities prioritize uniform temperature stratification to meet EU F-Gas Regulation compliance timelines.
- Air Distribution:General supply and return functions span all end-use categories, with micro-perforated composites absorbing specification share from aluminum spiral ductwork in temperature-critical process environments.
Ventilation commands current volume leadership, while Air Conditioning applications are gaining share fastest on HVAC efficiency upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with lower compliance costs for REACH chemical safety documentation, while EU F-Gas Regulation accelerates specification upgrades in high-compliance markets.
Germany
Pharmaceutical cleanroom operators in Baden-Württemberg and Bavaria are absorbing micro-perforated membrane systems to meet EU F-Gas refrigerant phase-down schedules. ECHA enforcement of REACH chemical safety frameworks restricts halogenated blowing agents in insulated duct thermal layers. The Rhine-Main cluster around Frankfurt anchors sterile manufacturing demand for precision air distribution with condensation prevention.
China
Food processing plants across Jiangsu and Zhejiang provinces are retiring galvanized steel ductwork for textile-based ventilation with reduced installation labor. MEE enforcement of dual carbon goals pressures industrial facilities to lower embodied carbon in HVAC retrofits. The Yangtze River Delta manufacturing corridor concentrates procurement volumes for permeable membrane materials.
United States
E-commerce fulfillment network expansion is driving insulated duct specification in refrigerated warehouse construction across the Midwest and Southeast. EPA ventilation efficiency guidelines and OSHA indoor air quality standards shape product certification requirements for new membrane formulations. The Dallas-Fort Worth logistics cluster anchors cold storage buildouts absorbing bio-based foam thermal layers.
Czech Republic
Specialized textile engineering capabilities in the Plzeň and South Moravian regions support EU-compliant fabric duct fabrication for pharmaceutical and food processing export markets. REACH documentation requirements for water-blown foam alternatives compress product development timelines for regional manufacturers. The Ostrava industrial zone channels fabricated systems toward German and Austrian cleanroom operators.
Netherlands
CSRD reporting mandates requiring Scope 3 supply chain disclosure are recalibrating procurement criteria among institutional buyers in the Randstad commercial building portfolio. EU Green Deal building electrification directives accelerate HVAC lifecycle cost modeling toward fabric systems with reduced fan energy demand. The Eindhoven high-tech campus cluster specifies precision permeability control for semiconductor cleanroom environments.
Fabric Air Ducts Market Vendor Landscape
North American producers anchor one tier; European specialists hold differentiated positions in precision textile engineering. The vendor base organizes around three strategic archetypes: vertically integrated membrane manufacturers, regional installation specialists, and technology licensors with proprietary permeability control. Capacity expansion and geographic licensing partnerships constitute the dominant competitive moves as players defend margin position against polyester feedstock volatility.
Among North American fabricators, DuctSox Corporation exemplifies the integrated-manufacturing archetype with captive distribution network control. PRIHODA s.r.o. occupies a position representing European textile engineering specialization anchored in Czech production capabilities. FabricAir sits within the technology-differentiation tier, its market presence tied to proprietary permeability control positioning for precision air distribution applications. These three company structures illustrate how competitive positioning fragments across manufacturing integration depth, regional engineering heritage, and intellectual property concentration.
| Leading Market Players |
|---|
| DuctSox Corporation |
| AIRMAX International |
| PRIHODA s.r.o. |
| Clever Engineering (Kent) Ltd |
| Hurlstones Northern Ltd |
| Durkeesox |
| FabricAir |
| Lindab |
| KE Fibertec NA |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates qualified supply access and premium-tier pricing power, restricting membrane manufacturers to REACH-certified water-blown foam formulations while rewarding certified fabricators with specification priority in pharmaceutical cleanrooms.
Pricing Analysis
Distributor margins compress pricing transparency across European supply chains, with three-tier pricing structure across premium, standard, and economy levels separating REACH-compliant insulated ducts from basic woven polyester configurations. Price differentiation hinges on certification grade and volume scale, with pharmaceutical cleanroom operators showing lowest price sensitivity due to regulatory compliance mandates. Cost compression in standard flexible ducts is intensifying because Chinese textile manufacturers are hardening supply chains for permeable membrane materials.
Supply Chain Analysis
REACH documentation requirements gate qualified supplier status, with permeable membrane production drawing from China, Czech Republic, and Germany for specialized woven substrates and textile engineering capabilities. Raw material dependencies rest on petrochemical-derived polyester fibers, water-blown foam thermal layers, and micro-perforated membrane composites. Single-source vulnerability concentrates in Chinese woven substrate supply for downstream fabricators. Distribution runs through MEP contractor networks and specialized HVAC distributors serving commercial and industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fabric Air Ducts Market functions as a stable compounder, with EU F-Gas Regulation and building electrification mandates driving steady replacement cycles across pharmaceutical and food processing facilities.
For Market Incumbents: Deepen backward integration into permeable membrane manufacturing to offset polyester fiber input volatility and Chinese supply concentration risk. PRIHODA s.r.o. and DuctSox Corporation demonstrate how captive textile engineering capabilities defend margin position against emerging regional fabricators. Certification investment in REACH-compliant water-blown foam formulations anchors specification priority in EU pharmaceutical cleanrooms. For New Entrants and Emerging Players: Begin with modular duct configurations targeting temporary structures and exhibition halls, where rapid deployment cycles and lower certification barriers create accessible entry points. The US cold storage expansion driven by e-commerce fulfillment networks offers the most penetrable geography, with insulated duct variants commanding premium positioning. A go-to-market angle emphasizing bio-based foam thermal layers and embodied carbon reduction resonates with net-zero-certified developers. For Investors and Strategic Acquirers: Roll-up economics work for regional installation specialists with captive MEP contractor relationships because procurement is shifting toward lifecycle cost modeling and away from first-cost bidding. The 5-10 year viability window favors platforms consolidating fragmented European textile engineering capabilities. Acquisition target archetype: Czech or German fabricators with REACH documentation infrastructure and existing pharmaceutical cleanroom references. The signal to watch is CSRD Scope 3 disclosure mandates accelerating among Nordic institutional buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive supply of woven polyester substrates insulates margin from petrochemical volatility and Chinese concentration. |
| REACH-Compliant Foam Reformulation | Water-blown thermal layer certification unlocks specification priority in EU pharmaceutical cleanrooms facing F-Gas deadlines. |
| Modular Duct System Development | Reconfigurable segments capture event infrastructure and flexible workspace markets with rapid deployment requirements. |
| Lifecycle Carbon Accounting Integration | Embodied carbon scoring aligns with CSRD reporting mandates among Nordic commercial building portfolios. |
| Acoustic Attenuation Technology Licensing | Micro-perforated membrane patents open specification in open-plan commercial retrofits with ceiling plenum constraints. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MEP contractors, pharmaceutical facility engineers, textile manufacturing specialists, and HVAC procurement managers with secondary validation against customs trade data, EPA ventilation efficiency guidelines, ECHA REACH documentation databases, and EU F-Gas Regulation implementation reports. Bottom-up project pipeline analysis and top-down sectoral spend estimates were triangulated to anchor volume and value outputs.
Segment-weighting approaches distributed projections across flexible, insulated, non-insulated, and noise reduction duct categories, with installation type and end-user dimensions layered to capture procurement pattern divergence. CAGRs were derived from fitted growth curves against historical replacement cycle data and regulatory compliance timeline acceleration. Industry-specific forecast inputs included EU F-Gas refrigerant phase-down schedules and US cold storage construction permits across e-commerce fulfillment corridors.
Caveats apply where polyester fiber commodity price spikes, REACH enforcement intensity variations, or MEP contractor training bottlenecks could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance timeline adherence and substitution elasticity between textile and metal ductwork. A model refresh is warranted upon material change in EU Green Deal building electrification directive implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market