
 Compressor Controllers Market | 2026-2036
Compressor Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Compressor Controllers Market Analytics
The EU F-Gas Regulation is broadening the addressable market for compressor controllers by mandating tighter leak detection and energy efficiency thresholds across refrigeration and HVAC installations. Emerson Electric leverages its vertical integration into compressor hardware and control electronics to sustain pricing power in European retrofit cycles. Kaeser Kompressoren anchors its position through German-engineered controller integration with rotary screw systems. Atlas Copco competes on manufacturing scale, operating one of the largest global networks for industrial compressor and controller distribution.
Compressor controllers are electronic or electromechanical devices that regulate compressor motor speed, discharge pressure, and operating cycles through algorithms ranging from simple on/off logic to adaptive PID loops, typically interfacing with pressure transducers and temperature sensors via 4-20 mA or digital fieldbus protocols. Their primary commercial purpose is to minimize energy consumption, reduce mechanical wear, and maintain process stability in continuous or intermittent compressed air and refrigeration duty. Variable Frequency Drives dominate the product type landscape due to their proven kilowatt-hour savings in centrifugal and rotary screw applications, while Adaptive Control methods are gaining traction in oil and gas processing where load profiles fluctuate unpredictably and precise surge avoidance protects capital equipment.
The US Department of Energy enforces compressor efficiency test procedures that shape minimum performance standards and effectively filter low-tier controller architectures from federal procurement channels, while China's GB standards and MIIT efficiency directives enforce domestic certification requirements that foreign suppliers must navigate for market access. ISO 5389 and ISO 1217 provide international baselines for performance measurement that reduce cross-border technical friction but still allow regional regulators to layer additional stringency. Stakeholders must monitor how evolving carbon border mechanisms and building energy codes recalibrate the business case for controller upgrades versus full compressor replacement.
Market Dynamics
The EU F-Gas Regulation and comparable efficiency mandates in North America are forcing accelerated controller replacement cycles, compressing the payback period for Variable Frequency Drive upgrades from five years to under three in commercial HVAC installations.
Growth Catalysts
- EU F-Gas Regulation:Mandates for tighter leak detection and energy efficiency thresholds are expanding the retrofit market for advanced compressor controllers in European refrigeration and HVAC systems.
- Industrial automation investments in China:Domestic manufacturing expansion and smart factory initiatives are pulling in sophisticated compressor control systems for process reliability.
- Variable Frequency Drives:Proven kilowatt-hour savings in centrifugal and rotary screw applications are driving replacement demand across energy-intensive industries.
Market Restraints
- Semiconductor supply concentration:Controller production depends on specialized power electronics sourced from a concentrated East Asian supplier base, creating input volatility.
- Legacy system incompatibility:Analog 4-20 mA infrastructure in installed industrial bases limits plug-and-play upgrade paths for digital fieldbus controllers.
- Technical skill gaps:PID tuning and adaptive algorithm configuration require specialized commissioning expertise that remains scarce in secondary industrial markets.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for industrial machinery are creating localized demand for cost-optimized controller platforms.
- Surge avoidance in oil and gas:Adaptive Control methods for unpredictable load profiles represent an underpenetrated application with high equipment protection value.
- Cloud-based predictive maintenance:Convergence of edge computing and compressor telemetry is enabling subscription-based controller optimization services.
Industry Challenges
- Multi-protocol integration complexity:Fieldbus fragmentation across Modbus, PROFINET, and EtherNet/IP standards forces costly gateway development for universal controller compatibility.
- Certification timeline compression:China's GB standards and MIIT efficiency directives require domestic recertification that delays foreign supplier market entry by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressor Controllers Market |
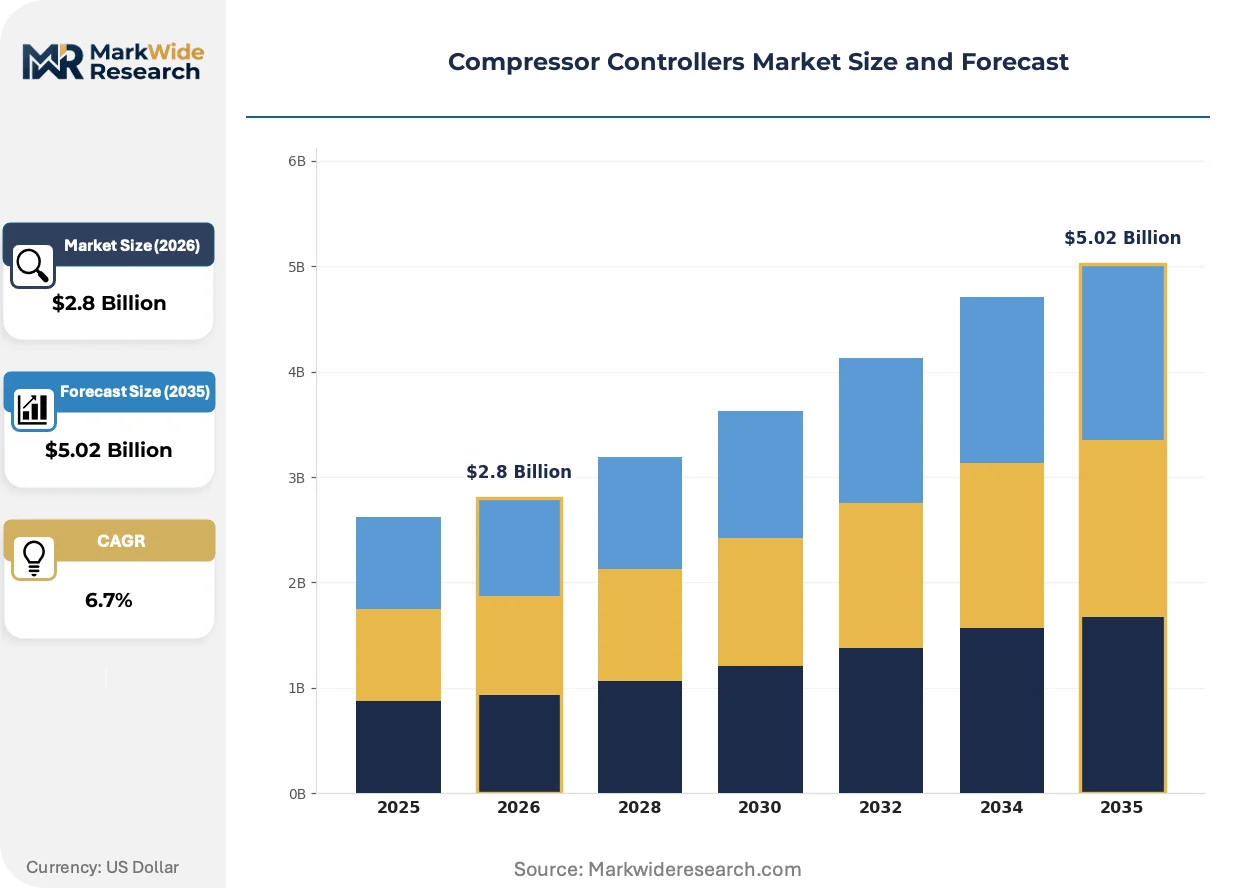
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Controllers, Variable Frequency Drives, Microcontrollers, Programmable Logic Controllers Installation Type: Indoor, Outdoor, Wall-Mounted, Rack-Mounted End User: Manufacturing, Oil & Gas, HVAC, Agriculture Control Method: On/Off Control, Proportional Control, PID Control, Adaptive Control |
| Companies Covered | Emerson Electric, Kaeser Kompressoren, Atlas Copco, Rockwell Automation, Gardner Denver, Ingersoll Rand, Danfoss, Schneider Electric, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressor Controllers Market Evolving Landscape
Digital twin technology and edge analytics are converging with compressor hardware to enable real-time performance optimization. Three developments are restructuring competitive positioning and customer value capture.
Model predictive control algorithms are converging with compressor motor drives to anticipate load fluctuations before they occur. Oil and gas processing facilities in the US Gulf Coast are piloting these systems for centrifugal compressor trains. The technology is converging with traditional PID architectures to compress the performance gap between standard and premium controller tiers.
REACH substance restrictions and RoHS compliance deadlines are forcing redesigns of controller printed circuit boards and power module assemblies. Manufacturers must eliminate specified flame retardants and heavy metals from production lines serving European customers. Industrial compressor OEMs are responding by dual-sourcing European-certified and legacy controller variants to maintain supply continuity.
Energy-as-a-service contracting is displacing traditional equipment purchase models in commercial building portfolios. Facility management firms are bundling controller upgrades into performance guarantees rather than capitalizing hardware separately. This shift is most visible in US federal buildings where the IRA efficiency incentives favor operational expenditure structures over upfront procurement.
Compressor Controllers Market Segmentation
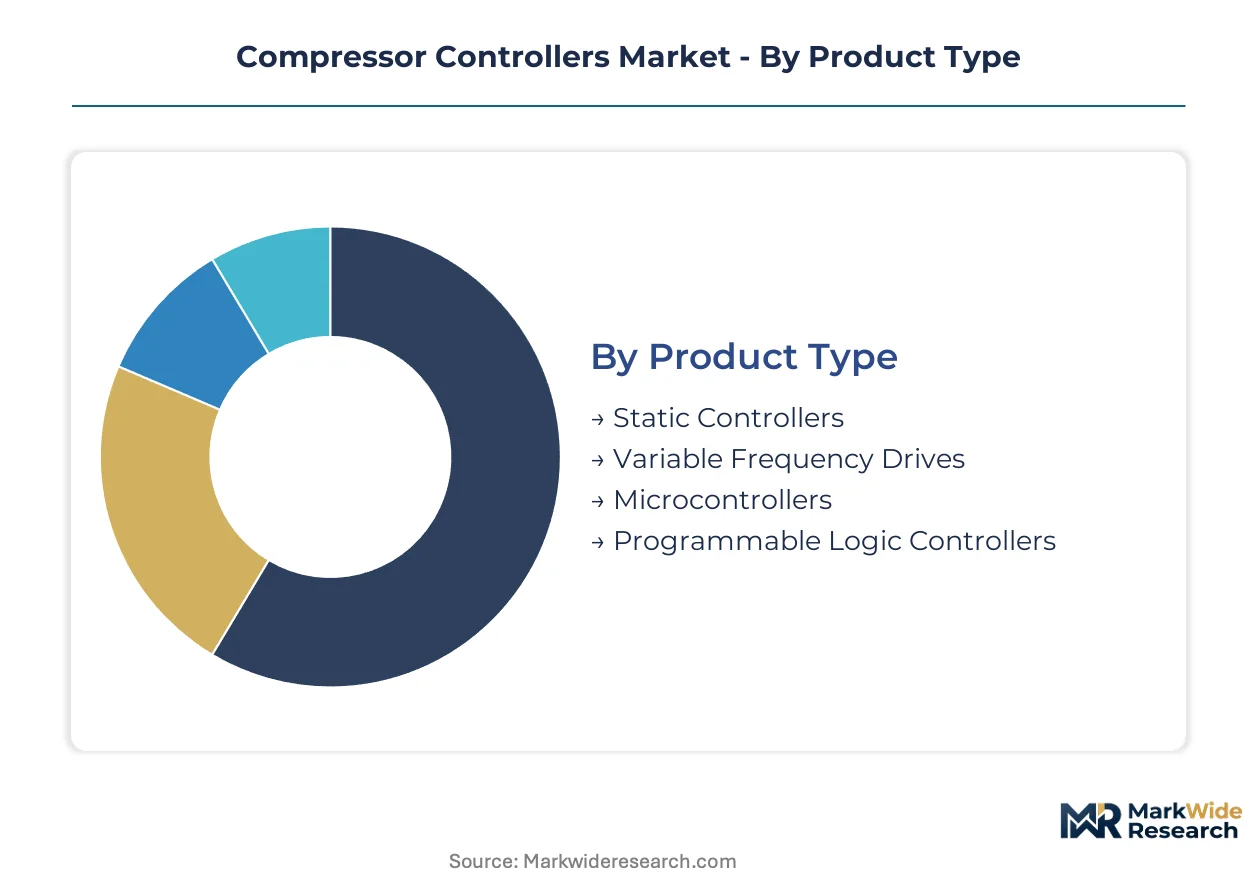
Controller architecture selection dictates upgrade economics across installed industrial bases. Procurement teams weigh retrofit compatibility against efficiency gains when mapping replacement cycles to segment-specific performance thresholds.
Product Type:
Replacement-cycle timing varies sharply across controller architectures, with efficiency mandates compressing payback calculations for premium electronic platforms.
- Variable Frequency Drives:These motor-speed modulation systems adjust compressor output to real-time demand through IGBT-based power conversion. Demand concentrates in German automotive stamping plants and Chinese steel foundries where EU F-Gas Regulation compliance deadlines accelerate retrofit timelines.
- Microcontrollers:Embedded single-chip processors execute fixed control algorithms with minimal peripheral complexity. Japanese precision equipment manufacturers favor these units for compact rotary screw installations where space constraints override advanced functionality requirements.
- Static Controllers:Electromechanical relay logic provides basic on/off cycling without variable-speed capability.
- Programmable Logic Controllers:Modular industrial computers integrate compressor control into broader factory automation networks.
Variable Frequency Drives sits at the top of the volume ranking, with Microcontrollers climbing the fastest.
Installation Type:
Physical mounting configuration shapes procurement patterns across climate zones and facility vintages, with enclosure ratings driving cost tier separation.
- Indoor:Climate-controlled cabinet installations protect sensitive power electronics from particulate and moisture exposure. US food processing facilities under FDA sanitary design guidelines specify these configurations to meet washdown compliance without external sealing premiums.
- Outdoor:NEMA-rated enclosures withstand temperature extremes and precipitation in remote pipeline stations. Demand clusters in Norwegian offshore platforms and Australian mining camps where shelter construction costs exceed hardened controller premiums.
- Wall-Mounted:Vertical surface attachment saves floor space in congested mechanical rooms.
- Rack-Mounted:Standardized 19-inch chassis enable rapid field replacement in data center cooling systems.
Indoor units dominate current procurement volumes, though Outdoor configurations are expanding most quickly in extractive industries.
End User:
Industry-specific duty cycles and regulatory exposure create divergent controller specification requirements across vertical markets.
- HVAC:Commercial building climate systems require controllers that modulate capacity across partial-load conditions. The EU Green Deal efficiency thresholds and comparable US IRA incentives are pulling digital fieldbus upgrades into European and North American retrofit pipelines.
- Oil & Gas:Centrifugal compressor trains in upstream processing demand surge-avoidance algorithms. US Gulf Coast refineries are piloting model predictive control systems to protect capital equipment during unpredictable load fluctuations.
- Manufacturing:General industrial compressed air systems prioritize reliability over precision in continuous-duty environments.
- Agriculture:Irrigation and post-harvest cooling applications favor simple electromechanical controllers for cost-sensitive deployment.
HVAC commands the largest addressable base, while Oil & Gas is gaining share fastest on equipment protection value.
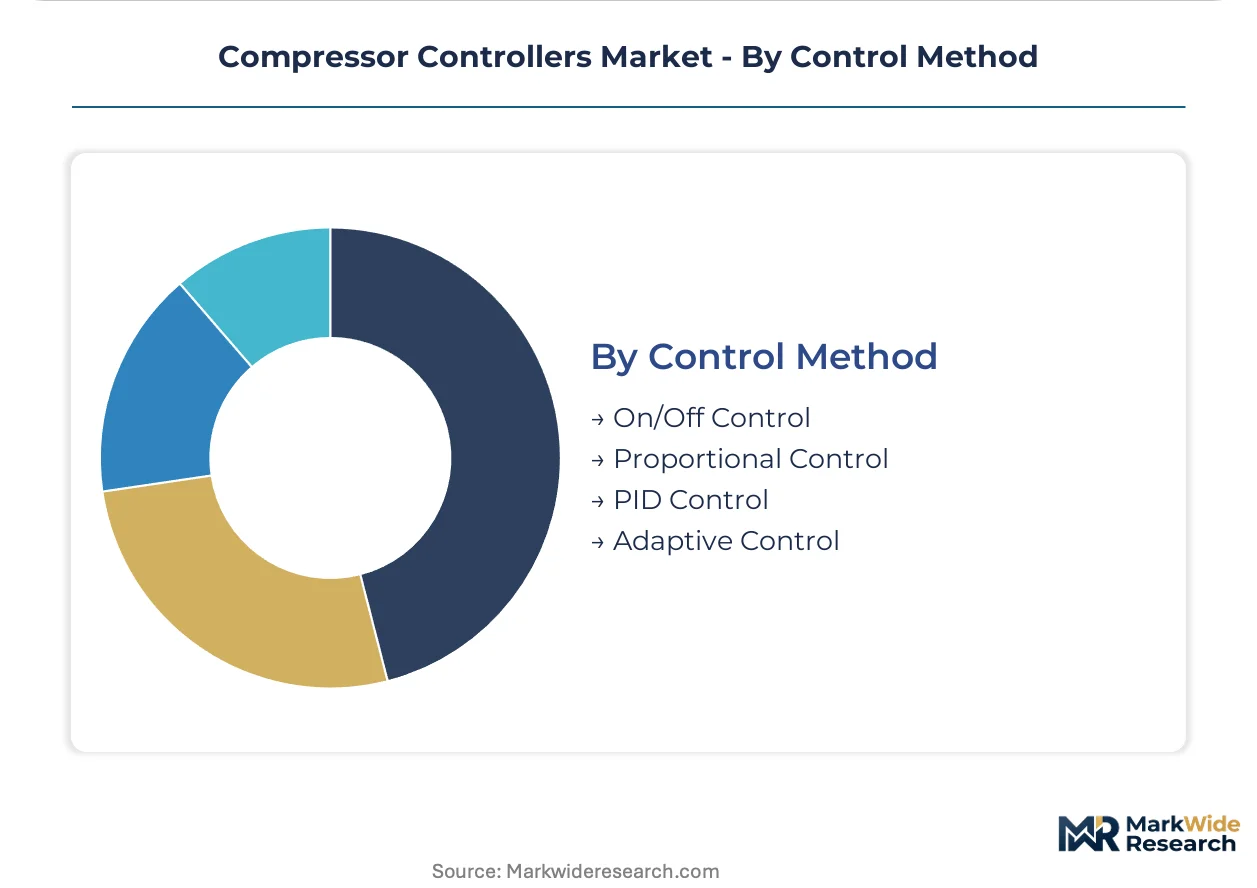
Control Method:
Algorithm sophistication tiers separate commodity replacements from premium upgrade opportunities in controller procurement.
- Adaptive Control:Self-tuning algorithms recalibrate setpoints in response to changing process conditions without manual intervention. Oil and gas processing facilities in the North Sea and Permian Basin are deploying these systems where load profiles defy fixed-parameter tuning.
- PID Control:Proportional-integral-derivative loops maintain steady-state operation through continuous error correction. Chinese smart factory initiatives are pulling demand for these controllers in automated assembly lines requiring precise pressure stability.
- On/Off Control:Binary cycling provides basic pressure maintenance without modulation capability.
- Proportional Control:Single-term feedback reduces oscillation compared to bang-bang cycling.
PID Control retains volume leadership, with Adaptive Control showing the steepest expansion trajectory on predictive maintenance convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent pools in Germany, China, and the United States anchor controller development and deployment capacity. Regional regulatory divergence is recalibrating upgrade economics and procurement timelines across major industrial bases.
Germany
Precision manufacturing clusters in Bavaria and Baden-Württemberg demand high-fidelity compressor control for automotive and machine tool applications. The EU F-Gas Regulation enforces leak detection and efficiency thresholds that accelerate Variable Frequency Drive retrofits in commercial refrigeration. Stuttgart-based OEMs integrate controller hardware with rotary screw systems for export markets.
China
Industrial automation investments in the Yangtze River Delta and Pearl River Delta are pulling advanced control systems into smart factory deployments. MIIT efficiency directives and GB standards mandate domestic certification that filters foreign supplier participation. Shenzhen and Shanghai manufacturing hubs are expanding captive controller production for domestic compressor OEMs.
United States
Petrochemical complexes along the Gulf Coast deploy surge-avoidance algorithms for centrifugal compressor protection in unpredictable load environments. The Department of Energy enforces compressor efficiency test procedures that shape federal procurement specifications. Houston refineries are piloting model predictive control systems for upstream processing reliability.
India
Production-linked incentives under the PLI scheme for industrial machinery are stimulating localized demand for cost-optimized controller platforms. The Bureau of Indian Standards enforces certification requirements that shape import compliance timelines. Gujarat and Maharashtra manufacturing corridors are absorbing mid-tier controller imports for textile and pharmaceutical compressed air systems.
Japan
Precision equipment manufacturers in the Chubu and Kansai regions favor compact microcontroller architectures for space-constrained rotary screw installations. METI industrial efficiency guidelines shape minimum performance expectations for factory automation components. Nagoya automotive suppliers integrate compressor control into broader mechatronic systems for lean production lines.
Compressor Controllers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the controller value chain. The market structures around three tiers: integrated compressor OEMs with captive electronics divisions, standalone controller specialists licensing firmware platforms, and industrial automation conglomerates distributing through multi-product channels. Strategic moves concentrate on backward integration into power electronics sourcing and cloud-based predictive maintenance service layering.
Within the integrated OEM tier, Emerson Electric and Kaeser Kompressoren exemplify manufacturers controlling hardware and electronics through captive production. Atlas Copco occupies a position among scale-driven distributors operating extensive industrial compressor and controller networks. These three anchors represent divergent pathways to pricing power: vertical control over component supply, German-engineered system integration, and manufacturing scale across global distribution nodes.
| Leading Market Players |
|---|
| Emerson Electric |
| Kaeser Kompressoren |
| Atlas Copco |
| Rockwell Automation |
| Gardner Denver |
| Ingersoll Rand |
| Danfoss |
| Schneider Electric |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Embedded firmware engineers concentrated in Stuttgart, Shenzhen, and Austin command wage premiums that propagate through controller pricing tiers, widening spreads between German-engineered premium platforms and cost-optimized Asian alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with certification grade under EU F-Gas Regulation and volume scale as primary differentiation drivers. Cost compression in economy tiers is intensifying because Chinese domestic manufacturers are scaling captive controller production. OEM procurement teams show highest price sensitivity, while oil and gas operators prioritize equipment protection over unit cost.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor hubs to European assembly plants is reshaping regional sourcing strategies, with manufacturers diversifying power electronics procurement. Controller production draws from Taiwan, South Korea, and Germany for IGBT modules, microcontrollers, and precision sensors. Single-source vulnerability in advanced power semiconductors threatens output continuity. Distribution runs through compressor OEM captive channels and industrial automation distributors serving retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Compressor Controllers Market functions as a stable compounder, with regulatory efficiency mandates across major industrial economies ensuring replacement-cycle visibility regardless of macroeconomic cycles.
For Market Incumbents: Extend firmware platform architectures across multiple compressor hardware lines to amortize R&D across broader installed bases. Deepen backward integration into power electronics sourcing to defend margin position against Asian cost competitors. Prioritize cloud-based predictive maintenance service layering to capture recurring revenue from existing hardware footprints. For New Entrants and Emerging Players: Capture surge-avoidance controller demand in North American oil and gas processing where incumbent presence remains thin. India's PLI scheme for industrial machinery offers localized manufacturing incentives that reduce import duty exposure. Lead with adaptive control algorithms as technical differentiator against legacy PID architectures. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking compressor controller capabilities to complete factory automation portfolios. Five-to-ten-year viability hinges on software-defined service attach rates rather than hardware shipment volumes. Monitor cloud-based predictive maintenance subscription attach rates as inflection indicator for valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive IGBT sourcing insulates margin from Taiwan semiconductor foundry pricing volatility. |
| Cloud-Based Predictive Maintenance Launch | Subscription revenue from Emerson and Siemens telemetry platforms recalibrates customer lifetime value. |
| Adaptive Control Algorithm Development | Self-tuning capabilities for Permian Basin compressor trains command equipment protection premiums. |
| India PLI Manufacturing Localization | Domestic assembly under Bureau of Indian Standards certification accelerates import substitution timelines. |
| EU F-Gas Compliance Certification | REACH and RoHS-compliant controller variants unlock European refrigeration retrofit procurement channels. |
Research Methodology
Direct dialogue with compressor OEM procurement directors, plant maintenance engineers, industrial automation system integrators, and aftermarket service heads grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K filings of listed compressor manufacturers, EU F-Gas Regulation implementation reports, MIIT efficiency directive publications, and customs trade data for controller component flows. Bottom-up and top-down triangulation cross-checked segment-level assumptions against aggregate market trajectories.
Top-down macroeconomic filtering and bottom-up segment modeling converged across the analysis window, with controller architecture, installation environment, end-use vertical, and control algorithm sophistication as core segmentation dimensions. CAGRs were derived from installed base replacement cycles, regulatory compliance deadlines, and automation investment intensity by geography. Oil and gas capital expenditure patterns and commercial building energy retrofit pipelines served as industry-specific demand inputs.
Semiconductor supply disruptions, regulatory timeline delays, and industrial automation budget freezes are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Chilled Beams Market