
 Industrial Air Heaters Market | 2026-2036
Industrial Air Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Air Heaters Market Outlook
Asset-light leasing models for thermal infrastructure is reconfiguring competitive entry barriers across the industrial air heater landscape. Watlow Electric Manufacturing Company leverages its captive ceramic heater fabrication to sustain margin control across high-temperature process lines. Danfoss anchors European district heating integration with its brazed heat exchanger expertise. Modine Manufacturing Company competes through specialized corrosion-resistant coatings for agricultural and greenhouse deployments.
Industrial air heaters are forced-convection or radiant thermal devices engineered to elevate process air temperatures between 40°C and 650°C using electric resistance elements, hydrocarbon combustion, or infrared radiation. These units integrate stainless-steel finned coils, modulating gas valves, or quartz emitter arrays to deliver precise enthalpy control for drying, curing, space conditioning, and freeze protection in commercial and manufacturing environments. Fixed installations dominate capital expenditure flows across manufacturing plants and warehouses, while portable electric units represent the fastest-expanding category driven by construction site mobilization and temporary facility heating. Natural gas fuel types retain the largest installed base due to operational cost advantages in baseload process applications, though electric segments capture premium margins where carbon intensity regulations tighten.
OSHA workplace heat hazard standards, EPA New Source Performance Standards for industrial boilers, and EU Ecodesign requirements under the F-Gas Regulation collectively mandate minimum combustion efficiency, emission controls, and refrigerant-phaseout compatibility in associated HVAC integration. These frameworks elevate upfront equipment costs while disqualifying non-compliant suppliers from public and regulated private procurement channels. Stakeholders must monitor evolving carbon border adjustment mechanisms and building performance standards to anticipate retrofit cycles and fuel-switching investment timelines.
Market Dynamics
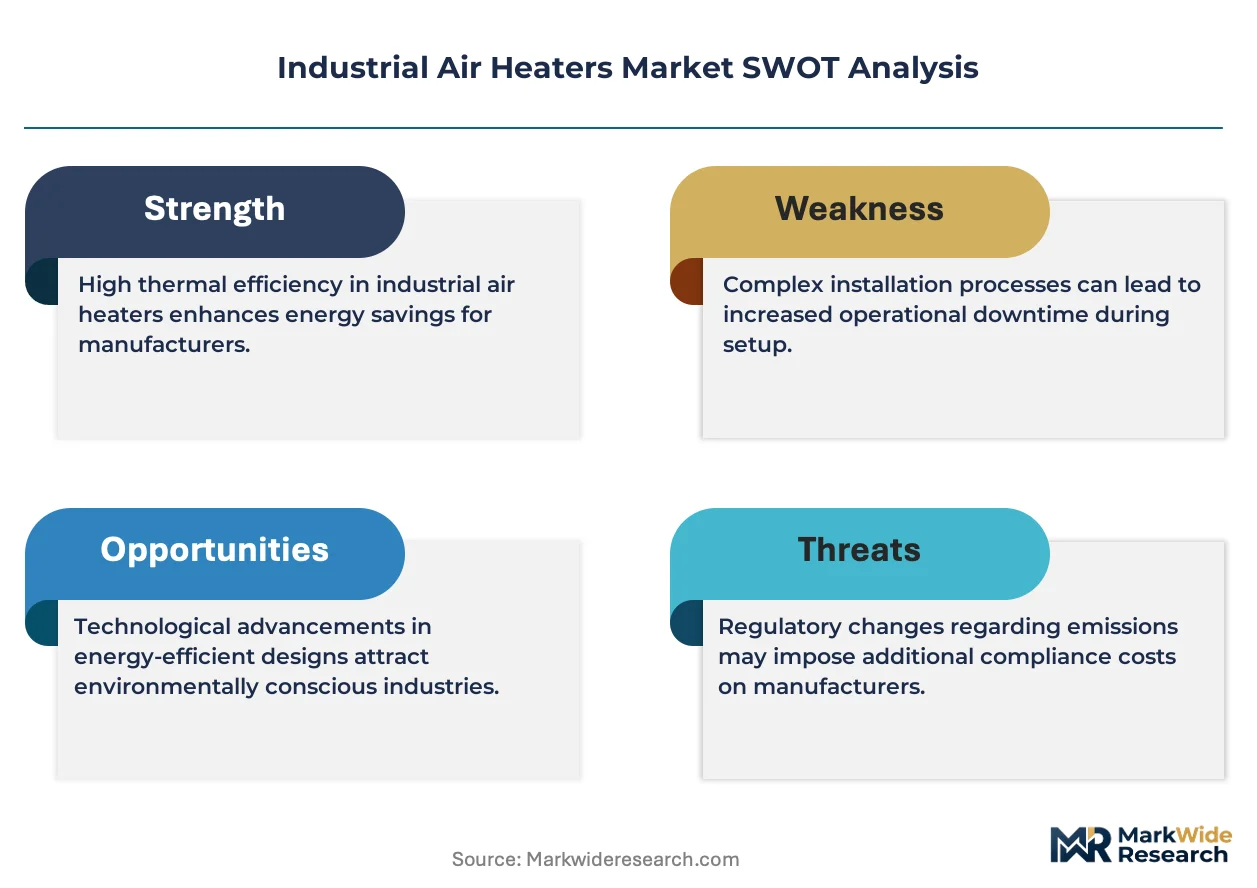
Asset-light leasing models for thermal infrastructure are compressing capital barriers and forcing incumbent manufacturers to reconfigure revenue streams around service contracts rather than equipment sales. This shift is redistributing margin capture toward lifecycle operators and away from traditional fabricators.
Growth Catalysts
- EPA New Source Performance Standards:Tightening emission thresholds for industrial combustion equipment are accelerating replacement cycles in US chemical processing facilities, creating pull for low-NOx burner retrofits.
- Stainless-steel finned coil advances:Enhanced heat transfer geometries are extending service intervals in high-particulate environments such as cement and mineral processing.
- Germany's industrial corridor:Concentrated demand around Cologne and Düsseldorf is anchoring specialized distribution networks for high-temperature process air systems.
Market Restraints
- Nickel alloy input volatility:Price swings in Inconel and stainless feedstocks destabilize fabrication cost structures for high-temperature coil assemblies.
- EU F-Gas Regulation phase-down:Refrigerant restrictions in associated HVAC integration are complicating hybrid heating-cooling system designs and extending engineering timelines.
- Electric resistance substitution ceiling:Baseload process applications above 400°C remain locked into combustion architectures due to power density limitations.
Strategic Opportunities
- India's PLI scheme for capital goods:Domestic manufacturing incentives are opening localized assembly pathways for mid-range electric process heaters serving food processing.
- Green hydrogen electrolyzer integration:Waste heat recovery from electrolysis stacks is creating novel thermal coupling opportunities with air preheating circuits.
- Outcome-based thermal service contracts:Energy-as-a-service models are penetrating warehousing and logistics facilities, shifting buyer relationships from capital expenditure to operational expenditure frameworks.
Industry Challenges
- Combustion technician scarcity:Qualified service personnel for modulating gas valve diagnostics and burner tuning are concentrated in aging workforce cohorts across North American industrial regions.
- NEMA efficiency certification timelines:Extended laboratory testing protocols for premium motor-driven fan systems are delaying product launches and compressing effective selling seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Air Heaters Market |
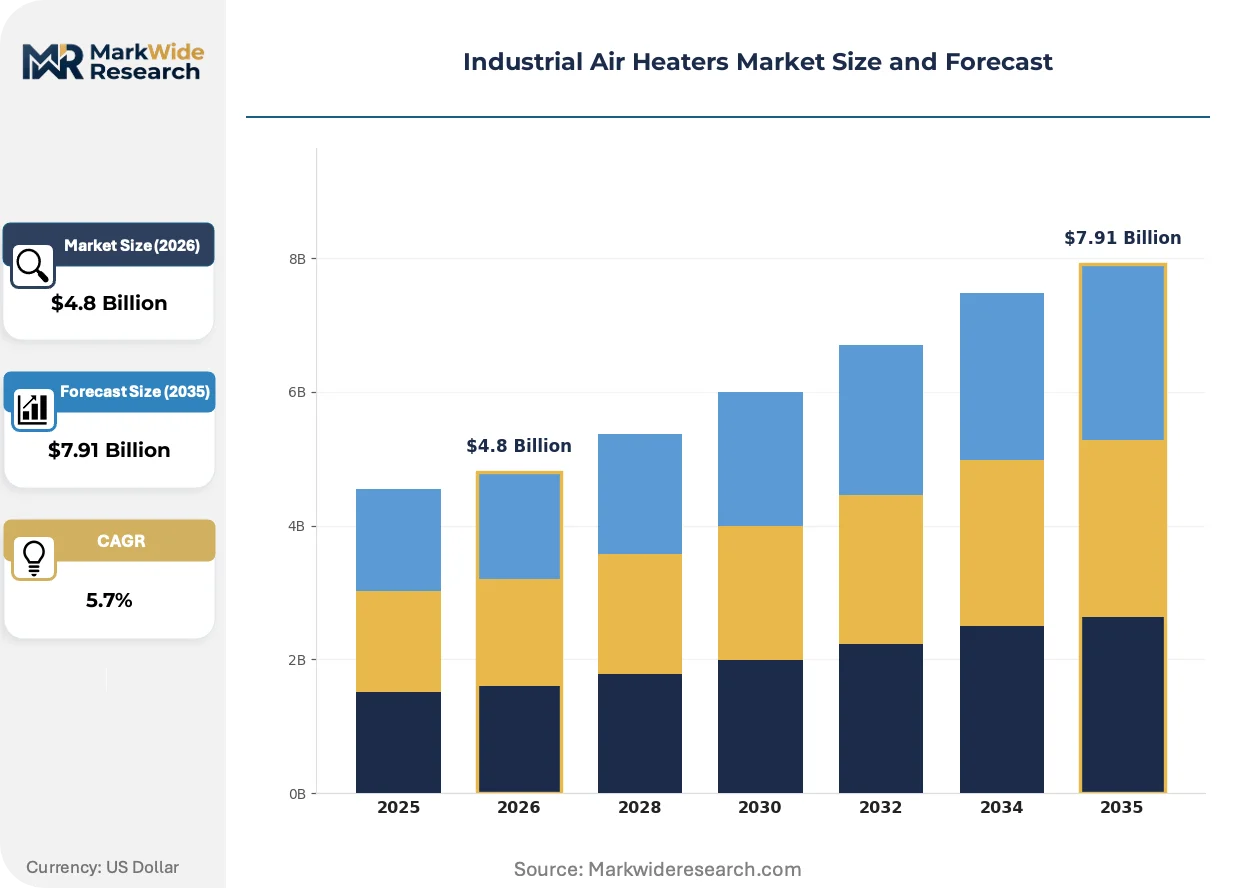
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Heaters, Fixed Heaters, Infrared Heaters, Convection Heaters Installation Type: Wall-Mounted, Floor-Mounted, Ceiling-Mounted, Ducted Fuel Type: Natural Gas, Propane, Electric, Diesel End User: Manufacturing Plants, Warehouses, Agricultural Facilities, Construction Sites |
| Companies Covered | Thermo King, Trane Technologies, Danfoss, Honeywell, Johnson Controls, Eberspächer, Modine Manufacturing Company, Watlow Electric Manufacturing Company, Chromalox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Air Heaters Market Strategic Shifts
Infrared quartz emitter arrays are penetrating process lines previously dominated by convection architectures, compressing heat-up times and enabling zone-specific temperature profiling. This shift is redistributing competitive advantage toward optical and materials specialists.
Silicon carbide heating elements are rendering obsolete traditional nickel-chrome resistance coils in applications above 600°C. Specialty ceramics producers are capturing specification authority in semiconductor wafer drying and advanced materials curing. The technology is rendering obsolete decade-old thermal designs that relied on metallic element redundancy.
OSHA workplace heat hazard standards are mandating engineered controls for indoor air temperature management in manufacturing environments. Facilities with legacy steam-based space heating are retrofitting forced-air systems to achieve compliance. Food processing plants in southern US states are prioritizing cooling-integrated heating architectures to satisfy dual-season requirements.
Buyers are consolidating vendor relationships around full-lifecycle thermal service providers rather than equipment-only suppliers. Large warehouse operators are bundling installation, maintenance, and energy optimization under single-source contracts. This concentration is most visible in German automotive supplier parks and US third-party logistics hubs.
Industrial Air Heaters Market Segmentation
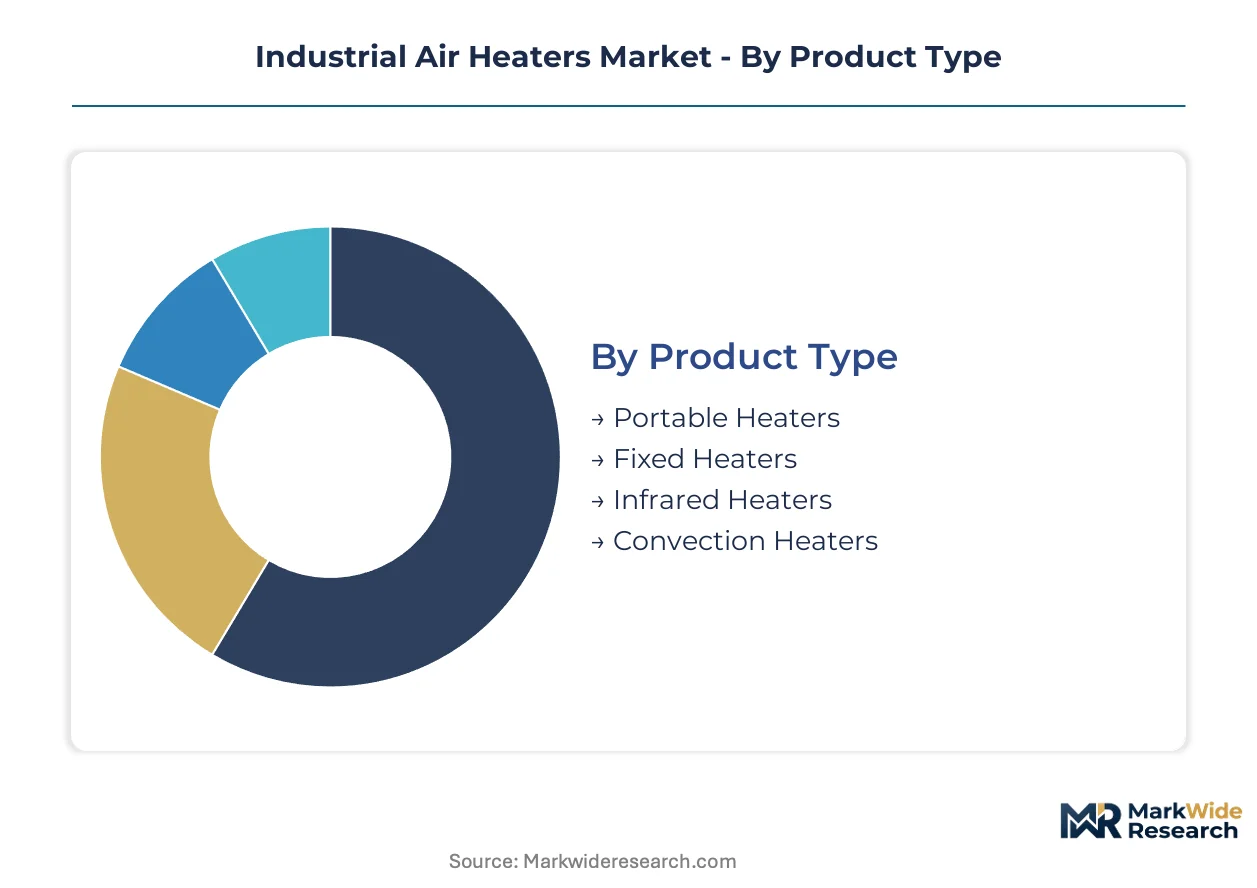
Segmentation in industrial air heaters reveals divergent service intensity requirements across product architectures. Fixed installations demand multi-year maintenance contracts and combustion technician networks, while portable units concentrate margin capture in rental fleet management and rapid-response logistics.
Product Type:
After-sales-service intensity varies sharply across product architectures, with fixed installations requiring specialized combustion technician networks and infrared arrays demanding optical calibration protocols.
- Portable Heaters:Compact forced-convection or radiant units designed for construction site mobilization and temporary facility conditioning. Demand concentrates in US third-party logistics hubs and German automotive supplier parks where seasonal surge capacity drives rental fleet expansion. EPA New Source Performance Standards are accelerating electric model substitution in enclosed workspaces.
- Fixed Heaters:Permanent installations integrating stainless-steel finned coils, modulating gas valves, and ductwork connections for process lines above 400°C. Chemical processing facilities around Cologne and Düsseldorf anchor replacement cycles as EU Ecodesign requirements tighten combustion efficiency thresholds.
- Infrared Heaters:Quartz emitter arrays delivering zone-specific temperature profiling through radiant energy transfer.
- Convection Heaters:Forced-air systems with centrifugal fans and finned heat exchangers for space conditioning applications.
Fixed heaters hold the largest share; momentum sits with portable units.
Installation Type:
Installation geometry determines upfront engineering complexity and retrofit accessibility, with wall-mounted systems dominating brownfield upgrades and ducted configurations capturing greenfield process lines.
- Wall-Mounted:Vertical installations optimizing floor space in warehousing and light manufacturing. Warehouses in Germany's industrial corridor specify these for OSHA workplace heat hazard compliance without sacrificing storage density.
- Floor-Mounted:Freestanding units with skid bases or caster mounts enabling repositioning in multi-product facilities. Agricultural facilities in southern US states favor these for dual-season heating-cooling flexibility.
- Ceiling-Mounted:Overhead radiant or forced-air distribution for high-bay environments with minimal obstruction.
- Ducted:Centralized air handling with distribution plenums for zonal temperature control across large footprints.
Wall-mounted configurations dominate retrofit volumes; ducted systems are climbing fastest in greenfield chemical processing.
Fuel Type:
Fuel selection locks buyers into diverging regulatory compliance pathways and carbon intensity accounting frameworks, with natural gas retaining baseload economics and electric segments capturing premium positioning.
- Natural Gas:Pipeline-delivered methane combustion through low-NOx burners for process temperatures between 200°C and 650°C. US chemical processing facilities accelerate replacement cycles under EPA New Source Performance Standards, while EU carbon border adjustment mechanisms erode long-term cost advantages.
- Electric:Resistance elements or silicon carbide arrays for precise enthalpy control below 600°C. Food processing plants prioritize these where carbon intensity regulations tighten and power density requirements permit.
- Propane:Liquefied petroleum gas combustion for off-grid or mobile applications lacking pipeline infrastructure.
- Diesel:Liquid fuel burners for construction site mobilization and emergency heating in remote locations.
Natural gas retains the largest installed base; electric segments gain share fastest in regulated jurisdictions.
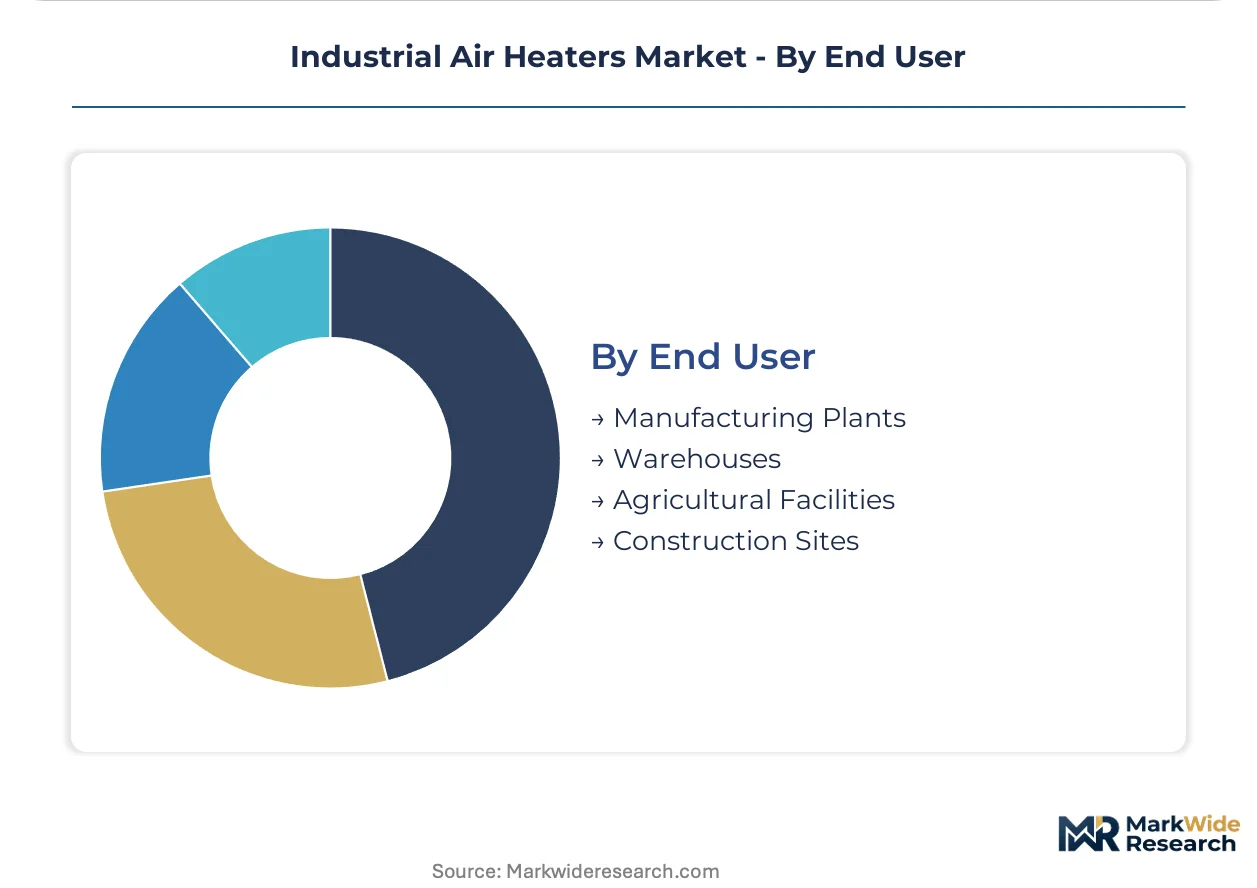
End User:
End-use verticals concentrate demand around distinct performance specifications, with manufacturing plants prioritizing process precision and construction sites optimizing mobilization speed.
- Manufacturing Plants:High-temperature process air systems for drying, curing, and thermal treatment lines. Semiconductor wafer drying and advanced materials curing in German industrial corridors specify silicon carbide heating elements above 600°C.
- Warehouses:Space conditioning and freeze protection for inventory preservation. US third-party logistics hubs bundle installation, maintenance, and energy optimization under single-source outcome-based thermal service contracts.
- Agricultural Facilities:Corrosion-resistant coatings and humidity-tolerant architectures for greenhouse and livestock environments.
- Construction Sites:Rapid-deployment portable units with temporary fuel supply logistics and minimal foundation requirements.
Manufacturing plants command the highest specification authority; warehouses are expanding most quickly through energy-as-a-service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in industrial air heaters tilt toward fabrication surpluses in Germany and the United States, while India's PLI scheme for capital goods is redirecting import dependency toward localized assembly pathways for mid-range electric process heaters.
United States
Chemical processing facilities across the Gulf Coast are accelerating replacement cycles for combustion equipment. EPA New Source Performance Standards tighten emission thresholds and disqualify non-compliant suppliers from regulated procurement channels. Houston and Baton Rouge anchor demand for low-NOx burner retrofits in petrochemical corridors.
Germany
EU Ecodesign requirements under the F-Gas Regulation mandate combustion efficiency upgrades in industrial thermal systems. The country's industrial corridor around Cologne and Düsseldorf concentrates specification authority for high-temperature process air systems. Automotive supplier parks in this region are bundling installation and maintenance under single-source outcome-based thermal service contracts.
China
Semiconductor wafer drying and advanced materials curing drive specification demand for silicon carbide heating elements above 600°C. MIIT efficiency mandates and GB standards for industrial electrical equipment elevate upfront equipment costs while accelerating domestic substitution. Yangtze River Delta fabrication clusters in Shanghai and Suzhou capture premium positioning in ceramic heater supply chains.
India
Food processing plants prioritize electric resistance systems where carbon intensity regulations tighten and power density requirements permit. The PLI scheme for capital goods opens localized assembly pathways for mid-range electric process heaters. Maharashtra and Gujarat industrial zones are consolidating vendor relationships around full-lifecycle thermal service providers.
Japan
METI industrial efficiency programs and JIS standards for thermal equipment compress engineering timelines for premium motor-driven fan systems. Precision manufacturing in Kanto and Kansai regions specifies zone-specific temperature profiling through infrared quartz emitter arrays. Nagoya-area automotive component suppliers are retrofitting forced-air systems to satisfy OSHA-equivalent workplace heat hazard compliance.
Industrial Air Heaters Market Competitive Environment
On the supply side, the industry is moderately consolidated with distinct tiering between integrated thermal specialists and component fabricators. Incumbents with captive ceramic production sustain margin control in high-temperature segments, while leasing operators capture recurring revenue through energy-as-a-service frameworks. Two strategic archetypes dominate: vertically integrated heater manufacturers with in-house coil fabrication, and lifecycle service providers bundling installation with maintenance contracts. Competitive moves concentrate on strategic partnerships for district heating integration and geographic expansion through localized assembly in incentivized jurisdictions.
Among North American-listed manufacturers, Trane Technologies and Honeywell occupy positions in climate control integration, while Johnson Controls exemplifies the building automation convergence archetype. Watlow Electric Manufacturing Company and Chromalox represent the captive fabrication tier with ceramic and resistance element specialization. Danfoss anchors European district heating integration through its brazed heat exchanger expertise. Modine Manufacturing Company sits within the corrosion-resistant coating specialization vector for agricultural and greenhouse deployments. Thermo King, Eberspächer, and the remaining specialized fabricators fragment across portable and fixed installation segments.
| Leading Market Players |
|---|
| Thermo King |
| Trane Technologies |
| Danfoss |
| Honeywell |
| Johnson Controls |
| Eberspächer |
| Modine Manufacturing Company |
| Watlow Electric Manufacturing Company |
| Chromalox |
| Others |
Value Chain & Pricing Dynamics
China's Yangtze River Delta fabrication clusters anchor silicon carbide heating element supply, concentrating margin capture with specialty ceramics producers who specification-authorize high-temperature process lines above 600°C. This upstream concentration funnels pricing power toward optical and materials specialists while compressing margins for metallic coil assemblers facing nickel alloy input volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture silicon carbide and infrared quartz configurations serving semiconductor wafer drying, while standard tiers concentrate natural gas combustion systems for chemical processing baseload applications. Price differentiation hinges on NEMA efficiency certification grade and EPA New Source Performance Standards compliance status. Cost compression in economy-tier metallic resistance coils is intensifying because Inconel feedstock volatility destabilizes fabrication cost structures. Food processing plants exhibit highest price sensitivity due to thin operating margins, whereas semiconductor fabs demonstrate lowest sensitivity given thermal precision requirements.
Supply Chain Analysis
Contract manufacturing capacity for industrial air heaters concentrates with German automotive supplier park integrators and US Gulf Coast petrochemical equipment fabricators. Geographic supply concentration centers on Germany, the United States, and China, with each hub specializing in distinct thermal architectures. Raw material dependencies rest on nickel alloy feedstocks, silicon carbide ceramics, and quartz emitter substrates. Single-source vulnerability in specialty ceramics for high-temperature elements poses structural risk as silicon carbide heating elements displace decade-old metallic designs. Distribution runs through specialized combustion technician networks for fixed installations and rental fleet operators for portable unit deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light leasing models fragment competitive positioning across the industrial air heater landscape, creating niches as buyers consolidate vendor relationships around full-lifecycle thermal service providers rather than equipment-only suppliers.
For Market Incumbents: Build captive ceramic fabrication moats to sustain margin control in high-temperature segments above 600°C. Incumbents should deepen backward integration into silicon carbide supply chains and anchor European district heating integration through brazed heat exchanger partnerships. Electrification mandates from EPA emissions standards and EU F-Gas Regulation phase-downs threaten combustion-centric revenue streams, necessitating rapid low-NOx burner retrofit certification investment. For New Entrants and Emerging Players: Pursue India's PLI scheme for capital goods to establish localized assembly pathways for mid-range electric process heaters serving food processing. Agricultural facilities in southern US states present the most penetrable segment due to corrosion-resistant coating gaps and dual-season heating-cooling flexibility requirements. Outcome-based thermal service contracts offer the strongest go-to-market angle, shifting buyer relationships from capital expenditure to operational expenditure frameworks. For Investors and Strategic Acquirers: Capital is best deployed toward lifecycle service providers bundling installation, maintenance, and energy optimization under single-source contracts. Long-term viability favors operators capturing recurring revenue through energy-as-a-service frameworks over pure-play fabricators exposed to nickel alloy input volatility. The inflection signal to watch is carbon border adjustment mechanism implementation timelines, which will accelerate fuel-switching investment cycles and retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Supply | Captive silicon carbide production secures specification authority in semiconductor wafer drying applications. |
| Localized Assembly under India's PLI Scheme | Domestic manufacturing incentives open mid-range electric heater pathways for food processing demand. |
| Outcome-Based Thermal Service Contracts | Energy-as-a-service models penetrate warehousing and logistics facilities through operational expenditure frameworks. |
| Low-NOx Burner Retrofit Certification | EPA New Source Performance Standards compliance qualifies suppliers for regulated procurement channels. |
| Green Hydrogen Electrolyzer Integration | Waste heat recovery from electrolysis stacks creates novel thermal coupling with air preheating circuits. |
Study Parameters
Desk research of customs trade data, SEC equipment manufacturer filings, and EU Ecodesign regulatory precedents preceded structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and combustion technicians. Primary fieldwork with maintenance directors at chemical processing facilities and thermal infrastructure operators validated secondary findings. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the industrial heating value chain.
Assumptions held fixed include EPA New Source Performance Standards enforcement intensity and EU F-Gas Regulation phase-down timelines, while nickel alloy pricing trajectories and carbon border adjustment mechanism adoption rates were varied across sensitivity scenarios. The analytical framework modeled product type, fuel category, installation geometry, and end-use vertical dimensions throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles and regulatory compliance investment waves, with semiconductor capital expenditure patterns and chemical processing capacity additions serving as industry-specific demand inputs.
Sensitivities concentrate around Inconel price volatility, combustion technician workforce availability, and EU carbon border adjustment implementation cadence. Forecasts reflect these documented assumptions regarding regulatory enforcement and technology substitution rates. Quarterly review of EPA enforcement actions, MIIT efficiency mandate updates, and semiconductor fabrication construction permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
France HVAC Market