
 Latin America Heat Exchanger Market | 2026-2036
Latin America Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Heat Exchanger Market Intelligence
Equipment distribution through regional industrial distributors is fragmenting as OEMs build direct service networks in Brazil and Mexico. Alfa Laval AB leverages its aftermarket parts logistics to sustain recurring revenue from refinery clients. Kelvion Holding GmbH anchors its Latin American presence through localized brazed heat exchanger production. Danfoss A/S competes on HVAC system integration, extending its reach beyond component sales into packaged solutions.
A heat exchanger is a thermal transfer device fabricated from stainless steel, titanium, or nickel alloys, employing corrugated plates, finned tubes, or shell-and-tube configurations to move thermal energy between process fluids without mixing. Its primary industrial purpose is temperature regulation, energy recovery, and phase change management across continuous process operations. Plate heat exchangers dominate maintenance-intensive chemical processing installations where compact footprint and cleanability offset higher capital cost. Shell and tube designs occupy legacy power generation and heavy oil refining infrastructure where pressure tolerance and fouling resistance command premium positioning. Air-cooled units are displacing water-cooled systems in water-scarce northern Mexico and Chilean mining districts.
Brazil's ANP refining standards and Mexico's NOM energy efficiency mandates shape equipment specification and replacement timelines across downstream energy facilities. Argentina's IRAM certification requirements and Chile's SEC thermal performance regulations create compliance thresholds that filter import channels and favor established suppliers with local testing partnerships. Stakeholders must monitor regulatory harmonization progress under Mercosur technical standards and assess whether unified certification will consolidate supplier tiers or preserve country-specific qualification barriers.
Market Dynamics
Equipment replacement cycles across Latin American refineries are compressing as ANP and NOM mandates force thermal efficiency upgrades, while water scarcity in northern mining belts accelerates air-cooled system adoption against conventional water-cooled infrastructure.
Growth Catalysts
- Brazil's ANP refining standards:Mandated thermal performance thresholds are forcing equipment turnover at Petrobras facilities and private refiners, creating sustained demand for welded plate configurations.
- Water-scarce mining districts:Chilean copper operations and northern Mexican extraction sites are converting cooling infrastructure to air-cooled heat exchangers to reduce freshwater dependence.
- Titanium alloy adoption:Corrosion-resistant plate materials are penetrating coastal petrochemical installations where salt-laden atmospheres degrade carbon steel units.
Market Restraints
- Import duty structures:Mercosur's common external tariff on non-regional fabricated metal equipment elevates landed costs for European and Asian OEMs serving Brazilian buyers.
- Nickel price volatility:Heat exchanger fabricators face margin compression when alloy input costs spike, particularly affecting shell-and-tube producers with fixed-price contracts.
- Specialized welding skill scarcity:Certified orbital welders for titanium and nickel alloy joints concentrate in São Paulo and Monterrey, constraining production scaling.
Strategic Opportunities
- Colombian unconventional oil:Heavy crude thermal extraction projects in the Llanos Basin require specialized high-viscosity heat exchanger designs currently undersupplied by regional fabricators.
- Mexico NOM-001-ENER efficiency mandates:Industrial facility energy audits are triggering systematic HVAC and process cooling equipment replacement with certified high-efficiency units.
- Remote monitoring convergence:IoT sensor integration with predictive maintenance platforms is opening service contract revenue streams beyond hardware margins.
Industry Challenges
- IRAM certification timelines:Argentine import qualification procedures extend equipment approval cycles, delaying project commissioning for infrastructure developers.
- Legacy system integration:Shell-and-tube replacement with compact plate designs requires piping reconfiguration and control system upgrades that inflate total project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Heat Exchanger Market |
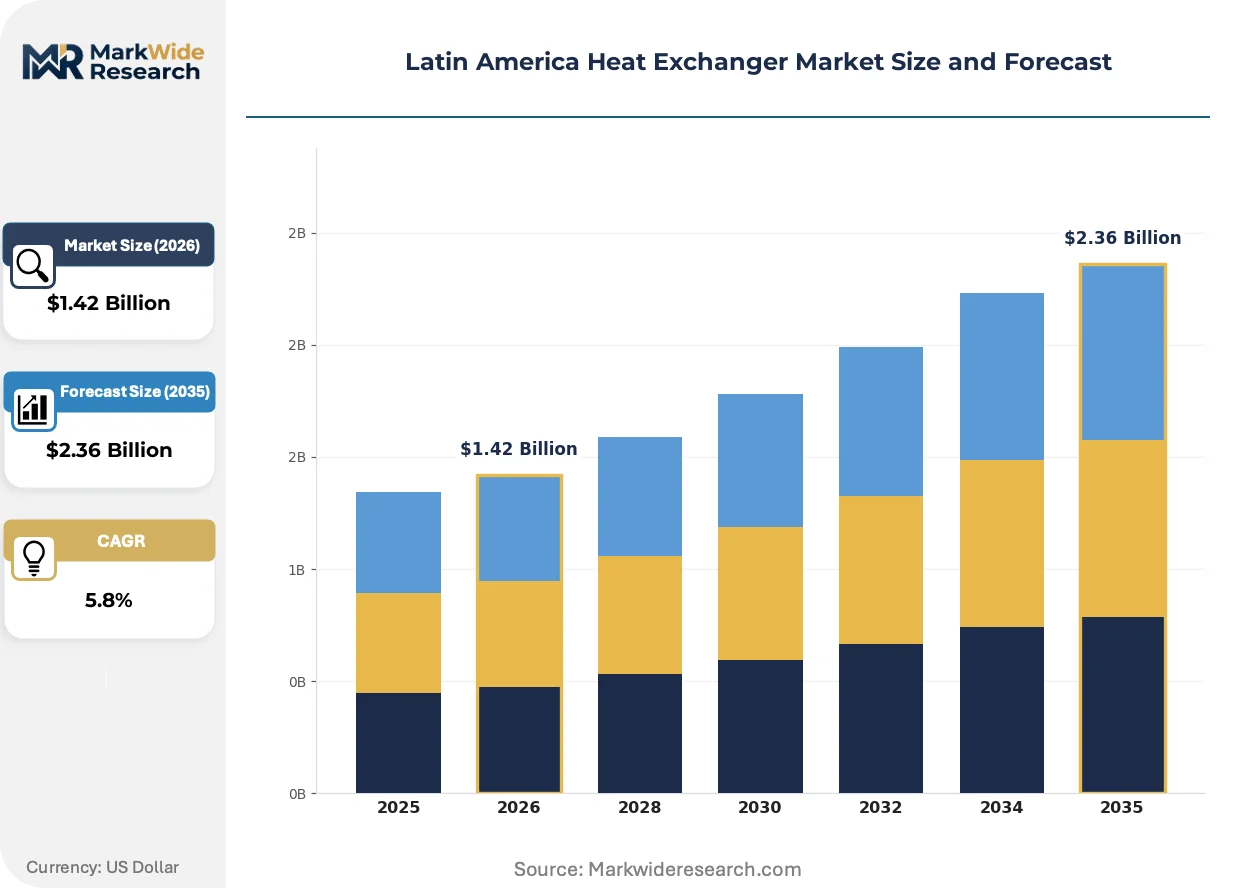
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell & Tube, Plate, Air-Cooled, Double Tube End User: Power Generation, Oil & Gas, Chemical Processing, HVAC Application: Cooling, Heating, Condensing, Heat Recovery Technology: Microchannel, Brazed, Welded, Finned Tube |
| Companies Covered | Alfa Laval AB, Danfoss A/S, Kelvion Holding GmbH, GEA Group Aktiengesellschaft, API Heat Transfer, Xylem Inc, Johnson Controls International plc, Chart Industries Inc, FUNKE Wärmeaustauscher Apparatebau GmbH, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Heat Exchanger Market Strategic Shifts & Innovations
Digitalization of thermal asset management is intersecting with material science advances and regulatory pressure to reshape equipment specification, procurement, and lifecycle service models across Latin American industrial corridors.
Printed circuit heat exchanger (PCHE) technology, employing chemically etched micro-channels in stainless steel or titanium stacks, delivers extreme compactness and thermal effectiveness for offshore and subsea applications. Brazilian pre-salt platform operators are piloting PCHE units for high-pressure gas processing. The technology is rendering obsolete conventional shell-and-tube footprints where deck space commands premium valuation.
Mexico's NOM-001-ENER and NOM-013-ENER standards establish minimum thermal performance coefficients for process cooling and HVAC equipment, with compliance verification through accredited testing laboratories. Industrial facility operators must document energy consumption benchmarks and upgrade non-conforming assets within mandated windows. Petrochemical and food processing installations in Tamaulipas and Veracruz are prioritizing certified plate heat exchangers to satisfy audit requirements.
Aftermarket service unbundling is disrupting traditional distributor-captive maintenance relationships. End-users in São Paulo's chemical corridor are negotiating direct spare parts supply agreements with OEM logistics hubs, bypassing regional distributors who previously controlled technical support access. Brazilian refinery operators are consolidating vendor lists and demanding localized parts inventory commitments as contract conditions.
Latin America Heat Exchanger Market Segmentation
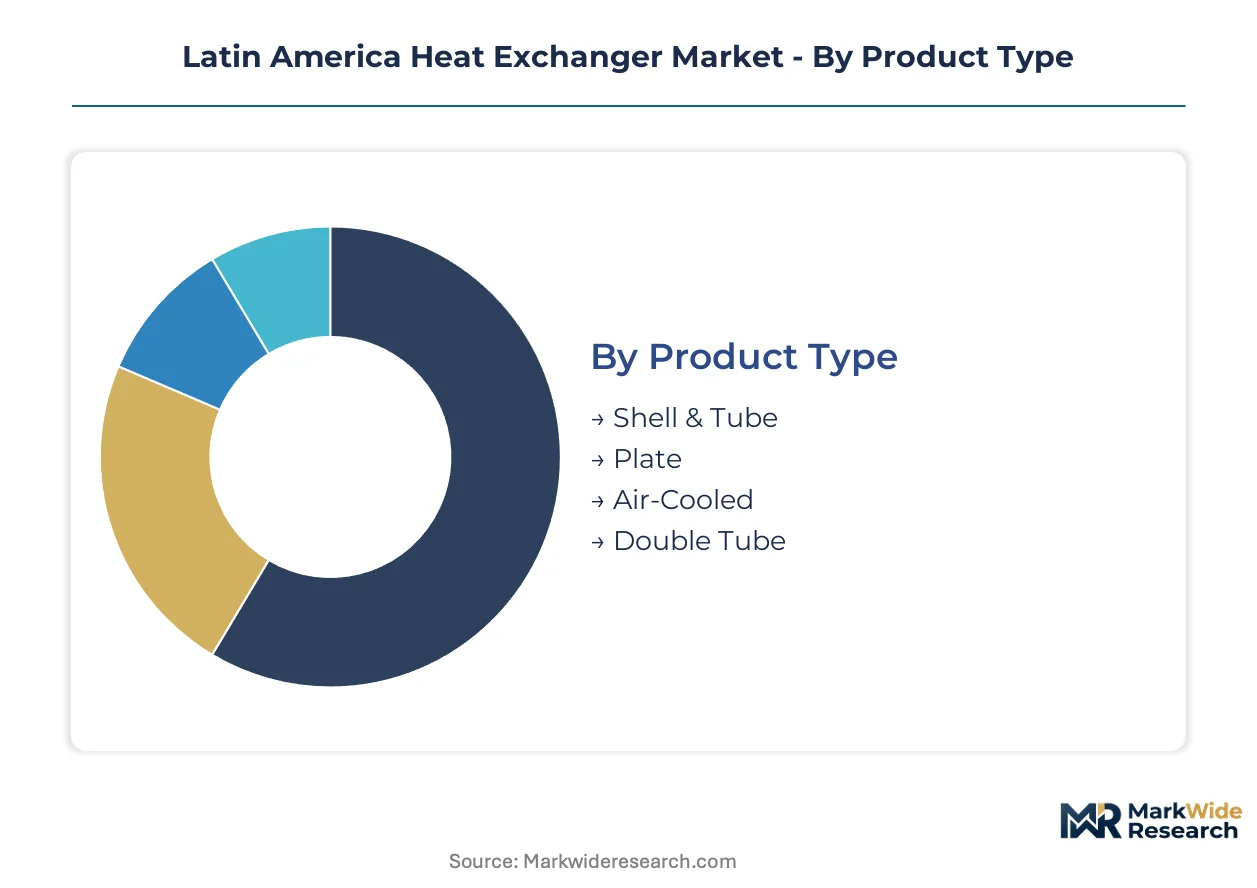
Heat exchanger procurement patterns across Latin America diverge sharply by product architecture and end-use intensity, with maintenance contracts and spare parts logistics driving vendor selection as much as initial capital cost. Equipment specification varies by thermal duty, fluid corrosivity, and regional regulatory compliance requirements.
Product Type:
After-sales service intensity varies dramatically across heat exchanger architectures, with welded plate designs demanding specialized gasket inventories and shell-and-tube units requiring tube bundle replacement programs.
- Shell & Tube:Fabricated from carbon steel or nickel alloys with removable tube bundles for mechanical cleaning, these units dominate legacy refinery infrastructure across Brazil's Southeast industrial corridor where Petrobras maintains extensive maintenance partnerships. ANP thermal efficiency mandates are accelerating replacement cycles at older facilities.
- Plate:Corrugated stainless steel or titanium plates compressed within bolted frames deliver compact footprints and superior thermal effectiveness for chemical processing installations. Demand concentrates in São Paulo state's petrochemical corridor where cleanability and modularity offset higher capital outlay.
- Air-Cooled:Finned tube bundles forced by axial fans eliminate cooling water dependence, penetrating northern Mexican mining districts and Chilean copper operations facing freshwater scarcity constraints.
- Double Tube:Concentric tube configurations handle small-batch thermal duties with minimal fouling risk, serving specialty chemical producers in Argentina's Buenos Aires industrial belt.
Shell & Tube holds the largest share; momentum sits with Plate configurations.
End User:
Customer procurement sophistication spans from standardized HVAC specifications to engineered process solutions, with oil and gas operators commanding the most intensive technical support requirements.
- Power Generation:Combined cycle and thermal plants deploy shell-and-tube feedwater heaters and surface condensers, with Brazilian utilities prioritizing ANP-compliant thermal performance upgrades.
- Oil & Gas:Refineries and upstream processing facilities specify welded plate exchangers for crude preheating and gas cooling, with Mexico's NOM efficiency audits triggering systematic equipment replacement across Tamaulipas and Veracruz installations.
- Chemical Processing:Corrosion-resistant titanium plate units serve chlor-alkali and fertilizer producers in Brazil's Cubatão complex and Argentina's Bahía Blanca petrochemical hub.
- HVAC:Commercial building and industrial facility climate control systems adopt brazed plate heat exchangers for chilled water loops, with Mexico City and Santiago compliance deadlines compressing replacement timelines.
Oil & Gas commands the deepest vendor relationships; HVAC is expanding most quickly.
Application:
Functional thermal duty determines material selection and control system complexity, with heat recovery applications commanding premium engineering margins.
- Cooling:Process fluid temperature reduction dominates volume across all end-use sectors, with air-cooled systems gaining share in water-constrained geographies.
- Heating:Preheating duties in refining and chemical synthesis favor high-pressure shell-and-tube configurations with extensive safety instrumentation.
- Condensing:Vapor-to-liquid phase change applications in power and petrochemical plants require precise pressure-temperature control and non-condensable gas venting provisions.
- Heat Recovery:Waste heat capture from exhaust streams and process effluents delivers energy efficiency compliance for NOM and ANP audits, with Brazilian sugar-ethanol distilleries pioneering integration.
Cooling represents the largest installed base; heat recovery is climbing the fastest.
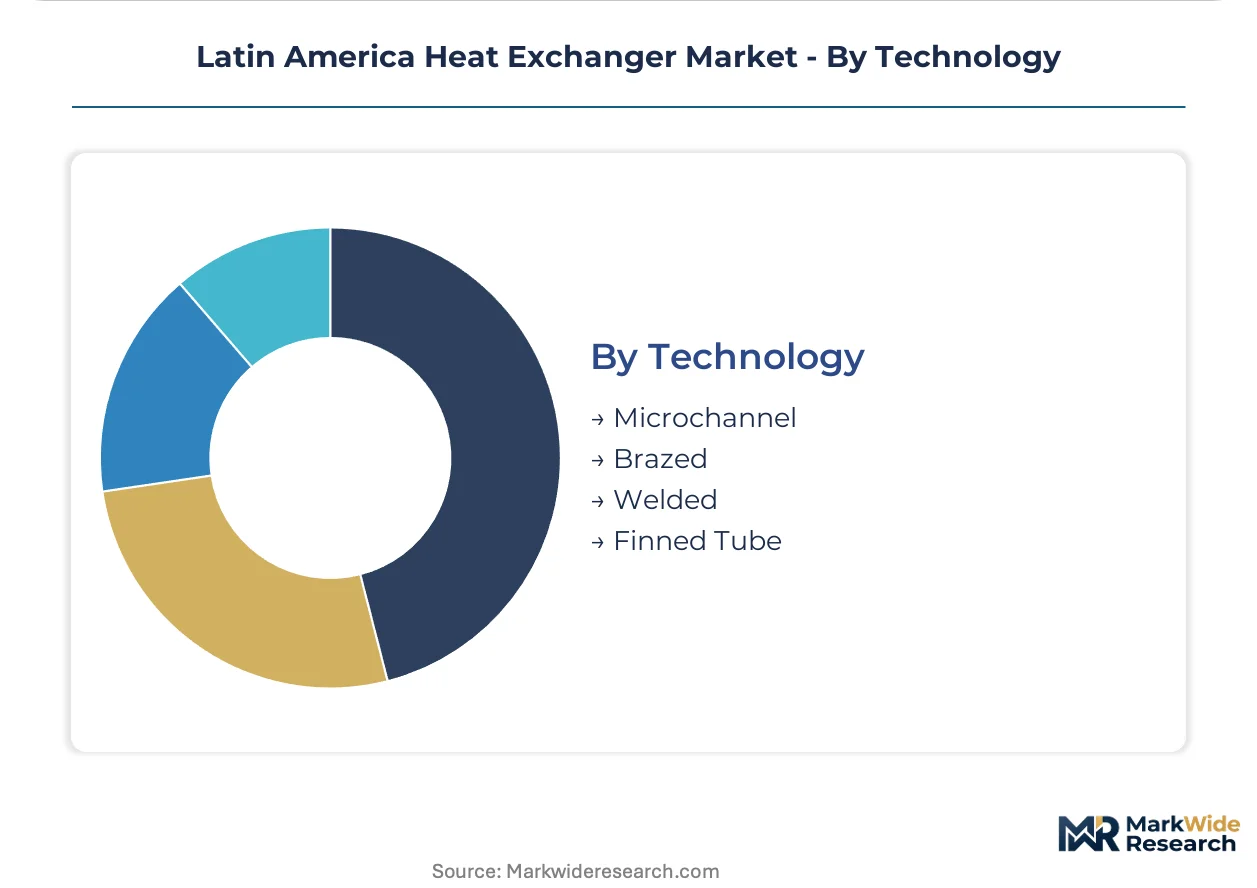
Technology:
Fabrication method and channel geometry dictate thermal effectiveness, pressure tolerance, and field serviceability, with microchannel designs penetrating high-specification niches.
- Microchannel:Chemically etched sub-millimeter flow passages in stacked metal plates deliver extreme compactness for offshore platform and subsea gas processing, with Brazilian pre-salt operators piloting PCHE variants.
- Brazed:Copper- or nickel-bonded aluminum plate cores serve HVAC and light industrial applications where capital cost sensitivity outweighs cleanability requirements, with Kelvion's localized production anchoring regional supply.
- Welded:Fully welded plate packs eliminate gasket maintenance for aggressive fluids and high-temperature duties, penetrating coastal petrochemical installations where salt-laden atmospheres degrade conventional sealing systems.
- Finned Tube:Extended surface tubing enhances air-side heat transfer for cooling and condensing services, dominating air-cooled heat exchanger construction across mining and power applications.
Welded technology holds the largest share; microchannel is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANP thermal efficiency mandates anchor Brazilian demand across the Southeast industrial corridor, while Mexico's NOM energy efficiency standards compress replacement timelines in northern refining and petrochemical clusters. Argentina's IRAM certification requirements and Chile's SEC thermal performance regulations create compliance thresholds that filter import channels and concentrate procurement among established regional suppliers.
Brazil
Petrobras refining upgrades and private sector petrochemical expansions drive welded plate heat exchanger procurement. ANP thermal performance thresholds force equipment turnover at legacy facilities. São Paulo state's Cubatão petrochemical complex and Rio de Janeiro's refining corridor concentrate demand for corrosion-resistant titanium units.
Mexico
NOM-001-ENER and NOM-013-ENER efficiency audits trigger systematic HVAC and process cooling replacement across industrial facilities. Pemex refining modernization and private downstream investments accelerate demand. Tamaulipas and Veracruz petrochemical installations prioritize certified plate configurations to satisfy compliance deadlines.
Argentina
IRAM certification procedures extend equipment approval cycles, delaying project commissioning for infrastructure developers. Bahía Blanca's petrochemical hub sustains demand for specialized chemical processing configurations. Buenos Aires industrial belt operators navigate import qualification complexity through established supplier partnerships.
Chile
SEC thermal performance regulations and freshwater scarcity constraints accelerate air-cooled system adoption in copper mining operations. Northern Antofagasta Region extraction sites convert cooling infrastructure to reduce water dependence. Santiago commercial building compliance deadlines compress HVAC replacement timelines.
Colombia
Heavy crude thermal extraction projects in the Llanos Basin require specialized high-viscosity heat exchanger designs currently undersupplied by regional fabricators. Ecopetrol unconventional oil development creates specification gaps. Bogotá industrial distributors bridge supply through European and North American import channels.
Latin America Heat Exchanger Market Key Industry Players
Integrated thermal solutions providers and specialized component fabricators split the market along service intensity lines. European-headquartered multinationals with Latin American aftermarket logistics dominate premium process applications, while regional distributors retain price-sensitive HVAC and light industrial segments. Two strategic archetypes anchor competitive positioning: full-lifecycle service integrators leveraging predictive maintenance platforms, and capital-efficient fabricators competing on equipment cost and delivery speed. Consolidation pressure intensifies as end-users demand localized parts inventory commitments and direct technical support access.
Within the full-lifecycle service tier, Alfa Laval AB and Kelvion Holding GmbH exemplify archetypes built on aftermarket parts logistics and localized production respectively. Danfoss A/S occupies a position bridging component supply and packaged system integration. These three European-origin entities anchor the competitive structure through differentiated approaches to technical support density and manufacturing proximity.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Danfoss A/S |
| Kelvion Holding GmbH |
| GEA Group Aktiengesellschaft |
| API Heat Transfer |
| Xylem Inc |
| Johnson Controls International plc |
| Chart Industries Inc |
| FUNKE Wärmeaustauscher Apparatebau GmbH |
| Others |
Cost & Logistics Intelligence
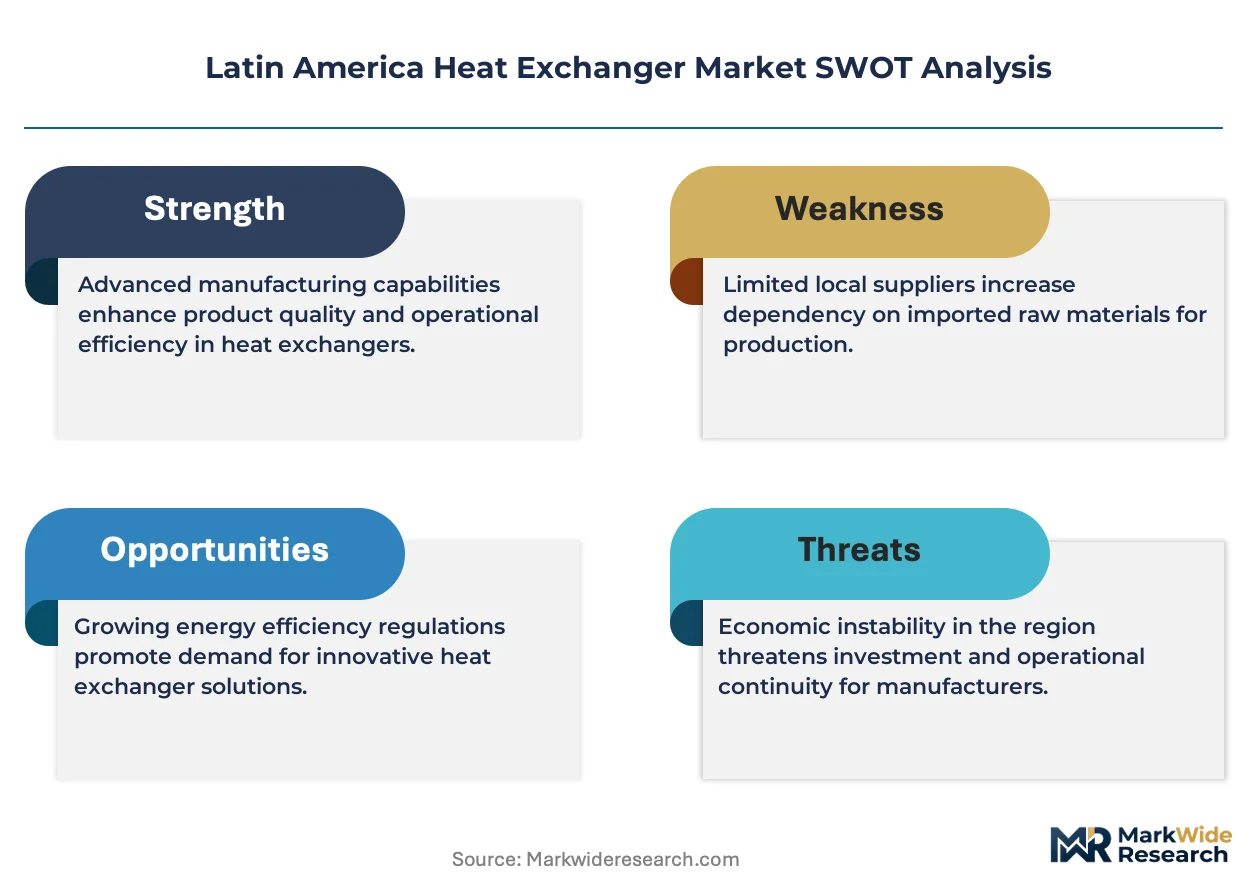
Nickel price volatility functions as the dominant risk vector governing both pricing tier spreads and supply chain configuration across Latin American heat exchanger markets. Alloy input cost spikes compress fabricator margins unevenly, forcing shell-and-tube producers with fixed-price contracts into deeper discounting while welded plate specialists with material pass-through clauses preserve premium positioning.
Pricing Analysis
The customization-premium spread separates configured-to-order titanium welded plate units from standard carbon steel shell-and-tube configurations. Project-based pricing dominates process equipment procurement, with differentiation driven by certification level (ANP compliance tier for Brazilian refineries, NOM-001-ENER efficiency grade for Mexican installations) and after-sales service bundling. Cost compression in standard HVAC brazed plate segments is intensifying because Kelvion's localized Mexican production erodes import markups. Industrial facility operators in São Paulo's chemical corridor demonstrate lowest price sensitivity; commercial building HVAC buyers in Santiago and Mexico City exhibit highest.
Supply Chain Analysis
Contract manufacturing concentration for brazed aluminum cores centers on Kelvion's Guadalajara facility and regional Mexican metal fabricators serving HVAC demand. Raw material sourcing draws from Brazilian stainless steel mills, Chinese titanium sponge suppliers, and European nickel alloy producers. Single-source vulnerability concentrates in certified orbital welding services for titanium joints, with qualified labor pools restricted to São Paulo and Monterrey. Distribution runs through industrial distributors in Brazil's Southeast corridor, though OEM direct service networks are displacing traditional channel control in refinery accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified welding capacity scarcity defines competitive positioning across Latin American heat exchanger markets. The gap between qualified titanium alloy fabricators and pre-salt platform demand volumes creates structural bottlenecks that reshape vendor selection criteria.
For Market Incumbents: Build aftermarket parts logistics moats through localized inventory commitments in Rio de Janeiro and Veracruz refinery clusters. Anchor direct technical support density to counter distributor disintermediation threats from São Paulo chemical operators. Pursue backward integration into titanium plate stockholding to offset nickel price volatility exposure in shell-and-tube segments. For New Entrants and Emerging Players: Build out specialized high-viscosity heat exchanger capabilities targeting Colombian Llanos Basin heavy crude thermal extraction projects currently served through European import channels. Capture white-space in Argentina's IRAM-certified equipment segment where approval timelines filter established competitors. Lead with remote monitoring platform integration as differentiated go-to-market positioning against legacy maintenance relationships. For Investors and Strategic Acquirers: Regional fabricators with ANP and NOM testing laboratory partnerships represent priority acquisition targets given regulatory qualification barriers. Long-term viability hinges on service contract revenue streams displacing hardware margin dependence across the analysis window. Monitor IoT sensor adoption rates in Brazilian pre-salt installations as inflection indicator for predictive maintenance platform penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Brazed Plate Production | Kelvion's Guadalajara facility anchors regional HVAC supply against European import costs. |
| Remote Monitoring Platform Integration | IoT sensor deployment in Brazilian refineries opens recurring service contract revenue streams. |
| Titanium Alloy Fabrication Certification | ANP-compliant welding qualifications filter vendor tiers in coastal petrochemical installations. |
| Direct Aftermarket Parts Logistics | São Paulo chemical operators negotiate spare parts supply agreements bypassing distributors. |
| Air-Cooled System Specialization | Northern Chilean copper operations convert cooling infrastructure to reduce freshwater dependence. |
Research Approach
The analysis maps shell-and-tube, plate, air-cooled, and microchannel technology segments, each validated through maintenance directors at Brazilian refineries, procurement leads at Mexican petrochemical installations, and aftermarket service heads at regional distributors. Primary interview insights triangulate against ANP regulatory filings, NOM-001-ENER efficiency certification databases, SEC filings from listed OEMs, and customs trade data on alloy imports. Bottom-up equipment shipment tracking and top-down industrial capital expenditure estimates converge across the analysis window.
Assumption sets held regulatory enforcement timelines and nickel alloy price bands within observed ranges while varying Pemex refining modernization pace and Colombian unconventional oil development scale. Segmentation modeling spans product architecture, end-use intensity, application thermal duty, and fabrication technology dimensions. CAGRs derive from equipment replacement cycle compression analysis under ANP and NOM mandates, with Brazilian pre-salt platform PCHE adoption rates and Mexican HVAC compliance deadlines as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fabricators or accelerated Mercosur tariff harmonization would shift outcomes. Quarterly review of ANP equipment approval timelines, NOM audit completion rates, and certified welder training program graduations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Blowers Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
US Residential Heat Pump Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Centrifugal Chillers Market