
 Europe Hydronic Radiators Market | 2026-2036
Europe Hydronic Radiators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydronic Radiators Market Analysis
Low-temperature specification tiers is collapsing the legacy high-temperature radiator paradigm across European heating renovations. Purmo Group leverages its Baltic manufacturing footprint to supply EN442-certified steel panel systems for heat pump-optimized installations. Zehnder Group differentiates through designer radiator architectures that occupy premium residential and hospitality channels. Kermi anchors technical credibility with corrosion-resistant aluminum constructions for commercial building refurbishments.
Europe hydronic radiators are heat-emitting terminal units engineered for closed-loop hot water circulation, typically operating at supply temperatures between 45°C and 80°C with thermal outputs calibrated per EN442 testing protocols. These devices distribute thermal energy from central boilers, district heating networks, or heat pumps into conditioned spaces through convection and radiant heat transfer. Steel panel radiators sustain dominant volume positions across mass residential replacement cycles, while aluminum constructions represent the fastest-expanding material category due to superior responsiveness in low-temperature heat pump systems. Designer radiators command concentrated margin pools in architect-specified new builds and luxury renovations, whereas cast iron retains niche durability applications in heritage building restorations.
The EU Green Deal and F-Gas Regulation are reshaping product specifications by mandating compatibility with lower flow temperatures and refrigerant-transitioned heat sources. Ecodesign requirements and CE marking under the Construction Products Regulation enforce minimum efficiency thresholds that disqualify legacy high-temperature-only radiator designs from new installations. Stakeholders must monitor national transpositions of the Energy Performance of Buildings Directive and assess whether existing product portfolios align with emerging low-temperature system mandates.
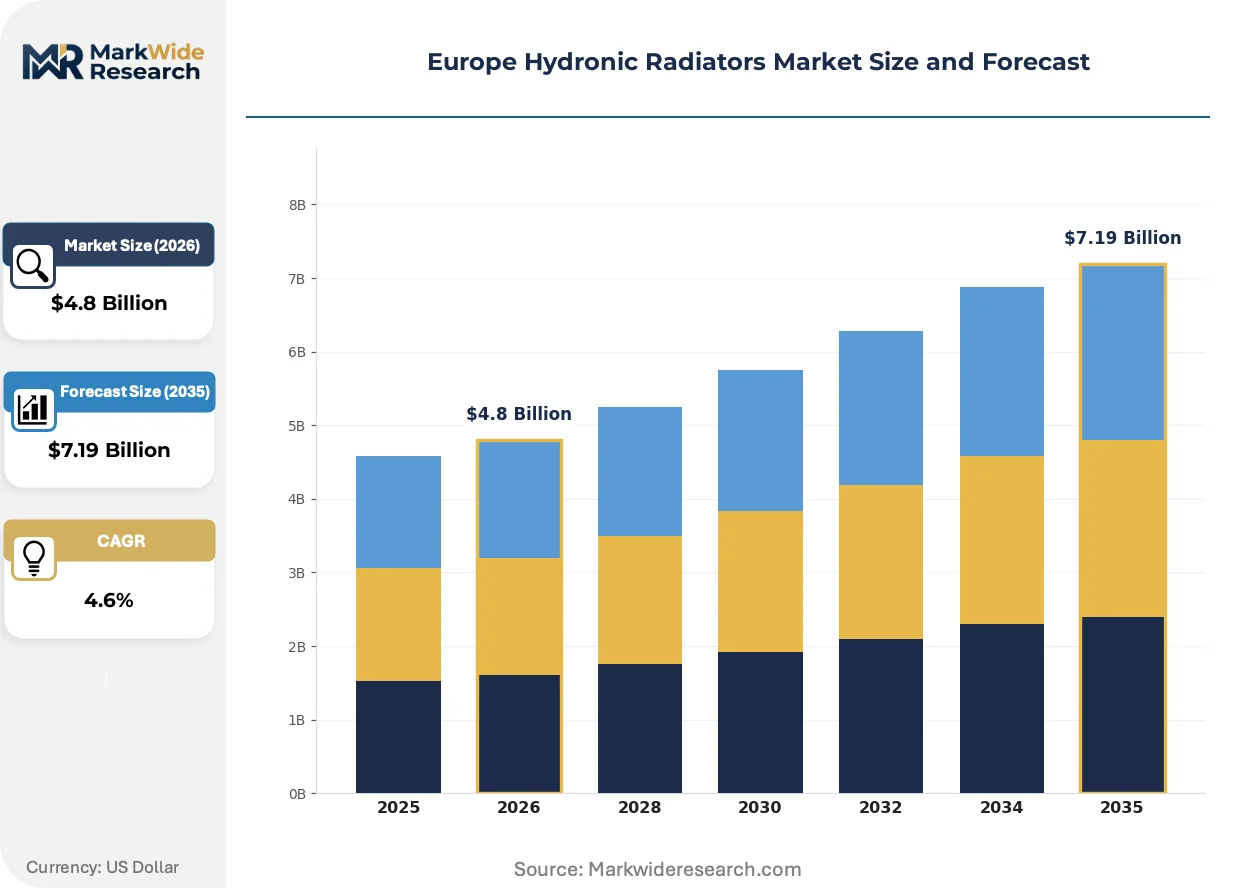
Market Dynamics
The EU Green Deal's tightening Energy Performance of Buildings Directive is collapsing the legacy high-temperature radiator paradigm, forcing wholesale redesign of hydronic terminal units for heat pump compatibility across European renovation cycles.
Growth Catalysts
- EPBD Renovation Mandates:The Energy Performance of Buildings Directive requires member states to achieve zero-emission building stocks by 2050, accelerating replacement of outdated heating systems in Germany, France, and Poland.
- Heat Pump Rollouts:Low-temperature heat pump installations are proliferating across Nordic and Benelux markets, creating pull demand for aluminum radiator constructions optimized for 45-55°C supply temperatures.
- District Heating Modernization:Eastern European cities are retrofitting centralized heat networks with demand-responsive terminal units, opening volume opportunities for EN442-certified steel panel systems.
Market Restraints
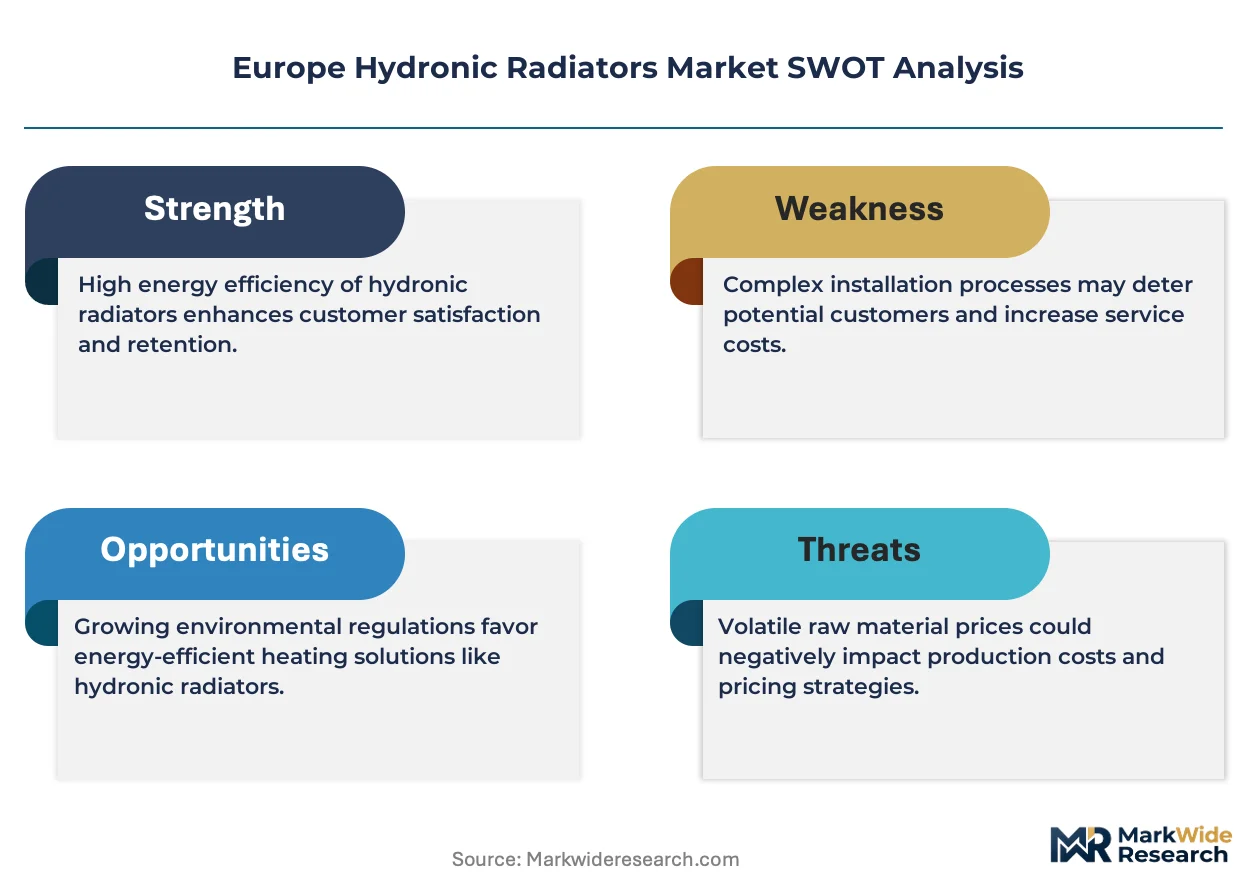
- Steel Price Volatility:Cold-rolled steel coil fluctuations compress margins for mass-market panel radiator manufacturers dependent on commodity feedstock.
- Installation Skill Bottlenecks:Qualified hydronic technicians are concentrated in aging workforces across Germany and Italy, constraining deployment velocity for complex low-temperature system retrofits.
- Heat Pump Cost Barriers:Residential air-source heat pumps remain capital-intensive for Polish and Romanian households, delaying the radiator replacement cycles tied to heat source upgrades.
Strategic Opportunities
- Romanian and Bulgarian New Build:These markets show underpenetrated hydronic heating infrastructure relative to Western European saturation, offering first-mover positioning for EN442-compliant system suppliers.
- CE Marking Harmonization:The Construction Products Regulation's unified compliance pathway reduces certification fragmentation, enabling faster cross-border product launches for aluminum low-temperature designs.
- Heat Pump-Radiator Bundling:OEM partnerships between heat pump manufacturers and radiator producers are creating integrated system offerings that bypass traditional wholesale channels.
Industry Challenges
- Low-Temperature System Design Expertise:Engineering teams lack fluency in heat pump-optimized hydronic calculations, slowing specification transitions from 70°C to 45°C operating regimes.
- Legacy Inventory Stranding:Distributors hold substantial high-temperature-only radiator stock that CE marking and Ecodesign requirements are rendering non-compliant for new installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydronic Radiators Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Steel, Aluminum, Cast Iron, Designer Application: Residential, Commercial, Industrial, Institutional Installation Method: Wall-Mounted, Floor-Mounted, Ceiling-Mounted, Freestanding End User: Homeowners, Contractors, Architects, Facility Managers |
| Companies Covered | Purmo Group, Arbonia AG, Zehnder Group, Kermi, Vasco Group, Buderus, Jaga Heating Products, Watts Water Technologies, Stelrad Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydronic Radiators Market Emerging Trajectories
Product architectures are fragmenting across temperature-performance tiers as heat pump diffusion forces radiator manufacturers to engineer for thermal responsiveness rather than raw output capacity.
Aluminum radiator construction is miniaturizing. These extruded alloy systems deliver superior thermal conductivity for low-temperature operation, enabling Nordic residential installers to specify smaller physical footprints without sacrificing heat output. The technology is compressing installation space requirements while maintaining EN442-certified performance ratings.
The F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in heat pump systems, indirectly reshaping radiator specifications. Lower flow temperatures become mandatory as refrigerant transitions constrain heat pump thermal lift capabilities. Commercial building refurbishments in Germany and the Netherlands are prioritizing aluminum constructions that perform efficiently at reduced supply temperatures.
Specification authority is migrating from mechanical contractors to energy performance consultants. These technical advisors now dominate equipment selection for deep renovation projects in France and Belgium, displacing traditional merchant distributor influence. The shift concentrates purchasing decisions among engineering firms fluent in whole-system efficiency modeling rather than component-level procurement.
Europe Hydronic Radiators Market Segmentation
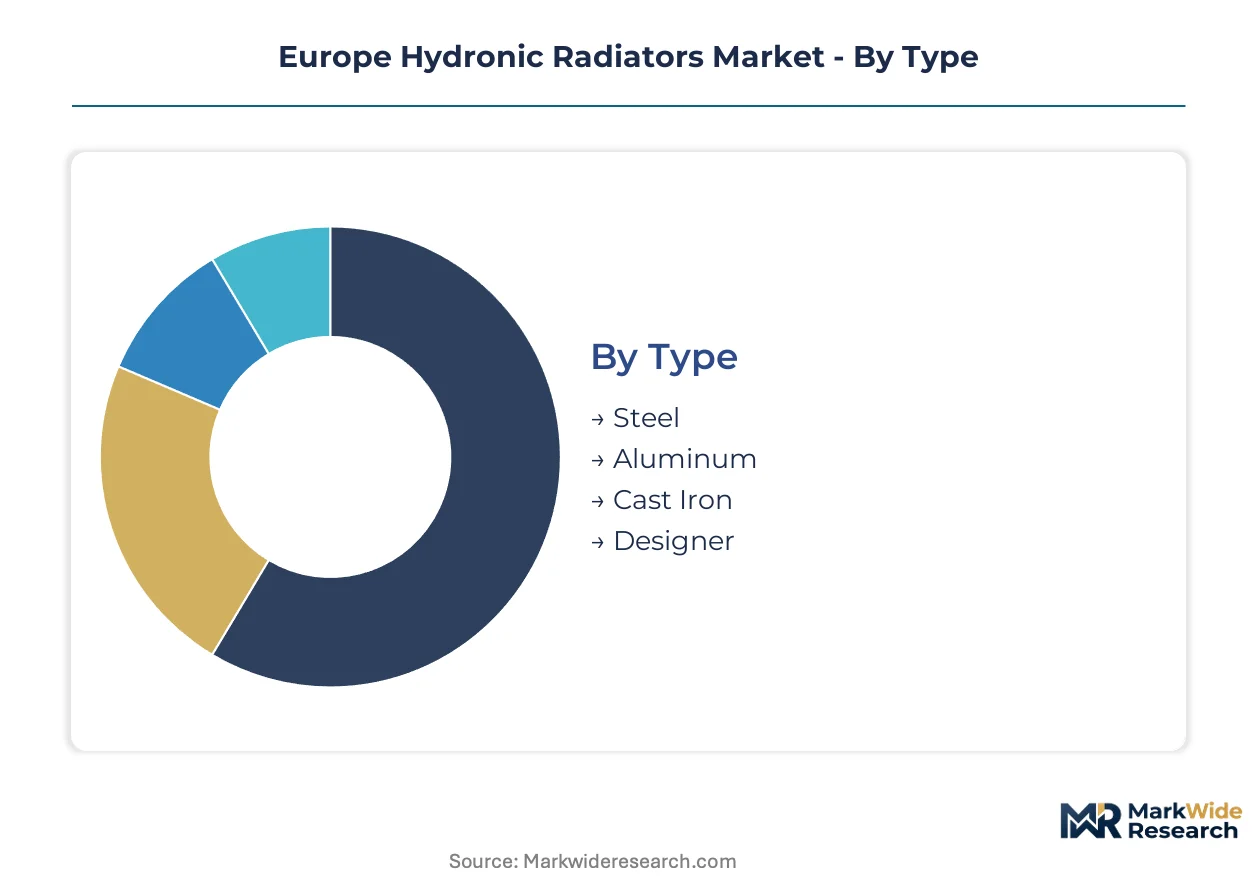
Europe's hydronic radiator segmentation reflects divergent channel economics across material technologies and specification authority. Installer preferences, regulatory compliance tiers, and heat pump compatibility requirements fragment procurement pathways across residential replacement and commercial new build cycles.
Type:
Material-based segments flow through distinct wholesale and specification channels, with mass-market distributors handling volume steel panel sales while aluminum and designer variants route through specialized hydronic merchants and architect-direct procurement.
- Steel:Cold-rolled steel panel constructions dominate volume replacement cycles through merchant distributor networks across Germany, France, and Poland. EN442-certified systems anchor mass residential retrofits where contractors prioritize cost efficiency and installation familiarity over thermal responsiveness. Steel price volatility compresses margins for manufacturers dependent on commodity feedstock procurement.
- Aluminum:Extruded aluminum alloys deliver superior thermal conductivity for low-temperature heat pump pairings, with demand concentrating in Nordic and Benelux markets where 45-55°C supply temperatures are becoming standard. Specification authority migrates toward energy performance consultants selecting these constructions for deep renovation projects in the Netherlands and Denmark.
- Cast Iron:Heritage building restorations in Italy and France sustain niche procurement through specialized restoration contractors.
- Designer:Architect-specified premium channels in hospitality and luxury residential verticals command concentrated margin pools.
Steel dominates installed base across replacement-heavy Western European markets. Aluminum is where expansion concentrates as heat pump diffusion accelerates low-temperature system mandates.
Application:
End-use segmentation maps to divergent specification timelines, with residential replacement cycles running 15-20 years while commercial refurbishments cluster around regulatory compliance deadlines and lease renewal events.
- Residential:Single-family and multi-family housing retrofits in Germany, Poland, and France drive volume demand through contractor-mediated procurement. The EU Green Deal's tightening Energy Performance of Buildings Directive accelerates replacement of outdated high-temperature systems, though heat pump cost barriers delay upgrade cycles in Romanian and Bulgarian households.
- Commercial:Office and retail building refurbishments in Germany and the Netherlands prioritize aluminum constructions compatible with reduced district heating supply temperatures. Facility managers and energy performance consultants now dominate equipment selection, displacing traditional mechanical contractor influence.
- Industrial:Manufacturing facility heating sustains demand for high-output steel panel systems through MRO procurement channels.
- Institutional:School and hospital renovations across Eastern European cities open volume opportunities for EN442-certified demand-responsive terminal units.
Residential applications anchor volume throughput. Commercial refurbishment is climbing the fastest as regulatory deadlines compress specification windows.
Installation Method:
Mounting configurations correlate with construction typology and thermal engineering requirements, with wall-mounted systems retaining default status while floor and ceiling variants gain traction in space-constrained renovations and architect-specified new builds.
- Wall-Mounted:Standard steel panel configurations retain dominant specification share across mass residential replacements, with installers favoring familiar mounting hardware and piping conventions. Polish and German renovation contractors default to these systems unless space constraints or aesthetic requirements mandate alternatives.
- Floor-Mounted:Low-profile aluminum constructions address full-height glazing and curtain wall applications in commercial new builds across Belgium and France, where thermal bridging concerns and space planning priorities displace traditional wall-mounted solutions.
- Ceiling-Mounted:Integrated ceiling systems serve high-end residential and hospitality channels where wall space is reserved for architectural features.
- Freestanding:Designer radiator architectures in premium segments occupy specification niches in architect-directed renovations.
Wall-mounted systems retain default specification status. Floor-mounted configurations are gaining share fastest as commercial glazing ratios increase and low-temperature aluminum miniaturization enables space-efficient thermal output.
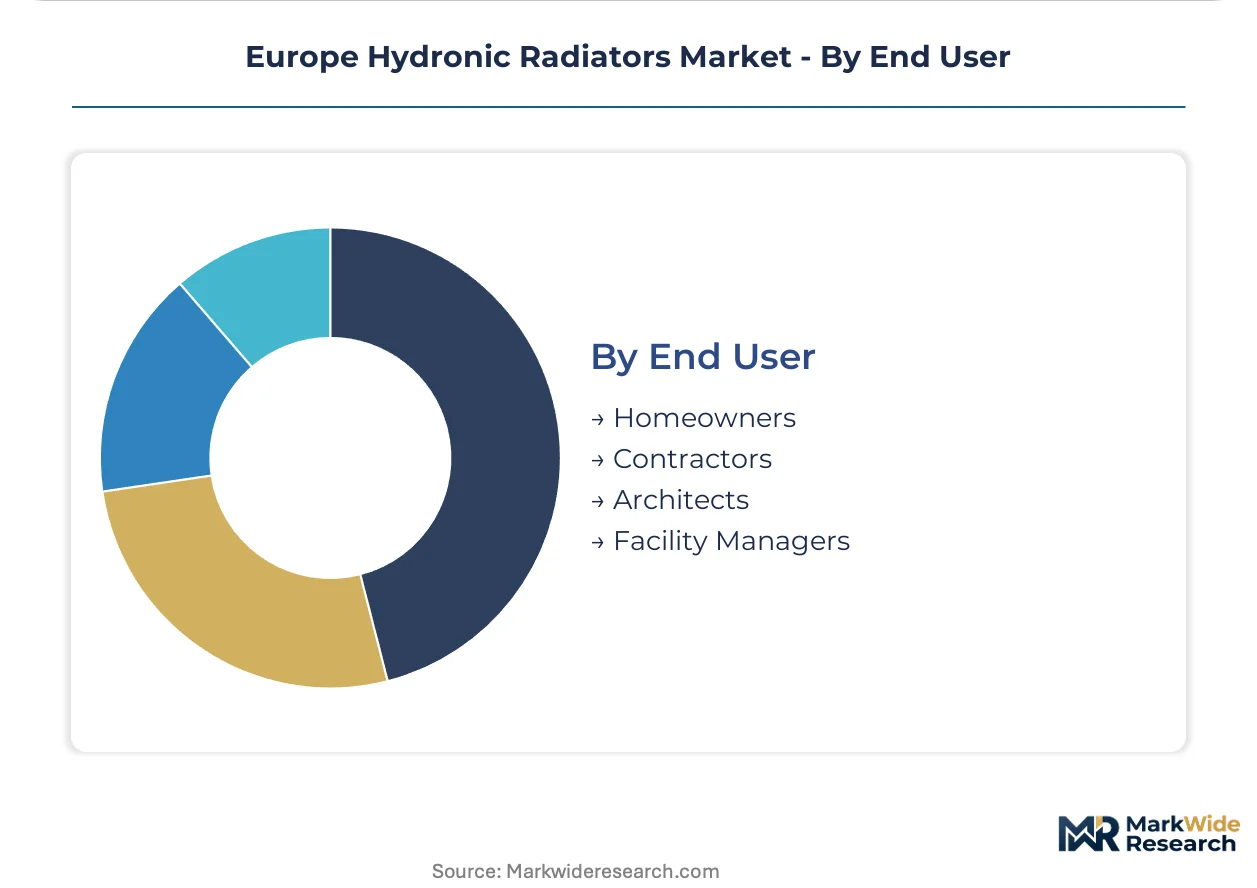
End User:
Procurement authority fragmentation intensifies across stakeholder types, with homeowners and contractors retaining influence in residential replacement while architects and energy consultants capture specification control in commercial and deep renovation contexts.
- Homeowners:Individual households in Germany and France initiate radiator replacement through contractor referrals and merchant distributor showrooms, with purchasing decisions constrained by heat pump bundling economics and available retrofit subsidies. Capital cost sensitivity delays upgrade cycles where heat source replacement is not simultaneous.
- Contractors:Installation firms across Italy and Germany concentrate qualified hydronic technician capacity, becoming gatekeepers for system specification in residential retrofits where their labor availability constrains deployment velocity.
- Architects:Design professionals dominate premium residential and hospitality channel procurement, specifying designer radiator architectures that occupy concentrated margin pools.
- Facility Managers:Commercial building operators in the Netherlands and Germany increasingly delegate equipment selection to energy performance consultants fluent in whole-system efficiency modeling.
Contractors and homeowners anchor residential volume channels. Architects and facility managers are where margin expansion concentrates as specification authority migrates toward technical advisory roles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel panel manufacturing clusters concentrate in Poland and Germany, supplying EN442-certified systems across Central European renovation corridors. Baltic production bases serve Nordic low-temperature heat pump markets with aluminum extrusion capabilities.
Germany
Residential retrofit volumes in North Rhine-Westphalia and Bavaria drive steel panel demand as the KBA enforces building energy performance upgrades. The EU Green Deal's EPBD transposition mandates heat pump compatibility for replacement installations. Frankfurt and Stuttgart contractor networks specialize in low-temperature system conversions for multi-family housing stock.
France
Île-de-France and Auvergne-Rhône-Alpes lead aluminum radiator specification for heat pump pairings in deep renovation projects. ANSM-aligned energy performance consultants now dominate equipment selection for commercial refurbishments. Lyon-based engineering firms specify demand-responsive terminal units for district heating modernization.
Poland
Warsaw and Kraków residential districts accelerate replacement cycles as national building codes tighten under EU Green Deal compliance timelines. Polish steel fabrication clusters supply cost-efficient panel systems for mass-market retrofits. Silesian manufacturing bases export EN442-certified units to Romanian and Bulgarian new build markets.
Netherlands
Randstad urban corridors prioritize aluminum constructions for 45-55°C heat pump operation in low-energy building renovations. Dutch energy performance consultants specify miniaturized radiator architectures for space-constrained Amsterdam and Rotterdam housing. CE marking harmonization enables rapid cross-border product launches from Benelux distribution hubs.
Sweden
Stockholm and Gothenburg residential markets mandate low-temperature system designs compatible with air-source heat pump diffusion. Nordic installer networks specify aluminum extrusion systems for superior thermal responsiveness at reduced supply temperatures. Swedish district heating operators retrofit demand-responsive terminal units across multi-family housing portfolios.
Europe Hydronic Radiators Market Vendor Landscape
Concentration sits with integrated heating system specialists and regional steel fabricators competing across distinct specification channels. The vendor base separates into three archetypes: Baltic-manufacturing volume players serving mass residential replacement, premium designer radiator architects, and aluminum specialists optimized for heat pump pairings. Strategic moves center on OEM bundling partnerships with heat pump manufacturers and backward integration into steel coil procurement to defend margin positions against commodity volatility.
Among Nordic and Central European manufacturers, Purmo Group, Zehnder Group, and Kermi exemplify divergent competitive positioning. Purmo Group occupies the volume-tier with Baltic production scale for EN442-certified steel panel distribution. Zehnder Group represents the premium-channel archetype through architect-specified designer radiator architectures. Kermi anchors the technical-specialist position with aluminum constructions for low-temperature commercial applications. These three patterns illustrate how material technology specialization and channel focus fragment competitive dynamics across European renovation cycles.
| Leading Market Players |
|---|
| Purmo Group |
| Arbonia AG |
| Zehnder Group |
| Kermi |
| Vasco Group |
| Buderus |
| Jaga Heating Products |
| Watts Water Technologies |
| Stelrad Group |
| Others |
Supply Flow & Price Mechanics
Baltic manufacturing scale economies concentrate EN442-certified steel panel production in Estonia and Latvia, compressing unit economics for mass-market radiator suppliers while establishing price floors that commodity-dependent fabricators struggle to breach. This capacity clustering funnels volume procurement through Polish and German distribution hubs, amplifying pricing power for integrated producers with captive coil supply.
Pricing Analysis
CE marking under the Construction Products Regulation dictates the pricing tier structure across European hydronic radiator markets, separating EN442-certified systems from non-compliant legacy inventory. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal performance certification and heat pump compatibility grades, with designer aluminum architectures commanding architect-specified premiums. Cost compression in standard steel panels is intensifying because cold-rolled coil volatility erodes fabricator margins. Polish and Romanian residential contractors exhibit highest price sensitivity, while Dutch energy performance consultants prioritize thermal efficiency over unit cost.
Supply Chain Analysis
Danish Straits maritime transit underwrites raw material flows for Nordic aluminum extrusion facilities serving low-temperature heat pump markets. Manufacturing concentrates in Poland, Germany, and the Baltic states, with steel coil feedstock drawing from Ukrainian and Russian-origin suppliers subject to trade restriction volatility. Supply chain risk centers on single-source dependency for specialized aluminum alloys used in corrosion-resistant commercial constructions. Distribution runs through merchant wholesale networks across Central Europe, with specification-grade products bypassing traditional channels via OEM heat pump bundling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across material technologies and specification channels creates multiple viable positioning niches as heat pump diffusion rewrites procurement authority. The collapse of legacy high-temperature system demand generates entry points for specialized low-temperature suppliers.
For Market Incumbents: Fortify Baltic production scale through backward integration into steel coil procurement, insulating margin positions against commodity volatility while extending EN442-certified capacity. Deepen OEM bundling partnerships with heat pump manufacturers to bypass wholesale channel displacement, and invest in aluminum extrusion capabilities for Nordic low-temperature specification capture. For New Entrants and Emerging Players: Differentiate on heat pump-optimized thermal responsiveness rather than raw output capacity, targeting Romanian and Bulgarian new build markets with underpenetrated hydronic infrastructure. Architect-direct specification for commercial glazing-intensive projects in Belgium and France offers the most penetrable premium channel, with floor-mounted low-profile aluminum systems as the specific go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated heating system specialists with OEM bundling relationships and district heating modernization contracts. Long-term viability hinges on regulatory alignment with EPBD renovation mandates and F-Gas Regulation refrigerant transitions. Acquisition targets should demonstrate aluminum low-temperature engineering depth and Baltic or Polish manufacturing footprint. The signal to watch as inflection indicator is national transposition timelines for Energy Performance of Buildings Directive zero-emission building deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Supply | Captive raw material sourcing defends margins against commodity volatility for Polish fabricators. |
| OEM Heat Pump Bundling Partnerships | Integrated system offerings bypass traditional wholesale channels in German and Dutch markets. |
| Aluminum Extrusion Capacity Expansion | Low-temperature thermal responsiveness captures Nordic and Benelux heat pump specification. |
| CE Marking Harmonization Investment | Unified compliance pathway accelerates cross-border launches for aluminum low-temperature designs. |
| Architect-Direct Specification Programs | Premium designer radiator channels command concentrated margin pools in French hospitality. |
Methodological Framework
Cross-validation between installer interviews and regulatory filing analysis anchors the qualitative findings across European hydronic radiator markets. Primary fieldwork encompassed heating system contractors, energy performance consultants, merchant distributor procurement managers, and OEM heat pump engineering teams. Secondary validation drew from EU Construction Products Regulation filings, national building code transposition documents, EN442 certification registries, and district heating operator procurement disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation converged on volume and value estimates.
Sensitivity analysis tested forecast robustness against steel price volatility scenarios and heat pump adoption pace variations across the projection horizon. The analytical framework segmented by material technology, application type, installation method, and end-user procurement authority, with heat pump compatibility tier as the industry-specific dimension. CAGRs derived from regression against renovation cycle timing, regulatory compliance deadlines, and heat source transition economics, incorporating EPBD mandate intensity and F-Gas Regulation refrigerant phase-down schedules as forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated heat pump subsidy withdrawal would require recalibration. Forecasts reflect documented assumptions regarding renovation cycle timing and material substitution elasticity. Practitioners should keep alternative scenarios live as national EPBD transposition timelines and district heating modernization commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
Thermo Ventilators Market