
 Pneumatic Conveying Systems Market | 2026-2036
Pneumatic Conveying Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Conveying Systems Market Intelligence
Buyer concentration in European pharmaceutical manufacturing is pivoting toward integrated facility engineering firms that specify entire pneumatic material-handling trains. Schenck Process Holding GmbH sustains technology leadership in dense-phase weighing and feeding integration for chemical processors. Dynamic Air Inc. anchors North American market presence through specialization in abrasive-material handling systems for mining and minerals applications. Piab AB leverages its vacuum technology portfolio to compete across food and pharmaceutical clean-room installations.
Pneumatic conveying systems transport dry bulk materials through enclosed pipelines using differential air pressure or vacuum, with operating velocities ranging from 15 m/s in dilute-phase systems to below 5 m/s in dense-phase configurations to prevent degradation of fragile powders. These systems eliminate dust emissions, reduce manual handling, and enable continuous process integration across batch and continuous manufacturing environments. Dilute-phase systems occupy the largest installed base due to lower capital cost and simpler maintenance, though dense-phase technology is displacing legacy equipment in chemical processing where particle attrition and line wear carry significant economic penalties. Powder conveying within pharmaceutical clean-room suites commands premium pricing and requires validation documentation that locks in supplier relationships across replacement cycles.
OSHA combustible-dust standards and EPA National Emission Standards for Hazardous Air Pollutants shape system design requirements in U.S. manufacturing facilities, mandating explosion-venting and filtration configurations that increase engineering complexity. REACH registration obligations in Europe restrict polymer and additive compositions used in pipeline liners and seals, directly influencing material-selection decisions by Coperion GmbH and Nilfisk Group for EU-domiciled customers. Stakeholders must monitor evolving MEE enforcement in China and emerging state-level dust-regulation harmonization in India to anticipate where certification burdens will concentrate and which system architectures will secure market access.
Market Dynamics
Pharmaceutical manufacturers are consolidating procurement around integrated facility engineering firms that specify complete pneumatic material-handling trains, compressing vendor fragmentation into single-source accountability structures.
Growth Catalysts
- FDA contamination-prevention mandates:Automated powder handling systems eliminate manual intervention risks in sterile suites. Validation documentation requirements lock supplier relationships across replacement cycles.
- MEE dust-emission enforcement:China's Ministry of Ecology and Environment rules force cement producers toward vacuum-system retrofits. Compliance deadlines accelerate capital deployment.
- Dense-phase chemical processing:Germany's chemical corridor adopts low-velocity conveying to prevent particle attrition. Line wear reduction delivers measurable operating cost savings.
Market Restraints
- Stainless steel input volatility:Pipeline and vessel fabrication depends on austenitic grades subject to nickel price swings. Margin pressure concentrates on European fabricators.
- Specialized blower supplier concentration:Positive-displacement blower manufacturing clusters in Germany and Japan. Geopolitical friction threatens spare-part availability.
- Mechanical conveying substitution:Bucket elevators and screw conveyors retain cost advantage in short-distance, non-hazardous applications. Price-sensitive buyers in bulk agriculture defer pneumatic adoption.
Strategic Opportunities
- India's state-level dust harmonization:Emerging regulations in Maharashtra and Gujarat create certification windows for explosion-vented systems. Early entrants capture specification influence.
- AI-driven predictive maintenance:Vibration and pressure sensors feed machine-learning models for blower failure anticipation. Food processors in Denmark pilot subscription-based uptime guarantees.
- Modular skid-mounted units:Pre-engineered packages reduce field installation labor and commissioning time. Contract manufacturers in Poland target mid-scale chemical batch operations.
Industry Challenges
- ATEX and IECEx certification timelines:Explosion-protection documentation for zone-classified installations extends delivery schedules. Project managers face penalty clauses.
- Legacy DCS integration complexity:Brownfield pharmaceutical sites operate proprietary control architectures. Protocol translation adds engineering hours and commissioning risk.
- Pneumatic conveying simulation expertise scarcity:Computational fluid dynamics modeling for dense-phase saltation prediction requires specialized training. Engineering consultancies compete for limited talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Conveying Systems Market |
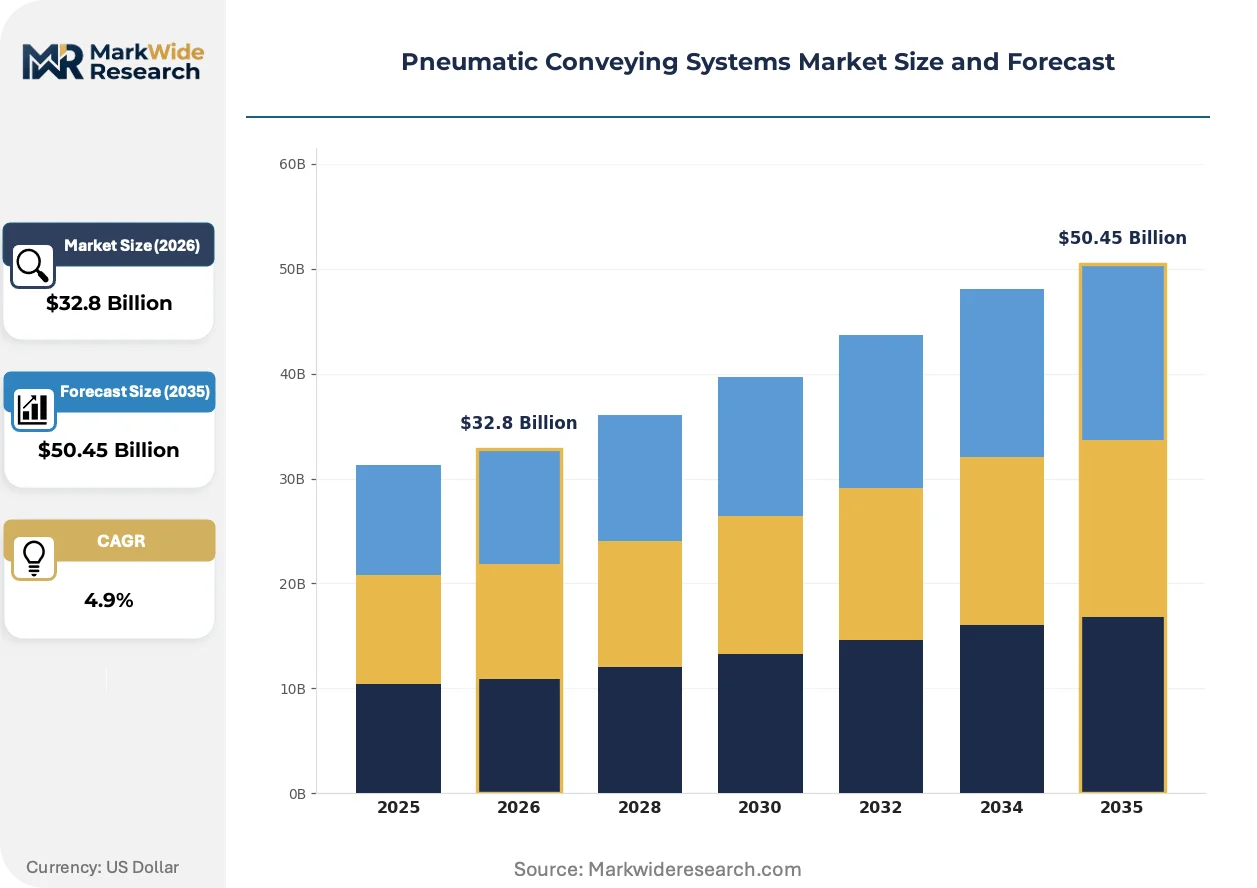
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $50.45 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Dense Phase, Dilute Phase, Vacuum, Pressure Material Conveyed: Powders, Granules, Pellets, Fibers, Flakes Application Sector: Food Processing, Chemical Processing, Mining Operations, Pharmaceuticals, Cement Manufacturing End User Industry: Metal Refining, Plastics Fabrication, Paper Production, Textiles, Building Materials |
| Companies Covered | Flexicon Corporation, Cyclonaire Corporation, Dynamic Air Inc., Piab AB, Schenck Process Holding GmbH, Atlas Copco AB, VAC-U-MAX, Nilfisk Group, Coperion GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Conveying Systems Market Strategic Shifts & Innovations
Digital twin deployment and materials science advances are compressing system design cycles while expanding the addressable application range beyond traditional bulk solids into fragile and reactive chemistries.
Plug-and-play dense-phase conveying skids are modularizing project execution for chemical processors. Standardized vessel, blower, and control configurations reduce custom engineering from months to weeks. Lanxess and BASF pilot these units in Ludwigshafen to accelerate line changeovers.
REACH registration obligations restrict polymer compositions for pipeline liners and seals. ECHA substance evaluations force Coperion and Nilfisk to reformulate elastomer specifications. EU-domiciled chemical customers now require full material disclosure documentation.
Integrated facility engineering firms are unbundling after-sales service from equipment supply. Pharmaceutical buyers in Switzerland and Ireland negotiate performance-based maintenance contracts tied to uptime metrics. Schenck Process and Piab respond with remote diagnostic platforms and regional spare-part hubs.
Pneumatic Conveying Systems Market Segmentation
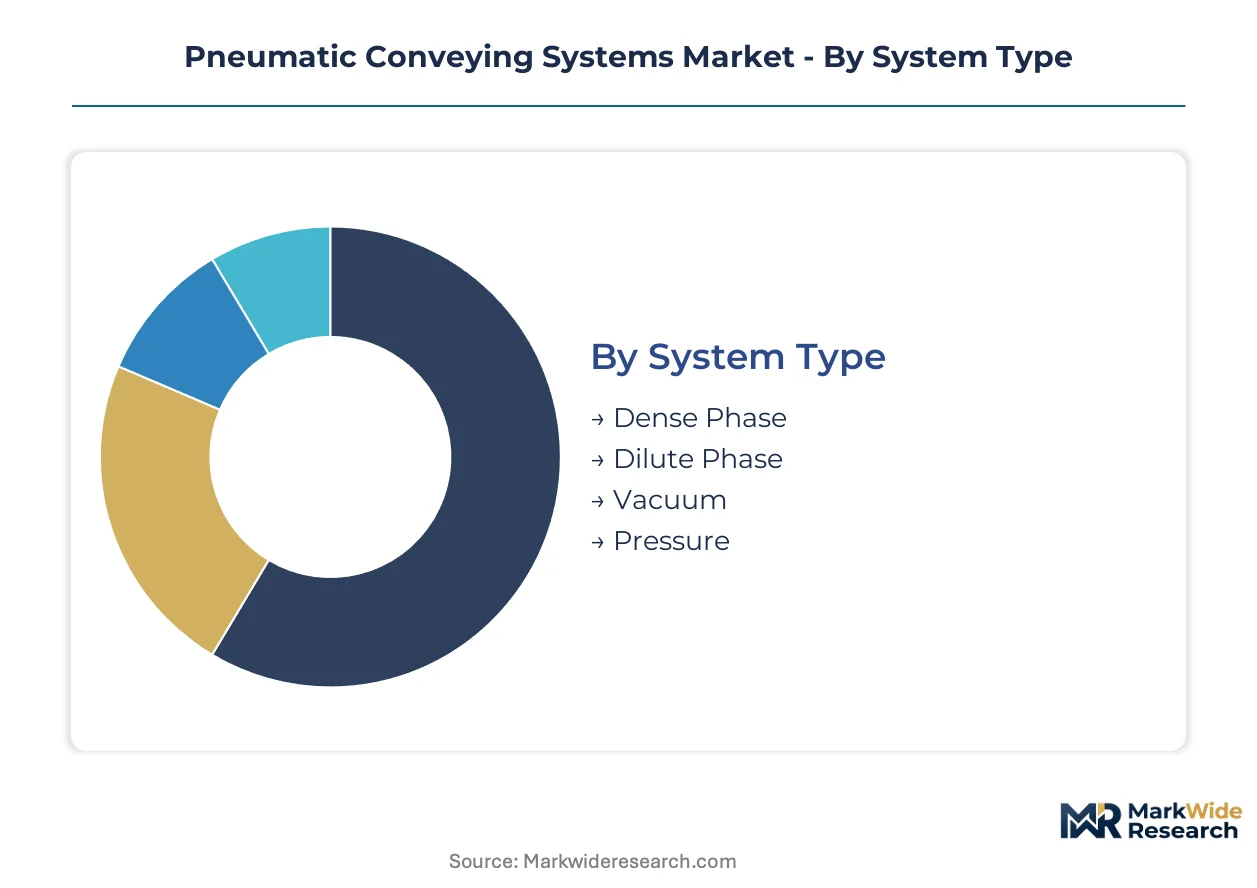
Pneumatic conveying architectures vary dramatically in capital intensity, operating velocity, and regulatory compliance burden. System selection locks in lifecycle costs and determines which supplier ecosystems become accessible to buyers. Segmentation reveals where technology substitution is displacing legacy equipment and which material classes command premium engineering margins.
System Type:
Customization intensity spans from standardized blower packages to fully engineered dense-phase trains with proprietary saltation modeling. Dilute-phase systems cluster at the commodity end of this spectrum, while vacuum and dense-phase configurations demand application-specific design.
- Dense Phase:Low-velocity conveying below 5 m/s prevents particle attrition in fragile chemistries. Germany's chemical corridor drives specification, with Lanxess and BASF piloting modular skids in Ludwigshafen to accelerate line changeovers and reduce engineering lead times.
- Dilute Phase:High-velocity systems operating at 15 m/s dominate installed base due to lower capital cost and simpler maintenance. Cement producers in China under MEE dust-emission rules deploy these for high-volume material transfer where particle degradation carries limited economic penalty.
- Vacuum:Negative-pressure configurations eliminate dust emissions at pickup points. Pharmaceutical clean-room suites in Switzerland and Ireland specify these for sterile powder handling with validation documentation locking supplier relationships.
- Pressure:Positive-pressure systems achieve longer conveying distances and higher throughputs. Mining operations in abrasive-material applications favor these for their robustness against line wear.
Leading the category by volume: Dilute Phase. Expanding most quickly: Dense Phase.
Material Conveyed:
Physical properties dictate system architecture, with particle size distribution and friability determining velocity thresholds and pipeline material selection.
- Powders:Fine particulates below 500 microns require careful velocity control to prevent segregation and electrostatic buildup. Pharmaceutical manufacturers expanding automated material handling to meet FDA contamination-prevention mandates drive specification of vacuum-compatible powder systems.
- Granules:Intermediate particle sizes offer forgiving conveying characteristics across system types. Food processing applications in Denmark pilot AI-driven predictive maintenance on granule-handling lines to guarantee uptime through subscription models.
- Pellets:Uniform geometry enables high-velocity dilute-phase transport with minimal attrition. Plastics fabrication facilities favor these for continuous feed to extrusion operations.
- Fibers:Aspect ratios above 10:1 create bridging and entanglement risks requiring specialized feeder designs. Textile producers specify low-velocity dense-phase to preserve fiber integrity.
- Flakes:Irregular shapes with high surface-area-to-mass ratios demand gentle handling. Paper production facilities processing recycled fiber streams use vacuum systems to prevent dust generation.
Widest application span: Granules. Steepest specification growth: Powders.
Application Sector:
Regulatory intensity and contamination sensitivity create tiered demand patterns, with pharmaceutical and food processing commanding engineering premiums over bulk mineral handling.
- Food Processing:Hygienic design requirements and allergen segregation protocols dominate system specification. Clean-in-place compatibility and FDA-compliant contact materials lock in supplier relationships across replacement cycles.
- Chemical Processing:Reactive and hazardous material handling drives explosion-protection engineering. Germany's chemical corridor adopts dense-phase technology to reduce particle attrition and line wear in continuous operations.
- Mining Operations:Abrasive mineral transport prioritizes pipeline durability over energy efficiency. Bucket elevators and mechanical conveyors retain cost advantage in short-distance applications, compressing pneumatic adoption to hazardous or remote installations.
- Pharmaceuticals:Sterile powder handling in classified clean rooms commands highest engineering margins. Validation documentation requirements and ATEX certification timelines extend delivery schedules and concentrate procurement around integrated facility engineering firms.
- Cement Manufacturing:High-volume bulk transport under environmental compliance pressure. China's Ministry of Ecology and Environment dust-emission rules force vacuum-system retrofits with accelerated capital deployment to meet compliance deadlines.
Highest margin concentration: Pharmaceuticals. Fastest regulatory-driven upgrade cycle: Cement Manufacturing.
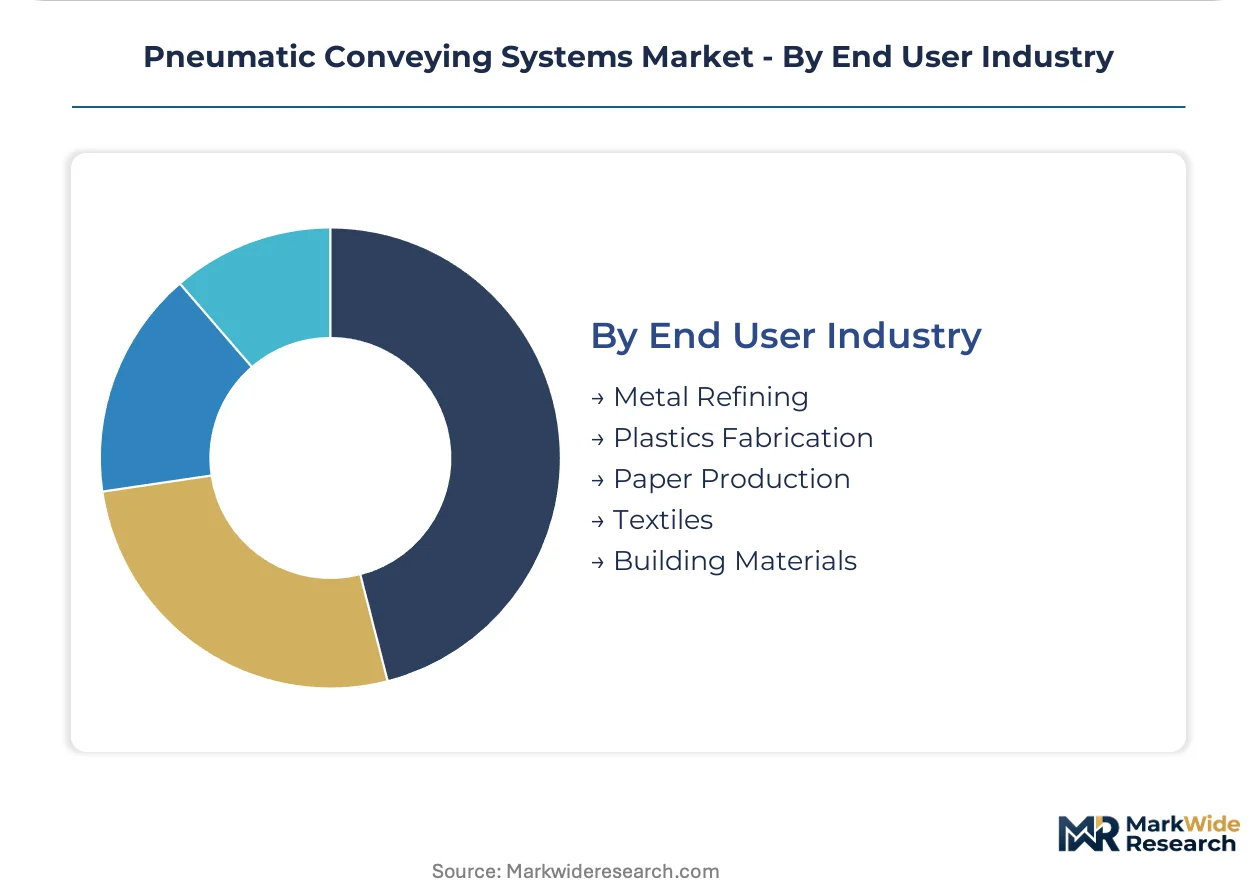
End User Industry:
Downstream process integration requirements determine control system complexity and the premium commanded by modular skid-mounted configurations.
- Metal Refining:High-temperature and reactive material handling demands specialized pipeline liners. REACH registration obligations in Europe restrict polymer compositions, forcing material disclosure documentation from suppliers.
- Plastics Fabrication:Continuous feed requirements to extrusion and compounding lines favor reliable dilute-phase systems. Resin pellet conveying dominates specification.
- Paper Production:Recycled fiber handling with high moisture variability requires adaptive blower control. Vacuum systems prevent dust emissions in open-plan mill layouts.
- Textiles:Synthetic fiber preservation demands gentle dense-phase transport. Building materials producers in Poland target mid-scale chemical batch operations with modular skid-mounted units to reduce field installation labor.
- Building Materials:Price-sensitive bulk handling with limited contamination risk. Mechanical conveying substitution retains cost advantage, deferring pneumatic adoption to dust-regulated environments.
Largest installed base: Plastics Fabrication. Fastest modularization uptake: Metal Refining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Switzerland and Ireland concentrate procurement authority around integrated facility engineering firms, while cement producers across China accelerate vacuum-system deployments under tightening environmental enforcement.
United States
Pharmaceutical clean-room suites in New Jersey and Massachusetts drive specification of validated powder-handling systems. OSHA combustible-dust standards and EPA National Emission Standards for Hazardous Air Pollutants mandate explosion-venting configurations that extend engineering timelines. Mining operations in Arizona and Nevada favor abrasive-material handling systems for remote mineral transport.
Germany
Lanxess and BASF in Ludwigshafen pilot modular dense-phase skids to reduce particle attrition in continuous chemical processing. REACH registration obligations restrict polymer compositions for pipeline liners and seals, forcing material disclosure documentation. The chemical corridor along the Rhine anchors European demand for low-velocity conveying technology.
China
Cement producers in Hebei and Shandong provinces retrofit vacuum systems to comply with MEE dust-emission rules ahead of accelerated compliance deadlines. The Yangtze River Delta concentration of building materials manufacturers faces intensifying environmental inspection regimes. Vacuum-system upgrades dominate capital deployment in bulk minerals handling.
Switzerland
Pharmaceutical manufacturers in Basel negotiate performance-based maintenance contracts tied to uptime metrics for sterile powder handling. Swissmedic validation requirements lock supplier relationships across replacement cycles. Clean-room installations command premium engineering margins with extended ATEX certification timelines.
India
Emerging state-level dust-regulation harmonization in Maharashtra and Gujarat creates certification windows for explosion-vented systems. Pharmaceutical manufacturers in Hyderabad and Mumbai expand automated material handling to meet contamination-prevention standards. Early entrants capture specification influence before regulatory deadlines crystallize.
Pneumatic Conveying Systems Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular skid configurations and AI-driven predictive maintenance subscriptions. The vendor base organizes around three strategic archetypes: integrated facility engineering firms that specify complete material-handling trains, specialized dense-phase technology providers, and vacuum-system specialists serving pharmaceutical clean-room applications. Dominant competitive moves include geographic expansion through regional spare-part hubs and portfolio diversification into subscription-based uptime guarantees.
Within the dense-phase technology tier, Schenck Process Holding GmbH and Coperion GmbH exemplify European engineering-centric positioning. Dynamic Air Inc. anchors North American presence through specialization in abrasive-material applications. These three occupy distinct competitive spaces without direct overlap in core technology emphasis.
| Leading Market Players |
|---|
| Flexicon Corporation |
| Cyclonaire Corporation |
| Dynamic Air Inc. |
| Piab AB |
| Schenck Process Holding GmbH |
| Atlas Copco AB |
| VAC-U-MAX |
| Nilfisk Group |
| Coperion GmbH |
| Others |
Cost & Logistics Intelligence
MEE dust-emission enforcement in China gates qualified vacuum-system supply and reserves premium-tier pricing access for vendors with validated clean-room documentation. Stainless steel input volatility and specialized blower supplier concentration in Germany and Japan compress margins for European fabricators while amplifying pricing power for integrated facility engineering firms.
Pricing Analysis
Volume concentrates in dilute-phase commodity systems while margins accrue to dense-phase and vacuum configurations for pharmaceutical clean-room applications. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified pharmaceutical trains from chemical processing skids and bulk mineral blowers. Cost compression in standard-tier dilute-phase equipment is intensifying because mechanical conveying substitutes retain cost advantage in short-distance agriculture applications. Cement manufacturers in China exhibit highest price sensitivity; Swiss pharmaceutical buyers negotiating performance-based maintenance contracts show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from integrated facility engineering firms specifying complete material-handling trains. Manufacturing concentrates in Germany, China, and Japan for blowers and control systems; pipeline fabrication draws from Italy, Poland, and India for stainless steel vessels. Nickel price volatility in austenitic grades and REACH-restricted polymer compositions for liners constitute raw material dependencies. Single-source vulnerability in positive-displacement blower manufacturing clusters threatens spare-part availability during geopolitical friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized blower manufacturing concentration in Germany and Japan props pricing for qualified suppliers, constraining capacity expansion and sustaining margin premiums for validated system architectures.
For Market Incumbents: Deepen backward integration into stainless steel vessel fabrication to offset nickel price volatility compressing European margins. Expand regional spare-part hub presence in India before state-level dust harmonization crystallizes procurement relationships. Invest in AI-driven predictive maintenance platforms to defend against emerging subscription-based uptime guarantee competitors in food processing. For New Entrants and Emerging Players: MEE enforcement in China opens a window for vacuum-system retrofit specialists targeting Hebei and Shandong cement producers ahead of accelerated compliance deadlines. Target modular skid-mounted configurations for mid-scale chemical batch operations in Poland where field installation labor costs deter incumbent customization. Pursue specification influence through early ATEX certification investment in Maharashtra and Gujarat before regulatory deadlines mature. For Investors and Strategic Acquirers: Pharmaceutical buyers consolidating procurement around integrated facility engineering firms is the leading indicator that single-source accountability structures will concentrate vendor relationships and lock in replacement-cycle revenues. Target dense-phase technology providers with proprietary saltation modeling capabilities and established chemical corridor references. Watch for AI-driven predictive maintenance pilot outcomes in Denmark as signal for subscription model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive vessel production insulates Schenck Process and Coperion from nickel price swings compressing European margins. |
| Modular Skid-Mounted Unit Expansion | Pre-engineered packages reduce Lanxess and BASF line changeover timelines from months to weeks in Ludwigshafen. |
| AI-Driven Predictive Maintenance Launch | Vibration and pressure sensor subscriptions guarantee uptime for Danish food processors piloting machine-learning blower monitoring. |
| Regional Spare-Part Hub Establishment | Proximity inventory in Hyderabad and Mumbai captures specification influence before India's dust harmonization deadlines crystallize. |
| ATEX Certification Acceleration | Explosion-protection documentation completion ahead of Maharashtra and Gujarat regulatory windows secures pharmaceutical and chemical access. |
Research Approach
Trade association filings, customs and import-export databases, and SEC 10-K disclosures from industrial equipment manufacturers formed the secondary backbone for this analysis. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at pneumatic conveying system operators provided operational validation. Bottom-up installation base enumeration and top-down macroeconomic factor adjustment enabled triangulation across data sources.
Historical trendline analysis established baseline growth patterns across system type, material conveyed, application sector, and end user industry segmentation dimensions. CAGRs were derived through regression analysis of correlated industrial capital expenditure indicators and regulatory enforcement timelines. Dense-phase saltation modeling adoption rates and vacuum-system retrofit deployment in cement manufacturing under MEE enforcement served as industry-specific forecast inputs throughout the projection horizon.
Caveats apply where nickel price volatility, REACH polymer composition restrictions, or geopolitical friction in blower manufacturing clusters could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency and industrial capacity expansion timelines. Periodic stress-testing of base assumptions against stainless steel input cost trajectories and ATEX certification timeline extensions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
High Pressure Grease Hose Market