
 Halal Food and Beverages Market | 2026-2036
Halal Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Food and Beverages Market Intelligence
Premium-grade halal certification is rotating toward the center of procurement decisions for multinational foodservice buyers. Nestlé SA leverages its in-house halal compliance infrastructure across manufacturing sites in Malaysia and Indonesia to sustain shelf-space dominance in Southeast Asian retail. Unilever Plc anchors its position through dedicated halal production lines for sauces and spreads, while Al Islami Foods specializes in chilled and frozen halal meat across Gulf Cooperation Council markets.
Halal food and beverages comprise consumable products manufactured, processed, and handled in full compliance with Islamic dietary law, requiring slaughter according to prescribed methods, absence of pork derivatives, alcohol-free formulations, and supply chain segregation from non-halal contaminants. The primary commercial purpose centers on serving Muslim consumer populations while attracting non-Muslim buyers seeking perceived safety and quality assurance. Meat and poultry retains the largest revenue share among product types due to structural reliance on ritual slaughter and cold-chain integrity, though beverages now registers the fastest trajectory as halal-compliant functional drinks and zero-alcohol alternatives capture younger demographics. Online platforms within distribution channels are expanding fastest, driven by direct-to-consumer halal subscription models and cross-border e-commerce penetration.
Indonesia's Badan Penyelenggara Jaminan Produk Halal enforces mandatory certification timelines that reshape export eligibility for foreign suppliers. Malaysia's JAKIM and Singapore's MUIS maintain mutual recognition frameworks that reduce duplication costs for brands operating across ASEAN. Stakeholders must monitor divergence between national halal standards as fragmentation in slaughter methodology rulings and additive permissibility creates compliance complexity for centralized production strategies.
Market Dynamics
Indonesia's mandatory halal certification deadlines under Law No. 33/2014 are forcing supply chain reconfiguration across Southeast Asian food exporters, as compliance gates now determine market access eligibility for foreign manufacturers.
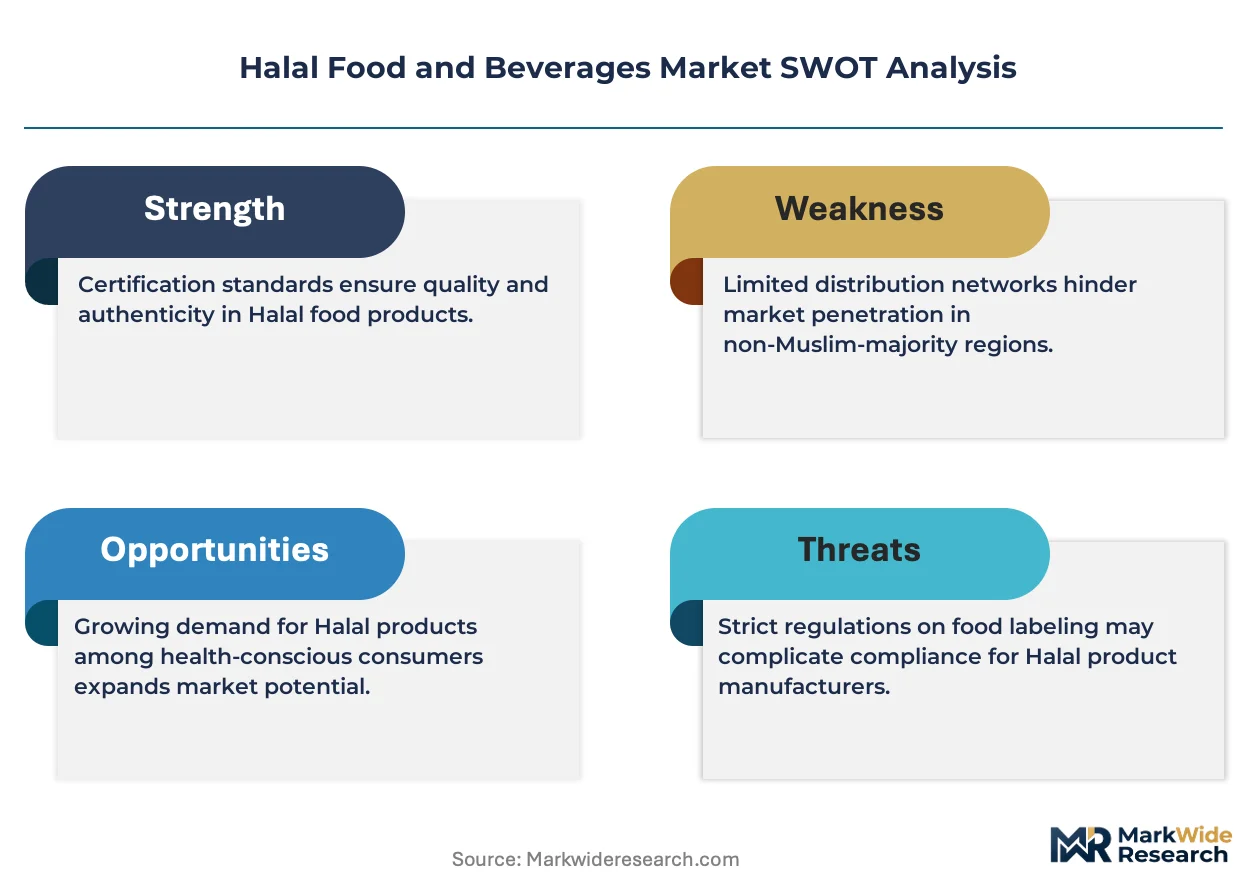
Growth Catalysts
- BPJPH Phase-In Mandates:Indonesia's sector-by-sector certification deadlines create captive demand pull for compliant suppliers in processed foods and beverages.
- Quick-Service Restaurant Expansion:Southeast Asian fast-food chains now require certified halal poultry at volume, locking in long-term procurement contracts with approved slaughterhouses.
- Cold-Chain Infrastructure:Refrigerated logistics networks across Malaysia and Indonesia enable fresh halal meat distribution to previously unreachable urban clusters.
Market Restraints
- Feed Cost Volatility:Global grain price swings directly compress margins for halal poultry integrators operating on thin working capital cycles.
- Slaughterhouse Concentration:Malaysia and Indonesia host the majority of JAKIM-approved facilities, creating geographic chokepoints for exporters from elsewhere.
- Certification Duplication:Divergent rulings on mechanical slaughter permissibility between national halal bodies force redundant facility audits.
Strategic Opportunities
- Halal Functional Beverages:Zero-alcohol wellness drinks and protein-fortified juices capture health-conscious Muslim demographics in Indonesia's tier-two cities.
- Cross-Border E-Commerce:Direct-to-consumer halal subscription platforms bypass traditional retail gatekeepers in Gulf Cooperation Council markets.
- Mutual Recognition Expansion:ASEAN-wide harmonization of JAKIM-MUIS certification standards would slash compliance costs for regional brands.
Industry Challenges
- Halal Auditor Shortage:Qualified personnel capable of verifying supply chain segregation and slaughter compliance remain scarce across Southeast Asia.
- Legacy System Integration:Small and mid-sized processors struggle to embed traceability software required for real-time certification documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Food and Beverages Market |
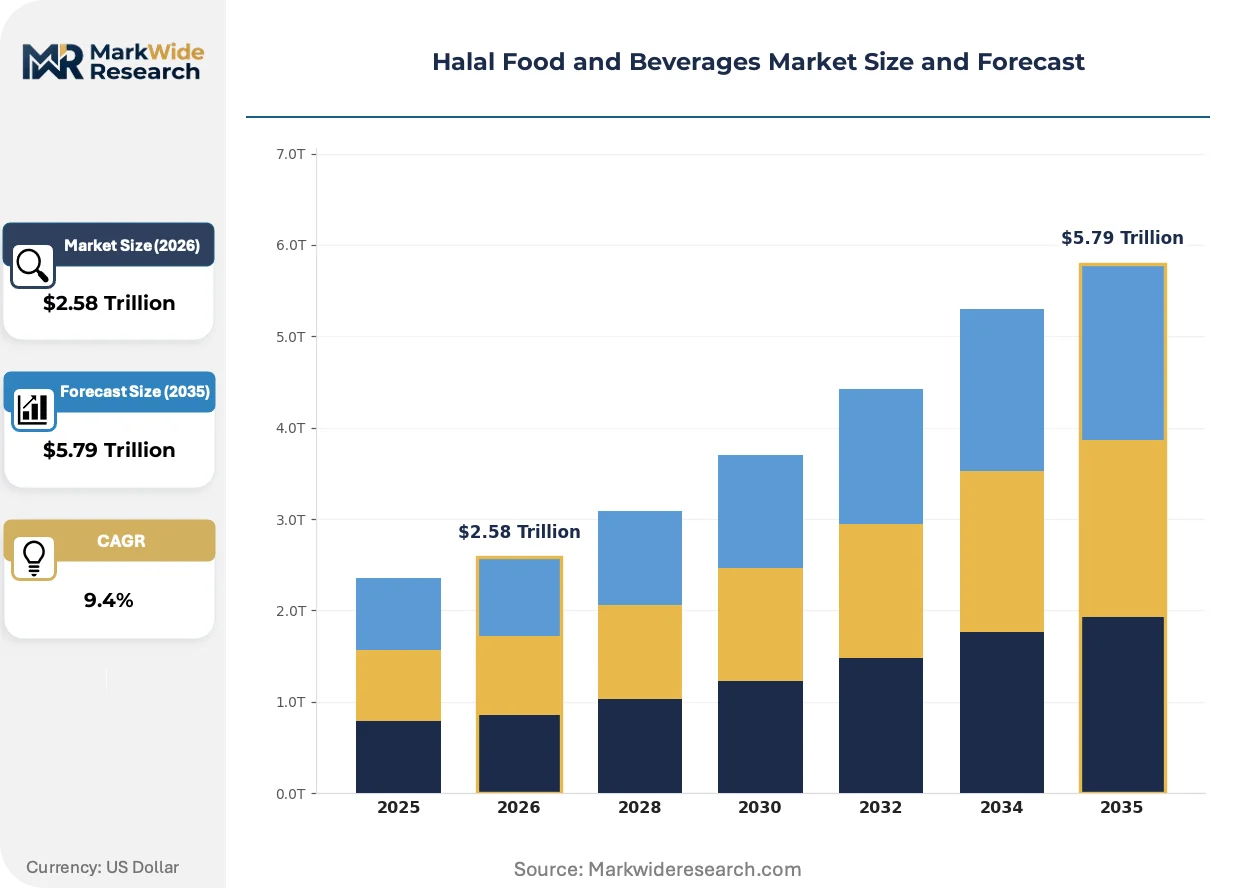
| Market Size in 2026 | $2.58 Trillion |
| Market Size in 2035 | $5.79 Trillion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat & Poultry, Dairy Products, Beverages, Bakery, Confectionery Application: Retail Outlets, Food Service, Catering Services, Institutional Consumption, Hospitality Certification: JAKIM, MUI, MUIS, Indonesian Ulema Council, Halal Authority Board Distribution Channel: Supermarkets, Specialty Stores, Online Platforms, Wholesalers, Convenience Stores |
| Companies Covered | Cargill Inc., Crescent Foods Inc., Nestlé SA, Mondelez International, Al Islami Foods, JBS SA, American Foods Group LLC, Unilever Plc, BRF SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Food and Beverages Market Strategic Shifts & Innovations
Digital traceability tools and alternative protein formulations are restructuring how halal compliance is verified and what ingredients qualify as permissible, shifting competitive advantage toward technology-enabled suppliers.
Blockchain-based supply chain verification is bifurcating the certification landscape. Major retailers in Indonesia and Malaysia now mandate immutable transaction records for halal ingredient sourcing. This technology is compressing audit cycles from months to days while excluding smaller suppliers lacking IT infrastructure.
Indonesia's BPJPH enforcement timeline tightens compliance windows for foreign exporters. The regulation mandates sector-specific deadlines through 2034, with food and beverages facing earlier gates than cosmetics. Indonesian domestic producers are accelerating captive slaughterhouse investments to capture import substitution opportunities.
Young Muslim consumers in Indonesia and Malaysia now prioritize ethical sourcing credentials alongside traditional halal certification. Direct-to-consumer brands leverage social media channels to communicate animal welfare and environmental claims. This preference shift rewards vertically integrated players with controlled supply chain narratives.
Halal Food and Beverages Market Segmentation
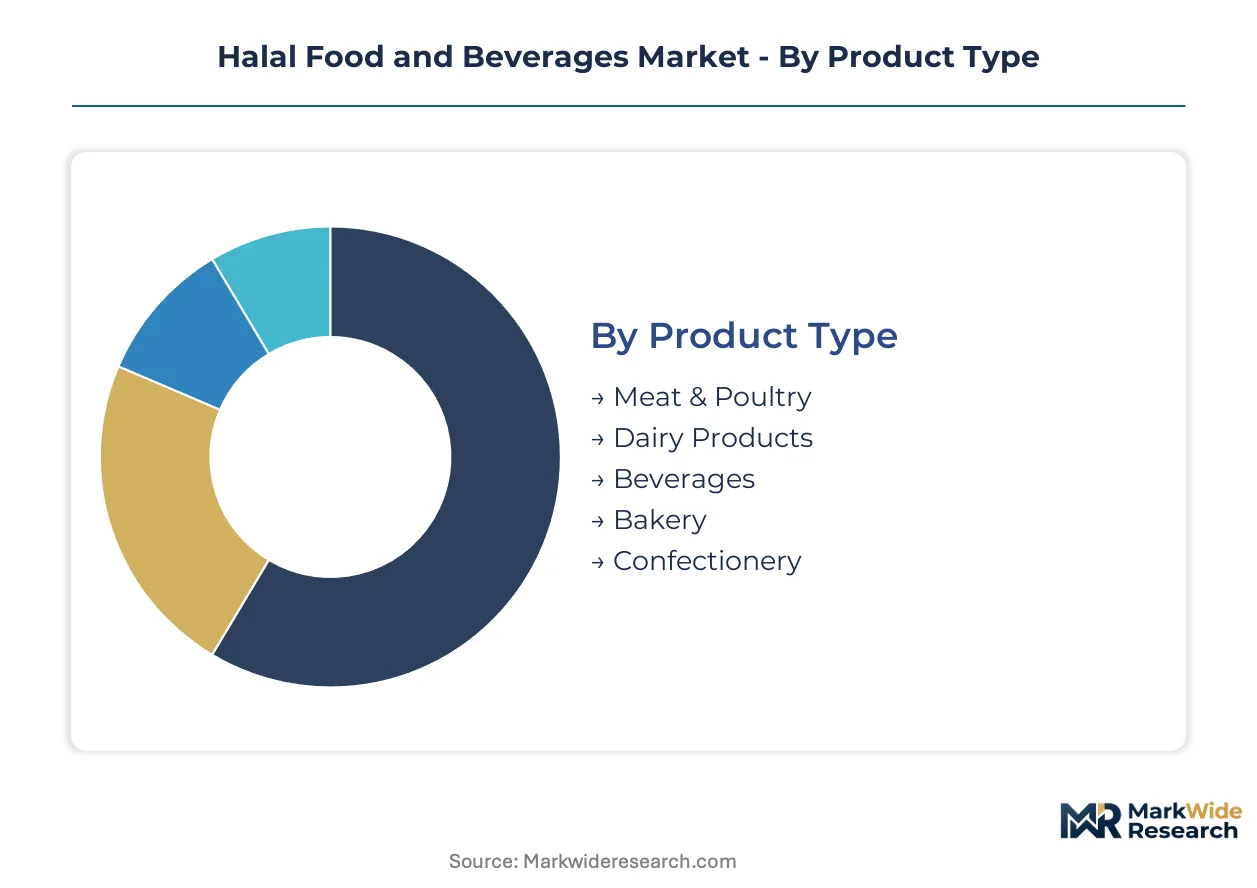
Halal food and beverages segmentation reveals where certification premiums concentrate and which channels capture shifting consumer procurement patterns. Product categories face divergent substitution threats from plant-based alternatives and conventional non-halal offerings depending on price elasticity and religious observance intensity.
Product Type:
Meat and poultry segments confront the most acute substitution pressure from cultivated protein startups and flexitarian dietary shifts among urban Muslim demographics.
- Meat & Poultry:Ritual-slaughtered beef, lamb, and chicken requiring full cold-chain integrity from abattoir to retail shelf. Demand concentrates in Indonesian quick-service restaurant chains sourcing JAKIM-certified poultry at volume for franchise expansion into tier-two cities.
- Beverages:Zero-alcohol functional drinks, juices, and dairy alternatives formulated without ethanol-based flavor carriers or gelatin stabilizers. Indonesian health-conscious millennials in Jakarta and Surabaya drive procurement of protein-fortified halal sports drinks through convenience store channels.
- Dairy Products:Cheese, yogurt, and milk verified free of non-halal rennet and cross-contamination during processing.
- Bakery:Bread, pastries, and cakes using halal-certified emulsifiers and shortening alternatives to lard.
- Confectionery:Candies and chocolates excluding alcohol-based flavorings and non-halal gelatin from porcine sources.
Meat and poultry retains volume leadership; beverages holds the steepest expansion curve.
Application:
Margin structures diverge sharply across application tiers, with institutional contracts squeezing suppliers on price while hospitality commands certification premiums.
- Retail Outlets:Supermarkets and hypermarkets stocking packaged halal goods for household consumption. Malaysian retail chains in Kuala Lumpur and Selangor now mandate blockchain-verified provenance for fresh meat counters.
- Food Service:Quick-service restaurants, casual dining, and café chains requiring certified ingredients at scale. Southeast Asian fast-food operators in Indonesia and Malaysia lock in multi-year poultry supply agreements with JAKIM-approved integrators.
- Catering Services:Wedding, corporate, and event catering with high-batch production requirements.
- Institutional Consumption:School, hospital, and military canteen procurement with cost-sensitive tender processes.
- Hospitality:Hotels and resorts serving Muslim tourists in Gulf Cooperation Council destinations and Southeast Asian resort corridors.
Food service captures the largest revenue pool; online-direct retail channels are climbing fastest.
Certification:
Supply concentration around Southeast Asian approval bodies creates geographic chokepoints for exporters lacking local audit relationships.
- JAKIM:Malaysia's Department of Islamic Development operates the most internationally recognized halal certification with mutual recognition agreements across 47 countries. Nestlé and Unilever anchor regional manufacturing in JAKIM-certified Malaysian facilities to serve ASEAN markets.
- MUI:Indonesian Ulema Council certification with deep penetration across archipelago supply chains. Domestic Indonesian producers accelerate captive slaughterhouse investments to capture import substitution opportunities under BPJPH enforcement timelines.
- MUIS:Singapore's Islamic Religious Council with stringent audit protocols for high-value re-export hubs.
- Indonesian Ulema Council:Archipelago-wide religious authority with overlapping jurisdiction on food products.
- Halal Authority Board:Gulf Cooperation Council-aligned standards with acceptance across Saudi Arabia and UAE import regimes.
JAKIM retains the broadest international acceptance; BPJPH-aligned Indonesian certifications are expanding most quickly.
Distribution Channel:
Customer type stratification separates bulk institutional buyers from premium-seeking direct consumers willing to pay traceability premiums.
- Online Platforms:Direct-to-consumer halal subscription services and cross-border e-commerce bypassing traditional retail gatekeepers. Gulf Cooperation Council consumers in Riyadh and Dubai increasingly procure Malaysian-certified meat through dedicated halal delivery apps.
- Supermarkets:Full-format retail with dedicated halal sections and fresh meat counters. Indonesian hypermarket chains in Jakarta and Bandung expand chilled halal poultry SKUs to meet BPJPH compliance deadlines.
- Specialty Stores:Ethnic grocery and halal butcher shops with high-touch service and custom cutting.
- Wholesalers:Volume distributors serving restaurants, caterers, and institutional kitchens with case-lot pricing.
- Convenience Stores:Grab-and-go packaged halal snacks and beverages in urban transit corridors.
Supermarkets dominate transaction volume; online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency in halal meat concentrates in Gulf Cooperation Council markets while Southeast Asian nations build export capacity through certification infrastructure. Malaysia and Indonesia now supply certified poultry to Middle Eastern buyers seeking JAKIM-approved slaughter standards.
Indonesia
Domestic consumption of processed halal foods accelerates under BPJPH enforcement timelines mandating sector-by-sector compliance. The national halal product law obligates certification for all consumer goods by phase-in deadlines through 2034. Jakarta and Surabaya processors expand captive slaughterhouse investments to displace Australian and Brazilian beef imports.
Malaysia
JAKIM-certified poultry exports to Gulf markets rise as Saudi Arabia and UAE recognize Malaysian slaughter protocols. The Department of Islamic Development maintains mutual recognition agreements spanning 47 countries. Port Klang cold-chain facilities now serve as re-export hubs for Indonesian and Thai producers seeking international halal certification.
Saudi Arabia
Domestic poultry integrators face feed cost pressures while government programs promote food security through localized halal production. SFDA import regulations favor suppliers with approved slaughterhouse equivalency. Riyadh-based distributors lock in long-term supply contracts with Brazilian and Australian exporters holding Halal Authority Board accreditation.
United Arab Emirates
Dubai's logistics infrastructure anchors Gulf re-export trade for halal commodities entering Saudi and Kuwaiti markets. MOHAP halal standards align with GCC harmonization frameworks reducing duplicate certification. Jebel Ali free zone cold storage capacity expands to accommodate Indonesian and Malaysian meat shipments during Ramadan demand spikes.
United States
Domestic halal meat production concentrates in Midwest processing facilities serving Muslim population centers in Michigan and Illinois. USDA slaughter inspection protocols accommodate religious exemption requests for hand-cut ritual methods. Chicago-based distributors supply quick-service restaurant chains seeking certified poultry for Southeast Asian franchise expansion.
Halal Food and Beverages Market Key Industry Players
Listed multinationals compete with private specialists across certification infrastructure and geographic coverage. Nestlé SA and Unilever Plc leverage manufacturing scale across JAKIM-certified Southeast Asian facilities, while Al Islami Foods and Crescent Foods Inc. concentrate on Gulf market penetration through dedicated halal production lines. Three archetypes dominate: diversified conglomerates with in-house compliance infrastructure, regional meat specialists with captive slaughter capacity, and private-label processors serving foodservice procurement. Competitive moves center on backward integration into approved slaughter facilities and mutual recognition lobbying to reduce audit duplication costs.
Among diversified conglomerates, Nestlé SA and Unilever Plc exemplify the certification-anchored archetype through dedicated halal production lines in Malaysia and Indonesia. Al Islami Foods represents the regional specialist model with concentrated Gulf market presence. These three occupy positions spanning packaged goods, beverages, and chilled meat categories without overlapping geographic strongholds.
| Leading Market Players |
|---|
| Cargill Inc. |
| Crescent Foods Inc. |
| Nestlé SA |
| Mondelez International |
| Al Islami Foods |
| JBS SA |
| American Foods Group LLC |
| Unilever Plc |
| BRF SA |
| Others |
Cost & Logistics Intelligence
Plant-based protein formulations displacing conventional halal meat in Indonesian quick-service restaurant trials simultaneously redraw procurement geography toward domestic slaughterhouse investments and compress margin structures for legacy poultry integrators dependent on imported feed grains.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Southeast Asian foodservice procurement. Three-tier pricing structure across premium JAKIM-certified, standard MUI-compliant, and economy non-certified tiers separates multinational chains from regional players from cost-sensitive institutional canteens. Cost compression in economy tiers is intensifying because Brazilian and Australian beef exporters face escalating BPJPH compliance costs. Quick-service restaurant chains demonstrate least price sensitivity due to franchise fee structures, while school and hospital canteen tenders exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate Ramadan demand cycles, with Jebel Ali and Port Klang cold-storage facilities accumulating Indonesian and Malaysian poultry shipments ahead of seasonal spikes. Geographic supply concentration centers on Malaysia, Indonesia, and Brazil as the tripod of JAKIM-approved slaughter capacity. Raw material dependencies rest on soybean meal imports from Argentina, corn from Ukraine, and halal-compliant feed additives from specialized European suppliers. Single-source vulnerability concentrates in JAKIM auditor availability, where qualified personnel scarcity creates certification bottlenecks. Distribution runs through supermarket halal counters, quick-service restaurant direct procurement, and emerging subscription-platform channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's BPJPH enforcement timeline constitutes a regulatory inflection accelerating market consolidation, as mandatory certification deadlines force foreign suppliers to either build domestic slaughter capacity or surrender shelf space to compliant local processors.
For Market Incumbents: Secure captive slaughterhouse investments in Indonesian tier-two cities before BPJPH food and beverage deadlines eliminate import eligibility for non-compliant suppliers. Deepen backward integration into feed grain sourcing to buffer against Argentine and Ukrainian price volatility threatening poultry margin structures.
For New Entrants and Emerging Players: Halal functional beverage white-space in Indonesian convenience stores offers penetrable terrain where Nestlé and Unilever lack specialized zero-alcohol wellness positioning. Target Jakarta and Surabaya millennials through direct-to-consumer subscription models bypassing traditional retail slotting fees.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Malaysian poultry integrators holding JAKIM certification infrastructure but lacking BPJPH compliance pathways. Long-term viability hinges on Indonesian regulatory arbitrage resolution. Watch BPJPH auditor training program expansion as inflection indicator for certification bottleneck easing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slaughter Capacity | Captive JAKIM-approved facilities in Malaysia and Indonesia lock in Southeast Asian quick-service restaurant procurement. |
| Halal Functional Beverage Launch | Zero-alcohol protein-fortified drinks capture health-conscious Jakarta millennials ahead of incumbent repositioning. |
| Blockchain Traceability Implementation | Immutable supply chain records satisfy Indonesian retailer mandates while excluding smaller competitors lacking IT infrastructure. |
| Cross-Border E-Commerce Platform Expansion | Direct-to-consumer halal subscription models bypass traditional Gulf Cooperation Council retail gatekeepers. |
| Mutual Recognition Lobbying | ASEAN-wide JAKIM-MUIS standard harmonization slashes audit duplication costs for regional brand portfolios. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with halal certification auditors, quick-service restaurant procurement directors, cold-chain logistics operators, and BPJPH regulatory affairs specialists. Secondary validation drew from JAKIM certification registries, Indonesian trade ministry import statistics, ASEAN customs databases, and foodservice industry procurement disclosures. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, certification body, and distribution channel dimensions.
Across the analysis window, projections integrated segmented demand modeling by meat and poultry, beverages, dairy, bakery, and confectionery categories against institutional, retail, foodservice, and hospitality application tiers. CAGRs derived from historical trajectory analysis adjusted for regulatory phase-in impacts and substitution elasticity parameters. Forecast inputs incorporated BPJPH enforcement timeline adherence rates, JAKIM mutual recognition expansion scenarios, and cold-chain infrastructure investment flows.
Material uncertainties — feed grain price volatility, auditor availability constraints, and mechanical slaughter permissibility rulings — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation consistency and certification body cooperation. Revision becomes warranted when BPJPH deadline extensions or JAKIM standard divergence cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Foodservice Market
Food Service
Breakfast Takeout Market
Food Service
Europe Airline Catering Services Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Plates Market
Food Service
Switzerland Food Service Market
Food Service
Clear Ice Maker Market
Food Service
Healthy Takeout Market
Food Service
Gas Fryers Market
Food Service
Hospital Food Services Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Global Sushi Restaurants Market
Food Service
Ship Catering Service Market
Food Service
Full-Service Restaurants Market
Food Service
United States Quick Service Restaurants Market
Food Service
Europe Food Service Market