
 Canada Plant-Based Food and Beverages Market | 2026-2036
Canada Plant-Based Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Plant-Based Food and Beverages Market Outlook
Foodservice procurement is shifting as Canadian restaurant groups and institutional cafeterias diversify protein sourcing beyond conventional meat and dairy. Maple Leaf Foods Inc. leverages its domestic meat-processing infrastructure to build parallel plant-based production capacity. Beyond Meat, Inc. competes through burger-format products designed for Canadian quick-service menus. Earth's Own Food Company Inc. anchors oat-milk supply across western Canadian retail channels.
Plant-based food and beverages comprise formulated products derived from legumes, cereals, nuts, or oilseeds through mechanical extraction, fermentation, or enzymatic processing, designed to replicate the sensory and nutritional properties of animal-derived foods. Dairy Alternatives occupy the largest revenue pool, led by oat and soy milk formats with extended shelf stability through ultra-high temperature treatment. Beverages represent the fastest-growing product type, propelled by functional formulations incorporating protein fortification and probiotic cultures. The Frozen form commands premium positioning in retail, while Ready-to-Eat formats expand through convenience-oriented distribution.
Health Canada governs nutrition labeling and novel food approvals under the Food and Drugs Act, directly influencing product composition claims and market entry timelines. The Canadian Food Inspection Agency enforces plant-based protein labeling standards that distinguish fermented from extracted protein sources. The Competition Bureau monitors environmental marketing claims to prevent greenwashing in plant-based branding. Stakeholders must track evolving standards for protein quality scoring and carbon labeling as these frameworks reshape competitive positioning and consumer trust.
Market Dynamics
Health Canada's protein-quality scoring framework and provincial carbon-labeling pilots are compressing formulation timelines while forcing simultaneous compliance with multiple standards. Manufacturers must now validate nutritional equivalence and environmental claims through parallel certification tracks.
Growth Catalysts
- Health Canada Food Guide:The 2019 revision elevates plant proteins to primary dietary recommendations, redirecting institutional procurement across Canadian school boards and hospital networks toward legume-based alternatives.
- Pulse crop abundance:Saskatchewan and Manitoba's lentil and pea processing infrastructure provides domestic protein isolate supply, reducing import dependency for extruded meat analogues.
- Enzymatic oat processing:Proprietary lipase treatments now yield creamy mouthfeel without added oils, accelerating oat-milk adoption in Vancouver and Toronto coffeehouse chains.
Market Restraints
- Canola oil price volatility:Input cost swings for the primary fat source in Canadian plant-based meat formulations compress margin stability for domestic processors.
- Novel food approval timelines:Health Canada's 12-18 month safety assessment window for fermented proteins delays product launches versus US and EU regulatory pathways.
- Conventional dairy lobbying:Provincial marketing boards in Quebec and Ontario restrict plant-based labeling terminology, creating compliance fragmentation across provincial borders.
Strategic Opportunities
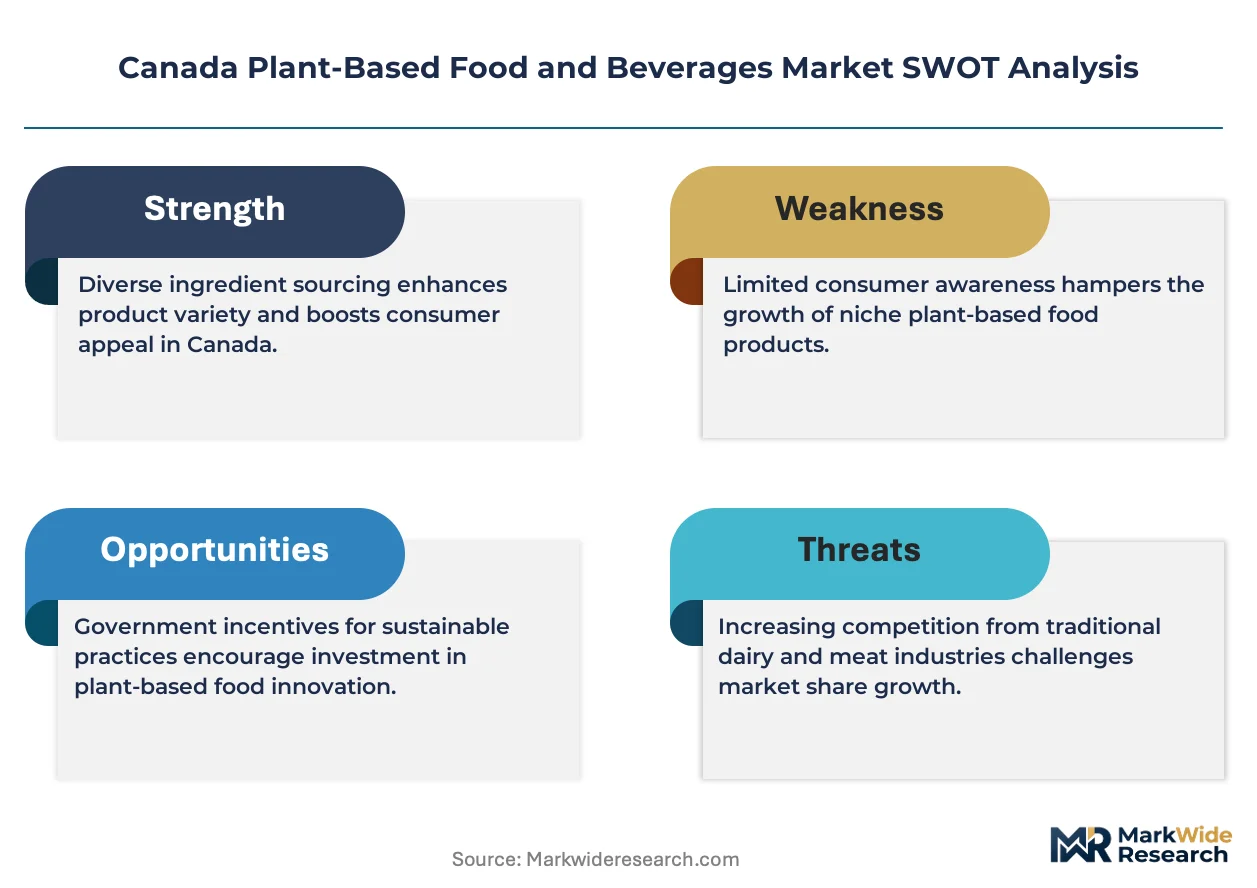
- Atlantic Canada underpenetration:Halifax and St. John's retail channels carry 40% fewer SKUs than Vancouver equivalents, presenting first-mover shelf space for regional distributors.
- Fermentation-derived ingredients:Precision biomass from Winnipeg-based facilities qualifies for accelerated novel food pathways, enabling mycoprotein expansion into Canadian frozen entrées.
- Direct-to-foodservice channels:Bypassing retail slotting fees through institutional contracts with Aramark and Compass Group Canada unlocks volume commitments for emerging processors.
Industry Challenges
- Protein functionality expertise:Shortage of food scientists trained in high-moisture extrusion and shear-cell technology limits domestic R&D capacity for texturized vegetable protein development.
- Cross-contamination certification:Dual kosher-halal verification for shared production lines with conventional meat equipment extends facility commissioning by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Plant-Based Food and Beverages Market |
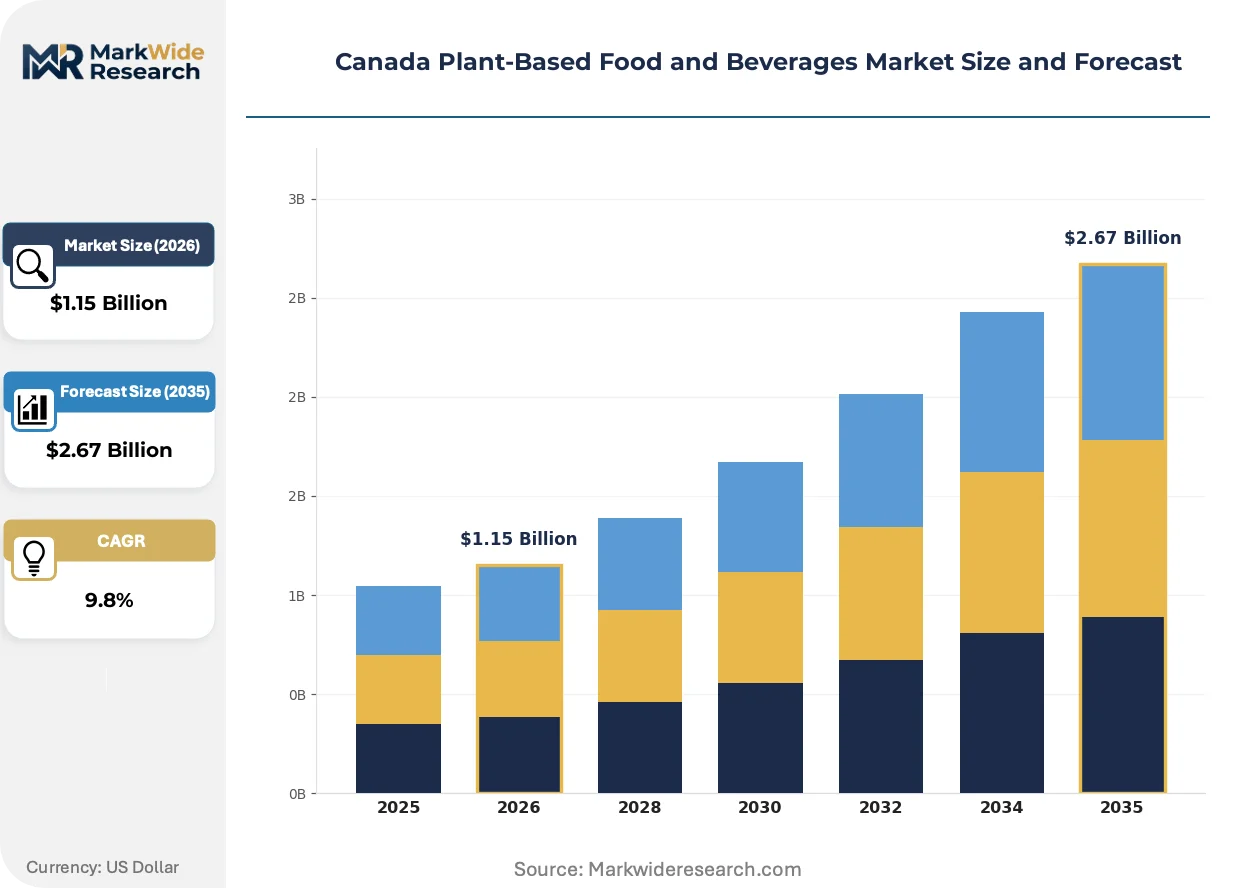
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.67 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Proteins, Dairy Alternatives, Snacks, Beverages End User: Retail Consumers, Restaurants, Foodservice Chains, Health Food Stores Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Distributors Form: Frozen, Ready-to-Eat, Powdered, Liquid |
| Companies Covered | SunOpta Inc., Maple Leaf Foods Inc., Danone S.A., The Hain Celestial Group Inc., Daiya Foods Inc., Beyond Meat, Inc., Earth's Own Food Company Inc., Vitasoy International Holdings Ltd., Nestlé S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Plant-Based Food and Beverages Market Strategic Shifts
Fermentation and enzymatic processing are displacing conventional mechanical extraction as the dominant production paradigm, while provincial regulators experiment with front-of-package labeling mandates that privilege environmental claims.
Precision fermentation for dairy-identical proteins is converging with Canadian canola and sunflower oil emulsion systems to replicate functional properties of butter and cream in bakery applications. Quebec-based ingredient suppliers are piloting these hybrid formulations with industrial bakeries in Montreal and Toronto. The technology is converging with existing dairy processing infrastructure, enabling retrofit rather than greenfield capital deployment.
Health Canada's proposed front-of-package nutrition symbol regulations will mandate warning labels on products exceeding saturated fat thresholds, directly affecting coconut-oil-based cheese alternatives. British Columbia's voluntary carbon-labeling pilot for retail products is creating competitive pressure for lifecycle assessment disclosure. Plant-based meat substitutes with higher saturated fat profiles face reformulation pressure, while oat-milk producers leverage favorable nutritional scores for shelf positioning.
Foodservice operators are consolidating procurement through broadline distributors rather than direct manufacturer relationships, compressing supplier margins while demanding exclusive formulation rights. Sysco Canada and Gordon Food Service now specify protein content minimums and clean-label ingredient restrictions in national contracts. This consolidation is most visible in Ontario's quick-service restaurant chains, where standardized menus across hundreds of locations favor single-source supply agreements over fragmented regional purchasing.
Canada Plant-Based Food and Beverages Market Segmentation
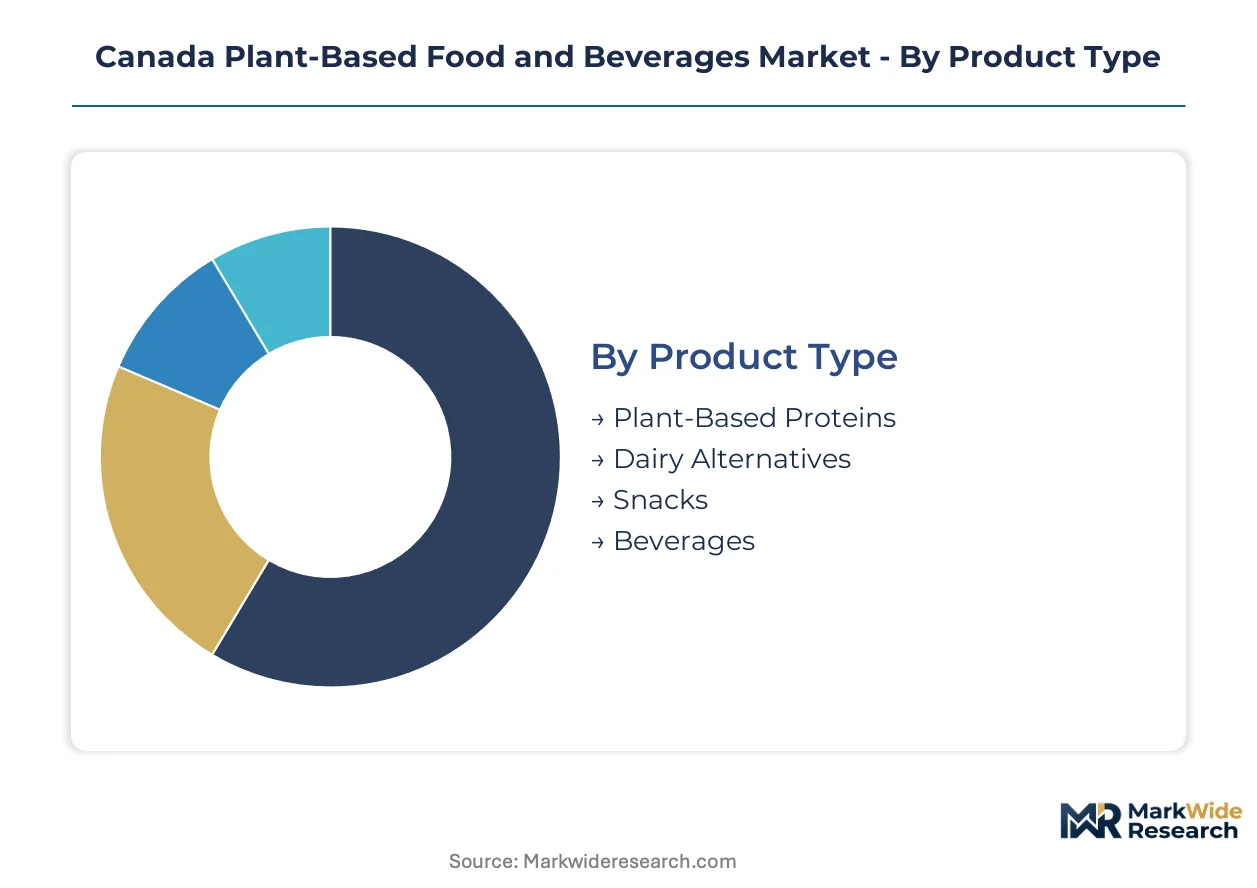
Health Canada's novel food approval pathways create asymmetric barriers across product categories, with fermented proteins facing 12-18 month safety assessments while mechanically extracted alternatives clear faster. Provincial carbon-labeling pilots and front-of-package nutrition symbols further stratify which segments can sustain premium positioning versus reformulation pressure.
Product Type:
Dairy Alternatives and fermented protein products carry the heaviest certification burden under Health Canada's Food and Drugs Act, requiring novel food submissions for biomass-derived ingredients that mechanically extracted isolates bypass.
- Dairy Alternatives:Oat and soy milk formats dominate shelf-stable retail through ultra-high temperature treatment, with enzymatic lipase processing now yielding creamy mouthfeel without added oils. Vancouver and Toronto coffeehouse chains are accelerating adoption, though coconut-oil-based cheese alternatives face reformulation pressure from proposed front-of-package saturated fat warnings.
- Beverages:Functional formulations incorporating protein fortification and probiotic cultures are climbing the fastest, propelled by Health Canada's protein-quality scoring framework that privileges complete amino acid profiles. British Columbia's voluntary carbon-labeling pilot creates competitive pressure for lifecycle assessment disclosure in this high-visibility segment.
- Plant-Based Proteins:Extruded meat analogues rely on Saskatchewan and Manitoba lentil and pea processing infrastructure for domestic isolate supply.
- Snacks:Shelf-stable formats leverage extended distribution reach across Atlantic Canada's underpenetrated retail channels.
Leading the category by volume: Dairy Alternatives. Expanding most quickly: Beverages.
End User:
Cost tier stratification separates institutional procurement—driven by Health Canada Food Guide compliance— from premium retail channels where environmental claims command price premiums.
- Foodservice Chains:Aramark and Compass Group Canada consolidate procurement through national contracts specifying protein content minimums and clean-label restrictions, bypassing retail slotting fees for emerging processors. Sysco Canada and Gordon Food Service now demand exclusive formulation rights, compressing supplier margins while locking in volume commitments across Ontario quick-service networks.
- Restaurants:Independent operators in Montreal and Toronto pilot precision fermentation-derived dairy alternatives with Quebec-based ingredient suppliers, retrofitting existing dairy processing infrastructure rather than deploying greenfield capital.
- Retail Consumers:Concentrated in Vancouver and Toronto metropolitan corridors where oat-based purchases are expanding fastest.
- Health Food Stores:Specialty positioning targets consumers seeking probiotic-fortified functional beverages with verified carbon footprints.
Highest absolute spend: Foodservice Chains. Steepest growth trajectory: Restaurants integrating fermented ingredients.
Distribution Channel:
Geographic concentration determines channel viability, with Halifax and St. John's carrying 40% fewer SKUs than Vancouver equivalents, creating first-mover advantages for regional distributors.
- Supermarkets:Ontario and British Columbia retail channels anchor national rollout, with shelf positioning increasingly determined by Health Canada's proposed front-of-package nutrition scores. Oat-milk producers leverage favorable nutritional ratings to secure premium placement against coconut-oil-based competitors.
- Food Distributors:Broadline consolidation through Sysco Canada and Gordon Food Service compresses fragmented regional purchasing into standardized national contracts, favoring single-source supply agreements over diversified supplier bases.
- Online Retail:Direct-to-consumer penetration remains limited by refrigerated logistics constraints for frozen and liquid formats.
- Specialty Stores:Concentrated in urban centers with higher willingness-to-pay for carbon-labeled and kosher-halal certified products.
Dominant by throughput: Supermarkets. Gaining share fastest: Food Distributors capturing institutional volume.
Form:
Margin structure inverts across form types, with frozen formats commanding premium retail positioning while ready-to-eat expands through convenience-oriented distribution at compressed unit economics.
- Frozen:Premium positioning in retail reflects extended shelf stability and higher perceived quality, with mycoprotein expansion from Winnipeg-based precision fermentation facilities targeting Canadian frozen entrées through accelerated novel food pathways.
- Ready-to-Eat:Convenience-oriented distribution expands through foodservice channels and grab-and-go retail, though shorter shelf life limits geographic reach compared to frozen alternatives.
- Liquid:Oat-milk formulations lead volume, with enzymatic processing enabling clean-label positioning.
- Powdered:Protein fortification applications concentrate in health food and specialty supplement channels.
Highest revenue per unit: Frozen. Broadest volume base: Liquid formats in retail and foodservice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian plant-based food and beverage demand concentrates in Ontario and British Columbia metropolitan corridors, with Vancouver and Toronto coffeehouse chains accelerating oat-milk adoption through enzymatic processing innovations.
Ontario
Toronto anchors national foodservice procurement through consolidated contracts with Aramark and Compass Group Canada. Health Canada's Food Guide revision redirects institutional purchasing across Ontario school boards and hospital networks toward legume-based alternatives. Sysco Canada and Gordon Food Service now specify protein content minimums in standardized quick-service menus across hundreds of locations.
British Columbia
Vancouver coffeehouse chains drive oat-milk volume through proprietary lipase treatments yielding creamy mouthfeel without added oils. The province's voluntary carbon-labeling pilot creates competitive pressure for lifecycle assessment disclosure in retail channels. Precision fermentation facilities in the Lower Mainland pilot dairy-identical proteins for bakery applications with Montreal and Toronto industrial bakeries.
Quebec
Montreal independent restaurants pilot precision fermentation-derived dairy alternatives with Quebec-based ingredient suppliers. Provincial marketing boards restrict plant-based labeling terminology, creating compliance fragmentation versus Ontario standards. Existing dairy processing infrastructure enables retrofit production rather than greenfield capital deployment for hybrid formulations.
Prairie Provinces
Saskatchewan and Manitoba lentil and pea processing infrastructure supplies domestic protein isolate for extruded meat analogues. Winnipeg-based precision fermentation facilities target accelerated novel food pathways for mycoprotein expansion into frozen entrées. Pulse crop abundance reduces import dependency for domestic meat analogue processors.
Atlantic Canada
Halifax and St. John's retail channels carry fewer SKUs than Vancouver equivalents, presenting first-mover shelf space opportunities for regional distributors. Health Canada compliance requirements compress formulation timelines for emerging processors entering underpenetrated markets. Atlantic institutional procurement lags Ontario and British Columbia in Food Guide-aligned protein diversification.
Canada Plant-Based Food and Beverages Market Competitive Environment
Canadian domestic producers anchor one tier; European and US multinational specialists hold premium positioning through established brand equity. The market exhibits tiered concentration with three to five domestic processors controlling mid-market volume while global players capture premium retail shelf space. Strategic archetypes include meat-processing incumbents diversifying into parallel plant-based capacity, oat-milk specialists leveraging western Canadian retail channels, and precision fermentation entrants targeting foodservice bypass. Dominant competitive moves encompass facility retrofit versus greenfield capital deployment and direct-to-institutional contracting to avoid retail slotting fees.
Within the domestic incumbent tier, Maple Leaf Foods Inc. exemplifies meat-processing infrastructure redeployment for plant-based parallel capacity. Among oat-milk specialists, Earth's Own Food Company Inc. anchors western Canadian retail distribution. On the multinational entrant vector, Beyond Meat, Inc. occupies a position calibrated for quick-service menu integration.
| Leading Market Players |
|---|
| SunOpta Inc. |
| Maple Leaf Foods Inc. |
| Danone S.A. |
| The Hain Celestial Group Inc. |
| Daiya Foods Inc. |
| Beyond Meat, Inc. |
| Earth's Own Food Company Inc. |
| Vitasoy International Holdings Ltd. |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement through Sysco Canada and Gordon Food Service is forcing domestic processors toward volume commitments at compressed margins, driving backward integration into Saskatchewan and Manitoba pulse processing to reclaim pricing power.
Pricing Analysis
Volume commitments through institutional contracts compress margins while frozen formats sustain premium retail positioning. Pricing stratifies across carbon-labeled premium tiers, Health Canada nutrition-score tiers, and conventional economy tiers. Cost compression in foodservice channels intensifies as broadline distributors specify protein minimums and clean-label restrictions. Retail consumers in Vancouver and Toronto corridors show lowest price sensitivity, while Atlantic Canada institutional buyers exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics infrastructure for refrigerated oat-milk returns remains underdeveloped, constraining direct-to-consumer channel viability. Domestic supply draws from Saskatchewan lentil processing, Manitoba pea isolate facilities, and Quebec precision fermentation infrastructure. Input dependencies center on canola oil, enzymatic processing agents, and novel food approval timelines. Single-source vulnerability concentrates in Health Canada's 12-18 month safety assessment window for fermented proteins. Distribution runs through Ontario and British Columbia retail anchors with Atlantic Canada penetration gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation is accelerating as novel food approval timelines and broadline distributor procurement consolidation force sub-scale processors toward exit or acquisition.
For Market Incumbents: To counter margin compression from Sysco Canada and Gordon Food Service national contracts, secure backward integration into Prairie Provinces pulse processing infrastructure and invest in dual kosher-halal certification to accelerate facility commissioning timelines. For New Entrants and Emerging Players: Launch via direct-to-foodservice channels bypassing retail slotting fees, targeting Atlantic Canada underpenetrated markets where Halifax and St. John's carry 40% fewer SKUs than Vancouver equivalents, and leverage Winnipeg-based precision fermentation for accelerated novel food pathways. For Investors and Strategic Acquirers: The window for entry favors mid-cap domestic processors with Health Canada novel food approvals in progress and Prairie Provinces sourcing relationships. Watch for inflection signals in Health Canada protein-quality scoring framework implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Processing | Captures Saskatchewan and Manitoba lentil and pea isolate supply for domestic meat analogue production. |
| Dual Kosher-Halal Certification Investment | Reduces facility commissioning delays by 4-6 months for shared production lines. |
| Direct-to-Foodservice Channel Development | Bypasses retail slotting fees through Aramark and Compass Group Canada institutional contracts. |
| Precision Fermentation Capacity Buildout | Enables Winnipeg-based mycoprotein expansion into frozen entrées via accelerated approval pathways. |
| Carbon-Labeling Compliance Program | Secures competitive positioning under British Columbia's voluntary retail pilot and anticipated federal expansion. |
Study Parameters
Health Canada regulatory filings, Canadian Food Inspection Agency enforcement records, and provincial carbon-labeling pilot documentation formed the secondary backbone. Primary interviews with foodservice procurement directors, plant-based R&D scientists, retail category buyers, and precision fermentation facility operators combined with bottom-up and top-down triangulation.
Bottom-up modeling anchored volume projections across product type, end user, distribution channel, and form dimensions, while top-down validation cross-checked against provincial agricultural output data. CAGRs were derived from segment-level growth trajectory analysis incorporating Health Canada Food Guide implementation pace and enzymatic processing adoption curves.
Novel food approval delays, canola oil price volatility, and provincial labeling terminology fragmentation are the dominant revision risks. Practitioners should monitor Health Canada front-of-package regulation finalization and Saskatchewan pulse crop yields for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
North America Tofu Market
Plant Based Food
Europe Tofu Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Chicory Roots Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Soy Protein Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Global Tofu Market
Plant Based Food
Middle East and Africa Meat Substitute Market