
 Restaurants and Mobile Food Services Market | 2026-2036
Restaurants and Mobile Food Services Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurants and Mobile Food Services Market Analytics
The gap between full-service kitchens and mobile food units is narrowing as operators adopt modular equipment and shared commissary models. McDonald's leverages its real estate footprint to sustain drive-thru dominance across North American suburban corridors. Chipotle anchors its growth in digital-native formats with smaller physical footprints. Yum China Holdings Inc. competes through localized menu engineering and dense urban store networks.
Restaurants and Mobile Food Services encompass fixed-location establishments and motorized or trailer-based food vendors that prepare meals for immediate consumption, requiring compliance with commercial-grade ventilation, refrigeration, and wastewater containment standards. The primary commercial purpose centers on delivering prepared food through varying service speeds and price points matched to occasion-based consumer needs. Fast Food and Street Food categories dominate transaction volume, while Fine Dining retains outsized margin pools per cover. Online Ordering and Contactless Payment technologies are expanding fastest among service type and technology segments, though POS Systems still occupy the largest installed base across mature markets.
FDA food code updates, EU hygiene package directives, and local health department permitting frameworks shape equipment specifications, staff training mandates, and market entry barriers for new operators. These regulatory layers intensify compliance costs for mobile units while creating structural advantages for chains with dedicated legal and safety infrastructure. Stakeholders must monitor how municipal zoning liberalization for food trucks interacts with rising labor standards to determine optimal format mix and geographic sequencing.
Market Dynamics
Delivery-first consumption patterns are compressing the traditional dine-in model as urban density rises and kitchen real estate costs escalate, forcing operators to reconfigure format economics around speed and footprint efficiency.
Growth Catalysts
- EU Hygiene Package Directives:Standardized food safety protocols across member states reduce cross-border compliance friction for mobile operators expanding into adjacent markets.
- Cloud Kitchen Infrastructure:Shared commissary models in Mumbai, Bangkok, and Jakarta slash capital requirements for market entry while enabling rapid menu testing.
- Contactless Payment Rails:QR-code and NFC transaction penetration accelerates throughput at high-volume street food clusters where cash handling previously throttled capacity.
Market Restraints
- Commercial Refrigerant Input Volatility:F-Gas Regulation phase-down schedules in Europe constrain cold-chain equipment availability and inflate replacement costs for mobile units.
- Municipal Zoning Fragmentation:Inconsistent street vending permits across Indian state capitals create operational discontinuity and legal exposure for national fleet operators.
- Labor Standard Escalation:Rising minimum wage mandates and tip-credit restrictions in US metropolitan areas compress unit-level margins for full-service formats.
Strategic Opportunities
- Secondary Southeast Asian Cities:Surabaya, Cebu, and Da Nang exhibit mobile food penetration gaps relative to capital-city saturation with underdeveloped dine-in alternatives.
- Ghost Kitchen Convergence:Integration of autonomous delivery robotics with centralized production hubs creates last-mile density without customer-facing real estate.
- FSSAI Streamlined Licensing:India's single-window clearance portal for food business operators reduces permit timelines from months to weeks in tier-2 urban centers.
Industry Challenges
- Certified Food Handler Scarcity:ServSafe and equivalent credential pipelines fail to match operator expansion velocity in high-growth Indian and Southeast Asian markets.
- Legacy POS Migration Friction:Tablet-based cloud systems encounter integration failures with established inventory and accounting software at mid-scale chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurants and Mobile Food Services Market |
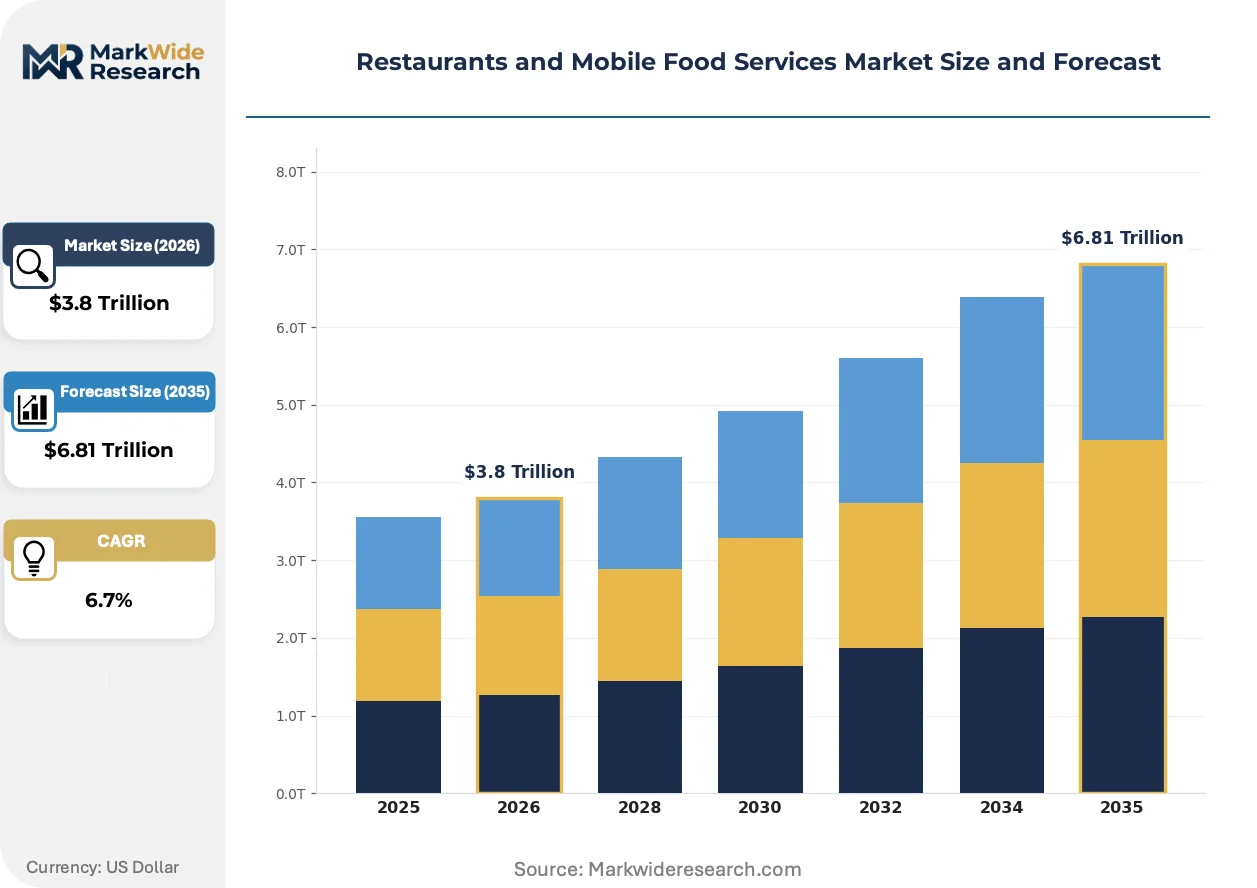
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $6.81 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-in, Takeout, Delivery, Catering Food Category: Fast Food, Casual Dining, Fine Dining, Street Food Customer Type: Families, Young Adults, Professionals, Tourists Technology: Online Ordering, POS Systems, Mobile Apps, Contactless Payment |
| Companies Covered | Restaurant Brands International Inc., Zensho Holdings Co Ltd, McDonald's, Chick-fil-A, Subway, Yum China Holdings Inc., Chipotle, Bloomin' Brands, Darden Restaurants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurants and Mobile Food Services Market Evolving Landscape
Modular kitchen equipment and autonomous logistics infrastructure are dissolving the fixed-versus-mobile boundary, enabling format fluidity that responds to demand signals rather than real estate constraints.
Compact ventless cooking systems utilizing catalytic oxidation and recirculating filtration are collapsing the ventilation infrastructure barrier that previously confined high-heat cooking to permanent installations. Cloud kitchen operators in Singapore and Dubai deploy these units in parking structures and warehouse shells without hood construction. The technology compresses site selection timelines from quarters to weeks.
FDA Food Code 2022 updates mandate enhanced allergen controls and time-temperature logging across US jurisdictions. Commercial kitchen equipment vendors now embed Bluetooth temperature probes and automated HACCP documentation as standard features. Full-service chains absorb compliance costs through centralized training infrastructure while independent operators face steeper capability gaps.
Subscription-based meal programs and employer-subsidized corporate dining contracts are displacing individual transaction models in dense Indian and Southeast Asian business districts. Aggregator platforms bundle predictable volume commitments with kitchen operators, shifting revenue recognition from per-cover to recurring structures. Bengaluru and Ho Chi Minh City exhibit the fastest contract penetration among white-collar employment clusters.
Restaurants and Mobile Food Services Market Segmentation
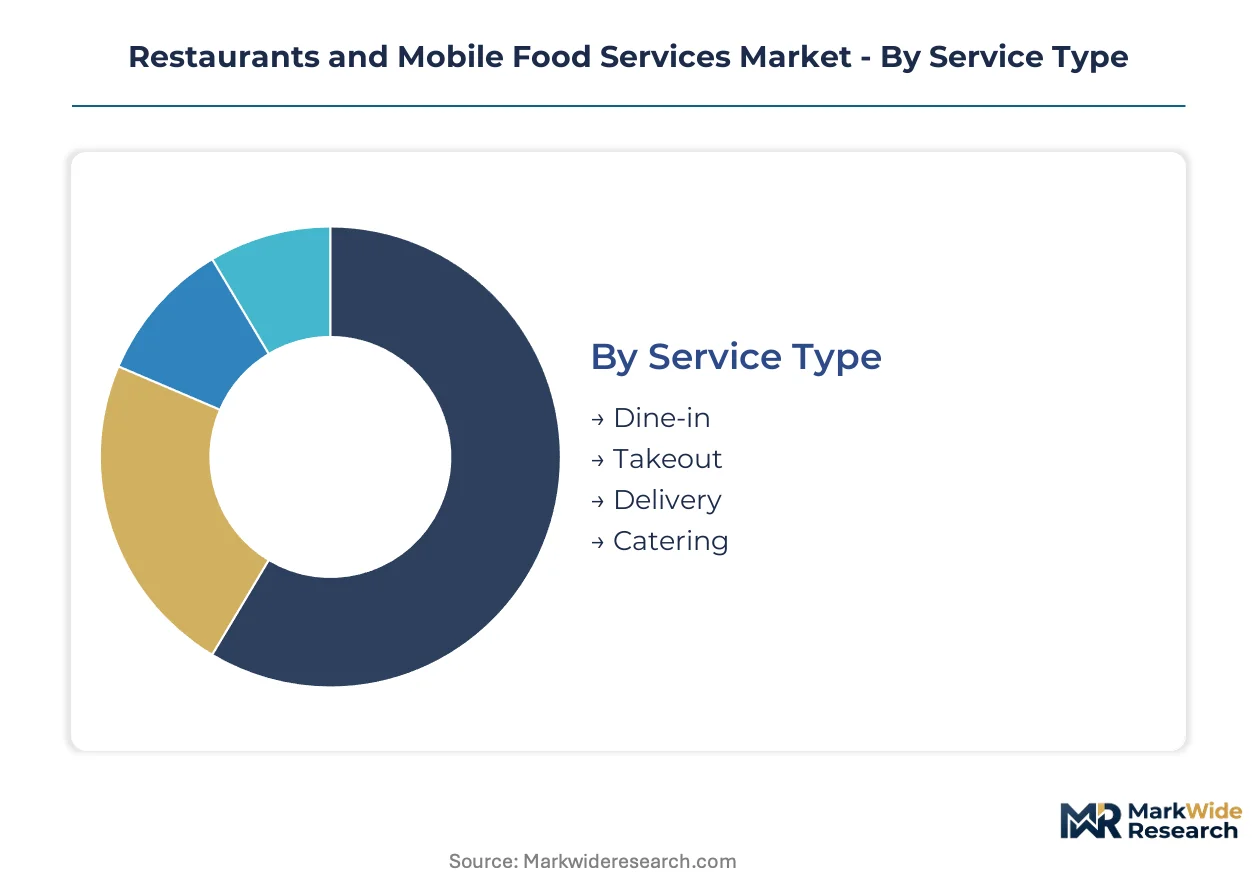
Format economics and service velocity requirements create divergent investment profiles across segment boundaries. Operators must align capital allocation with occasion-based consumption patterns rather than pursuing uniform coverage.
Service Type:
After-sales service intensity varies sharply—delivery platforms demand continuous algorithm optimization while dine-in requires physical maintenance cadences.
- Dine-in:Full-service environments with dedicated seating, table service protocols, and ambiance-driven capital expenditure. Demand concentrates in Indian tier-2 urban centers and Vietnamese secondary cities where emerging middle-class households seek occasion-based experiences outside home kitchens.
- Takeout:Counter-service models optimized for speed with minimal customer dwell time. Bangkok and Jakarta food courts exhibit the steepest expansion trajectory as office workers prioritize convenience over experience during compressed lunch windows.
- Delivery:Kitchen-only production with third-party logistics integration or captive rider fleets. Cloud kitchen operators in Mumbai and Singapore deploy this format to minimize real estate exposure while maximizing digital reach.
- Catering:Large-batch production for events, institutions, and corporate contracts with advance scheduling requirements. FSSAI licensing simplification in Indian tier-2 cities unlocks mid-scale operators previously excluded by permit complexity.
Dine-in holds the largest share; momentum sits with Delivery.
Food Category:
Margin architecture separates segments—Fine Dining commands per-cover premiums while Street Food optimizes throughput velocity.
- Fast Food:Standardized menus with limited customization, drive-thru or counter formats, and supply chain centralization. Dense urban corridors in the Philippines and Indonesia sustain volume concentration as commute patterns favor grab-and-go consumption.
- Casual Dining:Full-service at moderate price points with broader menu variety and relaxed pacing. Young adult demand clusters in Ho Chi Minh City and Bengaluru tech districts favor this segment for social occasions without Fine Dining expenditure.
- Fine Dining:Chef-driven concepts with premium ingredients, extended service rituals, and wine program integration. Tourist corridors in Dubai and Singapore maintain concentration despite local market compression.
- Street Food:Mobile or fixed-cart operations with minimal infrastructure, hyper-local menus, and cash-equivalent transaction speeds. Regulatory fragmentation across Indian state capitals constrains national fleet scaling despite consumer demand.
Fast Food holds the largest share; Street Food is climbing the fastest.
Customer Type:
Frequency and basket size patterns diverge—Professionals generate predictable weekday lunch volume while Families concentrate spending on weekend occasions.
- Families:Multi-cover transactions with shared dishes, child-accommodating environments, and celebration-driven timing. Weekend demand peaks in suburban Jakarta and Manila retail-entertainment complexes.
- Young Adults:Digital-native ordering, social media visibility requirements, and price-sensitive experimentation. This cohort drives aggregator platform penetration in Vietnamese and Thai urban centers.
- Professionals:Compressed time windows, loyalty program responsiveness, and corporate subsidy eligibility. Subscription meal contracts in Bengaluru and Singapore business districts displace individual transactions.
- Tourists:Experience-seeking with low repeat probability, guidebook influence, and currency convenience needs. Recovery patterns concentrate in Dubai and Southeast Asian aviation hubs.
Families hold the largest share; Professionals are gaining share fastest.
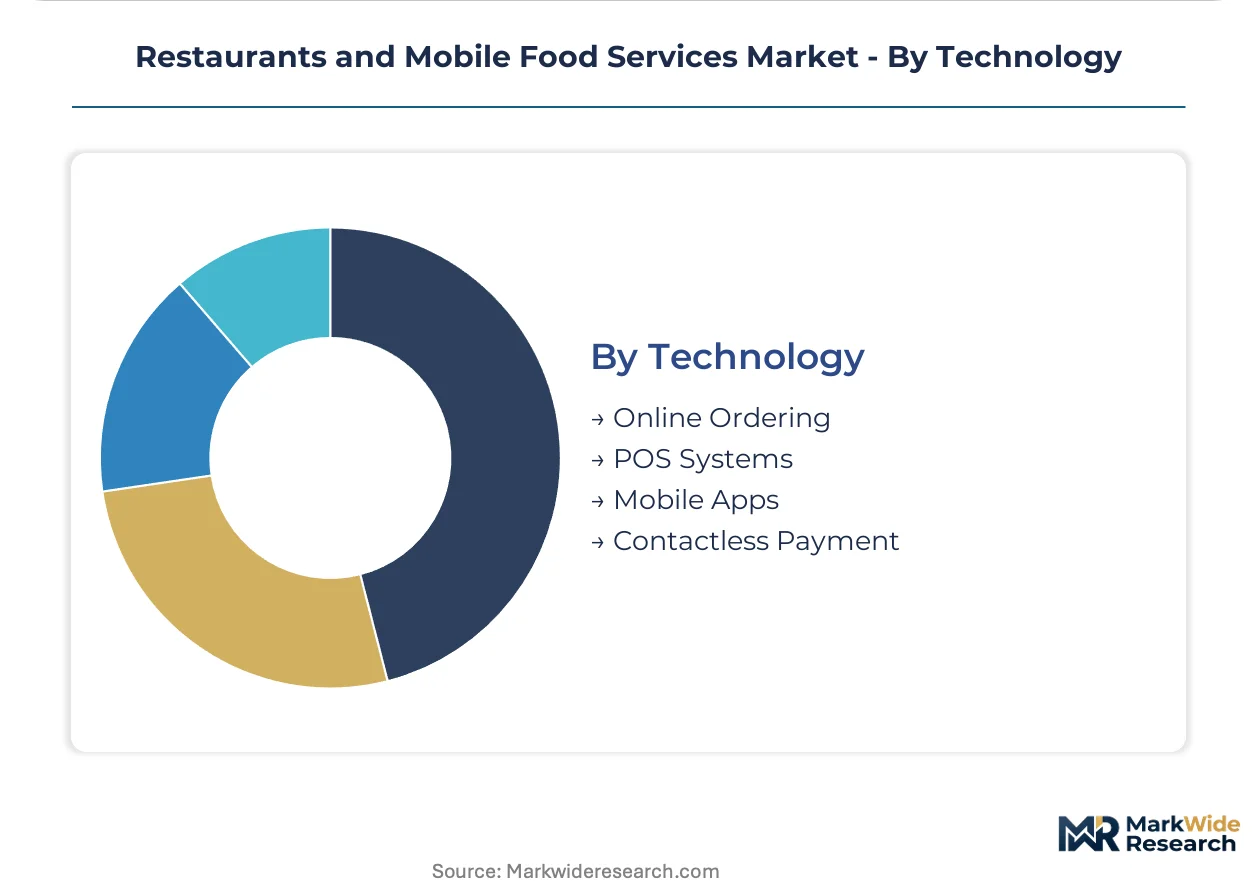
Technology:
Integration complexity escalates from payment rails through full-stack ordering platforms.
- Online Ordering:Web and app-based placement with kitchen display system integration and estimated wait algorithms. Cloud kitchen operators in Mumbai and Bangkok treat this as primary customer interface.
- POS Systems:Transaction processing with inventory tracking, labor scheduling, and reporting modules. Legacy migration friction persists at mid-scale Indian chains with established accounting software dependencies.
- Mobile Apps:Branded ordering with loyalty program architecture and push notification marketing. Quick-service chains in Singapore and Dubai deploy these to reduce aggregator commission exposure.
- Contactless Payment:QR-code and NFC transaction rails eliminating cash handling friction. Street food clusters in Jakarta and Manila exhibit steepest adoption curves as throughput constraints ease.
POS Systems hold the largest installed base; Contactless Payment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Pune Expressway corridor anchors India's mobile food distribution network, connecting cloud kitchen clusters to dense consumer basins across Maharashtra state.
United States
Drive-thru velocity dominates suburban consumption patterns across the Sun Belt. FDA Food Code 2022 updates mandate enhanced allergen documentation and time-temperature logging. McDonald's leverages its real estate footprint across North American suburban corridors to sustain throughput dominance.
India
Urban density in Bengaluru and Mumbai compresses dine-in economics toward delivery-first models. FSSAI streamlined licensing through its single-window clearance portal reduces permit timelines from months to weeks in tier-2 centers. Cloud kitchen operators in Mumbai deploy shared commissary models to slash capital requirements.
Singapore
Compact ventless cooking systems enable parking-structure kitchen deployments without hood construction. The country's national food safety regulator maintains stringent hygiene enforcement that elevates compliance costs for independent operators. Hawker center modernization in Tampines and Jurong anchors street food formalization.
Indonesia
Jakarta's food court expansion captures office-worker lunch demand with compressed service windows. Municipal zoning fragmentation across Indonesian state capitals creates operational discontinuity for national fleet operators. Surabaya exhibits mobile food penetration gaps relative to capital-city saturation.
Germany
EU Hygiene Package Directives standardize food safety protocols that reduce cross-border compliance friction. F-Gas Regulation phase-down schedules constrain cold-chain equipment availability and inflate replacement costs. Berlin's Kreuzberg district concentrates alternative food service formats with minimal infrastructure.
Restaurants and Mobile Food Services Market Competitive Landscape
On the supply side, the industry is consolidating around format specialists with dedicated legal infrastructure and centralized training capabilities. Chains with captive commissary networks absorb compliance cost escalations that marginalize independent operators. Two strategic archetypes dominate: real estate-heavy drive-thru operators and digital-native cloud kitchen platforms. Competitive moves concentrate on M&A for regional footprint expansion and technology licensing for POS integration.
Within the quick-service tier, McDonald's and Restaurant Brands International Inc. exemplify real estate-leveraged scale strategies, while Chipotle and Yum China Holdings Inc. occupy positions emphasizing digital integration and localized menu engineering respectively. These operators represent divergent responses to the compression between fixed-location and mobile format economics.
| Leading Market Players |
|---|
| Restaurant Brands International Inc. |
| Zensho Holdings Co Ltd |
| McDonald's |
| Chick-fil-A |
| Subway |
| Yum China Holdings Inc. |
| Chipotle |
| Bloomin' Brands |
| Darden Restaurants |
| Others |
Value Network & Pricing Analysis
F-Gas Regulation phase-down schedules in Europe constrain cold-chain equipment availability and inflate replacement costs, compressing margin spreads between premium full-service chains and economy mobile operators while forcing supply chain restructuring toward modular, ventless equipment architectures.
Pricing Analysis
Volume-discount tiering structures separate enterprise cloud kitchen networks from independent street vendors, with procurement scale determining per-unit equipment costs and SaaS-based POS subscription rates. Price differentiation hinges on FSSAI certification tier and captive commissary vertical integration, with certified operators commanding premium contract terms from aggregator platforms. Pricing pressure intensifies in the delivery-first segment as commission rates from Swiggy and Zomato compress kitchen-level margins. Quick-service chains exhibit lowest price sensitivity due to brand-anchored demand, while unbranded mobile units face acute cost pass-through constraints.
Supply Chain Analysis
Contract-manufacturing concentration for commercial kitchen equipment centers on China, Germany, and Italy, with Guangdong province dominating ventless cooking system assembly and Bavaria anchoring precision refrigeration component fabrication. Raw material dependencies span stainless steel grades, catalytic oxidation substrates, and semiconductor-based temperature sensors. Supply chain risk concentrates in single-source vulnerability for F-gas refrigerant alternatives under EU phase-down mandates. Distribution runs through regional equipment distributors in Mumbai, Singapore, and Dubai who bundle installation and maintenance service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in food service are approaching an inflection as aggregator interoperability with kitchen display systems and autonomous delivery fleets reshapes value capture between production and logistics layers.
For Market Incumbents: Build captive rider fleet density as a moat against rising third-party commission extraction. Yum China Holdings Inc. and McDonald's should accelerate backward integration into cloud kitchen real estate in Bengaluru and Jakarta, locking in production capacity ahead of zoning liberalization. FDA Food Code 2022 compliance infrastructure investments create regulatory barriers that marginalize independent operators lacking centralized training capabilities. For New Entrants and Emerging Players: Pursue secondary Southeast Asian cities—Surabaya, Cebu, and Da Nang—where mobile food penetration gaps coexist with underdeveloped dine-in infrastructure and permissive municipal zoning. Ghost kitchen convergence with subscription meal contracts in Indian tier-2 tech corridors offers the most penetrable entry vector. A go-to-market angle anchored in employer-subsidized corporate dining bundles displaces individual transaction competition. For Investors and Strategic Acquirers: Cloud kitchen operators with integrated logistics software and FSSAI streamlined licensing access represent the priority acquisition archetype for platform consolidation plays. Long-term viability hinges on recurring revenue contract penetration displacing per-cover volatility. The signal to watch is municipal zoning liberalization velocity for food trucks across Indian state capitals, indicating addressable market expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Network Expansion | Shared kitchen infrastructure in Mumbai and Bangkok slashes capital requirements for multi-brand operators. |
| Contactless Payment Integration | QR-code rails at Jakarta street food clusters accelerate throughput and reduce cash-handling labor. |
| Regulatory Compliance Certification | FDA Food Code 2022 documentation systems create structural advantages for chains with dedicated safety infrastructure. |
| Autonomous Delivery Partnership | Robotics integration with Singapore cloud kitchens eliminates last-mile labor cost escalation. |
| Subscription Contract Bundling | Employer-subsidized meal programs in Bengaluru business districts shift revenue to recurring structures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud kitchen operators, municipal health department licensing officers, aggregator platform strategy leads, commercial kitchen equipment distributors, and FSSAI compliance consultants. Secondary validation drew from FDA Food Code documentation, EU Hygiene Package directive filings, FSSAI licensing portal statistics, municipal zoning ordinance databases, and cloud kitchen real estate transaction records. Bottom-up unit economics modeling triangulated against top-down market sizing from trade association membership data.
Calibration across the analysis window employed scenario-weighted projections for regulatory implementation timelines and technology adoption curves. Segmentation dimensions modeled include service type, food category, customer archetype, and technology integration depth, with regional regulatory cluster treated as an orthogonal stratification layer. CAGRs derived from fitted growth curves against historical cloud kitchen expansion velocity and mobile food permit issuance rates. Industry-specific forecast inputs incorporated F-gas phase-down compliance cost trajectories and contactless payment penetration saturation curves.
Sensitivities concentrate around municipal zoning liberalization velocity, FSSAI licensing portal operational reliability, and aggregator commission rate negotiations. Forecasts embed assumptions regarding sustained urban density growth in Indian and Southeast Asian megacities and stable regulatory enforcement intensity. Quarterly review of food truck permit issuance statistics, cloud kitchen square footage absorption, and aggregator GMV disclosure patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Cloud Kitchen Market
Food Service
Egypt Food Service Market
Food Service
Food Trays Market
Food Service
Commercial Charbroiler Market
Food Service
Full-Service Restaurants Market
Food Service
Online Grocery Market
Food Service
Europe Inflight Catering Market
Food Service
Food Service Gloves Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
South Africa Fast Food Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
India Quick Service Restaurant Market
Food Service
Food Service Disposables Market
Food Service
Beverage Napkins Market
Food Service
Onboard Rail Catering Market