
 Saudi Arabia Out of Home (OOH) Delivery Market | 2026-2036
Saudi Arabia Out of Home (OOH) Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Out of Home (OOH) Delivery Market Insights
SFDA food safety certification for cloud kitchen operations is redrawing competitive boundaries in Saudi Arabia's OOH delivery ecosystem. JCDecaux SE leverages its digital infrastructure expertise to position advertising-integrated delivery touchpoints across urban retail zones. Saudi Signs Media Co. anchors physical presence through billboard-to-delivery-point conversion networks in Riyadh and Jeddah. Alan Media and Advertising Co. competes by specializing in venue-specific pickup locker installations tied to sports and entertainment complexes.
Out of Home (OOH) Delivery encompasses prepared food and grocery logistics executed through off-premise channels including mobile applications, centralized kitchens, and automated pickup points, with order fulfillment cycles typically ranging from fifteen to forty-five minutes depending on traffic algorithms and batch optimization. The service type dimension spans food delivery, groceries, alcohol, and prepared meals, with food delivery occupying the largest transaction volume while subscription orders capture the highest customer lifetime value through recurring revenue structures. Mobile apps dominate the technology layer, though kiosk-based ordering at transit hubs and office towers represents the fastest-growing interface as landlords integrate food service into building amenity packages.
SFDA licensing requirements govern food handler certification and facility hygiene standards, while SAMR commercial registration rules shape market access for foreign platform operators seeking local establishment. The CITC framework for digital payment integration and data localization adds compliance layers to app-based ordering infrastructure. Stakeholders must monitor how MOF excise tax adjustments on sugary beverages and prepared foods cascade through menu pricing and consumer basket composition.
Market Dynamics
SFDA licensing requirements for cloud kitchens are compressing operational margins while simultaneously raising barriers to entry across Saudi Arabia's OOH delivery ecosystem. Platform operators now face mandatory food handler certification and facility hygiene audits that extend setup timelines and capital requirements.
Growth Catalysts
- Corporate Catering Concentration:Riyadh's central business district corridor generates dense order clustering that enables batch optimization algorithms and reduces per-unit delivery costs.
- CITC Digital Payment Framework:Data localization mandates and integrated payment infrastructure accelerate consumer trust in app-based ordering platforms.
- Kiosk Deployment at Transit Hubs:Landlords in Jeddah's commercial towers are embedding food service into building amenity packages, creating captive demand pools.
Market Restraints
- SFDA Compliance Costs:Facility hygiene standards and certification timelines impose fixed cost burdens that disadvantage smaller cloud kitchen operators.
- Input Cost Volatility:MOF excise tax adjustments on sugary beverages and prepared foods compress menu pricing flexibility and consumer basket margins.
- Geographic Demand Skew:Transaction volumes concentrate in Riyadh and Jeddah, leaving secondary urban centers with insufficient density for unit economics.
Strategic Opportunities
- Eastern Province Expansion:Dammam and Khobar present underpenetrated corridors where corporate and industrial catering demand exceeds current platform coverage.
- Subscription Model Penetration:Recurring revenue structures capture higher customer lifetime value than transactional ordering, particularly in corporate meal programs.
- Automated Pickup Locker Networks:Venue-specific installations at sports and entertainment complexes reduce last-mile costs while improving order throughput.
Industry Challenges
- Food Safety Certification Timelines:SFDA facility audits and handler training requirements extend go-to-market timelines for new cloud kitchen entrants.
- Legacy POS Integration:Established restaurant chains face technical friction when connecting proprietary systems to third-party delivery platforms.
- Batch Optimization Complexity:Traffic algorithm refinement for fifteen-to-forty-five-minute fulfillment windows demands specialized data science capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Out of Home (OOH) Delivery Market |
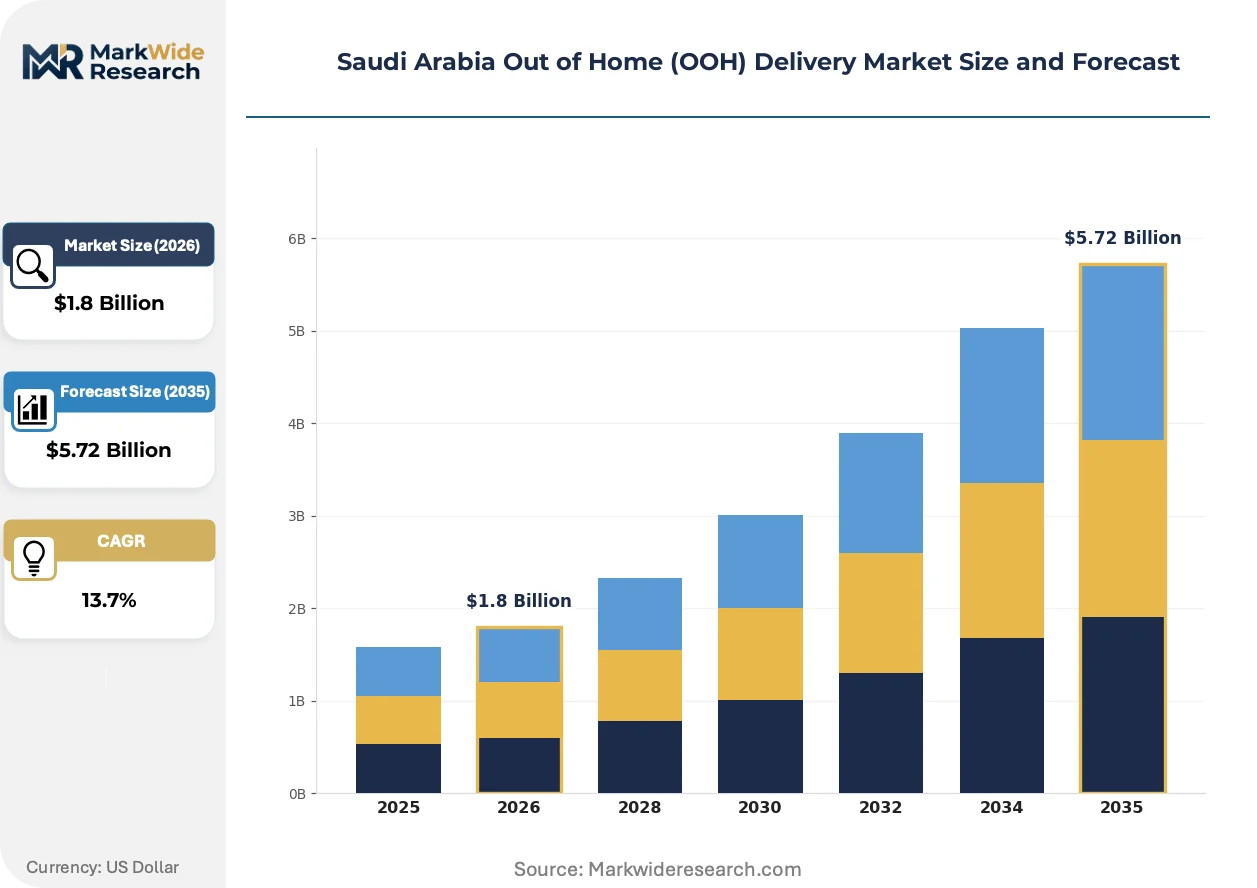
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Delivery, Groceries, Alcohol, Prepared Meals Customer Type: Individuals, Corporates, Events, Institutions Technology: Mobile Apps, Websites, Kiosks, SMS Order Size: Small Orders, Large Orders, Bulk Orders, Subscription Orders |
| Companies Covered | AlArabia, JCDecaux SE, Saudi Signs Media Co., Alan Media and Advertising Co., Alliance Media Holdings, Daktronics, Advertising Ways Company Ltd., Faden Media Advertising Agency, Rotana Media Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Out of Home (OOH) Delivery Market Trends and Innovations
Delivery infrastructure is diverging from pure platform competition toward embedded physical touchpoints that merge advertising, logistics, and consumer convenience. This reconfiguration favors operators with real estate access and digital infrastructure expertise over pure software plays.
AI-powered traffic algorithms are fragmenting the competitive landscape by enabling smaller operators to achieve batch efficiencies previously reserved for scale players. Mid-sized cloud kitchens in Jeddah now deploy dynamic routing systems that match incumbent delivery windows. The technology is fragmenting market share concentration and compressing the premium commanded by first-mover platforms.
SFDA food safety licensing requirements are tightening facility standards and extending compliance timelines for new entrants. Cloud kitchen operators must now demonstrate continuous temperature monitoring and traceability systems before receiving operational permits. Delivery-only facilities in Riyadh are responding by investing in automated hygiene monitoring and blockchain-based ingredient tracking.
Corporate procurement of catering services is consolidating around subscription-based models that lock in volume commitments and reduce per-order transaction friction. Bulk ordering platforms are displacing ad-hoc restaurant selection for event-driven and recurring meal programs. This shift is most visible in Riyadh's central business district, where enterprise accounts now represent the dominant revenue stream for specialized OOH delivery operators.
Saudi Arabia Out of Home (OOH) Delivery Market Segmentation
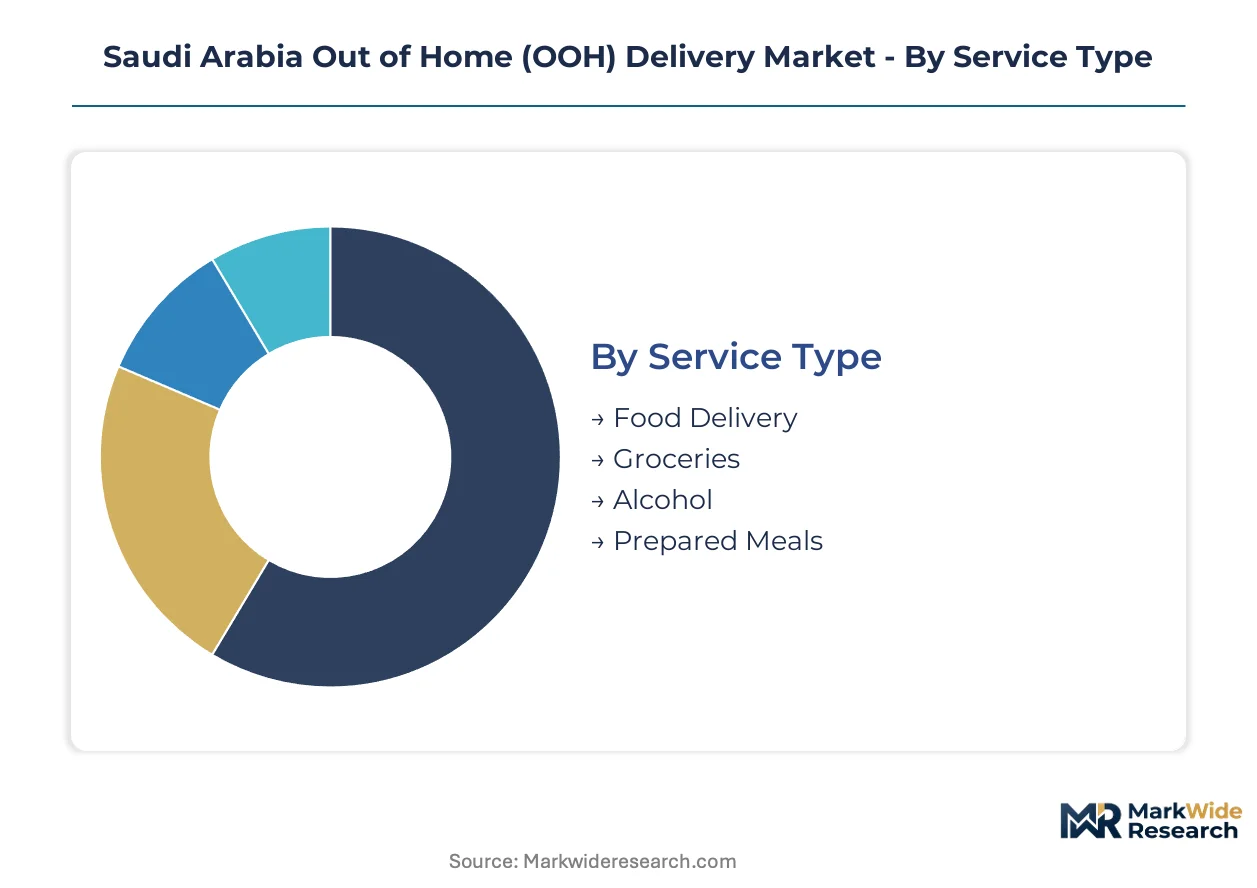
Segmentation in Saudi Arabia's OOH delivery market reveals how regulatory frameworks and urban geography concentrate value across distinct service configurations. Understanding these divisions exposes where SFDA compliance costs and Riyadh-Jeddah demand density reshape competitive economics.
Service Type:
Domestic consumption patterns dominate all service categories, with no export-oriented segments given the localized nature of food logistics and SFDA jurisdiction.
- Food Delivery:Quick-service restaurant chains and cloud kitchens execute fulfillment through centralized production facilities. Riyadh's central business district corridor generates dense order clustering that enables batch optimization algorithms and reduces per-unit delivery costs.
- Groceries:Supermarket partnerships and dark store networks manage inventory-heavy logistics with temperature-controlled handling requirements. Jeddah's commercial tower landlords embed grocery kiosks into building amenity packages, creating captive demand pools in high-density residential zones.
- Alcohol:Non-alcoholic beverage substitutes and premium mocktail delivery operate within MOF excise tax frameworks. Regulatory constraints limit operational flexibility for this segment.
- Prepared Meals:Subscription-based corporate catering and event-driven bulk orders target institutional procurement channels. SFDA licensing requirements extend setup timelines for facilities producing ready-to-eat portions.
Food delivery commands the established base. The steepest expansion runs through prepared meals.
Customer Type:
Cost tier differentiation separates high-volume corporate accounts from transactional individual users, with institutional procurement demanding specialized compliance infrastructure.
- Individuals:Mobile app users generate fragmented demand across residential neighborhoods. Last-mile costs remain elevated outside Riyadh and Jeddah urban cores due to insufficient order density.
- Corporates:Enterprise meal programs and recurring catering contracts lock in volume commitments through subscription structures. Riyadh's central business district anchors this segment with concentrated headquarters operations.
- Events:Temporary demand spikes from conferences and entertainment venues require surge capacity planning. Alan Media and Advertising Co. targets this segment through venue-specific pickup locker installations.
- Institutions:Healthcare facilities and educational campuses demand continuous service with strict SFDA hygiene documentation. Long procurement cycles characterize this tier.
Individual orders capture transaction volume. Corporate accounts deliver margin expansion through recurring revenue structures.
Technology:
Application maturity separates established mobile platforms from emerging physical interfaces, with kiosk deployment accelerating fastest in Jeddah commercial real estate.
- Mobile Apps:Dominant interface for individual and corporate ordering with integrated CITC-compliant payment infrastructure. Platform operators invest in AI-powered traffic algorithms to compress fifteen-to-forty-five-minute fulfillment windows.
- Websites:Secondary channel for corporate procurement and institutional accounts requiring detailed menu documentation. Legacy POS integration friction affects established restaurant chains connecting proprietary systems.
- Kiosks:Transit hub and office tower installations represent the fastest-growing interface as landlords integrate food service into building amenity packages. JCDecaux SE leverages digital infrastructure expertise to position advertising-integrated delivery touchpoints.
- SMS:Fallback channel for low-bandwidth environments and demographic segments with limited smartphone penetration. Minimal platform investment targets this modality.
Mobile apps anchor current infrastructure. Kiosk deployment shows the steepest upward trajectory in urban retail zones.
Order Size:
Volume economics divide the market, with subscription and bulk configurations enabling route optimization that small orders cannot achieve.
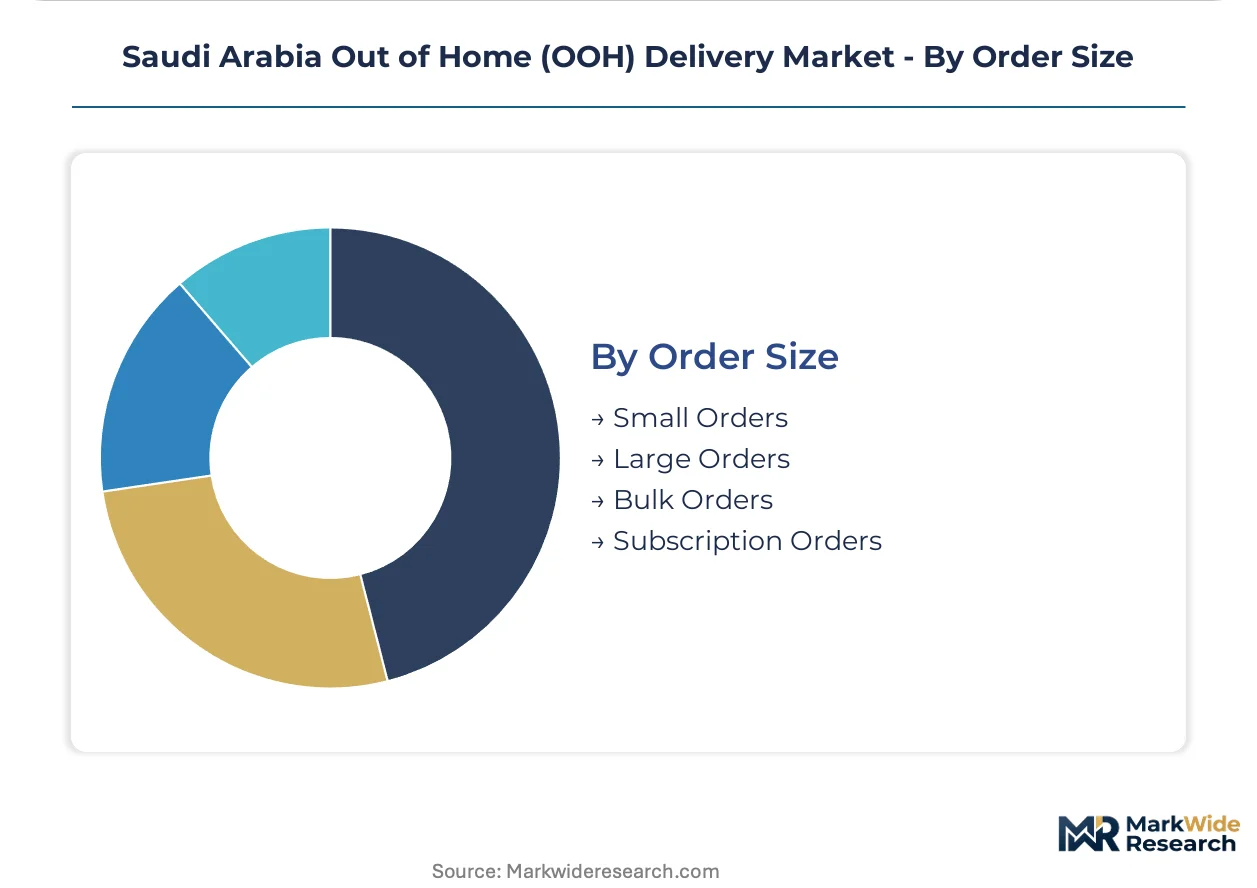
- Small Orders:Individual meal transactions with high per-unit delivery cost burdens. Batch optimization algorithms struggle to achieve efficiency at this scale outside dense urban corridors.
- Large Orders:Family-sized portions and multi-item baskets improve unit economics through consolidated preparation and delivery. Corporate catering often structures demand at this threshold.
- Bulk Orders:Event-driven and institutional procurement with dedicated logistics scheduling. Saudi Signs Media Co. anchors physical presence through billboard-to-delivery-point conversion networks supporting this segment.
- Subscription Orders:Recurring revenue structures capture the highest customer lifetime value through locked-in volume commitments. Corporate meal programs in Riyadh's central business district increasingly consolidate around this model.
Small orders dominate transaction counts. Subscription configurations gain share fastest through enterprise procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate catering contracts and cloud kitchen density concentrate demand across Saudi Arabia's major urban corridors, with regulatory compliance requirements from SFDA and SAMR shaping operational economics differently by sub-region.
Riyadh
Central business district headquarters operations generate dense order clustering for batch-optimized delivery algorithms. SFDA food handler certification requirements extend setup timelines for new cloud kitchen entrants in the capital. King Abdullah Financial District anchors corporate meal program procurement with subscription-based volume commitments.
Eastern Province
Dammam and Khobar industrial corridors present underpenetrated demand for corporate and industrial catering services. SAMR commercial registration rules shape market access for platform operators establishing local entities. Dhahran's corporate campuses concentrate institutional procurement with strict hygiene documentation requirements.
Jeddah
Commercial tower landlords embed food service kiosks into building amenity packages, creating captive demand pools. CITC digital payment frameworks accelerate consumer trust in app-based ordering across Red Sea coastal zones. King Abdulaziz International Airport vicinity generates event-driven bulk order spikes requiring surge capacity.
Western Region
Makkah and Madinah pilgrimage infrastructure supports seasonal demand volatility for prepared meal logistics. MOF excise tax adjustments on sugary beverages compress menu pricing flexibility in hospitality-heavy zones. Holy site proximity drives specialized halal certification requirements above baseline SFDA standards.
NEOM Northwest
Greenfield urban development enables integrated delivery infrastructure design without legacy system constraints. The country's national investment fund backing mandates smart city technology adoption from inception. Oxagon industrial zone planning incorporates automated pickup locker networks into district logistics architecture.
Saudi Arabia Out of Home (OOH) Delivery Market Competitive Landscape
Player mix skews toward advertising-integrated infrastructure operators and physical network specialists rather than pure software platforms. Market structure concentrates around entities with real estate access and digital signage expertise. Three archetypes dominate: outdoor media converters, venue-specific locker installers, and transit hub kiosk deployers. Competitive moves center on billboard-to-delivery-point conversions and landlord partnership negotiations for building amenity integration.
Within the outdoor media converter archetype, JCDecaux SE and Saudi Signs Media Co. occupy positions leveraging digital infrastructure expertise for advertising-integrated delivery touchpoints. JCDecaux SE exemplifies the transit hub kiosk deployer model through urban retail zone positioning. Saudi Signs Media Co. anchors the physical network specialist tier with Riyadh and Jeddah corridor coverage. Alan Media and Advertising Co. represents the venue-specific locker installer archetype targeting sports and entertainment complexes. Alliance Media Holdings and Daktronics sit within the digital signage technology supply tier supporting platform operator hardware requirements.
| Leading Market Players |
|---|
| AlArabia |
| JCDecaux SE |
| Saudi Signs Media Co. |
| Alan Media and Advertising Co. |
| Alliance Media Holdings |
| Daktronics |
| Advertising Ways Company Ltd. |
| Faden Media Advertising Agency |
| Rotana Media Services |
| Others |
Pricing and Supply Chain Analysis
Fifteen-to-forty-five minute fulfillment windows compress inventory holding periods across Saudi Arabia's OOH delivery network, tethering pricing power to real-time batch optimization capabilities rather than static cost-plus structures. Cloud kitchen operators in Riyadh and Jeddah face margin pressure from SFDA compliance investments that cannot be passed through to price-sensitive individual consumers, while corporate subscription accounts absorb premium positioning through locked volume commitments.
Pricing Analysis
Cost-plus contracts with MOF excise tax indexation dominate prepared meal procurement for institutional accounts, insulating caterers from input volatility while compressing menu flexibility. Price differentiation rests on SFDA certification tier and geographic delivery density, with Riyadh's central business district commanding premium positioning against Jeddah's dispersed residential zones. Cost compression in the individual transaction tier intensifies because batch algorithms struggle to achieve efficiency outside dense urban corridors. Corporate procurement teams show lowest price sensitivity due to subscription-locked budgets, while individual mobile app users exhibit acute responsiveness to delivery fee fluctuations.
Supply Chain Analysis
Just-in-time inventory preferences dominate perishable food logistics, though cloud kitchen operators maintain strategic stockpiles of shelf-stable inputs to buffer against MOF excise tax adjustments. Ingredient sourcing draws from India, Brazil, and regional Gulf producers for core commodities, with specialized halal certification requirements limiting supplier flexibility. Temperature-controlled packaging and last-mile fleet capacity represent critical component dependencies. Single-source vulnerability concentrates in SFDA-licensed cold storage facilities within Riyadh's industrial zones. Distribution runs through platform-operated dark stores and landlord-integrated kiosk networks at transit hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's OOH delivery market functions as a defensive-moat arena where SFDA regulatory entrenchment creates sustainable competitive advantage for established operators with certified facility networks.
For Market Incumbents: Fortify market position by deepening backward integration into cloud kitchen real estate in Riyadh's King Abdullah Financial District, securing captive production capacity against emerging platform competitors. Invest in blockchain-based ingredient traceability systems to extend SFDA compliance lead times into insurmountable barriers for unlicensed entrants. Channel control through exclusive landlord kiosk partnerships at Jeddah commercial towers locks in amenity-embedded demand pools. For New Entrants and Emerging Players: Lead with subscription-based corporate catering models in Dammam and Khobar's underpenetrated industrial corridors, where enterprise procurement lacks specialized OOH delivery infrastructure. Target the Eastern Province's healthcare and educational campus segments, where institutional procurement cycles favor new entrants with dedicated hygiene documentation capabilities. A go-to-market angle anchored in AI-powered batch optimization can match incumbent delivery windows without comparable fleet scale. For Investors and Strategic Acquirers: Carve-out targets emerge from outdoor media holding companies with underutilized billboard-to-delivery-point conversion networks in secondary urban corridors. Long-term viability over a multi-year horizon rests on regulatory entrenchment deepening rather than platform technology differentiation. Acquisition candidates with existing SFDA certifications and Riyadh-Jeddah corridor presence offer defensive positioning. The signal to watch is MOF excise tax expansion into additional prepared food categories, which would accelerate consolidation toward vertically integrated operators with captive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Pre-Investment | Early compliance commitment locks in operational permits before facility construction timelines extend. |
| Corporate Subscription Platform Launch | Recurring revenue structures capture higher customer lifetime value through Riyadh enterprise procurement consolidation. |
| Kiosk Network Landlord Partnership | Building amenity integration at Jeddah commercial towers creates captive demand pools with reduced acquisition costs. |
| AI-Powered Batch Optimization Deployment | Dynamic routing systems enable mid-sized operators to match incumbent fifteen-to-forty-five-minute fulfillment windows. |
| Eastern Province Geographic Expansion | Dammam and Khobar industrial corridors present underpenetrated demand exceeding current platform coverage. |
Research Methodology
Operator-level perspectives from cloud kitchen facility managers, corporate catering procurement leads, platform algorithm engineers, and SFDA compliance officers anchored the qualitative base. Primary interview data combined with secondary validation from SAMR commercial registration records, CITC digital payment framework disclosures, and MOF excise tax adjustment bulletins. Bottom-up unit economics modeling triangulated against top-down market sizing from platform transaction disclosures and landlord kiosk deployment announcements.
Sensitivity analysis framed the quantitative approach across the projection horizon, with segmentation dimensions spanning service type, customer archetype, technology interface, and order size configuration. CAGRs derived from installed base growth rates, corporate subscription penetration curves, and kiosk deployment trajectories in Riyadh and Jeddah commercial real estate. Forecast inputs incorporated SFDA licensing timeline extensions, MOF tax policy volatility, and batch algorithm efficiency improvements.
The analysis sits within stated boundaries; outcomes outside sustained corporate procurement consolidation and SFDA enforcement continuity would require recalibration. Forecasts reflect documented assumptions regarding urban demand density thresholds and technology adoption curves. Practitioners should keep alternative scenarios live as MOF excise tax scope expansion and CITC data localization refinements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Food Retail Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
South America Free from Food Market
Food Service
Food Service Disposables Market
Food Service
Global Digital Grocery Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Malaysia Food Service Market
Food Service
Sandwich Toasters Market
Food Service
Commercial Burger Grill Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
North America Food Service Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Online Grocery Market
Food Service
Beverage Napkins Market
Food Service
China Food Service Market