
 Europe Airline Catering Services Market | 2026-2036
Europe Airline Catering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Airline Catering Services Market Insights
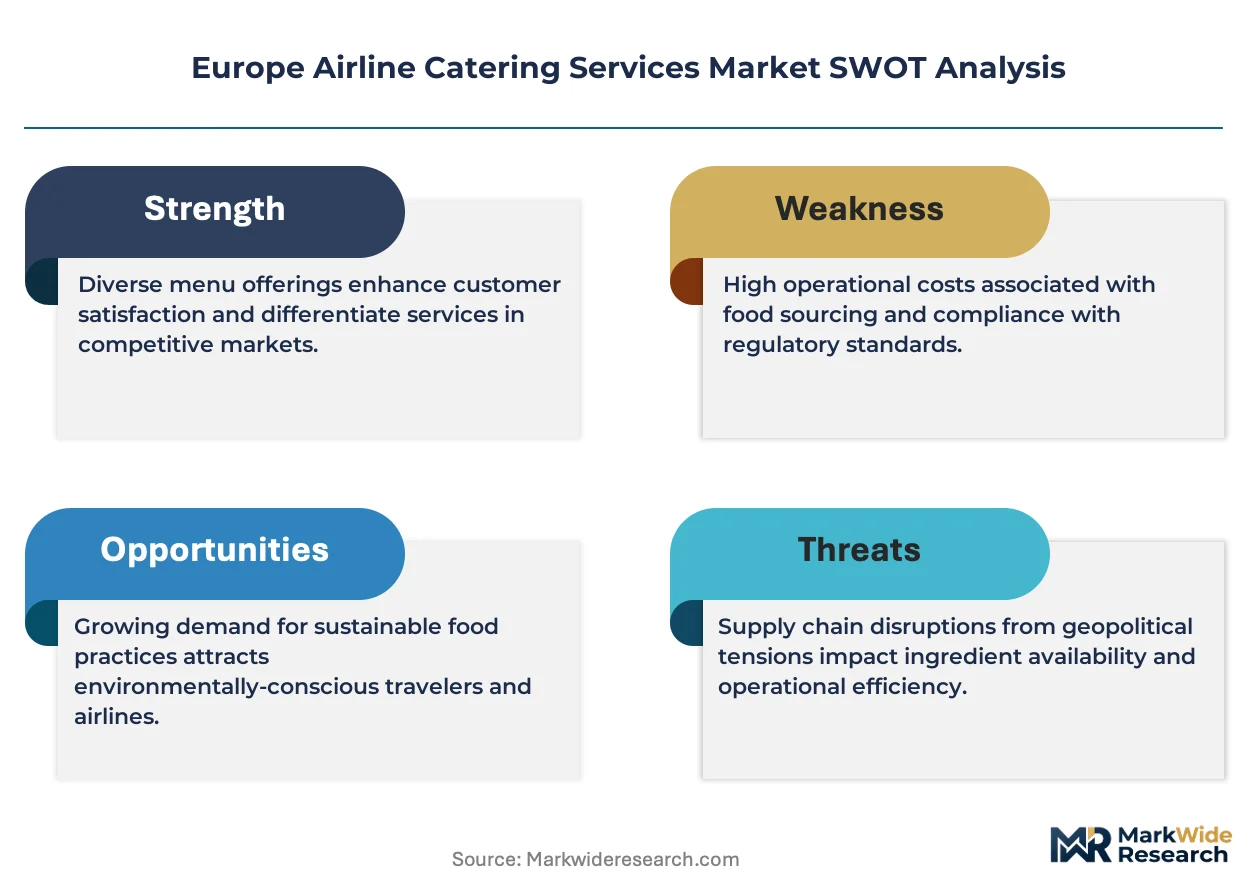
ISO 22000 certification is reorganizing competitive access across the Europe airline catering supply base, filtering out smaller commissary operators unable to sustain HACCP-aligned audit cycles. Gategroup leverages centralized kitchen networks across Amsterdam, Zurich, and London to sustain pan-European coverage for full-service carriers. DO & CO Aktiengesellschaft anchors premium culinary positioning through chef-staffed production facilities in Vienna and Frankfurt. Newrest Group Services competes on cost discipline in the low-cost segment with standardized meal kits produced at scale near Marseille and Barcelona.
Airline catering services encompass the procurement, preparation, assembly, and delivery of food and beverage items to aircraft, with meals typically blast-chilled to 4°C and maintained in temperature-controlled logistics chains until upload at the gate. The primary commercial purpose is to support airline passenger experience strategies while optimizing per-seat catering cost ratios against ticket yield. In-flight meals and special dietary meals command the deepest margin pools as premium cabins and medical-restricted diets justify higher unit pricing. Commercial airlines dominate client-type volumes, though private jets and charter services represent faster-expanding demand pockets as fractional ownership spreads across European executive travel corridors.
EASA food safety standards, EU Single-Use Plastics Directive constraints, and national veterinary border controls under TRACES govern ingredient sourcing, packaging substitution, and cross-border commissary operations throughout the continent. These frameworks elevate capital requirements for cold-chain infrastructure and compostable serviceware transitions, effectively consolidating procurement toward larger operators with compliance departments. Stakeholders must monitor how EU Green Deal aviation fuel mandates and airport slot allocation reforms reshape hub-and-spoke catering economics before committing to new production capacity.
Market Dynamics
ISO 22000 certification requirements and EASA food safety audits are filtering smaller commissary operators from Europe's airline catering supply base, consolidating procurement toward multi-hub networks with dedicated compliance infrastructure.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates for compostable serviceware are accelerating packaging substitution investments, creating first-mover advantages for suppliers with certified biodegradable supply chains.
- Low-cost carrier expansion:Buy-on-board program rollouts across Ryanair, Wizz Air, and EasyJet networks are generating incremental meal-kit demand at secondary airports.
- Blast-chilling automation:Continuous-flow rapid cooling systems are reducing microbial risk windows and extending prepared-food shelf stability for long-haul provisioning.
Market Restraints
- Ingredient cost volatility:Wheat, poultry, and dairy price swings compress margin predictability for fixed-price airline contracts indexed to quarterly adjustments.
- Hub airport supply concentration:Frankfurt, Amsterdam Schiphol, and London Heathrow dominate procurement volumes, creating dependency risk for operators without multi-site redundancy.
- Cross-border veterinary controls:TRACES documentation requirements for animal-origin ingredients add transit friction between production facilities and outstation airports.
Strategic Opportunities
- Private aviation corridors:Fractional jet ownership growth in Switzerland, Austria, and Monaco is outpacing commercial airline catering demand growth rates.
- EASA sustainable aviation fuel alignment:Green Deal mandates for carbon-neutral ground operations create co-marketing opportunities with airlines pursuing scope-3 emission reductions.
- AI-driven demand forecasting:Machine learning applied to passenger load factors and route-specific preferences is reducing overproduction waste and inventory carrying costs.
Industry Challenges
- HACCP auditor scarcity:Certified food safety specialists command premium salaries, constraining smaller operators' ability to maintain audit-ready documentation systems.
- Cold-chain capex intensity:Temperature-controlled vehicle fleets and gate-accessible holding facilities require capital deployment that strains balance sheets outside consolidated groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Airline Catering Services Market |
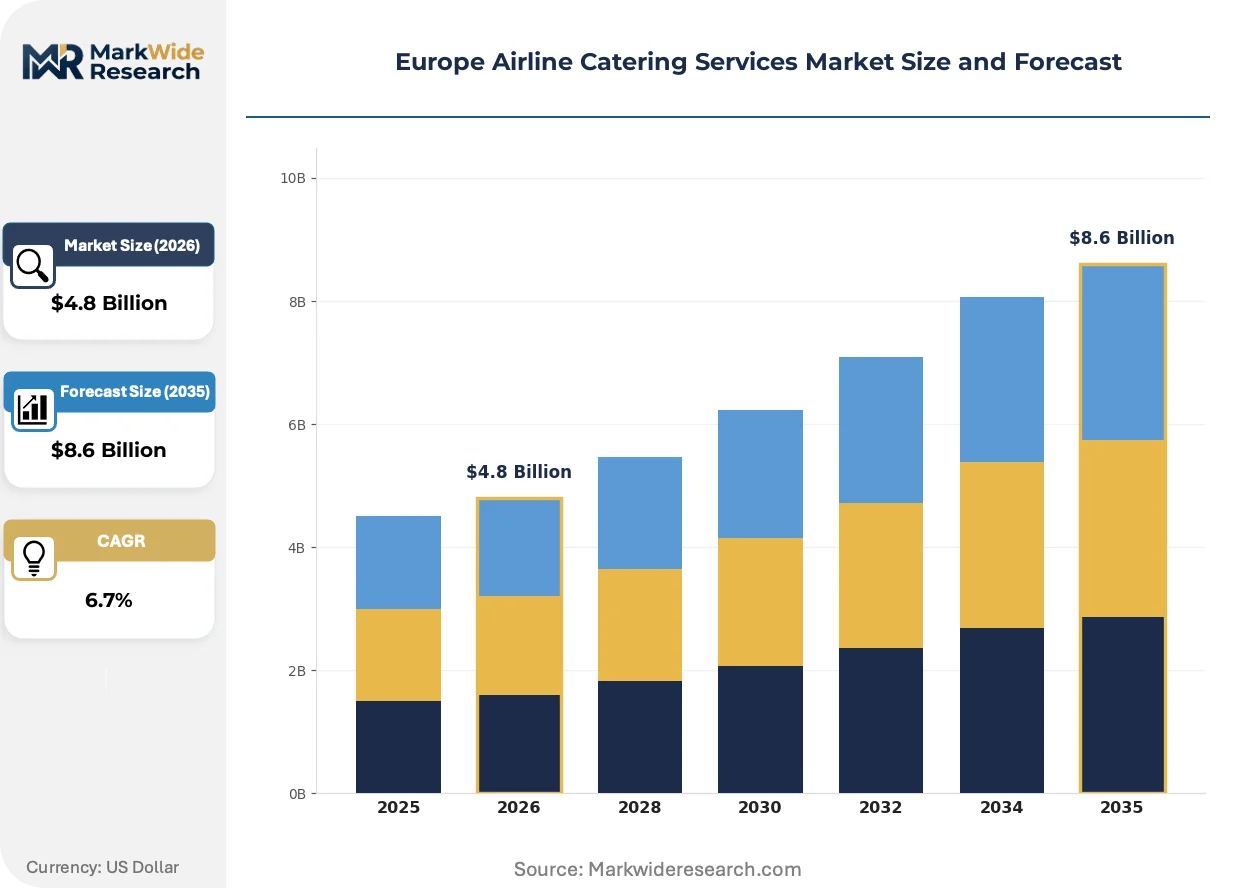
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
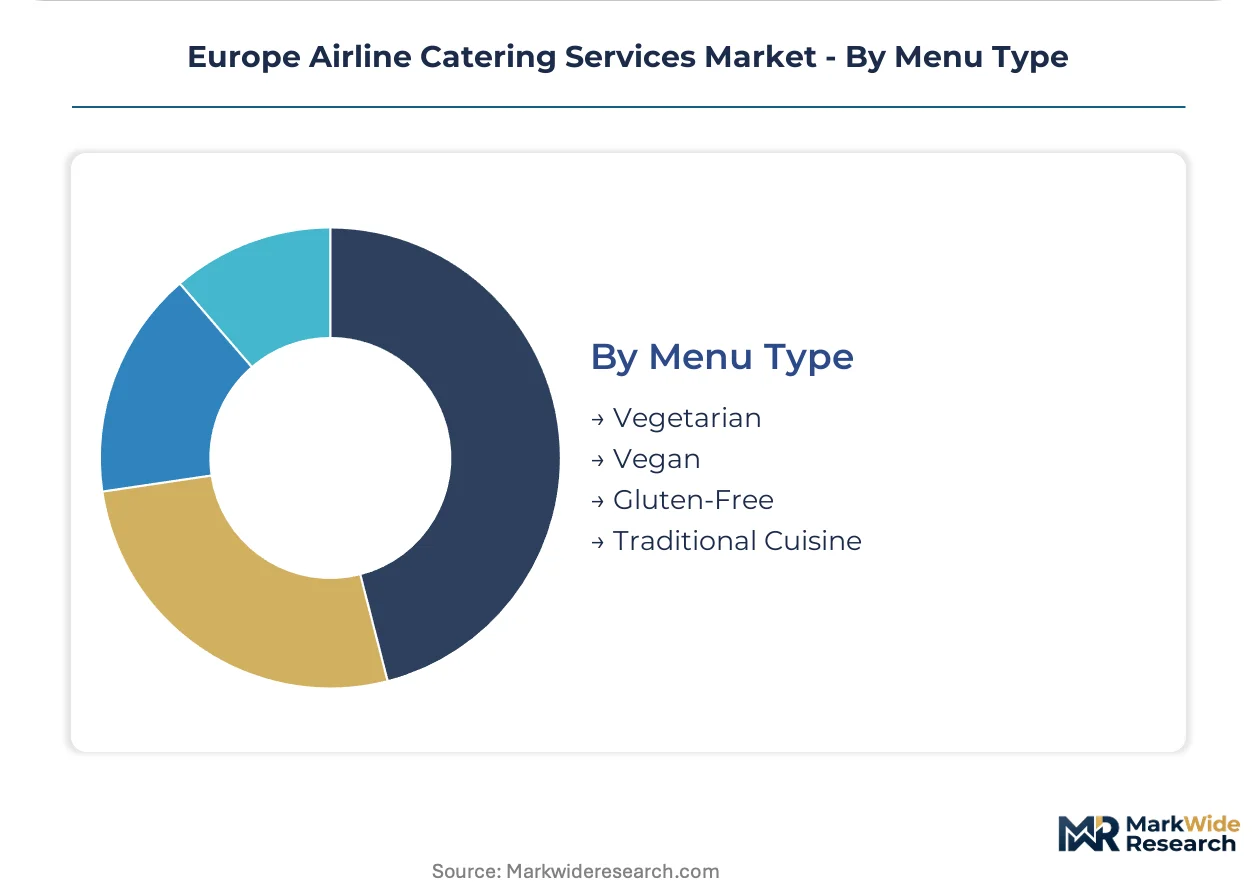
| Segmentation | Service Type: In-flight Meals, Beverages, Snack Boxes, Special Dietary Meals Client Type: Commercial Airlines, Private Jets, Cargo Airlines, Charter Services Delivery Mode: Direct Delivery, Pre-packaged, On-board Preparation, Catering Hubs Menu Type: Vegetarian, Vegan, Gluten-Free, Traditional Cuisine |
| Companies Covered | KLM Catering Services, Flying Food Group, Gategroup, Air Culinaire Worldwide, SATS Ltd, Newrest Group Services, The Emirates Group, Servair, DO & CO Aktiengesellschaft, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Airline Catering Services Market Trends and Innovations
Automation in meal assembly and regulatory pressure on packaging materials are converging to reshape production economics across Europe's airline catering value chain.
Robotic tray-setting systems are miniaturizing from centralized factory lines to modular cell configurations deployable at airport-adjacent facilities. LSG Sky Chefs and Newrest are piloting compact robotic arms for protein and starch portioning at Orly and Madrid-Barajas. This technology is miniaturizing the minimum viable production scale, enabling point-of-use kitchens that reduce transport distance and temperature excursion risk.
EASA's updated guidance on food allergen management and the EU's Green Deal aviation fuel mandates are tightening documentation requirements across the supply chain. Catering operators must now trace ingredient provenance through blockchain-enabled systems to satisfy both safety audits and sustainability reporting. Full-service carriers with premium cabin exposure face the steepest compliance cost escalation.
Airline procurement departments are unbundling galley equipment ownership from catering service contracts, shifting capital burden onto suppliers while retaining operational flexibility. Low-cost carriers in Spain and Italy pioneered this model; it now spreads to hybrid operators in Scandinavia and Eastern Europe. Suppliers with captive equipment leasing capabilities capture longer contract tenures and deeper route integration.
Europe Airline Catering Services Market Segmentation
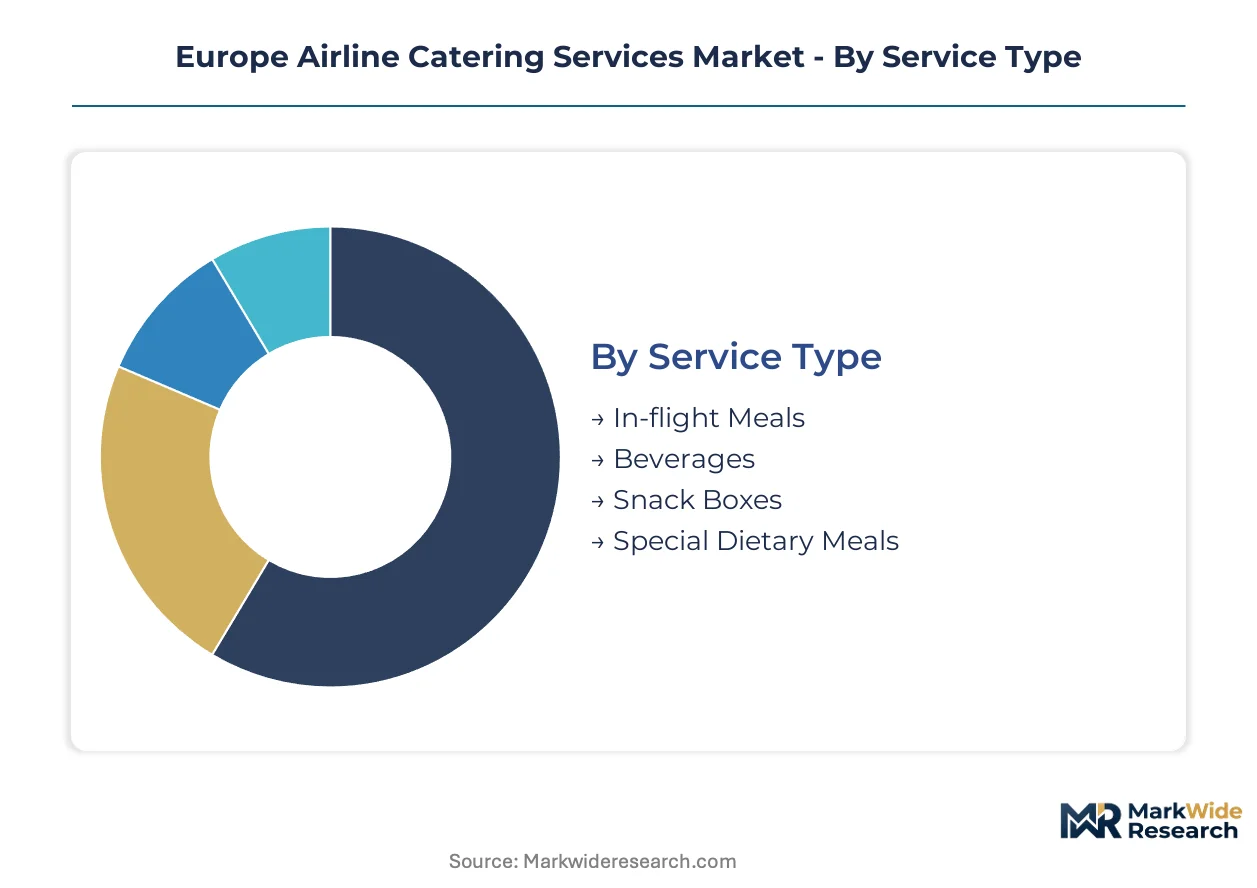
Segmentation in Europe's airline catering market reveals how procurement contracts bifurcate between cost-optimized bulk provisioning and premium culinary differentiation. Each dimension carries distinct compliance burdens and margin profiles that reshape supplier competitive positioning.
Service Type:
Substitution pressure from buy-on-board retail and airport lounge dining is compressing traditional meal service economics across all four segments.
- In-flight Meals:Full-tray assemblies with protein-starch-vegetable configurations blast-chilled to 4°C for long-haul provisioning. Germany and the United Kingdom concentrate demand as Lufthansa and British Airways maintain premium cabin commitments despite buy-on-board expansion in short-haul networks.
- Special Dietary Meals:Medical-restricted and religious-compliant preparations requiring segregated production lines and allergen documentation under EASA protocols. France and Switzerland drive procurement as full-service carriers compete on inclusive service standards.
- Beverages:Chilled juice, soft drink, and wine-spirit cartons loaded through galley lift systems.
- Snack Boxes:Pre-assembled dry goods and ambient-stable items for low-cost carrier retail programs.
In-flight meals anchor the volume base while special dietary meals gain share at the steepest rate.
Client Type:
Customer procurement sophistication varies sharply across cost discipline tiers, from yield-optimized commercial operators to experience-focused private aviation.
- Commercial Airlines:Full-service and low-cost carriers representing the procurement volume core with contract structures indexed to passenger load factors and route rotations. Hub concentration at Amsterdam Schiphol, Frankfurt, and London Heathrow creates geographic lock-in for incumbent suppliers.
- Private Jets:Fractional ownership and charter operators in Switzerland, Austria, and Monaco demanding bespoke culinary programs with 90-minute response windows. This segment commands unit pricing multiples above commercial contracts but requires distributed kitchen networks near executive airports.
- Cargo Airlines:Crew meal provisioning for freighter operations with standardized nutrition specifications and extended shelf-life requirements.
- Charter Services:Seasonal tour operators and sports team transport with volatile demand patterns and menu customization for group bookings.
Commercial airlines anchor the volume base while private jets expand most quickly.
Delivery Mode:
Cold-chain infrastructure investment requirements segment operators by capital intensity and hub proximity.
- Catering Hubs:Centralized production facilities with automated blast-chilling and temperature-controlled vehicle fleets serving multiple airlines from airport-adjacent commissaries. Zurich and Vienna host the most technologically advanced hub configurations with robotic tray assembly.
- Direct Delivery:Point-to-point transport from production kitchen to aircraft gate minimizing holding time and temperature excursion risk. Secondary airports in Spain and Italy increasingly demand this model as low-cost carriers bypass traditional hub structures.
- Pre-packaged:Ambient-stable and refrigerated items assembled off-airport for retail-style distribution.
- On-board Preparation:Fresh finishing and plating in aircraft galleys requiring crew training and equipment certification.
Catering hubs anchor the volume base while direct delivery climbs the fastest.
Menu Type:
Dietary restriction prevalence and sustainability positioning reshape ingredient sourcing and production line configuration.
- Traditional Cuisine:Country-specific preparations reflecting carrier origin and route destination profiles, requiring authentic ingredient sourcing through TRACES-documented supply chains. Italian and French carriers maintain the strongest commitments to origin-designated products.
- Vegan:Plant-based protein alternatives and dairy-egg exclusions with compostable serviceware alignment under EU Single-Use Plastics Directive mandates. Scandinavian carriers drive adoption as sustainability reporting requirements tighten.
- Vegetarian:Lacto-ovo preparations with cheese and egg components, historically the default special meal option.
- Gluten-Free:Celiac-safe preparations requiring segregated production environments and certified ingredient provenance.
Traditional cuisine anchors the volume base while vegan options gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Single-Use Plastics Directive compliance deadlines are accelerating infrastructure investments across national aviation hubs, with procurement volumes concentrating at airports with integrated cold-chain capabilities.
Germany
Lufthansa's premium cabin commitments at Frankfurt and Munich drive demand for blast-chilled meal assemblies with extended shelf stability. TRACES documentation requirements for animal-origin ingredients add transit friction to cross-border supply chains from eastern production facilities. DO & CO Aktiengesellschaft operates chef-staffed production facilities in Frankfurt, serving full-service carriers with segregated allergen lines.
United Kingdom
British Airways' hub operations at London Heathrow sustain high-volume procurement despite buy-on-board expansion across short-haul networks. EASA food safety audits enforce HACCP-aligned documentation systems that filter smaller commissary operators from supplier pools. Gategroup leverages centralized kitchen networks across London to sustain pan-European coverage with temperature-controlled vehicle fleets.
France
Air France's inclusive service standards concentrate special dietary meal demand in Paris, requiring segregated production lines for medical-restricted and religious-compliant preparations. EU Green Deal aviation fuel mandates create co-marketing opportunities with carriers pursuing scope-3 emission reductions. Newrest Group Services competes on cost discipline near Marseille with standardized meal kits for low-cost carrier retail programs.
Switzerland
Fractional jet ownership growth in Zurich and Geneva outpaces commercial airline catering demand expansion, with 90-minute response windows for bespoke culinary programs. Swissmedic oversight of food safety protocols elevates audit requirements for private aviation suppliers. Gategroup's Zurich hub hosts technologically advanced configurations with robotic tray assembly for full-service carrier networks.
Spain
Ryanair and Vueling buy-on-board rollouts at Barcelona and Madrid-Barajas generate incremental meal-kit demand at secondary airports bypassing traditional hub structures. Direct delivery models from production kitchen to aircraft gate minimize holding time and temperature excursion risk. LSG Sky Chefs pilots compact robotic arms for protein and starch portioning at Madrid-Barajas, miniaturizing minimum viable production scale.
Europe Airline Catering Services Market Competitive Landscape
Player mix skews toward consolidated multi-hub networks with dedicated compliance infrastructure, filtering smaller commissary operators unable to sustain ISO 22000 certification cycles. Three strategic archetypes dominate: premium culinary specialists with chef-staffed facilities, cost-disciplined scale operators with standardized meal-kit production, and private aviation corridor specialists with distributed kitchen networks. Competitive moves center on M&A to secure airport-adjacent real estate and strategic partnerships to embed galley equipment leasing within service contracts.
Within the premium culinary tier, DO & CO Aktiengesellschaft and Air Culinaire Worldwide exemplify chef-forward positioning through origin-designated ingredient sourcing and segregated allergen production lines. Gategroup and Newrest Group Services occupy the scale-driven end, with the former representing centralized hub networks across Amsterdam, Zurich, and London, and the latter anchoring cost-optimized production near Mediterranean secondary airports. KLM Catering Services and Flying Food Group sit within the full-service carrier supply base, their geographic naming reflecting hub-proximate operational footprints rather than portfolio diversification.
| Leading Market Players |
|---|
| KLM Catering Services |
| Flying Food Group |
| Gategroup |
| Air Culinaire Worldwide |
| SATS Ltd |
| Newrest Group Services |
| The Emirates Group |
| Servair |
| DO & CO Aktiengesellschaft |
| Others |
Pricing and Supply Chain Analysis
Blast-chilling automation investments at Zurich and Frankfurt hubs compress per-unit production costs while simultaneously elevating the capital threshold for market entry, concentrating procurement toward ISO 22000-certified operators with multi-site redundancy. EASA food safety audit cycles and EU Single-Use Plastics Directive compliance requirements further stratify the supply base, embedding quality-grade premiums into long-term airline contracts.
Pricing Analysis
Certification level creates the primary spread between premium culinary specialists and commodity meal-kit suppliers, with ISO 22000-aligned operators capturing pricing premiums from full-service carriers while cost-disciplined providers serve low-cost buy-on-board programs. Three-tier pricing structure across premium, standard, and economy levels reflects HACCP documentation depth, cold-chain infrastructure ownership, and galley equipment leasing bundling. Pricing pressure stems from wheat and poultry cost volatility indexed to quarterly contract adjustments, compressing margin predictability for fixed-price agreements. Low-cost carriers exhibit highest price sensitivity, while private aviation clients in Switzerland and Monaco accept substantial premiums for 90-minute bespoke response windows.
Supply Chain Analysis
Cross-border veterinary controls at the Brenner Pass and Channel Tunnel chokepoints inject documentation friction into animal-origin ingredient flows between Germany, France, and the United Kingdom. TRACES-certified supply chains draw from Dutch dairy cooperatives, Spanish poultry integrators, and Italian specialty ingredient distributors, with compostable serviceware sourcing increasingly localized to meet EU Single-Use Plastics Directive mandates. Single-source vulnerability concentrates in blast-chilled protein supply from centralized EU slaughterhouses. Distribution runs through temperature-controlled vehicle fleets operating from airport-adjacent commissaries, with hub-and-spoke logistics dominating Frankfurt, Amsterdam Schiphol, and London Heathrow procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Lufthansa, British Airways, and Air France consolidate procurement through multi-year framework agreements, squeezing mid-tier commissary operators without pan-European coverage.
For Market Incumbents: Compound defensive positioning through M&A targeting airport-adjacent real estate in secondary Spanish and Italian hubs, while embedding galley equipment leasing capabilities within service contracts to deepen route integration and extend contract tenures against low-cost carrier procurement consolidation. For New Entrants and Emerging Players: ISO 22000 fast-track certification enables rapid supplier qualification for private aviation corridors in Switzerland, Austria, and Monaco, where fractional jet ownership growth outpaces commercial airline catering expansion and bespoke culinary programs command unit pricing multiples above standardized meal-kit production. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation-enabled scale operators with robotic tray-assembly deployment at Madrid-Barajas and Orly, as blast-chilling automation reduces minimum viable production scale and enables point-of-use kitchen configurations. Target acquisition archetype: multi-hub networks with dedicated compliance infrastructure and captive equipment leasing capabilities. Monitor EASA sustainable aviation fuel alignment mandates as inflection indicator for co-marketing opportunity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Tray-Assembly Deployment | LSG Sky Chefs pilots compact systems at Madrid-Barajas, miniaturizing viable production scale for secondary airports. |
| Compostable Serviceware Transition | EU Single-Use Plastics Directive compliance creates first-mover advantages for certified biodegradable supply chains. |
| Galley Equipment Leasing Integration | Suppliers embedding capital burden within service contracts capture longer tenures and deeper route integration. |
| Private Aviation Corridor Expansion | Fractional jet ownership growth in Zurich and Geneva demands distributed kitchen networks with 90-minute response windows. |
| Blockchain Provenance Documentation | EASA allergen management and EU Green Deal mandates require traceable ingredient sourcing for audit readiness. |
Research Methodology
Initial hypotheses were tested against primary input from airline procurement directors, commissary operations managers, cold-chain logistics coordinators, and EASA food safety auditors, then refined through secondary validation against EU regulatory filings, customs trade data for animal-origin ingredients, airport authority procurement disclosures, and airline sustainability reports. Bottom-up triangulation across production facility capacity assessments and top-down demand modeling from passenger load factor projections established volume and value estimates.
Variance-decomposition analysis isolated growth contributions from low-cost carrier expansion, private aviation corridor development, and regulatory compliance cost pass-through across service type, client type, delivery mode, and menu type segmentation dimensions. CAGRs were derived from log-linear trend fitting applied to hub airport procurement volumes, with forecast inputs incorporating blast-chilling automation penetration rates and EU Single-Use Plastics Directive implementation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained hub airport slot allocation stability and EASA food safety protocol continuity; material deviation in aviation fuel mandate stringency or cross-border veterinary control enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal aviation fuel alignment requirements and airline scope-3 emission reduction commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Hyperlocal Grocery Delivery Market
Food Service
North America Food Service Disposable Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
Chile Food Delivery Market
Food Service
Flat Top Grills Market
Food Service
India Online Grocery Market
Food Service
Stirrers Market
Food Service
United States Foodservice Market
Food Service
Germany Foodservice Market
Food Service
Mexico Foodservice Market
Food Service
Aquarium Protein Skimmers Market
Food Service
South Korea Foodservice Market
Food Service
United Kingdom Foodservice Market
Food Service
United Arab Emirates Foodservice Market
Food Service
China Online Food Delivery Market
Food Service
United States Food Truck Market