
 Gas Fryers Market | 2026-2036
Gas Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Fryers Market Foresight
ENERGY STAR certification is repositioning the cost-of-entry calculus for gas fryer manufacturers by mandating minimum cooking energy efficiency and idle energy rates. Frymaster leverages its vertical integration into burner system design to sustain compliance leadership across North American commercial kitchens. Henny Penny anchors its competitive stance through R&D intensity in oil management systems, while Pitco dominates the floor-standing segment with manufacturing scale advantages.
Gas fryers are pressurized or atmospheric vessels that use natural gas or propane combustion to heat cooking oil between 300°F and 375°F for submerged food preparation, with fry pot capacities ranging from 15 to 150 pounds and recovery times measured in seconds per batch. Floor-standing gas fryers occupy the largest installed base across full-service restaurants due to throughput requirements and ventilation integration needs. Quick service restaurants represent the fastest-growing application segment as chains retrofit kitchens with high-capacity models to support expanded fried menu offerings.
The U.S. EPA administers ENERGY STAR specifications that dictate thermal efficiency benchmarks, while OSHA governs ventilation and combustion safety in commercial kitchen environments. The EU F-Gas Regulation indirectly shapes gas fryer demand in Europe by restricting hydrofluorocarbon use in competing electric refrigeration-based systems. Stakeholders must monitor evolving municipal gas hookup moratoriums and building electrification codes that threaten to displace gas-fired cooking infrastructure in key urban markets.
Market Dynamics
Building electrification codes and municipal gas hookup moratoriums are creating structural pressure on gas fryer deployment timelines across urban foodservice corridors. Manufacturers must now engineer for dual-fuel compatibility and accelerated replacement cycles.
Growth Catalysts
- Quick Service Restaurant Expansion:Chains are retrofitting kitchens with high-capacity floor-standing models to support expanded fried menu portfolios. Texas and California foodservice corridors concentrate new equipment procurement.
- ENERGY STAR Thermal Efficiency Thresholds:The U.S. EPA's tightened certification standards are pulling forward replacement demand among compliance-sensitive operators. Certified units command specification preference in institutional procurement.
- Oil Management Automation:Automated filtration and temperature control systems are reducing labor input and extending oil life cycles. Full-service restaurants prioritize these features for operational cost containment.
Market Restraints
- Natural Gas Infrastructure Access:Municipal gas hookup moratoriums in California, New York, and Washington are blocking new gas fryer installations in ground-up construction. Electric alternatives capture these displaced opportunities.
- Stainless Steel Input Volatility:Fry pot and cabinet fabrication depends on nickel-alloy steel pricing, which fluctuates with mining output and trade policy. Cost pass-through encounters resistance from price-sensitive independent operators.
- Ventilation System Capital Burden:Gas combustion requires hood and fire suppression integration that adds fifteen to twenty-five thousand dollars per installation. This capex barrier slows adoption in ghost kitchen and food hall formats.
Strategic Opportunities
- Propane-Compatible Portable Units:Food truck and outdoor event catering segments lack grid-connected infrastructure. Manufacturers developing high-BTU propane variants access this underpenetrated mobile foodservice channel.
- Rebuild-versus-Replace Programs:Component-level retrofit kits for burner systems and controls extend equipment life at forty percent of replacement cost. Independent operators in secondary markets respond to this value proposition.
- Utility Rebate Stacking:Gas utilities in Ohio, Pennsylvania, and Georgia offer equipment incentives for high-efficiency models. Manufacturers partnering on rebate administration accelerate sales cycle velocity.
Industry Challenges
- Certified Technician Scarcity:Gas line connection and combustion adjustment require licensed plumbers and HVAC technicians. Labor shortages in these trades extend installation timelines and elevate service costs.
- Dual-Fuel Engineering Complexity:Developing units that switch between gas and electric operation without performance degradation demands redundant control systems. R&D timelines stretch eighteen to twenty-four months for validated designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Fryers Market |
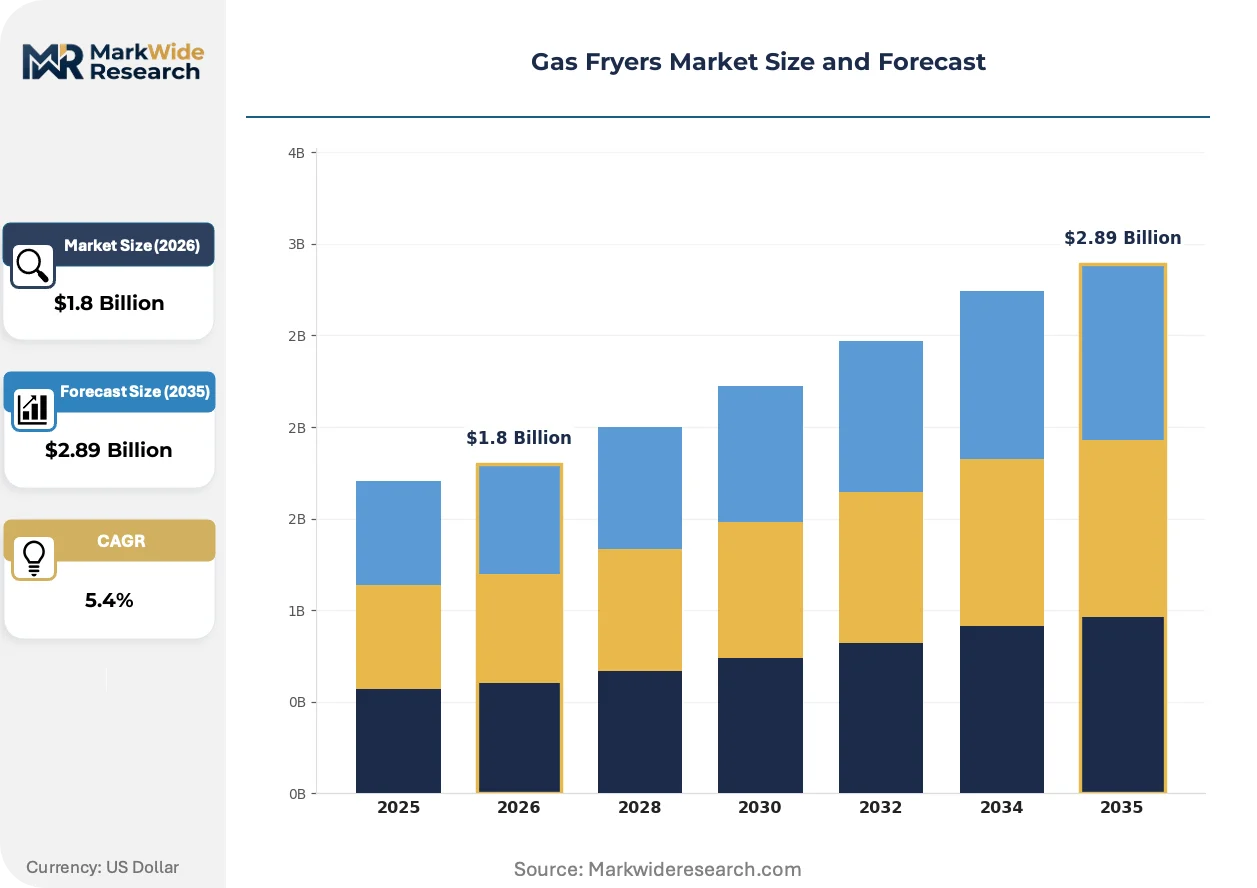
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Gas Fryers, Floor-Standing Gas Fryers, High-Capacity Gas Fryers, Commercial Gas Fryers Technology: Direct Gas Heating, Indirect Gas Heating, Infrared Gas Heating, Convection Gas Heating Application: Quick Service Restaurants, Cafeterias, Food Trucks, Catering Services, Street Food Vendors End User: Restaurants, Hospitality Chains, Institutional Kitchens, Food Processing Units |
| Companies Covered | Frymaster, Henny Penny, Pitco, Vulcan, Middleby Corporation, Ali Group, Avantco Equipment, ITW, Electrolux Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Fryers Market Shifts & Advancements
Automation in oil management and burner control is compressing operating cost structures while regulatory pressure on combustion emissions intensifies equipment specification requirements. Three developments are restructuring competitive positioning.
Intelligent fryer control systems incorporating machine learning for temperature prediction and basket timing are expanding into high-volume quick service operations. Chains with centralized kitchen engineering teams deploy these systems to standardize product quality across franchise locations. The technology is expanding into mid-scale regional chains that previously lacked capital for automation infrastructure.
The U.S. EPA's ENERGY STAR Version 3.0 specifications for commercial fryers mandate minimum cooking energy efficiency of fifty percent and idle energy rates below nine thousand BTU per hour. Equipment failing these thresholds loses specification eligibility in federal foodservice contracts and utility rebate programs. Manufacturers with captive burner design capabilities are responding fastest to the revised thermal performance requirements.
Equipment-as-a-service financing models are displacing outright purchase in independent restaurant segments. Leasing providers bundle maintenance, oil management supplies, and compliance certification into monthly payments. This arrangement concentrates most visibly in Texas and Florida markets where independent operator density supports portfolio risk pooling.
Gas Fryers Market Segmentation
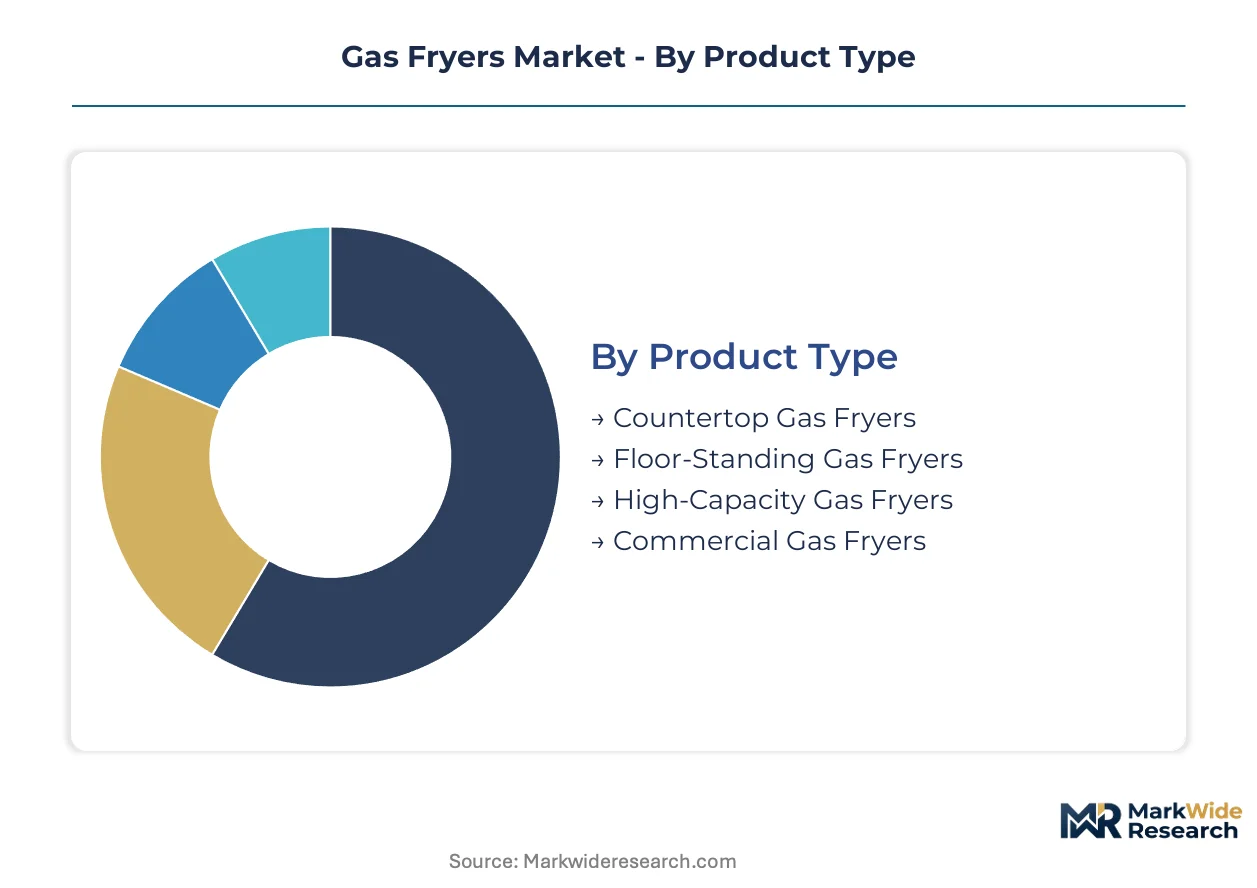
Gas fryer procurement patterns diverge sharply across equipment formats, heating architectures, and operational environments. Each segmentation dimension reveals distinct margin structures, replacement cadences, and regulatory exposure profiles that reshape vendor go-to-market priorities.
Product Type:
Supply concentration in fry pot fabrication and burner system manufacturing favors scaled producers of high-volume floor-standing configurations.
- Floor-Standing Gas Fryers:These units feature 40-150 pound oil capacities and integrated filtration systems designed for continuous high-throughput operations. Full-service restaurants in Texas and California foodservice corridors specify these models for ventilation integration and batch recovery requirements. ENERGY STAR thermal efficiency mandates pull replacement demand among compliance-sensitive operators.
- High-Capacity Gas Fryers:Engineered with multiple fry pots and 100,000+ BTU burner arrays to sustain peak-hour output without temperature degradation. Quick service restaurant chains retrofit kitchens with these models to support expanded fried menu portfolios. Recovery time specifications measured in seconds per batch determine competitive positioning.
- Countertop Gas Fryers:Compact 15-30 pound capacity units targeting ghost kitchens and food hall formats with constrained footprints.
- Commercial Gas Fryers:General-purpose category spanning institutional procurement specifications and mid-scale independent operators.
Today's leader: Floor-Standing Gas Fryers. Tomorrow's challenger: High-Capacity Gas Fryers.
Technology:
Cost tier differentiation separates premium infrared and convection architectures from baseline direct heating systems.
- Direct Gas Heating:Burner elements transfer combustion energy directly to the fry pot bottom through atmospheric or power burner configurations. This architecture dominates installed bases across price-sensitive independent restaurants and legacy institutional kitchens. U.S. EPA ENERGY STAR Version 3.0 efficiency thresholds are eliminating non-compliant direct heating designs from federal procurement eligibility.
- Infrared Gas Heating:Ceramic radiant panels distribute heat across the fry pot surface with reduced thermal lag and improved temperature uniformity. Quick service restaurant chains with centralized engineering teams specify infrared systems for product consistency across franchise locations. Capital cost premiums of 25-40 percent over direct heating constrain penetration in secondary markets.
- Indirect Gas Heating:Heat exchanger configurations isolate combustion gases from cooking oil, addressing ventilation and flavor contamination concerns in enclosed kitchen environments.
- Convection Gas Heating:Forced-air circulation systems accelerate heat transfer rates and reduce recovery times for high-volume batch operations.
Direct Gas Heating retains volume leadership. Infrared Gas Heating climbs the fastest on efficiency compliance pull-through.
Application:
Volume concentration in quick service restaurant chains creates procurement scale advantages that reshape vendor pricing structures.
- Quick Service Restaurants:High-frequency frying operations with standardized menu specifications and centralized equipment procurement protocols. Texas and California foodservice corridors concentrate new equipment deployment as chains expand fried item portfolios. Automated oil management and intelligent temperature control systems reduce labor input and extend oil life cycles.
- Catering Services:Event-based demand patterns requiring portable propane-compatible units for outdoor and temporary kitchen configurations. Seasonal revenue volatility and asset utilization constraints favor equipment-as-a-service financing models.
- Food Trucks:Mobile operations lacking grid-connected infrastructure, driving specification of high-BTU propane variants with compact footprints.
- Cafeterias:Institutional procurement governed by federal ENERGY STAR specifications and utility rebate program eligibility.
- Street Food Vendors:Informal sector operators with extreme price sensitivity and minimal compliance exposure.
Quick Service Restaurants anchor current procurement volumes. Food Trucks represent the steepest expansion trajectory on mobile foodservice growth.
End User:
Customer type stratification separates compliance-intensive institutional buyers from margin-pressured independent operators.
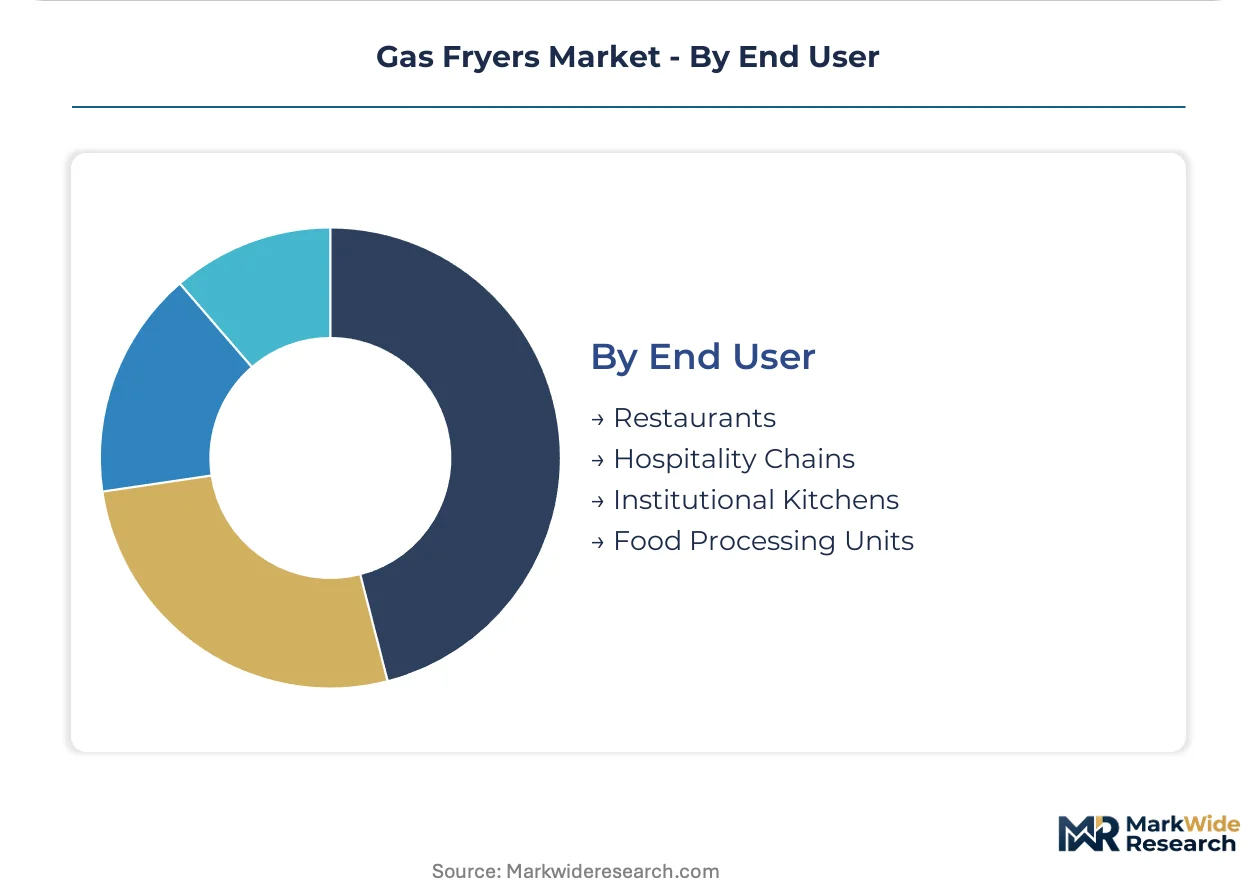
- Restaurants:Spanning full-service independents through national chain affiliates with divergent capital allocation and replacement cadences. ENERGY STAR certification commands specification preference among compliance-sensitive operators. Oil management automation features prioritize operational cost containment.
- Institutional Kitchens:Federal, state, and municipal foodservice operations bound by procurement regulations mandating certified equipment. U.S. EPA specifications and utility rebate program eligibility determine vendor shortlists.
- Hospitality Chains:Hotel and resort operators integrating fryers into centralized kitchen facilities with ventilation and fire suppression system integration requirements.
- Food Processing Units:Industrial-scale frying operations with continuous production requirements and specialized equipment configurations.
Restaurants dominate installed base economics. Institutional Kitchens drive specification standardization through regulatory procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial gas fryer industry traces its modern scaling to post-war American diner culture and the subsequent franchising wave of quick service restaurants. Equipment standardization and thermal efficiency engineering concentrated initially in the United States before diffusing to European and Asian foodservice markets. Today's procurement patterns still reflect this lineage, with North American specification standards influencing global certification frameworks.
United States
Texas and California foodservice corridors drive replacement cycles as chains expand fried menu portfolios. The U.S. EPA's ENERGY STAR Version 3.0 specifications mandate minimum cooking energy efficiency thresholds that eliminate non-compliant equipment from federal procurement. Houston and Dallas-Fort Worth metropolitan clusters concentrate high-capacity floor-standing installations for ventilation-integrated kitchen footprints.
Germany
Commercial kitchen operators prioritize thermal efficiency compliance amid rising natural gas input costs and carbon pricing mechanisms. The EU F-Gas Regulation indirectly shapes equipment selection by restricting hydrofluorocarbon alternatives in competing electric systems. Bavaria and North Rhine-Westphalia host dense concentrations of institutional foodservice procurement governed by federal efficiency standards.
China
Quick service restaurant chains retrofit central kitchens with automated oil management systems to reduce labor input and standardize product quality. The country's national standards body issues thermal efficiency benchmarks for commercial cooking equipment that align with international certification frameworks. Yangtze River Delta manufacturing clusters produce burner system components for both domestic installation and export assembly.
Japan
Compact kitchen footprints in urban food halls and ghost kitchen formats favor countertop and high-efficiency floor-standing configurations. METI efficiency labeling programs for commercial cooking equipment influence specification preferences among chain operators. Osaka and Nagoya metropolitan areas concentrate equipment procurement for integrated hospitality and foodservice operations.
United Kingdom
Institutional foodservice procurement in schools and hospitals mandates certified equipment eligibility for public contracts. Building electrification codes in Greater London and select municipal jurisdictions create displacement pressure on new gas fryer installations. The Midlands manufacturing corridor supplies burner system components to domestic fabricators and European assembly operations.
Gas Fryers Market Competitive Landscape
The competitive structure tilts toward integrated specialists with captive burner design capabilities and scaled floor-standing production. Market concentration is moderate, with tiered differentiation between premium efficiency-compliant manufacturers and price-positioned independents. Three archetypes dominate: vertically integrated thermal system specialists, diversified foodservice equipment conglomerates, and regional fabricators serving price-sensitive independents. Strategic moves center on R&D acceleration for dual-fuel compatibility and equipment-as-a-service financing model deployment.
Among North American thermal equipment specialists, Frymaster, Henny Penny, and Pitco occupy positions that exemplify the integrated specialist archetype. These companies represent varying approaches to burner system design and oil management automation. Their positioning reflects the competitive premium placed on ENERGY STAR compliance leadership and ventilation integration engineering. European-based competitors including Electrolux Professional and Ali Group sit within diversified conglomerate structures that leverage cross-category procurement relationships. The vendor landscape also includes regional fabricators from Chinese manufacturing clusters that serve secondary markets through cost-focused positioning.
| Leading Market Players |
|---|
| Frymaster |
| Henny Penny |
| Pitco |
| Vulcan |
| Middleby Corporation |
| Ali Group |
| Avantco Equipment |
| ITW |
| Electrolux Professional |
| Others |
Supply & Pricing Matrix
ENERGY STAR Version 3.0 compliance gates both qualified supply access and premium-tier pricing power, as manufacturers lacking captive burner design capabilities forfeit federal procurement eligibility and utility rebate program participation. Stainless steel input volatility and certified technician scarcity compress margins across non-compliant tiers while concentrating pricing power among integrated thermal system specialists serving institutional buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by ENERGY STAR certification grade and oil management automation depth. Price differentiation stems from thermal efficiency thresholds and after-sales service bundling, with certified units commanding specification preference in federal contracts. Cost compression in economy tiers intensifies because nickel-alloy steel pricing fluctuates with mining output. Independent operators in secondary markets exhibit highest price sensitivity, while institutional procurement teams prioritize compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale quick service restaurant chain demand, while distributor networks serve fragmented independent operators. Manufacturing concentrates in the United States, China, and Germany, with burner system component production anchored in Yangtze River Delta and Midlands corridors. Supply chains draw from nickel-alloy steel, ceramic radiant panels, and intelligent control module inputs. Single-source vulnerability in specialized combustion engineering talent creates procurement risk. Distribution runs through foodservice equipment dealers and direct institutional sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas fryers market reads as a late-cycle quality story, with procurement gravity shifting toward ENERGY STAR-certified premium specifications that disqualify legacy equipment from federal and utility incentive programs.
For Market Incumbents: Anchor compliance leadership through captive burner system R&D and accelerated dual-fuel engineering timelines. Defensive consolidation should prioritize Ohio, Pennsylvania, and Georgia utility rebate program partnerships to lock in specification preference. Electrification codes in California and New York threaten installed base retention, demanding proactive equipment-as-a-service financing deployment to extend customer relationships. For New Entrants and Emerging Players: ENERGY STAR Version 3.0 in the United States opens a window for specification-compliant entrants targeting federal procurement and institutional kitchen segments bypassed by legacy manufacturers. White-space concentration appears in propane-compatible portable units for food trucks and outdoor catering, plus rebuild-versus-replace retrofit kits for independent operators. A component-level aftermarket value proposition unlocks secondary market penetration without full manufacturing scale requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with burner system design capabilities because certified technician scarcity and dual-fuel R&D complexity create defensive moats against pure price competition. Acquisition targets should demonstrate ENERGY STAR compliance validation and established utility rebate administration relationships. The signal to watch is municipal gas hookup moratorium expansion velocity, which accelerates replacement cycle timing and dual-fuel premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engineering Acceleration | California and New York electrification codes force gas-electric compatibility investment to preserve addressable market. |
| Equipment-as-a-Service Financing | Texas and Florida independent operator density supports portfolio risk pooling for bundled maintenance and compliance certification. |
| Utility Rebate Program Partnership | Ohio, Pennsylvania, and Georgia gas utility incentives accelerate sales cycle velocity for high-efficiency models. |
| Propane-Compatible Product Line Extension | Food truck and outdoor catering segments lack grid infrastructure, creating underpenetrated mobile foodservice channel access. |
| Rebuild-versus-Replace Program Launch | Component-level retrofit kits at forty percent replacement cost unlock independent operator secondary market value capture. |
Research Methodology
Bottom-up restaurant and institutional kitchen modeling reconciled against top-down burner system and fry pot manufacturing tracking forms the analytical core of this study. Primary interviews with commercial kitchen engineering directors, foodservice equipment procurement managers, HVAC technician trade association leaders, and utility rebate program administrators combined with secondary validation from EPA ENERGY STAR certification databases, OSHA ventilation safety filings, and foodservice industry trade publications. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices segment volume and value projections across product type, heating technology, application, and end user dimensions throughout the forecast period. CAGRs derive from equipment replacement cadence modeling, regulatory compliance deadline impacts, and fried menu portfolio expansion rates in quick service restaurant chains. Industry-specific forecast inputs include ENERGY STAR Version 3.0 adoption curves and municipal gas hookup moratorium rollout timelines.
Revisions become necessary when building electrification code adoption accelerates beyond modeled trajectories or when stainless steel input volatility disrupts manufacturing cost structures. Forecasts reflect documented assumptions regarding technician labor availability and utility incentive program continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
A La Carte Market
Food Service
Food Trucks Market
Food Service
Plates Market
Food Service
Africa Foodservice Market
Food Service
Global Digital Food Delivery Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
United States Foodservice Market
Food Service
Takeout Dinner Market
Food Service
Qatar Food Service Market
Food Service
Italy Foodservice Market
Food Service
Commercial Ice Dispenser Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Europe Online Grocery Market
Food Service
Commercial Air Fryer Market
Food Service
Clear Ice Maker Market