
 Hospital Food Services Market | 2026-2036
Hospital Food Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Food Services Market Analytics
Acute care hospital reliance on outsourced foodservice management is hardening as health systems consolidate and de-emphasize self-operated kitchens. Sodexo leverages its global healthcare infrastructure to secure multi-hospital contracts across integrated delivery networks. Compass Group plc anchors its position through technology-enabled meal tracking systems that align with patient safety protocols. Aramark competes by specializing in retail dining environments within hospital campuses, capturing staff and visitor spend alongside patient meal programs.
Hospital food services encompass the procurement, preparation, distribution, and nutritional management of meals within acute care, long-term care, and specialty hospital settings, requiring compliance with therapeutic diet specifications, allergen controls, and temperature safety parameters from kitchen to bedside. The primary purpose is to support clinical outcomes through medically appropriate nutrition while generating auxiliary revenue from retail food operations. Meal Type segmentation shows gluten-free and organic categories expanding fastest as patient preference data and clinical allergy protocols reshape menu planning. Delivery Mode tilts toward room service models as hospitals seek to reduce food waste and improve patient satisfaction scores. End User demand among staff and visitors creates margin pools that subsidize regulated patient meal programs with constrained reimbursement.
FDA dietary guideline enforcement and CMS Conditions of Participation for hospital nutrition care shape procurement standards and vendor qualification requirements across the United States. Joint Commission accreditation criteria further tighten food safety auditing, compelling contractors to maintain HACCP-certified production facilities and documented cold-chain integrity. OSHA workplace safety rules govern commercial kitchen operations within hospital environments, adding compliance cost layers that favor large-scale contractors over regional competitors. Stakeholders must monitor how Medicare reimbursement shifts toward value-based care models reshape hospital willingness to invest in premium foodservice infrastructure versus cost-minimization contracting.
Market Dynamics
Health system consolidation is compressing vendor rosters as integrated delivery networks demand enterprise-scale foodservice contracts with unified technology platforms and centralized nutritional databases across multiple hospital sites.
Growth Catalysts
- CMS Conditions of Participation:The United States Medicare reimbursement rules now mandate documented nutritional screening within 24 hours of admission, forcing hospitals to upgrade meal tracking infrastructure and outsource to qualified contractors.
- Gluten-free menu expansion:Celiac disease diagnosis rates and patient allergy protocols are reshaping therapeutic diet specifications, requiring specialized procurement and preparation workflows that favor large-scale operators.
- Room service delivery models:Acute care hospitals are abandoning tray-line systems for on-demand meal ordering to cut food waste and improve satisfaction metrics tied to value-based reimbursement.
Market Restraints
- Labor cost escalation:Commercial kitchen wages in urban hospital markets are rising faster than reimbursement rates for patient meals, squeezing contractor margins on regulated services.
- Supply concentration in protein sourcing:Consolidated meat and dairy suppliers in the Midwestern United States create vulnerability to price volatility and contamination recalls affecting nationwide hospital networks.
- Cold-chain integrity requirements:Joint Commission HACCP auditing demands continuous temperature monitoring from production through bedside delivery, adding capital and compliance burdens that disadvantage smaller regional competitors.
Strategic Opportunities
- Retail dining capture:Hospital campuses in the United States are expanding grab-and-go markets and coffee kiosks to monetize staff and visitor traffic with higher-margin offerings subsidizing patient meal programs.
- Clinical nutrition integration:Electronic health record connectivity between dietary departments and physician order entry systems creates openings for contractors to embed registered dietitians into care teams.
- Organic ingredient sourcing:USDA organic certification is becoming a differentiator in competitive bidding as hospital marketing departments emphasize wellness positioning to attract commercially insured patients.
Industry Challenges
- Registered dietitian shortages:Hospital foodservice operations struggle to hire clinical nutrition staff qualified for therapeutic diet verification and physician collaboration under tightened CMS protocols.
- Legacy kitchen infrastructure:Aging steam table systems and tray assembly lines in older hospital buildings require costly retrofitting to accommodate cook-chill production and room service distribution models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Food Services Market |
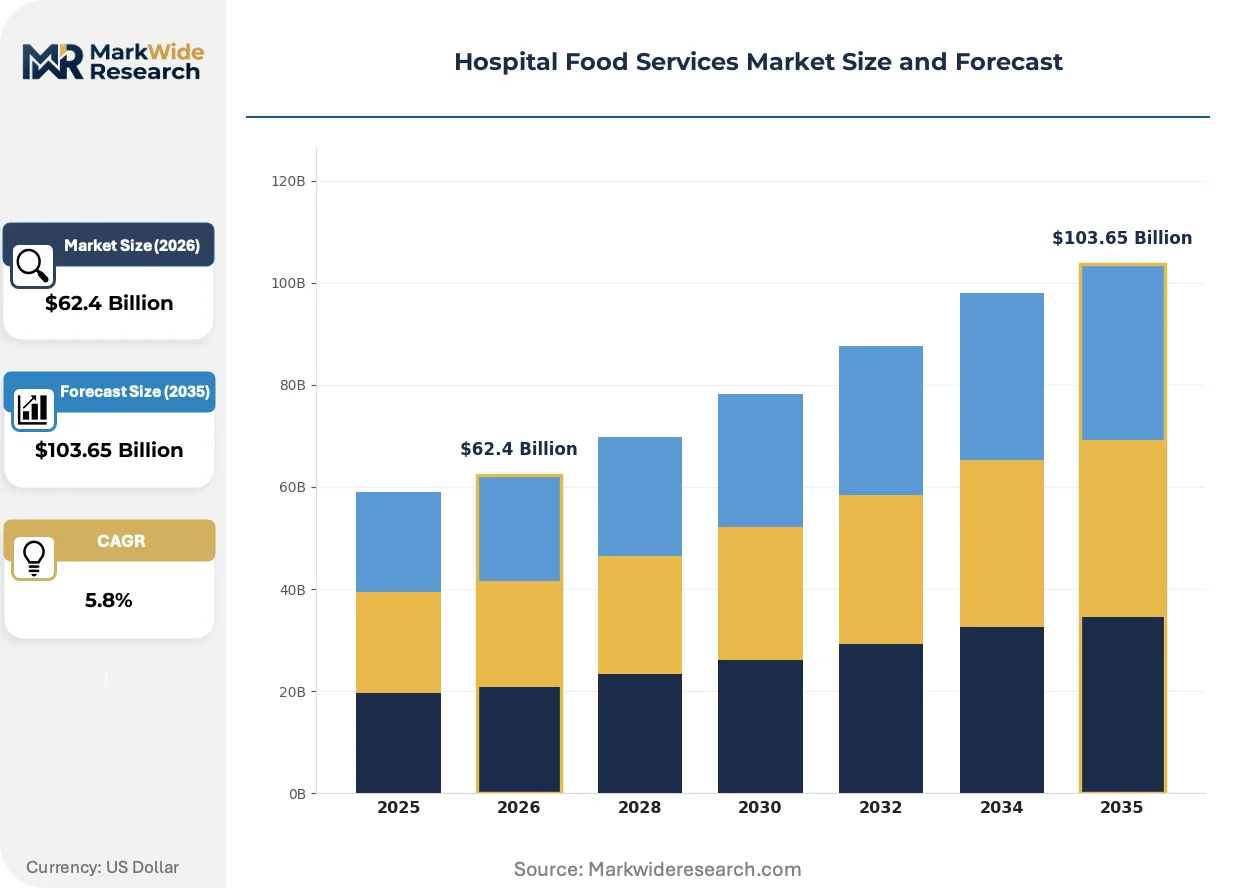
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Distribution, Nutritional Counseling, Dietary Management, Catering End User: Patients, Staff, Visitors, Caregivers Delivery Mode: Inpatient, Outpatient, Room Service, Cafeteria Meal Type: Organic, Vegetarian, Gluten-Free, Standard |
| Companies Covered | Compass Group plc, Sodexo, Aramark, Elior Group, Healthcare Services Group, Inc., ISS World, Metz Culinary Management, AVI Foodsystems, Inc., Whitsons Culinary Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Food Services Market Evolving Landscape
Digital meal ordering platforms and automated inventory systems are transforming how hospitals manage patient nutrition, replacing paper-based processes with real-time data integration.
Cloud-based foodservice management software is modularizing kitchen operations across multi-site health systems. Acute care networks in Texas and Florida are deploying these platforms to standardize recipes, allergens, and nutritional data across dozens of hospitals. The technology is modularizing procurement decisions, allowing corporate dietitians to adjust menus centrally while maintaining local regulatory compliance.
FDA enforcement of Food Safety Modernization Act traceability rules is compelling contractors to implement blockchain-enabled supply chain tracking. Large foodservice operators must now document ingredient provenance within seconds of a contamination event. Hospital systems in California and New York are responding by requiring blockchain-ready vendors in competitive tenders.
Patient self-directed meal ordering through bedside tablets and mobile applications is displacing traditional call-center models. Staff and visitor segments are driving adoption of retail-style payment systems separate from patient meal accounts. This shift is most visible in academic medical centers where technology budgets and patient demographics align with consumer expectations.
Hospital Food Services Market Segmentation
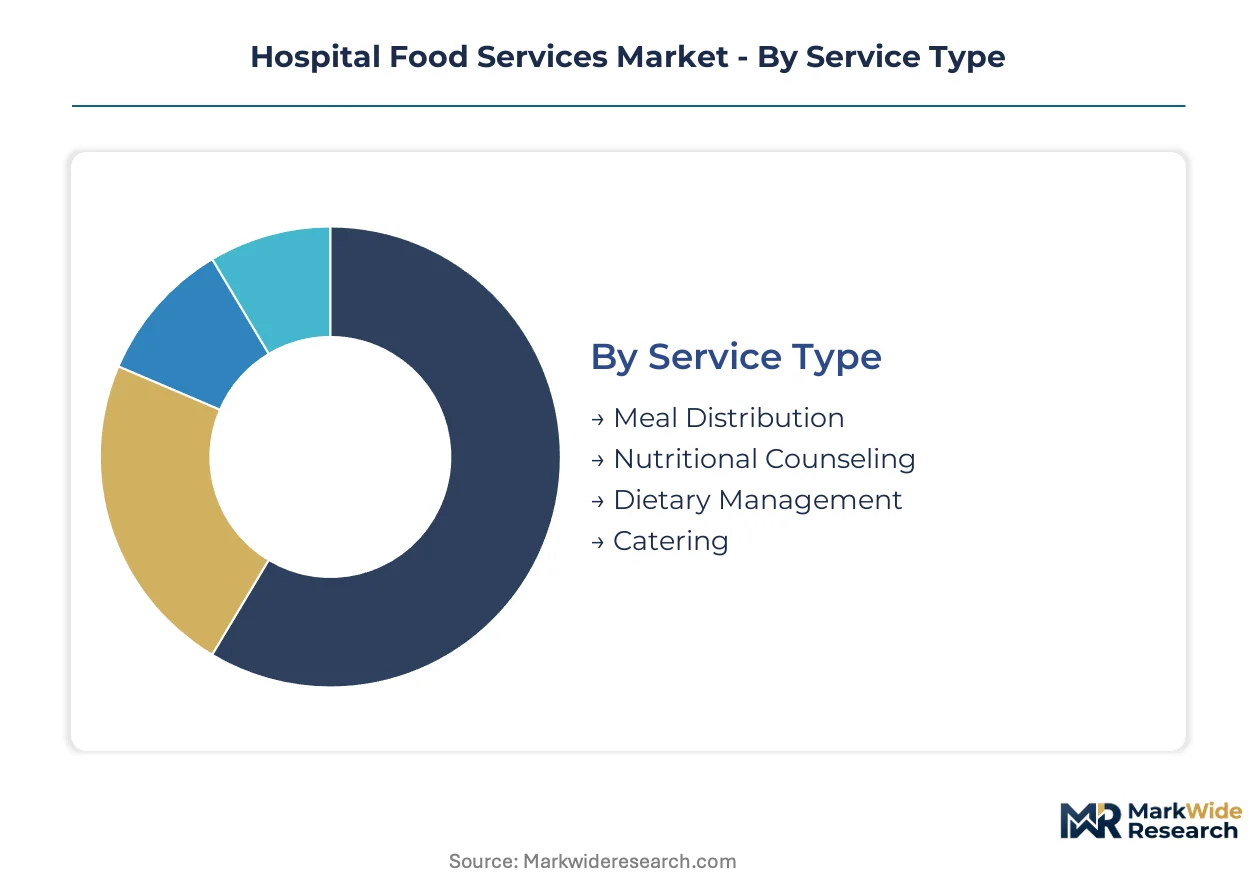
Hospital food service segmentation reflects divergent operational requirements across clinical, retail, and therapeutic contexts. Procurement specifications vary sharply between regulated patient meals and discretionary retail offerings. Contractors must engineer separate workflows for each segment while maintaining unified compliance frameworks.
Service Type:
Technology integration distinguishes high-touch clinical services from commoditized distribution functions.
- Meal Distribution:Automated tray tracking systems with barcode verification ensure temperature integrity from kitchen to bedside. Demand concentrates in acute care networks across the United States where Joint Commission auditing mandates documented cold-chain compliance. Labor shortages and wage escalation in urban markets pressure contractors to deploy robotics for final-mile delivery.
- Nutritional Counseling:Registered dietitians embedded in care teams conduct therapeutic diet assessments and physician collaboration under CMS Conditions of Participation. Deployment concentrates in academic medical centers and integrated delivery networks seeking value-based reimbursement advantages through reduced readmission rates.
- Dietary Management:Centralized menu planning platforms standardize allergen controls and therapeutic specifications across multi-site operations.
- Catering:Event and conference services generate ancillary revenue from medical education programs and administrative functions.
Mature deployment sits with Meal Distribution. Newer deployment is concentrated in Nutritional Counseling.
End User:
Revenue margin structure separates regulated patient populations from discretionary spenders.
- Patients:Therapeutic diets with documented nutritional screening within 24 hours of admission per CMS rules. Reimbursement constraints limit margins, requiring cross-subsidy from retail operations.
- Staff:Grab-and-go markets and coffee kiosks capture recurring daily traffic with premium pricing power. Demand concentrates in tertiary hospitals with large employee bases where 24/7 operations sustain volume throughput.
- Visitors:Retail dining environments monetize family presence during extended patient stays.
- Caregivers:Meal programs for home health aides and informal caregivers extend service reach beyond hospital walls.
Volume leadership belongs to Patients. Margin expansion concentrates in Staff.
Delivery Mode:
Capital intensity and waste reduction potential differentiate legacy systems from on-demand models.
- Room Service:Patient-directed meal ordering through bedside tablets eliminates tray-line waste and improves satisfaction scores tied to value-based reimbursement. Deployment accelerates in Texas and Florida health systems retrofitting aging infrastructure for cook-chill production.
- Inpatient:Traditional scheduled tray delivery maintains dominance in long-term care and specialty hospitals with limited capital budgets.
- Outpatient:Ambulatory surgery centers and clinic-based programs require rapid turnaround logistics.
- Cafeteria:Self-service retail environments capture staff and visitor spend with higher throughput efficiency.
Legacy dominance persists in Inpatient. Investment flow concentrates in Room Service.
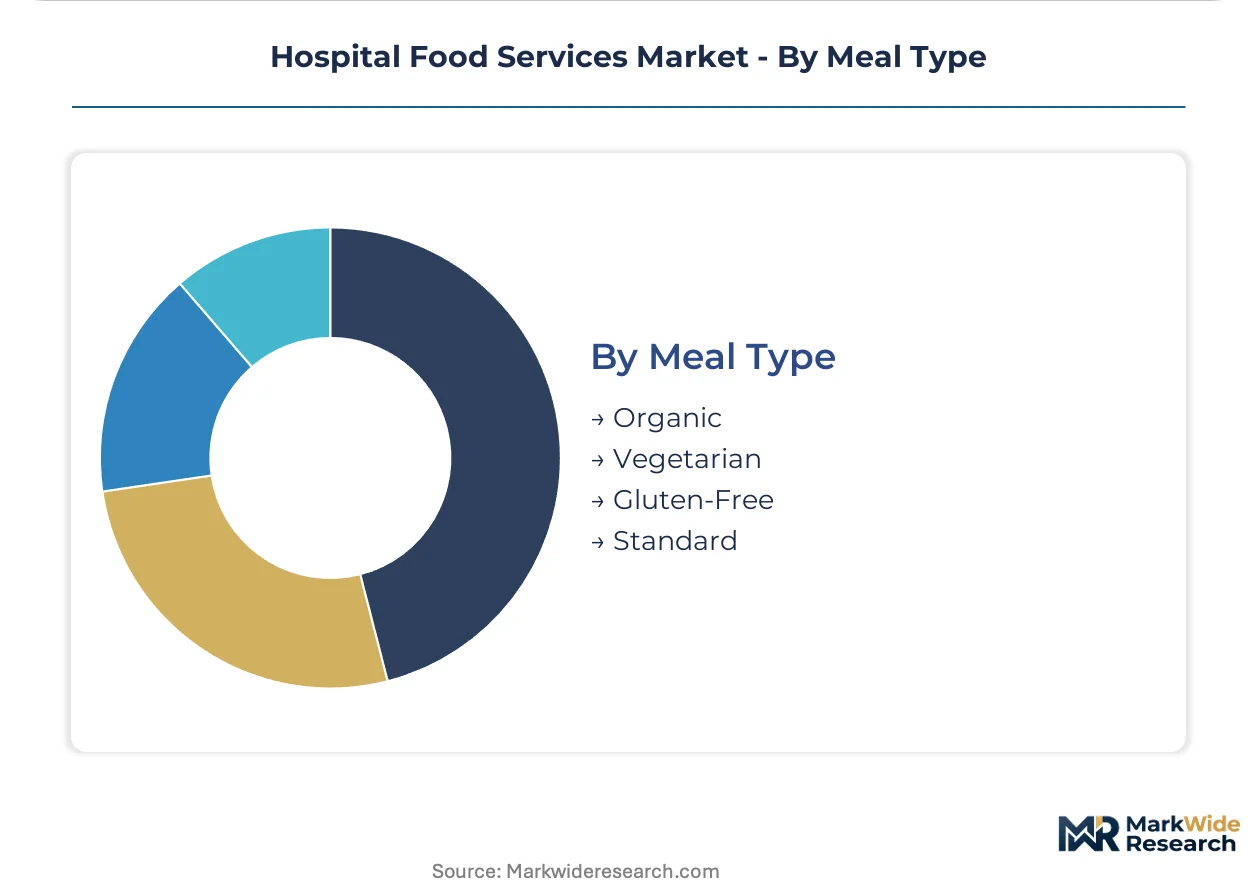
Meal Type:
Clinical protocol evolution and consumer preference data reshape procurement specifications.
- Gluten-Free:Celiac disease diagnosis rates and allergen protocols demand segregated preparation workflows with dedicated equipment and ingredient sourcing. Large-scale operators invest in certified production facilities to meet competitive tender requirements from California and New York hospital systems.
- Organic:USDA certification serves as marketing differentiator for hospitals positioning wellness credentials to attract commercially insured patients. Sourcing complexity and price premiums limit penetration to premium contract tiers.
- Vegetarian:Plant-forward menus address sustainability commitments and diverse patient populations.
- Standard:Conventional therapeutic diets maintain volume base across cost-constrained operations.
Volume concentration sits with Standard. Specification intensity climbs fastest in Gluten-Free.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax-advantaged healthcare zones in the United States concentrate outsourced foodservice procurement, while Germany's hospital modernization programs and Japan's aging-care infrastructure investments reshape contractor selection criteria across distinct regulatory environments.
United States
Health system consolidation in Texas and Florida drives enterprise-scale foodservice contracts requiring unified technology platforms. CMS Conditions of Participation mandate nutritional screening within 24 hours of admission, forcing hospitals toward qualified contractors with documented cold-chain compliance. The Dallas-Fort Worth metroplex anchors multi-hospital procurement networks retrofitting aging kitchens for room service distribution.
Germany
Hospital modernization funds under the Hospital Future Act accelerate outsourcing of dietary management to specialized contractors. EFSA nutritional labeling requirements and federal hygiene standards tighten vendor qualification thresholds. The Rhine-Ruhr metropolitan region concentrates integrated delivery networks standardizing allergen controls across university hospital systems.
Japan
Super-aging society demographics expand long-term care hospital foodservice demand beyond acute care capacity. METI guidelines on food safety management systems and PMDA therapeutic diet protocols elevate contractor technical requirements. The Kanto region surrounding Tokyo anchors consolidation of municipal hospital food operations under regional purchasing cooperatives.
United Kingdom
NHS England cost improvement programs push trust hospitals toward outsourced catering with performance-linked contracts. Food Standards Agency allergen regulations and CQC inspection frameworks shape procurement specifications. The Greater Manchester health system exemplifies centralized foodservice contracting across formerly independent hospital sites.
Australia
State health department procurement centralization in Victoria and New South Wales compresses vendor rosters for multi-site contracts. FSANZ food safety standards and Aged Care Quality Commission nutrition audits elevate compliance burdens. Melbourne's hospital precinct leads adoption of cook-chill production systems supporting room service delivery models.
Hospital Food Services Market Competitive Landscape
Top-tier vendors anchor multi-billion-dollar healthcare infrastructure, while mid-scale regional specialists compete on localized compliance expertise. The market exhibits moderate concentration with three global contractors commanding significant integrated delivery network contracts alongside fragmented regional players serving single-hospital or small-system accounts. Strategic archetypes include technology-enabled platform operators, clinical nutrition integrators, and retail dining monetization specialists. Competitive dynamics center on multi-hospital contract consolidation and cold-chain compliance certification investments.
Among the global contract foodservice operators, Compass Group plc, Sodexo, and Aramark occupy positions exemplifying divergent strategic emphases. Compass Group plc represents the technology-enabled platform archetype through meal tracking systems aligning with patient safety protocols. Sodexo anchors the clinical nutrition integration vector leveraging global healthcare infrastructure for multi-hospital contract penetration. Aramark exemplifies retail dining monetization, capturing staff and visitor spend alongside regulated patient meal programs. These three entities sit within the premium tier where scale advantages meet compliance capability requirements.
| Leading Market Players |
|---|
| Compass Group plc |
| Sodexo |
| Aramark |
| Elior Group |
| Healthcare Services Group, Inc. |
| ISS World |
| Metz Culinary Management |
| AVI Foodsystems, Inc. |
| Whitsons Culinary Group |
| Others |
Value Network & Pricing Analysis
Outsourced foodservice management anchors supply positioning and pricing power across hospital networks, with large-scale contractors leveraging centralized procurement and HACCP-certified production facilities to command premium contract terms while regional competitors face margin compression from compliance cost burdens.
Pricing Analysis
Short lead-time premiums for room service deployment and on-demand meal ordering distinguish acute care contracts from conventional tray-line pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with USDA organic and gluten-free certified tiers commanding substantial markups over standard therapeutic diets. Cost compression in economy-tier patient meal programs is intensifying because urban labor wage escalation outpaces CMS reimbursement adjustments. Academic medical centers and integrated delivery networks demonstrate lowest price sensitivity due to value-based reimbursement incentives, while standalone community hospitals remain most price-constrained.
Supply Chain Analysis
Freight costs for temperature-controlled distribution from centralized cook-chill facilities to multiple hospital sites represent a significant cost layer that scales with geographic dispersion of contract coverage. Protein sourcing concentrates in the Midwestern United States, with consolidated meat and dairy suppliers creating single-source vulnerability to contamination recalls affecting nationwide networks. Supply chains draw from specialized gluten-free ingredient processors in California and New York, organic produce distributors across the Pacific Northwest, and conventional broadline distributors for standard therapeutic diets. Tariff exposure on imported specialty ingredients and equipment creates margin risk. Distribution runs through regional distribution centers with cold-chain integrity monitoring, feeding last-mile delivery via refrigerated transport to hospital receiving docks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based foodservice management platforms are displacing legacy paper-based meal ordering and inventory systems, creating a technology-transition window where contractor selection criteria favor vendors with demonstrated EHR integration capabilities.
For Market Incumbents: Acquire blockchain-enabled supply chain tracking capabilities to meet FDA Food Safety Modernization Act traceability requirements emerging in California and New York competitive tenders. Consolidate regional competitors facing capital constraints from Joint Commission HACCP auditing investments. Defend against mid-scale clinical nutrition specialists by embedding registered dietitians into care teams for value-based reimbursement positioning. For New Entrants and Emerging Players: The gap between premium organic-certified contracts and economy-tier cost-minimization procurement creates white-space opportunity in mid-market integrated delivery networks seeking technology-enabled standardization without full premium pricing. Target secondary and tertiary hospitals in Texas and Florida health systems retrofitting aging infrastructure for room service conversion. Penetrate through modular SaaS pricing for cloud-based menu management platforms that integrate with existing kitchen equipment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by global contract foodservice operators seeking geographic density in high-growth health system consolidation markets. Five-to-ten-year viability favors contractors with demonstrated multi-hospital technology platform deployment and registered dietitian staffing capabilities. Watch for inflection signals in Medicare reimbursement rulemaking around nutritional care integration into bundled payment models.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Supply Chain Implementation | FDA traceability compliance enables competitive tender qualification in California and New York systems. |
| Room Service Infrastructure Retrofit | Cook-chill production systems reduce food waste and improve CMS-tied satisfaction metrics. |
| Registered Dietitian Staffing Expansion | CMS Conditions of Participation compliance creates differentiation against labor-constrained regional competitors. |
| Retail Dining Monetization Buildout | Grab-and-go markets capture staff and visitor spend to subsidize regulated patient meal programs. |
| EHR Integration Platform Development | Physician order entry connectivity embeds contractors into clinical workflow for renewal lock-in. |
Research Methodology
Multi-period observation of health system consolidation patterns, CMS regulatory implementation timelines, and foodservice contract award flows anchored the trend analysis, supplemented by interviews with hospital procurement directors, foodservice contract managers, registered dietitians, and GPO contracting specialists. Secondary validation drew from FDA enforcement action databases, CMS Conditions of Participation rulemaking dockets, Joint Commission accreditation survey results, and hospital capital expenditure disclosures. Bottom-up triangulation across individual hospital contract values and top-down reconciliation against health system reported operating expenses ensured cross-verification.
Segment-weighting approaches applied differential growth assumptions across service type, end user, and delivery mode dimensions, with meal distribution services, staff retail spend, and room service models receiving distinct trajectory parameters. Modeled variables included health system consolidation velocity, registered dietitian labor availability by metropolitan statistical area, and kitchen infrastructure age distributions. CAGRs were derived from logistic diffusion curves for technology adoption and elasticity-adjusted demand projections for regulated versus discretionary spend categories.
Underlying measurement precision varies by segment; technology-enabled service types with documented contract values carry tighter precision than emerging clinical nutrition integration categories with limited standardization. Forecasts reflect assumptions around Medicare reimbursement stability, labor cost trajectories, and protein supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Airline Catering Services Market
Food Service
Chile Food Delivery Market
Food Service
Global Dark Store Market
Food Service
Online Catering Market
Food Service
Bahrain Food Service Market
Food Service
Wok Market
Food Service
A La Carte Market
Food Service
Global Vending Machine Market
Food Service
Kamado Grill Market
Food Service
Global Online Food Ordering Market
Food Service
Plates Market
Food Service
North America Food Service Market
Food Service
Europe Food Service Market
Food Service
United States Full Service Restaurants Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Mexico Foodservice Market