
 China Retail Bubble Tea Kits Market | 2026-2036
China Retail Bubble Tea Kits Market Size, Share, and Industry Trends Forecast 2026-2036
China Retail Bubble Tea Kits Market Insights
Smart packaging integration with QR-code-enabled brewing tutorials and freshness tracking is reshaping how Chinese consumers interact with retail bubble tea kits at home. HeyTea leverages its premium brand equity to sustain direct-to-consumer channel control through proprietary mini-programs. Nayuki anchors its kit portfolio with seasonal fruit-forward formulations that differentiate from conventional milk-tea concentrates. Mixue Ice Cream & Tea competes on manufacturing scale, supplying standardized tapioca pearl sachets across its franchise network.
China retail bubble tea kits comprise pre-portioned combinations of tea bases, tapioca starch pearls, flavored syrups, and textured toppings designed for home preparation without commercial equipment. Most kits specify brewing temperatures between 85°C and 95°C for optimal tea extraction and require four- to six-minute pearl simmering cycles to achieve Q-bounce texture. Tapioca pearl kits lead volume due to established consumer familiarity, while flavor syrup segments capture margin pools through limited-edition collaborations and regional taste localization. Online retail channels now dominate distribution, though specialty stores in Shanghai and Shenzhen maintain relevance for premium gift-box positioning and experiential sampling.
SAMR enforces pre-market registration and nutritional labeling compliance for all pre-packaged beverage components sold through domestic retail channels. GB standards for food contact materials regulate plastic film and paper packaging used in kit assemblies, while NMPA oversight extends to any functional ingredient claims targeting digestive or metabolic benefits. Stakeholders must monitor how MIIT's digital commerce regulations reshape live-streaming sales dynamics, as this channel currently drives the bulk of new consumer acquisition for kit brands.
Market Dynamics
Live-streaming commerce on Douyin and Xiaohongshu now captures the majority of new consumer acquisition for bubble tea kit brands, compressing traditional e-commerce conversion funnels and forcing rapid inventory turnover cycles.
Growth Catalysts
- GB Standards for Food Contact Materials:SAMR's tightened packaging safety requirements push manufacturers toward higher-grade barrier films, elevating perceived product quality and justifying premium positioning.
- Gen Z At-Home Consumption:Post-pandemic habit persistence among 18-25 year olds in Chengdu and Hangzhou sustains repeat purchase rates for DIY beverage preparation.
- Smart Packaging Integration:QR-code-enabled brewing tutorials and freshness tracking systems reduce preparation failure rates and lower customer service costs.
Market Restraints
- Tapioca Starch Input Volatility:Cassava price fluctuations in Southeast Asian supply corridors compress margin pools for pearl-intensive kit configurations.
- MIIT Digital Commerce Enforcement:Stricter live-streaming disclosure requirements increase compliance overhead for influencer-driven sales channels.
- Fresh Bubble Tea Substitution:Neighborhood Mixue Ice Cream & Tea franchise density in tier-three cities limits at-home kit penetration among convenience-seeking buyers.
Strategic Opportunities
- Yangtze River Delta Manufacturing Clusters:Proximity to flavor syrup and tea base suppliers enables same-day replenishment for direct-to-consumer fulfillment models.
- Seasonal Fruit-Forward Formulations:Limited-edition collaborations with regional agricultural brands create scarcity-driven purchase urgency.
- NMPA Functional Ingredient Pathway:Prebiotic and digestive health claims open margin expansion for wellness-positioned kit variants.
Industry Challenges
- Brewing Temperature Calibration:Consumer execution variance between 85°C and 95°C extraction protocols generates inconsistent taste experiences and negative reviews.
- Q-Bounce Texture Consistency:Four- to six-minute pearl simmering cycle adherence depends on household equipment heterogeneity.
- Cross-Platform Inventory Synchronization:Real-time stock visibility across Douyin, Tmall, and proprietary mini-programs strains ERP system architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Retail Bubble Tea Kits Market |
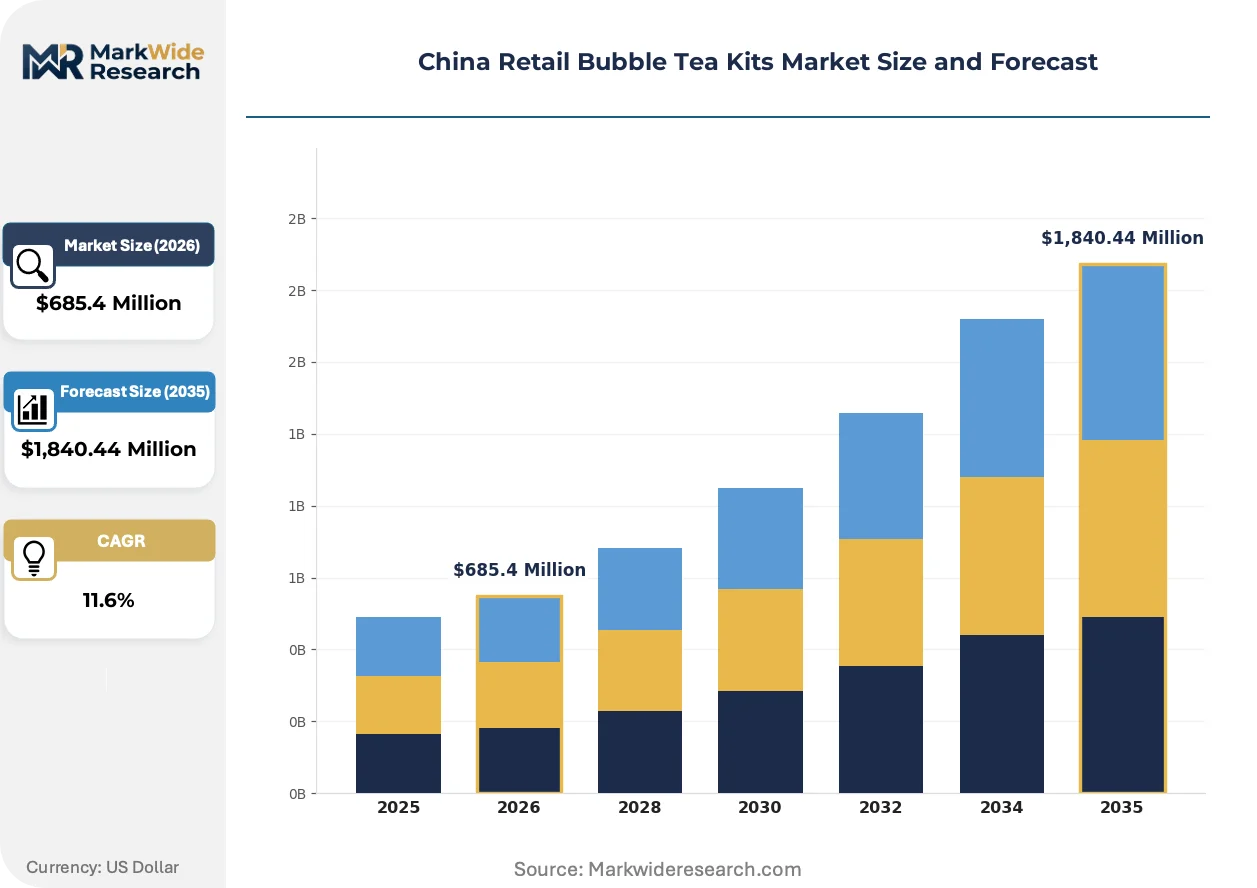
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,840.44 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pudding Kits, Tapioca Pearls, Flavor Syrups, Tea Leaves Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Target Consumer: Students, Young Professionals, Families, Health Conscious Ingredient Source: Local Suppliers, Imported Materials, Organic Farms, Others |
| Companies Covered | Mixue Ice Cream & Tea, HeyTea, Nayuki, CHAGEE, GoodMe Milk Tea, CoCo Fresh Tea & Juice, Chatime Group, Tiger Sugar, Happy Lemon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Retail Bubble Tea Kits Market Trends and Innovations
Packaging intelligence and regulatory disclosure depth are converging to reshape how Chinese consumers evaluate retail bubble tea kits before purchase.
Active freshness indicators using time-temperature integrator dyes are migrating from pharmaceutical cold-chain applications into premium kit assemblies. Tier-one city buyers now expect visible spoilage warnings on tapioca pearl sachets. This transparency layer compresses brand trust-building timelines and accelerates first-time trial conversion.
SAMR's nutritional labeling enforcement now mandates per-serving sugar and caffeine disclosure on all pre-packaged beverage components. Manufacturers reformulate syrup concentrates to hit cleaner-label thresholds. Gift-box positioning in Shanghai and Shenzhen specialty stores faces reformulation costs that online-only brands avoid.
Subscription bundling through WeChat mini-programs displaces single-transaction purchasing among heavy users. Pearl and topping replenishment cycles now anchor retention economics. Hangzhou and Chengdu exhibit the highest auto-renewal activation rates, correlating with Gen Z demographic concentration.
China Retail Bubble Tea Kits Market Segmentation
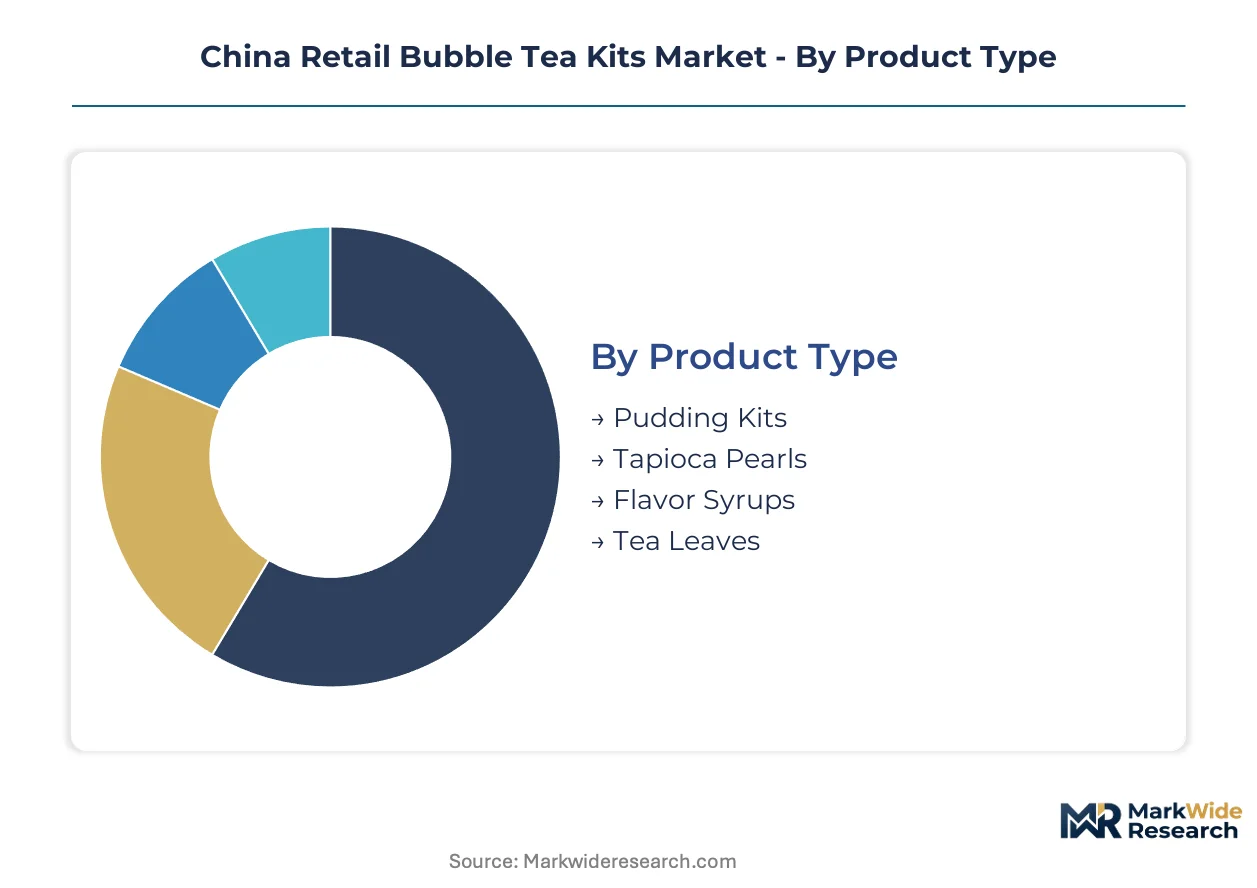
Segmentation in China's retail bubble tea kits market exposes divergent service intensity requirements across product formats and purchasing contexts. Technical support demands vary sharply between complex multi-component kits and single-ingredient replenishment purchases. Distribution channel selection directly shapes return rates and customer lifetime value calculations for kit brands operating at scale.
Product Type:
After-sales service intensity escalates dramatically for multi-component kits requiring precise preparation coordination between elements.
- Tapioca Pearls:Starch-based spheres requiring four- to six-minute controlled simmering cycles to achieve target Q-bounce texture. Demand concentrates in Chengdu and Hangzhou among Gen Z consumers who prioritize texture authenticity over convenience, though cooking failure rates drive disproportionate customer service inquiries.
- Flavor Syrups:Concentrated sweetening and flavoring agents with precise dilution ratios specified per serving. Young professionals in Shanghai's Yangtze River Delta corridor favor limited-edition seasonal formulations that command premium positioning through scarcity-driven release cycles.
- Pudding Kits:Gelatin or agar-based dessert components requiring refrigeration and specific setting times.
- Tea Leaves:Loose-leaf or sachet formats with origin-specific brewing temperature protocols between 85°C and 95°C.
Tapioca pearls hold the largest share; momentum sits with flavor syrups.
Distribution Channel:
Cost tier stratification separates high-touch experiential retail from automated digital fulfillment with minimal marginal service cost.
- Online Retail:Douyin and Tmall-dominated channels with live-streaming commerce driving bulk of new customer acquisition. Auto-renewal subscription economics through WeChat mini-programs now anchor retention models for heavy users in tier-two cities.
- Specialty Stores:Shanghai and Shenzhen physical locations emphasizing gift-box positioning and experiential sampling with trained staff guidance. Premium price realization depends on tactile product evaluation and immediate preparation troubleshooting support.
- Supermarkets:Mass-market shelf placement with standardized packaging and limited staff expertise.
- Direct Sales:Brand-controlled proprietary channels bypassing platform commission structures.
Online retail holds the largest share; specialty stores are gaining share fastest through premium positioning.
Target Consumer:
Application context determines kit complexity preferences and preparation tolerance thresholds across demographic cohorts.
- Young Professionals:Time-constrained urban workers aged 25-35 seeking convenient at-home alternatives to queue-based fresh bubble tea purchases. Post-pandemic habit persistence sustains repeat purchase rates for DIY preparation among this cohort in Hangzhou and Chengdu.
- Students:Price-sensitive 18-24 year old demographic with higher preparation time availability and social sharing motivation.
- Families:Multi-person household units prioritizing bulk formats and child-friendly flavor options.
- Health Conscious:Wellness-oriented buyers seeking reduced-sugar formulations and clean-label ingredient transparency.
Young professionals hold the largest share; health conscious consumers are expanding most quickly.
Ingredient Source:
Supply concentration geography shapes cost structures and regulatory compliance burden for kit assemblers.
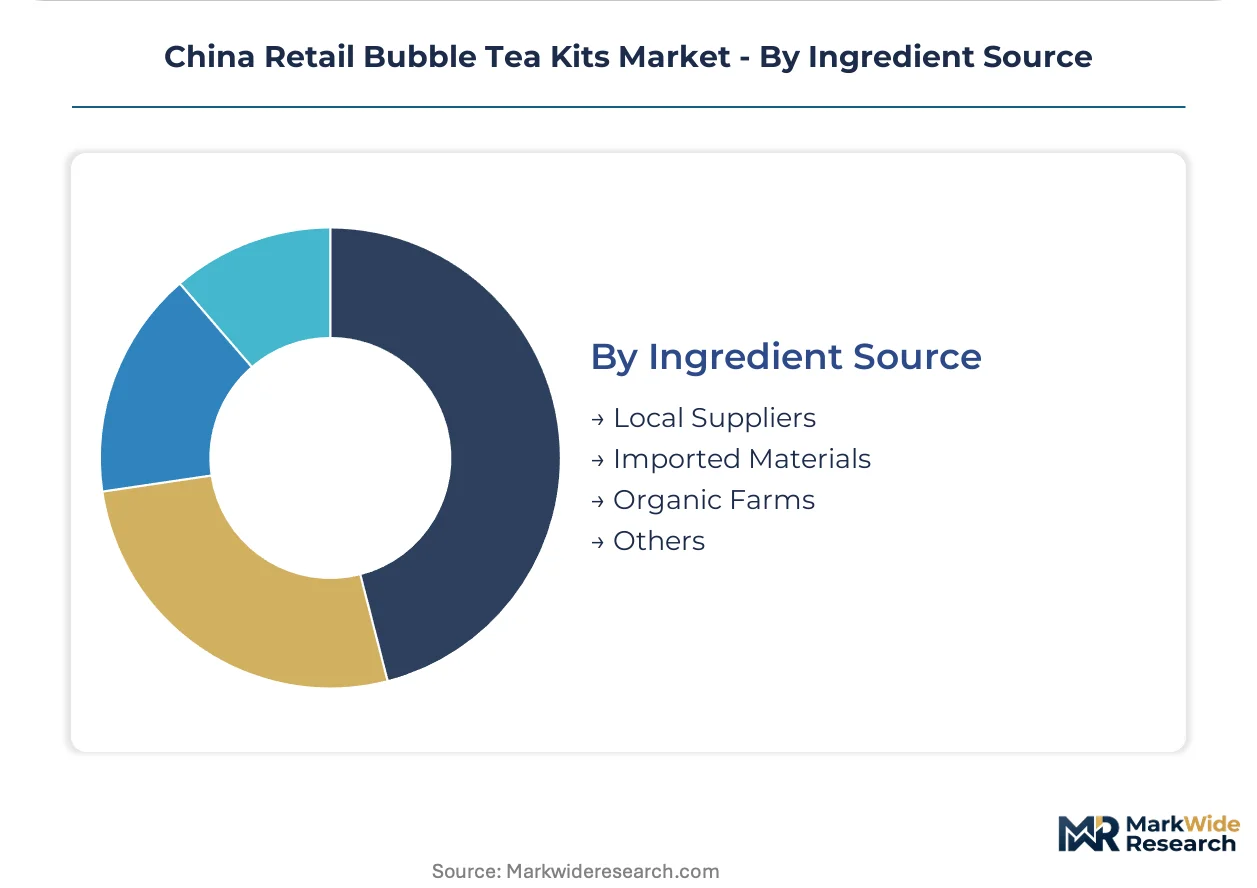
- Local Suppliers:Domestic tea base and flavor syrup producers within Yangtze River Delta manufacturing clusters enabling same-day replenishment for direct-to-consumer fulfillment. SAMR's GB standards for food contact materials apply uniformly across domestic sourcing arrangements.
- Imported Materials:Southeast Asian cassava starch for tapioca pearls subject to price volatility and customs clearance timing.
- Organic Farms:Certified agricultural operations commanding premium positioning through third-party verification.
- Others:Specialty or hybrid sourcing arrangements outside standard procurement categories.
Local suppliers hold the largest share; organic farms are climbing the fastest on wellness-positioned kit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's retail bubble tea kits market operates as a net importer of cassava starch for tapioca pearls while exporting finished kit assemblies to Southeast Asian diaspora communities. The domestic production base concentrates in coastal manufacturing clusters with tier-two cities driving consumption growth.
Yangtze River Delta
Shanghai anchors premium kit consumption with specialty stores commanding gift-box price realization. SAMR's GB standards for food contact materials elevate packaging compliance costs for local assemblers. Hangzhou's Gen Z demographic sustains the highest WeChat mini-program subscription renewal rates nationwide.
Pearl River Delta
Shenzhen's tech-forward consumer base demands QR-code-enabled smart packaging with freshness tracking integration. MIIT digital commerce regulations reshape live-streaming sales dynamics on Douyin and Xiaohongshu. Guangzhou's flavor syrup suppliers enable same-day replenishment for direct-to-consumer fulfillment models.
Sichuan-Chongqing
Chengdu's 18-25 year old cohort prioritizes texture authenticity in tapioca pearl preparation despite higher cooking failure rates. SAMR nutritional labeling enforcement mandates per-serving sugar disclosure on all pre-packaged components. Local tea base processors source from Yunnan and Guizhou plantations for origin-specific formulations.
Beijing-Tianjin-Hebei
Health-conscious consumers in Beijing's urban core drive demand for reduced-sugar and clean-label kit variants. NMPA oversight extends to functional ingredient claims targeting digestive benefits. Tianjin's port infrastructure handles imported cassava starch shipments from Southeast Asian supply corridors.
China Retail Bubble Tea Kits Market Competitive Landscape
On the supply side, the industry is bifurcated between premium brand-controlled channels and scale-driven franchise networks. Tier-one city operators leverage proprietary mini-programs for direct-to-consumer retention. Tier-two and tier-three markets favor standardized, price-accessible configurations. Strategic archetypes include premium lifestyle brands, mass-market franchise suppliers, and specialty ingredient specialists. Competitive moves concentrate on vertical integration into flavor syrup production and exclusive agricultural partnerships for seasonal formulations.
Among premium-tier operators, HeyTea and Nayuki exemplify brand equity monetization through controlled distribution channels. Mixue Ice Cream & Tea occupies a position at the scale-driven end, anchoring mass-market penetration through franchise network standardization. CHAGEE and GoodMe Milk Tea represent mid-tier challengers competing on regional taste localization.
| Leading Market Players |
|---|
| Mixue Ice Cream & Tea |
| HeyTea |
| Nayuki |
| CHAGEE |
| GoodMe Milk Tea |
| CoCo Fresh Tea & Juice |
| Chatime Group |
| Tiger Sugar |
| Happy Lemon |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta manufacturing clusters concentrate flavor syrup and tea base production capacity, granting assemblers same-day replenishment leverage that compresses competitor pricing windows and elevates premium tier realization in coastal markets.
Pricing Analysis
Smart packaging-enabled kits command a generation-ahead premium over conventional sachet configurations, while basic pearl-only formats face commoditization pressure from franchise network standardization. Three-tier pricing structure across premium, standard, and economy levels separates gift-box specialty positioning from mass-market online penetration. Cost compression in the economy tier intensifies because of cassava starch input volatility and live-streaming commission structures. Students exhibit highest price sensitivity, while young professionals in Shanghai tolerate premium positioning for experiential packaging and freshness tracking.
Supply Chain Analysis
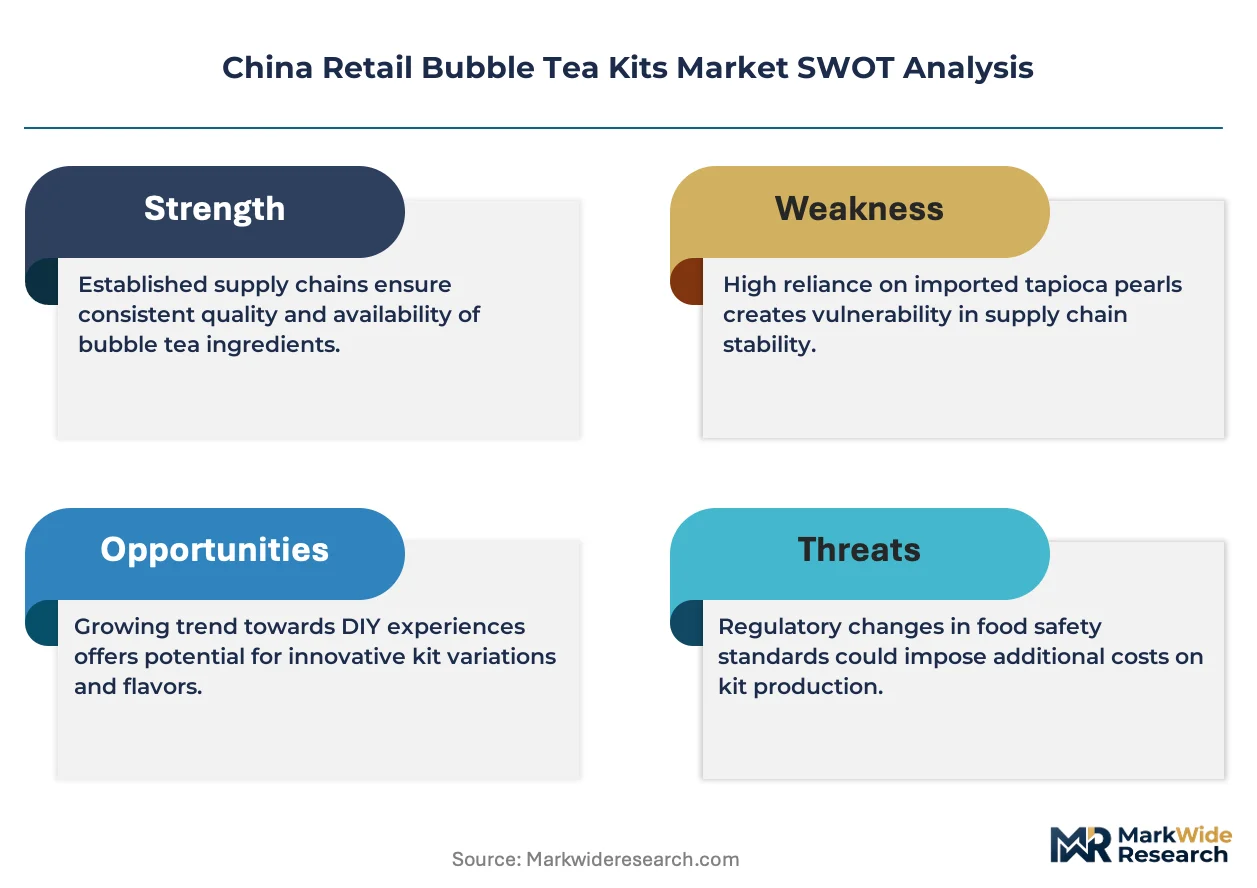
Cassava starch feedstock draws from Thailand, Vietnam, and Indonesia, creating import dependency for tapioca pearl production that tethered margin stability to Southeast Asian agricultural output cycles. Tea bases and flavor syrups source from domestic Yangtze River Delta suppliers, while barrier film packaging hinges on GB standards-compliant domestic converters. Single-source vulnerability concentrates in cassava supply corridors exposed to climate disruption and customs clearance timing. Distribution runs through Douyin and Tmall live-streaming channels with WeChat mini-program subscription anchoring replenishment economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on WeChat mini-program ecosystem lock-in, where subscription bundling and proprietary channel control separate defensible incumbents from commission-dependent challengers across tier-two city expansion.
For Market Incumbents: Pre-empt fresh bubble tea substitution threats in tier-three markets by anchoring captive supply of flavor syrup production and securing exclusive agricultural partnerships for seasonal scarcity releases. Channel control through proprietary mini-programs, not platform dependency, protects margin pools against MIIT disclosure compliance cost escalation. For New Entrants and Emerging Players: Establish a beachhead in health-conscious kit variants targeting Beijing's wellness-oriented demographic with NMPA functional ingredient pathway positioning. White-space concentrates in reduced-sugar clean-label formulations and organic farm-certified sourcing tiers. Go-to-market through Xiaohongshu community-driven discovery, not Douyin price competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors flavor syrup specialists with backward integration into tea base processing and smart packaging integration capabilities. Long-term viability hinges on subscription retention economics rather than single-transaction acquisition. The signal to watch is auto-renewal activation rate divergence between tier-one and tier-two city cohorts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flavor Syrup Production | Captive supply secures margin pools against commodity volatility in Yangtze River Delta clusters. |
| Smart Packaging Integration | QR-code-enabled tutorials reduce preparation failure rates and customer service cost burdens. |
| Exclusive Agricultural Partnerships | Seasonal fruit-forward collaborations create scarcity-driven purchase urgency in tier-one cities. |
| WeChat Mini-Program Subscription Launch | Auto-renewal economics displace single-transaction purchasing among heavy users in Hangzhou. |
| Clean-Label Reformulation Investment | SAMR nutritional labeling compliance enables premium positioning in health-conscious Beijing segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across brand managers at kit assemblers, category buyers at Douyin and Tmall platforms, flavor syrup procurement leads in Yangtze River Delta manufacturing clusters, and regulatory affairs specialists navigating SAMR and NMPA compliance pathways. Secondary validation drew from customs import records for cassava starch, MIIT digital commerce enforcement circulars, GB standards documentation for food contact materials, and Nielsen retail audit data for online channel share. Bottom-up demand modeling and top-down supply capacity triangulation anchored volume estimates.
Calibration against historical live-streaming commerce penetration rates and subscription service adoption curves in adjacent beverage categories informed trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product format complexity, distribution channel cost tier, target consumer preparation tolerance, and ingredient source geography. CAGRs derived from fitted growth curves against demographic cohort expansion and habit persistence indicators, with Gen Z concentration in Chengdu and Hangzhou weighted heavily.
Sensitivities concentrate around cassava price volatility, live-streaming regulatory enforcement intensity, and fresh bubble tea franchise density in tier-three markets. Cross-checking against MIIT digital commerce transaction disclosures and SAMR pre-market registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Inflight Catering Market
Food Service
Europe Cloud Kitchen Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
North America Cafes & Bars Market
Food Service
Italy Foodservice Market
Food Service
Bar Refrigeration Market
Food Service
Contract Catering Market
Food Service
Ice Cream Carts Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Australia Foodservice Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Food Service Pasta Market
Food Service
Hyperlocal Grocery Delivery Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
United States Foodservice Market
Food Service
Galley Equipment Market